

- Market Size (2026)
- USD 5.8 Bn
- Forecast (2036)
- USD 7.8 Bn
- CAGR (2026 to 2036)
- 2.9%
How big is Fish Waste Management Market in 2026?
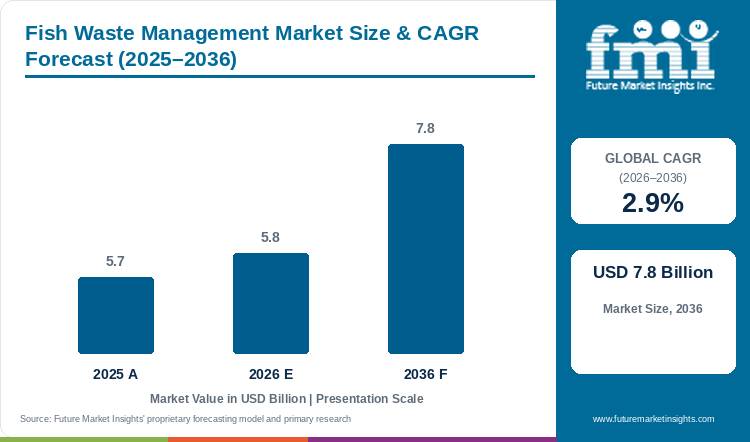
Sales in the fish waste management market are projected to grow at 2.9% CAGR, with the market size rising from USD 5.7 billion in 2025 to USD 5.8 billion in 2026 and reaching USD 7.8 billion by 2036.
Increasing volumes of processed seafood coupled with stringent municipal wastewater and environmental disposal norms have forced industrial seafood plants to transition from basic waste dumping toward valorization of fish residues. According to Future Market Insights analysis, the global fish waste management market is valued at USD 5.7 billion in 2025 and rises to USD 5.8 billion in 2026. Industry turnover is projected to reach USD 7.8 billion by 2036, advancing at a 2.9% CAGR and generating approximately USD 1.9 billion in added revenue across the forecast period. Seafood processors are separating heads, viscera, skin, and frames at the evisceration line to capture commercial value before rapid enzymatic decomposition and lipid oxidation spoil the raw biomass.
In June 2025, FAO published a global marine stock assessment covering 2,570 stocks across 92 countries, demonstrating that complete utilization of harvested aquatic biomass is essential to sustain seafood supply without increasing wild harvest pressures [1]. Fish meal and animal feed represents the largest application category, accounting for 58.6% of demand in 2026 as livestock and aquaculture producers require digestible, circular marine proteins. Across evaluated countries, South Korea exhibits the highest expansion rate at 3.8% CAGR, while Japan records 1.5%, though rapid coastal spoilage and high logistics expenses for decentralized landings continue to restrict processing economics.
Key Market Trends & Insights
- By waste source: Fish-processing residues are forecast to lead with 64.2% share in 2026, driven by concentrated volumes at filleting and canning plants.
- By application: Fish meal and animal feed are projected to account for 58.6% in 2026, underpinned by established protein and oil recovery routes.
- By processing method: Rendering is estimated to hold 45.7% in 2026, owing to dependable throughput and broad feed-market acceptance.
- By end user: Aquafeed manufacturers are likely to capture 39.4% in 2026, supported by demand for marine protein inputs and circular sourcing.
Regional Highlights
- Fastest-growing evaluated country: South Korea, at 3.8% CAGR from 2026 to 2036.
- Germany at 3.4%, the USA at 3.2%, and Norway at 3.1% follow, while Japan records 1.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Fish Waste Management Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.7 billion |
| Estimated Market Size in 2026 | USD 5.8 billion |
| Projected Market Size by 2036 | USD 7.8 billion |
| CAGR, 2026 to 2036 | 2.9% |
| Added Revenue, 2026 to 2036 | USD 1.9 billion |
Country operational conditions differ as fish waste retains commercial value only when stabilization begins before microbial spoilage and oil rancidity ruin the protein fraction. An FMI analyst notes that refrigerated bin collection, ensiling, and dedicated rendering agreements will gain preference, as feed formulators mandate consistent nutrient specifications while processors seek to prevent odours and wastewater penalties. In April 2025, the FAO Sub-Committee on Aquaculture prioritized by-product valorization across animal feed and bioenergy as central circular pathways [2]. These circular mandates provide processors with compelling economic justification to segregate clean waste streams directly on the cutting floor.
Recovery-Volume and Value-Conversion Sizing
Table 2: Recovery-Volume and Commercial Conversion Indicators for the Fish Waste Management Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.7 | 5.8 | 7.8 |
| Managed fish residues (million tonnes) | 21.5 to 24.0 | 22.1 to 24.7 | 29.0 to 33.0 |
| Recovered saleable output (million tonnes) | 8.6 to 10.8 | 9.0 to 11.2 | 12.8 to 16.5 |
| Average managed value (USD/tonne) | 237 to 264 | 237 to 265 | 236 to 268 |
Processor and Facility Economics
Fish residues start losing commercial quality soon after cutting and evisceration, hence distance between the processor and recovery plant becomes part of the product economics. Cooling and ensiling can give more time, but these also add handling cost. Plants having regular volumes can separate food, marine collagen and oil-rich streams, while smaller mixed loads are more likely to move towards feed, fertilizer or energy. This difference is expected to keep recovery concentrated around processing clusters rather than every landing point. This routing also connects recovered skin with marine collagen demand and oil-rich fractions with commercial fish oil buyers.
Table 3: Processor Economics Indicators for the Fish Waste Management Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Managed value per tonne (USD) | 237 to 264 | 237 to 265 | 236 to 268 |
| Recoverable output ratio | 40% to 45% | 41% to 46% | 44% to 50% |
| Collection radius benchmark | 50 to 180 km | 50 to 180 km | 40 to 160 km |
| Stabilization window | 4 to 12 hours | 4 to 12 hours | 3 to 10 hours |
Table 4: Application Revenue Indicators for the Fish Waste Management Market, 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 5.8 billion | Report value |
| Fish meal and animal feed revenue | USD 3.4 billion | 58.6% share |
| Other applications revenue | USD 2.4 billion | 41.4% balance |
| Added revenue through 2036 | USD 1.9 billion | Forecast difference |
Analyst Perspective
“Fish processors are treating by-products as controlled raw materials rather than disposal loads. Suppliers that preserve freshness and separate clean streams can secure higher-value feed, nutrition, and bioenergy contracts.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Fish Waste Management Market segmented?
The market is segmented by waste source, application, processing method, and end user. In 2026, fish-processing residues lead waste source, fish meal and animal feed lead application, rendering leads processing method, and aquafeed manufacturers lead end user.
By waste source: Fish-processing residues, aquaculture mortalities, wild-catch discards, and others.
By application: Fish meal and animal feed, fish oil, fertilizers, bioenergy, collagen and gelatin, and others.
By end user: Aquafeed manufacturers, pet food producers, agriculture, nutraceuticals and cosmetics, energy operators, and others.
Why do Fish-Processing Residues lead the waste source category?
Fish-processing residues represent 64.2% of waste source in 2026, supported by concentrated collection at industrial plants.
Table 5: Waste Source Share for the Fish Waste Management Market, 2026
| Waste Source | Share (2026) |
|---|---|
| Fish-Processing Residues | 64.2% |
| Other Segments Combined | 35.8%* |
| Total | 100.0% |
*Calculated as the balance after deducting the leading segment share from 100.0%.
Table 6: Waste Source Leadership and Market Growth, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 2.9% |
| Leading Segment | Fish-Processing Residues |
Fish-processing residues hold 64.2% share because filleting and canning plants generate material at one place, with a known species and a regular shift pattern. This makes pickup, testing and temperature control easier than the recovery of scattered discards. The share can remain high when processors keep skin, frames and viscera separate; however, mixing these fractions can quickly push a clean stream towards lower-value rendering.
- Fish-processing residues are projected to hold 64.2% share in 2026, driven by collection efficiency at fixed processing sites.
- Pelagia reports that it converts all raw material into food, feed ingredients, or health products [3].
Why does Fish Meal and Animal Feed define the largest application segment?
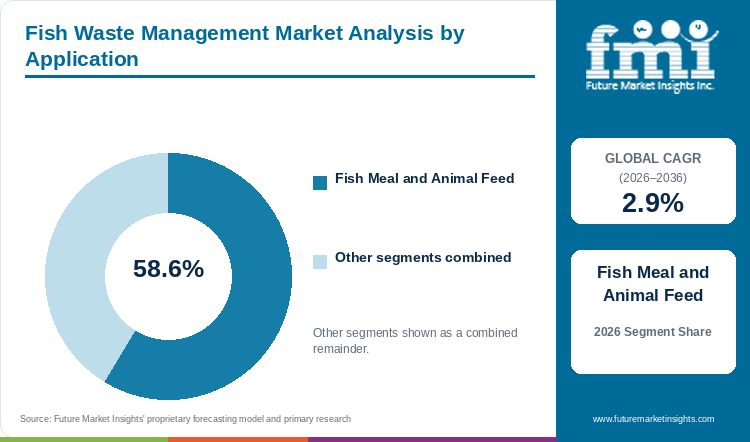
Fish meal and animal feed account for 58.6% of application in 2026, meeting recurring protein and oil requirements.
Fish meal and animal feed account for 58.6% share as rendering already gives processors a regular outlet for mixed heads, frames and trimmings. Feed buyers do not purchase waste only because it is available; buyers need digestibility, protein quality and oil stability from one load to another. Consequently, established cooking, pressing and drying capacity supports the segment, while poor freshness or uncertain species origin can reduce the price or close the feed route. The same output competes inside fishmeal and aquafeed purchasing systems.
- By application, fish meal and animal feed are estimated to hold 58.6% in 2026, underpinned by established feed demand.
What keeps Rendering ahead by processing method?
Rendering holds 45.7% of processing method demand in 2026, driven by high-throughput conversion of mixed residues.
Rendering leads with 45.7% share because it can take a wider mix of residues and produce a stable meal and oil which already has a buyer base. The method also handles volume better than small specialty extraction lines. Still, high moisture means more evaporation and drying, therefore power cost and freshness can decide whether the same tonne produces a useful margin or only avoids disposal cost.
- In 2026, rendering is expected to lead processing method with 45.7% share, owing to scalable throughput.
- Pelagia operates feed activities across fishmeal, marine oil, and protein concentrate categories [3].
What gives Aquafeed Manufacturers the leading position in end user?
Aquafeed manufacturers represent 39.4% of end user demand in 2026, managing recurring marine ingredient procurement.
Aquafeed manufacturers hold 39.4% share because marine proteins and oils can return into fish diets where digestibility and fatty-acid value are understood. The share does not mean every recovered stream qualifies for aquafeed. Oxidation, contamination and missing species records can shift material towards fertilizer or energy, which is why suppliers having chilled collection and batch testing are likely to secure repeat purchases.
- Aquafeed manufacturers are likely to capture 39.4% share in 2026, supported by demand for circular marine inputs.
- Mowi reported 559 thousand tonnes of Atlantic salmon harvest volume in 2025 [5].
What are the drivers, restraints, and opportunities in the Fish Waste Management Market?
Seafood throughput expands recoverable biomass, while rapid spoilage and fragmented logistics restrict value, and high-purity extraction creates premium opportunities.
- Driver: Rising seafood processing and circular-economy requirements increase the volume directed into controlled recovery channels.
- Restraint: High moisture, rapid oxidation, mixed species, and dispersed coastal collection reduce usable yield and raise transport costs.
- Opportunity: Enzymatic hydrolysis, collagen extraction, and integrated biorefineries raise returns from clean separated by-product streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Scheduled collection is increasing because a processor cannot wait for enough waste to accumulate when nutrient value is falling every hour. The 2025 FAO review covered 2,570 marine stocks and also showed how stronger management improves sustainability outcomes [1]. The same discipline after harvest favours separated skin, frames, viscera and oil-rich fractions. A processor having stable cold collection can sell more than one output, whereas an irregular mixed load remains tied to commodity fishmeal or disposal pricing.
Risk Assessment of the Fish Waste Management Market: Operational and Processing Friction
Fresh residues can turn from raw material into a liability within the same operating day. Microbial activity, oil oxidation and enzymatic breakdown lower protein quality and increase odour and wastewater load. The April 2025 FAO circular-aquaculture paper identified by-product use across food, feed, agriculture and energy, but it also noted implementation constraints [2]. Thus, remote landing sites can face the highest theoretical availability and still recover the least value when refrigerated pickup or local ensiling is not economical.
Commercial Opportunity Analysis: Recovery Differentiation and Value-Add Formats
Higher return sits in fractions which remain clean enough for a defined use. Skin and scales can move into marine collagen or gelatin, while viscera and trimmings can support oil, hydrolysate and feed production. Once these are mixed, the processor loses the option to route each fraction according to quality. This is why separation at the cutting line, chilled storage and analytical testing are expected to create more value than adding another treatment step after deterioration has already started. Pelagia and ScanBio corporate disclosures confirm that cold-chain segregation directly unlocks high-purity protein fractions [3].
Fish Waste Management Market by Country (2026 to 2036)
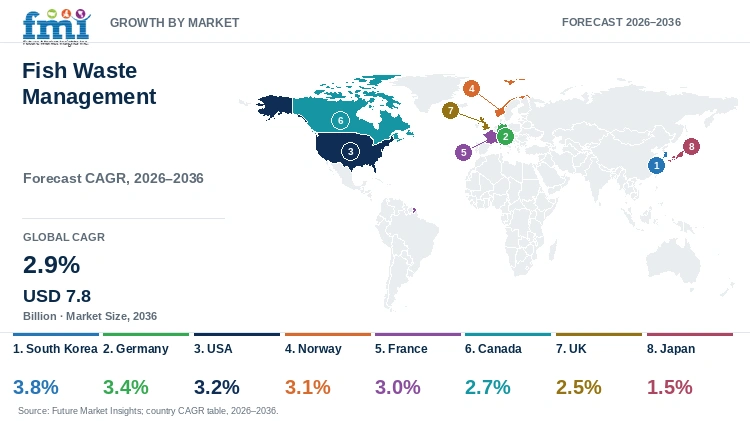
According to FMI, South Korea represents the fastest-growing fish waste management market among eight evaluated countries at 3.8% CAGR, while Japan records 1.5%. Commercial success depends on seafood concentration, collection infrastructure, and local demand for recovered feed or bioenergy inputs.
Table 7: Country CAGR and Primary Growth Levers for the Fish Waste Management Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 3.8% | Seafood-processing clusters and circular food policy |
| Germany | 3.4% | Bioeconomy policy and high-value ingredient recovery |
| USA | 3.2% | Large seafood supply chain and feed-market demand |
| Norway | 3.1% | Integrated salmon farming and silage logistics |
| France | 3.0% | Feed, fertilizer, and marine ingredient channels |
| Canada | 2.7% | Atlantic and Pacific seafood by-product recovery |
| UK | 2.5% | Zero-waste processing and specialty biopolymer interest |
| Japan | 1.5% | Mature fish use and slower processing-volume growth |
Source: Future Market Insights analysis
South Korea Fish Waste Management Market Outlook (2026 to 2036)
South Korea is expected to grow at 3.8% CAGR through 2036, the fastest among the evaluated countries, because seafood-processing activity is concentrated along coastal industrial areas and recovery contractors can collect a useful load without crossing very long distances. The hurdle sits with smaller plants having limited space for chilled bins and source separation. Shared pretreatment hubs, sealed pickup and domestic feed or pet food demand can push adoption, but recovery can slow when contractors receive mixed material with uncertain oxidation level. Domestic pet food formulators can give separated protein fractions an additional outlet.
Germany Fish Waste Management Market Outlook (2026 to 2036)
Germany is anticipated to expand at 3.4% CAGR through 2036. The country does not have the same fish residue base as Norway, therefore growth is more likely to come from better use of imported and domestically processed seafood rather than a large rise in landings. Strict by-product handling raises compliance cost, yet the same rules favour traceable skin, bone and protein streams for specialty ingredients. Mixed material can still move into anaerobic digestion or fertilizer, which limits disposal but does not give the same return as clean extraction. Lower-grade fractions may also support biofertilizer or anaerobic digestion where feed eligibility is unavailable.
USA Fish Waste Management Market Outlook (2026 to 2036)
The USA is forecast to rise at 3.2% CAGR through 2036, supported by federal policy initiatives such as Executive Order 14276 on American seafood competitiveness [10]. However, one national collection model is unlikely to work because Alaska, the Pacific Northwest, New England and the Gulf have different seasons and travel distances. Large processors can support rendering and fish oil, while remote or seasonal sites may need modular ensiling and cold storage before shipment. Demand from pet food, feed and marine oil can support recovery; however, weak plant loading outside the fishing season can raise the cost per tonne and delay new capacity.
Norway Fish Waste Management Market Outlook (2026 to 2036)
Norway is likely to record 3.1% CAGR through 2036 as salmon farming produces regular mortality and processing streams within an already organized marine supply chain. This gives the country an advantage over markets dependent on scattered wild-catch waste. Biosecurity can also be the main hurdle because category separation, vessel sanitation and licensed handling decide where the material can go. Suppliers combining collection, ensiling and certified ingredient output are better placed, while a breach in segregation can move an entire load towards a lower-value route.
France Fish Waste Management Market Outlook (2026 to 2036)
France is projected to grow at 3.0% CAGR through 2036. The opportunity is spread across feed, fertilizer and cosmetic ingredients, though fragmented ports and mixed auction volumes make collection less straightforward than recovery from a large canning plant. Regional consolidation and species-specific containers can improve the case. Clean skins and frames may enter collagen or hydrolysate production, while irregular mixed residues will remain dependent on rendering or digestion and therefore carry lower price upside.
Canada Fish Waste Management Market Outlook (2026 to 2036)
Canada is expected to advance at 2.7% CAGR through 2036 because Atlantic and Pacific seafood seasons create material in sizeable batches, but the batches are far apart and do not arrive evenly through the year. Remote communities can face freight cost before the residue reaches a commercial plant. Modular ensiling or small hydrolysis systems can preserve the load, and partnerships with farms, feed mills or energy operators can improve plant use. Without such local outlets, seasonal peaks can still return to disposal despite available biomass. Local waste to energy capacity can absorb streams which do not justify long-distance transport.
UK Fish Waste Management Market Outlook (2026 to 2036)
The UK is estimated to post 2.5% CAGR through 2036. Growth is expected to come less from bulk rendering and more from separating skin, scales and trimmings for marine biopolymers, fertilizer and specialty ingredients. Variable landings and energy cost can make a continuously operated dryer difficult to justify. Port-level segregation and contract processing can help, though contamination at the collection point can remove the premium route and place the same material back into meal or low-value treatment. Scale and skin fractions can also support bioplastics development when specification and volume are maintained.
Japan Fish Waste Management Market Outlook (2026 to 2036)
Japan is forecast to grow at 1.5% CAGR through 2036, the slowest evaluated rate, because fish by-products are already used across food, feed and fertilizer and therefore less unserved material remains. The market can still improve yield by separating species-specific skin, bone and oil for premium use. Small coastal operators and an ageing workforce can hold this back. Compact equipment and cooperative pickup can support adoption, but revenue growth will depend more on better value from each tonne than on a major increase in residue volume. Species-specific oils can move closer to omega-3 ingredient applications.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fish waste management market?
Pelagia, ScanBio Marine Group, Biomega Group, Mowi, TripleNine Group, Sopropeche, Aker BioMarine, and Cooke Inc. (operating Omega Protein as a subsidiary) are notable companies operating in this market.
Competition is divided between companies having their own seafood stream and specialists that collect residues from several producers. An integrated processor starts with better control over species and freshness, while a collector can create value by giving smaller sites access to more than one treatment route. Buyers are expected to compare pickup coverage, category approval, oxidation control and feed-safety records before price, because one rejected or delayed load can remove the value created across several collections.
- Integrated marine ingredient platforms: Pelagia, TripleNine Group, Sopropeche, and Omega Protein.
- Seafood by-product recovery specialists: ScanBio Marine Group and Biomega Group.
- Integrated seafood companies generating recoverable by-product streams: Mowi.
Competitive Benchmarking: Fish Waste Management Market
Table 8: Competitive Benchmarking for the Fish Waste Management Market, 2026
| Company | Collection / Recovery Breadth | Value-Added Processing | Feed / Energy Access | Geographic Reach |
|---|---|---|---|---|
| Pelagia | High | High | High | High |
| ScanBio Marine Group | High | Medium | High | Medium |
| Biomega Group | High | High | Medium | Medium |
| Mowi | Medium | Medium | High | High |
| TripleNine Group | High | Medium | High | Medium |
| Sopropeche | Medium | High | Medium | Medium |
| Aker BioMarine | Medium | High | Medium | High |
| Cooke Inc. (Omega Protein) | High | Medium | High | Medium |
Scoring basis: High indicates broad public evidence across the stated capability. Medium indicates a narrower or more regionally concentrated position. Ratings are qualitative and do not represent financial rankings.
- In April 2026, Pelagia published its 2025 annual report and reaffirmed operations across food, feed, and health product streams [6].
- In March 2026, Mowi released its 2025 annual report after reporting 559 thousand tonnes of Atlantic salmon harvest volume [5].
- In March 2026, Aker BioMarine published its 2025 annual report with continued focus on circularity and ocean stewardship. [7]
Key Players in the Fish Waste Management Market
Recovery and Collection Specialists
- ScanBio Marine Group
- Biomega Group
Marine Ingredient Platforms
- Pelagia
- TripleNine Group
- Sopropeche
- Omega Protein
Integrated Seafood and Nutrition Companies
- Mowi
- Aker BioMarine
Fish Waste Management Market - Report Scope
Table 9: Report Scope for the Fish Waste Management Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Waste Source; Application; Processing Method; End User |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from collection, stabilization, treatment, and conversion of fish residues into saleable feed, food, agriculture, bioenergy, and ingredient outputs. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Germany, USA, Norway, France, Canada, UK, Japan, and additional countries |
| Key Companies Covered | Pelagia, ScanBio Marine Group, Biomega Group, Mowi, TripleNine Group, Sopropeche, Aker BioMarine, Omega Protein |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Fish Waste Management Market - Research Methodology
Table 10: Research Methodology for the Fish Waste Management Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with seafood processors, collectors, renderers, feed manufacturers, ingredient producers, waste contractors, and industry experts validate demand, pricing, technology, and purchasing decisions. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public sources support the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess managed residue volumes, service values, conversion yields, application shares, and the 2026 to 2036 forecast. |
| Data Triangulation and Validation | Data is validated against seafood output, feed demand, regulatory conditions, corporate disclosures, and historical trends to reduce double counting across adjacent markets. |
Fish Waste Management Market by Segments
Fish Waste Management Market segmented by Waste Source:
- Fish-Processing Residues
- Aquaculture Mortalities
- Wild-Catch Discards
- Others
Fish Waste Management Market segmented by Application:
- Fish Meal and Animal Feed
- Fish Oil
- Fertilizers
- Bioenergy
- Collagen and Gelatin
- Others
Fish Waste Management Market segmented by Processing Method:
- Rendering
- Ensiling
- Enzymatic Hydrolysis
- Anaerobic Digestion
- Composting
- Others
Fish Waste Management Market segmented by End User:
- Aquafeed Manufacturers
- Pet Food Producers
- Agriculture
- Nutraceuticals and Cosmetics
- Energy Operators
- Others
Fish Waste Management Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Norway
- Spain
- Eastern Europe
- Poland
- Romania
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, June 11). FAO releases the most detailed global assessment of marine fish stocks to date. Official source
- [2] Food and Agriculture Organization of the United Nations. (2025, April). Aquaculture and the circular economy. Committee on Fisheries Sub-Committee on Aquaculture. Official source
- [3] Pelagia. (2026). Corporate operations, sustainability, and marine ingredient platform.
- [4] ScanBio Marine Group. (2026). Ingredients from seafood by-products for feed and bioenergy.
- [5] Mowi ASA. (2026, March 25). Mowi Annual Report 2025.
- [6] Pelagia Holding AS. (2026, April 29). Annual Report 2025.
- [7] Aker BioMarine ASA. (2026, March 26). Annual Report 2025: Sustainable ocean management and circularity.
- [8] Future Market Insights. (2025, March 29). Fish Waste Management Market, 2025 to 2035 edition.
- [9] Government of India, Department of Fisheries. (2025). Annual Report 2024-25. Official source
- [10] The White House. (2025, April 17). Executive Order 14276: Restoring American Seafood Competitiveness. Official source
- [11] Hussain, I. A., & Yasmin, R. (2025). Transforming fish waste for economic and environmental gains. Scientia Review, 1(1), 1-12.
- [12] VALORISH Consortium. (2026). Circular biorefinery pathways for fish-industry by-products.
This bibliography is provided for reader reference and is not exhaustive. The full report contains detailed source records and working papers.
This Report Answers
- How large is the fish waste management market in 2026 and what is forecast for 2036?
- Which processing and circular-economy pressures support demand?
- Why do fish-processing residues lead the waste source category?
- Why does fish meal and animal feed lead application demand?
- How do country growth rates differ across evaluated economies?
- Which companies collect and convert seafood by-products?
- What limits adoption or supplier switching?
- What should buyers evaluate before selecting a recovery partner?
Frequently Asked Questions
How big is the fish waste management market in 2026, and what is forecast for 2036?
Future Market Insights estimates USD 5.8 billion in 2026. The market is projected to reach USD 7.8 billion by 2036.
What is the CAGR from 2026 to 2036?
Future Market Insights projects a 2.9% CAGR over the assessment period.
Which application leads the market?
Fish meal and animal feed are projected to hold 58.6% of application demand in 2026.
Which waste source leads?
Fish-processing residues are forecast to account for 64.2% of waste source volume in 2026.
Which evaluated country has the fastest outlook?
South Korea is projected to register a 3.8% CAGR from 2026 to 2036.
Who are the key players?
Notable participants include Pelagia, ScanBio Marine Group, Biomega Group, Mowi, TripleNine Group, Sopropeche, Aker BioMarine, and Omega Protein.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Waste Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Waste Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Waste Source, 2026 to 2036
- Fish-Processing Residues
- Aquaculture Mortalities
- Wild-Catch Discards
- Others
- Y-o-Y Growth Trend Analysis By Waste Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Waste Source, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Fish Meal and Animal Feed
- Fish Oil
- Fertilizers
- Bioenergy
- Collagen and Gelatin
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Method, 2026 to 2036
- Rendering
- Ensiling
- Enzymatic Hydrolysis
- Anaerobic Digestion
- Composting
- Others
- Y-o-Y Growth Trend Analysis By Processing Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Method, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Aquafeed Manufacturers
- Pet Food Producers
- Agriculture
- Nutraceuticals and Cosmetics
- Energy Operators
- Others
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Norway
- Spain
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Romania
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- By Waste Source
- By Application
- By Processing Method
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Source
- By Application
- By Processing Method
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- Norway
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Source
- By Application
- By Processing Method
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Waste Source
- By Application
- By Processing Method
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pelagia
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ScanBio Marine Group
- Biomega Group
- Mowi
- TripleNine Group
- Sopropeche
- Aker BioMarine
- Omega Protein
- Pelagia
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


