

- Market Size (2026)
- USD 42.0 Bn
- Forecast (2036)
- USD 71.1 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Food Waste Management Market in 2026?
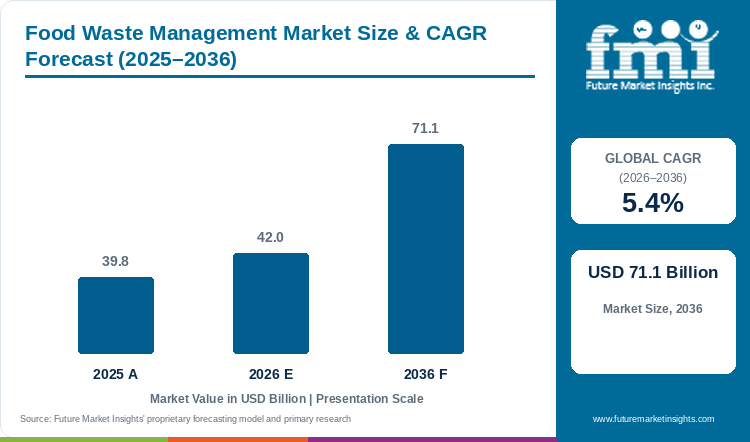
Sales in the food waste management market are projected to grow at 5.4% CAGR, with the market size rising from USD 39.8 Billion in 2025 to USD 42.0 Billion in 2026 and reaching USD 71.1 Billion by 2036.
Diverting commercial organic discards away from municipal landfills has become a financial necessity for food factories and grocery chains facing rising tipping surcharges and methane penalties. Survey updates published by the United States Environmental Protection Agency in August 2026 confirmed that food-waste anaerobic digestion plants processed over nineteen million tons of segregated organics annually for renewable power and gas [1]. Market valuation advances from USD 39.8 Billion in 2025 to USD 42.0 Billion in 2026 and is projected to reach USD 71.1 Billion by 2036, recording a 5.4% CAGR and USD 29.1 Billion in ten-year expansion. Cereals and grains hold 32.6% of waste type volume in 2026 as starch-rich bakery byproducts accelerate biogas yields inside sealed digesters. Furthermore, service contracts in integrated waste management increasingly bundle route hauling with mechanical depackaging, though plastic film contamination still pressures plant margins.
Key Market Trends & Insights
- By waste type: With a 32.6% share in 2026, cereals and grains led the category through continuous bakery byproduct volumes and high methane yields in commercial digesters.
- By process / method: Anaerobic digestion and biogas represented 42.1% of revenue in 2026, supported by utility demand for pipeline-injected renewable natural gas and digestate fertilizer.
- By source / origin: Food processing and manufacturing accounted for 44.2% of volume in 2026, because industrial processing lines generate segregated organic waste streams at single plant gates.
- By application: Renewable energy and biofuels held the leading share of 38.5% in 2026, underpinned by clean fuel feed-in tariffs and industrial decarbonization contracts.
Regional Highlights
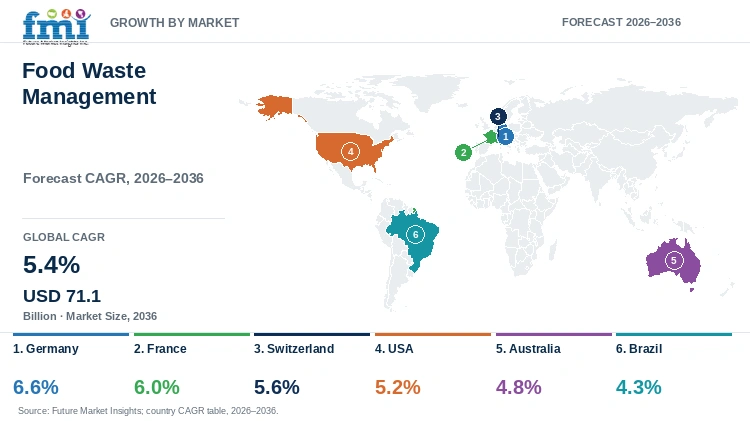
- Fastest-growing evaluated country: Germany, at 6.6% CAGR from 2026 to 2036.
- By country: France at 6.0%, Switzerland at 5.6%, and the USA at 5.2% follow, while Brazil records the lowest evaluated CAGR at 4.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Food Waste Management Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 39.8 Billion |
| Estimated Market Size in 2026 | USD 42.0 Billion |
| Projected Market Size by 2036 | USD 71.1 Billion |
| CAGR, 2026 to 2036 | 5.4% |
| Added Revenue, 2026 to 2036 | USD 29.1 Billion |
German, French, and California biogas plants encounter severe pump wear and digester grit accumulation whenever supermarket and catering food discards arrive mixed with plastic film wraps and metal clips. Unsorted packaging fragments jam progressive cavity pumps and disqualify finished digestate from agricultural land application under European Union and state soil rules. Technical platform updates from the Food and Agriculture Organization in September 2026 reported that post-harvest and retail food losses still exceed thirteen percent of global production, prompting municipal authorities to mandate front-end mechanical separation before biological treatment [2]. Bioprocessing operators are therefore pairing high-torque hammermill depackagers with packaging waste recycling sorting lines to strip polymers out of wet organic slurries.
Municipal Food Waste Generation and Bio-Processing Capacity Sizing
Table 2: Municipal Food Waste Generation and Bio-Processing Capacity Sizing for the Food Waste Management Market (USD Billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 39.8 | 42.0 | 71.1 |
| Commercial food waste treated (million metric tons) | 480 to 520 | 505 to 550 | 850 to 920 |
| Biogas energy yield (billion cubic meters) | 38.4 to 41.6 | 40.4 to 44.0 | 68.0 to 73.6 |
| Average tipping fee realization per metric ton (USD) | 78.5 to 84.0 | 80.2 to 86.5 | 98.4 to 105.0 |
Calculation basis: Throughput ranges combine municipal separate-collection registries and industrial food-processing discard tonnage with weighted regional gate tipping fees.
Per Capita Generation and Processing Expenditure Indicators
Metropolitan waste authorities and multi-site grocery chains rely on centralized digestion and composting plants to keep wet kitchen scraps out of municipal landfills. Rising landfill gate surcharges encourage haulers to build regional transfer and depackaging stations close to urban food corridors. Coordinating organic bin pickups with municipal solid waste handling routes also helps commercial food factories pass third-party zero-waste audits.
Table 3: Per Capita and Municipal Spending Indicators for the Food Waste Management Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 4.84 | 5.06 | 7.94 |
| Spend per 1,000 people (USD) | 4,835.9 | 5,060.2 | 7,944.1 |
| Commercial food manufacturing facility annual spend (USD thousand) | 42.5 to 48.0 | 44.2 to 50.5 | 68.0 to 75.0 |
Table 4: Facility & Industrial Processing Sizing Indicators for the Food Waste Management Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 42.0 Billion | Report value |
| Licensed bioprocessing and digestion plants worldwide | 18.5 thousand | 2024 industrial census |
| Average annual revenue per processing facility | USD 2.27 Million | Calculated average |
| Food processing source revenue, 2026 | USD 18.56 Billion | 44.2% share |
Analyst Perspective
"Mandatory landfill diversion laws and corporate biomethane off-take contracts are converting segregated food residues into high-yield bio-refinery feedstocks. Mixed plastic packaging contamination and volatile tipping fees still require operators to install automated depackaging lines before anaerobic digestion."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the food waste management market segmented?
The food waste management market is segmented by waste type, process / method, source / origin, and application. In 2026, Cereals & Grains is projected at 32.6%, anaerobic digestion & biogas at 42.1%, food processing & manufacturing at 44.2%, and renewable energy & biofuels at 38.5%.
By waste type: Cereals and grains, fruits and vegetables, dairy and meat products, and fish and seafood.
By process / method: Anaerobic digestion and biogas, composting and soil enrichment, incineration and gasification, and animal feed conversion.
By source / origin: Food processing and manufacturing, food service and hospitality, retail and wholesale, and municipal and residential.
By application: Renewable energy and biofuels, agricultural fertilizer, animal feed and pet food, and biochemical extraction.
Why do Cereals & Grains lead the waste type category?
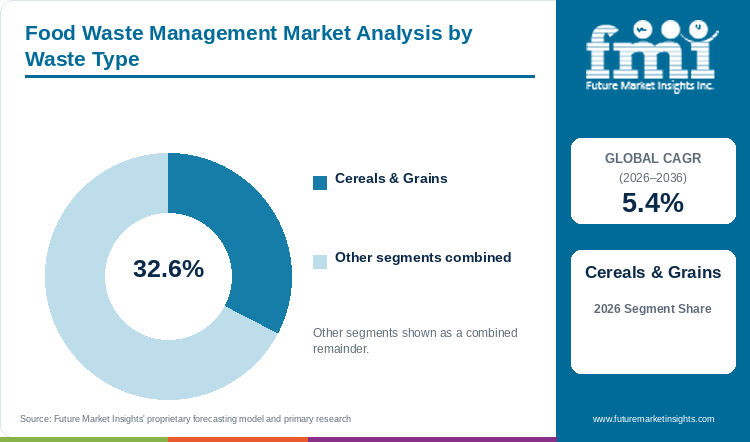
With an estimated 32.6% share in 2026, cereals and grains lead the waste type category, reflecting high starch methane yields.
Table 5: Waste Type Share for the Food Waste Management Market (percentage share), 2026
| Waste Type | Share (2026) |
|---|---|
| Cereals & Grains | 32.6% |
| Other Segments Combined | 67.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Waste Type Leadership and Market Growth for the Food Waste Management Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Leading Segment | Cereals & Grains |
Bioprocess engineers favor cereal and grain discard streams because uniform carbohydrate concentrations accelerate methanogenic fermentation without souring digester pH levels. Spent brewer's grain, industrial bakery trimmings, and flour milling hulls provide predictable carbon-to-nitrogen ratios that raise gas output per dry ton compared with high-moisture vegetable scraps. Owing to their dry matter stability, clean grain byproducts are also channeled into upcycled products from food waste and animal feed rations. Seasonal moisture swings in collected bakery dough still require slurry dilution control at plant intake.
- Cereals and grains represent 32.6% of waste type volume in 2026, bolstered by year-round byproduct generation from commercial bakeries, breweries, and grain mills.
- United Nations Environment Programme SDG 12.3 food waste index findings released in November 2025 confirmed that starch-rich cereal and baking residues provide the highest commercial recovery yield among organic substrates [3].
Why does Anaerobic Digestion & Biogas define the largest process category?
By processing method, anaerobic digestion and biogas is set to capture 42.1% in 2026, propelled by utility biomethane off-take agreements.
Sealed anaerobic digestion vessels attract the largest share of capital investment because operators monetize both pipeline gas sales and nutrient-rich digestate fertilizer alongside gate tipping fees. Whereas open windrow composting triggers municipal odor complaints and yields low-value mulch, continuous stirred-tank reactors capture fugitive methane inside an enclosed loop. Expanding commercial biogas generation also allows industrial food parks to offset factory boiler fuel purchases. Multi-year feedstock tonnage guarantees are still required before banks finance new digester builds.
- Anaerobic digestion and biogas accounts for 42.1% of processing method revenue in 2026, stimulated by utility power purchase agreements and biomethane grid-injection incentives.
- European Environment Agency bio-waste briefings published in April 2025 showed that anaerobic digestion and biological treatment capacity across member states expanded to meet mandatory municipal organics recycling targets [4].
What keeps Food Processing & Manufacturing ahead by source origin?
Food processing and manufacturing is anticipated to contribute 44.2% of source origin volume in 2026, enabled by uniform factory byproduct streams.
Cannery peelings, dairy whey effluents, and meatpacking offal accumulate in segregated, single-origin truckloads at factory loading docks, making industrial food plants the most economical feedstock source. While residential curbside bins require optical sorting to remove glass and plastic wrappers, factory byproduct streams enter digestion tanks or mechanized compost turning machines with minimal pre-screening. Multinational food producers also sign multi-year off-take agreements with licensed bio-recyclers to maintain zero-waste facility certifications.
- Food processing and manufacturing holds 44.2% of source origin volume in 2026, aided by uncontaminated, high-tonnage organic byproduct streams at factory gates.
- Reviews from Germany's Federal Ministry for the Environment, Nature Conservation, Nuclear Safety and Consumer Protection in May 2025 indicated that commercial food manufacturing plants achieved over eighty-five percent biological recovery compliance [5].
What gives Renewable Energy & Biofuels the leading position in application?
Renewable energy and biofuels is expected to retain 38.5% of application revenue in 2026, linked to low-carbon transport fuel mandates.
Upgraded renewable natural gas and combined-heat-and-power electricity command substantially higher market realizations than bulk agricultural compost, keeping energy recovery at the top of the application mix. Municipal transit fleets and long-haul logistics carriers buy compressed biomethane refined from fermented food slurry to cut fleet carbon intensity without replacing heavy-duty engines. Investments in membrane pipeline biomethane upgrading enable digestion plants to inject purified gas directly into national transmission grids.
- Renewable energy and biofuels captures 38.5% of application revenue in 2026, promoted by clean fuel standard credits and utility biomethane off-take contracts.
- Veolia Environnement S.A. inaugurated a regional biomethane refining complex in June 2026 capable of converting 300,000 metric tons of industrial food residues annually into grid-grade gas [6].
What are the drivers, restraints, and opportunities in the food waste management market?
Landfill diversion legislation accelerates commercial processing, while packaging contamination raises pre-treatment costs, and insect-derived protein creates high-value markets.
- Driver: Statutory landfill bans and municipal organic waste diversion targets compel food processors and commercial catering networks to outsource organic recycling.
- Restraint: Packaging film and microplastic contamination in municipal organics elevate mechanical sorting expenses and cause operational wear in anaerobic digestion lines.
- Opportunity: Upcycling nutrient-rich food discards into black soldier fly insect biomass generates valuable protein meal and lipid oils for animal feed formulations.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Municipal and state governments are steadily outlawing the disposal of commercial food scraps in untreated landfills to curb fugitive methane emissions. Supermarkets, hospital cafeterias, and food factories subject to mandatory organics diversion rules must contract with licensed bio-recyclers or pay per-ton non-compliance fines. Haulers are installing bin-level smart waste tracking systems on collection trucks to log verified diversion weights for corporate ESG audits. Sectoral waste evaluations published by NITI Aayog in February 2026 showed that urban local bodies expanding biomethanation and source-segregated wet waste collection achieved substantial reductions in municipal landfill loading [7]. Operators still need odor-sealed transfer stations and dependable pickup schedules before commercial kitchens commit to multi-year contracts.
Risk Assessment of the Food Waste Management Market: Operational and Formulation Friction
Plastic packaging film, metal twist-ties, and glass shards mixed into post-consumer food waste create severe mechanical bottlenecks that inflate operating expenses at bioprocessing plants. When unsorted supermarket and restaurant discards enter anaerobic digesters, flexible film wraps around mixer shafts and abrasive grit wears down progressive cavity pumps. Operational audits published by the International Solid Waste Association in May 2025 demonstrated that high packaging contamination in municipal food waste streams increases mechanical pre-treatment and residue disposal costs by twenty-eight percent [8]. Furthermore, microplastic fragments in finished digestate cause agricultural regulators to reject land application, forcing plant operators to pay hazardous landfill tipping fees for rejected cake.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Traditional windrow composting sells for modest bulk soil-amendment prices that barely cover urban hauling costs. Cultivating black soldier fly larvae and extracting volatile fatty acids from homogeneous pre-consumer food byproducts allows biotechnology operators to unlock much higher revenue per ton. Insect bioconversion turns brewery grains and bakery dough into concentrated protein meal and lauric-acid lipids used in insect-based pet nutrition and aquaculture rations. Covanta Holding Corporation expanded commercial organics separation and bioconversion partnerships in April 2026 to extract higher-value industrial feedstocks from pre-sorted commercial food streams [9]. Processors must secure uncontaminated, single-source food factory inputs to satisfy feed-grade safety rules.
Food Waste Management Market by Country (2026 to 2036)
Statutory landfill bans, municipal biowaste bin coverage, and grid biomethane tariffs set the pace of country-level expansion between 2026 and 2036. An FMI analyst notes that Germany records the fastest growth among the profiled markets at a 6.6% CAGR and France follows at 6.0%, while Switzerland (5.6%) and the United States (5.2%) outpace Australia (4.8%) and Brazil (4.3%). Where European utilities focus on optical plastic removal to meet strict soil digestate thresholds, Latin American operators generate most of their volume from captive agro-industrial sugar, citrus, and meatpacking residues.
Table 7: Country CAGR and Primary Growth Levers for the Food Waste Management Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 6.6% | Kreislaufwirtschaftsgesetz organics recycling mandates and strict Biotonne plastic limits |
| France | 6.0% | AGEC anti-waste source-sorting obligations for commercial kitchens and micro-methanization |
| Switzerland | 5.6% | Complete municipal landfill bans and enclosed urban fermentation plant upgrades |
| USA | 5.2% | State-level commercial organics landfill bans and utility renewable natural gas credits |
| Australia | 4.8% | National Food Waste Strategy targets and municipal FOGO kerbside collection expansion |
| Brazil | 4.3% | Agro-industrial sugarcane and slaughterhouse residue biomethane co-digestion |
Source: Future Market Insights analysis
Germany Food Waste Management Market Outlook (2026 to 2036)
Strict enforcement of the amended German Bio-waste Ordinance (BioAbfV) sets Germany apart from volume-driven emerging markets by shifting investment toward optical contaminant detection and high-purity biomethane refining. Nationwide separate organic collection bins (Biotonne) already capture millions of tons of kitchen and catering scraps, yet new rules cap foreign plastic impurities in incoming biowaste at under one percent. Germany is forecast to emerge as a high-growth market, registering 6.6% CAGR through 2036 on the strength of municipal digester retrofits and biomethane grid-injection tariffs. Waste management statistics from Germany's Federal Statistical Office (Destatis) in September 2025 showed that municipal biowaste treatment plants processed over fourteen million metric tons of separately collected organics [10]. Operators meet strict soil fertilizer thresholds by installing AI camera sorters on collection trucks and multi-stage hydro-pulpers at plant gates.
Key takeaway: Stringent German BioAbfV foreign-matter limits and biomethane grid tariffs drive capital upgrades in automated optical sorting and hydro-pulping lines.
France Food Waste Management Market Outlook (2026 to 2036)
In France, demand for food waste management is predicted to advance at 6.0% CAGR through 2036, propelled by full implementation of the AGEC anti-waste law requiring every restaurant, grocer, and household to segregate bio-waste at source. Commercial foodservice operators face compliance fines if wet kitchen scraps are mixed into general residual refuse containers. Compliance audits conducted by the French Agency for Ecological Transition (ADEME) in July 2025 noted a sharp increase in municipal and commercial bio-waste sorting contracts across metropolitan departments [11]. However, narrow historic streets in dense city centers and dispersed rural bistro routes complicate heavy truck collection. French waste contractors overcome route friction by using compact natural-gas collection vans that feed decentralized agricultural co-digestion plants.
Key takeaway: Mandatory French AGEC bio-waste sorting rules across catering and retail sites fuel steady demand for urban collection routing and farm co-digestion.
Switzerland Food Waste Management Market Outlook (2026 to 2036)
Decades-long bans on direct organic landfilling and high civic sorting participation give Switzerland one of Europe's highest per-capita biowaste recovery rates, focusing market growth on odor-free urban fermentation and nutrient loop closure. Revenue from food waste treatment services in Switzerland is projected to rise at 5.6% CAGR over the assessment period, backed by high pay-as-you-throw municipal refuse bag taxes that incentivize residents and hotels to separate kitchen scraps. Waste resource reviews from the Swiss Federal Office for the Environment (FOEN) in August 2025 confirmed that cantonal fermentation and composting facilities recovered phosphorus and biogas from the vast majority of collected municipal green and kitchen waste [12]. Because strict alpine air-quality and odor ordinances restrict open composting near towns, Swiss operators construct negative-pressure enclosed digestion halls fitted with woody bio-filters.
Key takeaway: High Swiss municipal bag taxes and strict cantonal odor rules channel investment into fully enclosed, negative-pressure urban fermentation plants.
USA Food Waste Management Market Outlook (2026 to 2036)
The outlook for commercial organics recovery in the USA remains strong, with service revenue projected to increase at 5.2% CAGR through 2036 amid state-level organic landfill bans in California, Massachusetts, New York, and Washington. Supermarkets and food manufacturers in regulated coastal states must contract with certified organics haulers or face municipal enforcement penalties. Updated Wasted Food Scale guidance issued by the U.S. Environmental Protection Agency in September 2026 prioritized anaerobic digestion with beneficial soil digestate use over landfilling and wastewater sewering [13]. Nonetheless, low landfill tipping fees across interior Midwestern and Southern states slow voluntary municipal collection rollouts. Private equity-backed operators bypass municipal inertia by signing direct off-take contracts with large beverage, dairy, and bakery plants to generate high-value transportation fuel credits.
Key takeaway: State-level commercial organics bans and federal renewable fuel credits in the USA drive private investment into industrial food-factory digesters.
Australia Food Waste Management Market Outlook (2026 to 2036)
Food waste management adoption across Australia is anticipated to register 4.8% CAGR during the forecast period, aided by rising state landfill levies in New South Wales and Victoria and municipal Food Organics and Garden Organics (FOGO) kerbside rollouts. Federal targets to halve food waste by 2030 push metropolitan councils and supermarket chains to divert perishable food trimmings away from metropolitan landfills. Feasibility assessments from Australia's Department of Climate Change, Energy, the Environment and Water in November 2025 reported expanding FOGO processing capacity across suburban composting and digestion hubs [14]. However, long hauling distances between coastal cities and inland agricultural districts raise freight costs for bulk compost. Australian processors address transport economics by deploying modular on-site depackagers and granulating digestate into concentrated pelleted soil conditioners.
Key takeaway: Escalating Australian state landfill levies and municipal FOGO kerbside bin rollouts sustain public-private investment in regional organics processing.
Brazil Food Waste Management Market Outlook (2026 to 2036)
The Brazil market is predicted to witness 4.3% CAGR through 2036, stemming from large-scale agro-industrial residue valorization across citrus juice, sugar-ethanol, and meatpacking complexes rather than residential curbside sorting. While municipal solid waste budgets in smaller Brazilian towns remain constrained and reliant on mixed landfilling, export-oriented agribusinesses generate massive, uncontaminated organic streams at single industrial sites. National Solid Waste Policy updates from Brazil's Ministry of the Environment and Climate Change (MMA) in December 2025 expanded incentives supporting biomethane production from agro-industrial and urban wholesale food market (CEASA) residues [15]. Waste service firms capture reliable returns in Brazil by building captive on-site anaerobic digesters that supply both boiler power and biomethane fuel for agro-industrial truck fleets.
Key takeaway: Captive biomethane digesters at large Brazilian citrus, meatpacking, and wholesale food hubs lead commercial growth ahead of municipal residential sorting.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the food waste management market?
Veolia Environnement S.A., Waste Management Inc., Republic Services Inc., Clean Harbors Inc., Covanta Holding Corporation, Remondis SE & Co. KG, Suez S.A., and FCC Environment are the significant market players in this market.
Contract retention in commercial organics recovery turns on route collection density, front-end mechanical depackaging, and guaranteed downstream outlets for gas and digestate. Integrated environmental utilities led by Veolia Environnement S.A., Waste Management Inc., and Republic Services Inc. pair municipal collection fleets with utility-scale anaerobic digesters and landfill gas networks. Industrial service contractors such as Clean Harbors Inc., Covanta Holding Corporation, and Remondis SE & Co. KG handle liquid food factory effluents and packaged grocery recalls. Alongside them, Suez S.A. and FCC Environment operate municipal biowaste fermentation plants linked to organic fertilizer production for regional farming cooperatives.
- Global Integrated Waste Utilities: Veolia Environnement S.A., Waste Management Inc., and Republic Services Inc. operate broad commercial collection fleets and multi-site anaerobic digestion hubs.
- Dedicated Environmental Service Providers: Clean Harbors Inc., Covanta Holding Corporation, and Remondis SE & Co. KG manage industrial food-byproduct depackaging and energy recovery.
- Regional Circular Economy Specialists: Suez S.A. and FCC Environment run municipal bio-waste fermentation plants and agricultural digestate valorization programs.
Competitive Benchmarking: Food Waste Management Market
Table 8: Competitive Benchmarking for the Food Waste Management Market (qualitative capability ratings), 2026
| Company | Bioprocessing Facility Capacity | Mechanical Depackaging Depth | Municipal Concession Access | Geographic Reach |
|---|---|---|---|---|
| Veolia Environnement S.A. | High | High | High | High |
| Waste Management Inc. | High | High | High | Medium |
| Republic Services Inc. | High | Medium | High | Medium |
| Clean Harbors Inc. | High | High | Medium | Medium |
| Covanta Holding Corporation | Medium | Medium | High | Medium |
| Remondis SE & Co. KG | High | High | High | Medium |
| Suez S.A. | High | High | High | High |
| FCC Environment | Medium | High | High | Medium |
Scoring basis: Evaluations reflect audited digester intake tonnage, front-end contaminant removal hardware, and public tender holdings. Operators managing over 500,000 metric tons of annual biological treatment capacity with automated hydro-pulping lines score High in facility and depackaging depth.
Key Developments in the Food Waste Management Market
- In March 2026, Veolia Environnement S.A. commissioned an upgraded biomethane anaerobic digestion plant in France treating 150,000 metric tons of commercial food residues annually [16].
- In January 2026, Waste Management Inc. completed an expansion of its California organics recycling and depackaging network to process supermarket and restaurant food scraps [17].
- In November 2025, Clean Harbors Inc. acquired a regional industrial organics recycling operator in the U.S. Midwest, adding three commercial depackaging and composting sites [18].
- In August 2025, Republic Services Inc. partnered with renewable energy developers to construct two pipeline-grade biomethane upgrading plants linked to municipal organic waste streams [19].
Key Players in the Food Waste Management Market
Global Integrated Waste Utilities
- Veolia Environnement S.A.
- Waste Management Inc.
- Republic Services Inc.
Dedicated Environmental Service Providers
- Clean Harbors Inc.
- Covanta Holding Corporation
- Remondis SE & Co. KG
Regional Circular Economy Specialists
- Suez S.A.
- FCC Environment
Food Waste Management Market - Report Scope
Table 9: Report Scope for the Food Waste Management Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Waste Type; Process / Method; Source / Origin; Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial operator and utility revenue from organized collection, depackaging, anaerobic digestion, composting, and recovery of food-derived organic waste. Excludes non-food dry recyclables and standalone equipment sales outside service contracts. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany, France, Switzerland, USA, Australia, Brazil, and additional countries in the full report |
| Key Companies Covered | Veolia Environnement S.A., Waste Management Inc., Republic Services Inc., Clean Harbors Inc., Covanta Holding Corporation, Remondis SE & Co. KG, Suez S.A., FCC Environment |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Food Waste Management Market - Research Methodology
Table 10: Research Methodology for the Food Waste Management Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with municipal solid waste directors, anaerobic digestion plant managers, corporate food-processor sustainability heads, and depackaging equipment engineers. |
| Secondary Research | Secondary research synthesized EPA, FAO, UNEP, and Destatis waste registries, municipal tipping fee schedules, state organics diversion statutes, and corporate sustainability disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined commercial organic waste tonnage flows with regional tipping fees and biomethane/digestate recovery realizations. |
| Data Triangulation and Validation | Estimates were validated against licensed digester and composting facility capacities, municipal separate-collection volumes, and corporate revenue disclosures. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's environmental circularity econometric model, calibrating evaluated national growth rates against the 5.4% global baseline through verified municipal organic diversion mandates, landfill tipping taxes, and commercial anaerobic digestion subsidies. |
| Operational Benchmark Traceability | Operational benchmarks (commercial food waste treated tonnages, biogas yield per ton, and pipeline biomethane upgrading efficiency) represent modeled estimates synthesized from UNEP Food Waste Index reports, EPA anaerobic digestion surveys, FAO platform bulletins, and commercial waste processor disclosures. |
Food Waste Management Market by Segments
Food Waste Management Market segmented by Waste Type:
- Cereals & Grains
- Fruits & Vegetables
- Dairy & Meat Products
- Fish & Seafood
Food Waste Management Market segmented by Process / Method:
- Anaerobic Digestion & Biogas
- Composting & Soil Enrichment
- Incineration & Gasification
- Animal Feed Conversion
Food Waste Management Market segmented by Source / Origin:
- Food Processing & Manufacturing
- Food Service & Hospitality
- Retail & Wholesale
- Municipal & Residential
Food Waste Management Market segmented by Application:
- Renewable Energy & Biofuels
- Agricultural Fertilizer
- Animal Feed & Pet Food
- Biochemical Extraction
Food Waste Management Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Turkiye
Research Sources and Bibliography
- [1] Office of Resource Conservation and Recovery. (2026, August 04). Anaerobic Digestion Facilities Processing Food Waste in the United States. U.S. Environmental Protection Agency.
- [2] Food and Agriculture Organization of the United Nations. (2026, October 09). Technical Platform on the Measurement and Reduction of Food Loss and Waste. FAO Agricultural Bulletins.
- [3] United Nations Environment Programme. (2025, November 08). SDG 12.3 Food Waste Index Circular Economy Report. UNEP Technical Monographs.
- [4] European Environment Agency. (2025, April 20). Bio-Waste in Europe: Transforming Municipal Organic Residues into Renewable Energy and Digestate. EEA Briefing No. 08/2025.
- [5] Federal Ministry for the Environment, Nature Conservation, Nuclear Safety and Consumer Protection (BMUV). (2025, May 22). National Circular Economy Strategy: Commercial Organic Waste Diversion Compliance. BMUV Technical Reports.
- [6] Veolia Environnement S.A. (2026, June 18). Inauguration of Regional Biomethane Facility Converting Industrial Food Residues into Grid Energy. Corporate Press Release.
- [7] NITI Aayog. (2026, February 14). Sectoral Insights on Urban Wet Waste Biomethanation and Organics Recovery. Government of India Policy Reports.
- [8] International Solid Waste Association (ISWA). (2025, May 15). Operational Optimization and Depackaging Efficiency in Commercial Anaerobic Digestion Plants. Waste Management & Research, 43(5), 412-428.
- [9] Covanta Holding Corporation. (2026, April 05). Commercial Organics Separation and Bioconversion Partnerships for Industrial Food Streams. Corporate Whitepaper.
- [10] Federal Statistical Office (Destatis). (2025, September 10). Waste Management Statistics: Collection and Treatment of Municipal Biowaste in Germany. Statistisches Bundesamt.
- [11] French Agency for Ecological Transition (ADEME). (2025, July 16). Organic Waste Sorting Mandates Under the AGEC Law: Commercial Catering Compliance Review. ADEME Technical Reports.
- [12] Federal Office for the Environment (FOEN). (2025, August 25). Waste and Resources Review: Fermentation and Phosphorus Recovery of Municipal Food Waste in Switzerland. FOEN Environment Monographs.
- [13] Office of Resource Conservation and Recovery. (2026, September 16). Sustainable Management of Food: Wasted Food Scale and Diversion Pathways. U.S. Environmental Protection Agency.
- [14] Department of Climate Change, Energy, the Environment and Water. (2025, November 18). National Food Waste Strategy Feasibility Assessment and FOGO Processing Capacity. Commonwealth of Australia.
- [15] Ministry of the Environment and Climate Change (MMA). (2025, December 12). National Solid Waste Policy: Agro-Industrial Organic Residue Valorization and Biomethane Production in Brazil. Government of Brazil.
- [16] Veolia Environnement S.A. (2026, March 26). Commissioning of Upgraded Biomethane Anaerobic Digestion Plant for Commercial Food Waste in France. Environmental Business Review.
- [17] Waste Management Inc. (2026, January 14). Expansion of California Organics Recycling and Automated Depackaging Capacity. Corporate Update.
- [18] Clean Harbors Inc. (2025, November 08). Strategic Acquisition of Midwest Industrial Organics Recycling and Composting Operations. Investor Press Release.
- [19] Republic Services Inc. (2025, August 19). Joint Development of Pipeline-Quality Renewable Natural Gas Upgrading Facilities. Renewable Fuel Bulletin.
- [20] Remondis SE & Co. KG. (2025, October 22). Optical Sorting and Hydro-Pulping Plant Upgrades Across German Biowaste Facilities. Waste Management Review.
- [21] Suez S.A. (2026, February 11). Closed-Loop Organic Resource Recovery Contracts for Retail Grocery and Food Processing Chains. Industrial Sector Monograph.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food waste management market in 2026 and what is forecast for 2036?
- Which environmental and statutory regulations support demand for food waste management?
- Why do cereals and grains lead the waste type category?
- Why does anaerobic digestion lead the processing method category globally?
- How do growth rates prominently differ across Germany, France, Switzerland, and the USA?
- Which leading companies supply relevant commercial organics recycling services today?
- What limits adoption or facility processing efficiency in the food waste management market?
- What should municipal procurement officers evaluate deeply before contracting with a commercial waste processor?
Frequently Asked Questions
How big is the food waste management market in 2026, and what is forecast for 2036?
Commercial food waste management revenues reach an estimated USD 42.0 Billion in 2026 and are projected to climb to USD 71.1 Billion by 2036 as cities and food factories phase out untreated organic landfilling.
What is the CAGR for the food waste management market from 2026 to 2036?
According to FMI, global service turnover will advance at a 5.4% CAGR through 2036, propelled by mandatory organics diversion statutes and utility biomethane off-take contracts.
Which waste type segment leads the food waste management market?
Cereals & Grains hold 32.6% of waste type volume in 2026 because bakery, brewery, and milling residues supply uniform starch density that maximizes methane output inside sealed digesters.
Which processing method leads the food waste management market?
Anaerobic digestion & biogas captures 42.1% of processing method revenue in 2026 by generating dual income streams from grid-injected renewable natural gas and nutrient-rich digestate cake.
Which country has a notable growth outlook during the assessment period?
FMI research indicates that Germany will pace the evaluated countries at a 6.6% CAGR from 2026 to 2036, driven by nationwide Biotonne separate collection and strict BioAbfV plastic purity rules.
Who are the key players in the market?
Veolia Environnement S.A., Waste Management Inc., Republic Services Inc., Clean Harbors Inc., Covanta Holding Corporation, Remondis SE & Co. KG, Suez S.A., and FCC Environment lead commercial operations across hauling, depackaging, and anaerobic digestion.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Waste Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Waste Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Waste Type, 2026 to 2036
- Cereals & Grains
- Fruits & Vegetables
- Dairy & Meat Products
- Fish & Seafood
- Y-o-Y Growth Trend Analysis By Waste Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Waste Type, 2026 to 2036
- Global Market Analysis and Forecast, By Process / Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Process / Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Process / Method, 2026 to 2036
- Anaerobic Digestion & Biogas
- Composting & Soil Enrichment
- Incineration & Gasification
- Animal Feed Conversion
- Y-o-Y Growth Trend Analysis By Process / Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Process / Method, 2026 to 2036
- Global Market Analysis and Forecast, By Source / Origin, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source / Origin, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source / Origin, 2026 to 2036
- Food Processing & Manufacturing
- Food Service & Hospitality
- Retail & Wholesale
- Municipal & Residential
- Y-o-Y Growth Trend Analysis By Source / Origin, 2021 to 2025
- Absolute $ Opportunity Analysis By Source / Origin, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Renewable Energy & Biofuels
- Agricultural Fertilizer
- Animal Feed & Pet Food
- Biochemical Extraction
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Turkiye
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Waste Type
- By Process / Method
- By Source / Origin
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Veolia Environnement S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Waste Management Inc.
- Republic Services Inc.
- Clean Harbors Inc.
- Covanta Holding Corporation
- Remondis SE & Co. KG
- Suez S.A.
- FCC Environment
- Veolia Environnement S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


