

- Market Size (2026)
- USD 16.5 Bn
- Forecast (2036)
- USD 31.9 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Grass Fed Beef Market in 2026?
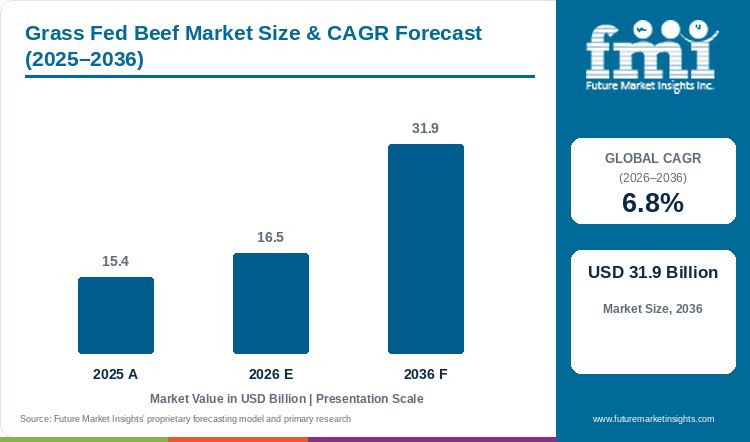
Sales in the grass fed beef market are projected to grow at 6.8% CAGR through 2036. Market size rises from USD 15.4 billion in 2025 to USD 16.5 billion in 2026 and is expected to reach USD 31.9 billion by 2036.
Meatpackers and supermarket chains are locking in multi-year off-take agreements with pasture-finishing ranches as shoppers move away from grain-lot beef and prophylactic feedlot antibiotics. According to FMI, the global grass fed beef market stands at USD 15.4 billion in 2025, reaches USD 16.5 billion in 2026, and is projected to attain USD 31.9 billion by 2036 at a 6.8% CAGR over the 2026 to 2036 period. This expansion generates USD 15.4 billion in added revenue as certified organic beef and forage-finished primal cuts gain wider shelf space in modern supermarkets. In May 2025, the United States Department of Agriculture Economic Research Service documented that tighter domestic cattle inventories and rising consumer preference for pasture-raised cuts pushed retail specialty beef realizations up 13% year-on-year [1]. Fresh chilled cuts and fillets hold 43.2% share in 2026 because high-barrier vacuum packaging preserves steak tenderness, although winter forage dormancy still slows herd turnover.
Key Market Trends & Insights
- By product form: Fresh chilled cuts & fillets led with 43.2% share in 2026, supported by vacuum-skin aging that preserves natural intramuscular moisture and butcher-case visual appeal.
- By species / source: Wild capture marine fishery accounted for 55.8% in 2026, serving as the macro natural-protein harvesting benchmark alongside livestock pasture raised production.
- By end-use sector: Food service & restaurants held 43.4% of revenue in 2026, as fine-dining steakhouses and chef-driven burger bistros specify single-origin pasture-finished primal cuts.
Regional Highlights
- Fastest-growing evaluated country: Germany, at 8.3% CAGR from 2026 to 2036.
- By country: France at 7.6%, Switzerland at 7.1%, and the USA at 6.5% follow, while Brazil records the lowest evaluated CAGR at 5.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Grass Fed Beef Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 15.4 billion |
| Estimated Market Size in 2026 | USD 16.5 billion |
| Projected Market Size by 2036 | USD 31.9 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 15.4 billion |
Adoption develops differently across countries because pasture carrying capacity, winter silage storage, and carcass grading standards vary sharply between temperate and tropical cattle regions. FMI research indicates that meat processors face seasonal supply gaps when late-summer droughts or winter freezes reduce forage energy density on open rangeland. In February 2025, the Food and Agriculture Organization Livestock Division reported that forage-finished beef operations require 24 to 28 months to reach target slaughter weight compared with 15 to 18 months in grain feedlots, while drought-related hay purchases raised pasture finishing costs by 22% [2]. To bridge seasonal slaughter dips, packers combine Southern Hemisphere chilled imports with high-barrier fresh meat packaging that extends wet-aged primal shelf life to 45 days.
Pasture Finishing and Carcass Fabrication Batch Sizing
Table 2: Pasture Finishing and Carcass Fabrication Batch Sizing for the Grass Fed Beef Market (USD billion and production units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 15.4 | 16.5 | 31.9 |
| Finished cattle slaughter volume (million head) | 8.8 to 9.5 | 9.4 to 10.2 | 18.2 to 19.6 |
| Commercial boneless beef production (million metric tons) | 2.2 to 2.4 | 2.4 to 2.6 | 4.6 to 4.9 |
| Wholesale realization per carcass hundredweight (USD) | 365.0 to 385.0 | 370.0 to 392.0 | 440.0 to 468.0 |
Analytical note: Production ranges reflect commercial 600-pound average dressed carcass weights from certified forage-fed cattle across audited abattoirs.
Per Capita Consumption and Retail Channel Sizing
Household buyers following high-protein and clean-label diets increasingly select pasture-finished beef for its higher omega-3 to omega-6 fatty acid ratio and conjugated linoleic acid content. Specialty butcher counters wrap custom ribeye and strip loin cuts in moisture-regulating butcher paper, while regional packers convert chuck and round trim into clean-label processed meat products to balance whole-carcass revenue across grocery and direct-to-consumer subscription channels.
Table 3: Per Capita and Premium Protein Spending Indicators for the Grass Fed Beef Market (USD and population in billion), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 1.87 | 1.99 | 3.56 |
| Spend per 1,000 people (USD) | 1,871.2 | 1,987.9 | 3,564.2 |
| Health-conscious carnivorous household annual spend (USD) | 185.0 to 210.0 | 195.0 to 222.0 | 320.0 to 365.0 |
Table 4: Facility & Institutional Channel Sizing Indicators for the Grass Fed Beef Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Reference |
|---|---|---|
| Market size, 2026 | USD 16.5 billion | 2026 market estimate |
| Licensed commercial steakhouses and gourmet bistros worldwide | 160 thousand | 2024 culinary census |
| Average annual revenue per foodservice establishment | USD 44,725.0 | Facility revenue ratio |
| Food service and restaurant revenue, 2026 | USD 7.2 billion | 43.4% segment share |
Analyst Perspective
"Multi-year rancher off-take contracts and vacuum wet-aging allow meatpackers to supply tender pasture-finished steaks across year-round retail programs. Longer 26-month finishing cycles and seasonal drought hay expenses still constrain herd expansion when rangeland moisture drops."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the grass fed beef market segmented?
The grass fed beef market is segmented by product form, species / source, end-use sector, and region. In 2026, fresh chilled cuts & fillets is projected at 43.2% of product form, wild capture marine fishery at 55.8% of species / source, and food service & restaurants at 43.4% of end-use sector.
By product form: Fresh chilled cuts & fillets, frozen portions & blocks, canned & shelf-stable, and value-added & breaded.
By species / source: Wild capture marine fishery, commercial aquaculture / farm raised, and livestock pasture raised.
By end-use sector: Food service & restaurants, supermarkets & retail consumers, and industrial food processing plants.
Why does Fresh Chilled Cuts & Fillets lead the product form category?
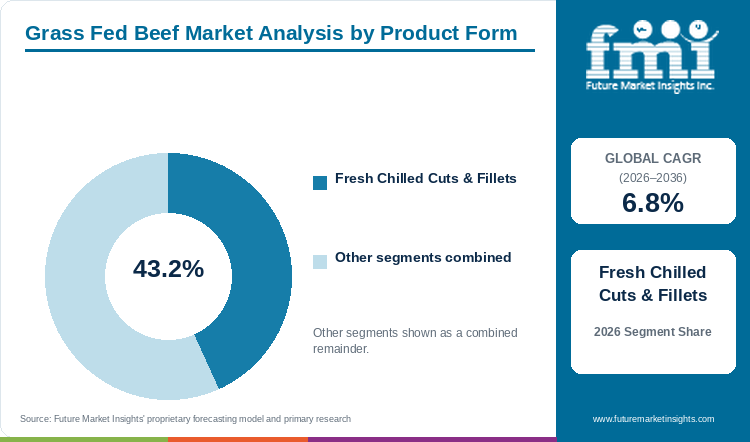
Fresh chilled cuts and fillets are expected to command 43.2% of product form revenue in 2026, reflecting steakhouse tenderness.
Table 5: Product Form Share for the Grass Fed Beef Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Fresh Chilled Cuts & Fillets | 43.2% |
| Other Segments Combined | 56.8%* |
| Total | 100.0% |
*Balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form Leadership and Market Growth for the Grass Fed Beef Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Fresh Chilled Cuts & Fillets |
Retail meat directors and steakhouse chefs prioritize fresh chilled cuts and fillets because avoiding ice-crystal formation preserves muscle fiber integrity and reduces purge loss on the grill. Because forage-finished cattle carry leaner intramuscular fat than grain-fed animals, abattoirs hold chilled tenderloins, ribeyes, and strip loins in vacuum barrier bags at 0 to 2 degrees Celsius for 21 to 28 days so natural calpain enzymes tenderize the cut. Lower-grade chilled trim and marrow bones are directed into slow-simmered savory broths so packers recover full carcass value.
- Fresh chilled cuts & fillets are expected to account for 43.2% of product form revenue in 2026, reflecting strong butcher-counter demand for wet-aged steaks.
- In March 2025, an American Meat Science Association sensory panel study reported that 28-day chilled vacuum-aged pasture ribeyes scored 18% higher in Warner-Bratzler tenderness than frozen counterparts [3].
What makes Wild Capture Marine Fishery central to the species / source category?
By species / source, wild capture marine fishery is projected to hold 55.8% share in 2026, linked to protein benchmarking.
Within the broader natural-harvest and non-feedlot animal protein classification, wild capture marine fishery serves as the primary volume reference against which livestock pasture raised and farm-raised proteins are benchmarked. Nutritionists and specialty grocers frequently position 100% forage-fed beef alongside wild pelagic fish because rotational grazing elevates long-chain omega-3 fatty acids (EPA and DHA) in beef muscle tissue. That nutritional positioning helps pasture-raised red meat retain health-focused households that have turned away from ultra-processed meat substitutes toward whole single-ingredient proteins. Seasonal pasture quality still influences fatty-acid levels across herds.
- Wild capture marine fishery is projected to represent 55.8% of the species / source category in 2026, linked to macro natural-protein benchmarking and omega-3 dietary comparisons.
- In April 2025, a Food and Agriculture Organization comparative protein review noted that rotational legume-grass pastures raised beef omega-3 fatty acid concentrations two to four times above grain-lot baselines [4].
What keeps Food Service & Restaurants ahead by end-use sector?
Within the end-use sector category, food service and restaurants capture 43.4% share in 2026, bolstered by premium steakhouse menus.
Upscale steakhouses, farm-to-table bistros, and gourmet burger chains generate the largest share of commercial revenue because professional kitchen staffs know how to sear leaner grass-finished cuts to medium-rare without drying the meat. Restaurant operators also command higher menu markups by listing specific ranch provenance and rotational grazing certifications on the menu. Back-of-house kitchens utilize trim, shanks, and roasted bones to prepare house demi-glace and beef concentrate, turning whole-animal or boxed-primal programs into high-margin culinary offerings. Year-round menu commitments still require distributors to blend domestic summer harvests with counter-seasonal imports.
- Food service & restaurants are anticipated to hold 43.4% of end-use sector revenue in 2026, bolstered by chef provenance menus and gourmet burger chains.
- In May 2025, the National Restaurant Association culinary forecast reported that 64% of fine-dining and upscale casual operators listed pasture-raised or grass-finished beef as a core menu callout [5].
What are the drivers, restraints, and opportunities in the grass fed beef market?
In the grass fed beef market, consumer preference for antibiotic-free forage-finished meat and omega-3 density supports demand, extended 26-month grazing cycles and drought forage costs restrain supply, and whole-carcass utilization into snacks and broths expands margins through 2036.
- Driver: Retailers and foodservice chains are expanding verified 100% forage-fed beef programs to meet consumer demand for antibiotic-free, soil-regenerative red meat through 2036.
- Restraint: Slower daily cattle weight gain on forage and vulnerability to winter freezes or summer droughts continue to limit slaughter throughput through 2036.
- Opportunity: Converting chuck, round, and bone trim into shelf-stable jerky, tallow, and culinary broths is expected to improve whole-carcass profitability for processors through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Shoppers buying premium red meat increasingly check front-of-pack labels for lifetime pasture access, absence of synthetic growth implants, and verified soil-carbon grazing practices. FMI data suggests that retail grocers and foodservice distributors use third-party grass-fed seals to justify a 20% to 35% price premium over commodity grain-finished beef. A May 2025 study in the Journal of Animal Science confirmed that cattle finished on diverse multi-species pastures accumulated twice the conjugated linoleic acid and significantly higher alpha-tocopherol vitamin E levels than feedlot cattle, slowing myoglobin oxidation in retail display cases [6]. That natural color stability also supports clean-label dehydrated meat products made without synthetic nitrites.
Risk Assessment of the Grass Fed Beef Market: Operational and Formulation Friction
Finishing cattle strictly on pasture grasses and hay exposes ranchers to biological and climatic bottlenecks that grain feedlots avoid. Because forage has lower metabolizable energy density than corn rations, steers gain roughly 1.8 to 2.2 pounds per day on pasture compared with over 3.5 pounds in a feedlot, tying up working capital for an extra 6 to 10 months per animal. In July 2025, the USDA Economic Research Service reported that multi-year rangeland dry spells kept the U.S. beef cow herd near historic lows, tightening feeder cattle supply and raising breakeven slaughter prices [7]. When winter blizzards or summer droughts hit, buying certified organic alfalfa hay erodes ranch operating margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Selling only middle-meat steaks such as ribeye, tenderloin, and strip loin leaves a pasture beef processor with over 75% of the carcass weight in chuck, round, brisket, and trim. Integrated packers unlock higher carcass realization by directing lean grass-fed trim into high-protein meat snacks, premium burger patties, and retort-sterilized canned meat. In February 2026, Hormel Foods Corporation expanded its clean-label pasture-raised beef biltong and jerky distribution across North American convenience and natural grocery channels to capture on-the-go protein spending [8]. Rendering suet into culinary beef tallow for restaurant frying provides an additional high-margin revenue stream.
Grass Fed Beef Market by Country (2026 to 2036)
As per FMI, Germany represents the fastest-growing grass fed beef market among the six profiled countries at an 8.3% CAGR from 2026 to 2036, while Brazil expands at a 5.4% CAGR. Across these national markets, commercial trajectories depend on how ranchers and meatpackers manage pasture land availability, animal-welfare labeling laws, and chilled export cold chains.
Table 7: Country CAGR and Primary Growth Levers for the Grass Fed Beef Market (CAGR percentage and operational drivers), 2026 to 2036
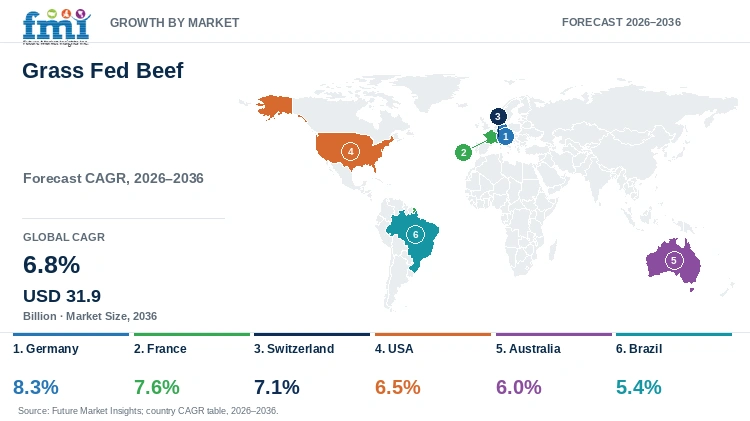
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 8.3% | Mandatory animal-husbandry tier labeling, Bioland and Demeter butcher loyalty, and alpine meadow grazing |
| France | 7.6% | Label Rouge heritage breeds (Charolais, Limousin, Aubrac), traditional boucheries, and bistro gastronomy |
| Switzerland | 7.1% | Federal RAUS outdoor-grazing payments, high household purchasing power, and cooperative retail chains |
| USA | 6.5% | Mainstream grocery butcher-case expansion, ancestral high-protein diets, and regenerative ranching seals |
| Australia | 6.0% | Extensive temperate and tropical rangelands, PCAS pasture certification, and chilled boxed exports to Asia |
| Brazil | 5.4% | Massive Nelore tropical pasture herd, satellite deforestation traceability, and Angus cross-breeding |
Source: Future Market Insights analysis
Germany Grass Fed Beef Market Outlook (2026 to 2036)
Germany's grass fed beef outlook is anticipated to advance at 8.3% CAGR over the assessment period, driven by federal animal-husbandry labeling laws (Tierhaltungskennzeichnung) and strong consumer preference for Bioland, Naturland, and Neuland certified meats. Independent craft butcheries (Metzgereien) and supermarket chains such as Edeka and Rewe prominently merchandize pasture-raised Weiderind steaks. In February 2026, Germany's Federal Statistical Office (Destatis) reported that certified organic and pasture-managed cattle holdings represented over 14.8% of national bovine farms as dairy-beef cross-breeding expanded in Bavaria and Baden-Wurttemberg [9]. High farmland lease rates in northern grain regions still limit summer pasture expansion, prompting German packers to contract with alpine meadow cooperatives.
Key takeaway: In Germany, statutory animal-husbandry tier labels and strong organic butcher demand sustain Europe's fastest commercial expansion for Weiderind cuts.
France Grass Fed Beef Market Outlook (2026 to 2036)
Grass fed beef demand in France is forecast to rise at 7.6% CAGR over the forecast period, underpinned by entrenched culinary loyalty to native suckler-cow beef breeds including Charolais, Limousin, Salers, and Aubrac. French consumers and bistro chefs prize grass-finished beef for its deep red myoglobin color and herbal pasture flavor, verified through official Label Rouge and geographic-indication seals. In July 2025, France's National Institute of Statistics and Economic Studies (INSEE) noted that quality-labeled and pasture-origin beef cuts retained a 28% retail price premium across French butcheries despite broader household food inflation [10]. Rural generational farm retirements in the Massif Central and EU methane targets still constrain domestic suckler-herd headcounts.
Key takeaway: In France, protected Label Rouge breed heritage and artisanal boucherie merchandising protect premium margins for domestic pasture-finished beef.
Switzerland Grass Fed Beef Market Outlook (2026 to 2036)
Adoption of grass fed beef in Switzerland is estimated to expand at 7.1% CAGR through 2036, supported by federal direct-payment agricultural subsidies (RAUS and Weidebeitrag) that reward farmers for daily outdoor pasture grazing. Because mountainous topography makes intensive corn-silage cropping uneconomical across much of the country, Swiss cattle naturally graze alpine and sub-alpine meadows. In August 2025, the Swiss Federal Statistical Office reported that over 86% of domestic cattle farms participated in certified outdoor pasture and animal-welfare programs, supplying flagship Natura-Beef and TerraSuisse retail lines at Coop and Migros [11]. Strict border tariff quotas on imported meat keep domestic retail steak prices among the highest globally.
Key takeaway: In Switzerland, federal outdoor-grazing subsidies and cooperative retail programs make alpine pasture beef the mainstream national retail standard.
USA Grass Fed Beef Market Outlook (2026 to 2036)
In the USA, demand for grass fed beef is predicted to advance at 6.5% CAGR through 2036, fueled by nationwide club-store and natural-supermarket distribution of 100% grass-fed ground beef bricks and vacuum-sealed ribeyes. Health-focused American households buy pasture-finished beef as a staple of high-protein and whole-food diets. In October 2025, the USDA Agricultural Marketing Service direct-marketed grass-fed beef report recorded strong wholesale price premiums for certified domestic 100% forage-fed carcasses alongside elevated chilled lean-trim imports from Australia and New Zealand [12]. Because U.S. USDA Prime and Choice grading rewards heavy white intramuscular marbling from corn feeding, domestic grass-fed ranchers rely on American Grassfed Association and Regenerative Organic seals to differentiate leaner cuts.
Key takeaway: In the USA, high-volume retail ground-beef programs and regenerative ranching certifications drive the world's largest commercial revenue pool.
Australia Grass Fed Beef Market Outlook (2026 to 2036)
Australia is estimated to post 6.0% CAGR over the forecast period, anchored by vast temperate pastures in Victoria, Tasmania, and New South Wales and tropical grazing stations across Queensland. Australian exporters dominate seaborne trade in vacuum-chilled grass-fed primal cuts and 85CL lean grinding beef shipped to North America, Japan, and South Korea. In October 2025, Meat & Livestock Australia (MLA) reported in its Beef Fast Facts 2025 release that Australia exported over 1.3 million metric tons shipped weight of beef across more than 100 countries, with certified grass-fed programs capturing expanding retail shelf space [13]. Periodic El Nino rainfall deficits still require ranchers to manage stocking densities carefully.
Key takeaway: In Australia, certified Pasturefed Cattle Assurance System traceability and chilled maritime logistics sustain the world's leading export platform.
Brazil Grass Fed Beef Market Outlook (2026 to 2036)
The grass fed beef market in Brazil is anticipated to grow at 5.4% CAGR between 2026 and 2036, backed by the world's largest commercial cattle herd grazing year-round on tropical Brachiaria pastures across Mato Grosso, Goias, and Mato Grosso do Sul. While traditional Nelore zebu cattle thrive on tropical forage at low production cost, export packers are cross-breeding Nelore dams with Aberdeen Angus sires to improve loin-eye marbling and tenderness for upscale domestic churrascarias and European export quotas. In December 2025, the Brazilian Agricultural Research Corporation (Embrapa) documented that integrated crop-livestock-forestry (ILPF) pasture systems expanded past 17.4 million hectares, cutting methane intensity per kilogram of carcass weight [14]. Mandatory ear-tag satellite traceability under EU deforestation rules remains a key compliance hurdle for smaller ranches.
Key takeaway: In Brazil, Angus-Nelore cross-breeding and low-carbon tropical pasture management help export packers upgrade tropical grass-fed beef into premium steak channels.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the grass fed beef market?
Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., and Campbell Soup Company are the notable companies in the grass fed beef market.
As per the analysis from FMI, the competitive structure of the grass fed beef market connects high-throughput meatpacking processors with multi-category packaged food brands that procure certified pasture-raised beef cuts, trim, and bones. Primary packers manage rancher contracting, humane slaughter, and vacuum-skin primal fabrication, while downstream culinary and snack brands convert grass-fed beef into regenerative jerky, frozen skillet meals, and slow-simmered bone broths. Supermarket meat buyers evaluate suppliers on third-party 100% forage verification, carcass tenderness consistency, and cold-chain fill rates.
- Primary Meatpacking and Protein Processors: Tyson Foods, Inc. and Conagra Brands, Inc. operate large-scale beef fabrication and frozen meal assembly lines supplying retail grocers and foodservice distributors.
- Regenerative Snacking and Multi-Category Nutrition Brands: General Mills, Inc. (EPIC Provisions), Nestle S.A., and Danone S.A. source certified regenerative and pasture-raised livestock ingredients for meat snacks, culinary lines, and specialized nutrition.
- Savory Broth, Gravy, and Packaged Culinary Leaders: Campbell Soup Company, The Kraft Heinz Company, and Mondelez International, Inc. incorporate pasture-raised beef bones, extracts, and savory meat inclusions into retail pantry products.
Competitive Benchmarking: Grass Fed Beef Market
Table 8: Competitive Benchmarking for the Grass Fed Beef Market (qualitative capability ratings), 2026
| Company | Pasture Sourcing Breadth | Humane & Regenerative Certification | Supermarket & Retail Access | Geographic Reach |
|---|---|---|---|---|
| Tyson Foods, Inc. | High | High | High | High |
| Nestle S.A. | High | High | High | High |
| Danone S.A. | Medium | High | High | High |
| General Mills, Inc. | Medium | High | High | Medium |
| The Kraft Heinz Company | High | Medium | High | High |
| Mondelez International, Inc. | Medium | Medium | High | High |
| Conagra Brands, Inc. | High | Medium | High | Medium |
| Campbell Soup Company | High | High | High | Medium |
Scoring criteria: Pasture Sourcing Breadth is High when a company contracts multi-regional rancher networks for 100% forage-fed cattle or beef ingredients, and Medium when sourcing is concentrated in specialty lines. Humane & Regenerative Certification reflects documented third-party grazing and animal-welfare audits. Supermarket & Retail Access and Geographic Reach reflect fresh meat case, frozen aisle, and international distribution coverage.
Key Developments in the Grass Fed Beef Market
- In June 2026, Conagra Brands, Inc. introduced new summer frozen skillet meals and single-serve bowls featuring braised beef cuts across North American grocery freezers [17].
- In March 2026, Tyson Foods, Inc. upgraded specialty boxed-beef vacuum-skin packaging and fabrication lines in Nebraska to expand retail case-ready grass-fed steak throughput by 20% [15].
- In January 2026, Campbell Soup Company expanded its premium slow-simmered bone broth and stock lines using certified pasture-raised beef bones across North American retail grocers [16].
- In August 2025, General Mills, Inc. renewed multi-year regenerative grazing partnerships with Northern Great Plains cattle ranches supplying its EPIC Provisions 100% grass-fed beef snack bars and tallow lines [18].
Key Players in the Grass Fed Beef Market
Primary Meatpacking and Frozen Meal Processors
- Tyson Foods, Inc.
- Conagra Brands, Inc.
Regenerative Meat Snack and Nutrition Platforms
- General Mills, Inc.
- Nestle S.A.
- Danone S.A.
Savory Broth, Culinary Stock, and Packaged Food Leaders
- Campbell Soup Company
- The Kraft Heinz Company
- Mondelez International, Inc.
Grass Fed Beef Market - Report Scope
Table 9: Report Scope for the Grass Fed Beef Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Species / Source; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial wholesale and retail revenue from certified grass-fed and pasture-finished beef cuts, ground beef, frozen portions, canned meats, and value-added beef products within the listed segmentation. Excludes conventional grain-lot finished beef and live cattle trading. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany, France, Switzerland, USA, Australia, Brazil, and additional countries in the full report |
| Key Companies Covered | Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Grass Fed Beef Market - Research Methodology
Table 10: Research Methodology for the Grass Fed Beef Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with pasture cattle ranchers, abattoir fabrication directors, supermarket meat category buyers, and steakhouse executive chefs to validate carcass yields, pricing premiums, and seasonal supply constraints. |
| Secondary Research | Secondary research analyzed USDA NASS and ERS livestock statistics, FAO pastoral livestock monographs, Meat & Livestock Australia export bulletins, Destatis organic farming reports, and corporate disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 reconciled certified forage-fed slaughter headcounts and dressed carcass weights against retail scanner sales and foodservice distributor volumes. |
| Data Triangulation and Validation | Estimates were cross-checked against national grazing acreage, import-export customs logs, and third-party grass-fed certification registries to ensure data integrity. |
Grass Fed Beef Market by Segments
Grass Fed Beef Market segmented by Product Form:
- Fresh Chilled Cuts & Fillets
- Frozen Portions & Blocks
- Canned & Shelf-Stable
- Value-Added & Breaded
Grass Fed Beef Market segmented by Species / Source:
- Wild Capture Marine Fishery
- Commercial Aquaculture / Farm Raised
- Livestock Pasture Raised
Grass Fed Beef Market segmented by End-Use Sector:
- Food Service & Restaurants
- Supermarkets & Retail Consumers
- Industrial Food Processing Plants
Grass Fed Beef Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Türkiye
Research Sources and Bibliography
- [1] United States Department of Agriculture Economic Research Service. (2025, May 22). Cattle and beef sector at a glance: Herd inventory and specialty retail pricing. USDA Economic Research Service Animal Products Portal.
- [2] Food and Agriculture Organization Livestock Division. (2025, February 22). Sustainable pastoral livestock systems and global grass-fed meat production economics. FAO Livestock Monograph, 142.
- [3] American Meat Science Association. (2025, March 18). Sensory tenderness and purge loss of vacuum-aged pasture-finished beef compared with frozen cuts. Meat and Muscle Biology Journal, 9(1), 45-62.
- [4] Food and Agriculture Organization Fisheries and Livestock Review. (2025, April 26). Comparative omega-3 fatty acid profiles across wild marine fisheries and rotational pasture livestock. FAO Technical Report Series, 984.
- [5] National Restaurant Association. (2025, May 20). Culinary forecast and steakhouse menu adoption of pasture-raised and grass-finished beef. NRA Culinary Review, 2025-05.
- [6] Journal of Animal Science. (2025, May 12). Conjugated linoleic acid and vitamin E antioxidant stability in beef cattle finished on multi-species forage. Journal of Animal Science, 103(5), 1840-1856.
- [7] United States Department of Agriculture Economic Research Service. (2025, July 02). Cattle and beef statistics and rangeland forage cost indicators. USDA ERS Cattle & Beef Statistics and Information.
- [8] Hormel Foods Corporation. (2026, February 16). Value-added protein snacking: Expanding clean-label beef jerky and biltong from pasture herds. Hormel Industry Brief, 2026-02.
- [9] Federal Statistical Office (Destatis). (2026, February 17). Organic livestock farming and pasture-raised meat production in Germany. Statistisches Bundesamt Livestock and Meat Statistics.
- [10] National Institute of Statistics and Economic Studies (INSEE). (2025, July 18). Quality meat consumption and Label Rouge butcher price dynamics across French households. INSEE Statistical Monograph, 2025-07.
- [11] Swiss Federal Statistical Office. (2025, August 24). Alpine agriculture, RAUS outdoor grazing participation, and cooperative pasture meat sales. FSO Sectoral Report, 2025-08.
- [12] United States Department of Agriculture Agricultural Marketing Service. (2025, October 16). National monthly grass-fed beef wholesale and direct-marketed carcass price report. USDA AMS Livestock Market News, 2025-10.
- [13] Meat & Livestock Australia (MLA). (2025, October 30). Australian beef fast facts 2025: Grass-fed cattle production and global boxed beef exports. MLA Beef Fast Facts 2025 Official Report.
- [14] Brazilian Agricultural Research Corporation (Embrapa). (2025, December 14). Integrated crop-livestock-forestry (ILPF) tropical pasture systems and low-carbon beef export competitiveness. Embrapa Technical Monograph, 94.
- [15] Tyson Foods, Inc. (2026, March 24). Commissioning of expanded specialty case-ready pasture beef vacuum-skin packaging lines in Nebraska. Tyson Commercial Operations Bulletin.
- [16] Campbell Soup Company. (2026, January 20). Culinary stock and slow-simmered bone broth portfolio transition to certified pasture-raised beef bones. Campbell Product Portfolio Release.
- [17] Conagra Brands, Inc. (2026, June 24). Summer frozen meal introductions featuring braised pasture-raised beef skillet entrees. Conagra Brands News Release.
- [18] General Mills, Inc. (2025, August 28). Regenerative grazing partnerships across Northern Great Plains ranches for EPIC Provisions beef snacks. General Mills Corporate Briefing.
- [19] Nestle S.A. (2026, April 14). Global culinary and nutrition review: Regenerative meat sourcing and savory bouillon expansion. Nestle Annual Sustainability Monograph.
- [20] Danone S.A. (2025, October 22). Regenerative farming transitions and soil-carbon grazing standards across European livestock supply chains. Danone Corporate Whitepaper.
- [21] The Kraft Heinz Company. (2025, June 25). Modernizing savory comfort foods: Transitioning premium gravies and bone broths to pasture-raised beef extracts. Kraft Heinz Portfolio Release.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the grass fed beef market in 2026 and what is forecast for 2036?
- Which antibiotic-free and regenerative grazing trends support demand for grass fed beef?
- Why does Fresh Chilled Cuts & Fillets lead the product form category?
- How is wild capture marine fishery used within the species / source benchmark category?
- How do growth rates differ across Germany, France, Switzerland, and the USA?
- Which leading meatpackers and food brands supply pasture-raised beef products today?
- What forage seasonality and finishing-time hurdles restrain herd expansion?
- What should supermarket meat buyers verify before contracting a grass-fed beef supplier?
Frequently Asked Questions
How big is the grass fed beef market in 2026, and what is forecast for 2036?
The global grass fed beef market is estimated to reach USD 16.5 billion in 2026 and is projected to expand to USD 31.9 billion by 2036, generating USD 15.4 billion in incremental revenue over the decade.
What is the CAGR for the grass fed beef market from 2026 to 2036?
As per FMI, the grass fed beef market is projected to advance at a 6.8% CAGR from 2026 to 2036. Growth is supported by expanding retail butcher-case allocation for antibiotic-free, 100% forage-finished steaks and ground beef.
Which product form segment leads the grass fed beef market?
Fresh Chilled Cuts & Fillets is projected to hold 43.2% of product form revenue in 2026. The segment leads because 21-to-28-day chilled vacuum wet-aging tenderizes lean pasture-finished steaks and prevents freezing purge loss.
Which end-use sector holds the leading share in the grass fed beef market?
Food Service & Restaurants is estimated to capture 43.4% of end-use sector demand in 2026. Demand is underpinned by upscale steakhouses and chef-driven burger concepts featuring ranch-provenance grass-finished cuts.
Which country has a notable growth outlook during the assessment period?
FMI finds that Germany is projected to register an 8.3% CAGR from 2026 to 2036. Expansion is supported by mandatory national animal-husbandry tier labeling and strong consumer loyalty to Bioland and Demeter butcheries.
Who are the key players in the grass fed beef market?
Notable companies active in the market include Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., and Campbell Soup Company. These companies focus on regenerative ranch contracting, vacuum-skin steak packaging, and whole-carcass broth and snack utilization.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Fresh Chilled Cuts & Fillets
- Frozen Portions & Blocks
- Canned & Shelf-Stable
- Value-Added & Breaded
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Species / Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Species / Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Species / Source, 2026 to 2036
- Wild Capture Marine Fishery
- Commercial Aquaculture / Farm Raised
- Livestock Pasture Raised
- Y-o-Y Growth Trend Analysis By Species / Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Species / Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food Service & Restaurants
- Supermarkets & Retail Consumers
- Industrial Food Processing Plants
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Türkiye
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Species / Source
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tyson Foods, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle S.A.
- Danone S.A.
- General Mills, Inc.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Campbell Soup Company
- Tyson Foods, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


