

- Market Size (2026)
- USD 6.9 Bn
- Forecast (2036)
- USD 26.6 Bn
- CAGR (2026 to 2036)
- 14.5%
How big is Healthcare Interoperability Solutions Market in 2026?
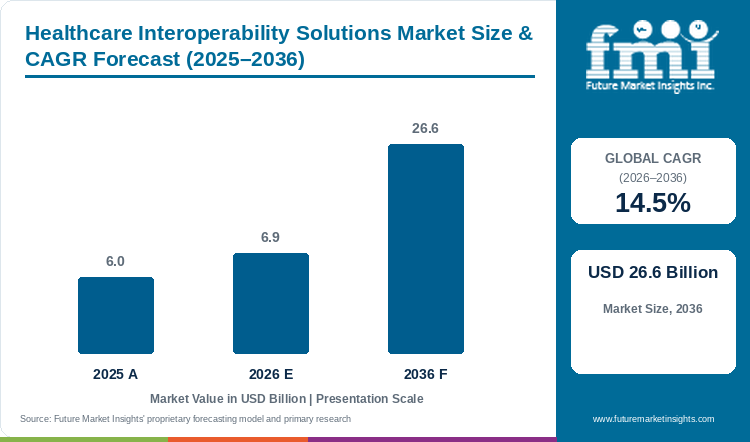
Demand is projected to expand at 14.5% CAGR from 2026 to 2036. Market value rises from USD 6 billion in 2025 to USD 6.9 billion in 2026 and USD 26.6 billion by 2036.
Providers purchase these capabilities to make information available across systems in a form that staff can use during care, bringing interfaces and the receiving workflow into the same implementation task. France's Mon espace santé reporting distinguishes documents supplied from professional consultation, identifying a practical opportunity to improve how users reach information. [1] The Notts shared record adds an operating example of professional access within a regional service. [2] Standards changes create further integration work, with the US HTI-4 prescribing criteria providing a defined module-level transition. [4] Buyers therefore need software and assistance that keep the connection useful as participating systems change, with clear responsibilities for access and maintenance. Through 2036, suppliers can develop stronger relationships by connecting additional data sources with ordinary clinical tasks, allowing information exchange to become a dependable part of the provider's working process.
Key Market Trends & Insights
- Providers seek connections that make outside information usable within the clinical or administrative task performed by staff. [1][2]
- Standards transitions create defined integration work around affected prescribing modules. [4]
- Operating exchanges can develop through additional data sources and partners connected with continuing maintenance support. [2]
Regional Highlights
- India's ABDM record-sharing framework connects participating providers through a consent-based arrangement, with official reporting identifying more than one billion records linked to ABHA by May 2026 (FMI outlook: 17.3% CAGR, 2026 to 2036).
- German provider organizations need exchange arrangements that keep information usable as it moves between record systems and clinical teams, giving implementation and continuing maintenance a substantial role in procurement (FMI outlook: 15.9% CAGR, 2026 to 2036).
- US prescribing certification creates a defined integration task through the HTI-4 transition to NCPDP SCRIPT 2023011 and the linked prescription-benefit criterion for affected modules (FMI outlook: 13.1% CAGR, 2026 to 2036).
Market Size & Forecast
Table 1: Market Size and Forecast for Healthcare Interoperability Solutions Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 6 billion |
| 2026 market value | USD 6.9 billion |
| 2036 market value | USD 26.6 billion |
| CAGR 2026 to 2036 | 14.5% |
| Revenue increase 2026 to 2036 | USD 19.7 billion |
| Market expansion 2026 to 2036 | 3.86 times |
The market covers health-data exchange and integration through standards, middleware and APIs. Deployment of an electronic record alone does not establish successful cross-provider exchange.
Interoperability becomes part of digital healthcare transformation when providers connect the information already held in separate systems with the clinical and administrative tasks staff perform every day.
Record exchange, professional access and module-level upgrades
Official and provider evidence identifies several practical requirements behind interoperability spending, including consultation within an existing record service, additional partner connections and defined prescribing-interface transitions. These observations connect available information with the work required to make it usable across systems. [1][2][3][4]
Table 2: Industry evidence relevant to the healthcare interoperability solutions market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| France | Mon espace santé reporting | Document supply and professional consultation identify different workflow requirements | [1] |
| United Kingdom | Notts Care Record | Operating professional access creates a setting for further interface expansion | [2] |
| India | ABDM-linked records | Consent-based sharing creates connection and access responsibilities | [3] |
| United States | HTI-4 prescribing criteria | Affected modules face a defined standards transition | [4] |
Analyst Perspective
"Basic connectivity gives healthcare organisations a starting point for exchanging information, but professionals still need a usable receiving workflow. Interoperability suppliers should connect interfaces with access responsibilities and maintenance, so that additional sources can be brought into a service without losing the usefulness of the existing records."
- Anurag Sharma, Principal Consultant, FMI
How is the Healthcare Interoperability Solutions Market segmented?
The market is segmented by Product, Level of Interoperability, Deployment, Application, End Use, Distribution Channel, and Region.
Product separates Interoperability Solutions and Interoperability Services. Level of Interoperability covers Foundational, Structural, and Semantic Interoperability, while Deployment distinguishes Cloud Based and On Premise. Application comprises Clinical Data Exchange, Administrative Data Exchange, and Population Health Management. End Use covers Healthcare Providers and Healthcare Payers, with Distribution Channel comprising Direct Sales, Partner and Channel Sales, and Online Sales. These axes connect the capability purchased with the information exchanged and the organization using it.
Why do interoperability solutions hold the larger product share?
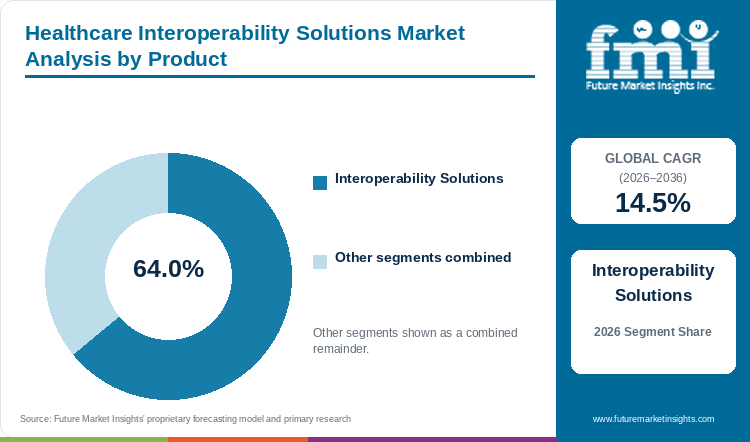
Table 3: Product Share for Healthcare Interoperability Solutions Market (percentage share), 2026
| Product | Estimated share (2026) |
|---|---|
| Interoperability Solutions | 64.0% |
| Interoperability Services | 36.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Healthcare Interoperability Solutions Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 14.5% |
| Profiled product segment | Interoperability Solutions |
Software connections and exchange platforms provide the capability through which organizations make information available across systems, giving solutions a central role within an interoperability purchase. The buyer needs the interface to address a defined clinical or administrative task and remain manageable as the connected applications change. France's reporting on professional consultation and the Notts shared-record service illustrate the operating setting in which that capability becomes useful. [1][2] The Interoperability Solutions segment is projected to account for 64.0% of product demand in 2026 as providers develop those connections. Implementation services support the work around the platform, while the solution itself organizes the exchange and access functions the customer has selected, making its fit with the receiving workflow important to procurement.
The Interoperability Solutions segment is projected to account for 64.0% of product demand in 2026.
- Interoperability Solutions: 64.0% of product demand (2026 estimate), with Interoperability Services accounting for the remaining 36.0%.
- Useful exchange connects the available information with the professional's receiving workflow, giving interface design and continuing support a practical role in selection. [1][2]
What supports the substantial role of foundational interoperability?
Table 5: Level of Interoperability Share for Healthcare Interoperability Solutions Market (percentage share), 2026
| Level of Interoperability | Estimated share (2026) |
|---|---|
| Foundational Interoperability | 39.0% |
| Other level of interoperability segments | 61.0% |
| Total | 100.0% |
Basic connectivity allows one system to make information available to another, providing an initial requirement for organizations that need to exchange records. A provider developing that capability has to establish the participating systems and the information to be passed before addressing more detailed interpretation within the receiving application. The Foundational Interoperability segment is projected to account for 39.0% of level-based demand in 2026 as buyers establish and maintain those connections. India's consent-based record-sharing arrangement provides a concrete setting in which access and participating providers form part of the exchange process. [3] Suppliers can strengthen their proposition through clear interfaces and operating responsibilities, helping the customer maintain dependable connectivity while additional sources and more structured information requirements are introduced over time.
The Foundational Interoperability segment is projected to account for 39.0% of level of interoperability demand in 2026.
- The Foundational Interoperability segment is projected to hold 39.0% of demand by interoperability level in 2026, supporting basic data exchange and system connectivity.
- Defined access and operating responsibilities help providers maintain the underlying connection as additional sources and more detailed information requirements develop.
- Information gathered through connected systems can support healthcare business intelligence, with consistent data structures helping managers interpret activity and resources across participating services.
What are the drivers, restraints, and opportunities in the Healthcare Interoperability Solutions Market?
The commercial requirement is a connection that makes relevant information usable within a professional's task, bringing interfaces and workflow design into the same purchase. Standards transitions and additional data sources create further implementation work, while continuing support keeps the arrangement useful as systems change. Suppliers can build relationships around maintaining and extending those dependable exchange capabilities. [1][2][4]
Driver
Providers need information from other systems within clinical and administrative tasks, creating demand for interfaces that connect the source with the receiving workflow. France's consultation evidence and the Notts regional service illustrate that operating requirement, while the US prescribing transition identifies a specific module-level integration task. [1][2][4] Suppliers can address these needs through clear connections and supporting services that keep the selected capability useful as applications and participants change.
Restraint
A connection has to accommodate different applications, information structures and operating responsibilities, making implementation a substantial part of the purchasing commitment. Staff also need a practical way to retrieve the relevant content during their work. France's distinction between document supply and professional consultation illustrates why convenience at the receiving end matters. [1] Buyers therefore evaluate the interface together with continuing support and the work required to maintain access as connected systems develop.
Opportunity
An operating exchange creates opportunities to add relevant sources and participants around a service that professionals already use. The Notts record identifies planned additions to its information coverage and partners, giving suppliers a defined route to further interface work. [2] Vendors can develop stronger relationships through practical integration and maintenance support, helping customers extend useful connectivity while keeping the receiving workflow manageable for staff.
Interfaces with enterprise laboratory informatics need to preserve sample and result context, allowing the receiving care system to present the relevant findings within the patient's clinical workflow.
Which country CAGRs are profiled in the Healthcare Interoperability Solutions Market?
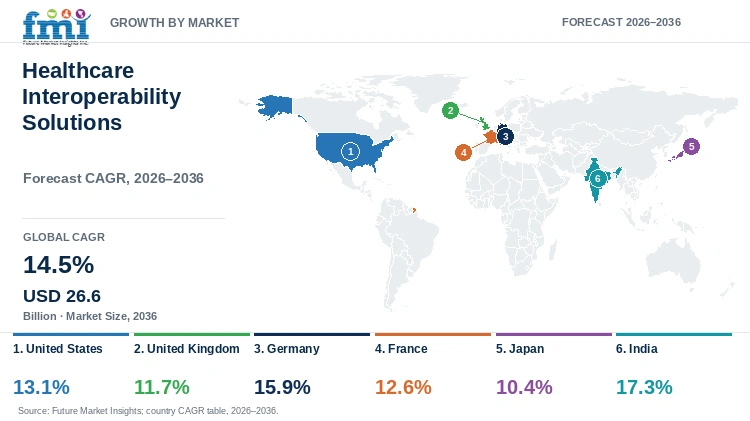
Table 6: Country CAGR Comparison for Healthcare Interoperability Solutions Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| United States | 13.1% |
| United Kingdom | 11.7% |
| Germany | 15.9% |
| France | 12.6% |
| Japan | 10.4% |
| India | 17.3% |
Country-wise Analysis
United States Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
US prescribing certification creates a defined integration task through the HTI-4 transition to NCPDP SCRIPT 2023011 and the linked prescription-benefit criterion for affected modules. [4] A provider needs the relevant application and receiving systems to work together, making configuration and support important to the upgrade decision. Suppliers can address the requirement by identifying the module, information and interfaces involved, then supporting the connection as the participating systems change. The commercial relationship consequently extends beyond the initial implementation, with dependable operation helping staff use the available information within the task they need to perform.
United Kingdom Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
The Notts Care Record provides a practical UK example of exchange value developing through professional use, with more than one million views reported after its July 2025 launch. The service also identifies planned additions to its information and partner coverage, creating further interface work around an operating regional system. [2] Suppliers therefore need to understand the receiving workflow and the responsibilities shared between organizations, making support and maintainable interfaces central to selection. A useful extension allows staff to reach relevant information with a manageable change to the way they already work.
Germany Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
German provider organizations need exchange arrangements that keep information usable as it moves between record systems and clinical teams, giving implementation and continuing maintenance a substantial role in procurement. A hospital connecting another source has to establish the content, access arrangements and responsibilities for keeping the interface working, while the receiving application needs to present information usefully to staff. Suppliers can strengthen their position through clear configuration and support that fit the customer's operating environment. The purchasing relationship therefore includes both the connection and the work required to maintain its usefulness as applications, participants and information requirements change over time.
France Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
France's Mon espace santé evidence separates the large volume of documents supplied from professional consultation, making convenient retrieval a concrete commercial requirement within an established information base. The accompanying upgrade direction addresses access within the professional workflow, linking further development with the way clinicians use the available records. [1] Suppliers can address the work through interfaces that make relevant information accessible within ordinary tasks, with implementation and support helping the organizations involved maintain a dependable arrangement. The opportunity consequently follows the practical use of shared records and the extension of useful connections around the existing service.
Japan Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
A Japanese provider connecting referrals, laboratory information and clinical records needs an exchange arrangement that fits the systems and staff involved in receiving the data. The basic connection has to remain dependable, while the content and presentation need to support the task being performed at the point of care. Suppliers can create value through clear interfaces and implementation support, especially where several applications contribute information to the same workflow. A maintainable arrangement also needs responsibilities for updates and assistance to be understood, allowing the customer to extend the connection as more sources and more detailed information requirements are introduced.
India Healthcare Interoperability Solutions Market Outlook (2026 to 2036)
India's ABDM record-sharing framework connects participating providers through a consent-based arrangement, with official reporting identifying more than one billion records linked to ABHA by May 2026. [3] That operating setting creates requirements for interfaces, access and support that make the available information useful within care. A supplier needs to understand the customer's existing software and the responsibilities involved in sharing and retrieving information, making integration assistance important to the purchase. The commercial relationship can deepen as additional sources are connected, with maintainable interfaces helping the provider use the chosen arrangement consistently during ordinary clinical work.
Who are the notable companies in the Healthcare Interoperability Solutions Market?
Oracle Health; Epic; Infor; Redox; Health Gorilla
Interoperability suppliers compete through the connections that make information useful across healthcare systems, with record-platform companies, integration specialists and exchange services occupying distinct positions. Provider demand can involve a single interface or an expanding network of data sources, so continuing administration and implementation responsibilities influence the commercial arrangement. France's shared-record program, Nottinghamshire's recorded use and the US standards timetable illustrate different operating settings for those connections. [1][2][4] The practical value rests in the information reaching the professional and task for which it is needed.
Competitive Benchmarking: Healthcare Interoperability Solutions Market
Table 7: Competitive positioning for the healthcare interoperability solutions market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Oracle Health | Healthcare record and exchange technology | Defined interface and receiving workflow |
| Epic | Record-platform interoperability | Connection and consultation within care |
| Infor | Healthcare integration technology | Interface scope and administration |
| Redox | Healthcare integration services | API connectivity and ongoing operation |
| Health Gorilla | Health-data exchange services | Exchange role and data-access workflow |
Key Developments in the Healthcare Interoperability Solutions Market
- The Notts Care Record reported more than one million professional views by September 2026 and identified planned additions to its information and partner coverage. [2]
- India's May 2026 reporting placed ABHA-linked records above one billion within the consent-based ABDM sharing arrangement. [3]
- The US HTI-4 framework sets a transition to NCPDP SCRIPT 2023011 for affected prescribing certification, creating defined module-level integration work. [4]
Key Players in the Healthcare Interoperability Solutions Market
Healthcare record and exchange technology
- Oracle Health
Record-platform interoperability
- Epic
Healthcare integration technology
- Infor
Healthcare integration services
- Redox
Health-data exchange services
- Health Gorilla
Healthcare Interoperability Solutions Market Report Scope
Table 8: Report Scope for Healthcare Interoperability Solutions Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | The market covers health-data exchange and integration through standards, middleware and APIs. Deployment of an electronic record alone does not establish successful cross-provider exchange. |
| Quantitative units | USD billion |
| Historical reference year | 2025 |
| Forecast period | 2026 to 2036 |
| Market breakdown | Product; Level of Interoperability; Deployment; Application; End Use; Distribution Channel; Region |
| Countries profiled | United States; United Kingdom; Germany; France; Japan; India |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Key companies profiled | Oracle Health; Epic; Infor; Redox; Health Gorilla |
Healthcare Interoperability Solutions Market Research Methodology
Table 9: Research Methodology for Healthcare Interoperability Solutions Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | The market covers health-data exchange and integration through standards, middleware and APIs. Deployment of an electronic record alone does not establish successful cross-provider exchange. |
| Secondary research | Public institutional reports, regulator publications, technical literature and supplier documentation provide the operating context for the market. |
| Quantitative coverage | Market values are expressed in USD billion, with a 2025 base value, a 2026 estimate and a projection for 2036. |
| Segment and country assessment | Segment categories retain distinct demand measures, while each country profile is linked with its estimated CAGR for 2026 to 2036. |
| Company comparison | Representative participants are compared by the product or service offered, the customer application and the implementation requirements relevant to procurement. |
Healthcare Interoperability Solutions Market by Segments
Healthcare Interoperability Solutions Market segmented by Product:
- Interoperability Solutions
- Electronic Health Record Interoperability
- Health Information Exchange Interoperability
- Integration and Middleware Solutions
- Interoperability Services
- Consulting Services
- Implementation Services
- Electronic Health Record Interoperability
Healthcare Interoperability Solutions Market segmented by Level of Interoperability:
- Foundational Interoperability
- Basic Data Exchange
- System Connectivity
- Structural Interoperability
- Data Format Standardization
- Message Structuring
- Semantic Interoperability
- Data Interpretation
- Advanced Data Integration
- Basic Data Exchange
Healthcare Interoperability Solutions Market segmented by Deployment:
- Cloud Based
- Public Cloud Deployment
- Private Cloud Deployment
- On Premise
- Enterprise Deployment
- Local Server Deployment
- Public Cloud Deployment
Healthcare Interoperability Solutions Market segmented by Application:
- Clinical Data Exchange
- Patient Data Sharing
- Diagnostic Data Integration
- Administrative Data Exchange
- Claims and Billing Integration
- Operational Data Sharing
- Population Health Management
- Health Analytics
- Public Health Reporting
- Patient Data Sharing
Healthcare Interoperability Solutions Market segmented by End Use:
- Healthcare Providers
- Hospitals
- Clinics
- Healthcare Payers
- Public Payers
- Private Payers
- Hospitals
Healthcare Interoperability Solutions Market segmented by Distribution Channel:
- Direct Sales
- Enterprise Sales
- Partner and Channel Sales
- System Integrators
- Value Added Resellers
- Online Sales
- Digital Platforms
Healthcare Interoperability Solutions Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Assurance Maladie / Agence du Numérique en Santé. 29 January 2026. Mon espace santé: press dossier
- [2] NHS Digital Notts. 28 September 2026. Notts Care Record exceeds one million views
- [3] Ministry of Health and Family Welfare / PIB. 22 May 2026. One billion health records linked with ABHA
- [4] ASTP/ONC. October 2025. HTI-4 Final Rule overview and key dates
This Report Answers
- How large is the Healthcare Interoperability Solutions Market in 2026?
- What is the growth outlook for the Healthcare Interoperability Solutions Market through 2036?
- What is the 2026 share of Interoperability Solutions?
- What is the 2026 share of Foundational Interoperability?
- Which profiled market has the highest projected growth?
- Who are the notable participants in the Healthcare Interoperability Solutions Market?
Frequently Asked Questions
How large is the Healthcare Interoperability Solutions Market in 2026?
The market is estimated at USD 6.9 billion in 2026, compared with USD 6 billion in 2025.
What is the growth outlook for the Healthcare Interoperability Solutions Market through 2036?
The market is projected to reach USD 26.6 billion by 2036, representing a CAGR of 14.5% from 2026 to 2036.
What is the 2026 share of Interoperability Solutions?
The Interoperability Solutions segment is estimated to account for 64% of product demand in 2026. Useful exchange connects the available information with the professional's receiving workflow, giving interface design and continuing support a practical role in selection. [1][2]
What is the 2026 share of Foundational Interoperability?
The Foundational Interoperability segment is estimated to account for 39% of level of interoperability demand in 2026. Defined access and operating responsibilities help providers maintain the underlying connection as additional sources and more detailed information requirements develop.
Which profiled market has the highest projected growth?
India has the highest projected rate among the markets profiled, at 17.3% CAGR from 2026 to 2036.
Who are the notable participants in the Healthcare Interoperability Solutions Market?
Representative participants include Oracle Health, Epic, Infor, Redox, Health Gorilla.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Interoperability Solutions
- Electronic Health Record Interoperability
- Health Information Exchange Interoperability
- Integration and Middleware Solutions
- Interoperability Services
- Consulting Services
- Implementation Services
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Level of Interoperability, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Level of Interoperability, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Level of Interoperability, 2026 to 2036
- Foundational Interoperability
- Basic Data Exchange
- System Connectivity
- Structural Interoperability
- Data Format Standardization
- Message Structuring
- Semantic Interoperability
- Data Interpretation
- Advanced Data Integration
- Y-o-Y Growth Trend Analysis By Level of Interoperability, 2021 to 2025
- Absolute $ Opportunity Analysis By Level of Interoperability, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment, 2026 to 2036
- Cloud Based
- Public Cloud Deployment
- Private Cloud Deployment
- On Premise
- Enterprise Deployment
- Local Server Deployment
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Clinical Data Exchange
- Patient Data Sharing
- Diagnostic Data Integration
- Administrative Data Exchange
- Claims and Billing Integration
- Operational Data Sharing
- Population Health Management
- Health Analytics
- Public Health Reporting
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Healthcare Providers
- Hospitals
- Clinics
- Healthcare Payers
- Public Payers
- Private Payers
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct Sales
- Enterprise Sales
- Partner and Channel Sales
- System Integrators
- Value Added Resellers
- Online Sales
- Digital Platforms
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Level of Interoperability
- By Deployment
- By Application
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Oracle Health
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Epic
- Infor
- Redox
- Health Gorilla
- Oracle Health
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


