

- Market Size (2026)
- USD 2.5 Bn
- Forecast (2036)
- USD 4.3 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Hydrophobic Coatings Market in 2026?
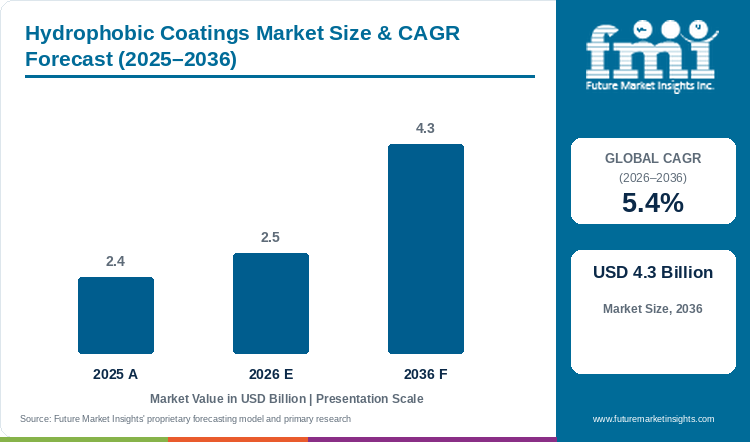
Hydrophobic coatings will grow at a CAGR of 5.4% from 2026 to 2036. Sales stood at USD 2.4 billion in 2025. For 2026, market size is estimated at USD 2.5 billion. Market size is projected to reach USD 4.3 billion by the end of 2036.
Hydrophobic coatings are worth USD 2.5 billion in 2026, up from USD 2.4 billion in 2025. Over the next decade, sales will record a 5.4% CAGR and reach USD 4.3 billion by 2036.
However, formulators will face the EU-wide PFAS restriction. For instance, ECHA's Committee for Risk Assessment completed the scientific evaluation in March 2026, European Coatings reported, and a final SEAC opinion is anticipated by the end of 2026.[1] The proposal targets all PFAS uses, bringing fluorinated repellent grades sold in Europe within scope.[1] Suppliers will therefore move repellent lines to silicone and other fluorine-free binders before the SEAC opinion.
Fluorinated repellent grades use resin from the fluoropolymer market, on a 5.6% CAGR from 2026 to 2036. Resin growth this close to hydrophobic coatings means PFAS limits change formulas sooner than volumes. Anti-fouling grades coat hulls in the marine coatings market, also on a 5.6% CAGR, so drydock repaint cycles set anti-fouling orders. Body shops in the automotive refinish coatings market, on a 5.3% CAGR, apply water-repellent clearcoats, so repair work keeps automotive near the hydrophobic average.
Automotive takes 32.6% of 2026 application sales, and anti-corrosion grades hold 27.4% of property sales. In the pursuit of growth in adjacent markets, self-cleaning grades, an estimated 21.3%, will add volume on glass and facades. As per FMI, India will grow fastest at 8% through 2036, with China second on 6%.
Key Market Trends & Insights
- Anti-corrosion formed the largest property type in 2026 at 27.4%, followed by self-cleaning at an estimated 21.3%.
- Automotive took 32.6% of application sales in 2026. France banned PFAS in water-repellent agents, textiles, ski wax, cosmetics and footwear from 1 January 2026.[2]
Regional Highlights
- Fastest-growing profiled country: India (8% CAGR, 2026 to 2036).
- By country: China grows at 6% and Spain at 4%, Canada stands at 3.3%, and the United States records 3%, the lowest of the five.
- Canada expects a proposed PFAS instrument for firefighting foams in the Canada Gazette, Part I in spring 2027, with entry into force no earlier than spring 2029.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Hydrophobic Coatings Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.4 billion |
| Estimated Market Size in 2026 | USD 2.5 billion |
| Projected Market Size by 2036 | USD 4.3 billion |
| CAGR, 2026 to 2036 | 5.4% |
| Added Revenue, 2026 to 2036 | USD 1.8 billion |
| Market Expansion Multiple | 1.7x |
Upstream fluoropolymer sales grow a shade faster than hydrophobic coatings. The fluoropolymer market carries USD 11.8 billion of 2026 sales, with a 5.6% CAGR to 2036. FMI ties hydrophobic coatings growth to construction, marine, electronics, automotive and aerospace protection. Hydrophobic coatings growth comes from surface area coated, and fluorinated additives make up only one input.
PFAS Restrictions and the Fluorine-Free Shift Across Countries
Europe sets the strictest PFAS timetable. RAC finished the science on the EU-wide PFAS restriction in March 2026, and SEAC is due to give a final opinion by the end of 2026.[1] France moved first at national level. Decree 2025-1376 put PFAS bans on textiles, ski wax, cosmetics, footwear and water-repellent agents into force on 1 January 2026.[2] Products made before that date may be sold for twelve months, and limits stand at 25 ppb for each targeted PFAS, 250 ppb for the sum and 50 ppm for PFAS including polymers.[2] Personal protective equipment and technical textiles for industrial use are exempt.[2] Spain falls under the EU rule once adopted, so Spanish applicators will buy fluorine-free grades before the French and EU dates converge.
Outside Europe, PFAS rules take the form of reporting duties in the USA, phased bans in Canada and chemical lists in China and India. EPA issued a final rule on 13 April 2026 that moved the TSCA PFAS reporting window to open on 31 January 2027 for six months.[4] Manufacturers, including importers, of PFAS or PFAS-containing articles in any year from 2011 to 2022 fall in scope.[4] Canada set consultations on Phase 2 consumer applications with known alternatives for 2027.[3] China adopted the third batch of Priority Control Chemicals on 29 December 2025, with 23 groups that include long-chain PFCAs.[5] India published a draft FSSAI amendment on 6 October 2025 to prohibit PFAS in food contact materials.[6] Coating makers will need one fluorine-free platform that clears French limits, US reporting and Chinese permit declarations together.
Table 2: PFAS Regulatory Indicators by Country for the Hydrophobic Coatings Market (dates, thresholds and substance groups), 2025 to 2027
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| EU PFAS restriction, RAC opinion | Adopted March 2026; final SEAC opinion anticipated by end of 2026 | Covers all PFAS uses, including coatings inputs. | [1] |
| France Decree 2025-1376 | In force 1 January 2026; twelve-month sell-off for older stock | Water-repellent agents are a named product category. | [2] |
| France PFAS limits | 25 ppb per targeted PFAS; 250 ppb sum; 50 ppm including polymers | Polymer limit captures fluorinated binders. | [2] |
| US TSCA PFAS reporting rule | Window opens 31 January 2027 for six months | Article importers report on PFAS content. | [4] |
| Canada Phase 1, firefighting foams | Proposed instrument spring 2027; in force no earlier than spring 2029 | Phase 2 consultations on consumer uses follow in 2027. | [3] |
| China Priority Control Chemicals, 3rd batch | 23 groups adopted 29 December 2025, including long-chain PFCAs | EIA and permit filings need to declare these chemicals. | [5] |
| India FSSAI draft packaging amendment | Published 6 October 2025; 60-day comment period | PFAS in food contact materials would be prohibited. | [6] |
Analyst Perspective
“Fluorine-free hydrophobic grades with proven durability on vehicle glass and coated steel are the largest opening in this market through 2036. Coating makers that clear French and EU PFAS limits early will set the specification that buyers in India and China adopt next.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the hydrophobic coatings market segmented?
The hydrophobic coatings market splits into property type, application and region. Anti-corrosion grades lead property type at 27.4% in 2026, and automotive leads application at 32.6%.
By property type: anti-corrosion, anti-microbial, anti-icing/wetting, anti-fouling, self-cleaning, and others.
By application: automotive, aerospace, construction, medical, optical, and others.
By region: Central Asia, North America, Balkan and Baltic Countries, East Asia, Western Europe, Latin America, Russia and Belarus, South Asia and Pacific, Eastern Europe, and Middle East and Africa.
Why do anti-corrosion coatings lead property type sales?
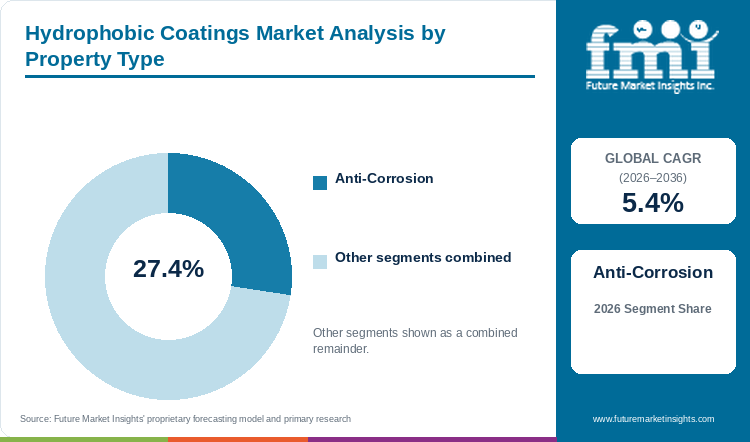
Anti-corrosion coatings account for 27.4% of 2026 property type sales, with self-cleaning grades next at an estimated 21.3%.
Table 3: Property Type Share for the Hydrophobic Coatings Market (percentage share), 2026
| Property Type | Estimated Share (2026) |
|---|---|
| Anti-Corrosion | 27.4% |
| Self-Cleaning | 21.3% |
| Anti-Fouling | 16.9% |
| Anti-Icing/Wetting | 13.8% |
| Anti-Microbial | 12.2% |
| Others | 8.4% |
| Total | 100.0% |
Table 4: Property Type Leadership and Market Growth for the Hydrophobic Coatings Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Leading Segment | Anti-Corrosion |
Steel protection covers pipelines, bridges, machinery and marine structures, a spread no single self-cleaning or anti-fouling use matches. FMI data show anti-corrosion at 27.4%. Self-cleaning follows at an estimated 21.3%, with anti-fouling at about 16.9%. Self-cleaning grades serve glass and facades, and anti-fouling grades follow hull work in the marine coatings market. Anti-icing and wetting grades hold an estimated 13.8%. NTT-AT planned November 2025 sales of a new PFAS-free HIREC version for rain, snow and ice protection.[7] Anti-microbial grades take 12.2%, tied to medical devices. Corrosion buyers already purchase from the wider anti-corrosion coatings market, so hydrophobic topcoats enter through existing maintenance specifications.
- Self-cleaning at 21.3% and anti-fouling at 16.9% form the next tier behind anti-corrosion.
- NTT-AT reported an initial water contact angle of over 150 degrees for the existing HIREC coating.[7]
Why does automotive lead application sales?
Automotive accounts for 32.6% of 2026 application sales, and construction for an estimated 24.1%.
Table 5: Application Share for the Hydrophobic Coatings Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Automotive | 32.6% |
| Construction | 24.1% |
| Aerospace | 14.7% |
| Medical | 11.5% |
| Optical | 9.8% |
| Others | 7.3% |
| Total | 100.0% |
Car makers pick water-repellent and anti-soiling finishes for glass, body panels and wheels, and construction buyers pick them for concrete and steel. Automotive holds 32.6% in the FMI breakdown. Construction follows at an estimated 24.1% and aerospace at about 14.7%. Premium vehicle output and passenger car sales in India, China and other emerging markets keep automotive ahead. Body shops in the automotive refinish coatings market add a second route to the vehicle parc. Aerospace work overlaps with the erosion protection coatings market on leading edges and panels. A 3M quarterly filing for the period ended 30 September 2025 restated the plan to exit all PFAS manufacturing by the end of 2025.[8] Medical at an estimated 11.5% and optical at roughly 9.8% close the list.
- Construction at 24.1% and aerospace at 14.7% rank behind automotive in the application split.
- 3M reported that PFAS exit restructuring had impacted approximately 1,200 positions globally.[8]
What are the drivers, restraints, and opportunities in the hydrophobic coatings market?
Demand for hydrophobic coatings is supported by corrosion, weather and contamination protection across vehicles, buildings and devices. Key challenges faced by manufacturers include PFAS compliance, high application cost and cheap counterfeit products.
- Driver: Infrastructure protection, EV and aerospace output, and medical device longevity raise coating use per asset.
- Restraint: Reformulation cost under PFAS rules, application damage risk and low-price imitations narrow margins.
- Opportunity: Fluorine-free silicone and polyurethane systems open premium lines in textiles, glass and outdoor equipment.
Outdoor Assets Need Weather and Ice Protection
NTT-AT said in October 2025 that the PFAS-free HIREC keeps the water repellency of the existing line and serves communication gear, infrastructure and artwork.[7] The stated aim is to avoid accretion of rain, snow and ice for safety or maintenance.[7] Government infrastructure programmes, sustainability projects and transport building in India add further demand, FMI finds. Telecom and utility owners will specify repellent coatings on towers, antennas and housings across cold and wet regions.
Compliance Paperwork and Application Cost Hold Back Smaller Suppliers
US article importers fall under the TSCA PFAS reporting rule, with a twelve-month window for small manufacturers that report only as importers.[4] Each coated part imported with a fluorinated finish adds a reporting line. FMI notes that high application cost and damage risk during application already limit sales. Small brands without testing budgets will exit fluorinated lines first.
Fluorine-Free Binders Reach Textile and Fabric Finishing
European Coatings reported in May 2026 on a water-borne polyurethane that avoids bio-toxic fluorides and reached a water contact angle of 148.0° on cotton.[9] Repellency held after 360 h of weathering and 50 abrasion cycles.[9] The emulsions run on conventional pad-dry-cure lines.[9] Fluorine-free textile binders form the next wave of investment opportunities, and finishers facing the French ban on PFAS water-repellent agents will test water-borne polyurethane systems first.
Which country CAGRs are profiled in the hydrophobic coatings market?
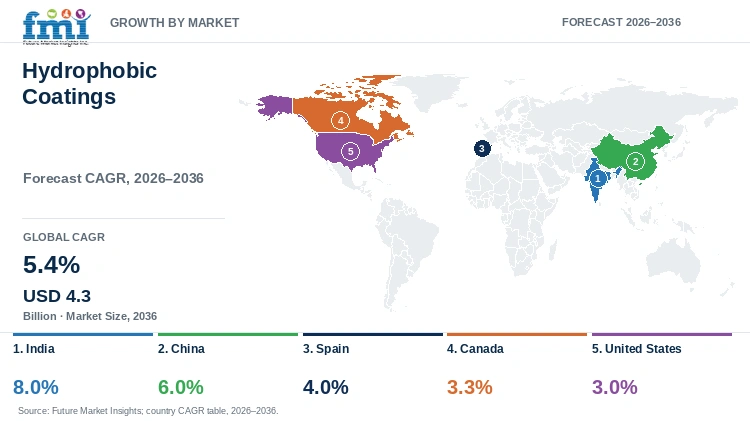
Table 6: Country CAGR Comparison for the Hydrophobic Coatings Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 8% |
| China | 6% |
| Spain | 4% |
| Canada | 3.3% |
| United States | 3% |
How do country-level CAGRs compare in the hydrophobic coatings market?
Country-level differences are shaping the outlook, with India and China growing faster than Spain, Canada and the United States. India posts 8% and China 6% from 2026 to 2036, according to FMI. Spain follows at 4%, then Canada at 3.3%, with the United States last on 3%. North America and Europe together hold about half of global sales, so North American and European demand sets the base, and the Indian 8% and Chinese 6% rates top the profiled table.
- India links EV adoption and medical infrastructure with a pending PFAS food-contact ban.
- China joins EV and aviation output with new priority control filings for long-chain PFCAs.
- Spain combines EU PFAS restriction exposure with French rules next door.
- Canada pairs a phased PFAS ban with consumer-use consultations in 2027.
- The United States matches multi-substrate coatings with TSCA PFAS reporting.
Full report country CAGRs cover: East Asia; South Asia and Pacific; Western Europe; North America; Middle East and Africa; Latin America; Eastern Europe; Central Asia; Russia and Belarus; Balkan and Baltic Countries.
Country-wise Analysis
India Hydrophobic Coatings Market Outlook (2026 to 2036)
Pharmaceutical and medical infrastructure projects create openings for anti-microbial and easy-clean grades in India. EV adoption, transport projects and foreign investment add automotive and OEM volume. FSSAI released a draft packaging amendment on 6 October 2025 that would prohibit PFAS in food contact materials, with 60 days for feedback.[6] India tops the country table at 8% CAGR for 2026 to 2036.
Key takeaway: Indian buyers face a first PFAS rule in packaging, which will push coating suppliers toward fluorine-free grades before any coatings rule arrives.
China Hydrophobic Coatings Market Outlook (2026 to 2036)
China adopted the Catalogue of Priority Control Chemicals (3rd Batch) on 29 December 2025.[5] Impact assessments for new construction projects now disclose the quantity, variety and usage of listed chemicals, and enterprises declare them when applying for discharge permits.[5] Automotive and aviation output, rapid EV growth and domestic polysiloxane production support demand. China grows at 6% CAGR from 2026 to 2036.
Key takeaway: Local polysiloxane supply gives Chinese formulators a ready fluorine-free base as permit filings tighten.
Spain Hydrophobic Coatings Market Outlook (2026 to 2036)
Spain grows at 4% CAGR from 2026 to 2036, the third-highest rate among the five profiled countries. Spanish coating buyers fall under the EU restriction process. RAC completed an opinion on the EU proposal in March 2026, and SEAC is due to give a final opinion by the end of 2026.[1] Automotive plants and construction contractors will request PFAS declarations from suppliers ahead of the SEAC opinion.
Key takeaway: Spain will follow the EU timetable, so applicators that stock compliant grades early avoid a forced switch later.
Canada Hydrophobic Coatings Market Outlook (2026 to 2036)
Canada published a Phase 1 risk management approach for PFAS in firefighting foams in September 2025, proposing to prohibit manufacture, use, sale and import.[3] Comments closed on 25 November 2025.[3] Phase 2 targets consumer applications with known alternatives, and consultations are anticipated in 2027.[3] Canadian sales expand at a 3.3% CAGR through 2036.
Key takeaway: Consumer coatings fall in the Canadian Phase 2 queue, giving suppliers about two years to qualify alternatives.
United States Hydrophobic Coatings Market Outlook (2026 to 2036)
PPG Industries, 3M, NeverWet and NEI are key US suppliers, and NeverWet grew in automotive and residential glass with a rain repellent for wet-weather visibility. Multi-substrate coatings that bond to glass, metal, plastic and concrete drive US demand. The TSCA PFAS reporting window opens on 31 January 2027.[4] The United States grows slowest of the profiled countries, with a 3% CAGR forecast for the decade.
Key takeaway: US growth is slow, and federal reporting will push importers of coated parts to document every fluorinated finish.
Who are the notable companies in the hydrophobic coatings market?
BASF SE, AkzoNobel N.V., 3M, PPG Industries, Aculon Inc., Accucoat Inc., Aurolab, Excel Coatings, NeverWet and NEI form the core supplier group for water-repellent finishes.
The market is very competitive and fast-growing, FMI finds, with construction and transportation as the main customer base. In the race to capture emerging demand, manufacturers launch sustainable products and merge with larger companies to widen ranges. Key players like NeverWet also move into commercial and residential glass work. 3M announced in 2022 a plan to exit all PFAS manufacturing by the end of 2025, and the quarterly filing for the period ended 30 September 2025 showed an accrued restructuring balance of $52 million for that plan.[8]
- Chemical and coatings majors: BASF SE, AkzoNobel N.V., 3M, and PPG Industries.
- Surface-treatment specialists: Aculon Inc., Accucoat Inc., Aurolab, Excel Coatings, NeverWet, and NEI.
Competitive Benchmarking: Hydrophobic Coatings Market
Table 7: Competitive Benchmarking for the Hydrophobic Coatings Market (qualitative documentation ratings), 2026
| Company | PFAS Disclosure | Product Range | Dated Activity | Regional Reach |
|---|---|---|---|---|
| 3M | High | High | High | High |
| NTT-AT | Medium | Low | High | Low |
| BASF SE | Medium | High | Low | High |
| AkzoNobel N.V. | Medium | High | Low | High |
| NeverWet | Low | Low | Low | Medium |
Ratings track dated PFAS and product activity and say nothing about share, rank or product performance.
Key Developments in the Hydrophobic Coatings Market
- In May 2026, European Coatings reported a fluorine-free water-borne polyurethane coating with a 148.0° water contact angle on cotton.[9]
- In April 2026, EPA issued a final rule moving the TSCA PFAS reporting window to 31 January 2027.[4]
- In March 2026, ECHA's RAC completed an opinion on the EU-wide PFAS restriction.[1]
- In December 2025, China adopted 23 groups of Priority Control Chemicals, including long-chain PFCAs.[5]
- In December 2025, France signed Decree 2025-1376, applying PFAS bans from 1 January 2026.[2]
- In October 2025, NTT-AT announced a PFAS-free version of the HIREC super-hydrophobic coating.[7]
- In October 2025, FSSAI released a draft amendment to prohibit PFAS in food contact materials.[6]
- In September 2025, Canada published the Phase 1 PFAS risk management approach for firefighting foams.[3]
Key Players in the Hydrophobic Coatings Market
Chemical and Coatings Majors
- BASF SE
- AkzoNobel N.V.
- 3M
- PPG Industries
Surface-Treatment Specialists
- Aculon Inc.
- Accucoat Inc.
- Aurolab
- Excel Coatings
- NeverWet
- NEI
Hydrophobic Coatings Market - Report Scope
Table 8: Report Scope for the Hydrophobic Coatings Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Property type; application; region |
| Quantitative units | USD billion |
| Market definition | Water-repellent surface coatings with anti-corrosion, anti-microbial, anti-icing or wetting, anti-fouling and self-cleaning properties for automotive, aerospace, construction, medical, optical and other uses. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; Balkan and Baltic Countries; Russia and Belarus; Central Asia; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; Spain; Canada; United States |
| Key companies profiled | BASF SE, AkzoNobel N.V., Aculon Inc., Accucoat Inc., 3M, Aurolab, Excel Coatings, PPG Industries, NeverWet, NEI |
| Forecast period | 2026 to 2036 |
Hydrophobic Coatings Market - Research Methodology
Table 9: Research Methodology for the Hydrophobic Coatings Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Regulatory facts come from government decrees and notices, company filings and trade press dated May 2025 or later. |
| Desk Research | Desk research covers PFAS restriction milestones in the EU, France, the US, Canada, China and India, plus fluorine-free product releases. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 2.4 billion and the 5.4% CAGR. |
| Data Validation | Restriction dates and thresholds come straight from the decrees, final rules and agency opinions in each jurisdiction. |
Hydrophobic Coatings Market by Segments
Hydrophobic Coatings Market segmented by Property Type:
- Anti-Corrosion
- Anti-Microbial
- Anti-Icing/Wetting
- Anti-Fouling
- Self-Cleaning
- Others
Hydrophobic Coatings Market segmented by Application:
- Automotive
- Aerospace
- Construction
- Medical
- Optical
- Others
Hydrophobic Coatings Market by Region
- North America
- United States
- Canada
- Latin America
- Western Europe
- Spain
- Eastern Europe
- Balkan and Baltic Countries
- Russia and Belarus
- Central Asia
- East Asia
- China
- South Asia and Pacific
- India
- Middle East and Africa
Research Sources and Bibliography
- [1] European Coatings. (2026, March 5). ECHA's RAC adopts opinion on PFAS restriction proposal. https://www.european-coatings.com/news/legislation/echas-rac-adopts-opinion-on-pfas-restriction-proposal/
- [2] AIDA, INERIS. (2025, December 28). Décret n° 2025-1376 du 28/12/25 relatif à la prévention des risques résultant de l'exposition aux substances perfluoroalkylées et polyfluoroalkylées. https://aida.ineris.fr/reglementation/decret-ndeg-2025-1376-281225-relatif-a-prevention-risques-resultant-lexposition
- [3] Environment and Climate Change Canada. (2025, September 26). Risk management approach for PFAS, Phase 1: firefighting foams. https://www.canada.ca/en/environment-climate-change/services/canadian-environmental-protection-act-registry/publications/risk-management-pfas-phase1-firefighting-foams-afff.html
- [4] SGS. (2026, May 4). SafeGuardS 063/26: US EPA Extends TSCA PFAS Reporting Rule. https://www.sgs.com/en-us/news/2026/05/safeguards-06326-us-epa-extends-tsca-pfas-reporting-rule
- [5] ChemLinked. (2025, December 31). China consults on new batch of priority control chemicals including BPA and LC-PFCAs. https://chemical.chemlinked.com/news/chemical-news/china-consults-on-new-batch-of-priority-control-chemicals-including-bpa-and-lc-pfcas
- [6] ChemRadar. (2025, November 5). India Plans to Completely Ban PFAS and Bisphenol A in Food Contact Materials. https://www.chemradar.com/en/service/detail/f36du4j43oqo
- [7] Meteorological Technology World Expo. (2025, October 10). NTT-AT has successfully developed a PFAS-free super-hydrophobic coating HIREC. https://meteorologicaltechnologyworldexpo.com/exhibitor-news/ntt-at-has-successfully-developed-a-pfas-free-super-hydrophobic-coating-hirec
- [8] 3M Company (SEC filing). (2025, October). Form 10-Q for the quarterly period ended September 30, 2025. https://www.sec.gov/Archives/edgar/data/66740/000006674025000089/mmm-20250930.htm
- [9] European Coatings. (2026, May 15). Fluorine-free WPU coating delivers durable water repellency. https://www.european-coatings.com/?p=159639
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will hydrophobic coatings market size be in 2026?
- What value will the market reach by 2036?
- Which property type will hold the largest share?
- Which application will lead sales?
- Which countries will grow fastest?
- Which companies will compete in hydrophobic coatings?
Frequently Asked Questions
How large is the hydrophobic coatings market expected in 2026?
In 2026, hydrophobic coatings market size will stand at USD 2.5 billion. By 2036, the FMI forecast puts market size at USD 4.3 billion.
What CAGR is projected for the hydrophobic coatings market through 2036?
A CAGR of 5.4% will hold from 2026 to 2036. Infrastructure, vehicles and medical devices will carry the USD 1.8 billion added by 2036.
Which property type holds a notable market share in 2026?
Anti-corrosion grades will lead with 27.4% of property type sales in 2026. Self-cleaning grades will follow at an estimated 21.3%.
Which application holds a notable market share in 2026?
In 2026, automotive will make up 32.6% of application sales, and construction will add about 24.1% (estimated).
Which country has a notable expansion outlook through 2036?
India will post 8% CAGR over 2026 to 2036, the top profiled rate, FMI finds. China will follow at 6%.
Who are the key companies in the hydrophobic coatings market?
BASF SE, AkzoNobel N.V., 3M and PPG Industries will anchor the large-company group. Aculon, Accucoat, Aurolab, Excel Coatings, NeverWet and NEI will compete as specialists.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Property Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Property Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Property Type, 2026 to 2036
- Anti-Corrosion
- Anti-Microbial
- Anti-Icing/Wetting
- Anti-Fouling
- Self-Cleaning
- Others
- Y-o-Y Growth Trend Analysis By Property Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Property Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Automotive
- Aerospace
- Construction
- Medical
- Optical
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Property Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Property Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Spain
- By Property Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Balkan and Baltic Countries
- Russia and Belarus
- Central Asia
- By Property Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- By Property Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- By Property Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Property Type
- By Application
- Market Attractiveness Analysis
- By Country
- By Property Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Property Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Property Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Property Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Property Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Property Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Property Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- 3M
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- NTT-AT
- BASF SE
- AkzoNobel N.V.
- NeverWet
- PPG Industries
- Aculon Inc.
- Accucoat Inc.
- Aurolab
- Excel Coatings
- NEI
- 3M
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


