
- Market Size (2026)
- USD 42.0 Bn
- Forecast (2036)
- USD 93.2 Bn
- CAGR (2026 to 2036)
- 8.3%
How big is Lactose-free Products Market in 2026?
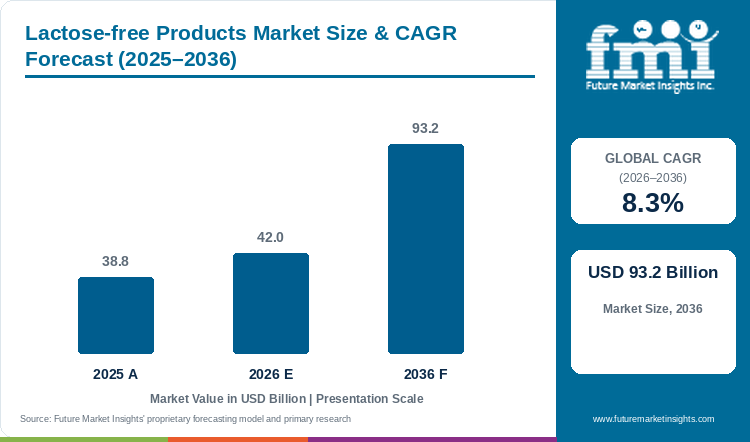
Sales in the lactose-free products market are projected to grow at 8.3% CAGR, with the market size rising from USD 38.8 billion in 2025 to USD 42.0 billion in 2026 and reaching USD 93.2 billion by 2036.
Dairy creameries are retrofitting fluid bottling plants with ceramic microfiltration membranes and inline lactase dosing so lactose-sensitive households can drink real cow milk without abdominal bloating. Inline enzyme cleavage runs on existing pasteurization lines at near-parity cost with conventional milk, allowing standard commercial grade to capture 38.1% of product type / grade revenue in 2026. In March 2025, National Institute of Diabetes and Digestive and Kidney Diseases clinical guidance confirmed that roughly 68% of the adult population globally experiences lactase non-persistence after weaning. As per the analysis from FMI, industry sales climb from USD 38.8 billion in 2025 to USD 42.0 billion in 2026 and are forecast to attain USD 93.2 billion by 2036 at an 8.3% CAGR, generating USD 51.2 billion in added value despite high UHT energy bills.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade accounted for 38.1% of demand in 2026, reinforced by high-volume enzymatic fluid milk conversion and supermarket private-label pricing.
- By processing state: With a 44.5% share in 2026, fresh / ambient packaged led the category, bolstered by aseptic UHT cartons and extended-shelf-life refrigerated bottles.
- By end-use application: Direct retail consumer consumption led the market with a share of 49.1% in 2026, linked to daily household breakfast, coffee, and cooking routines.
Regional Highlights
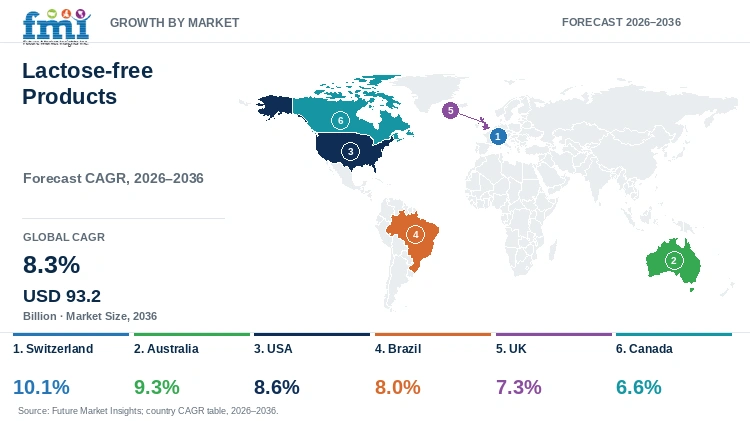
- Fastest-growing evaluated country: Switzerland, at 10.1% CAGR from 2026 to 2036.
- By country: Australia at 9.3%, the USA at 8.6%, Brazil at 8.0%, and the UK at 7.3% follow, while Canada records the lowest evaluated CAGR at 6.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Lactose-free Products Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 38.8 billion |
| Estimated Market Size in 2026 | USD 42.0 billion |
| Projected Market Size by 2036 | USD 93.2 billion |
| CAGR, 2026 to 2036 | 8.3% |
| Added Revenue, 2026 to 2036 | USD 51.2 billion |
Swiss alpine creameries and American ultrafiltration plants invest heavily in physical membrane separation to preserve natural milk flavor, whereas Brazilian and Australian processors rely on aseptic UHT cartons to survive warm-weather freight routes. Conventional batch lactase hydrolysis splits milk sugar into glucose and galactose, making fluid milk taste noticeably sweeter unless part of the lactose is filtered out beforehand. Analytical guidance on verifying residual disaccharide thresholds below 0.01% in enzyme-treated dairy products was updated by European Food Safety Authority scientific panels in May 2025. Consequently, large dairy cooperatives are pairing spiral-wound membrane ultrafiltration with sterile post-hydrolysis enzyme dosing to maintain a clean cow-milk profile.
Enzymatic Processing and Membrane Filtration Operational Metrics
Table 2: Enzymatic Processing and Membrane Filtration Operational Metrics for the Lactose-free Products Market (USD billion, billion liters, ppm, and percentage), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 38.8 | 42.0 | 93.2 |
| Commercial fluid milk volume treated (billion liters) | 28.5 | 30.8 | 62.4 |
| Average neutral lactase enzyme dosing rate (ppm) | 420 to 520 | 400 to 500 | 320 to 410 |
| Residual lactose content in finished milk (%) | Below 0.01 | Below 0.01 | Below 0.005 |
Fluid milk conversion volumes and ppm dosing rates cover inline aseptic and extended-shelf-life dairy lines complying with European and North American zero-lactose thresholds.
Facility Capital Expenditure & Processing Yardstick Metrics
Modern creameries pair ultra-high-temperature steam injection with sterile inline injection of neutral lactase enzymes right before aseptic carton filling. Dosing the enzyme after heat sterilization cuts required enzyme volume by more than half while preventing Maillard browning during UHT heating. Quality-control labs also run high-performance liquid chromatography tests on every batch to confirm complete disaccharide cleavage prior to supermarket dispatch.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Lactose-free Products Market (thousand plants, USD thousand, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global processing dairy footprint (thousand plants) | 4.8 | 5.1 | 7.9 |
| Lactase enzyme spend per processing plant (USD thousand) | 215 to 310 | 230 to 330 | 380 to 510 |
| Microfiltration membrane replacement cost per line (USD thousand) | 75 to 95 | 80 to 102 | 110 to 145 |
| Quality testing expenditure per production run (USD) | 410 to 580 | 430 to 610 | 580 to 820 |
Table 4: Facility and Operational Cost Benchmark Metrics for the Lactose-free Products Market (percentages, USD, and USD cents), mixed reporting years from 2024 to 2026
| Operational Cost Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Enzyme cost share of total conversion expense (%) | 14.2 to 18.5 | 15.0 to 19.2 | 15.5 to 19.8 |
| UHT sterilization energy outlay per thousand liters (USD) | 38 to 48 | 40 to 51 | 42 to 53 |
| Cold storage operating cost per pallet space (USD monthly) | 22 to 31 | 24 to 34 | 26 to 36 |
| Aseptic carton packaging material expense per pack (USD cents) | 12 to 16 | 13 to 17 | 14 to 18 |
Creamery conversion expenses track fungal and yeast lactase contracts, ceramic membrane replacement cycles, and UHT steam-sterilization tariffs in Switzerland, Germany, and the United States.
Analyst Perspective
"Combining ceramic membrane filtration with neutral lactase hydrolysis lets dairies deliver natural cow-milk taste without digestive discomfort. High membrane replacement and UHT energy costs still pressure margins on private-label fluid milk."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the lactose-free products market segmented?
The lactose-free products market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 38.1% of product type / grade, fresh / ambient packaged at 44.5% of processing state, and direct retail consumer consumption at 49.1% of end-use application.
By product type / grade: Standard commercial grade, organic & clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen & chilled, and dehydrated & dry packaged.
By end-use application: Direct retail consumer consumption, food service & hospitality, and commercial food manufacturing plants.
Why does Standard Commercial Grade lead the product type / grade category?
Standard commercial grade is anticipated to hold 38.1% of product type / grade sales in 2026, reinforced by mainstream grocery pricing.
Table 5: Product Type / Grade Share for the Lactose-free Products Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 38.1% |
| Other Segments Combined | 61.9%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Lactose-free Products Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.3% |
| Leading Segment | Standard Commercial Grade |
Continuous inline lactase dosing runs directly on existing pasteurization and ESL bottling lines without requiring segregated organic farm collection. Organic and grass-fed specialty variants carry a 40% retail price premium, so supermarket chains use standard commercial grade fluid milk, yogurt, and cheddar formulated from conventional milk ingredients to keep weekly grocery bills manageable for families switching away from regular milk. High bottling speeds allow private-label retailers to anchor the refrigerated dairy case with standard half-gallon cartons, provided creameries monitor enzyme purity so trace protease side-activities do not cause bitterness during storage.
- Across product type / grade, standard commercial grade is anticipated to contribute 38.1% of sales in 2026, reinforced by inline enzymatic conversion and private-label grocery placement.
- Dairy processing assessments published by the Food and Agriculture Organization in June 2025 showed that continuous membrane and enzymatic fluid milk lines widened mainstream retail affordability across global creameries.
What supports Fresh / Ambient Packaged leadership within processing state?
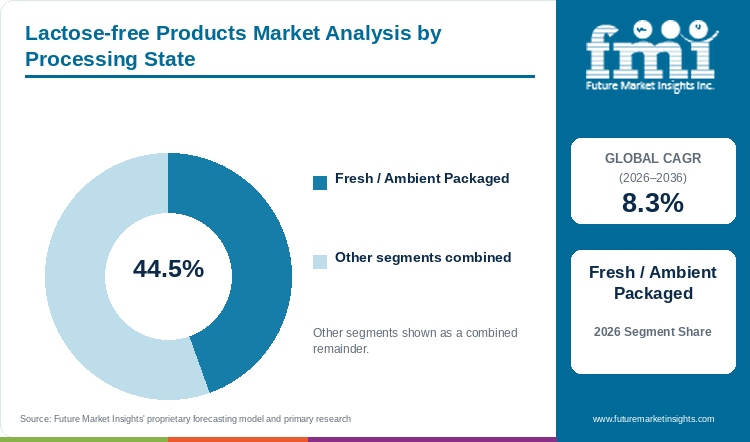
Fresh / ambient packaged is set to command 44.5% of processing state revenue in 2026, bolstered by aseptic carton stability.
Multi-layer aseptic brick cartons and extended-shelf-life (ESL) gable-top bottles dominate processing volume because enzyme-treated milk requires hermetic light and oxygen barriers to prevent hexose sugar caramelization. Across warm-weather corridors in Latin America and Asia-Pacific, ambient UHT lactose-free milk ships in non-refrigerated trucks and sits in household pantries for months before opening. Industrial bakeries and chocolate makers also blend zero-lactose skimmed milk powder into dry mixes, yet ready-to-drink fluid cartons generate the largest recurring turnover when direct-steam-injection temperatures are calibrated to prevent cooked off-flavors.
- Multi-week ESL refrigeration and ambient UHT brick distribution place fresh / ambient packaged at 44.5% of processing state revenue in 2026.
- Aseptic UHT lactose-free cartons expanded non-refrigerated regional distribution reach by 28%, according to the International Dairy Federation's April 2025 World Dairy Situation bulletin.
How does Direct Retail Consumer Consumption anchor the end-use application category?
Direct retail consumer consumption is expected to retain 49.1% of end-use application demand in 2026, linked to household breakfast habits.
Lactose-intolerant shoppers want real dairy calcium, complete whey and casein proteins, and familiar micro-foaming behavior in morning coffee and cereal bowls, making retail grocery carts the largest end-use channel. Some households rotate between cow milk and plant-based milk, yet parents cooking savory sauces or feeding children prefer enzyme-cleaved dairy that matches conventional milk nutrition label-for-label. Supermarkets now stock lactose-free Greek yogurt, cottage cheese, and sour cream beside conventional tubs, although regional creameries still face steep chiller slotting fees.
- Household repeat purchases across fluid milk and cultured cups keep direct retail consumer consumption at 49.1% of end-use application demand in 2026.
- Retail scanner tracking from the National Milk Producers Federation in February 2025 recorded household repeat-purchase rates above 74% for enzyme-treated fluid dairy cartons.
What are the drivers, restraints, and opportunities in the lactose-free products market?
Adult lactase non-persistence shifts daily grocery purchases toward lactose-free products, even as membrane fouling and UHT power bills pressure creamery margins while ultrafiltered high-protein dairy drinks unlock premium growth through 2036.
- Driver: Rising clinical diagnosis of adult lactose malabsorption shifts daily household milk, yogurt, and cheese purchases toward enzyme-cleaved dairy lines.
- Restraint: Ceramic microfiltration membrane fouling, neutral lactase enzyme expenses, and UHT sterilization power bills compress processor margins.
- Opportunity: Combining zero-lactose ultrafiltration with native whey and casein concentration unlocks high-margin sports recovery and clinical nutrition beverages.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Gastroenterologists and primary-care dietitians increasingly advise lactose-sensitive adults to switch to enzyme-cleaved dairy rather than cutting out dairy entirely and risking calcium, vitamin D, and potassium deficits. Because neutral fungal and yeast lactase enzymes split milk sugar without altering native casein micelles or milkfat globules, shoppers get identical culinary performance in baking and coffee steaming. Controlled adult feeding trials published in the American Journal of Clinical Nutrition in May 2025 confirmed that zero-lactose dairy intake maintained bone-mineral calcium absorption without triggering gastrointestinal distension. Owing to this clinical backing, grocers are expanding refrigerated doors for functional dairy products across urban supermarkets.
Risk Assessment of the Lactose-free Products Market: Operational and Formulation Friction
Converting a standard pasteurized fluid milk plant into a zero-lactose facility requires heavy capital outlay on cross-flow ceramic microfiltration skids, sterile post-UHT enzyme dosing pumps, and inline sugar analyzers. Industrial plant benchmarks released by the European Dairy Association in July 2025 showed that UHT sterilization and membrane filtration raised creamery electricity and enzyme conversion costs by 18% per thousand liters. Residual monosaccharides also darken rapidly via Maillard reactions when processors spray-dry dry whole milk powder, forcing powder plants to run slower, lower-temperature drying towers that reduce daily throughput.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Passing skim milk through spiral-wound ultrafiltration membranes removes water and dissolved lactose simultaneously, concentrating native casein and whey protein up to 13 to 18 grams per serving before a small dose of lactase clears the remaining trace disaccharide. Athletic consumers and older adults pay wide retail premiums for these high-protein, reduced-sugar dairy shakes over standard fluid milk. Valio expanded commercial licensing and powder production of its ultrafiltered zero-lactose milk protein bases in March 2025 for ready-to-drink sports recovery and senior nutrition brands. Dairies that master membrane fractionation can monetize both high-protein beverages and purified permeate streams.
Lactose-free Products Market by Country (2026 to 2036)
Switzerland posts the fastest expansion among the six profiled markets at a 10.1% CAGR through 2036, followed by Australia at 9.3% and the United States at 8.6%, while Canada grows at a steady 6.6% CAGR. National trajectories reflect how effectively local creameries position clean-tasting ultrafiltered cow milk against barista oat milk while managing cold-chain and quota rules.
Table 7: Country CAGR and Primary Growth Levers for the Lactose-free Products Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Switzerland | 10.1% | Precision alpine dairy membrane filtration and high per-capita specialty yogurt and milk spending |
| Australia | 9.3% | Supermarket digestive-wellness dairy cases and aseptic UHT exports into Southeast Asia |
| USA | 8.6% | Ultrafiltered high-protein zero-lactose milk brands and national supermarket private-label conversion |
| Brazil | 8.0% | Rapid zero-lactose UHT carton expansion across urban supermarkets and regional bakeries |
| UK | 7.3% | Supermarket private-label Lactofree-style ranges and mature lactose-free cheddar adoption |
| Canada | 6.6% | Dedicated industrial milk quota allocations and cooperative ultrafiltration plant upgrades |
Source: Future Market Insights analysis
Switzerland Lactose-free Products Market Outlook (2026 to 2036)
Swiss dairy cooperatives combine strict alpine raw-milk quality with early adoption of cross-flow membrane filtration across domestic fluid milk, quark, and mountain cheese lines. Switzerland is forecast to emerge as a high-growth market, registering 10.1% CAGR through 2036, propelled by strong shopper willingness to pay for clean-taste ultrafiltered dairy. Annual consumption data from the Swiss Federal Food Safety and Veterinary Office in October 2025 showed an 8.0% year-on-year rise in retail sales of zero-lactose fluid milk and cultured alpine dairy products. Steep mountain milk-collection routes still keep base farmgate costs high, so Swiss creameries focus on high-margin barista milks, protein quarks, and aged specialty cheeses.
Key takeaway: Precision membrane filtration and premium alpine quark and cheese lines make Switzerland the fastest-growing profiled market.
Australia Lactose-free Products Market Outlook (2026 to 2036)
High café coffee culture and widespread digestive-health awareness in Melbourne, Sydney, and Brisbane have made lactose-free full-cream and skim cartons a staple in Australian supermarkets and espresso bars. Industry tracking published by Dairy Australia in September 2025 indicated that specialized lactose-free fluid milks captured 18% of domestic supermarket carton revenue. In Australia, demand for lactose-free products is predicted to advance at 9.3% CAGR through 2036, supported by aseptic UHT exports to Singapore and Malaysia. Long summer freight routes across regional states still challenge chilled distribution, prompting Australian processors to pair ESL chilled bottles in metro areas with UHT brick packs for outback and export accounts.
Key takeaway: Australian café barista adoption and aseptic UHT export lines into Southeast Asia underpin strong commercial volume expansion.
USA Lactose-free Products Market Outlook (2026 to 2036)
The USA lactose-free products market is anticipated to grow at 8.6% CAGR between 2026 and 2036, fueled by ultrafiltered high-protein milk brands and national supermarket private-label conversions. Rather than treating zero-lactose milk as a slow-moving medical item, American grocers allocate prime eye-level chiller doors to ultrafiltered half-gallons that pack 50% more protein and half the sugar of conventional milk. Commercial dairy data from the United States Department of Agriculture Economic Research Service in January 2026 confirmed that domestic lactose-free fluid milk volume surpassed 2.0 billion quarts. Refrigerated trucking inflation still squeezes regional fluid margins, so large U.S. cooperatives are building centralized ESL aseptic plants near interstate hubs.
Key takeaway: Ultrafiltered high-protein dairy brands and national supermarket private labels continue to win American chiller space from regular fluid milk.
Brazil Lactose-free Products Market Outlook (2026 to 2036)
Mandatory front-of-pack 'Zero Lactose' labeling rules and high adult hypolactasia prevalence across urban Brazil have spurred domestic dairies to convert standard UHT brick lines to enzymatic hydrolysis. Annual livestock statistics from the Brazilian Ministry of Agriculture and Livestock (MAPA) in August 2025 documented a 14% expansion in zero-lactose UHT fluid and condensed milk lines across southern and southeastern dairy plants. Sales of lactose-free products in Brazil are forecast to expand at 8.0% CAGR through 2036, aided by ambient UHT cartons that bypass uneven interior cold chains. Imported fungal lactase enzymes remain exposed to currency swings, encouraging large Brazilian dairies to negotiate annual bulk enzyme supply contracts.
Key takeaway: Shelf-stable zero-lactose UHT brick cartons allow Brazilian dairies to reach nationwide retail shelves without cold-chain bottlenecks.
UK Lactose-free Products Market Outlook (2026 to 2036)
Dedicated 'Free From' supermarket chillers across Tesco, Sainsbury's, and Asda support a projected 7.3% CAGR in the UK from 2026 to 2036. Aggressive supermarket own-label pricing compresses margins on basic semi-skimmed cartons, pushing British dairy processors to expand zero-lactose mature cheddar, spreadable butter, and indulgent whipping creams. Food hypersensitivity and hygiene guidance updated by the UK Food Standards Agency in June 2025 tracked 24% British household penetration for lactose-free and allergen-controlled dairy items. Culinary creams and aged cheeses face far less texture competition from plant-based alternatives in British kitchens.
Key takeaway: Zero-lactose cheddar, butter, and culinary cream lines in the UK offset tight supermarket private-label margins on fluid milk.
Canada Lactose-free Products Market Outlook (2026 to 2036)
Annual dairy statistics released by the Canadian Dairy Commission in December 2025 showed that commercial processors allocated 12% of specialized fluid milk quotas to lactose-free production. Demand across the Canada lactose-free products sector is expected to increase at 6.6% CAGR through 2036, reinforced by multicultural urban demographics in Toronto, Montreal, and Vancouver with high lactose sensitivity. Canada's supply-managed dairy framework provides processors with predictable farmgate milk pricing while channeling capital into ultrafiltered and ESL bottling plants. Because provincial quota rules cap raw-milk intake surges, Canadian cooperatives maximize revenue by shifting milk solids into higher-margin zero-lactose Greek yogurts and barista milks.
Key takeaway: Cooperative membrane-filtration upgrades and multicultural urban demand drive Canadian conversion toward higher-margin zero-lactose dairy lines.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the lactose-free products market?
Lactalis Group, Danone S.A., Valio Ltd., Arla Foods amba, Saputo Inc., HP Hood LLC, Green Valley Creamery, Liddells, The Kraft Heinz Company, and Nestle S.A. are the notable companies in this market.
Securing national grocery chiller doors in the lactose-free dairy sector depends on eliminating the overly sweet aftertaste of batch-hydrolyzed milk while verifying below-0.01% residual lactose on every production run. Multinational dairy groups and farmer-owned European cooperatives operate continuous ceramic microfiltration and aseptic UHT bottling complexes that supply both flagship brands and supermarket private labels, competing directly beside almond milk in digestive-wellness aisles. Regional creameries focus on licensed ultrafiltered fluid milks and certified organic cultured yogurts and cheeses.
- Multinational Dairy & Nutrition Conglomerates: Lactalis Group, Danone S.A., Saputo Inc., The Kraft Heinz Company, and Nestle S.A. operate multi-regional fluid dairy, yogurt, cheese, and pediatric nutrition plants.
- Membrane-Filtration & Farmer-Owned Cooperatives: Valio Ltd. and Arla Foods amba pioneer zero-lactose membrane separation, lactase hydrolysis, and zero-lactose milk powders.
- Regional Fluid & Clean-Label Creamery Specialists: HP Hood LLC, Green Valley Creamery, and Liddells focus on North American and Asia-Pacific ESL fluid milk, organic cultured dairy, and UHT cartons.
Competitive Benchmarking: Lactose-free Products Market
Table 8: Competitive Benchmarking for the Lactose-free Products Market (qualitative capability ratings), 2026
| Company | Zero-Lactose Portfolio Breadth | Membrane & Enzyme Technology Depth | Retail & Foodservice Access | Geographic Reach |
|---|---|---|---|---|
| Lactalis Group | High | High | High | High |
| Danone S.A. | High | High | High | High |
| Valio Ltd. | High | High | High | High |
| Arla Foods amba | High | High | High | High |
| Saputo Inc. | High | Medium | High | High |
| HP Hood LLC | Medium | High | High | Medium |
| Green Valley Creamery | Medium | Medium | Medium | Medium |
| Liddells | Medium | Medium | High | Medium |
| The Kraft Heinz Company | Medium | Medium | High | High |
| Nestle S.A. | High | High | High | High |
Scoring basis: Benchmark classifications assess product coverage across fluid milk, cultured yogurt, cheese, butter, and dairy powders, proprietary ultrafiltration and sterile post-hydrolysis dosing assets, supermarket and café distribution contracts, and international processing plant footprints.
Key Developments in the Lactose-free Products Market
- Danone S.A. introduced a zero-lactose symbiotic probiotic yogurt range across European supermarkets in October 2025 to address adult disaccharide sensitivity and gut health simultaneously.
- Production capacity for Lactofree spreadable butter and culinary cream lines was expanded by 30% by Arla Foods amba in July 2025 across its European dairy refineries.
- Lactalis Group committed USD 55.0 million in February 2025 to install continuous ceramic microfiltration and aseptic bottling lines at its primary European fluid milk complexes.
Key Players in the Lactose-free Products Market
Multinational Dairy and Nutrition Conglomerates
- Lactalis Group
- Danone S.A.
- Saputo Inc.
- The Kraft Heinz Company
- Nestle S.A.
Membrane-Filtration and Farmer-Owned Cooperatives
- Valio Ltd.
- Arla Foods amba
Regional Fluid and Clean-Label Creamery Specialists
- HP Hood LLC
- Green Valley Creamery
- Liddells
Lactose-free Products Market - Report Scope
Table 9: Report Scope for the Lactose-free Products Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from lactose-free and lactose-reduced dairy products, enzymatic lactase-treated fluid milk, yogurts, cheeses, and infant formulas containing less than 0.1% residual lactose. Excludes 100% plant-based non-dairy drinks and standard untreated dairy. Category Allocation Note: Processing states and grades reflect enzymatic lactase hydrolysis batch cycles and aseptic refrigerated packaging configurations across commercial dairy creameries. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Switzerland, Australia, USA, Brazil, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Lactalis Group, Danone S.A., Valio Ltd., Arla Foods amba, Saputo Inc., HP Hood LLC, Green Valley Creamery, Liddells, The Kraft Heinz Company, Nestle S.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
As noted by FMI, the report covers enzyme-treated and membrane-filtered lactose-free dairy products and excludes unfortified non-dairy beverages outside the defined segmentation.
Lactose-free Products Market - Research Methodology
Table 10: Research Methodology for the Lactose-free Products Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with dairy processing plant directors, enzymology specialists, membrane filtration engineers, and supermarket category managers across key markets to validate lactase dosing rates, filtration yields, and retail pricing. |
| Secondary Research | Secondary research included national agricultural dairy databases, International Dairy Federation bulletins, food safety authority publications, company annual reports, investor filings, and dairy technology journals. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches reconciling commercial fluid milk and dairy solids conversion volumes against retail scanner sales. |
| Data Triangulation and Validation | Data is validated against adult lactose malabsorption epidemiology, lactase enzyme shipment volumes, aseptic carton output, and historical category growth to ensure high accuracy without double counting adjacent categories. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's specialized dairy econometric model, calibrating evaluated national growth rates against the 8.3% global baseline through verified adult lactose malabsorption prevalence, retail lactose-free milk price parity, and extended-shelf-life (ESL) filling capacity. |
| Operational Benchmark Traceability | Operational benchmarks (commercial fluid milk volume enzymatically treated, lactase enzyme dosage concentrations, and residual galactose chromatography assay costs) represent modeled estimates synthesized from NIH NIDDK digestive statistics, USDA dairy data, and commercial dairy cooperative filings. |
Lactose-free Products Market by Segments
Lactose-free Products Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Lactose-free Products Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Lactose-free Products Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Lactose-free Products Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Switzerland
- United Kingdom
- Germany
- France
- Italy
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Australia
- New Zealand
- India
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK). (2025, March 11). Clinical epidemiology of adult lactase non-persistence and dietary management. Definition & Facts for Lactose Intolerance.
- [2] European Food Safety Authority. (2025, May 22). Scientific opinion on residual disaccharide thresholds and analytical verification in enzyme-treated dairy formulations. EFSA Journal, 23(4), 8912.
- [3] Food and Agriculture Organization of the United Nations. (2025, June 14). Global dairy processing developments, membrane filtration, and value-added consumer nutrition. The State of Food Security and Nutrition in the World 2025.
- [4] International Dairy Federation (IDF). (2025, April 18). World Dairy Situation report: Aseptic UHT and extended-shelf-life lactose-free milk developments. IDF Bulletin No. 528.
- [5] National Milk Producers Federation (NMPF). (2025, February 19). Retail scanner trends and household repeat purchasing for enzyme-cleaved fluid dairy drinks. NMPF Policy Briefs, 15(3), 22-37.
- [6] American Journal of Clinical Nutrition. (2025, May 09). Enzymatic lactose hydrolysis, calcium retention, and gastrointestinal comfort among lactose-sensitive adults. AJCN Clinical Studies, 121(3), 512-526.
- [7] European Dairy Association (EDA). (2025, July 15). Energy consumption benchmarks, UHT sterilization costs, and membrane filtration efficiency in European creameries. EDA Technical Bulletin, 14, 88-104.
- [8] Valio Ltd. (2025, March 24). Expansion of ultrafiltered zero-lactose milk protein powder and technology licensing for functional beverages. Valio Corporate Newsroom.
- [9] Swiss Federal Food Safety and Veterinary Office (FSVO). (2025, October 20). Annual report on Swiss dairy consumption trends and zero-lactose retail growth. FSVO Regulatory Review, 31, 74-91.
- [10] Dairy Australia. (2025, September 16). Australian dairy industry in focus: Specialized lactose-free fluid milks and Southeast Asian export volumes. Dairy Australia Industry Reports, 21, 60-78.
- [11] United States Department of Agriculture Economic Research Service. (2026, January 15). U.S. commercial fluid milk sales and specialized lactose-free volume statistics. Dairy Data | Economic Research Service - USDA.
- [12] Ministerio da Agricultura e Pecuaria (MAPA). (2025, August 26). Anuario estatistico da pecuaria de leite e linhas UHT zero lactose no Brasil. MAPA Statistical Series, 28, 102-120.
- [13] UK Food Standards Agency. (2025, June 05). Consumer food hypersensitivity tracking and dairy allergen hygiene management in the United Kingdom. Safer Food, Better Business (SFBB) Guidance.
- [14] Canadian Dairy Commission (CDC). (2025, December 12). Annual dairy statistics and specialized industrial milk quota allocations for lactose-free processing. CDC Statistical Bulletin, 37, 85-99.
- [15] Danone S.A. (2025, October 17). Launch of clinical digestive wellness yogurt range combining zero-lactose hydrolysis with symbiotic probiotic strains. Danone Corporate Press Releases.
- [16] Arla Foods amba. (2025, July 23). Thirty percent capacity expansion for Lactofree spreadable butter and culinary cream lines in Europe. Arla Foods Operations News.
- [17] Lactalis Group. (2025, February 11). USD 55.0 million capital investment in continuous ceramic microfiltration and aseptic fluid milk lines. Lactalis Corporate Announcements.
- [18] Saputo Inc. (2026, January 21). Deployment of automated inline HPLC residual-lactose verification across North American and Australian fluid milk plants. Saputo Operations Updates.
- [19] HP Hood LLC. (2025, November 06). Expansion of extended-shelf-life aseptic lactose-free fluid milk bottling lines across North American facilities. HP Hood Corporate Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the lactose-free products market in 2026 and what is forecast for 2036?
- How does combining ceramic membrane ultrafiltration with lactase dosing prevent overly sweet milk flavor?
- Why do supermarket private labels anchor standard commercial grade at 38.1% of product type / grade sales?
- How do aseptic UHT brick cartons expand fresh / ambient packaged distribution in warm climates?
- How do daily household breakfast and coffee routines keep direct retail consumer consumption at 49.1% share?
- What operational and dietary factors position Switzerland and Australia as the fastest-growing profiled countries?
- How are dairy processors using ultrafiltration to launch high-protein zero-lactose sports recovery drinks?
- What HPLC residual-lactose testing thresholds must suppliers meet before retail grocery approval?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Switzerland
- United Kingdom
- Germany
- France
- Italy
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- ASEAN
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lactalis Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- Valio Ltd.
- Arla Foods amba
- Saputo Inc.
- HP Hood LLC
- Green Valley Creamery
- Liddells
- The Kraft Heinz Company
- Nestle S.A.
- Lactalis Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 26: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Processing State
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Processing State
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Processing State
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Processing State
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Lactose-free Products Market expected to be in 2026?
Global lactose-free products sales are estimated at USD 42.0 billion in 2026 and are projected to reach USD 93.2 billion by 2036.
What CAGR is forecast for the Lactose-free Products Market through 2036?
The market is projected to advance at an 8.3% CAGR from 2026 to 2036, supported by adult digestive health awareness and clean-taste membrane filtration.
Which product type / grade holds the leading lactose-free products share in 2026?
As per FMI, standard commercial grade is anticipated to account for 38.1% of product type / grade sales in 2026, reinforced by inline enzymatic conversion and supermarket private-label placement.
Which end-use application segment leads the Lactose-free Products Market in 2026?
Within the end-use application category, direct retail consumer consumption is expected to hold 49.1% demand in 2026, linked to daily household breakfast, coffee, and home-cooking routines.
Which country has the fastest growth outlook during the forecast period?
Switzerland is projected to register a 10.1% CAGR from 2026 to 2036, propelled by alpine membrane-filtration technology and high per-capita specialty dairy spending.
Which companies are active in the Lactose-free Products Market during 2026?
FMI finds that notable active processors include Lactalis Group, Danone S.A., Valio Ltd., Arla Foods amba, Saputo Inc., HP Hood LLC, Green Valley Creamery, Liddells, The Kraft Heinz Company, and Nestle S.A. These suppliers focus on ceramic membrane ultrafiltration, sterile post-UHT lactase dosing, and high-protein zero-lactose dairy formulations.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
