

- Market Size (2026)
- USD 1.9 Bn
- Forecast (2036)
- USD 3.8 Bn
- CAGR (2026 to 2036)
- 6.4%
How big is Lip Powder Market in 2026?
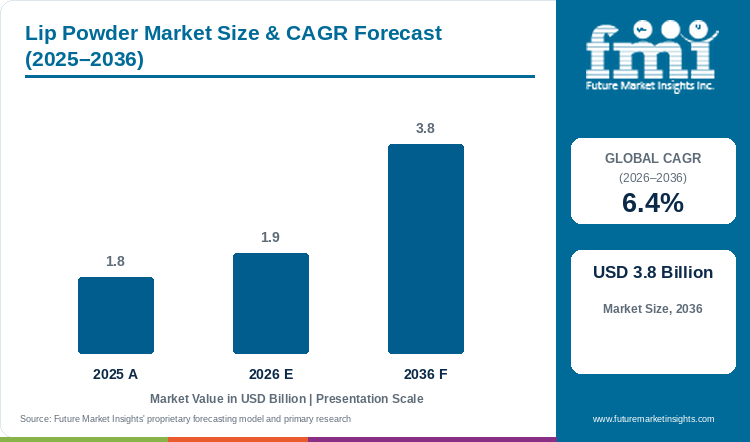
Sales of lip powder will grow at a CAGR of 6.4% from 2026 to 2036. Market size was USD 1.80 billion in 2025 and is projected to reach USD 1.92 billion in 2026 and USD 3.83 billion by 2036.
Lip powder market size stood at USD 1.80 billion in 2025, is estimated at USD 1.92 billion in 2026 and is projected to reach USD 3.83 billion by 2036, growing at a CAGR of 6.4% from 2026 to 2036, according to FMI.
Powder formats will enter the category as brands look for new textures, and palettes will carry the format to younger buyers online. Sales potential is expected to emerge from China, as buyers there try new formats.
Estée Lauder reported that M·A·C growth in fiscal 2026 was primarily due to a March 2026 launch in select U.S. Sephora locations and also reflected the lip subcategory, including Powder Kiss Lipstick and Lip Pencil[1]. Estée Lauder Mainland China net sales reached USD 3,058 million, up 12%[1]. The same release reported that Bobbi Brown net sales fell on declines in the lip and eye sub-categories[1]. A powder lipstick is selling at one brand and a lip decline is hurting another, so formats and brand positioning will decide who gains.
FMI names cosmetic safety, ingredient transparency and potential allergens among the challenges. Brands will answer with clearer labelling and tested formulas, and buyers will reward the brands that publish ingredient lists in full. Powder formats will also suit travel and gifting sets.
Key Market Trends & Insights
- By form, palettes led the market with a share of 55% in 2026, ahead of pens at 45%.
- By end user, the Up to 30 group accounted for 40% of sales in 2026, and the Up to 45 group followed with as much as 30%. L'Oréal Consumer Products grew 4.1% like-for-like in the first half of 2026, with Maybelline New York Serum Lipstick named among makeup innovations.[2]
- By sales channel, e-retailers led with an estimated 34% of sales in 2026. E-Com made up 33.1% of Douglas Group sales in April to June 2026.[3]
Regional Highlights
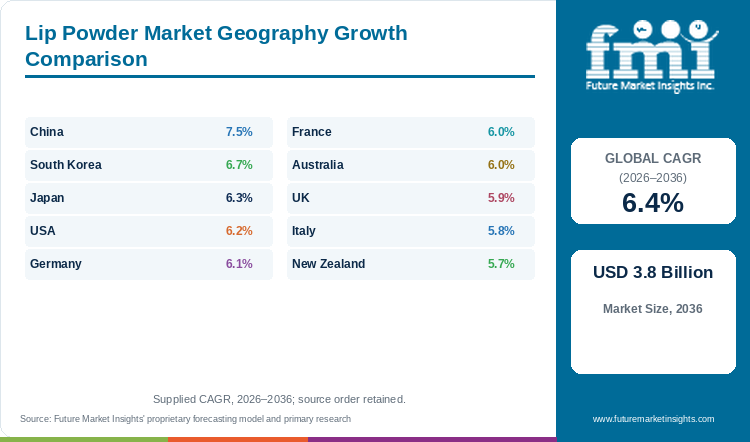
- Fastest-growing profiled country: China (7.5% CAGR, 2026 to 2036).
- By country: South Korea (6.7%) and Japan (6.3%) follow, with the USA at 6.2%, Germany at 6.1%, France and Australia at 6%, the UK at 5.9% and Italy at 5.8%, and New Zealand recording the lowest profiled CAGR at 5.7%.
- Estée Lauder reported Mainland China net sales of USD 3,058 million for fiscal 2026, up 12%.[1]
Market Size & Forecast
Table 1: Market Size and Forecast for the Lip Powder Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.80 billion |
| Estimated Market Size in 2026 | USD 1.92 billion |
| Projected Market Size by 2036 | USD 3.83 billion |
| CAGR, 2026 to 2036 | 6.4% |
| Added Revenue, 2026 to 2036 | USD 1.91 billion |
| Market Expansion Multiple | 2.0x |
Lip powder market size is projected to add USD 1.91 billion between 2026 and 2036, a 2.0x expansion on the 2026 base. That addition is small beside the cosmetics market, so gains come from converting existing lipstick and gloss buyers. FMI links the build to lightweight, long-wearing matte and soft-focus colour. Coty reported Consumer Beauty net revenues of USD 2,000.8 million for fiscal 2026, down 3%, and described US sell-out for CoverGirl as improving.[4] Low awareness of the powder format and competition from lipsticks, liquid lipsticks and lip stains hold back trial.
Adjacent Lip Formats and Brand Momentum
Brands that already sell lipsticks, pencils and pressed colour hold the shortest path to lip powder. L'Oréal Consumer Products grew 4.1% like-for-like in the first half of 2026, and makeup innovation included Maybelline New York Serum Lipstick.[2] Puig reported Makeup net revenue of EUR 359 million for the half, up 9.1% like-for-like, with Charlotte Tilbury the largest brand in the segment.[5] Both owners are growing in makeup, which gives each a base of lip customers to offer a powder.
Pace differs by owner. Coty reported Consumer Beauty net revenues down 7% like-for-like in fiscal 2026, with final portfolio decisions on the Consumer Beauty strategic review due by the end of CY26.[4] Shiseido's NARS brand grew 3% like-for-like in the first half of 2026.[6] A lip powder from a brand under review carries a different risk from one launched by a brand in a growth phase. The 6.4% CAGR gives room to all, and the open question is which lip format earns the next launch budget.
Table 2: Adjacent Lip Format and Brand Indicators for the Lip Powder Market (percentage and currency values), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| L'Oréal Consumer Products, first half 2026 | Sales of EUR 8,642.8 million, up 4.1% like-for-like; Maybelline New York Serum Lipstick named as an innovation | A lip launch ranks among recent makeup innovations. | [2] |
| Estée Lauder makeup, fiscal 2026 | Makeup net sales virtually flat; M·A·C lip subcategory drove growth, including Powder Kiss Lipstick and Lip Pencil | Lip results differed by brand inside one group, as Bobbi Brown net sales fell on declines in the lip and eye sub-categories. | [1] |
| Puig Makeup, first half 2026 | Net revenue of EUR 359 million, up 9.1% like-for-like | Charlotte Tilbury is the largest brand in the segment. | [5] |
| Coty Consumer Beauty, fiscal 2026 | Net revenues of USD 2,000.8 million, down 3% reported and 7% like-for-like | Final portfolio decisions on the strategic review are due by the end of CY26. | [4] |
| Shiseido NARS, first half 2026 | Like-for-like sales up 3%; first quarter up 7%, second quarter down 1% | Growth slowed in the second quarter. | [6] |
| Douglas Group, April to June 2026 | E-Com at 33.1% of sales, up from 32.7%; store sales of EUR 661.0 million, down 2.5% | Online carried one third of sales at a premium beauty retailer. | [3] |
| FDA talc testing rule, November 2025 | Proposed rule of 27 December 2024 withdrawn; a new proposed rule to follow under section 3505 of MoCRA | Talc-containing powders face a pending testing rule. | [7] |
Analyst Perspective
“Lip powder will grow fastest as established lip brands extend a trusted shade range into the powder format, as the 2026 results from L'Oréal, Estée Lauder and Puig show. Suppliers that pair palettes with pens and keep microfine pigment supply steady will hold the strongest position through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Lip Powder Market segmented?
The lip powder market is segmented into form, end user, and sales channel, and region. In 2026, palettes hold 55% of form sales, the Up to 30 group holds 40% of end user sales and e-retailers hold an estimated 34% of sales channel sales.
By form: palettes and pens.
By end user: Under 18, Up to 30, Up to 45, and Above 45.
By sales channel: specialty outlets, supermarkets and hypermarkets, convenience stores, beauty stores, e-retailers, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, South Asia and Pacific, East Asia, and Middle East and Africa.
Why do palettes lead form sales?
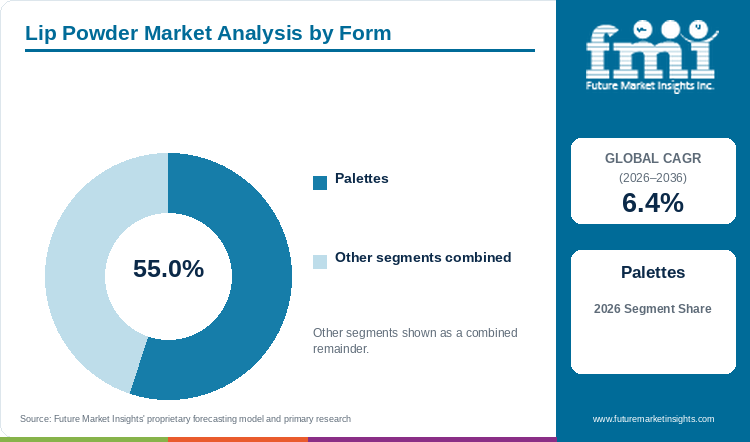
Palettes account for 55% of form sales in 2026, ahead of pens at 45%.
Table 3: Form Share for the Lip Powder Market (percentage share), 2026
| Form | Estimated Share (2026) |
|---|---|
| Palettes | 55% |
| Pens | 45% |
| Total | 100.0% |
Table 4: Form Leadership and Market Growth for the Lip Powder Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.4% |
| Leading Segment | Palettes |
Buyers choose palettes first, as the FMI split puts palettes at 55% of form sales in 2026 against 45% for pens. Estée Lauder named Lip Pencil among the drivers of M·A·C lip growth in fiscal 2026, so the pen shape already has a proven neighbour in the lip aisle.[1] Both formats use microfine pigments, which come from the cosmetic pigment market, and raw material cost swings for pigments restrain margins. A pigment price step affects palettes and pens alike.
- Pens give brands a pencil-style route into the lip aisle.
- Estée Lauder reported that M·A·C lip growth in fiscal 2026 included Powder Kiss Lipstick and Lip Pencil.[1]
Why does the Up to 30 group lead end user sales?
The Up to 30 group accounts for 40% of end user sales in 2026, with the Up to 45 group at as much as 30%.
Younger buyers set the pace. The Up to 30 group carries 40% of end user sales in 2026 and the Up to 45 group follows with as much as 30%, in the FMI report. Wider shade ranges can open further demand among Under 18 and Above 45 buyers. Shiseido said in August 2026 that the China and travel retail segment returned to growth and gained market share on strong 618 performance.[6] Promotion events and new shades therefore matter more than shelf permanence for a young base.
- Inclusive shade ranges bring the Under 18 and Above 45 groups into the category.
- Shiseido reported China and travel retail net sales of JPY 191.4 billion for the first half of 2026, down 0.1% like-for-like.[6]
Why do e-retailers lead sales channel sales?
E-retailers account for an estimated 34% of sales channel sales in 2026.
The FMI report lists six sales channels, from specialty outlets to e-retailers, and names direct-to-consumer brands as a driver of access. Douglas Group reported E-Com at 33.1% of sales in April to June 2026, up from 32.7%, and store sales fell 2.5% to EUR 661.0 million.[3] MECCA kept opening stores, with a 4,000 sqm Melbourne flagship and four new stores in the April 2026 announcement.[8] Online and store retail therefore both draw investment. A supplier choosing one primary channel faces a split between conversion online and discovery in store.
- Direct-to-consumer brands widen access to lip powder beyond store shelves.
- Douglas Group store sales were EUR 661.0 million in April to June 2026.[3]
What are the drivers, restraints, and opportunities in the Lip Powder Market?
In the lip powder market, demand for lightweight, long-wearing matte and soft-focus colour drives sales, pigment cost swings and low awareness of the format constrain growth, and inclusive shade ranges with digital-first marketing open the main commercial opportunity.
- Driver: Lightweight, long-wearing colour, microfine pigments and direct-to-consumer access support sales.
- Restraint: Ingredient transparency concerns, pigment cost swings and competition from lipsticks limit trial.
- Opportunity: Inclusive shade ranges, new finishes and influencer partners widen the buyer base.
Lightweight Colour and Brand Innovation Support Demand
Demand for lightweight, long-wearing matte and soft-focus colour is the first growth driver. L'Oréal said on 29 July 2026 that Consumer Products makeup growth was driven by innovations including Maybelline New York Serum Lipstick.[2] Puig reported Makeup net revenue of EUR 359 million in the first half of 2026, up 9.1% like-for-like.[5] Major groups still fund makeup launches, and a lip powder competes for the same launch budget.
Safety Rules and Competing Lip Formats Limit Trial
Cosmetic safety, ingredient transparency and potential allergens appear among the restraints. FDA withdrew the proposed rule on asbestos testing of talc-containing cosmetics in a notice scheduled for 28 November 2025 and said a new proposal would follow.[7] Coty reported Consumer Beauty net revenues down 7% like-for-like in fiscal 2026.[4] Estée Lauder said Bobbi Brown net sales fell on declines in the lip and eye sub-categories.[1] Powder makers face an open US rule and a mixed lip category.
Inclusive Shades and Digital Marketing Open New Buyers
Sales potential is expected to emerge from wider shade ranges for the Under 18 and Above 45 groups, influencer partners and digital-first marketing. Douglas Group reported that E-Com reached 33.1% of sales in April to June 2026, up from 32.7%.[3] Estée Lauder reported Mainland China net sales up 12% in fiscal 2026.[1] Brands that pair wider shades with online selling can reach both pools of buyers.
Which country CAGRs are profiled in the Lip Powder Market?
Table 5: Country CAGR Comparison for the Lip Powder Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 7.5% |
| South Korea | 6.7% |
| Japan | 6.3% |
| USA | 6.2% |
| Germany | 6.1% |
| France | 6% |
| Australia | 6% |
| UK | 5.9% |
| Italy | 5.8% |
| New Zealand | 5.7% |
How do country-level CAGRs compare in the lip powder market?
Growth across the ten profiled countries differs owing to retail structure, regulation and the finishes buyers prefer. As per the analysis from FMI, China is projected at 7.5% CAGR from 2026 to 2036, followed by South Korea at 6.7% and Japan at 6.3%. The USA is estimated at 6.2%, Germany at 6.1%, France and Australia at 6%, the UK at 5.9% and Italy at 5.8%, and New Zealand is projected at 5.7%.
- China pairs ultra-light formulas for young consumers with growth at two prestige groups.
- South Korea draws on cushion textures and ceramide or squalane formulas, with ODM makers growing on skincare and suncare.
- Japan links sheer finishes and department stores to flat prestige sales.
- The USA combines smudge-proof, talc-free and refillable products with an open FDA talc testing rule.
- Germany favours hypoallergenic, dermatologist-recommended and fragrance-free products in a softer premium market.
- France draws on plant-infused and organic products with eco-friendly packaging.
- Australia links sweat-resistant, sun-protective and vegan products to store investment by MECCA.
- The UK links cruelty-free, vegan and dual-function lip and cheek powders to growing makeup groups.
- Italy combines intensely pigmented, transfer-resistant options with prestige-client growth at Intercos.
- New Zealand pairs plant-based products and biodegradable packaging with shared Australian retail.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; South Asia and Pacific; East Asia; Middle East and Africa.
Country-wise Analysis
China Lip Powder Market Outlook (2026 to 2036)
Ultra-light formulas popular with young consumers drive demand for lip powder in China. The country is projected to lead the ten countries with a CAGR of 7.5% from 2026 to 2036. Estée Lauder reported Mainland China net sales of USD 3,058 million for fiscal 2026, up 12% reported and 9% organic.[1] Shiseido said the China and travel retail segment returned to growth and gained market share on strong 618 performance, with first-half 2026 net sales of JPY 191.4 billion, down 0.1% like-for-like.[6] Estée Lauder grew Mainland China net sales by double digits on a reported basis, and the Shiseido China and travel retail segment was flat like-for-like.
Key takeaway: China sets the fastest pace, and prestige sales growth at Estée Lauder gives young-skewed powder launches a firmer base.
South Korea Lip Powder Market Outlook (2026 to 2036)
Cosmax reported first-half 2026 revenue of KRW 1.4769 trillion, up 22%, and Kolmar Korea reported KRW 1.5893 trillion, up 15%, on a surge in demand for skincare and suncare products as indie brands expanded overseas.[9] Both are cosmetics ODM makers. Korean buyers reward advanced cushion textures and ceramide or squalane formulas, and South Korea is projected to grow at a CAGR of 6.7% from 2026 to 2036, second among the profiled countries.
Key takeaway: Korean formulators are growing on skincare and suncare, so lip powder needs a skincare-grade texture story to reach the same buyers.
Japan Lip Powder Market Outlook (2026 to 2036)
Japan is projected to grow at a CAGR of 6.3% from 2026 to 2036, third among the profiled countries. Japanese shoppers prefer sheer finishes with camellia oil and silk extracts, and department stores remain a key channel. Shiseido reported Japan net sales of JPY 144.7 billion for the first half of 2026, down 0.4% like-for-like, with core operating profit up 7.2% and a margin of 14.4%.[6] NARS grew 3% like-for-like in the same half.[6]
Key takeaway: Japan shows flat sales and rising profit, so launch spending in the country is more selective than the CAGR suggests.
USA Lip Powder Market Outlook (2026 to 2036)
FDA withdrew the proposed rule on asbestos testing of talc-containing cosmetics in a notice scheduled for 28 November 2025 and stated that a new proposal will follow under section 3505 of MoCRA.[7] American buyers seek out smudge-proof, talc-free and refillable products, so the withdrawal keeps talc-free formulation both a selling point and a compliance question. Estée Lauder reported Americas net sales up 1% to USD 4,463 million in fiscal 2026, and Coty described CoverGirl sell-out in the US as improving.[1][4] The USA is projected to grow at a CAGR of 6.2% from 2026 to 2036.
Key takeaway: Until FDA reissues the talc testing rule, US powder makers carry a formulation risk that talc-free lines avoid.
Germany Lip Powder Market Outlook (2026 to 2036)
Consumer demand for premium beauty was lower in Germany and the Netherlands in April to June 2026, Douglas Group reported, and sales in the DACHNL segment fell 2.8% to EUR 466.8 million.[3] German demand favours hypoallergenic, dermatologist-recommended and fragrance-free products, and those claims suit a cautious buyer. Germany is projected to grow at a CAGR of 6.1% from 2026 to 2036.
Key takeaway: A soft premium market makes proof of skin tolerance the German buyer's first test for a new lip powder.
France Lip Powder Market Outlook (2026 to 2036)
Plant-infused and organic formulas in eco-friendly packaging appeal to French shoppers. L'Oréal reported 5.7% like-for-like growth in Europe in the first half of 2026 and named makeup as a growth driver in the zone.[2] France is projected to grow at a CAGR of 6% from 2026 to 2036.
Key takeaway: Makeup growth across Europe gives plant-infused lip powders a supportive backdrop in France.
Australia Lip Powder Market Outlook (2026 to 2036)
Australian consumers look for sweat-resistant, sun-protective and vegan lip products, and the sun-protective claim ties lip powder to the sun care products market. RTCH Pty Ltd, parent of MECCA in Australia, reported revenue of $1.43 billion for the year ending 27 December 2025.[8] The announcement of 20 April 2026 described a 4,000 sqm Melbourne flagship, four new stores, seven relocations and five expansions.[8] Australia is projected to grow at a CAGR of 6% from 2026 to 2036.
Key takeaway: Store investment by MECCA keeps in-person shade testing central to Australian lip powder sales.
UK Lip Powder Market Outlook (2026 to 2036)
Puig reported Makeup net revenue of EUR 359 million in the first half of 2026, up 9.1% like-for-like, with Charlotte Tilbury the largest brand in the segment.[5] The Puig EMEA region grew 2.6% like-for-like. UK demand centres on cruelty-free, vegan and dual-function lip and cheek powders, a focus shared with the vegan cosmetics market. The UK is projected to grow at a CAGR of 5.9% from 2026 to 2036.
Key takeaway: A dual-function lip and cheek powder lets a UK brand sell one pan for two uses, and growing makeup groups show premium buyers still add products.
Italy Lip Powder Market Outlook (2026 to 2036)
Intercos, based in Agrate Brianza, reported first-half 2026 revenue of EUR 512.5 million, broadly in line with the previous year, with Make-up down 3.2% at current exchange rates.[10] The Make-up division benefited from significant growth among Prestige clients in the second quarter.[10] Italian consumers ask for intensely pigmented, transfer-resistant shades, and Italy is projected to grow at a CAGR of 5.8% from 2026 to 2036, second lowest of the ten.
Key takeaway: Prestige clients drove the second-quarter Make-up growth at Intercos, which ties pigment strength to launch calendars.
New Zealand Lip Powder Market Outlook (2026 to 2036)
Plant-based products and biodegradable packaging carry growth in New Zealand. The country is projected to record the lowest CAGR of the ten of 5.7% from 2026 to 2036. In April 2026, MECCA described bringing the world's best beauty brands to Australia and New Zealand, with more than 7,000 team members across the two countries.[8]
Key takeaway: New Zealand has the smallest CAGR of the ten, so shared Australian and New Zealand retail is the practical route for suppliers.
Who are the notable companies in the Lip Powder Market?
L'Oréal (Maybelline), Estée Lauder (MAC Cosmetics), Revlon, Coty (CoverGirl), Shiseido (NARS), Fenty Beauty, Charlotte Tilbury, and Sephora Collection are notable companies profiled in this market.
L'Oréal leads company shares at 20% to 25%, followed by Estée Lauder at 15% to 20%, Revlon at 10% to 15%, Coty at 8% to 12% and Shiseido at 5% to 9%, as per FMI. Other companies together hold 25% to 30%. Makeup momentum differs across owners. Puig reported Makeup net revenue growth of 9.1% like-for-like, Estée Lauder reported flat makeup net sales, and Coty has a strategic review of Consumer Beauty due to conclude by the end of CY26.[5][1][4] Fenty Beauty, Charlotte Tilbury and Sephora Collection also hold key positions.
- Leading share-estimate companies: L'Oréal, Estée Lauder, Revlon, Coty, and Shiseido.
- Other key players: Fenty Beauty, Charlotte Tilbury, and Sephora Collection.
Competitive Benchmarking: Lip Powder Market
Table 6: Competitive Benchmarking for the Lip Powder Market (qualitative documentation ratings), 2026
| Company | Lip Focus | Makeup Results | Activity | Disclosure |
|---|---|---|---|---|
| L'Oréal | High | Medium | Medium | High |
| Estée Lauder | High | High | Medium | High |
| Coty | Low | Medium | High | High |
| Shiseido | Low | Medium | Medium | High |
| Puig | Low | High | Medium | High |
Key Developments in the Lip Powder Market
- In August 2026, Estée Lauder reported that M·A·C net sales rose on a March 2026 launch in select US Sephora locations, with lip growth led by Powder Kiss Lipstick and Lip Pencil.[1]
- In August 2026, Shiseido reported first-half NARS like-for-like sales up 3%, with NARS declining in the Americas and a channel selection review under way.[6]
- In July 2026, Puig reported Makeup net revenue of EUR 359 million for the first half, up 9.1% like-for-like.[5]
- In July 2026, L'Oréal named Maybelline New York Serum Lipstick among makeup innovations in Consumer Products.[2]
- In November 2025, FDA withdrew the proposed rule on asbestos testing of talc-containing cosmetic products and said a new proposed rule would follow.[7]
Key Players in the Lip Powder Market
Leading Share-estimate Companies
- L'Oréal (Maybelline)
- Estée Lauder (MAC Cosmetics)
- Revlon
- Coty (CoverGirl)
- Shiseido (NARS)
Other Key Players
- Fenty Beauty
- Charlotte Tilbury
- Sephora Collection
Lip Powder Market - Report Scope
Table 7: Report Scope for the Lip Powder Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; end user; sales channel; region |
| Quantitative units | USD billion |
| Product scope | Lip powder in palette and pen forms, tracked by end user age group and sales channel. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; South Asia and Pacific; East Asia; Middle East and Africa |
| Countries covered | China; South Korea; Japan; USA; Germany; France; Australia; UK; Italy; New Zealand |
| Key companies profiled | L'Oréal, Estée Lauder, Revlon, Coty, Shiseido, Fenty Beauty, Charlotte Tilbury, Sephora Collection |
| Forecast period | 2026 to 2036 |
Lip Powder Market - Research Methodology
Table 8: Research Methodology for the Lip Powder Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company facts come from filings, press releases, regulator notices and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company results releases, a regulator notice and trade press on makeup, lip products and beauty retail. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base market size of USD 1.80 billion and the 6.4% CAGR. |
| Data Validation | Brand results, retailer updates and the FDA notice are cross-read so that each dated figure agrees across sources. |
Lip Powder Market by Segments
Lip Powder Market segmented by Form:
- Palettes
- Pens
Lip Powder Market segmented by End User:
- Under 18
- Up to 30
- Up to 45
- Above 45
Lip Powder Market segmented by Sales Channel:
- Specialty Outlets
- Supermarkets/Hypermarkets
- Convenience Stores
- Beauty Stores
- E-Retailers
- Others
Lip Powder Market by Region
- North America
- USA
- Latin America
- Western Europe
- Germany
- Italy
- France
- UK
- Eastern Europe
- South Asia and Pacific
- Australia
- New Zealand
- East Asia
- China
- Japan
- South Korea
- Middle East and Africa
Research Sources and Bibliography
- [1] The Estée Lauder Companies Inc. (2026, August 19). The Estée Lauder Companies Reports Fiscal 2026 Results [Press release]. https://www.elcompanies.com/en/news-and-media/newsroom/press-releases/2026/08-19-2026-110037466
- [2] L'Oréal. (2026, July 29). 2026 Half-Year Results [Press release]. https://www.loreal-finance.com/eng/press-release/2026-half-year-results
- [3] DOUGLAS Group (EQS News). (2026, August 12). DOUGLAS Group reports third quarter results in line with expectations and confirms full-year guidance. https://live.deutsche-boerse.com/news/EQS-News-DOUGLAS-Group-reports-third-quarter-results-in-line-with-expectations-and-confirms-full-year-guidance-ca6160a8-5032-448d-95b5-ee769605aa3e
- [4] Coty Inc. (Business Wire). (2026, August 19). Coty Announces Fourth Quarter Fiscal Year 2026 Results. https://secure.businesswire.com/news/home/20260819037136/en/Coty-Announces-Fourth-Quarter-Fiscal-Year-2026-Results
- [5] Puig. (2026, July 30). H1 2026 Results Press Release. https://uploads.puig.com/uploads/H1_2026_Results_Press_Release_ENG_e0929148e2.pdf
- [6] Shiseido Company, Limited. (2026, August 5). 2026 First Half Results (investor presentation). https://corp.shiseido.com/en/ir/pdf/ir20260805_296.pdf
- [7] Food and Drug Administration. (2025, November 28). Testing Methods for Detecting and Identifying Asbestos in Talc-Containing Cosmetic Products; Withdrawal. Federal Register. https://public-inspection.federalregister.gov/2025-21407.pdf
- [8] RTCH Pty Ltd (MECCA). (2026, April 20). RTCH announces FY25 results [Press release]. https://contenthub-delivery.mecca.com/api/public/content/rtch-announces-fy25-results-press-release-apr-26-DIsOVG0IQCKyR6IDlRYeA.pdf
- [9] Kim Eung-tae, EDAILY. (2026, August 12). K-Beauty Takes Flight: KOLMAR KOREA and COSMAX, INC. Post Record Earnings One After Another. https://en.edaily.co.kr/news/eda202608125566/
- [10] FashionNetwork. (2026, August 23). Intercos accelerates growth in the first half. https://uk.fashionnetwork.com/news/Intercos-accelerates-growth-in-the-first-half,1860085.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the lip powder market during 2026?
- What market size is projected by 2036?
- Which form holds notable share?
- Which end user group holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the lip powder market expected in 2026?
Future Market Insights estimates that lip powder market size is projected to reach USD 1.92 billion in 2026. Market size is projected to reach USD 3.83 billion by 2036, reflecting steady growth over the forecast period.
What CAGR is projected for the lip powder market through 2036?
As per FMI analysis, lip powder sales will grow at a CAGR of 6.4% from 2026 to 2036. Lightweight, long-wearing colour and direct-to-consumer access support the outlook.
Which form holds a notable market share in 2026?
Palettes account for 55% of form sales in 2026, and pens account for 45%. Buyers choose the pressed palette first.
Which end user group holds a notable market share in 2026?
The Up to 30 group accounts for 40% of end user sales in 2026, and the Up to 45 group holds as much as 30%. Younger buyers set the pace for launches.
Which country has a notable expansion outlook through 2036?
China is projected to record the fastest growth at a CAGR of 7.5% from 2026 to 2036, according to FMI. Ultra-light formulas popular with young consumers support that pace.
Who are the key companies in the lip powder market?
Notable companies include L'Oréal, Estée Lauder, Revlon, Coty, Shiseido, Fenty Beauty, BareMinerals, Charlotte Tilbury, and Sephora Collection.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Palettes
- Pens
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Under 18
- Up to 30
- Up to 45
- Above 45
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Specialty Outlets
- Supermarkets/Hypermarkets
- Convenience Stores
- Beauty Stores
- E-Retailers
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- South Asia and Pacific
- East Asia
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- By Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Form
- By End User
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Italy
- France
- UK
- By Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Form
- By End User
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- By Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Form
- By End User
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Form
- By End User
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End User
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By End User
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- L'Oréal
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Estée Lauder
- Coty
- Shiseido
- Puig
- L'Oréal (Maybelline)
- Estée Lauder (MAC Cosmetics)
- Revlon
- Coty (CoverGirl)
- Shiseido (NARS)
- Fenty Beauty
- Charlotte Tilbury
- Sephora Collection
- L'Oréal
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


