

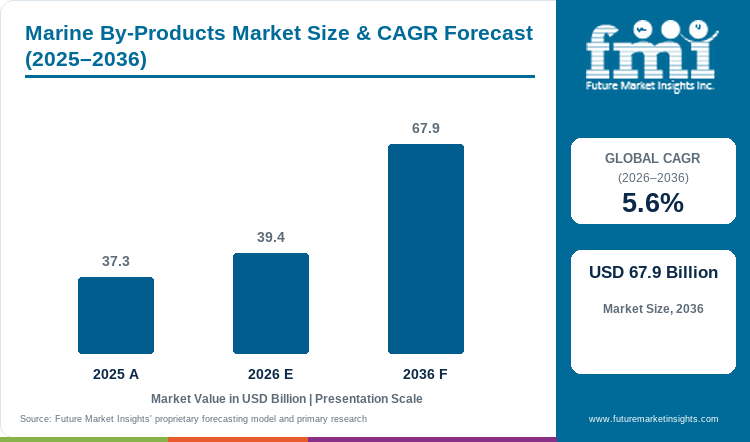
- Market Size (2026)
- USD 39.4 Bn
- Forecast (2036)
- USD 67.9 Bn
- CAGR (2026 to 2036)
- 5.6%
How big is Marine By-Products Market in 2026?
USD 39.4 billion in 2026 and USD 67.9 billion by 2036, expanding at 5.6% CAGR.
Demand for marine by-products is projected to expand at 5.6% CAGR between 2026 and 2036, growing from USD 37.3 billion in 2025 to USD 39.4 billion in 2026, and escalating to USD 67.9 billion by 2036. Processors are working with a larger global aquatic raw-material base that creates both saleable seafood products and recoverable side streams. FAO recorded 195 million tonnes of aquatic animals in 2024 and placed 89% into direct human consumption. The remaining material includes non-food uses led by fishmeal and fish oil. Commercial recovery therefore depends on separating usable residues before quality loss narrows their application options.
India is projected to grow at 7.4% CAGR through 2036 compared with 6.3% for the USA. India produced 19.775 million tonnes of fish in 2024-2025 according to the national Department of Fisheries. NOAA valued US industrial fishery products at USD 745.5 million in 2023. These national production bases create different recovery routes because Indian growth is tied to expanding fish throughput while US demand includes established feed and supplement uses for industrial marine products.
Key Takeaways
- Aquatic processing supports marine by-product demand because commercial value increases when usable residues are separated into feed and higher-value applications.
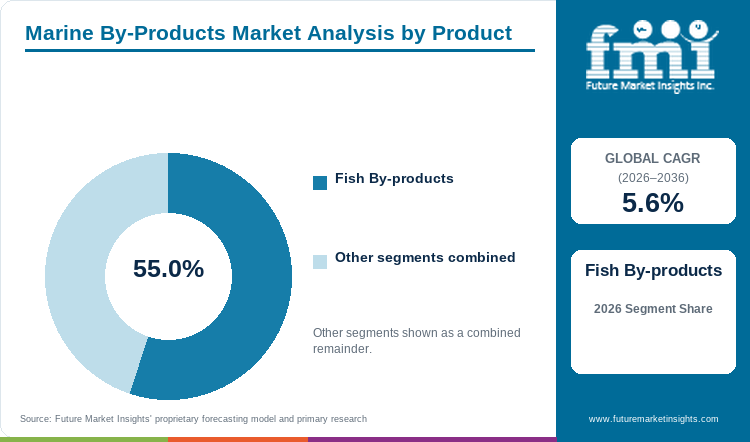
- By product, fish by-products are estimated to hold 55.0% share in 2026 because fish processing produces established meal and oil routes plus silage and hydrolysates.
- Dry is set to lead Form with 60.0% share in 2026 because powders and pellets simplify storage plus measured downstream handling.
- In 2026, animal feed is expected to lead application with 50.0% share because fishmeal remains concentrated in aquaculture and livestock nutrition channels.
- Raw-material quality and fishery availability constrain recovery because residues lose value when collection is delayed or whole-fish supply tightens under quota controls.
- Some of the key players in this market include Nutreco and TripleNine Group. FF Skagen and Copeinca are included alongside Omega Protein Corporation and Austevoll Seafood. Pacific Bio Products and GC Rieber VivoMega are also profiled. Corpesca and Golden Omega complete the company set.
Analyst Perspective
"Marine by-products create the strongest commercial return when processors preserve usable fractions before quality declines. Consistent collection and documented origin let feed and nutrition customers qualify recovered material without treating every residue stream as interchangeable."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the marine by-products market segmented?
The marine by-products market is segmented by Product, Form, Application, End Use, Source, Processing Method, and Region.
The marine by-products market is segmented by product, form, application, end use, source, processing method, and region for the 2026 to 2036 assessment period. Product covers fish, crustacean, mollusk, and other marine by-products. Form includes dry, liquid, and semi-solid formats. Application covers animal feed, agriculture, industrial uses, and food or nutraceutical uses. Source separates seafood processing, wild fisheries, and aquaculture while processing method covers rendering, fermentation, mechanical processing, and enzymatic hydrolysis.
How do fish by-products convert processing residues into repeatable product streams?
Fish processing produces side streams with established routes into meal and oil plus silage and hydrolyzed ingredients. Recovery economics improve when processors separate heads and frames from viscera and trimmings before spoilage reduces protein or lipid quality. fishmeal and fish oil provide mature outlets for large-volume material while higher-specification fractions can enter protein or nutraceutical processing. FAO reported that non-food uses represented 11% of aquatic animal production in 2024 and identified fishmeal plus fish oil as the dominant outlets. The commercial requirement is early segregation that preserves a consistent specification for the intended downstream process.
- Based on product, fish by-products are projected to account for 55.0% in 2026 because established recovery routes support meal and oil alongside silage and hydrolyzed ingredients.
- Fish by-products can serve several value tiers from feed ingredients to refined nutrition inputs. Processors protect repeat orders by matching each recovered fraction with the quality threshold of its intended application.
How does dry form simplify handling across marine by-product applications?
Dry formats reduce water content and make marine by-products easier to store within controlled commercial systems. Powders and pellets support measured inclusion in feed or agricultural formulations without requiring liquid tanks at every receiving site. fish meal is the clearest mature example because drying converts perishable marine material into a concentrated ingredient that can move through bulk feed channels. Drying does not remove the need for quality control because oxidation and protein damage can still reduce usable value. Suppliers therefore compete on stable composition and documented processing rather than dryness alone.
- By form, dry is estimated to hold 60.0% in 2026 because storage and measured handling are simpler across several downstream formulations.
- Powder and pellet formats also reduce dependence on dedicated liquid handling systems at smaller receiving sites. The operating advantage is strongest when moisture control preserves product stability through storage and transport.
How does animal feed concentrate demand within the application category?
Animal feed provides a repeat outlet for marine proteins and lipids because feed mills buy ingredients against defined nutritional specifications. Aquaculture remains important as farmed aquatic output grows beyond capture fisheries. Feed formulators are adjusting aquafeed formulations as marine proteins supply amino acids and marine oils supply long-chain omega-3 fatty acids. FAO GLOBEFISH reported that roughly 90% of fishmeal is used in aquaculture. Feed mills also evaluate contaminant control and traceability before approving recurring ingredient supply. Qualification therefore depends on consistent nutrient composition and origin records that let mills change suppliers without destabilizing finished feed performance.
- Animal feed is set to lead the application category with 50.0% share in 2026, driven by established fishmeal use in aquaculture and other compound feed systems.
- FAO reported 103 million tonnes of aquaculture aquatic animals in 2024 compared with 92 million tonnes from capture fisheries. That production balance keeps feed demand connected to reliable marine ingredient supply even as alternative proteins gain use.
What are the drivers, restraints and opportunities in the Marine By-Products Market?
Aquaculture feed demand supports repeat purchases, fishery and quality constraints limit usable supply, and better residue recovery opens higher-value processing routes.
- Driver: Aquaculture and compound feed production support recurring demand for standardized marine proteins and oils with documented nutrient composition.
- Restraint: Quotas and residue quality can reduce usable raw material before processors can replace contracted ingredient volumes from another source.
- Opportunity: Better segregation and hydrolysis can move suitable processing residues into higher-value feed and nutrition applications plus agricultural uses.
Feed demand keeps marine protein and oil specifications tied to repeat purchasing
Aquaculture feed mills are buying marine ingredients against protein and lipid specifications that must remain stable across production cycles. FAO GLOBEFISH reported that about 90% of fishmeal is used in aquaculture. FAO also reported that aquaculture supplied 59% of aquatic animal food in 2024. Feed manufacturers therefore need reliable nutrient density rather than undifferentiated residue volume. fish oil remains relevant when long-chain omega-3 content is part of the finished feed design.
Fishery limits and residue quality can tighten usable supply before downstream demand changes
Marine by-product output depends on raw material that cannot be recovered at the same quality under every landing and processing condition. The Atlantic States Marine Fisheries Commission set the 2026 Atlantic menhaden TAC at 186,840 metric tonnes following a 20% reduction. Quota decisions can narrow whole-fish inputs even when feed demand remains available. Processing residues also lose value when collection is delayed or mixed with unsuitable material. fish hydrolysate production requires protein-rich inputs that still meet processing and safety requirements. Flexible sourcing matters because a volume substitute is not useful when its composition fails qualification. Processors therefore need alternate approved sources before supply interruptions affect contracted output.
Controlled side-stream recovery can move residues into higher-value ingredient routes
Processors are separating trimmings and other side streams earlier because quality preservation determines which recovery route remains available. Nutreco reported in May 2026 that 88% of its marine ingredients were sourced through a Fishery Improvement Project during 2025. That sourcing standard increases the commercial value of traceable material that can pass feed qualification. Protein-rich fractions can enter fish protein hydrolysate production when enzymatic processing matches the intended specification. Early sorting also allows processors to direct lower-grade fractions toward feed or industrial routes without contaminating higher-value inputs. The opportunity depends on collecting identifiable raw material and assigning it to a process that preserves measurable functional value.
Which country CAGRs are profiled in the Marine By-Products Market?
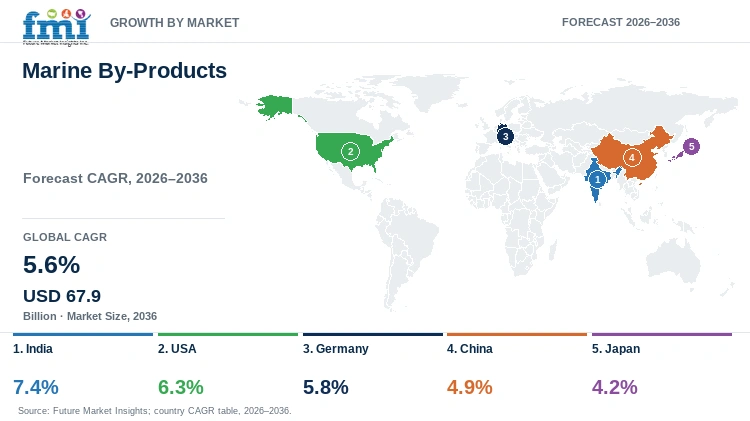
| Country | CAGR |
|---|---|
| India | 7.4% |
| USA | 6.3% |
| Germany | 5.8% |
| China | 4.9% |
| Japan | 4.2% |
How do country-level CAGRs compare in the Marine By-Products Market?
India forms the upper forecast band at 7.4% CAGR followed by the USA at 6.3% and Germany at 5.8%. China is projected at 4.9% while Japan is forecast at 4.2%. The 3.2 percentage-point spread describes forecast pace rather than current revenue because production scale and recovery routes differ across these national markets.
- India combines rapid fish-production growth with expanding processing throughput that can increase recoverable marine side streams for feed and ingredient conversion.
- USA demand includes a mature industrial fishery-products channel with established use of fish meal and fish oil across feed and nutrition applications.
- Germany has a stable national fish-consumption base that supports predictable processing volumes and documented residue collection within established food channels.
- China operates the largest aquatic production base among the listed countries with aquaculture providing most national aquatic output.
- Japan combines substantial seafood imports with a measurable non-food fishery-products stream used for feed and fertilizer applications.
Country growth rates describe different operating conditions rather than a common demand mechanism. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Marine by-products demand in India is forecast to rise at 7.4% CAGR over the forecast period, supported by expanding fish production and processing throughput. The Department of Fisheries reported national fish production of 19.775 million tonnes in 2024-2025 compared with 18.393 million tonnes a year earlier. Larger throughput increases the amount of trimmings and non-edible fractions available for controlled recovery. Protein-rich residues can enter marine protein hydrolysate routes when collection preserves quality and traceability. Feed and ingredient producers still need consistent composition because mixed residues can reduce functional value. Commercial growth therefore depends on converting higher production into qualified material rather than treating every processing residue as saleable output.
- The USA marine by-products outlook is anticipated to advance at 6.3% CAGR over the assessment period, supported by an established industrial fishery-products channel. NOAA valued US industrial fishery products at USD 745.5 million in 2023 and identified fish meal plus fish oil among the principal non-food products. The same national report estimated that imports supplied 80% of seafood consumed in the country. Domestic processors therefore operate beside a large imported food stream and a managed fisheries base. Raw-material qualification matters because quota changes can alter local availability without changing feed or supplement specifications. Suppliers protect recurring demand by documenting origin and maintaining consistent protein or fatty-acid performance across approved sources.
- Germany is projected to grow at 5.8% CAGR through 2036, influenced by a stable national fish-consumption base that sustains seafood processing activity. Fisch-Informationszentrum reported 419,131 tonnes of fishery and aquaculture products purchased by private households in 2024. Frozen fish accounted for 127,040 tonnes of that volume. Stable consumer throughput supports regular processing and distribution but does not guarantee uniform residue quality. Processors need controlled segregation before protein-rich fractions can move into meal or other recovered ingredient routes. Energy and storage costs also affect the economics of drying wet residues. German suppliers can defend repeat business by pairing documented collection with predictable composition for feed and industrial customers.
- Adoption of marine by-products in China is estimated to expand at 4.9% CAGR through 2036, supported by the country’s large aquaculture and seafood-processing base. The National Bureau of Statistics reported 76.57 million tonnes of aquatic products in 2025 and 63.24 million tonnes came from cultured production. That scale creates substantial side-stream volume but recovery value still depends on separation and processing discipline. Shell and fish residues can enter marine collagen routes when raw material meets food or nutraceutical quality requirements. Lower-grade fractions remain better suited to feed or industrial uses. Processors therefore need application-specific sorting so large production volume converts into consistent commercial ingredients instead of mixed low-value residue.
- Marine by-product demand in Japan is predicted to advance at 4.2% CAGR through 2036, shaped by import dependence and a measurable non-food fishery-products stream. The Fisheries Agency estimated total domestic fish and shellfish supply at 6.52 million tonnes in FY2023 and classified 1.51 million tonnes as non-food use for feed and fertilizer. The agency also recorded 2.16 million tonnes of fish and fishery-product imports in 2024. Refiners serving EPA DHA omega-3 ingredients need stable oil quality and complete origin records across imported inputs. Japan’s slower forecast therefore still supports specialized value recovery where processors can document composition and preserve high-specification fractions through handling and refining.
Who are the notable companies in the Marine By-Products Market?
Nutreco, TripleNine Group, FF Skagen, Copeinca, Omega Protein Corporation, Austevoll Seafood, Pacific Bio Products, GC Rieber VivoMega, Corpesca, and Golden Omega are active across marine ingredient processing, residual recovery, feed sourcing, and concentrated marine-oil routes.
Competition spans fishmeal and fish-oil processors alongside residual-recovery businesses. Aquaculture feed groups and human-nutrition refiners complete the main routes. Entry depends on raw-material access and verifiable quality systems rather than corporate scale alone. Recovered protein fractions also require processing controls that preserve intended functionality from variable marine residues.
- TripleNine Group and FF Skagen operate close to fishmeal or fish-oil production. Copeinca and Omega Protein Corporation follow the same direct production route. Austevoll Seafood and Corpesca also manage marine raw materials for meal or oil production.
- Nutreco and Pacific Bio Products represent feed-demand and residual-recovery routes that connect marine ingredients with qualification requirements for animal nutrition.
- GC Rieber VivoMega and Golden Omega focus on refined omega-3 ingredients that require tighter fatty-acid specifications and documented marine sourcing.
Competitive Benchmarking: Marine By-Products Market
| Company | Marine Ingredient Production | Circular / Traceable Sourcing | Human-Nutrition Omega-3 | Geographic Reach |
|---|---|---|---|---|
| Nutreco | Low | High | Low | Global aquaculture feed operations through Skretting |
| TripleNine Group | High | High | Low | Denmark by-product facility at Thyborøn |
| FF Skagen | High | High | Low | Denmark production and approved by-product sourcing |
| Copeinca | High | Medium | Low | Peru fishmeal processing in Sechura |
| Omega Protein Corporation | High | High | Low | United States Atlantic and Gulf menhaden operations |
| Austevoll Seafood | High | Medium | Low | Norway-based Pelagia marine protein and oil operations |
| Pacific Bio Products | Medium | Medium | Low | Oregon by-product facilities in Warrenton and Newport |
| GC Rieber VivoMega | Medium | High | High | Norway concentrated omega-3 production |
| Corpesca | High | Medium | Low | Chile pelagic fishery and marine ingredient operations |
| Golden Omega | Medium | Medium | High | Arica production with a 2026 commercial launch in China |
Scoring basis: High marine ingredient production requires current evidence of direct fishmeal or fish-oil processing. Medium identifies documented by-product or concentrated-oil processing with a narrower production role. Low identifies no direct production role in the admitted source set. High circular or traceable sourcing requires current certification or an approved by-product sourcing route. Medium identifies regulated or documented recovery without the same certification depth. Low indicates no direct sourcing evidence in the admitted source set. High human-nutrition omega-3 requires current concentrated EPA or DHA production evidence. Medium requires narrower human-nutrition oil evidence and Low indicates no direct evidence in the admitted source set.
Key Developments in the Marine By-Products Market
- In September 2026, Corpesca received a Sernapesca authorization for a cession by the industrial vessel operator under Chilean pelagic fishery regulations. The action affects access management for raw material used by marine ingredient processing.
- In August 2026, Peru's Ministry of Production admitted Copeinca's environmental study update for its 170 t/h high-protein fishmeal plant in Sechura. The filing keeps plant operations tied to current environmental review requirements.
- In July 2026, Golden Omega launched a new concentrate line with Zhiqi in Jin Hua during Food Ingredients China. The action expanded its route for concentrated omega-3 ingredients in the Chinese market.
Key Players in the Marine By-Products Market
Integrated fishmeal and fish-oil processors
- TripleNine Group
- FF Skagen
- Copeinca
- Omega Protein Corporation
- Austevoll Seafood
- Corpesca
Feed-demand and residual-recovery platforms
- Nutreco
- Pacific Bio Products
High-purity omega-3 refiners
- GC Rieber VivoMega
- Golden Omega
Marine By-Products Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product, form, application, end use, source, processing method, and region. |
| Quantitative Units | USD billion. |
| Market Definition | Revenue includes commercially traded fish, crustacean, mollusk, and other marine by-products sold through organized commercial channels across feed, agriculture, industrial, food, and nutraceutical applications. Raw unprocessed non-commercial material and synthetic substitutes are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | India, USA, Germany, China, Japan, and 30+ countries included in the full report. |
| Key Companies Profiled | Nutreco, TripleNine Group, FF Skagen, Copeinca, Omega Protein Corporation, Austevoll Seafood, Pacific Bio Products, GC Rieber VivoMega, Corpesca, Golden Omega. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Marine By-Products Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Marine By-Products Market by Segments
Marine By-Products Market segmented by Product:
- Fish By-products
- Fish Meal
- Fish Oil
- Fish Silage
- Crustacean By-products
- Shrimp Waste
- Crab Waste
- Mollusk By-products
- Oyster Shells
- Mussel Waste
- Other Marine By-products
- Seaweed Residues
- Marine Collagen Waste
Marine By-Products Market segmented by Form:
- Dry
- Powder
- Pellets
- Liquid
- Oil
- Silage
- Semi-solid
- Paste
- Slurry
Marine By-Products Market segmented by Application:
- Animal Feed
- Aquaculture Feed
- Livestock Feed
- Agriculture
- Organic Fertilizers
- Biofertilizers
- Industrial Applications
- Biofuels
- Biopolymers
- Food and Nutraceuticals
- Functional Ingredients
- Dietary Supplements
Marine By-Products Market segmented by End Use:
- Feed Manufacturers
- Commercial Feed Producers
- Agricultural Sector
- Farmers
- Industrial Manufacturers
- Biofuel Producers
- Food and Nutraceutical Companies
- Supplement Manufacturers
Marine By-Products Market segmented by Source:
- Seafood Processing Industry
- Processing Waste
- Trim and Offcuts
- Wild Fisheries
- Capture Fisheries
- Ocean Harvest
- Aquaculture
- Farmed Fish Waste
- Processing Residues
Marine By-Products Market segmented by Processing Method:
- Rendering
- Fermentation
- Mechanical Processing
- Enzymatic Hydrolysis
Marine By-Products Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Food and Agriculture Organization of the United Nations. (2026, June 16). SOFIA 2026: Global fisheries and aquaculture production reaches new highs.
- Press Information Bureau, Government of India. (2026, August 11). Assistance to coastal fishermen.
- NOAA Fisheries. (2026, March 3). Fisheries of the United States.
- Fisch-Informationszentrum. (2025, September). Ein Markt in Balance.
- National Bureau of Statistics of China. (2026, February 28). Statistical communiqué of the People’s Republic of China on the 2025 national economic and social development.
- Fisheries Agency of Japan. (2025, June). Chapter 1: Trends in the supply-and-demand and consumption of fish and fishery products in Japan.
- FAO GLOBEFISH. (2026, July 7). Global aquatic food trade: The latest findings from SOFIA 2026.
- Atlantic States Marine Fisheries Commission. (2025, October). ASMFC Atlantic Menhaden Board reduces 2026 TAC by 20% and initiates addendum for Chesapeake Bay cap.
- Nutreco. (2026, May 5). Nutreco cuts Scope 1 and 2 emissions by 47%, publishes its Impact Report 2025.
- Servicio Nacional de Pesca y Acuicultura. (2026, September 15). Res.Ex. N° 2201 - 11.09.2026 | Autorizó cesión por parte del armador industrial CORPESCA S.A.
- Ministerio de la Producción, Peru. (2026, August 7). Resolución Directoral N.° 00202-2026-PRODUCE/DGAAMPA.
- Golden Omega. (2026, July 23). Chinese market.
- MarinTrust. (2026, May). By-product assessment report BP041: FF Skagen A/S.
- MarinTrust. (2026, April). By-product assessment report BP044: Thyborøn (TripleNine).
- Marine Stewardship Council. (2026, March 26). U.S. Atlantic menhaden purse seine: Certification status.
- MarinTrust. (2026, April 28). GC Rieber VivoMega AS certificate 2026-2029.
- Friend of the Sea. (2026, January 29). GC Rieber VivoMega renews Friend of the Sea certification.
- Austevoll Seafood ASA. (2026, May 12). Q1 2026 financial report and presentation.
- NOAA Fisheries. (2026, March 23). Approved establishments 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How do the 2025 baseline and 2036 forecast define market expansion?
- Which recovery conditions convert marine residues into commercially qualified ingredients?
- Which product category accounts for 55.0% of revenue during 2026?
- Which form category accounts for 60.0% of revenue during 2026?
- Why does animal feed account for 50.0% of application demand?
- Which raw-material conditions constrain marine by-product recovery and qualification?
- How do country forecast paths differ across the five analyzed markets?
- Which companies operate across marine ingredient processing and recovery routes?
Frequently Asked Questions
How big is the marine by-products market in 2026 and what is forecast for 2036?
The marine by-products market is valued at USD 39.4 billion in 2026 and is projected to reach USD 67.9 billion by 2036. The 2025 baseline is USD 37.3 billion and the forecast depends on qualified recovery across feed and several higher-value applications.
What CAGR is projected for the marine by-products market from 2026 to 2036?
The marine by-products market is projected to grow at 5.6% CAGR from 2026 to 2036. Growth depends on processing throughput and feed demand alongside traceable recovery plus usable raw-material quality.
Which product category holds the largest modeled share in 2026?
Fish by-products are estimated to hold 55.0% of the product category in 2026. Established recovery into fish meal and fish oil supports the segment alongside silage and hydrolyzed ingredients.
Which form category holds the largest modeled share in 2026?
Dry is projected to hold 60.0% of the form category in 2026. Powders and pellets support storage plus measured inclusion without requiring liquid handling at every receiving site.
Which application category holds the largest modeled share in 2026?
Animal feed is expected to hold 50.0% of the application category in 2026. Fishmeal and marine oils remain established feed ingredients when mills require consistent nutrition and documented origin.
Which companies are active across the marine by-products market and its main supply routes?
Key companies operating in the marine by-products market include Nutreco and TripleNine Group. FF Skagen and Copeinca are included with Omega Protein Corporation and Austevoll Seafood. Pacific Bio Products and GC Rieber VivoMega are also profiled. Corpesca and Golden Omega complete the set. Their roles span feed purchasing and marine ingredient processing alongside residual recovery plus concentrated omega-3 refining.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- How big is Marine By-Products Market in 2026?
- Key Takeaways
- Analyst Perspective
- How is the marine by-products market segmented?
- How do fish by-products convert processing residues into repeatable product streams?
- How does dry form simplify handling across marine by-product applications?
- How does animal feed concentrate demand within the application category?
- What are the drivers, restraints and opportunities in the Marine By-Products Market?
- Feed demand keeps marine protein and oil specifications tied to repeat purchasing
- Fishery limits and residue quality can tighten usable supply before downstream demand changes
- Controlled side-stream recovery can move residues into higher-value ingredient routes
- Which country CAGRs are profiled in the Marine By-Products Market?
- How do country-level CAGRs compare in the Marine By-Products Market?
- Country-wise Analysis
- Who are the notable companies in the Marine By-Products Market?
- Competitive Benchmarking: Marine By-Products Market
- Key Developments in the Marine By-Products Market
- Key Players in the Marine By-Products Market
- Integrated fishmeal and fish-oil processors
- Feed-demand and residual-recovery platforms
- High-purity omega-3 refiners
- Marine By-Products Market - Report Scope
- Marine By-Products Market - Research Methodology
- Marine By-Products Market by Segments
- Marine By-Products Market segmented by Product:
- Marine By-Products Market segmented by Form:
- Marine By-Products Market segmented by Application:
- Marine By-Products Market segmented by End Use:
- Marine By-Products Market segmented by Source:
- Marine By-Products Market segmented by Processing Method:
- Marine By-Products Market by Region:
- Research Sources and Bibliography
- This Report Answers
- Frequently Asked Questions
- Competitive Landscape


