

- Market Size (2026)
- USD 155.2 Mn
- Forecast (2036)
- USD 319.9 Mn
- CAGR (2026 to 2036)
- 7.5%
How big is Muscovado & Specialty Unrefined Sugars Market in 2026?
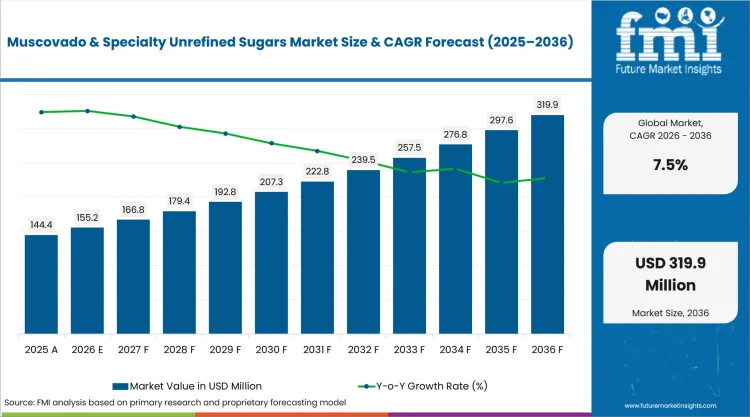
USD 155.2 million in 2026 and USD 319.9 million by 2036 at a 7.5% CAGR.
Demand for muscovado and specialty unrefined sugars is projected to expand at 7.5% CAGR between 2026 and 2036, reaching USD 319.9 million. Industrial bakeries pay premiums when specialty cane sugar changes finished-product flavor or moisture during repeat commercial production. Nordzucker documented customer-specific sugar qualities and crystal sizes during its March 2026 Nordstemmen campaign. These functional characteristics can influence formulation outcomes, making consistency an important consideration for bakeries evaluating higher-value sugar ingredients.
US specialty-sugar economics differ because commercial bakeries can source ordinary sucrose through established domestic channels. USDA data updated in September 2025 place long-run US cane and beet sugar output near 8.6 million short tons raw value, raising the premium threshold for imported specialty grades seeking recurring industrial bakery orders.
Key Takeaways
- Industrial bakery demand rises once technical teams convert molasses flavor and moisture into specifications that justify premium pricing.
- Fine grades hold 38.0% of type demand in 2026 owing to faster dispersion during commercial mixing.
- By form, powder - dry is estimated to hold 39.0% in 2026 owing to familiar handling for crystalline ingredients.
- In 2026, bread & rolls is expected to lead application with 31.0% share because frequent production rewards stable dough performance.
- Nutrition policy and conventional sugar pricing require stronger evidence from manufacturers approving higher-cost specialty grades for routine production.
- Some of the key players in this market include Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, BENEO GmbH, Südzucker AG, Nordzucker AG, ASR Group, Cargill, Incorporated, Ragus Sugars (Manufacturing) Limited, and ADM.
Analyst Perspective
“Industrial bakeries treat muscovado as a functional sugar only after trials confirm how molasses solids affect color, moisture and mixing behavior. The premium survives repeated purchasing if processors control crystal size and flavor intensity and protect the product from humidity during storage.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the muscovado & specialty unrefined sugars market segmented?
The market is segmented by type, form, application, claim, sales channel and region.
Type and form classifications cover fine grades, coarse & decorative, organic and blends plus powder - dry, liquid, paste - semi-solid and granules - pieces. Application, claim and sales-channel classifications retain bread & rolls and the other approved bakery uses plus conventional, clean label, organic, non-GMO - identity preserved and the four approved buying routes.
What makes Fine grades central to the Type category?
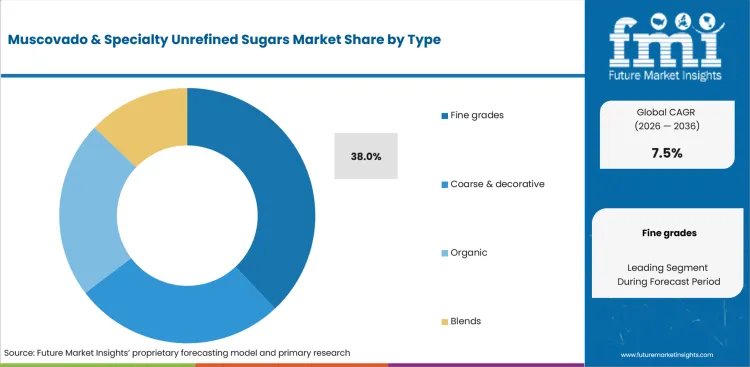
Fine grades suit bakery ingredient systems that need even sugar distribution during short commercial mixing cycles. Smaller crystals spread molasses character without leaving visible crystal residue in commercial dough or batter systems.
- Fine grades are projected to account for 38.0% of the type category in 2026, driven by rapid dispersion in industrial bakery formulas.
- Ragus explained in January 2026 that crystal size and molasses content change solubility, texture and finished-product performance across bakery applications.
Why does Powder - dry hold the primary Form position?
Powder - dry sugar fits commercial baking ingredient rooms that weigh crystalline materials by batch. Liquid and paste formats need dedicated pumping controls while baking ingredients stored dry use familiar storage and dosing equipment during routine industrial qualification.
- Powder - dry is estimated to capture 39.0% of the form category in 2026, attributable to familiar warehousing and batch-dosing routines.
- Ragus stated in June 2026 that industrial sugar selection depends on packaging and storage plus specification and production-line performance for food manufacturers.
How does Bread & rolls account for the Application share position?
Bread & rolls gives specialty sugar a repeat role in industrial bakery mixes because color and moisture must stay consistent during frequent production. Repeated commercial dough runs expose ingredient specification drift faster than occasional decorative bakery applications.
- Bread & rolls is anticipated to represent 31.0% of application demand in 2026, supported by routine production that rewards repeatable dough performance.
- Ragus documented that muscovado retains natural cane molasses and is used in baked goods where flavor, texture and moisture are part of the finished specification.
What supports Conventional demand within the Claim category?
Conventional grades serve recipes where performance and supply continuity outweigh a claim-specific premium during routine production. Organic and clean-label ingredients require documented sourcing controls that finished brands must justify commercially.
- Conventional is forecast to hold 50.0% of the claim category in 2026 driven by broad recipe compatibility without mandatory claim-specific certification.
- Südzucker reported in May 2026 that its sugar segment processed 24.8 million tonnes of beet and produced 3.8 million tonnes of sugar during fiscal 2025/26.
Why does Direct to industrial bakeries account for the Sales Channel share position?
Direct supply keeps grade approval and replenishment with one commercial counterparty for planned bakery production. Higher-volume sweetener supply systems also benefit from direct technical discussion before repeat orders scale.
- Direct to industrial bakeries is expected to represent 48.0% of sales-channel demand in 2026, owing to orders built on agreed specifications and delivery schedules.
- Ragus reported in May 2026 that industrial sugar buyers increasingly evaluate supplier continuity, logistics and specification control alongside the ingredient price itself.
What are the drivers, restraints and opportunities in the Muscovado & Specialty Unrefined Sugars Market?
Bakery differentiation supports molasses-rich grades while nutrition pressure limits dosage and traceable specialty specifications create selective premium openings.
- Driver: Industrial bakeries specify specialty sugar once flavor and moisture performance produces a finished-product difference that survives routine commercial production.
- Restraint: Nutrition policy and weak conventional sugar pricing reduce the applications where a higher-cost unrefined grade earns technical and commercial approval.
- Opportunity: Traceable origin and controlled identity can support premium bakery applications where documented claims accompany consistent industrial processing performance.
Industrial bakers combine specialty sugar with bakery ingredients when sweetness and molasses character must remain consistent. Tate & Lyle expanded its BioHarvest collaboration in May 2026 to develop plant-based sweetener molecules for sugar reduction. Muscovado retains demand where bakery teams preserve a distinctive sensory result against lower-sugar formulation systems.
Nutrition policy limits use where added sugar becomes a direct reformulation target for packaged bakery products. The UK government restricted advertising of less healthy food from January 5 2026 to reduce children’s exposure. Specialty grades need stronger flavor efficiency before manufacturers approve a higher-cost ingredient for recurring packaged-food production.
Traceable grades gain value only if origin and processing separation are documented without disrupting routine supply. Nordzucker stated in September 2026 that organic beet would be processed first at Schladen and Nykøbing. Separate processing windows let bakery brands substantiate origin claims while preserving practical production planning for repeat supply.
Which country CAGRs are profiled in the Muscovado & Specialty Unrefined Sugars Market?
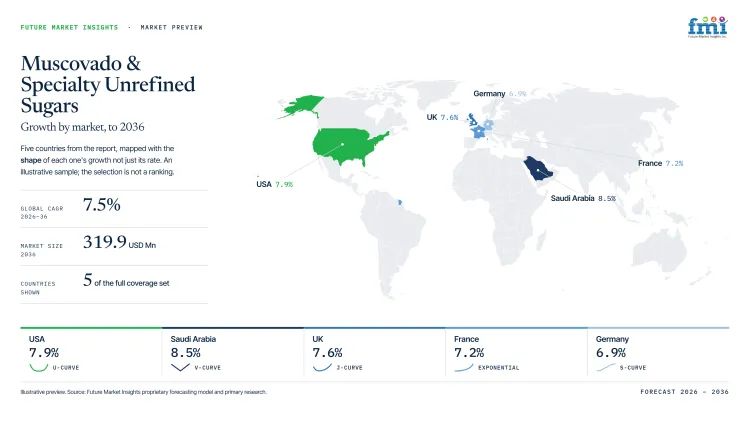
| Country | CAGR |
|---|---|
| UAE | 8.9% |
| Saudi Arabia | 8.5% |
| South Korea | 8.2% |
| USA | 7.9% |
| UK | 7.5% |
| France | 7.2% |
| Germany | 6.9% |
| Japan | 6.5% |
How do country-level CAGRs compare in the Muscovado & Specialty Unrefined Sugars Market?
The country comparison spans 2.4 percentage points from UAE at 8.9% to Japan at 6.5% through 2036. The difference is small enough that national supply depth, import controls and nutrition rules can matter more than the CAGR gap. Country priority therefore depends on the cost, qualification work and supply conditions behind each forecast.
- UAE growth is paired with national monitoring of sugar prices, so premium grades need a clear performance case against visible commodity pricing.
- Saudi Arabia combines a higher forecast rate with formal food-clearance requirements that importers must complete before commercial trials scale.
- South Korea couples above-global growth with mandatory nutrition disclosure, which makes added-sugar functionality more visible during packaged-bakery formulation.
- USA growth develops beside a large domestic sugar supply base, raising the proof threshold for imported or specialty cane grades.
- UK demand grows near the global rate while domestic refined-sugar availability keeps ordinary sucrose a strong benchmark for formulation cost.
- France combines moderate growth with strong domestic sugar production, so imported cane specialties need a distinct sensory role before approval.
- Germany also has an established beet-sugar base, making origin documentation and consistent physical specifications more important for specialty entry.
- Japan records 6.5% CAGR as mature sugar consumption keeps specialty adoption selective and landed economics important for imported cane grades.
Comparable CAGRs can mask entry differences because supply economics and nutrition rules alter qualification costs more than small growth-rate gaps. The full report covers North America and Latin America plus Western Europe and Eastern Europe. It also covers East Asia plus South Asia and Pacific plus Middle East and Africa.
Country-wise Analysis
- US industrial bakeries qualify specialty cane sugars against a deep domestic refined-sugar base and established bulk delivery networks. Demand for muscovado and specialty unrefined sugars in USA is forecast to rise at 7.9% CAGR over the forecast period. USDA’s August 2026 outlook placed national sugar supply at 14.436 million short tons raw value under updated production and import assumptions. This domestic supply depth raises the premium threshold for refined cane sugar alternatives used in industrial bakery recipes. Entrants therefore need application evidence that proves a finished-product difference without disrupting routine plant operations.
- Germany muscovado & specialty unrefined sugars industry is projected to record 6.9% CAGR through 2036. German bakery manufacturers compare muscovado with a mature beet-sugar base where traceability and processing consistency matter alongside sensory novelty. Destatis estimated 408,500 hectares of sugar beet for the 2025 harvest in May 2025 and placed acreage 6.6% below the prior year. Domestic beet production gives manufacturers a familiar sucrose alternative and adds origin pressure to imported cane specialties. Distributors can strengthen entry by documenting cane origin for flour improver systems used in commercial bakery production.
- Demand for muscovado and specialty unrefined sugars in France is forecast to rise at 7.2% CAGR through 2036. French bakers use dark sugars for sensory differentiation within a country that also has substantial domestic beet-sugar production. Agreste reported in July 2026 that French sugar production increased in 2025 and exports to the European Union remained an important outlet. Domestic output strengthens conventional price competition for imported cane specialties within industrial bakery purchasing decisions. Specialty grades therefore need stable color and molasses intensity that manufacturers can justify in premium recipes.
- UK bakery manufacturers already source within a mature domestic sugar system, so specialty grades must justify a clear recipe premium. In the UK, muscovado and specialty unrefined sugar demand is predicted to advance at 7.5% CAGR through 2036. Defra reported in September 2026 that domestic refined sugar represented 61% of new supply during 2025 following a 7.3 million-tonne beet crop. Domestic availability keeps ordinary sucrose commercially competitive against specialty grades in routine bakery formulations. Producers need consistent molasses intensity and dosage guidance for home baking ingredients and commercial bakery formulations.
- Saudi specialty sugar reaches industrial bakeries and foodservice users through regulated national import channels serving commercial accounts. Saudi Arabia is forecast to grow at 8.5% CAGR during the projection preriod. SFDA’s February 2025 national food-clearance rules require commercially imported food to pass electronic clearance through registered importers and registered items. The clearance requirement adds a documented approval step before bakery trials can expand into regular purchasing. Importers therefore need complete product records and stable supply before premium brown sugars can support repeat accounts.
- UAE specialty sugar moves through importers serving manufacturers and foodservice accounts that compare premium grades with visible commodity pricing. UAE demand is forecast to grow at 8.9% CAGR through 2036. The Ministry of Economy launched a national price-monitoring platform in February 2025 covering sugar and eight other essentials representing more than 90% of household consumption. National price visibility raises the commercial hurdle for imported premium grades whose value rests on sensory or handling differences. Distributors need protected storage and responsive replenishment before premium applications can scale beyond trial orders.
- Japanese bakery buyers place tight controls on color and crystal behavior which favors narrowly specified specialty grades over broad commodity substitution. Japan is estimated to post 6.5% CAGR through 2036 within the authorized market assessment period. ALIC reported in August 2026 that 2025 sugar-year consumption was about 1.77 million tonnes and decreased 0.8% from the previous year. Mature consumption limits easy volume expansion and keeps landed economics important for imported specialty cane sugars. Brands need exact physical specifications and local distribution that minimizes moisture pickup before premium applications justify added sourcing cost.
- South Korean packaged-bakery manufacturers operate under detailed nutrition labeling that makes sugar content and claim wording visible during formulation review. Specialty unrefined sugar sales in South Korea are forecast to expand at 8.2% CAGR by 2036. MFDS amended Food Labeling Standards in April 2025 as broader mandatory nutrition labeling was scheduled to take effect nationally on January 1 2026. Broader disclosure increases pressure to justify each gram of added sugar during packaged-bakery formulation review. Ingredient companies need label-ready specifications plus application guidance for packaged bakers defending premium differentiation during retail review.
Who are the notable companies in the Muscovado & Specialty Unrefined Sugars Market?
ASR Group, Ragus Sugars (Manufacturing) Limited, Südzucker AG and Nordzucker AG participate directly in sugar manufacturing and supply. Cargill, Incorporated supplies industrial sweeteners and bakery formulation support, while Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, BENEO GmbH and ADM compete mainly through adjacent sweetening or reformulation systems.
Direct sugar manufacturers compete on grade consistency and logistics while adjacent formulation companies compete for the same bakery budgets through sucrose reduction.
- ASR Group and Ragus Sugars (Manufacturing) Limited focus on direct specialty sugar while Cargill, Incorporated supplies industrial sweeteners and bakery formulation systems.
- Südzucker AG and Nordzucker AG provide European sugar-processing scale with industrial distribution and multiple sucrose formats for commercial food manufacturers.
- Tate & Lyle PLC and Ingredion Incorporated compete mainly through adjacent sugar-reduction and functional-ingredient systems. Roquette Frères, BENEO GmbH and ADM use comparable reformulation routes for food manufacturers reducing conventional sucrose.
Competitive Benchmarking: Muscovado & Specialty Unrefined Sugars Market
| Company | Specialty Sugar Route Depth | Industrial Food Application Support | Sugar-Reduction Formulation Activity | Geographic Reach |
|---|---|---|---|---|
| Tate & Lyle PLC | Low | High | High | Global |
| Ingredion Incorporated | Low | High | High | Global |
| Roquette Frères | Low | High | High | Global |
| BENEO GmbH | Medium | High | High | Europe and international markets |
| Südzucker AG | High | Medium | Low | Europe and international markets |
| Nordzucker AG | High | Medium | Low | Europe and Australia |
| ASR Group | High | High | Low | North America and Europe |
| Cargill, Incorporated | Medium | High | High | Global |
| Ragus Sugars (Manufacturing) Limited | High | High | Low | United Kingdom and export markets |
| ADM | Medium | High | High | Global |
High specialty-sugar depth requires direct evidence of several sugar routes while Medium covers narrower sugar participation and Low denotes adjacent sweetening only. High industrial-food support requires direct application evidence while Medium covers broader customer supply with less formulation support. High sugar-reduction activity requires a current documented reformulation route while Low identifies companies whose verified 2026 activity remains focused on direct sugar production.
Key Developments in the Muscovado & Specialty Unrefined Sugars Market
- In July 2026, Ingredion Incorporated announced new sugar-reduction ingredients and formulation systems for IFT FIRST 2026 including PURECIRCLE sweet protein solutions and FUSERA applications.
- In August 2026, Nordzucker AG commissioned a new extraction tower at its Schladen factory to improve sugar recovery and reduce energy use during production.
- In April 2026, Roquette Frères opened a starch and polyol pilot center in Lianyungang for customer-scale formulation and process trials.
Key Players in the Muscovado & Specialty Unrefined Sugars Market
Formulation and Sugar-Reduction Systems
- Tate & Lyle PLC
- Ingredion Incorporated
- Roquette Frères
Sugar and Functional Ingredient Platforms
- BENEO GmbH
- Südzucker AG
- Nordzucker AG
Cane Sugar and Industrial Sweetener Supply
- ASR Group
- Cargill, Incorporated
- Ragus Sugars (Manufacturing) Limited
- ADM
Muscovado & Specialty Unrefined Sugars Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By type, form, application, claim, sales channel and region. |
| Quantitative Units | USD million. |
| Market Definition | Food-grade muscovado and specialty unrefined sugar ingredients supplied for bakery, foodservice and industrial food manufacturing within the stated taxonomy. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | USA, Germany, France, UK, Saudi Arabia, UAE, Japan and South Korea, and 20+ countries included in the full report. |
| Key Companies Profiled | Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, BENEO GmbH, Südzucker AG, Nordzucker AG, ASR Group, Cargill, Incorporated, Ragus Sugars (Manufacturing) Limited, ADM. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Muscovado & Specialty Unrefined Sugars Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Muscovado & Specialty Unrefined Sugars Market by Segments
Muscovado & Specialty Unrefined Sugars Market segmented by Type:
- Fine grades
- Coarse & decorative
- Organic
- Blends
Muscovado & Specialty Unrefined Sugars Market segmented by Form:
- Powder - dry
- Liquid
- Paste - semi-solid
- Granules - pieces
Muscovado & Specialty Unrefined Sugars Market segmented by Application:
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
Muscovado & Specialty Unrefined Sugars Market segmented by Claim:
- Conventional
- Clean label
- Organic
- Non-GMO - identity preserved
Muscovado & Specialty Unrefined Sugars Market segmented by Sales Channel:
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
Muscovado & Specialty Unrefined Sugars Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Nordzucker AG. (2026, March 16). Start of the 2026 thick juice campaign at the Nordzucker site in Nordstemmen. Source context: Germany.
- USA Department of Agriculture, Economic Research Service. (2025, September 8). Sugar and sweeteners. Source context: United States.
- Ragus. (2026, January 15). Crystalline sugars: what’s the difference?Source context: Global technical.
- Ragus. (2026, June 18). How the right sugar ingredient supplier helps solve product and production challenges. Source context: Global industrial food manufacturing.
- Ragus. (2024, May 2). Muscovado sugar in granular detail. Source context: Global technical.
- Südzucker Group. (2026, May 21). Südzucker with significant decline in earnings in fiscal 2025/26 - Group forecast 2026/27 confirmed. Source context: Europe.
- Ragus. (2026, May 14). Global supply chain disruption and sugar supply: why supplier capability matters more than ever. Source context: Global industrial sugar supply.
- Tate & Lyle PLC. (2026, May 18). Tate & Lyle expands collaboration with BioHarvest to accelerate next-generation sweetener innovation. Source context: Global.
- UK Department of Health and Social Care. (2026, January 5). Landmark junk food ad ban to protect kids’ health. Source context: United Kingdom.
- Nordzucker AG. (2026, September 1). Nordzucker starts the 2026/2027 campaign - factories well prepared. Source context: Europe.
- USA Department of Agriculture, Economic Research Service. (2026, August 19). Sugar and Sweeteners - Market Outlook. Source context: United States.
- German Federal Statistical Office. (2025, May 19). Field crops. Source context: Germany.
- Agreste. (2026, July 28). En 2025, hausse de la production française de sucre dans un contexte d’offre mondiale abondante. Source context: France.
- Department for Environment, Food & Rural Affairs. (2026, July 29). Agriculture in the United Kingdom 2025: Chapter 7 crops. Source context: United Kingdom.
- Saudi Food and Drug Authority. (2025, February 6). Conditions and Requirements for Food Clearance. Source context: Saudi Arabia.
- Ministry of Economy - UAE. (2025, February 20). Ministry of Economy launches national platform for monitoring prices of essential commodities to enhance government oversight of markets and real-time price tracking. Source context: United Arab Emirates.
- Agriculture & Livestock Industries Corporation. (2026, August 10). Sugar supply and demand in Japan. Source context: Japan.
- Ministry of Food and Drug Safety. (2025, April 21). Food Labeling Standards amendment, Notice 2025-27. Source context: South Korea.
- ASR Group. (2026, May 6). Domino Sugar Chalmette refinery breaks ground on landmark modernization project. Source context: United States.
- Roquette Frères. (2026, April 6). Roquette inaugurates its new pilot center at Lianyungang. Source context: China.
- Ingredion Incorporated. (2026, July 6). Ingredion to Spotlight Next-Generation Solutions for Texture, Clean Labels and Positive Nutrition at IFT FIRST 2026. Source context: United States.
- Nordzucker AG. (2026, August 14). New extraction tower at Nordzucker’s Schladen factory increases efficiency in sugar production. Source context: Germany.
- Tate & Lyle PLC. (2026, July 28). Recommended cash acquisition of Tate & Lyle PLC by Ingredion Incorporated - Results of Shareholder Meetings. Source context: Global.
- Nordzucker AG. (2026, August 25). Nordzucker intends to cease sugar production in Nakskov. Source context: Denmark.
- ADM. (2026, January 15). ADM’s $26M Investment in Erlanger Facility Strengthens Capabilities for Growing Reformulation Demand. Source context: United States.
- Cargill. (2026, September 7). Cargill helps food manufacturers accelerate product development processes with tailored functional systems. Source context: Türkiye.
- Tate & Lyle PLC. (2026, February 23). Introducing Yume: A new standard for sweetness. Source context: Americas.
- Ingredion Incorporated. (2026, June 8). Ingredion Announces Recommended All-Cash Acquisition of Tate & Lyle. Source context: Global.
- Roquette Frères. (2026, February 3). NUTRIOSE Soluble Fibers: NutraStrong Prebiotic Verified. Source context: Global.
- BENEO GmbH. (2026, June 25). BENEO launches collection of inspirational sugar-free confectionery concepts to boost category innovation. Source context: Global.
- Südzucker AG. (2026, September 2). Südzucker weiht neue Logistik- und Abwasserbehandlungsanlage am Standort Wabern ein. Source context: Germany.
- Nordzucker AG. (2026, March 25). Nordzucker’s Finnish subsidiary Suomen Sokeri Oy adjusts its production structure. Source context: Finland.
- Ragus. (2026, August 13). Sugar market volatility: what buyers need to know for 2026/27. Source context: Global industrial sugar supply.
- Roquette Frères. (2026, June 26). Roquette Strengthens Food Innovation Presence at Seoul Food 2026. Source context: South Korea and Asia.
- Nordzucker AG. (2026, July 23). Intense preparation for the 2026/2027 campaign at all sites. Source context: Europe.
- Cargill, Incorporated. (2026, March 3). See Cargill solutions in action at Expo West. Source context: United States.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the market through 2036?
- What conditions justify premium specialty sugar in industrial bakeries?
- Which type and form categories hold the 2026 shares?
- Why does bread & rolls hold its application share?
- Which conditions explain the country CAGR spread?
- How do direct sugar and formulation companies differ?
- Which pressures can reduce specialty-grade use?
- What evidence supports repeat specialty sugar approval?
Frequently Asked Questions
How big is the Muscovado & Specialty Unrefined Sugars Market in 2026?
The muscovado & specialty unrefined sugars market is valued at USD 155.2 million in 2026 and is projected to reach USD 319.9 million by 2036. Industrial bakeries justify premium grades only where molasses character and processing performance remain repeatable during commercial production.
What is the CAGR of the Muscovado & Specialty Unrefined Sugars Market from 2026 to 2036?
The muscovado & specialty unrefined sugars market is projected to grow at a CAGR of 7.5% between 2026 and 2036. Expansion depends on premium bakery recipes retaining specialty sugar despite nutrition pressure and competitive conventional sugar pricing.
Which type leads the Muscovado & Specialty Unrefined Sugars Market?
The fine grades segment is expected to hold 38.0% of the muscovado & specialty unrefined sugars market type category in 2026, driven by faster dispersion during commercial mixing. Smaller crystals distribute molasses character more evenly and reduce visible residue during routine bakery production.
Which form leads the Muscovado & Specialty Unrefined Sugars Market?
The powder - dry segment is expected to hold 39.0% of the muscovado & specialty unrefined sugars market form category in 2026, attributable to familiar dry-ingredient handling. Bakery plants can weigh crystalline material with existing storage and batch-dosing equipment without adding pumping or sanitation steps.
Which companies are active in the Muscovado & Specialty Unrefined Sugars Market?
Key companies operating in the market include Tate & Lyle PLC and Ingredion Incorporated with Roquette Frères and BENEO GmbH plus Südzucker AG and Nordzucker AG. ASR Group and Cargill, Incorporated join Ragus Sugars (Manufacturing) Limited and ADM across direct sugar and bakery formulation roles.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Type, 2026 to 2036
- Fine grades
- Coarse & decorative
- Organic
- Blends
- Fine grades
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder / dry
- Liquid
- Paste / semi-solid
- Granules / pieces
- Powder / dry
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bread & rolls
- Cakes & muffins
- Biscuits & cookies
- Viennoiserie & pastry
- Other bakery & snacks
- Bread & rolls
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim, 2026 to 2036
- Conventional
- Clean label
- Organic
- Non-GMO / identity preserved
- Conventional
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to industrial bakeries
- Ingredient distributors
- Foodservice & artisan supply
- Online B2B
- Direct to industrial bakeries
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Form
- By Application
- By Claim
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tate & Lyle
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion
- Roquette
- BENEO
- Sudzucker
- Nordzucker
- ASR Group
- Cargill
- Ragus
- ADM
- Tate & Lyle
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


