

- Market Size (2026)
- USD 42.7 Bn
- Forecast (2036)
- USD 64.4 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Old Corrugated Container (OCC) Market in 2026?
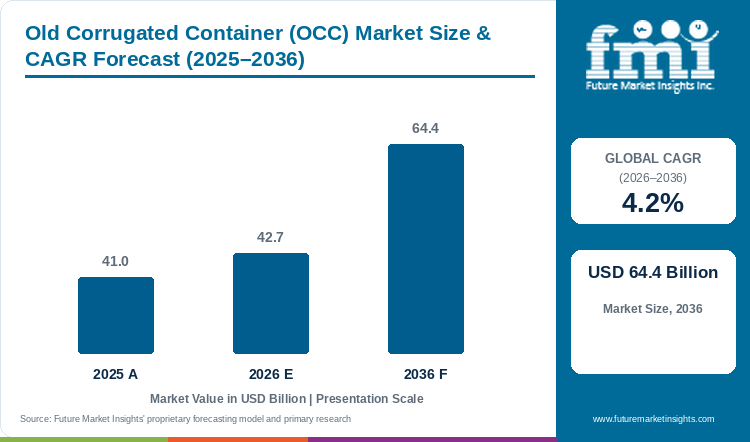
Sales in the old corrugated container (OCC) market are projected to grow at 4.2% CAGR, with market size rising from USD 41.0 billion in 2025 to USD 42.7 billion in 2026 and reaching USD 64.4 billion by 2036.
Corrugated containerboard mills are shifting procurement from gross collected tonnage to net dry fiber yield, as excessive moisture, tape, and film contaminants increase pulping rejections and effluent treatment costs. This commercial transition supports market valuation at USD 41.0 billion in 2025 and USD 42.7 billion in 2026, with revenue forecast to reach USD 64.4 billion by 2036 at a 4.2% CAGR, generating USD 21.7 billion in added revenue. In August 2026, the American Forest & Paper Association (AF&PA) reported that more than 33 million tons of cardboard were recycled across the United States in 2025, with a national recovery rate of 70% to 75% [1]. Containerboard manufacturing leads the application category with 47.8% share in 2026, as repulping operations demand consistent recovered fiber. This supports the hypothesis that fiber purchasing discipline is migrating toward verified source-separated streams; however, freight penalties on hauling moisture and unbaled boxes continue to compress recycling margins across informal collection networks.
Key Market Trends & Insights
- By grade or quality: Standard OCC is projected to account for 40.6% in 2026, supported by predictable fiber strength for routine linerboard and medium production.
- By source: Commercial sources are estimated to hold 38.4% in 2026, owing to cleaner warehouse and retail box streams.
- By processing method: Baling is forecast to represent 32.7% in 2026, driven by lower storage intensity and more efficient mill-bound freight.
- By application: Containerboard manufacturing is set to lead with 47.8% share in 2026, underpinned by repulping demand for linerboard and corrugating medium.
- By end-use industry: E-commerce retail is likely to capture 27.6% in 2026, linked to repeat carton recovery near fulfillment and delivery hubs.
Regional Highlights
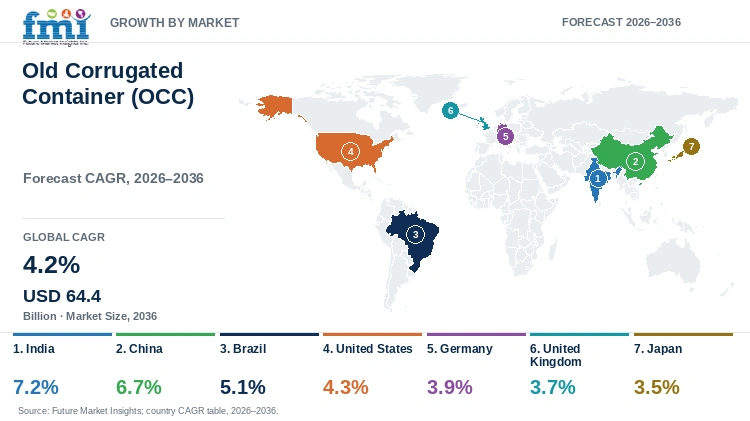
- Fastest-growing evaluated country: India, at 7.2% CAGR from 2026 to 2036.
- China follows at 6.7%, while Brazil reaches 5.1% and the United States records 4.3%. Japan has the lowest evaluated CAGR at 3.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Old Corrugated Container (OCC) Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 41.0 billion |
| Estimated Market Size in 2026 | USD 42.7 billion |
| Projected Market Size by 2036 | USD 64.4 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Revenue, 2026 to 2036 | USD 21.7 billion |
Country demand conditions differ across the profiled markets owing to distinct paper recovery infrastructures and mill furnish requirements. European packaging rules directly influence recovered fiber value, as Regulation (EU) 2025/40 enforces packaging minimization and recyclability from August 2026 [2]. While carton right-sizing stabilizes unit tonnage, cleaner retail sorting delivers higher usable fiber yield during mill pulping. This corroborates that mill profitability increasingly depends on moisture management and automated screening rather than raw collection volume.
Recovered Fiber Throughput and Mill-Intake Sizing
Table 2: Recovered Fiber Throughput Indicators for the Old Corrugated Container (OCC) Market (USD billion and scenario ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 41.0 | 42.7 | 64.4 |
| Implied traded OCC volume index | 100.0 | 103.9 | 157.1 |
| Quality-controlled mill intake share | 54% to 59% | 56% to 61% | 67% to 73% |
| Automated or optical sorting share | 22% to 27% | 24% to 29% | 36% to 43% |
Collection Economics and Facility Sizing
Collection economics are increasingly decided before a bale reaches the mill. Boxes collected from warehouses are normally kept away from food residue and household film, due to which the usable fibre remains higher and the chance of rejection remains lower. This supports recycled paper packaging procurement as mills can purchase against a known source instead of accepting mixed loads with uncertain moisture. Baling further improves truck payload, but the benefit can disappear when a dense bale carries water or prohibited material. Hence, covered storage and source separation are expected to decide which recyclers retain the freight advantage.
Table 3: Collection and Processing Economics for the Old Corrugated Container (OCC) Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market spend per recovered ton index | 100.0 | 104.1 | 157.1 |
| Bale rejection exposure | 6% to 10% | 5% to 9% | 3% to 6% |
| Transport density gain from baling | 3.5x to 5.0x | 3.6x to 5.1x | 4.0x to 5.5x |
| Moisture-control premium | 2% to 5% | 2% to 6% | 3% to 8% |
Table 4: Mill and Commercial Collection Indicators for the Old Corrugated Container (OCC) Market (USD billion and percentages), 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 42.7 billion | Report value |
| Containerboard application revenue, 2026 | USD 20.4 billion | 47.8% share |
| Commercial source revenue, 2026 | USD 16.4 billion | 38.4% share |
| Baling processing revenue, 2026 | USD 14.0 billion | 32.7% share |
Analyst Perspective
“Containerboard mills increasingly treat OCC quality as a production variable rather than a simple waste input. Recyclers controlling moisture, prohibited materials, and delivery consistency will gain stronger access to long-term mill contracts.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the old corrugated container (OCC) market segmented?
The old corrugated container (OCC) market is segmented by grade or quality, source, processing method, application, and end-use industry. In 2026, standard OCC is projected at 40.6%, commercial sources at 38.4%, baling at 32.7%, containerboard manufacturing at 47.8%, and e-commerce retail at 27.6%.
By grade or quality: Standard OCC, high-purity OCC, double-wall OCC, and mixed OCC.
By source: Commercial, residential, municipal, and industrial.
By processing method: Manual sorting, automated sorting, optical sorting, baling, and compaction.
By application: Containerboard, linerboard, corrugating medium, paperboard, and molded pulp.
By end-use industry: E-commerce retail, food packaging, logistics, consumer goods, and industrial manufacturing.
Why does Standard OCC account for a notable share of grade demand?
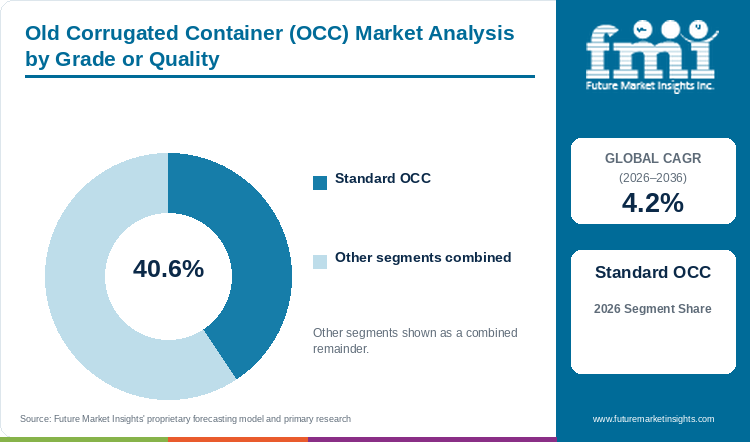
Standard OCC is projected to capture 40.6% of grade demand in 2026, supported by predictable fiber strength and standardized mill pulping recipes.
Table 5: Grade or Quality Share for the Old Corrugated Container (OCC) Market (percentage share), 2026
| Grade or Quality | Share (2026) |
|---|---|
| Standard OCC | 40.6% |
| Other Segments Combined | 59.4%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Grade Leadership and Market Growth for the Old Corrugated Container (OCC) Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Standard OCC |
Standard OCC is maintaining 40.6% share in 2026 as mills can use this grade without making frequent changes in furnish preparation. The share does not mean every standard bale carries the same value. Dry commercial boxes can move through pulping with lower reject generation, whereas a cheaper mixed bale may raise disposal cost and reduce machine consistency. This difference is keeping paper packaging buyers focused on usable fibre rather than only purchased tonnage.
- Standard OCC remains the primary furnish component because continuous repulping operations favor predictable tensile strength and drainability.
- In February 2025, the Institute of Scrap Recycling Industries updated circular paper specifications to establish stricter outthrow limits for standard OCC bales [14].
What supports Commercial Sources as a preferred collection route?
Commercial sources are estimated to represent 38.4% of collection volume in 2026, reflecting cleaner retail backroom recovery and lower contamination rates.
Commercial sources account for 38.4% in 2026 because the box is usually separated near the point where it is unpacked. This keeps food waste and household contamination away from the fibre and gives collectors repeat volume from the same location. Also, route density across retail and distribution sites lowers handling cost per ton. The advantage can weaken when stores leave material outside or mix stretch film into the bale, due to which waste management discipline at source remains more important than the number of collection points.
- Commercial channels deliver consistent recovered volumes that can be monitored for moisture levels and prohibited outthrows.
- In November 2025, the Confederation of European Paper Industries reported that commercial backroom collection accounted for over 60% of high-grade recovered containerboard across European processing mills [5].
How is Baling gaining use across processing methods?
Baling is forecast to command 32.7% of processing activity in 2026, driven by payload optimization and lower freight costs on long-haul routes.
Baling holds 32.7% share in 2026 as loose boxes occupy truck and yard space much faster than their weight can justify. A dense bale raises payload and makes mill storage easier, which is likely to protect margin on longer routes. However, compaction can hide moisture and contaminants inside the load. Recyclers combining calibrated checks with suitable recycling equipment are expected to gain more than operators using density alone, as mills can reject a heavy bale when the fibre yield is not visible.
- Dense rectangular baling minimizes warehouse storage footprints and enables maximum payload utilization on mill-bound trailers.
- Processors combining automated horizontal balers with infrared moisture detection reduce reject rates at receiving paper mills.
Why are buyers selecting Containerboard Manufacturing within applications?
Containerboard manufacturing is anticipated to generate 47.8% of application revenue in 2026, owing to continuous repulping demand for linerboard and medium.
Containerboard manufacturing holds 47.8% of application demand in 2026 because OCC goes back into products where fibre can be consumed at large scale and repeatedly. The economics remain favourable when mills receive dry furnish with controlled outthrows, as pulper downtime and residue disposal stay lower. In April 2025, Mondi started its Duino recycled containerboard machine with planned annual capacity of 420,000 tonnes, illustrating how modern papermaking infrastructure absorbs massive local recovered fiber streams [3].
- Repulping recovered boxes into testliner and fluting medium provides the highest-volume circular application across the paper industry.
- In September 2025, Mondi marked the commercial start-up of its Duino mill following conversion to lightweight recycled containerboard production [3].
Which market conditions keep E-commerce Retail relevant within end use?
E-commerce retail is set to command 27.6% of end-use demand in 2026, reinforced by concentrated box returns near fulfillment hubs.
E-commerce retail represents 27.6% in 2026 as fulfillment centres release boxes in concentrated volume and parcel networks create collection points close to distribution activity. This concentration can keep the fibre cleaner than dispersed household routes. Still, right-sized ecommerce packaging may reduce board used in each shipment, so future demand is likely to depend on parcel growth remaining ahead of material reduction. Recyclers located near hubs stand to gain when frequent collection prevents rain exposure and keeps large cartons out of mixed municipal waste.
- Concentrated parcel unpacking at sorting hubs creates dense, highly accessible corrugated collection nodes.
- Automated recovery agreements between large logistics operators and recycled paper mills ensure predictable weekly furnish volume.
What are the drivers, restraints, and opportunities in the old corrugated container market?
In the old corrugated container market, recycled containerboard expansions drive recurring mill furnish demand, moisture and film contamination restrain bale acceptance, and optical sorting technologies create high-yield commercial recovery opportunities through 2036.
- Driver: Recycled containerboard capacity additions require regular OCC intake with traceable moisture and contamination performance.
- Restraint: Wet boxes, plastic film, and mixed paper raise pulper rejects and trigger bale downgrades or mill rejection.
- Opportunity: Optical sorting, digital bale records, and source-separated commercial routes can support cleaner recovered fiber contracts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Growth of OCC is being pulled by mill requirement rather than collection volume alone. In August 2026, AF&PA documented that U.S. mills consumed 31.4 million tons of recycled paper during 2025, with containerboard accounting for the dominant share [1]. This confirms that recovered boxes are tied directly to active papermaking schedules rather than municipal disposal targets. As mills accelerate production speeds, supplier scorecards, covered storage yards, and automated inspection records gain prominence across corrugated boxes production, protecting continuous paper machine uptime.
Risk Assessment of the Old Corrugated Container Market: Quality and Freight Friction
Moisture is one of the quickest ways for OCC value to move downward. A wet bale carries paid weight without carrying equal fibre and the mill then bears drying, reject and disposal cost. Mixed film creates another hurdle as it can interrupt pulping even when total collection looks healthy. In April 2025, the European Paper Recycling Council highlighted that non-paper components and chemical adhesives in packaging waste increased pulping waste disposal costs by 15% across European mills [6]. Mills are therefore likely to tighten intake during weak containerboard cycles, leaving uncovered yards and export-dependent recyclers more exposed.
Commercial Opportunity Analysis: Sorting Differentiation and Mill-Ready Supply
Automated sorting can improve OCC value when it removes film and non-corrugated paper before baling, but the machine itself does not assure a mill contract. The gain appears when sensor separation is joined with source records, moisture checks and regular delivery. Adopting sustainable packaging solutions and high-purity OCC furnish also creates new commercial avenues in molded fibre pulp packaging, where clean repulped fibers replace single-use plastic cushions across consumer electronics shipping.
Old Corrugated Container (OCC) Market by Country (2026 to 2036)
As per Future Market Insights, India represents the fastest-growing old corrugated container market among the seven evaluated countries at 7.2% CAGR from 2026 to 2036, while Japan records the slowest expansion at 3.5%. Commercial success depends on collection quality, proximity to containerboard mills, and the ability to manage domestic recycling rules.
Table 7: Country CAGR and Primary Growth Levers for the Old Corrugated Container (OCC) Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 7.2% | Recovered-fiber mill dependence and expanding packaging paper demand |
| China | 6.7% | Large parcel recovery pool and domestic mill intake |
| Brazil | 5.1% | Retail box recovery and regional containerboard capacity |
| United States | 4.3% | Deep mill network and mature commercial collection |
| Germany | 3.9% | High-quality recovery and packaging compliance |
| United Kingdom | 3.7% | EPR-backed reporting and commercial collection |
| Japan | 3.5% | High collection discipline and mature paper recycling |
Source: Future Market Insights analysis
India Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
India is expected to record 7.2% CAGR through 2036 as packaging paper demand is increasing faster than the supply of consistently graded domestic fibre. Recovered paper already carries a major role in national paper production, yet collection remains split between organised buyers, municipal movement and informal aggregation. In May 2025, the India Brand Equity Foundation reported that domestic paper and packaging consumption expanded by over 8%, intensifying mill demand for local recovered fiber [7]. Covered aggregation near Gujarat, Maharashtra and southern mill clusters can change this equation by shortening holding time and grading boxes before they are mixed. The hurdle will remain price competition from low-grade supply, but domestic suppliers that prove yield can gain when imported fibre becomes costly or slow.
Key takeaway: In India, acute domestic fiber deficits and rapid corrugated box demand establish long-term growth for organized recovered fiber collection networks.
China Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
China is estimated to expand at 6.7% CAGR through 2036, supported by a parcel system that handled 199.0 billion courier parcels in 2025, according to official data from the State Post Bureau of China [8]. This gives the country a recovery pool which is more concentrated around coastal manufacturing and fulfillment areas than the global market. The same scale also creates inconsistency when household boxes, tapes and film enter mixed routes. Direct collection from distribution centres can keep large mills supplied with visible material origin, while regional price movements may continue to pull boxes away from stable contracts.
Key takeaway: In China, massive courier parcel volume and domestic mill repulping quotas drive large-scale commercial corrugated container recovery.
Brazil Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
Brazil is likely to grow at 5.1% CAGR through 2036, but its OCC economics are more exposed to distance and weather than several other evaluated markets. In July 2025, the Brazilian Tree Industry (Iba) reported that recycled paper collection reached 4.4 million tonnes, driven by expanding agricultural packaging demand [9]. Food distribution and retail activity generate corrugated boxes across wide consumption centres, while paper mills are not always located close to the collection point. A regional baling hub can reduce loose transport, although uncovered storage during heavy rainfall can quickly remove the freight benefit through added moisture.
Key takeaway: In Brazil, expanding agricultural box demand supports recovery, though long transit distances make regional baling and moisture protection vital.
United States Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
The United States is expected to move at 4.3% CAGR through 2036, backed by a deep domestic mill network and mature commercial collection. In October 2025, the U.S. Environmental Protection Agency (EPA) recorded that corrugated boxes constituted the single largest component of municipal solid waste recycling, with recovery rates consistently above 70% [10]. Pratt's 496,000-square-foot Warner Robins plant, producing boxes from 100% recycled containerboard, strengthens a regional loop between collection, mill output and conversion [4]. Suppliers near such loops can manage downturns better, while downgraded loads remain exposed to freight and export pricing.
Key takeaway: In the United States, direct closed-loop partnerships between box plants and containerboard mills anchor stable high-volume OCC demand.
Germany Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
Germany is projected at 3.9% CAGR through 2036 because the recovery system is already mature and leaves less room for easy tonnage growth. In August 2025, the Federal Ministry for the Environment (BMUV) reported a paper and cardboard packaging recycling rate exceeding 88% [11]Dense industrial packaging routes and strong documentation keep boxes traceable before baling.
Key takeaway: In Germany, saturated paper recovery rates reward investments in optical decontamination and closed-loop industrial packaging return systems.
United Kingdom Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
The United Kingdom is forecast to expand at 3.7% CAGR through 2036 and its market is being shaped more by reporting and domestic reprocessing than by fresh recovery volume. In September 2025, the Department for Environment, Food & Rural Affairs (Defra) confirmed an 86.4% packaging recycling rate for paper and cardboard packaging under extended producer responsibility guidelines [12]. EPR reporting can favour suppliers that prove weight and material origin, but export price movement can still pull value away from local mills. Retail contracts and source-separated distribution centres are therefore likely to matter more, as these routes provide cleaner bales without adding another sorting stage.
Key takeaway: In the UK, mandatory packaging waste reporting and rising EPR fees drive direct mill sourcing from commercial retail distribution hubs.
Japan Old Corrugated Container (OCC) Market Outlook (2026 to 2036)
Japan is anticipated to advance at 3.5% CAGR through 2036, the lowest rate among the evaluated countries, as collection discipline and mill coordination are already established. In June 2025, the Japan Paper Association recorded recovered paper utilization in containerboard production at over 93% [13]. This maturity keeps bale quality dependable but reduces the volume that can be newly recovered. Labour cost and frequent collection across smaller urban sites can press margin even when the fibre remains clean. Compact baling, retailer return logistics and digital traceability can protect route economics.
Key takeaway: In Japan, established collection discipline maintains exceptional bale quality, with market expansion driven by compact baling and domestic mill utilization.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the old corrugated container market?
Smurfit Westrock plc, International Paper Company, Mondi plc, Rengo Co., Ltd., Packaging Corporation of America, Cascades Inc., Pratt Industries, Lee & Man Paper Manufacturing Limited, and Nine Dragons Paper Holdings Limited are significant market participants.
Competition in OCC is not decided only by the number of collection trucks. Integrated producers can absorb recovered fibre inside their own mills and box plants, giving them an outlet when export prices weaken. Independent recyclers do not have the same protection and therefore compete through cleaner routes, faster baling and proof of moisture condition. Buyers are increasingly comparing how much usable fibre comes out of a load, due to which a smaller supplier with covered storage can hold a stronger mill position than a larger supplier moving mixed material.
- Global integrated producers: Smurfit Westrock, International Paper, Mondi, and Rengo combine paper mills with corrugated conversion networks.
- North American recycled-fiber platforms: Packaging Corporation of America, Cascades, and Pratt Industries connect mill intake with box production.
- Asian containerboard producers: Nine Dragons Paper and Lee & Man Paper operate large recycled-fiber and packaging paper systems.
Competitive Benchmarking: Old Corrugated Container (OCC) Market
Table 8: Competitive Benchmarking for the Old Corrugated Container (OCC) Market (qualitative capability ratings), 2026
| Company | Recovered Fiber Integration | Containerboard Scale | Collection / Mill Access | Geographic Reach |
|---|---|---|---|---|
| Smurfit Westrock plc | High | High | High | High |
| International Paper Company | High | High | High | High |
| Mondi plc | Medium | High | High | High |
| Rengo Co., Ltd. | Medium | High | Medium | Medium |
| Packaging Corporation of America | High | High | Medium | Medium |
| Cascades Inc. | High | Medium | High | Medium |
| Pratt Industries | High | High | High | Medium |
| Nine Dragons Paper Holdings | High | High | Medium | Medium |
Scoring basis: High indicates public evidence of broad capability across the named dimension. Medium indicates meaningful but more regionally concentrated capability. Ratings are qualitative and do not represent market share.
Key Developments in the Old Corrugated Container (OCC) Market
- In January 2026, Pratt Industries said its 496,000-square-foot Warner Robins facility would produce corrugated boxes using 100% recycled containerboard [4].
- In September 2025, Mondi marked the start-up of its Duino recycled containerboard mill with 420,000 tonnes of planned annual output after full ramp-up [3].
- In August 2026, AF&PA reported that U.S. mills used 31.4 million tons of recycled paper to manufacture new products during 2025 [1].
Key Players in the Old Corrugated Container (OCC) Market
Major Global Integrated Producers
- Smurfit Westrock plc
- International Paper Company
- Mondi plc
- Rengo Co., Ltd.
- Packaging Corporation of America
Specialist and Regional Players
- Cascades Inc.
- Pratt Industries
- Lee & Man Paper Manufacturing Limited
- Nine Dragons Paper Holdings Limited
Old Corrugated Container (OCC) Market - Report Scope
Table 9: Report Scope for the Old Corrugated Container (OCC) Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Grade or Quality; Source; Processing Method; Application; End-use Industry |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from recovered corrugated boxes collected, sorted, baled, traded, and supplied for paper mill intake. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, China, Brazil, United States, Germany, United Kingdom, Japan, and additional countries in the full report |
| Key Companies Covered | Smurfit Westrock, International Paper, Mondi, Rengo, Packaging Corporation of America, Cascades, Pratt Industries, Lee & Man Paper, Nine Dragons Paper |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Old Corrugated Container (OCC) Market - Research Methodology
Table 10: Research Methodology for the Old Corrugated Container (OCC) Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with recovered paper suppliers, recycling operators, mill procurement teams, corrugated converters, distributors, and industry specialists validated demand conditions and purchasing criteria. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public statistics were reviewed. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assessed recovered fiber value, mill intake, segment shares, and country demand for 2026 to 2036. |
| Data Triangulation and Validation | Results were checked against recycling rates, containerboard capacity, parcel activity, packaging regulation, corporate developments, and historical market behavior. |
Old Corrugated Container (OCC) Market by Segments
Old Corrugated Container (OCC) Market segmented by Grade or Quality:
- Standard OCC
- High-purity OCC
- Double-wall OCC
- Mixed OCC
Old Corrugated Container (OCC) Market segmented by Source:
- Commercial
- Residential
- Municipal
- Industrial
Old Corrugated Container (OCC) Market segmented by Processing Method:
- Manual Sorting
- Automated Sorting
- Optical Sorting
- Baling
- Compaction
Old Corrugated Container (OCC) Market segmented by Application:
- Containerboard
- Linerboard
- Corrugating Medium
- Paperboard
- Molded Pulp
Old Corrugated Container (OCC) Market segmented by End-use Industry:
- E-commerce Retail
- Food Packaging
- Logistics
- Consumer Goods
- Industrial Manufacturing
Old Corrugated Container (OCC) Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] American Forest & Paper Association. (2026, August 28). Paper industry announces 2025 U.S. paper recycling rates. AF&PA Newsroom.
- [2] European Parliament and Council. (2025, January 22). Regulation (EU) 2025/40 on packaging and packaging waste. Official Journal of the European Union.
- [3] Mondi plc. (2025, September 22). Mondi Duino marks start-up of recycled containerboard mill with international customers in Italy. Corporate Press Releases.
- [4] Pratt Industries. (2026, January 13). Growing where we began: Our investment in Peach County. Commercial Expansion Reports.
- [5] Confederation of European Paper Industries. (2025, November 18). Key statistics on European paper recycling and mill raw material consumption. Cepi Statistical Reports.
- [6] European Paper Recycling Council. (2025, April 14). Monitoring report 2024: European declaration on paper recycling. EPRC Publications.
- [7] India Brand Equity Foundation. (2025, May 20). Paper and packaging industry overview: Recovered fiber and packaging paper indicators. IBEF Industry Reports.
- [8] State Post Bureau of the People's Republic of China. (2026, January 15). Postal industry statistical bulletin for 2025. National Government Reports.
- [9] Brazilian Tree Industry. (2025, July 10). Annual report: Paper, packaging, and recovered fiber indicators. Ibá Publications.
- [10] U.S. Environmental Protection Agency. (2025, October 24). Paper and paperboard materials recovery and recycling overview. United States Government Reports.
- [11] Federal Ministry for the Environment, Climate Action, Nature Conservation and Nuclear Safety. (2025, August 12). Packaging waste and recycling statistics for paper and carton. BMUV Reports.
- [12] Department for Environment, Food & Rural Affairs. (2025, September 25). UK statistics on waste: Packaging recycling data for 2024. Defra Government Publications.
- [13] Japan Paper Association. (2025, June 18). Recovered paper utilization and recycling statistics in Japan. JPA Statistical Bulletins.
- [14] Institute of Scrap Recycling Industries. (2025, February 16). Scrap specifications circular: Paper stock standards and outthrow limitations. ISRI Technical Guidelines.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the old corrugated container market in 2026 and what is forecast for 2036?
- Which collection and mill-intake pressures support OCC demand?
- Why does standard OCC lead the grade or quality category?
- Why do commercial sources provide a preferred recovery route?
- How do growth rates differ across India, China, Brazil, and the United States?
- Which companies operate across recovered fiber and containerboard production?
- What limits bale acceptance or supplier switching in the OCC market?
- What should mill buyers evaluate before purchasing recovered corrugated fiber?
Frequently Asked Questions
How big is the old corrugated container market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global market will reach USD 42.7 billion in 2026 and USD 64.4 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 4.2% CAGR over the assessment period.
Which grade leads the market?
Standard OCC is projected to hold 40.6% share in 2026 due to predictable fiber quality and broad mill acceptance.
Which application leads demand?
Containerboard manufacturing is forecast to account for 47.8% of application demand in 2026.
Which country has the fastest evaluated growth outlook?
India is projected to register a 7.2% CAGR from 2026 to 2036, followed by China at 6.7%.
Who are the key players?
Notable companies operating in this market include Smurfit Westrock plc, International Paper Company, Mondi plc, Rengo Co., Ltd., Packaging Corporation of America, Cascades Inc., Pratt Industries, and Nine Dragons Paper Holdings.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Grade or Quality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade or Quality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade or Quality, 2026 to 2036
- Standard OCC
- High-purity OCC
- Double-wall OCC
- Mixed OCC
- Y-o-Y Growth Trend Analysis By Grade or Quality, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade or Quality, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Commercial
- Residential
- Municipal
- Industrial
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Method, 2026 to 2036
- Manual Sorting
- Automated Sorting
- Optical Sorting
- Baling
- Compaction
- Y-o-Y Growth Trend Analysis By Processing Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Method, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Containerboard
- Linerboard
- Corrugating Medium
- Paperboard
- Molded Pulp
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End-use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use Industry, 2026 to 2036
- E-commerce Retail
- Food Packaging
- Logistics
- Consumer Goods
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Grade or Quality
- By Source
- By Processing Method
- By Application
- By End-use Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Smurfit Westrock plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- International Paper Company
- Mondi plc
- Rengo Co., Ltd.
- Packaging Corporation of America
- Cascades Inc.
- Pratt Industries
- Nine Dragons Paper Holdings
- Lee & Man Paper Manufacturing Limited
- Nine Dragons Paper Holdings Limited
- Smurfit Westrock plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


