
- Market Size (2026)
- USD 1400.0 Mn
- Forecast (2036)
- USD 2614.2 Mn
- CAGR (2026 to 2036)
- 6.4%
How Big is the Pea Starch Concentrate Market in 2026?
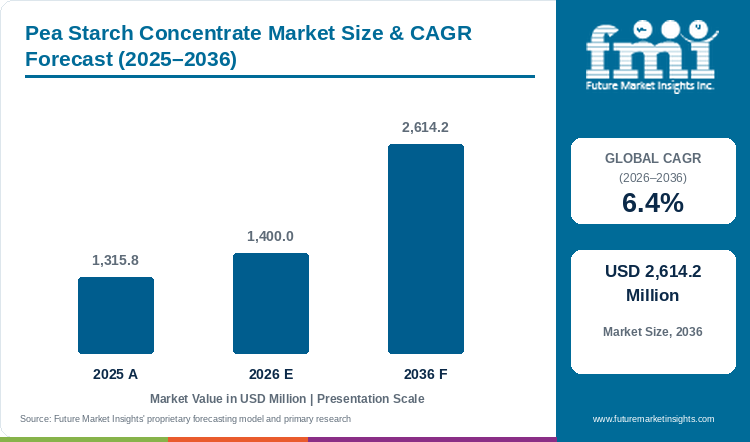
The pea starch concentrate market is valued at USD 1,400.0 million in 2026 and is projected to reach USD 2,614.2 million by 2036, growing at a 6.4% CAGR as per FMI synthetic survey
Pea starch concentrate market size is estimated at USD 1,400.0 Million in 2026, up from USD 1,315.8 Million in 2025, as per FMI, and will widen by USD 1,214.2 Million to USD 2,614.2 Million by 2036 at a 6.4% CAGR. Emsland Group describes yellow-pea starch as a material with about 30.0% to 35.0% amylose that forms firm gels on cooling [1]. That gel strength lets bakers and meat-analogue processors replace part of a corn or potato starch system without lengthening the ingredient label.
Pea starch supply follows protein economics more closely than starch demand, and the adjacent pea protein pool shows the scale of that push. Sales of pea protein will rise from USD 1.82 Billion in 2026 to USD 4.08 Billion by 2036 at an 8.4% CAGR, so the protein pool will keep growing faster than pea starch concentrate through 2036. Every added protein line leaves a starch-rich fraction that fractionators need to sell, and native starch volume will therefore expand faster than buyers ask for native powder. Demand for clean label starch offers a home for part of that surplus, set to expand from USD 1.3 Billion to USD 2.4 Billion at a 6.5% CAGR, a gain of USD 1.1 Billion. Mung bean starch is the smaller and costlier pool open to pea starch, gaining USD 215.0 Million at a 6.4% CAGR as value moves from USD 248.0 Million to USD 463.0 Million.
Value in pea starch is moving toward process-ready grades that absorb the surplus at a better price than native powder. In October 2025, Roquette introduced AMYSTA L 123, a thermally soluble pea starch made with only heat treatment and spray drying for beverages, soups and sauces [2]. PURIS split the company's range into native, pregelatinized and ready-to-eat formats in a July 2025 guide [3]. Investment in soluble and pregelatinized grades will decide how much of the growth pool fractionators turn into margin.
Key Takeaways
- Yellow peas will hold 62.2% of product type market share in 2026, and conventional supply will hold 93.8% by nature.
- Bakery will lead end use with 30.4% of revenue in 2026, and food grade will carry 75.1% of grade demand.
- Key companies operating in the pea starch concentrate market include Roquette Freres, Emsland Group, Ingredion Incorporated, and Cosucra Groupe Warcoing SA, and the full report covers many more players.
- By country, New Zealand will grow fastest at 7.6%, and Brazil will grow slowest at 2.9%.
Analyst Perspective
“Pea starch concentrate will find less obvious demand in glass noodles and vermicelli, as the high amylose in pea starch gives the firm, translucent strands normally made from costlier mung bean starch. I also see new openings in pet food kibble binding, edible films and biodegradable packaging, as gel strength and clean-label status are drawing buyers from outside the core bakery and snack space.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Pea Starch Concentrate Market Segmented?
Analysis splits the pea starch concentrate market by product type, nature, end use, grade, and region, with seven regions tracked.
Product type covers yellow peas and green peas.
Nature covers conventional and organic pea starch concentrate.
End use covers bakery, animal feed, snacks & savory, confectionery, processed meat products, pasta & noodles, ice-cream & desserts, and pharmaceuticals.
Grade covers food grade, feed grade, and industrial grade.
Why Do Yellow Peas Lead the Pea Starch Concentrate Market by Product Type?
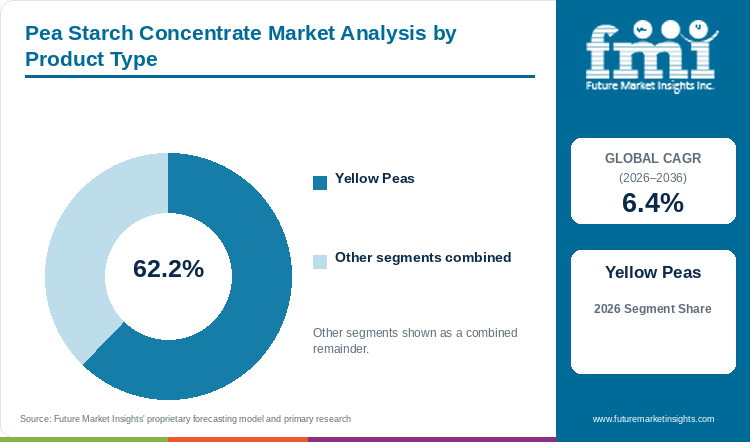
Yellow peas will account for 62.2% of product type market share in 2026, as the largest wet-fractionation lines run on yellow peas.
A wet-fractionation plant earns from protein, starch and fiber out of one pea intake, and the largest lines in operation run on yellow peas. Cosucra identifies NASTAR as a yellow-pea starch, and Nutri-Pea produces Accu-Gel pea starch from Canadian yellow peas [4] [5]. Green peas will remain a niche input, as the colour limits use in light bakery and noodle recipes.
- Yellow peas will hold 62.2% of product type revenue in 2026.
- In September 2026, Emsland Group listed yellow peas as the raw material for native, modified and cold-water-soluble pea starches [1].
Why Does Conventional Supply Lead the Pea Starch Concentrate Market by Nature?
Conventional pea starch concentrate will take 93.8% of nature market share in 2026, avoiding the segregation cost of organic supply.
Organic segregation adds handling cost at every step from field to fractionation plant, and few bakery or snack buyers are paying for that cost today. Most clean-label claims that formulators need come from conventional grades, with PURIS describing all of the company's pea starches as non-GMO and minimally processed from North American peas [3]. Organic grades will stay a smaller, premium option for natural-channel brands willing to absorb the segregation cost.
- Conventional pea starch concentrate will make up 93.8% of nature revenue in 2026.
- In July 2025, PURIS published a pea starch guide covering native PS85, pregelatinized PS85-PG and ready-to-eat PS85-RTE [3].
Why Does Bakery Lead the Pea Starch Concentrate Market by End Use?
At 30.4%, bakery will account for the highest market share by end use in 2026.
Gluten-free bakers face a structural gap, since removing wheat takes away the network that holds crumb and moisture together. Pea starch adds firm-gel binding to those recipes, and FMI places bakery at 30.4% of end-use demand in 2026. Growth of the gluten-free bakery premix category is opening a direct route into bread and cake mixes. Bakers will pick native or pregelatinized grades to match mixing and baking conditions, giving suppliers room to sell tailored grades at a premium over commodity starch.
- Bakery will take 30.4% of end-use demand in 2026, the largest single outlet.
- PURIS stated in July 2025 that native PS85 pea starch is used in cakes, cookies and breads [3].
Why Does Food Grade Lead the Pea Starch Concentrate Market by Grade?
Food grade will account for 75.1% of grade market share in 2026, backed by the specifications and certificates food plants ask for.
Qualification paperwork, from specifications to halal and non-GMO certificates, is the gate a starch passes before entering a food plant, and most supplier portfolios are already built around that gate. Ingredion, for example, describes PURITY P 1002 as a food-grade starch from non-GMO yellow peas for baked goods, snacks and meat products [6]. Food grade will therefore account for 75.1% of grade demand in 2026, according to FMI. Feed and industrial grades will add volume in pet food and adhesives at lower prices per tonne.
- Food grade material will carry 75.1% of grade market share in 2026.
- In July 2026, an IFANCA halal certificate listed Ingredion's PURITY P 1002 pea starch for a plant in Mooresville, Indiana [7].
What are the Drivers, Restraints, and Opportunities in the Pea Starch Concentrate Market?
FMI expects clean-label texture demand to drive sales till 2036, with process sensitivity and cheaper incumbent starches slowing switching and soluble and pregelatinized grades opening a higher-value revenue pool.
- Driver: Demand for pea starch concentrate will rise as food makers look for a pulse-based starch that binds, gels and thickens with a short, familiar ingredient label.
- Restraint: Native pea starch can lose viscosity under acid, shear or long cooking and weep water after cooling, adding validation work [6].
- Opportunity: Adoption potential of soluble and ready-to-eat grades will extend pea starch into beverages, soups and modified starch replacement briefs.
A February 2026 review in Comprehensive Reviews in Food Science and Food Safety described pea starch as a high-amylose ingredient with firm-gel and binding potential [8]. Ingredion's April 2026 specification for PURITY P 1002 states that the native starch tends to gel and show syneresis after cooking and cooling, and that strong acid, shear and long cooking cut viscosity [6]. Plant trials will remain the main point of friction, as buyers will ask for process data before replacing tapioca or corn starch. As a result, pea starch concentrate will compete on documented process tolerance, and physically treated grades will convert more briefs.
Which Country CAGRs are Profiled in the Pea Starch Concentrate Market?
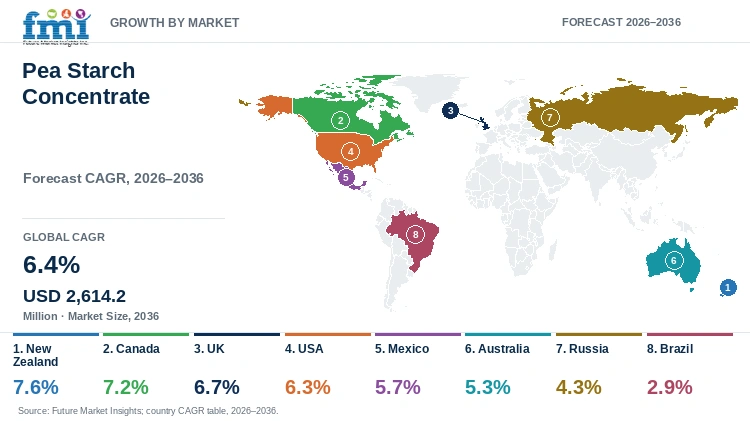
| Country | CAGR, 2026 to 2036 |
|---|---|
| New Zealand | 7.6% |
| Canada | 7.2% |
| UK | 6.7% |
| USA | 6.3% |
| Mexico | 5.7% |
| Australia | 5.3% |
| Russia | 4.3% |
| Brazil | 2.9% |
How do Country-level CAGRs Compare in the Pea Starch Concentrate Market?
FMI's country model spreads growth across a 4.7 percentage point range through 2036, from 7.6% in New Zealand down to 2.9% in Brazil. Canada at 7.2% and the UK at 6.7% complete a top three that sits above the 6.4% global rate. The ranking measures pace alone, so the USA can still carry more revenue at a slower rate.
- Growth in Australia at 5.3% will rest on a recovering pulse base, as winter crops posted a 20.0% rise in value for 2024-25 [9].
- Demand in Mexico at 5.7% will run through regional suppliers, with Ingredion listing PURITY P 1002 on a Mexican product page [10].
- Brazil will grow 4.7 points slower than New Zealand, as cassava starch will keep the cost of switching high for local processors.
Regional CAGRs for North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa sit in the full study, which covers 27 countries and country groups.
Country Outlook
- New Zealand leads the profiled countries at a 7.6% CAGR, a pace built on imports, since specialty food and snack formulators there buy finished grades from overseas suppliers. Suppliers holding regional stock will convert this demand first, as short lead times will count for more with small buyers than list price.
- Supply depth sets Canada apart, with Statistics Canada reporting 3.9 million tonnes of dry peas in 2025, up 32.1% from a year earlier [11]. That crop base will support a 7.2% CAGR till 2036, and Canadian processors will compete on purity, process tolerance and certified grades for export buyers.
- UK growth of 6.7% will lean on imported peas, as Defra reported 60 thousand hectares of field peas in 2025 after a 32.0% fall in area [12]. The same year brought the first confirmed UK detection of pea bruchid [12]. Traceability and landed cost will therefore steer supplier choice for British bakery and snack processors.
- USDA National Agricultural Statistics Service estimated dry edible pea production at 18.5 million cwt in 2025, up 9.0% from the prior season [13]. Domestic grades are already documented for food plants, with Ingredion listing PURITY P 1002 for baked goods, snacks and meat products and PURIS selling pea starch formats from North American peas [6] [3]. Repeat orders, more than new trials, will shape the 6.3% CAGR for the USA through 2036.
- Russia will grow at a 4.3% CAGR, the second-slowest rate in the group, as export buyers keep competing for raw peas. Federal Center Agroexport reported that Russian pea exports to China reached about USD 380 million in January to November 2025, twice the value of the same period in 2024 [14]. Domestic fractionators will keep bidding against Chinese demand for the same crop, holding starch output below what the harvest could support.
Who are the Notable Companies in the Pea Starch Concentrate Market?
Key companies in the market include Roquette Freres, Cosucra Groupe Warcoing SA, Emsland Group, AGT Food and Ingredients Inc., Ingredion Incorporated, Puris Foods, Vestkorn Milling AS, Yantai Shuangta Food Co., Ltd., and Nutri-Pea Limited.
Competition in pea starch concentrate is moderately consolidated, and the basis of competition differs by supplier type. Starch and texturizer majors such as Roquette, Emsland Group and Ingredion compete on grade range and technical service, with new grades as the main lever, as shown by the October 2025 launch of Roquette's AMYSTA L 123 for beverages, soups and sauces [2]. Integrated pea fractionators such as Cosucra, PURIS, Yantai Shuangta and Nutri-Pea sell protein, starch and fiber from the same pea, and Yantai Shuangta's 2025 annual report confirmed in-house pea starch output from a dedicated starch workshop [15]. Because these plants run mainly for protein, starch pricing will often be set to clear the fraction, keeping pressure on native-grade prices. Dry-milled concentrate suppliers such as AGT and Vestkorn enter at the lower-cost end, and Vestkorn sells a starch-rich pea concentrate for food use [16]. Entry barriers will stay in qualification more than in plant capital, since every new supplier faces the same bench and plant trials before a first order.
Competitive intensity, in FMI's view, will rise through 2036 as new pea protein capacity pushes more starch onto the market. Suppliers with soluble, pregelatinized and application-tested grades will hold better margins than producers selling native powder alone.
Profiled companies fall into three groups defined by how each one sources starch. Integrated plants sell protein, starch and pea fiber from one pea, so starch pricing will reflect protein economics, and dry millers will offer starch-rich flours at a lower processing cost than wet fractionation.
- Broad Starch and Texturizer Platforms: Roquette Freres, Emsland Group and Ingredion Incorporated pair pea starch with wider texturizer ranges and application laboratories.
- Integrated Pea Fractionators: Cosucra Groupe Warcoing SA, Puris Foods, Yantai Shuangta Food Co., Ltd. and Nutri-Pea Limited wet-process peas into protein, starch and fiber.
- Dry-Milled Pulse Concentrate Suppliers: AGT Food and Ingredients Inc. and Vestkorn Milling AS dry-mill pulses into starch-rich concentrates and flours, including AGT's high-viscosity pulse flour for thickening [17].
Competitive Benchmarking
| Company | Dedicated Pea Starch Range | Functional Processing Breadth | Application Coverage | Geographic Reach |
|---|---|---|---|---|
| Roquette Freres | High | Medium | Medium | Global |
| Cosucra Groupe Warcoing SA | High | High | High | Belgium and European markets |
| Emsland Group | High | High | High | Europe and North America |
| AGT Food and Ingredients Inc. | Medium | Medium | High | Canada, USA, and international markets |
| Ingredion Incorporated | High | Medium | High | North America |
| Puris Foods | High | High | High | USA and international customers |
| Vestkorn Milling AS | High | Medium | High | Norway and Denmark |
| Yantai Shuangta Food Co., Ltd. | High | Low | Low | China and export markets |
| Nutri-Pea Limited | High | Medium | High | Canada |
Scoring basis: Dedicated Pea Starch Range counts documented starch products, Functional Processing Breadth scores native, instant, pregelatinized, modified or soluble formats, and Application Coverage scores documented end uses. High marks broad documented capability, Medium marks narrower capability, and Low marks limited public documentation. Scores reflect an FMI review of public company documentation in September 2026.
Key Developments
- In July 2025, PURIS published a pea starch selection guide that splits native PS85, pregelatinized PS85-PG and ready-to-eat PS85-RTE by application, from baked goods to drink powders [3].
- In October 2025, Roquette introduced AMYSTA L 123, a thermally soluble pea starch produced by a patented heat and spray-drying process without enzymes or chemicals [2].
- In April 2026, Yantai Shuangta Food Co., Ltd. reported continued in-house pea starch production in a dedicated starch workshop in the company's 2025 annual report [15].
Key Players
Broad Starch and Texturizer Platforms
- Roquette Freres
- Emsland Group
- Ingredion Incorporated
Integrated Pea Fractionators
- Cosucra Groupe Warcoing SA
- Puris Foods
- Yantai Shuangta Food Co., Ltd.
- Nutri-Pea Limited
Dry-Milled Pulse Concentrate Suppliers
- AGT Food and Ingredients Inc.
- Vestkorn Milling AS
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | 4 categories: Product Type (Yellow Peas, Green Peas), Nature (Conventional, Organic), End Use (Bakery, Animal Feed, Snacks & Savory, Confectionery, Processed Meat Products, Pasta & Noodles, Ice-Cream & Desserts, Pharmaceuticals), Grade (Food Grade, Feed Grade, Industrial Grade), and Region |
| Quantitative units | USD Million |
| Market definition | Revenue from pea-derived starch ingredients and starch-rich concentrates sold mainly for starch functionality, including native, instant, pregelatinized, thermally soluble and functional grades. The definition excludes downstream finished-product revenue, other starches, isolated pea protein or fiber revenue, and whole pulse flour not marketed for starch functionality. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | 27 countries and country groups, including New Zealand, Canada, the UK, the USA, Mexico, Australia, Russia, and Brazil |
| Key companies profiled | A few of the notable companies among many players covered in the study include Roquette Freres, Cosucra Groupe Warcoing SA, Emsland Group, AGT Food and Ingredients Inc., Ingredion Incorporated, Puris Foods, Vestkorn Milling AS, Yantai Shuangta Food Co., Ltd., and Nutri-Pea Limited |
| Forecast period | 2026 to 2036 |
| Approach | A hybrid bottom-up and top-down sizing framework reconciles pea starch volumes, grade pricing and supplier revenue signals with pea crop, fractionation and food-processing indicators. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | The primary-research framework engages pea fractionators, starch and texturizer suppliers, distributors, bakery, snack and meat processors, and formulation specialists to test purchase drivers, grade requirements, pricing and repeat-order conditions. |
| Desk research | The analysis reviews crop statistics, trade data, technical literature, product specifications, certificates and company reports. The study retains sources that define demand, feedstock, grade performance or supplier activity inside the market boundary. |
| Market sizing and forecasting | The sizing framework combines the baseline value with segment structure, grade pricing and volume indicators, company participation and country-level pea supply and food processing. Forecasts consider new grades, protein capacity, substitute starch economics and qualification cycles. |
| Data validation | Estimates are checked against public data, company activity and interview findings. Other starches, pea protein and fiber revenue, overlapping revenues and unsupported claims are excluded before final reconciliation. |
Pea Starch Concentrate Market by Segments
Pea Starch Concentrate Market Segmented by Product Type
- Yellow Peas
- Green Peas
Pea Starch Concentrate Market Segmented by Nature
- Conventional
- Organic
Pea Starch Concentrate Market Segmented by End Use
- Bakery
- Animal Feed
- Snacks & Savory
- Confectionery
- Processed Meat Products
- Pasta & Noodles
- Ice-Cream & Desserts
- Pharmaceuticals
Pea Starch Concentrate Market Segmented by Grade
- Food Grade
- Feed Grade
- Industrial Grade
Pea Starch Concentrate Market Segmented by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] Emsland Group (2026, September). Pea starch & modified pea starch.
- [2] Roquette (2025, October 30). AMYSTA™ L 123, the New Label-Friendly Soluble Pea Starch.
- [3] PURIS (2025, July 1). Your Guide to Choosing the PURIS Pea Starch for Your Product.
- [4] Cosucra (2026, September). NASTAR Pea Starch.
- [5] Nutri-Pea (2026, September). Accu-Gel Pea Starch.
- [6] Ingredion (2026, April 1). PURITY P 1002 Technical Specification.
- [7] IFANCA / Ingredion (2026, July 20). Halal Certificate - PacMoore Process Technology, Mooresville.
- [8] Institute of Food Technologists / Wiley (2026, February 14). Pea Starch and Pea Fiber - A Review of Functional Properties, Sensory Characteristics, and Value-Added Uses. Comprehensive Reviews in Food Science and Food Safety.
- [9] Australian Bureau of Statistics (2026, March 2). Winter crops recover with 20% rise in value for 2024-25.
- [10] Ingredion (2026, September). PURITY P 1002 pea starch - Mexico.
- [11] Statistics Canada (2026, February 4). Canada's multi-billion-dollar bean business.
- [12] Department for Environment, Food & Rural Affairs (2026, September 3). Agriculture in the United Kingdom 2025, Chapter 7 - Crops.
- [13] USDA National Agricultural Statistics Service (2026, January 12). Crop Production 2025 Summary.
- [14] Federal Center Agroexport (2026, January 5). За 11 месяцев 2025 года российский агроэкспорт в Китай вырос на 14%.
- [15] Yantai Shuangta Food Co., Ltd. (2026, April 22). 2025 Annual Report.
- [16] Vestkorn (2026, September). Pea Starch Concentrate - Food.
- [17] AGT Food and Ingredients (2026, September). PulsePlus High Viscosity Flour V-6000.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will the Pea Starch Concentrate Market size be in 2026, and what value will the market reach by 2036?
- Which formulation needs will continue to support demand for pea starch concentrate?
- Why will yellow peas hold the leading position within the Product Type category in 2026?
- Why will conventional supply lead the Nature category?
- Why will bakery and food grade remain the main outlets for pea starch concentrate?
- How will growth rates differ across New Zealand, Canada, the UK, the USA, Mexico, Australia, Russia, and Brazil till 2036?
- How will soluble, pregelatinized and ready-to-eat grades raise the value of pea starch sales?
- How will process sensitivity and cheaper incumbent starches slow supplier switching?
- What will food manufacturers need to check before qualifying a new pea starch supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Yellow Peas
- Green Peas
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Bakery
- Animal Feed
- Snacks & Savory
- Confectionery
- Processed Meat Products
- Pasta & Noodles
- Ice-Cream & Desserts
- Pharmaceuticals
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Grade, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Grade, 2026 to 2036
- Food Grade
- Feed Grade
- Industrial Grade
- Y-o-Y Growth Trend Analysis By Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By End Use
- By Grade
- Key Takeaways
- Key Countries Market Analysis
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By End Use
- By Grade
- New Zealand
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By End Use
- By Grade
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Roquette Freres
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cosucra Groupe Warcoing SA
- Emsland Group
- AGT Food and Ingredients Inc.
- Ingredion Incorporated
- Puris Foods
- Vestkorn Milling AS
- Yantai Shuangta Food Co., Ltd.
- Nutri-Pea Limited
- Roquette Freres
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 26: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 28: East Asia Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 29: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Million) Forecast by Grade, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Million) Forecast by Grade, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Nature
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Grade
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Type
- Figure 29: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Nature
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Grade
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type
- Figure 42: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Nature
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Grade
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Type
- Figure 55: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Nature
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Grade
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Grade
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Type
- Figure 81: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Nature
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Grade
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Grade
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Grade
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How Big Is the Pea Starch Concentrate Market Expected to Be in 2026?
Sales of pea starch concentrate total USD 1,400.0 Million in 2026, up from USD 1,315.8 Million in 2025, according to FMI. Revenue will reach USD 2,614.2 Million by 2036 as formulators adopt pulse-derived starch for binding, gelling and short labels.
What Is the CAGR of the Pea Starch Concentrate Market from 2026 to 2036?
Sales of pea starch concentrate will grow at a 6.4% CAGR from 2026 to 2036. Conversion of plant trials into repeat orders will set the pace, with process-ready grades shortening validation.
Which Product Type Holds the Largest Share of the Pea Starch Concentrate Market?
Yellow peas will lead with 62.2% of product type revenue in 2026. Major fractionators run wet-processing lines on yellow peas and will keep selling starch alongside protein and fiber.
Which Nature Segment Leads the Pea Starch Concentrate Market?
FMI projects that conventional supply will account for 93.8% of nature revenue in 2026. A wider raw-material pool and no organic segregation cost will keep conventional grades ahead.
Which Country Is Expected to Grow Fastest in the Pea Starch Concentrate Market?
Growth of pea starch concentrate sales will be fastest in New Zealand, at a 7.6% CAGR till 2036, with Canada following at 7.2%. Brazil will sit last among the eight profiled countries at 2.9%.
What Notable Restraint Affects the Pea Starch Concentrate Market?
Key challenges in the pea starch concentrate market will include viscosity loss under acid, shear or long cooking and syneresis after cooling. Buyers will need bench and plant validation before replacing a familiar corn, potato or tapioca starch.
Which Are the Key Companies in the Pea Starch Concentrate Market?
Roquette Freres, Cosucra Groupe Warcoing SA, Emsland Group, AGT Food and Ingredients Inc., Ingredion Incorporated, Puris Foods, Vestkorn Milling AS, Yantai Shuangta Food Co., Ltd., and Nutri-Pea Limited rank among the notable companies covered in the study. Analysts will group these companies by starch route, separating broad texturizer platforms, integrated pea fractionators and dry-milled concentrate suppliers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
