

- Market Size (2026)
- USD 5.3 Bn
- Forecast (2036)
- USD 8.4 Bn
- CAGR (2026 to 2036)
- 5.0%
How big is Chickpea Flour Market in 2026?
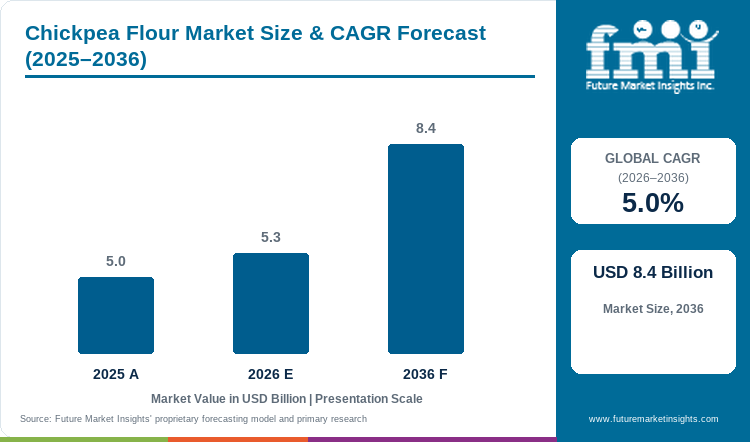
USD 5.3 Billion in 2026 and USD 8.4 Billion by 2036 at a 5.0% CAGR.
Sales of chickpea flour are estimated to grow at 5.0% from USD 5.3 Billion in 2026 to USD 8.4 Billion by 2036. The market was valued at USD 5.0 Billion in 2025. Traditional besan-based dishes remain an important demand base, while food manufacturers are extending chickpea flour into bakery, snacks and other pulse-based formulations.
The commercial opportunity is moving beyond nutrition alone. USDA Agricultural Research Service work reported in 2025 found that cultivar and processing choices influence off-flavors in bean and chickpea flours. This matters because a manufacturer can benefit from the protein and fiber content of a pulse ingredient only when its flavor and processing behavior fit the finished food. The wider pulse flours market and chickpea protein provide adjacent routes for processors seeking different levels of functionality and protein concentration.
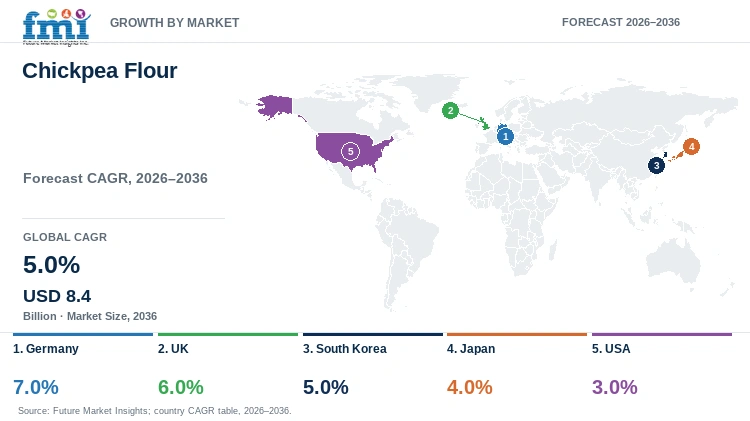
The growth mechanism differs by country. Germany leads the profiled markets at 7.0% CAGR, followed by the UK at 6.0%. The European Commission's 2025-2035 agricultural outlook expects healthier diets and greater demand for plant proteins to support food use of arable crops and pulses. In parallel, regulations governing ingredient declarations, import documentation and gluten-free claims influence which flour grades can move efficiently into commercial formulations.
Key Takeaways of Chickpea Flour Market
- Traditional besan consumption and new food formulations together support recurring chickpea flour demand.
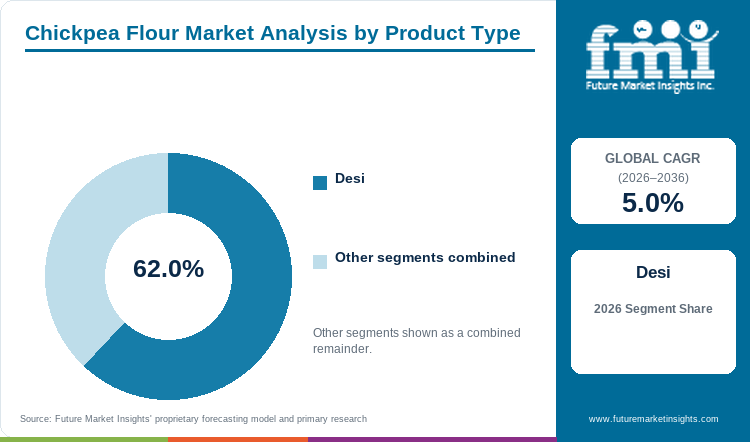
- In 2026, Desi leads the Product Type segment with a 62.0% share, reflecting its established role in traditional chickpea flour applications.
- Food Chain Services accounts for 30.0% of Distribution Channel demand in 2026, supported by its role in moving chickpea flour through food-related commercial channels.
- Crop variability and sensory differences can complicate consistent sourcing and formulation performance for industrial users.
- Germany records the highest profiled country CAGR at 7.0%, followed by the UK at 6.0%, reflecting different market development conditions.
- Notable participants include ADM, Ingredion Incorporated, AGT Food and Ingredients, Diefenbaker Spice & Pulse, and Bob's Red Mill, with direct chickpea-flour or pulse-flour offerings.
Analyst Perspective
“The strongest chickpea flour business is built around repeatable performance. Buyers will continue paying for a flour that holds texture, flavor and processing behavior across production runs, particularly when the ingredient is being introduced into a recipe that previously relied on another flour system.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Chickpea Flour Market segmented?
Chickpea Flour Market is segmented by Product Type, Distribution Channel and Region.
Product Type comprises Desi and Kabuli. Distribution Channel comprises Food Chain Services, Modern Trade, Convenience Store, Other Distribution Channel, Online Store and Departmental Store. Regional analysis covers North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Desi lead demand within the Product Type category?
Desi has a flour-first commercial position because it is deeply established in besan and related foods. Milling reduces the importance of the large seed appearance associated with Kabuli chickpeas and shifts the buying decision toward hydration, flavor, particle size and cooking behavior. The broader chickpea market therefore does not translate directly into the same product mix as the flour market because whole-seed and milled uses follow different purchasing criteria.
- Desi accounts for 62.0% of Product Type demand in 2026.
- Its lead reflects established flour consumption and familiarity in recipes where besan is already the expected ingredient.
Why do Food Chain Services lead demand within the Distribution Channel category?
Food Chain Services generate recurring demand once a chickpea-flour recipe becomes part of a regular menu. Restaurants and institutional kitchens need the same batter viscosity, binding behavior and finished texture across multiple outlets and preparation shifts. Retail consumers can switch between brands or pack sizes more easily, whereas a chain operator has a stronger reason to retain an approved specification once the recipe has been standardized.
- Food Chain Services account for 30.0% of Distribution Channel demand in 2026.
- Regular menu execution creates repeat purchasing and raises the commercial value of batch-to-batch consistency.
What are the drivers, restraints and opportunities in the Chickpea Flour Market?
Plant-forward recipe development supports demand, crop and sensory variability complicate repeat sourcing, and functional flour grades create opportunities in qualified formulations.
- Driver: Plant-forward menus create more occasions to qualify chickpea flour.
- Restraint: Crop and sensory variability can disrupt repeatable manufacturing performance.
- Opportunity: Functional grades can solve binding, viscosity and texture requirements.
Plant-forward product development is widening the addressable application base
Chickpea flour is well positioned to move into mainstream food manufacturing when it addresses more than a nutritional brief. Bakery, snack, batter and convenience-food developers increasingly weigh pulse ingredients on flavor, texture and process compatibility. USDA ARS reported in 2025 that cultivar and processing differences influence the sensory profile of chickpea flour, reinforcing the commercial importance of selecting material for the finished product rather than purchasing solely against a generic protein specification.
The ingredient also operates within the broader pulse ingredients space, where processors can choose between flour, protein-rich fractions and other functional components. Flour retains an advantage when a manufacturer wants a less fractionated ingredient that contributes solids, nutrition and functional behavior in one input.
Crop exposure and sensory inconsistency can raise switching costs
Chickpea production remains exposed to weather and agronomic pressures. GRDC's 2025 chickpea crop guidance continues to emphasize disease management, including Ascochyta blight and Botrytis grey mould. For flour buyers, agricultural variability becomes a commercial issue when it changes flavor, hydration or processing consistency between accepted lots.
The constraint is therefore not simply the availability of chickpeas. A manufacturer may have to repeat formulation work when a replacement flour behaves differently in mixing, extrusion, frying or baking. Lower raw-material cost can be offset by production downtime, altered yield or another round of application testing.
Functional grades can compete on cost-in-use rather than price per kilogram
Processed grades give suppliers an opportunity to sell against a specific manufacturing problem. AGT Food and Ingredients currently lists native chickpea flour as well as pregel chickpea flour, with functions including binding, viscosity development, gel formation and extrusion. ADM also lists chickpea ingredients in flour, grit, powder and whole formats.
This creates a route for chickpea flour to compete within the gluten-free flours category on processing performance as well as crop identity. The higher-value opportunity emerges when a particular flour reduces the total cost of reaching an acceptable texture, yield or finished-product specification.
Which country CAGRs are profiled in the Chickpea Flour Market?
| Country | CAGR |
|---|---|
| Germany | 7.0% |
| UK | 6.0% |
| South Korea | 5.0% |
| Japan | 4.0% |
| USA | 3.0% |
How do country-level CAGRs compare in the Chickpea Flour Market?
Germany and the UK form the higher-growth group at 7.0% and 6.0%, respectively. South Korea follows at 5.0%, while Japan and the USA are projected at 4.0% and 3.0%. The difference between Germany and the USA is 4.0 percentage points over the 2026 to 2036 forecast period.
Country-wise Analysis
- Germany: The German chickpea flour market is forecast to expand at 7.0% CAGR through 2036. The wider European food system is increasing attention to pulse production and plant-protein availability. The EU Agricultural Outlook 2025-2035 links food use of arable crops with consumer interest in healthier diets and plant proteins. For German food manufacturers, this provides a stronger environment for pulse-based bakery, snack and prepared-food development, but the flour still has to deliver acceptable flavor and processing behavior.
- UK: The UK market is projected to grow at 6.0% CAGR from 2026 to 2036. Foodservice and bakery buyers operate within detailed ingredient and allergen-labeling requirements. FSA guidance requires PPDS foods to display the food name, a full ingredient list and emphasized declarations for relevant allergens. Chickpea flour can support product reformulation, but supplier changes still require dependable ingredient information so customers can maintain compliant labels and internal specifications.
- South Korea: South Korea is forecast to expand at 5.0% CAGR. MFDS amended food labeling standards in April 2025 as South Korea prepared for broader nutrition-labeling requirements from 2026. This increases the value of clear compositional information when imported ingredients enter formulated foods. Chickpea flour suppliers serving the market therefore benefit from consistent technical documentation alongside functional performance.
- Japan: Japan's chickpea flour market is forecast to rise at 4.0% CAGR through 2036. The Ministry of Health, Labour and Welfare's FY2026 Imported Foods Monitoring Plan continues Japan's structured oversight of food imports from production through entry and domestic distribution. Ingredient suppliers therefore need shipment documentation and product specifications that remain aligned with the material being imported.
- USA: The US market is projected to grow at 3.0% CAGR. Chickpeas are naturally free from gluten, but that does not automatically qualify every milled product or finished food for a gluten-free claim. FDA guidance explains that cross-contact can occur through crop commingling, shared transport, storage or manufacturing equipment and that foods carrying the claim must contain less than 20 ppm gluten. This makes contamination control and supplier documentation commercially important for bakery and snack manufacturers using chickpea flour.
Who are the notable companies in the Chickpea Flour Market?
ADM, Ingredion Incorporated, AGT Food and Ingredients, Diefenbaker Spice & Pulse and Bob's Red Mill are notable companies with directly documented chickpea-flour or pulse-flour offerings.
Competition spans industrial ingredient platforms, specialist pulse processors and retail flour brands. ADM currently lists chickpea flour among its non-GMO chickpea formats. Ingredion's plant-based protein portfolio includes flours sourced from chickpea and other pulses. AGT Food and Ingredients offers both native and pregel chickpea flours through PulsePlus. Diefenbaker Spice & Pulse lists chickpea flour, also known as besan, among the ground products processed at its facility. Bob's Red Mill sells stone-ground chickpea flour for baking and cooking applications.
The competitive distinction is how each supplier converts chickpea availability into a usable flour specification. Industrial users tend to place greater weight on grade choice, formulation support, lot consistency and logistics, while retail brands compete more directly on pack format, accessibility and consumer familiarity.
- Industrial chickpea-flour platforms: ADM; Ingredion Incorporated; AGT Food and Ingredients.
- Specialist pulse milling: Diefenbaker Spice & Pulse.
- Retail and foodservice flour access: Bob's Red Mill.
Competitive Benchmarking: Chickpea Flour Market
Scoring basis: Chickpea-flour grade breadth is High where a supplier documents multiple chickpea flour formats or processed grades; Medium where a narrower flour range is documented; Low denotes a limited direct offer. Flour functionality evidence is High when documented properties address multiple processing functions; Medium denotes more limited functionality information. Application-development support is High where the supplier provides formulation resources or technical support, Medium where application guidance is narrower, and Low where the offer is primarily transactional. Unscored is used where the published scope does not support a dependable assessment.
| Company | Chickpea flour grade breadth | Flour functionality evidence | Application-development support | Geographic Reach |
|---|---|---|---|---|
| ADM | High | Medium | High | North America with broader international ingredient operations |
| Ingredion Incorporated | Medium | Medium | High | North America and international ingredient markets |
| AGT Food and Ingredients | High | High | Medium | North American processing and international pulse markets |
| Diefenbaker Spice & Pulse | Medium | Medium | Medium | Canada with export-oriented supply |
| Bob's Red Mill | Medium | Medium | High | United States retail and foodservice distribution |
Key Developments in the Chickpea Flour Market
- In January 2025, Ingredion Incorporated ceased operations at its Vanscoy plant protein concentrates and flour facility. The development increases the importance of identifying the actual supplying facility when buyers qualify pulse-flour contracts.
- In March 2026, Protein Industries Canada announced a project with AGT Food and Ingredients and Sweet Nutrition to improve the functionality of pulse proteins, starches and fibres derived from peas, lentils and faba beans, expand production capacity and commercialize Canadian pulse-based foods and ingredients.
- In May 2026, ADM launched eight new soy and pea protein products in North America and Europe. Although the launch centers on soy and pea rather than chickpea flour, it raises the competitive benchmark for pulse ingredients around functionality, nutrition and application support.
Key Players in the Chickpea Flour Market
Industrial chickpea-flour and pulse-ingredient platforms
- ADM
- Ingredion Incorporated
- AGT Food and Ingredients
Specialist pulse milling
- Diefenbaker Spice & Pulse
Retail and foodservice flour brands
- Bob's Red Mill
Chickpea Flour Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Distribution Channel; Region |
| Quantitative Units | Revenue in USD Billion and CAGR in %. |
| Market Definition | Revenue from food-grade Desi and Kabuli chickpea flour at its first external sale, including native and processed grades still sold as flour. Whole chickpeas, separated protein or starch ingredients, other pulse and cereal flours, animal-feed uses, downstream finished foods and foodservice meal revenue are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany; UK; South Korea; Japan; USA |
| Key Companies Profiled | ADM; Ingredion Incorporated; AGT Food and Ingredients; Diefenbaker Spice & Pulse; Bob's Red Mill |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Chickpea Flour Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, millers, ingredient suppliers, distributors, food manufacturers, foodservice buyers, procurement teams and subject-matter experts. Interviews examined purchasing criteria, formulation requirements, supply continuity, pricing, product qualification and technical support. |
| Desk Research | Desk research covered government statistics, regulatory publications, agricultural research, technical literature, standards, company filings, current product information and official corporate announcements. |
| Market Sizing and Forecasting | The market model combines the baseline value with historical performance, segment structure, pricing and volume indicators, company participation, purchasing behavior and country-level demand conditions. Forecast assumptions consider food formulation trends, agricultural supply, regulation and channel development. |
| Data Validation | Estimates are assessed against independent indicators including company activity, ingredient portfolios, crop conditions, regulatory developments, trade patterns and findings from primary interviews. |
Chickpea Flour Market by Segments
Chickpea Flour Market segmented by Product Type:
- Desi
- Kabuli
Chickpea Flour Market segmented by Distribution Channel:
- Food Chain Services
- Modern Trade
- Convenience Store
- Other Distribution Channel
- Online Store
- Departmental Store
Chickpea Flour Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- USDA Agricultural Research Service (2025). Detection of off-flavors in bean and chickpea flours.
- Grains Research and Development Corporation (2025). Chickpea Crop Improvement Plan.
- European Commission (2025). EU Agricultural Outlook 2025-2035.
- Food Standards Agency (2026). Labelling guidance for prepacked for direct sale food products.
- Ministry of Food and Drug Safety, South Korea (2025, April 21). Amendment to Food Labeling Standards, Notice No. 2025-27.
- Ministry of Health, Labour and Welfare, Japan (2026). Imported Foods Monitoring Plan for FY2026.
- US Food and Drug Administration (current). Questions and Answers on the Gluten-Free Food Labeling Final Rule.
- Ingredion Incorporated (2025, January 6). Form 8-K: Cessation of Operations at the Vanscoy Plant Protein Concentrates and Flour Facility.
- Protein Industries Canada (2026, March 31). Unlocking the full value of Canadian pulses through innovative foods and ingredients.
- ADM (2026, May 20). ADM Advances Protein Innovation with New Ingredient Solutions.
- ADM (current). Beans and Pulses.
- Ingredion Incorporated (current). Plant-Based Protein Portfolio.
- AGT Food and Ingredients (current). PulsePlus Flours.
- Diefenbaker Spice & Pulse (current). Special Crop Products: Chickpea Flour.
- Bob's Red Mill (current). Chickpea Flour.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the chickpea flour market in 2026 and what value is forecast for 2036?
- What food-development and purchasing conditions support chickpea flour demand?
- Why does Desi lead the Product Type category?
- Why do Food Chain Services lead the Distribution Channel category?
- How do growth rates differ across the profiled countries?
- Which companies currently document chickpea-flour products?
- What supply and formulation issues can slow adoption or supplier switching?
- What should buyers assess before converting an application trial into recurring purchasing?
Frequently Asked Questions
How big is the chickpea flour market in 2026 and what is forecast for 2036?
The chickpea flour market is valued at USD 5.3 Billion in 2026 and is forecast to reach USD 8.4 Billion by 2036. The market was valued at USD 5.0 Billion in 2025.
What is the chickpea flour market CAGR from 2026 to 2036?
The chickpea flour market is forecast to grow at 5.0% CAGR from 2026 to 2036.
Which Product Type leads the chickpea flour market?
Desi leads Product Type with 62.0% share in 2026. Long-established besan consumption provides a durable flour-specific demand base.
Which Distribution Channel leads the chickpea flour market?
Food Chain Services leads Distribution Channel with 30.0% share in 2026. Recurring menu preparation makes specification consistency important once a recipe has been approved.
Which profiled countries have the highest chickpea flour market growth rates?
Germany has the highest profiled CAGR at 7.0%, followed by the UK at 6.0% from 2026 to 2036.
Which companies are active in the chickpea flour market?
ADM, Ingredion Incorporated, AGT Food and Ingredients, Diefenbaker Spice & Pulse and Bob's Red Mill have directly documented chickpea-flour or pulse-flour product offerings.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Desi
- Kabuli
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Food Chain Services
- Modern Trade
- Convenience Store
- Other Distribution Channel
- Online Store
- Departmental Store
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ADM
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ingredion Incorporated
- AGT Food and Ingredients
- Diefenbaker Spice & Pulse
- Bob's Red Mill
- ADM
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


