
- Market Size (2026)
- USD 13.0 Bn
- Forecast (2036)
- USD 44.9 Bn
- CAGR (2026 to 2036)
- 13.2%
How Big Is the Plant-Based Meat Market in 2026?
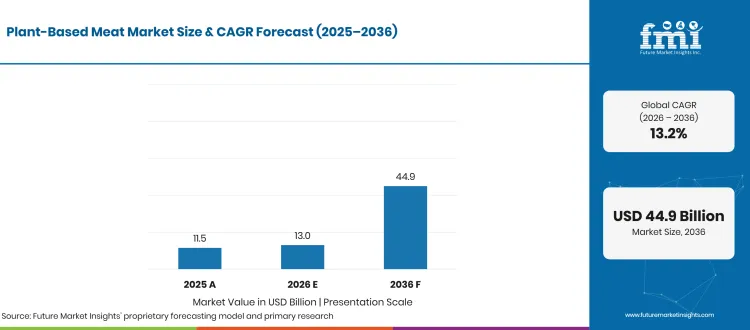
The global plant-based meat market is valued at USD 13.0 billion in 2026, up from USD 11.5 billion in 2025, and is projected by Future Market Insights (FMI) to reach USD 44.9 billion by 2036, expanding at a 13.2% CAGR to generate USD 31.9 billion in incremental revenue over the forecast decade.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 11.5 billion |
| 2026 Market Size (Estimated) | USD 13.0 billion |
| 2036 Market Size (Projected) | USD 44.9 billion |
| Compound Annual Growth Rate (2026 to 2036) | 13.2% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 31.9 billion |
| Dominant Source Protein Class (2026 Share) | Soy-Based Protein Concentrates (44.0% revenue share in 2026) |
| Leading Meat Substitute Format (2026 Share) | Plant-Based Burger Patties (42.5% revenue share in 2026) |
| Dominant Storage Condition & Channel (2026) | Frozen Plant-Based Formats (56.0% share) | Retail Supermarkets (58.0% share) |
| Leading Texturization Technology (2026 to 2036) | High-Moisture Twin-Screw Extrusion (51.5% in 2026, rising to 64.0% by 2036) |
| Largest Country Markets (2026 Global Share) | United States (32.3%), United Kingdom (10.8%), Germany (10.0%), Brazil (6.2%) |
| Fastest-Growing Country Markets (2026 to 2036) | United States (14.0% CAGR), Brazil (13.6% CAGR), United Kingdom (13.4% CAGR) |
| Leading Tier-1 Companies | Beyond Meat Inc., Impossible Foods Inc., Quorn Foods, Kellanova (Mars, Incorporated), JBS S.A. (Vivera & The Vegetarian Butcher Collective) |
Source: Future Market Insights analysis of the plant-based meat market, 2026.
Executive Market Overview
Demand for plant-based meat across grocery freezers and quick-service restaurant chains is transitioning from novelty trial toward repeat flexitarian purchasing within the broader plant-based food sector. Global retail tracking published by The Good Food Institute (April 2026) shows that retail sales of meat and seafood alternatives reached USD 6.6 billion in 2025 within a USD 28.9 billion total market aisle, as households seek healthier cholesterol-free meal options. Consumer demand remains strongest in North America and Western Europe, led by the United States, the United Kingdom, and Germany, while food manufacturers across Latin America and Asia scale non-GMO soy and pea extrusion lines to lower finished portion costs.
First-generation meat analogues faced consumer resistance over dry texture, sodium levels, and a 14.0% to 20.0% retail price premium against conventional ground meats. Manufacturers are overcoming these purchasing hurdles by co-extruding yellow pea isolates with fungal mycelium while sourcing high-purity inputs from the plant-based protein sector to close the parity gap. FMI projects pea-based protein isolates to advance at a 13.8% CAGR and plant-based chicken strips and whole-cut fillets at a 14.2% CAGR through 2036, supported by long-term supply agreements with contract co-packers. Market sizing covers structured plant-based and mycoprotein meat, poultry, and seafood analogues, while excluding traditional unflavored tofu, tempeh, insect proteins, and cell-cultivated meat.
Analyst Perspective
"Plant-based meat suppliers that replace methylcellulose and coconut fat with heart-healthy avocado or olive oil emulsions and high-moisture soy-pea-mycoprotein fibers will secure permanent supermarket and QSR contracts. The primary commercial risk is retail price elasticity, where any widening of the per-kilogram gap against beef or chicken immediately slows flexitarian basket turn."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights (FMI)
Major Market Trends and Insights
- Non-HFSS and Heart-Healthy Lipid Reformulations Restore Supermarket Repeat Velocity: Retail category managers in Europe and North America are resetting plant-based meat planograms around products that cut saturated fat and sodium while eliminating artificial binders. Quorn Foods (October 2026) documented in its Net Positive Report 2025-2026 that 95% of its mycoprotein portfolio meets UK non-HFSS standards and 99% qualifies as high in protein or fiber, while Impossible Foods Inc. (September 2026) entered UK retail supermarkets via a nationwide Tesco rollout featuring Burger Patties with 18 grams of protein and Smoky Chipotle Chicken Pieces with 21 grams of protein per 100 grams.
- M&A Consolidation Unites Pure-Play Brands with Multinational Distribution Scale: Corporate ownership across the plant-based meat aisle consolidated sharply between 2025 and 2026 as global food and meat groups combined brand equity with cold-chain scale. Unilever plc (March 2025) and Vivera (March 2025) executed the sale of The Vegetarian Butcher to JBS-owned Vivera to form The Vegetarian Butcher Collective, Mars, Incorporated (December 2025) received final European Commission approval to complete its USD 35.9 billion acquisition of Kellanova (MorningStar Farms), and the European Investment Bank (May 2025) signed a EUR 20.0 million financing loan with Heura Foods.
- High-Moisture Extrusion Optimization Enhances Whole-Muscle Fibrous Bite: Process engineers are replacing spongy low-moisture texturized vegetable protein (TVP) with wet twin-screw extrusion and long cooling dies that align globular plant proteins into anisotropic muscle fibers. Experimental extrusion studies in Gels (January 2026) and Foods (March 2026 and September 2026) demonstrate that running 30% isolated pea protein with soy protein at 55% moisture, 160°C barrel temperature, and 250 rpm screw speed maximizes longitudinal cutting strength, water-holding capacity, and freeze-thaw structural integrity.
What Are the Main Drivers, Restraints, and Opportunities?
Cardiometabolic health guidelines, supermarket private-brand expansion, and high-moisture extrusion efficiency propel sales of plant-based meat, whereas retail price premiums over animal meat and ultra-processed label scrutiny restrain turnover, leaving fermented mycoprotein whole cuts and institutional catering as key margin catalysts.
Driver: Cardiometabolic Dietary Shifts, Public Biotech Investment, and Private-Label Scale
Flexitarian households seeking cholesterol-free protein and lower saturated fat intake continue to anchor weekly grocery orders across commercial meat substitutes. Policy and infrastructure data from The Good Food Institute (May 2026) highlight a USD 51.0 million federal investment in the Illinois Fermentation and Agriculture Biomanufacturing Tech Hub alongside USD 881.0 million in 2025 alternative protein capital deployment. At the retail shelf, survey findings published by the Food Industry Association (July 2026) confirm that 60% of Generation Z shoppers and 61% of Millennials plan to keep purchasing supermarket private brands, accelerating grocer-branded meat-free assortment expansions.
Restraint: Retail Price Premiums Over Animal Meat and Ultra-Processed Ingredient Scrutiny
A 14.0% to 20.0% retail price gap per kilogram against conventional ground beef in 2026, paired with shopper skepticism toward ultra-processed hydrocolloid binders, restrains repeat volume during periods of food inflation. Clinical nutrition reviews in Frontiers in Nutrition (June 2026) note that plant-based convenience items face scrutiny when formulated with elevated sodium, driving formulators to integrate natural clean label ingredients. Those volume headwinds were reflected when Beyond Meat Inc. (March 2026 and November 2026) reported 2025 full-year net revenue of USD 246.0 million while executing factory consolidation to lower operational overhead.
Opportunity: Biomass-Fermented Whole Cuts, Clean-Label Emulsions, and Institutional Catering
Combining wet-extruded soy and pea fibers with Fusarium venenatum mycoprotein and cold-pressed emulsions generates higher-margin whole-cut steaks and chicken fillets for institutional foodservice. In Europe, the European Food Safety Authority (October 2026) expanded its Novel Food SME pre-submission advice program, while the European Investment Bank (November 2025) backed Heura Foods with EUR 20.0 million to commercialize clean-label legume meat alternatives across European grocery chains. Continuous pilot extrusion trials show that fungal mycelium creates anisotropic fibrous bundles that replicate mammalian muscle architecture without requiring chemical cross-linking agents.
How Is the Plant-Based Meat Market Segmented?
The global plant-based meat market is segmented by source protein class, meat substitute format, storage condition, distribution channel, texturization technology, and region, measured on a finished wet-weight tonnage and manufacturer revenue basis.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Main Growth Benchmark (2026 to 2036) |
|---|---|---|---|
| Source Protein Class | Soy-Based Protein Concentrates, Pea-Based Protein Isolates, Wheat Gluten and Seitan, Mycoprotein and Novel Pulses | Soy-Based Protein Concentrates (44.0% revenue share) | Pea-Based Protein Isolates (13.8% CAGR) and Mycoprotein gain share in soy-free SKUs |
| Meat Substitute Format | Plant-Based Burger Patties, Plant-Based Chicken Strips, Plant-Based Pork Sausages, Plant-Based Seafood Fillets | Plant-Based Burger Patties (42.5% revenue share) | Plant-Based Chicken Strips (14.2% CAGR) and Whole-Cut Fillets record fastest gains |
| Storage Condition | Frozen Plant-Based Formats, Refrigerated Chilled Formats, Modified-Atmosphere Deli Packs, Shelf-Stable Dehydrated Crumbles, Ambient Retort Meal Kits | Frozen Plant-Based Formats (56.0% revenue share) | Frozen doors minimize spoilage shrink; Shelf-Stable Crumbles grow in foodservice |
| Distribution Channel | Retail Supermarkets, Foodservice QSRs and Catering, Direct-to-Consumer E-Commerce, Specialty Vegan Grocers | Retail Supermarkets (58.0% sales share) | Foodservice QSRs and Institutional Catering expand via price-parity tenders |
| Texturization Technology | High-Moisture Twin-Screw Extrusion, Low-Moisture Dry Extrusion, Biomass Mycelium Fermentation, Shear-Cell Fiber Spinning | High-Moisture Twin-Screw Extrusion (51.5% share) | High-Moisture Twin-Screw Extrusion share rises from 51.5% in 2026 to 64.0% by 2036 |
| Region | North America, Western Europe, Latin America, East Asia, South Asia & Pacific, Eastern Europe, Middle East & Africa | North America & Western Europe (US at 32.3%, UK at 10.8%) | United States (14.0% CAGR) and Brazil (13.6% CAGR) lead national expansion |
Source: Future Market Insights analysis of the plant-based meat market, 2026.
Why Do Soy-Based Protein Concentrates Lead the Source Protein Class Segment?
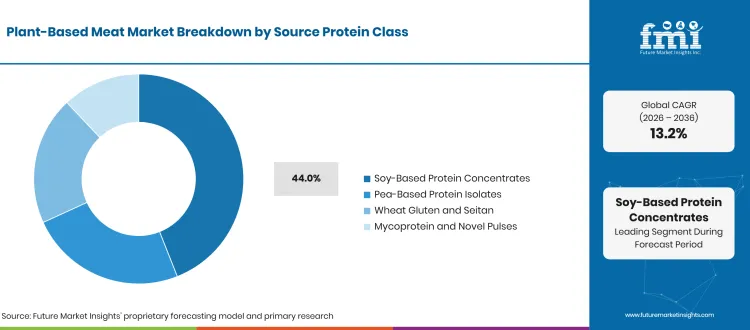
Soy-based protein concentrates lead the global market by source protein class, capturing 44.0% of revenue in 2026 as the primary texturization base for commercial meat analogues. Global food processors favor functional soy concentrates alongside refined soy protein isolate fractions for their complete PDCAAS 1.0 amino-acid score, water-binding capacity, and reliable thermomechanical gelling during extrusion. Extrusion research published in Foods (July 2025) confirms that supplementing soy matrices with 20% whole yeast powder densifies fibrous alignment, while Gels (February 2026) demonstrates how pea-based protein isolates (projected by FMI to expand at a 13.8% CAGR) and mycoprotein gain share in soy-free SKUs as Nestlé S.A. (February 2026) expands regenerative European soy and pea sourcing for its Garden Gourmet portfolio.
What Sustains Plant-Based Burger Patties Leadership by Meat Substitute Format?
Plant-based burger patties account for 42.5% of meat substitute format revenue in 2026, anchored by 1:1 menu replacement on restaurant grills without altering bun or condiment builds. Comminuted patties are technically simpler to extrude and bind than whole-muscle cuts, competing for grill space with premium plant-based beef formulations. Commercial momentum strengthened when Impossible Foods Inc. (September 2026) partnered with Tesco in the United Kingdom to roll out frozen retail burger patties and chicken pieces, while Quorn Foods (October 2026) confirmed 95% non-HFSS compliance across its burger and mince formats and FMI projects plant-based chicken strips to expand fastest at a 14.2% CAGR through 2036.
How Do Frozen Plant-Based Formats Retain the Majority of Storage Condition Demand?
Frozen plant-based formats command 56.0% of storage revenue in 2026, as blast-freezing extruded patties and plant-based chicken tenders extends shelf life to 12 months and eliminates markdown spoilage shrink. Supermarket category buyers consolidate inventory in multi-door freezer aisles so weekly flexitarian demand swings never result in discarded packs. Process engineering studies in Foods (September 2026) verify that optimizing long cooling-die temperature gradients between 140°C and 160°C during wet extrusion prevents ice-crystal damage during frozen storage, while Conagra Brands Inc. (September 2026) posted an 11.5% operating margin across its Gardein frozen portfolio.
Why Do Retail Supermarkets Command the Distribution Channel Category?
Retail supermarkets generate 58.0% of global plant-based meat sales in 2026, reflecting the dominance of at-home family meal preparation. Large grocery chains drive category volume through dedicated freezer doors, promotional end-caps, and private-label price-parity lines that source bulk pea protein to keep retail costs affordable. Shopper survey data from the Food Industry Association (July 2026) show that 94% of grocery shoppers intend to keep buying retailer private brands, reinforcing retail store-brand assortments alongside Impossible Foods Inc. (September 2026) branded rollouts across mass European and North American grocery stores.
What Drives High-Moisture Twin-Screw Extrusion Leadership in Texturization Technology?
High-moisture twin-screw extrusion holds 51.5% of texturization technology demand in 2026 and is projected by FMI to reach 64.0% by 2036. Processing protein slurries at 50% to 70% moisture creates aligned fibers in a single continuous pass, offering substantial sensory advantages over conventional dry textured vegetable protein that requires separate rehydration. Research in Gels (January 2026) and Foods (March 2026) confirms optimal fiber anisotropy at 55% moisture and 160°C, while Quorn Foods (October 2026) reduced fermentation electricity use per ton by 16% across its commercial protein facilities.
Plant-Based Meat Market by Region and Country (2026 to 2036)
North America and Western Europe anchor global plant-based meat revenue through 2036, while Latin America scales rapidly on vertically integrated soybean crushing and refrigerated meatpacker logistics. FMI projections show that the eight core countries in Table 3 account for 76.2% of global revenue in 2026 (USD 9.9 billion) and expand to 77.7% by 2036 (USD 34.9 billion), capturing USD 25.0 billion of the market's USD 31.9 billion 10-year gain. The United States alone represents 32.3% of global sales in 2026 (USD 4.2 billion) and contributes USD 11.4 billion in incremental revenue through 2036, while the four Western European leaders (United Kingdom, Germany, France, and Spain) expand from USD 3.9 billion in 2026 to USD 13.1 billion by 2036.
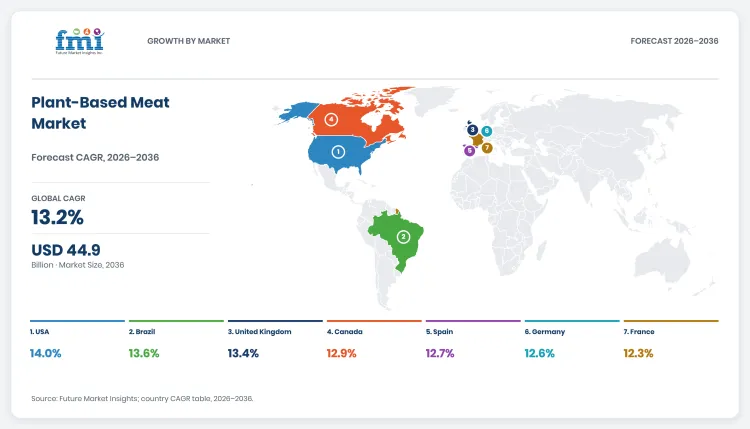
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 to 2036) |
|---|---|---|---|---|---|
| United States | USD 4.2 billion | USD 15.6 billion | +USD 11.4 billion | 14.0% | 32.3% to 34.7% |
| United Kingdom | USD 1.4 billion | USD 4.9 billion | +USD 3.5 billion | 13.4% | 10.8% to 10.9% |
| Germany | USD 1.3 billion | USD 4.3 billion | +USD 3.0 billion | 12.6% | 10.0% to 9.6% |
| Brazil | USD 0.8 billion | USD 2.9 billion | +USD 2.1 billion | 13.6% | 6.2% to 6.5% |
| France | USD 0.7 billion | USD 2.2 billion | +USD 1.5 billion | 12.3% | 5.4% to 4.9% |
| Canada | USD 0.6 billion | USD 2.0 billion | +USD 1.4 billion | 12.9% | 4.6% to 4.5% |
| Spain | USD 0.5 billion | USD 1.7 billion | +USD 1.2 billion | 12.7% | 3.8% to 3.8% |
| Italy | USD 0.4 billion | USD 1.3 billion | +USD 0.9 billion | 12.1% | 3.1% to 2.9% |
Source: Future Market Insights analysis of the plant-based meat market, 2026.
United States
The United States is both the world's largest plant-based meat market and the fastest-growing tracked nation at a 14.0% CAGR, rising from USD 4.2 billion in 2026 to USD 15.6 billion by 2036, adding USD 11.4 billion and lifting its global share from 32.3% to 34.7%. Commercial foodservice contracts across fast-casual chains, university dining, healthcare cafeterias, and Midwest co-extrusion hubs generate substantial procurement volume alongside retail grocery aisles. Regulatory clarity from the U.S. Food and Drug Administration (January 2025) on plant-based labeling and clean-label oil reformulations by Beyond Meat Inc. (November 2026) are stabilizing buyer repeat rates across major metropolitan supermarket chains. FMI analysis indicates that expanded institutional procurement and co-packing scale will anchor steady flexitarian adoption, lifting long-term supermarket turnover and driving strong commercial expansion through 2036.
United Kingdom
In the United Kingdom, demand for plant-based meat is forecast to expand at a 13.4% CAGR from USD 1.4 billion in 2026 to USD 4.9 billion by 2036, generating USD 3.5 billion in incremental sales while lifting its global share from 10.8% to 10.9%. British demand stands apart because consumers treat fermented mycoprotein pieces, meat-free sausages, and chilled supermarket private-label ranges as routine weeknight center-of-plate staples. Industry reporting from the USDA Foreign Agricultural Service (March 2026) highlights strict non-HFSS nutritional reformulation across UK grocers, reinforced by Quorn Foods (October 2026) achieving 95% non-HFSS portfolio compliance across regional distribution networks. FMI expects high retail compliance and store-brand proliferation to sustain household penetration, supporting durable private-label volume growth and steady grocery sales over the forecast period.
Germany
The plant-based meat industry in Germany is projected to expand at a 12.6% CAGR from USD 1.3 billion in 2026 to USD 4.3 billion by 2036, adding USD 3.0 billion as its global share moves from 10.0% to 9.6%. German market mechanics are defined by major supermarket and hard-discount chains pricing private-label vegan bratwurst, schnitzels, and cold cuts at or below conventional meat prices. According to the USDA Foreign Agricultural Service (March 2026), Germany is the European Union's largest processed food market, where retailers actively expand plant-forward assortments to satisfy health-conscious urban shoppers. FMI projects that price parity against conventional livestock cuts will remain the decisive commercial catalyst, unlocking high-volume recurring purchases and expanding discounter aisle share through 2036.
Brazil
Sales of plant-based meat across Brazil are projected to climb at a 13.6% CAGR between 2026 and 2036, rising from USD 0.8 billion in 2026 to USD 2.9 billion by 2036, adding USD 2.1 billion and lifting national share from 6.2% to 6.5%. Brazil differs fundamentally from Western import-reliant markets because domestic protein giants operate vertically integrated non-GMO soybean crushing, high-moisture extrusion, and nationwide refrigerated delivery fleets that price plant-based burgers competitively. Processing trade data from the USDA Foreign Agricultural Service (March 2026) confirm that Brazilian food manufacturing rose 8.0% in 2025, reflecting expanding domestic cold-chain logistics. With domestic primary processing providing a structural cost advantage, Brazilian producers are projected to accelerate middle-class flexitarian adoption and expand regional Latin American export shipments through 2036.
France
French plant-based meat revenue is projected to rise from USD 0.7 billion in 2026 to USD 2.2 billion by 2036 at a 12.3% CAGR, adding USD 1.5 billion over the forecast period while its global share moderates from 5.4% to 4.9%. Commercial growth in France centers on domestically cultivated yellow pea, wheat, and fava bean formulations designed to earn Nutri-Score A and B ratings across hypermarkets and institutional school canteens. Processing audits from the USDA Foreign Agricultural Service (April 2026) document French food manufacturers prioritizing domestic agricultural provenance and clean-label ingredient profiles. FMI believes this focus on nutritional scores and verified regional crop origin will sustain steady, high-margin culinary adoption across municipal catering and retail gourmet channels through 2036.
Canada
In Canada, plant-based meat sales are forecast to grow at a 12.9% CAGR from USD 0.6 billion in 2026 to USD 2.0 billion by 2036, generating USD 1.4 billion in 10-year incremental revenue as its global share adjusts from 4.6% to 4.5%. Canada leverages extensive domestic yellow field pea fractionation facilities across Saskatchewan and Manitoba alongside mandatory front-of-package sodium labeling that took effect in January 2026. Processing trade monitoring from the USDA Foreign Agricultural Service (August 2026) confirms robust domestic processing investment, supported by Maple Leaf Foods Inc. (November 2026) scaling fortified protein lines. FMI projects these localized processing hubs and regulatory quality standards to secure steady co-manufacturing capacity, sustaining domestic grocery adoption and expanding export flows through 2036.
Spain
Procurement of plant-based meat in Spain is projected to expand at a 12.7% CAGR from USD 0.5 billion in 2026 to USD 1.7 billion by 2036, adding USD 1.2 billion and maintaining a 3.8% to 3.8% share of global revenue across the decade. Spanish growth concentrates heavily in ready-to-cook tapas, plant-based croquettes, and Iberian ham alternatives tailored for Madrid and Barcelona retail grocers. Trade data from the USDA Foreign Agricultural Service (March 2026) confirm expanding retail distribution for value-added protein substitutes across southern European supermarket chains. Heura Foods (May 2025) expanded domestic supermarket distribution with pea-protein pork alternatives while major meat processors convert surplus sausage-casing lines to vegetarian formats, supporting continuous volume additions through 2036.
Italy
In Italy, commercial sales of plant-based meat are expected to rise at a 12.1% CAGR from USD 0.4 billion in 2026 to USD 1.3 billion by 2036, contributing USD 0.9 billion in incremental sales while national share shifts from 3.1% to 2.9%. Italian sales require stringent adherence to traditional culinary profiles, leading processors to formulate allergen-free pea and fava bean cutlets, bolognese-style minced proteins, and filled ravioli. Agricultural trade monitoring by the USDA Foreign Agricultural Service (April 2026) documents strong growth in certified Italian plant-forward food processing lines across northern industrial clusters. Domestic producers integrate non-GMO Italian soy and pulse proteins to satisfy foodservice chefs, driving high-value restaurant adoption and expanding metropolitan dining sales through 2036.
Competitive Environment and Notable Companies
Notable companies operating in the global plant-based meat market include Beyond Meat Inc., Impossible Foods Inc., Quorn Foods (Monde Nissin Corporation), Kellanova (Mars, Incorporated), Nestlé S.A., Conagra Brands Inc., JBS S.A. (Vivera & The Vegetarian Butcher Collective), Maple Leaf Foods Inc. (Greenleaf Foods), Tyson Foods Inc., and Heura Foods. Industry competition spans three operational models: dedicated plant-based and mycoprotein technology pioneers, multinational consumer packaged goods (CPG) brand owners, and vertically integrated meatpackers utilizing chilled and frozen protein distribution fleets.
How Are Companies Positioned in the Plant-Based Meat Market?
Pure-play innovators Beyond Meat Inc. (November 2026), Impossible Foods Inc. (September 2026), Quorn Foods (October 2026), and Heura Foods (May 2025) lead proprietary formulation in high-moisture extrusion, mycoprotein air-lift fermentation, and olive- or avocado-oil lipid structuring. Multinational CPG groups Kellanova (acquired by Mars, Incorporated in December 2025), Nestlé S.A. (February 2026), and Conagra Brands Inc. (September 2026) dominate supermarket freezer doors via MorningStar Farms, Garden Gourmet, and Gardein, while JBS S.A. (via Vivera, which acquired The Vegetarian Butcher from Unilever plc in March 2025), Maple Leaf Foods Inc. (November 2026), and Tyson Foods Inc. leverage integrated meat logistics.
What Matters When a Buyer Selects a Plant-Based Meat Supplier?
Supermarket meat-department buyers and QSR culinary directors evaluate suppliers on cook-from-frozen flat-top grill sear, holding-cabinet juiciness retention, and compliance with UK non-HFSS (Quorn Foods, October 2026), European Nutri-Score A/B, or U.S. Food and Drug Administration (January 2025) labeling and allergen guidelines. Equally critical is co-extrusion scale capable of narrowing the 14.0% to 20.0% retail price premium toward parity with conventional ground beef and poultry (The Good Food Institute, April 2026).
Which Capabilities Distinguish Product Offers?
Leading portfolios diverge across lipid chemistry, protein texturization, and fungal biomass efficiency: Beyond Meat Inc. formulates avocado-oil burger patties and launched Beyond Immerse plant protein drinks in October 2026; Impossible Foods Inc. (September 2026) engineers high-protein burger patties (18 g protein) and chicken pieces (21 g protein per 100 g) for UK retail; Quorn Foods (October 2026) ferments Fusarium venenatum mycoprotein with 95% non-HFSS compliance; and Heura Foods (May 2025) structures olive-oil Mediterranean whole cuts and sausages.
How Does Geographic Reach Affect Competition?
While Beyond Meat Inc., Impossible Foods Inc., Kellanova (Mars, Incorporated), Conagra Brands Inc., and Maple Leaf Foods Inc. anchor North American grocery freezers, European shelf leadership belongs to Quorn Foods, Nestlé S.A. (Garden Gourmet), Heura Foods, and JBS S.A. after JBS-owned Vivera (March 2025) united with The Vegetarian Butcher across Europe alongside JBS's Seara Incrível network in Brazil.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 20 March 2025: Vivera (a subsidiary of JBS S.A.) and Unilever plc announced a binding offer for Vivera to acquire The Vegetarian Butcher, forming The Vegetarian Butcher Collective (Unilever plc & Vivera, March 2025). | Consolidates two of Europe's largest chilled and QSR plant-based meat brands under JBS's global protein supply chain. | Benchmark pan-European chilled and QSR tender volumes across combined Vivera and Vegetarian Butcher lines. |
| 12 May 2025: The European Investment Bank signed a EUR 20.0 million loan with Heura Foods in Barcelona to finance clean-label plant-based meat R&D and commercialization (European Investment Bank, May 2025). | Accelerates olive-oil and legume-based whole-cut and sausage replacements free of artificial additives. | Expand Mediterranean clean-label and Nutri-Score A/B plant-based SKUs in European grocery aisles. |
| 8 December 2025: Mars, Incorporated received unconditional European Commission approval and completed its USD 35.9 billion acquisition of Kellanova, owner of MorningStar Farms (Mars, Incorporated, December 2025). | Integrates North America's leading frozen meat-free brand into Mars's global snacking and retail distribution network. | Leverage multi-category promotional bundles across frozen breakfast sausage, burger, and strip doors. |
| 23 September 2026 & 20 October 2026: Impossible Foods Inc. launched four frozen SKUs at UK Tesco stores, while Quorn Foods reported 95% non-HFSS compliance in its Net Positive Report 2025-2026 (Impossible Foods Inc., September 2026; Quorn Foods, October 2026). | Intensifies branded and mycoprotein competition in UK and European supermarket freezer and chilled aisles. | Prioritize high-protein, non-HFSS compliant patties and chicken pieces for mainstream family dinner slots. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Beyond Meat Inc. | Global pure-play plant-based meat pioneer producing Beyond Burger, Beyond Beef, Beyond Sausage, and Beyond Steak | Reported FY 2025 net revenue of USD 246.0 million in March 2026 and Q3 2026 financial results on 5 November 2026 (Beyond Meat Inc., March & November 2026). |
| Impossible Foods Inc. | Foodtech leader manufacturing Impossible Burger Patties, Beef, Chicken Nuggets, Chicken Pieces, and Pork | Entered UK supermarkets via a nationwide Tesco rollout of four frozen products on 23 September 2026 (Impossible Foods Inc., September 2026). |
| Quorn Foods (Monde Nissin Corporation) | Global pioneer in biomass-fermented Fusarium venenatum mycoprotein mince, pieces, nuggets, and fillets | Published its Net Positive Report 2025-2026 on 20 October 2026 confirming 95% non-HFSS compliance and 99% high-protein/fiber SKUs (Quorn Foods, October 2026). |
| Kellanova (Mars, Incorporated) | North American retail freezer leader marketing MorningStar Farms and Incogmeato patties, links, and strips | Acquired by Mars, Incorporated in a USD 35.9 billion transaction cleared by the European Commission in December 2025 (Mars, Incorporated, December 2025). |
| JBS S.A. (Vivera & The Vegetarian Butcher Collective) | Global protein producer operating Vivera and The Vegetarian Butcher in Europe and Seara Incrível in Brazil | JBS-owned Vivera agreed to acquire The Vegetarian Butcher from Unilever plc on 20 March 2025 to form The Vegetarian Butcher Collective (Unilever plc & Vivera, March 2025). |
| Nestlé S.A. | Global food group marketing Garden Gourmet plant-based burgers, grounds, fillets, and chicken pieces across Europe and HRI | Published its 2025 Non-Financial Statement in February 2026 detailing regenerative agriculture pea, wheat, and soy sourcing (Nestlé S.A., February 2026). |
| Conagra Brands Inc. | North American frozen food leader marketing Gardein Ultimate Plant-Based chicken, beef, pork, and seafood | Reported Q1 fiscal 2027 net sales of USD 2,632.6 million and 11.5% adjusted operating margin on 30 September 2026 (Conagra Brands Inc., September 2026). |
| Maple Leaf Foods Inc. (Greenleaf Foods) | Canadian protein group operating Lightlife and Field Roast chilled and frozen plant-based meats | Reported Q3 2026 sales of CAD 1,035.0 million and Adjusted EBITDA of CAD 129.0 million (12.5% margin) on 4 November 2026 (Maple Leaf Foods Inc., November 2026). |
| Heura Foods | European clean-label Mediterranean plant-based chicken, burger, and chorizo innovator using olive-oil emulsions | Secured a EUR 20.0 million financing loan from the European Investment Bank on 12 May 2025 to scale clean-label R&D (European Investment Bank, May 2025). |
| Tyson Foods Inc. | Multinational protein processor supplying plant-based nuggets, tenders, and blended protein bites for retail and foodservice | Utilizes North American and international cold-chain logistics and co-extrusion scale to serve mass grocery and QSR channels (Tyson Foods Inc., 2026). |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Plant-Based Meat Market Report Scope and Research Methodology
FMI sizes the global plant-based meat market by reconciling finished wet-weight extruded and mycoprotein shipment volumes (1.62 million to 1.80 million metric tons in 2026) and dry protein isolate input demand (565.0 thousand to 630.0 thousand metric tons) against retail scanner registries and commercial foodservice distributor invoices across each country. Retail grocery sales and foodservice QSR, university, healthcare, and hospitality volumes are standardized to finished wet-weight kilograms at manufacturer realization prices (USD 7.2 to USD 8.0 per kilogram in 2026). Country revenue is counted where the product is purchased and consumed, with segment and national totals summing to the global total every year. Corporate filings and institutional reports verify product launches, nutritional compliance, and M&A ownership.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Commercial retail and foodservice manufacturer revenue from structured plant-based and fungal mycoprotein meat, poultry, pork, and seafood analogues. |
| Source protein classes | Soy-Based Protein Concentrates, Pea-Based Protein Isolates, Wheat Gluten and Seitan, and Mycoprotein and Novel Pulses. |
| Meat substitute formats | Plant-Based Burger Patties, Plant-Based Chicken Strips, Plant-Based Pork Sausages, and Plant-Based Seafood Fillets. |
| Storage conditions | Frozen Plant-Based Formats, Refrigerated Chilled Formats, Modified-Atmosphere Deli Packs, Shelf-Stable Dehydrated Crumbles, and Ambient Retort Meal Kits. |
| Texturization technologies | High-Moisture Twin-Screw Extrusion, Low-Moisture Dry Extrusion, Biomass Mycelium Fermentation, and Shear-Cell Fiber Spinning. |
| Packaging formats | Frozen retail cartons and polybags, modified-atmosphere thermoformed trays, vacuum-sealed whole cuts, and bulk foodservice cases. |
| Distribution channels | Retail Supermarkets, Foodservice QSRs and Catering, Direct-to-Consumer E-Commerce, and Specialty Vegan Grocers. |
| End users | Flexitarian, vegetarian, and vegan households, quick-service restaurants (QSRs), institutional school and hospital catering, and HRI operators. |
| Exclusions | Traditional unflavored tofu, tempeh, whole canned beans and lentils, raw bulk commodity soy meal, insect proteins, and cell-cultivated animal meat. |
| Quantitative units | USD billion for value; million metric tons for finished wet-weight volume. |
| Volume basis | Metric tons of finished hydrated meat, poultry, pork, and seafood analogues (50% to 68% moisture basis). |
| Value basis | Manufacturer wholesale revenue from retail and foodservice sales counted in the country of consumption. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| National coverage | United States, United Kingdom, Germany, Brazil, France, Canada, Spain, and Italy. |
| Companies covered | Beyond Meat Inc., Impossible Foods Inc., Quorn Foods (Monde Nissin Corporation), Kellanova (Mars, Incorporated), JBS S.A. (Vivera & The Vegetarian Butcher Collective), Nestlé S.A., Conagra Brands Inc., Maple Leaf Foods Inc. (Greenleaf Foods), Heura Foods, and Tyson Foods Inc. |
Source: Future Market Insights analysis of the plant-based meat market, 2026.
Research Sources and Bibliography
- Beyond Meat Inc. (2026, March 31). Beyond Meat Reports Fourth Quarter and Full Year 2025 Financial Results. https://investors.beyondmeat.com/news-releases/news-release-details/beyond-meatr-reports-fourth-quarter-and-full-year-2025-financial
- Beyond Meat Inc. (2026, August 5). Beyond Meat Reports Second Quarter 2026 Financial Results. https://investors.beyondmeat.com/news-releases/news-release-details/beyond-meatr-reports-second-quarter-2026-financial-results-0
- Beyond Meat Inc. (2026, November 5). Beyond Meat Reports Third Quarter 2026 Financial Results. https://investors.beyondmeat.com/news-releases/news-release-details/beyond-meatr-reports-third-quarter-2026-financial-results
- Conagra Brands Inc. (2026, September 30). Conagra Brands Reports First Quarter Fiscal 2027 Results. https://www.conagrabrands.com/news-room/news-conagra-brands-reports-first-quarter-results-prn-122968
- European Food Safety Authority. (2026, September 22). SME support services and Novel Food pre-submission advice. https://www.efsa.europa.eu/en/applications/about/services/sme
- European Food Safety Authority. (2026, October 21). Novel food scientific assessments and regulatory framework. https://www.efsa.europa.eu/en/topics/topic/novel-food
- European Investment Bank. (2025, May 12). Spain: EIB provides Heura Foods with EUR 20 million in financing to develop innovative and sustainable plant-based food products. https://www.eib.org/en/press/all/2025-204-eib-finances-with-eur20-million-heura-foods-to-develop-innovative-and-sustainable-plant-based-food-products
- European Investment Bank. (2025, November 6). Swedish and Spanish companies help drive Europe's plant-based food innovation. https://www.eib.org/en/stories/food-innovation-legumes
- Food Industry Association. (2026, July 9). Are Younger Shoppers Driving the Next Wave of Growth in Private Brands? Power of Private Brands 2026. https://www.fmi.org/blog/view/fmi-blog/2026/07/09/are-younger-shoppers-driving-the-next-wave-of-growth-in-private-brands
- Foods. (2025, July 15). Development of Soy-Based Meat Analogues via Wet Twin-Screw Extrusion with Whole Yeast Powder and Soy Protein Isolate, 14(14), 2479. https://www.mdpi.com/2304-8158/14/14/2479
- Foods. (2026, March 1). Structural, Textural, and Functional Properties of Plant-Based Meat Analogues Produced via High-Moisture Extrusion, 15(5), 824. https://www.mdpi.com/2304-8158/15/5/824
- Foods. (2026, September 23). High-Moisture Extrusion of Plant-Based Meat Analogues: Cooling-Die Mechanisms and Frozen Stability, 15(19), 3388. https://www.mdpi.com/2304-8158/15/19/3388
- Frontiers in Nutrition. (2026, June 11). Ultra-processed food consumption across early life, Mediterranean diet, and plant-based dietary patterns, 13, 1806903. https://www.frontiersin.org/journals/nutrition/articles/10.3389/fnut.2026.1806903/full
- Gels. (2026, January 1). Effects of Formulation and Extrusion Conditions for Isolated Pea Protein-Based High-Moisture Meat Analogs: Insights into Gelation and Structural Development, 12(1), 42. https://www.mdpi.com/2310-2861/12/1/42
- Gels. (2026, February 16). Effects of Isolated Pea Protein on Extrusion-Induced Gelation and Gel-like Network Formation in Low-Moisture Meat Analog Systems, 12(2), 175. https://www.mdpi.com/2310-2861/12/2/175
- Impossible Foods Inc. (2026, September 23). Impossible Foods Teams Up with Tesco for Long-Anticipated Entry into U.K. Supermarkets, Launches Four All-New Products. https://impossiblefoods.com/en-gb/media/impossible-foods-launches-in-uk-supermarkets-with-tesco
- Maple Leaf Foods Inc. (2026, November 4). Maple Leaf Foods Reports Third Quarter 2026 Financial Results. https://www.mapleleaffoods.com/news/maple-leaf-foods-reports-third-quarter-2026-financial-results/
- Mars, Incorporated. (2025, December 8). Mars Receives Final Regulatory Approval and Moves to Close Acquisition of Kellanova. https://www.mars.com/news-and-stories/press-releases-statements/mars-final-regulatory-approval-kellanova-acquisition
- Nestlé S.A. (2026, February 19). Non-Financial Statement 2025: Regenerative Agriculture and Sustainable Ingredient Sourcing. https://www.nestle.com/sites/default/files/2026-02/non-financial-statement-2025.pdf
- Quorn Foods. (2026, October 20). Quorn Net Positive Report 2025-2026: Making healthier food the norm with 95% non-HFSS portfolio. https://www.quorn.co.uk/news/quorn-net-positive-report-2026-out-now
- The Good Food Institute. (2026, April 20). 2026 State of the Industry Report: Plant-Based Meat, Seafood, Eggs, Dairy, and Ingredients. https://gfi.org/wp-content/uploads/2026/04/GFI_State-of-the-Industry-report-Plant-based-meat-seafood-eggs-dairy-and-ingredients.pdf
- The Good Food Institute. (2026, May 20). The future of food is being decided now: Inside GFI's work to fund science and shape the bioeconomy. https://gfi.org/blog/the-future-of-food-is-being-decided-now/
- Unilever plc. (2025, March 20). Unilever to sell The Vegetarian Butcher to Vivera. https://www.unilever.com/news/press-and-media/press-releases/2025/unilever-to-sell-the-vegetarian-butcher-to-vivera/
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, March 24). United Kingdom: Food Processing Ingredients Annual (GAIN Report No. UK2026-0008). https://www.fas.usda.gov/data/gain/2026/03/united-kingdom-food-processing-ingredients-annual
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, March 30). Germany: Food Processing Ingredients Annual (GAIN Report No. GM2026-0007). https://www.fas.usda.gov/data/gain/2026/03/germany-food-processing-ingredients-annual
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, March 31). Brazil: Food Processing Ingredients Annual (GAIN Report No. BR2026-0011). https://www.fas.usda.gov/data/gain/2026/03/brazil-food-processing-ingredients-annual
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, March 31). Spain: Food Processing Ingredients Annual (GAIN Report No. SP2026-0003). https://www.fas.usda.gov/data/gain-report/2026/03/Food%20Processing%20Ingredients%20Annual_Madrid_Spain_SP2026-0003.pdf
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, April 2). Italy: Food Processing Ingredients Annual (GAIN Report No. IT2026-0001). https://www.fas.usda.gov/data/gain/2026/04/italy-food-processing-ingredients-annual
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, April 3). France: Food Processing Ingredients Annual (GAIN Report No. FR2026-0003). https://www.fas.usda.gov/data/gain/2026/04/france-food-processing-ingredients-annual
- U.S. Department of Agriculture, Foreign Agricultural Service. (2026, August 27). Canada: Food Processing Ingredients Annual (GAIN Report No. CA2026-0022). https://www.fas.usda.gov/data/gain/2026/08/canada-food-processing-ingredients-annual
- U.S. Food and Drug Administration. (2025, January 6). FDA Releases Allergen, Food Safety, and Plant-Based Alternative Labeling Guidances. https://www.fda.gov/food/hfp-constituent-updates/fda-releases-allergen-food-safety-and-plant-based-alternative-labeling-guidances
- Vivera. (2025, March 20). The Vegetarian Butcher joins forces with Vivera. https://vivera.com/newsarticles/vivera-lanceert-de-plantaardige-signature-burger/
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source Protein Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Protein Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Protein Class, 2026 to 2036
- Soy-Based Protein Concentrates
- Pea-Based Protein Isolates
- Wheat Gluten and Seitan
- Mycoprotein and Novel Pulses
- Y-o-Y Growth Trend Analysis By Source Protein Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Protein Class, 2026 to 2036
- Global Market Analysis and Forecast, By Meat Substitute Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Meat Substitute Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Meat Substitute Format, 2026 to 2036
- Plant-Based Burger Patties
- Plant-Based Chicken Strips
- Plant-Based Pork Sausages
- Plant-Based Seafood Fillets
- Y-o-Y Growth Trend Analysis By Meat Substitute Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Meat Substitute Format, 2026 to 2036
- Global Market Analysis and Forecast, By Storage Condition, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Storage Condition, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Storage Condition, 2026 to 2036
- Frozen Plant-Based Formats
- Refrigerated Chilled Formats
- Modified-Atmosphere Deli Packs
- Shelf-Stable Dehydrated Crumbles
- Ambient Retort Meal Kits
- Y-o-Y Growth Trend Analysis By Storage Condition, 2021 to 2025
- Absolute $ Opportunity Analysis By Storage Condition, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail Supermarkets
- Foodservice QSRs and Catering
- Direct-to-Consumer E-Commerce
- Specialty Vegan Grocers
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Texturization Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Texturization Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Texturization Technology, 2026 to 2036
- High-Moisture Twin-Screw Extrusion
- Low-Moisture Dry Extrusion
- Biomass Mycelium Fermentation
- Shear-Cell Fiber Spinning
- Y-o-Y Growth Trend Analysis By Texturization Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Texturization Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- Latin America
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source Protein Class
- By Meat Substitute Format
- By Storage Condition
- By Distribution Channel
- By Texturization Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Beyond Meat Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Impossible Foods Inc.
- Quorn Foods (Monde Nissin Corporation)
- Kellanova (Mars, Incorporated)
- JBS S.A. (Vivera & The Vegetarian Butcher Collective)
- Nestlé S.A.
- Conagra Brands Inc.
- Maple Leaf Foods Inc. (Greenleaf Foods)
- Heura Foods
- Tyson Foods Inc.
- Beyond Meat Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Source Protein Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Meat Substitute Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Storage Condition, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Texturization Technology, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source Protein Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Meat Substitute Format, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Storage Condition, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Texturization Technology, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Source Protein Class, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Meat Substitute Format, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Storage Condition, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Texturization Technology, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by Source Protein Class, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Meat Substitute Format, 2021 to 2036
- Table 22: Latin America Market Value (USD Billion) Forecast by Storage Condition, 2021 to 2036
- Table 23: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Latin America Market Value (USD Billion) Forecast by Texturization Technology, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Source Protein Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Source Protein Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Source Protein Class
- Figure 6: Global Market Value Share and BPS Analysis by Meat Substitute Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Meat Substitute Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Meat Substitute Format
- Figure 9: Global Market Value Share and BPS Analysis by Storage Condition, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Storage Condition, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Storage Condition
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Texturization Technology, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Texturization Technology, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Texturization Technology
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 25: North America Market Value Share and BPS Analysis by Source Protein Class, 2026 and 2036
- Figure 26: North America Market Y-o-Y Growth Comparison by Source Protein Class, 2026-2036
- Figure 27: North America Market Attractiveness Analysis by Source Protein Class
- Figure 28: North America Market Value Share and BPS Analysis by Meat Substitute Format, 2026 and 2036
- Figure 29: North America Market Y-o-Y Growth Comparison by Meat Substitute Format, 2026-2036
- Figure 30: North America Market Attractiveness Analysis by Meat Substitute Format
- Figure 31: North America Market Value Share and BPS Analysis by Storage Condition, 2026 and 2036
- Figure 32: North America Market Y-o-Y Growth Comparison by Storage Condition, 2026-2036
- Figure 33: North America Market Attractiveness Analysis by Storage Condition
- Figure 34: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 35: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 36: North America Market Attractiveness Analysis by Distribution Channel
- Figure 37: North America Market Value Share and BPS Analysis by Texturization Technology, 2026 and 2036
- Figure 38: North America Market Y-o-Y Growth Comparison by Texturization Technology, 2026-2036
- Figure 39: North America Market Attractiveness Analysis by Texturization Technology
- Figure 40: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Western Europe Market Value Share and BPS Analysis by Source Protein Class, 2026 and 2036
- Figure 42: Western Europe Market Y-o-Y Growth Comparison by Source Protein Class, 2026-2036
- Figure 43: Western Europe Market Attractiveness Analysis by Source Protein Class
- Figure 44: Western Europe Market Value Share and BPS Analysis by Meat Substitute Format, 2026 and 2036
- Figure 45: Western Europe Market Y-o-Y Growth Comparison by Meat Substitute Format, 2026-2036
- Figure 46: Western Europe Market Attractiveness Analysis by Meat Substitute Format
- Figure 47: Western Europe Market Value Share and BPS Analysis by Storage Condition, 2026 and 2036
- Figure 48: Western Europe Market Y-o-Y Growth Comparison by Storage Condition, 2026-2036
- Figure 49: Western Europe Market Attractiveness Analysis by Storage Condition
- Figure 50: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 51: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 52: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 53: Western Europe Market Value Share and BPS Analysis by Texturization Technology, 2026 and 2036
- Figure 54: Western Europe Market Y-o-Y Growth Comparison by Texturization Technology, 2026-2036
- Figure 55: Western Europe Market Attractiveness Analysis by Texturization Technology
- Figure 56: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 57: Latin America Market Value Share and BPS Analysis by Source Protein Class, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Source Protein Class, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Source Protein Class
- Figure 60: Latin America Market Value Share and BPS Analysis by Meat Substitute Format, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Meat Substitute Format, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Meat Substitute Format
- Figure 63: Latin America Market Value Share and BPS Analysis by Storage Condition, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by Storage Condition, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by Storage Condition
- Figure 66: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 69: Latin America Market Value Share and BPS Analysis by Texturization Technology, 2026 and 2036
- Figure 70: Latin America Market Y-o-Y Growth Comparison by Texturization Technology, 2026-2036
- Figure 71: Latin America Market Attractiveness Analysis by Texturization Technology
- Figure 72: Global Market - Tier Structure Analysis
- Figure 73: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the plant-based meat market in 2026?
Future Market Insights estimates the global plant-based meat market at USD 13.0 billion in 2026, up from USD 11.5 billion in 2025.
How fast is the plant-based meat market expected to grow through 2036?
FMI projects a 13.2% CAGR from 2026 to 2036, taking the global market to USD 44.9 billion by 2036 and generating USD 31.9 billion in incremental revenue.
Which source protein class leads the plant-based meat market?
Soy-Based Protein Concentrates lead with 44.0% of 2026 revenue, supported by complete PDCAAS 1.0 amino acid quality and low-cost fibrous extrusion gelling.
Which meat substitute format captures the largest revenue share?
Plant-Based Burger Patties hold 42.5% of 2026 revenue, anchored by 1:1 replacement compatibility on QSR flat-top grills and home barbecues.
Which storage condition and distribution channel dominate sales?
Frozen Plant-Based Formats account for 56.0% of 2026 revenue by eliminating chilled spoilage shrink, while Retail Supermarkets capture 58.0% of channel sales.
Which texturization technology leads the industry?
High-Moisture Twin-Screw Extrusion commands 51.5% of 2026 volume and is projected to reach 64.0% by 2036 as processors replicate whole-muscle poultry and beef fibers.
Which countries are the largest and fastest-growing plant-based meat markets?
The United States is both the largest (USD 4.2 billion in 2026; 32.3% share) and fastest-growing (14.0% CAGR) market, followed in growth by Brazil (13.6% CAGR) and the United Kingdom (13.4% CAGR).
How has M&A reshaped the competitive landscape in 2025 and 2026?
JBS-owned Vivera acquired The Vegetarian Butcher from Unilever plc in March 2025, Mars, Incorporated completed its USD 35.9 billion acquisition of Kellanova in December 2025, and Impossible Foods Inc. entered UK Tesco supermarkets in September 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
