

- Market Size (2026)
- USD 167.8 Mn
- Forecast (2036)
- USD 397.4 Mn
- CAGR (2026 to 2036)
- 9.0%
How big is Potato Protein Market in 2026?
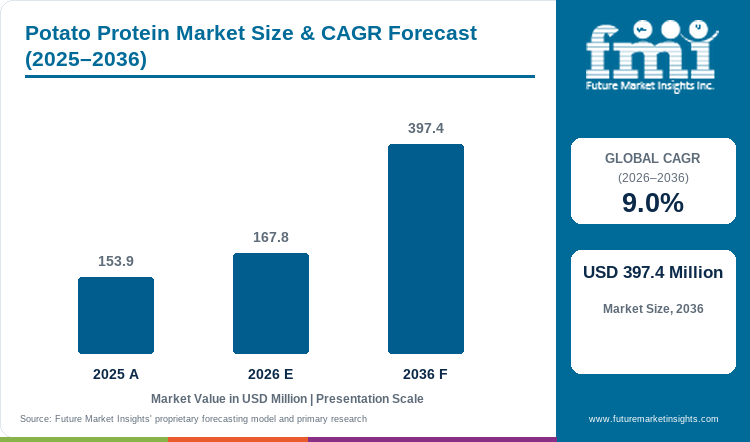
USD 167.8 million in 2026 and USD 397.4 million by 2036 at a 9.0% CAGR.
Sales of potato protein are estimated to grow at 9.0% from USD 167.8 million in 2026 to USD 397.4 million by 2036. The market was valued at USD 153.9 million in 2025. Commercial growth depends on whether processors can recover a consistent protein grade from potato streams and preserve the functionality needed by food, feed and nutrition customers. High-value grades earn repeat orders when they combine protein density with predictable binding, emulsification or gelling behavior.
The growth mechanism differs by country. Demand overlaps with the broader plant-based protein market where manufacturers are moving beyond protein content and testing taste, texture and processing reliability. Germany and Poland benefit from integrated potato-processing infrastructure, while Spain and the UK depend more heavily on application adoption and dependable regional supply. In each market, qualification moves faster when technical teams can connect a defined grade with the finished product rather than treating potato protein as a generic commodity.
Key Takeaways
- Potato protein demand rises when one ingredient can support protein enrichment and useful formulation functions such as binding, emulsification or gel formation.
- Conventional leads Nature with a 91.0% share in 2026, supported by the scale and continuity of established starch-potato processing campaigns.
- 70-90% leads Product Type with a 56.0% share in 2026 as high-protein grades balance concentration with practical recovery and application performance.
- Meat Additives, Analogs and Substitutes leads End Use Application with 19.0%, while Isolate leads Form with 78.0% in 2026.
- Process-sensitive functionality remains the main qualification restraint. Spain records the fastest profiled country CAGR at 11.0% from 2026 to 2036.
- Avebe, Tereos, Roquette Freres, Emsland Group, Kerry Group plc, AGRANA Beteiligungs-AG, KMC Ingredients and PEPEES Group are notable companies in the market.
Analyst Perspective
Potato protein earns a durable place in a formulation when the supplier can preserve native functionality at commercial scale and support the customer through qualification. Protein concentration is important, but repeat purchasing depends on the delivered grade behaving consistently in the buyer's actual process.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the potato protein market segmented?
The potato protein market is segmented by Nature, Product Type, End Use Application, Form and Region.
Nature comprises Conventional and Organic. Product Type covers 70-90%, 60-65%, 40-50% and 10-40%. End Use Application includes Meat Additives, Analogs and Substitutes; Dairy Alternatives; Bakery & Confectionery; Sports Nutrition; Dietary Supplements; Milk; Animal Nutrition; Breads; Pharmaceutical Products; and Breakfast Cereals. Form comprises Isolate, Hydrolyzed, Textured and Concentrate. Region coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Why does Conventional lead demand within the Nature category?
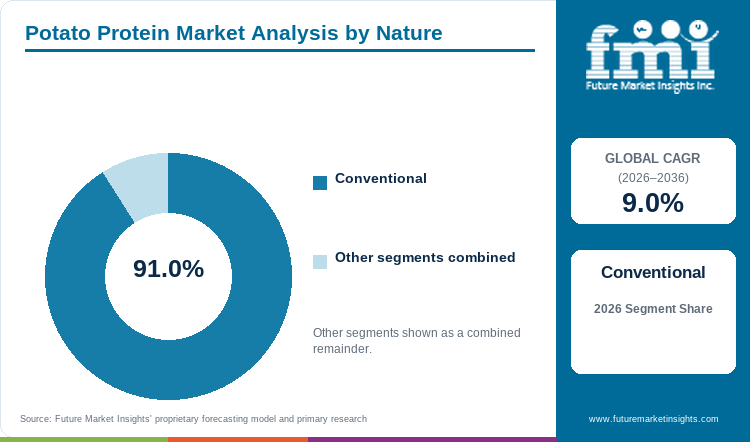
Conventional production fits the economics of large starch-potato campaigns. Protein is recovered from potato juice during starch processing, so raw-material continuity and plant utilization directly influence the cost of the protein stream. Organic potato protein has a clear role where certified feed or food programs require it, but segregation and certification narrow the available supply base. Buyers without an organic claim can therefore focus on functional performance and continuity rather than maintaining a separate certified chain.
- Conventional holds a 91.0% share in 2026, reflecting the scale of established industrial potato-processing systems.
- Avebe's August 2025 campaign update shows starch potatoes being processed into both potato starch and potato protein across Dutch and German factories.
Why does 70-90% lead demand within the Product Type category?
The 70-90% band gives formulators a high-protein ingredient without making extreme purification the only purchasing objective. Current Roquette TUBERMINE grades are positioned at about 78% protein for animal nutrition, while PEPEES markets feedstuff potato protein above 80% whole protein. These commercial examples sit inside the leading band and show why concentration is assessed alongside particle behavior, digestibility and process fit.
- 70-90% holds a 56.0% share in 2026, making it the leading Product Type band.
- Buyers compare the delivered protein specification with application performance rather than assuming a higher percentage automatically improves formulation economics.
Why do Meat Additives, Analogs and Substitutes lead demand within the End Use Application category?
Meat systems and alternatives need proteins that contribute cohesion and structure under heating. Avebe currently positions PerfectaSOL potato protein around gelation, emulsification and binding in plant-based meat. This connects potato protein directly with the meat substitutes market, where texture and processing repeatability are central to commercial formulation. The same functional logic can support processed meat systems when the selected grade fits the customer's sensory and process requirements.
- Meat Additives, Analogs and Substitutes holds a 19.0% share in 2026, the largest End Use Application allocation.
- Current product positioning emphasizes binding, gelation and emulsification, giving potato protein a role beyond simple protein fortification.
Why does Isolate lead demand within the Form category?
Isolates are suited to applications where formulators need concentrated protein with controlled sensory and functional behavior. AGRANA Research & Innovation Center reported a 2025 isolation process using pretreatment, reverse osmosis and ultrafiltration, with the resulting protein showing high solubility plus emulsifying, gelling and foaming behavior. These attributes matter in food and the sports nutrition market where a protein powder must deliver nutritional value without creating excessive flavor, color or dispersion problems.
- Isolate holds a 78.0% share in 2026, making it the leading Form category.
- The commercial premium depends on purification that preserves functionality rather than concentration alone.
What are the drivers, restraints and opportunities in the potato protein market?
Multifunctional plant protein supports demand, process-sensitive recovery constrains qualification, and higher-value use of starch-processing streams creates the clearest commercial opportunity.
- Driver: Potato protein can combine protein enrichment with binding, emulsification, gelling or texture support in one formulation.
- Restraint: Recovery and purification conditions can change solubility, color, taste and native functionality, extending buyer qualification.
- Opportunity: Starch processors can capture more value from potato streams through food-grade isolates, feed concentrates and application-specific grades.
Why multifunctional performance supports demand
Food manufacturers increasingly assess plant proteins for more than their nutrition panel. Avebe's current potato-protein portfolio highlights foaming, emulsifying and gelling performance, while KMC positions potato protein for bakery, snacks, pasta, beverages and nutrition. This broadens the addressable protein ingredients market because one grade can contribute both protein and process functionality. Suppliers gain repeat business when those properties remain stable at the customer's actual inclusion rate.
Why recovery conditions can slow qualification
Potato protein begins as a co-product stream inside a water-intensive starch process. Food-grade recovery adds separation and purification steps that can change native protein behavior. AGRANA's 2025 isolate work used pretreatment followed by membrane processes before final isolation. Buyers therefore need lot consistency as well as a headline protein percentage. A grade that varies in color, solubility or gel response can force recipe changes and delay conversion from trial quantities to regular purchasing.
Where higher-value applications create opportunity
The strongest opportunity is to move suitable potato-protein streams into applications that pay for controlled functionality. Current supplier portfolios cover plant-based meat, bakery, pet food and nutrition. The opportunity also overlaps with the dairy alternatives market where clean-label texture and protein enrichment can be combined in one reformulation. KMC's 2026 product-specific LCA for PotaPro 1500 adds another purchasing attribute by giving feed and pet-food buyers ingredient-level environmental data alongside nutrition specifications.
Which country CAGRs are profiled in the potato protein market?
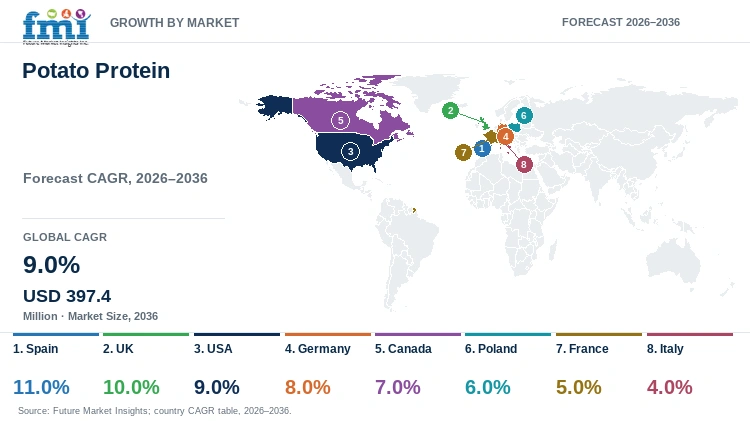
The profiled country CAGRs cover 2026 to 2036.
| Country | CAGR |
|---|---|
| Spain | 11.0% |
| UK | 10.0% |
| USA | 9.0% |
| Germany | 8.0% |
| Canada | 7.0% |
| Poland | 6.0% |
| France | 5.0% |
| Italy | 4.0% |
How do country-level CAGRs compare in the potato protein market?
Spain and the UK lead the profiled country growth rates at 11.0% and 10.0%. The USA and Germany follow at 9.0% and 8.0%, while Canada and Poland are projected at 7.0% and 6.0%. France and Italy record 5.0% and 4.0%. The seven-percentage-point spread reflects different processing bases, application adoption and supply conditions rather than the absolute size of each national market.
- Spain: Specialty ingredient growth depends on food-manufacturer adoption and dependable regional supply rather than a broad expansion in domestic potato acreage.
- UK: A large potato-processing base supports familiarity with potato-derived ingredients, while dry-season supply pressure keeps continuity visible in procurement.
- USA: Deep potato processing and established food-manufacturing channels support application-led qualification across nutrition and formulated foods.
- Germany: Large 2025 potato output and integrated starch-protein factories provide a strong industrial recovery base.
- Canada: High potato production supports ingredient availability, but regional yield variability keeps supply planning important.
- Poland: Strong 2025 crop output and PEPEES' direct potato-protein production create visible local supply participation.
- France: Processing demand supports potato utilization, while starch-asset economics remain important to co-product recovery.
- Italy: Recent agricultural improvement supports the raw-material base, but adoption depends more on specialty formulation and distribution than dedicated local protein capacity.
Country-wise Analysis
- Spain carries the fastest profiled growth rate at 11.0% CAGR from 2026 to 2036. The Spanish Ministry of Agriculture continues to identify potatoes as an established domestic crop, but the longer-term sector has faced acreage pressure. Potato-protein growth therefore depends on specialty formulation rather than simple crop expansion. Suppliers serving meat alternatives, bakery and nutrition accounts need stable imported or regional grades plus local technical support that can shorten application trials.
- The UK is projected to expand at a 10.0% CAGR from 2026 to 2036. Defra's 2025 crop account records more than 5 million tonnes of potatoes and highlights the effect of dry conditions on irrigation. A sizeable potato base supports processor familiarity, but raw-material volatility keeps specification continuity and supply planning central to ingredient purchasing. KMC's 2025 partnership with Daymer Ingredients also strengthens its route into UK manufacturers for potato-based ingredients.
- The USA is forecast at a 9.0% CAGR from 2026 to 2036. USDA's Potatoes 2024 Summary was published in September 2025 and shows the scale of the national crop and processing system. That depth gives ingredient buyers access to established food and pet-food development channels. Commercial adoption of potato protein still depends on sensory control, dispersion and functional performance relative to soy, dairy or egg proteins already used in the formulation.
- Germany is projected to grow at an 8.0% CAGR from 2026 to 2036. Destatis reported about 13.9 million tonnes of potatoes in the 2025 harvest. Avebe's August 2025 campaign update also confirmed processing at its German factories in Dallmin and Luchow. This combination of crop scale and integrated starch-to-protein infrastructure supports a direct industrial base for protein recovery and regional customer supply.
- Canada carries a 7.0% CAGR from 2026 to 2036. Statistics Canada reported 125.8 million hundredweight of potato production in 2025, with Alberta, Manitoba and Prince Edward Island among the leading provinces. The same release noted regional drought pressure. For potato-protein buyers, that makes geographic diversification and contract reliability important even when the purchased ingredient arrives as a standardized powder.
- Poland is profiled at a 6.0% CAGR from 2026 to 2036. Statistics Poland estimated the 2025 potato harvest at about 7.0 million tonnes. PEPEES provides direct category participation through feedstuff potato protein produced from potato intracellular fluid. Local starch processing gives the country an established recovery route, while wider growth depends on extending specification-led uses beyond conventional feed markets.
- France has a 5.0% CAGR profile from 2026 to 2036. Agreste reported in June 2025 that the abundant 2024 potato harvest pressured prices while processing demand helped absorb supply. Tereos currently lists potato protein within its animal-feed protein portfolio. French market growth therefore depends on utilization economics at integrated processing sites and the ability to place co-product protein into dependable feed and specialty applications.
- Italy is forecast at a 4.0% CAGR from 2026 to 2036. Istat reported in July 2025 that potato production volume had improved in 2024. The slower growth profile reflects a market where distributor reach and customer qualification matter more than a large dedicated potato-protein manufacturing base. Suppliers can expand through bakery, nutrition, dairy-alternative and pet-food applications when they provide a consistent grade and responsive technical support.
Who are the notable companies in the potato protein market?
Avebe, Tereos, Roquette Freres, Emsland Group, Kerry Group plc, AGRANA Beteiligungs-AG, KMC Ingredients and PEPEES Group are the notable companies profiled in this market.
Competition spans food-grade functional proteins, feed concentrates and application-led formulation systems. Avebe and KMC have broad current food-facing potato-protein platforms. AGRANA is developing a food-grade isolate route while maintaining feed production. Roquette, Tereos, Emsland Group and PEPEES provide current feed or pet-food potato-protein products. Kerry includes Protastar potato protein within pet-nutrition solutions. These positions give buyers different combinations of production control, functional support and channel reach.
- Food-grade functional platforms: Avebe and KMC Ingredients combine direct potato-protein portfolios with application support for food development.
- Integrated feed and recovery platforms: Tereos, Roquette Freres, Emsland Group, AGRANA Beteiligungs-AG and PEPEES Group connect potato processing with feed or pet-nutrition protein products.
- Application-led pet nutrition: Kerry Group plc lists Protastar potato protein within dry and wet pet-food solutions.
Competitive Benchmarking: Potato Protein Market
| Company | Direct Potato Protein Portfolio | Food-Grade Functional Capability | Feed & Pet Nutrition Capability | Geographic Reach |
|---|---|---|---|---|
| Avebe | High | High | Unscored | Netherlands and Germany with international food-ingredient activity. |
| Tereos | Medium | Unscored | High | France and wider European animal-feed markets. |
| Roquette Freres | Medium | Unscored | High | Europe and Americas documentation for TUBERMINE potato protein. |
| Emsland Group | Medium | Medium | High | Germany-based production with international food and animal-nutrition activity. |
| Kerry Group plc | Medium | Unscored | High | Global pet-nutrition channels with Protastar potato protein. |
| AGRANA Beteiligungs-AG | Medium | Medium | High | Austria and Central Europe with Gmund potato-protein production. |
| KMC Ingredients | High | High | High | Denmark-based potato ingredients with international food and feed channels. |
| PEPEES Group | Medium | Unscored | High | Poland-based potato processing with export-oriented ingredient activity. |
Scoring basis: High indicates broad current capability across the named area, while Medium indicates a narrower but direct product or application position. Unscored is retained where that capability is not central to the company's documented potato-protein role. The ratings describe capability depth and do not represent company market share.
Key Developments in the Potato Protein Market
- In January 2026, KMC Ingredients published third-party-verified, product-specific life-cycle data for PotaPro 1500 in the GFLI branded database. The feed and pet-food potato protein can now be compared using ingredient-level environmental information alongside nutrition specifications.
- In May 2025, AGRANA Research & Innovation Center described an improved process for food-grade potato protein isolate using pretreatment, reverse osmosis and ultrafiltration. The reported isolate combined high solubility with emulsifying, gelling and foaming functionality.
- In August 2025, Avebe began its 2025 potato campaign across Dutch and German factories, with potatoes processed into both starch and protein. The campaign reinforces the integrated raw-material model that underpins commercial potato-protein availability.
Key Players in the Potato Protein Market
Food-grade functional protein platforms
- Avebe
- KMC Ingredients
- AGRANA Beteiligungs-AG
Feed and pet-nutrition potato protein suppliers
- Tereos
- Roquette Freres
- Emsland Group
- PEPEES Group
Application-led pet nutrition
- Kerry Group plc
Potato Protein Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Nature, Product Type, End Use Application, Form and Region. |
| Quantitative Units | USD Million |
| Market Definition | Revenue covers potato protein ingredients sold within the listed Nature, Product Type, End Use Application and Form categories, including food and feed grades. Finished-product revenue, potato starch, potato fiber, other potato derivatives and non-potato protein substitutes are outside the market scope. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany; USA; UK; Italy; France; Spain; Poland; Canada |
| Key Companies Profiled | Avebe; Tereos; Roquette Freres; Emsland Group; Kerry Group plc; AGRANA Beteiligungs-AG; KMC Ingredients; PEPEES Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Potato Protein Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from potato processors, protein ingredient suppliers, food and feed manufacturers, distributors, procurement teams and technical experts. Interviews examined grade selection, application testing, supply continuity, pricing and the requirements that move a trial into regular purchasing. |
| Desk Research | Desk research covered government agricultural statistics, industry publications, company filings, current product information, technical literature and official corporate announcements. |
| Market Sizing and Forecasting | Market sizing combined the 2026 baseline with historical performance, segment structure, pricing and volume indicators, application adoption, company participation and country-level demand conditions. |
| Data Validation | Estimates were checked against independent indicators including crop data, current company activity, processing capacity signals and primary research. Segment and regional estimates were reconciled before the final market total was confirmed. |
Potato Protein Market by Segments
Potato Protein Market segmented by Nature:
- Conventional
- Organic
Potato Protein Market segmented by Product Type:
- 70-90%
- 60-65%
- 40-50%
- 10-40%
Potato Protein Market segmented by End Use Application:
- Meat Additives, Analogs and Substitutes
- Dairy Alternatives
- Bakery & Confectionery
- Sports Nutrition
- Dietary Supplements
- Milk
- Animal Nutrition
- Breads
- Pharmaceutical Products
- Breakfast Cereals
Potato Protein Market segmented by Form:
- Isolate
- Hydrolyzed
- Textured
- Concentrate
Potato Protein Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Royal Avebe (2025, August 21). Start of potato campaign 2025: first potatoes delivered in Gasselternijveen.
- Royal Avebe (n.d.). Potato protein and PerfectaSOL product information.
- AGRANA Research & Innovation Center (2025, May 14). Improved process for production of potato protein as food.
- AGRANA Beteiligungs-AG (n.d.). Potato protein for animal feed.
- KMC Ingredients (2026, January 5). KMC publishes verified LCA data for PotaPro 1500 in the GFLI branded database.
- KMC Ingredients (2025, May 20). New partnership with Daymer Ingredients Limited in the United Kingdom.
- KMC Ingredients (n.d.). Potato protein ingredients for modern food manufacturing.
- Tereos (n.d.). Animal Feed product portfolio.
- Roquette Freres (n.d.). TUBERMINE GP and TUBERMINE FV potato protein product information.
- Emsland Group (2025, March 27). Gluten Free & Nutritious: Potato-Based Pasta.
- Emsland Group (n.d.). Potato Protein and animal nutrition product information.
- Kerry Group plc (n.d.). Pet Nutrition & Wellness, including Protastar potato protein.
- PEPEES Group (n.d.). Feedstuff Potato Protein.
- Federal Statistical Office of Germany (2025). 2025 grain and potato harvest.
- UK Department for Environment, Food & Rural Affairs (2026). Agriculture in the United Kingdom 2025: Crops.
- USA Department of Agriculture, National Agricultural Statistics Service (2025, September 26). Potatoes 2024 Summary.
- Statistics Canada (2025, December 5). Canadian potato production, 2025.
- Statistics Poland (2025, December 18). Result estimate of the main agricultural and horticultural crops in 2025.
- Agreste, French Ministry of Agriculture (2025, June 17). L'abondance de la récolte 2024 pèse sur les prix des pommes de terre.
- Istat (2025, July 28). L'andamento dell'economia agricola - Anno 2024.
- Spanish Ministry of Agriculture, Fisheries and Food (n.d.). Patata.
- European Commission (2026, July 7). Reducing the plant protein deficit of the EU.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the potato protein market in 2025, 2026 and 2036?
- Which formulation and processing pressures support demand for potato protein?
- Why does Conventional lead the Nature category?
- Why does 70-90% lead the Product Type category?
- How do Meat Additives, Analogs and Substitutes and Isolate shape application demand?
- How do growth rates differ across the profiled countries?
- Which companies provide food-grade, feed or pet-nutrition potato protein?
- What should buyers test before approving a potato protein grade?
Frequently Asked Questions
How big is the potato protein market in 2026 and what is forecast for 2036?
The potato protein market is valued at USD 167.8 million in 2026 and is forecast to reach USD 397.4 million by 2036. The market was valued at USD 153.9 million in 2025.
What is the potato protein market CAGR from 2026 to 2036?
The market is forecast to expand at a 9.0% CAGR from 2026 to 2036. Realized purchasing depends on application qualification and dependable ingredient supply.
Which Nature segment leads the potato protein market?
Conventional leads Nature with a 91.0% share in 2026, supported by established starch-potato processing systems and broad conventional procurement.
Which Product Type segment leads the potato protein market?
70-90% leads Product Type with a 56.0% share in 2026. The range offers high protein delivery while retaining practical processing and application characteristics.
Which End Use Application and Form segments lead the potato protein market?
Meat Additives, Analogs and Substitutes leads End Use Application with a 19.0% share in 2026, while Isolate leads Form with a 78.0% share.
Which profiled countries have the highest potato protein market growth rates?
Spain has the highest profiled CAGR at 11.0%, followed by the UK at 10.0% and the USA at 9.0% from 2026 to 2036.
Which companies are profiled in the potato protein market?
The report profiles Avebe, Tereos, Roquette Freres, Emsland Group, Kerry Group plc, AGRANA Beteiligungs-AG, KMC Ingredients and PEPEES Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- 70-90%
- 60-65%
- 40-50%
- 10-40%
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use Application, 2026 to 2036
- Meat Additives, Analogs and Substitutes
- Dairy Alternatives
- Bakery & Confectionery
- Sports Nutrition
- Dietary Supplements
- Milk
- Animal Nutrition
- Breads
- Pharmaceutical Products
- Breakfast Cereals
- Y-o-Y Growth Trend Analysis By End Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Isolate
- Hydrolyzed
- Textured
- Concentrate
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Product Type
- By End Use Application
- By Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use Application
- By Form
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use Application
- By Form
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Product Type
- By End Use Application
- By Form
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Avebe
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Tereos
- Roquette Freres
- Emsland Group
- Kerry Group plc
- AGRANA Beteiligungs-AG
- KMC Ingredients
- PEPEES Group
- Avebe
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


