

- Market Size (2026)
- USD 850.0 Mn
- Forecast (2036)
- USD 4640.9 Mn
- CAGR (2026 to 2036)
- 18.5%
How big is Prebiotic Soda Market in 2026?
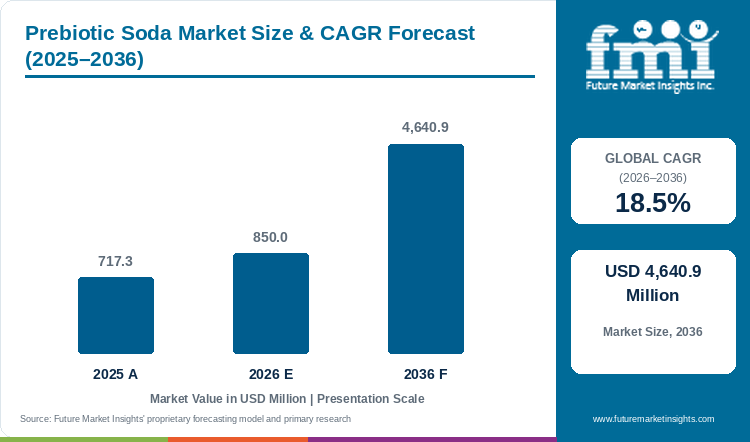
Demand for prebiotic soda is projected to rise at 18.5% CAGR through 2036. Sector valuation increases from USD 717.3 million in 2025 to USD 850.0 million in 2026 and is predicted to reach USD 4,640.9 million by 2036.
According to Future Market Insights analysis, global prebiotic soda revenue expands from USD 717.3 million in 2025 to USD 850.0 million in 2026 and is forecast to reach USD 4,640.9 million by 2036, advancing at an 18.5% CAGR and adding USD 3,790.9 million in cumulative new revenue. This rapid expansion reflects a structural shift in cold-vault retail space as grocery shoppers replace high-fructose carbonated soft drinks with low-sugar sodas delivering 2 to 9 grams of soluble dietary fiber per serving. Beverage producers blend chicory root oligofructose, Jerusalem artichoke inulin, cassava root dextrin, and organic apple cider vinegar to nourish colonic microbiota while keeping total sugars below 5 grams per 355 ml can. In June 2025, the International Scientific Association for Probiotics and Prebiotics updated its scientific consensus resources emphasizing that verified prebiotic substrates must be selectively utilized by host microorganisms to confer a documented health benefit [1]. Flavored / Botanical Infusion holds 45.4% of product variety / flavor revenue in 2026 alongside broader digestive health drinks portfolios.
Key Market Trends & Insights
- By product variety / flavor: Flavored / Botanical Infusion led the category with a 45.4% share in 2026, because citrus, berry, and ginger organic acids mask the earthy sweetness of inulin and stevia.
- By packaging format: Slim Aluminum Cans accounted for 39.3% of demand in 2026, as hermetically sealed sleek cans preserve carbonation pressure and signal premium positioning in open-deck retail coolers.
- By distribution channel: With a 43.9% share in 2026, Supermarkets & Hypermarkets held the leading position, owing to nationwide center-aisle planogram resets and 4-can and 12-can multipack promotions.
Regional Highlights
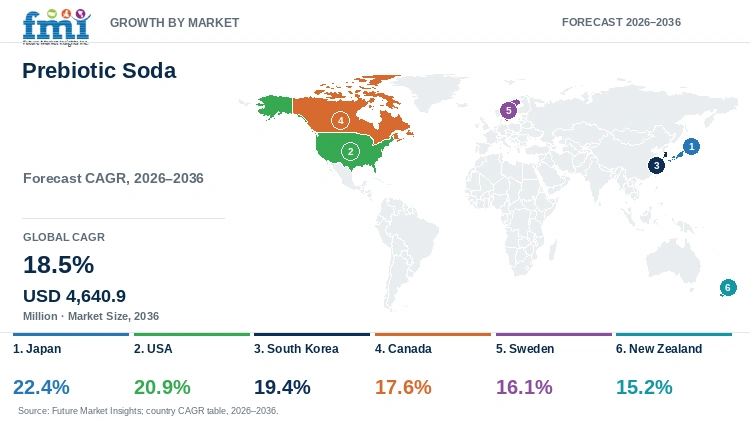
- Fastest-growing evaluated country: Japan, at 22.4% CAGR from 2026 to 2036.
- By country: The USA at 20.9%, South Korea at 19.4%, Canada at 17.6%, and Sweden at 16.1% follow, while New Zealand records an evaluated CAGR of 15.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Prebiotic Soda Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 717.3 million |
| Estimated Market Size in 2026 | USD 850.0 million |
| Projected Market Size by 2036 | USD 4,640.9 million |
| CAGR, 2026 to 2036 | 18.5% |
| Added Revenue, 2026 to 2036 | USD 3,790.9 million |
Nutrition labeling enforcement across North America, Europe, and East Asia determines which soluble carbohydrate polymers can be declared as dietary fiber on carbonated beverage panels. Under the U.S. Food and Drug Administration's updated Dietary Fiber Questions and Answers guidance (21 CFR 101.9(c)(6)(i)), isolated or synthetic non-digestible carbohydrates such as inulin, fructooligosaccharides, and resistant maltodextrin qualify for Nutrition Facts fiber declarations only when verified to confer a physiological health benefit [2]. Because shoppers increasingly alternate prebiotic sodas with fermented kombucha teas during afternoon refreshment occasions, co-packers must control tunnel-pasteurization temperatures and beverage pH above 3.2 so acid hydrolysis does not cleave fructan chains into simple sugars during ambient warehousing.
Cannery Output and Fiber Dosage Sizing
Table 2: Cannery Volume and Fiber Dosage Indicators for the Prebiotic Soda Market (USD million, million 355 ml cans, and thousand tonnes), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 717.3 | 850.0 | 4,640.9 |
| Packaged beverage volume (million 355 ml units) | 335 to 360 | 400 to 430 | 2,320 to 2,510 |
| Formulated soluble prebiotic fiber demand (thousand tonnes) | 1.8 to 2.1 | 2.2 to 2.6 | 12.8 to 14.5 |
| Average manufacturer realized price per 355 ml unit (USD) | 1.98 to 2.14 | 1.97 to 2.12 | 1.85 to 2.00 |
Operational note: Packaged unit and soluble fiber tonnage estimates reflect finished carbonated prebiotic soft drinks dosed at 3.0 to 9.0 grams of dietary fiber per 355 ml serving across commercial canning lines.
Per Capita & Retail Cooler Door Sizing
Migrating functional sodas from refrigerated natural-food produce coolers into ambient center-aisle soda shelves has multiplied unit velocity across North American and Asia-Pacific supermarkets. Shelf-stable formulations allow beverage distributors to ship 12-can pantry packs through standard dry-van logistics without cold-chain freight surcharges. Rising consumer familiarity with dietary prebiotic fibers also enables brand owners to lower single-can price gaps against legacy colas as contract canning batches scale above 50 million cans per facility.
Table 3: Per Capita and Retail Store Spending Indicators for the Prebiotic Soda Market (USD and cents metrics), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.09 | 0.10 | 0.52 |
| Spend per 1,000 people (USD) | 87.2 | 102.4 | 518.5 |
| Annual prebiotic soda wholesale revenue per stocked supermarket (USD) | 4,800 to 5,400 | 5,600 to 6,300 | 24,500 to 27,800 |
Table 4: Channel and Format Revenue Indicators for the Prebiotic Soda Market (USD million and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 850.0 million | Report value |
| Flavored / botanical infusion revenue, 2026 | USD 385.9 million | 45.4% product variety share |
| Slim aluminum cans revenue, 2026 | USD 334.1 million | 39.3% packaging format share |
| Supermarkets & hypermarkets revenue, 2026 | USD 373.2 million | 43.9% distribution channel share |
Operational note: Historical 2025 and base-year 2026 indicators in Tables 2, 3, and 4 are triangulated from FDA dietary fiber labeling filings, Aluminum Association can shipment records, and corporate acquisition disclosures, while 2036 figures represent FMI econometric model projections.
Analyst Perspective
"Ambient center-aisle multipacks and multinational bottler acquisitions are turning prebiotic soda into a mainstream grocery staple. Formulators must still balance slow-fermenting dextrins against short-chain fructans to prevent gastrointestinal discomfort during daily consumption."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the prebiotic soda market segmented?
The prebiotic soda market is segmented by product variety / flavor, packaging format, distribution channel, and region. In 2026, Flavored / Botanical Infusion is projected at 45.4%, Slim Aluminum Cans at 39.3%, and Supermarkets & Hypermarkets at 43.9%.
By product variety / flavor: Flavored / Botanical Infusion, Classic Nostalgic Soda Profiles (Cola, Root Beer & Ginger Ale), and Zero-Sugar / Sugar-Free Variant.
By packaging format: Slim Aluminum Cans, Standard 355ml Aluminum Cans, Glass Bottles, and Recyclable PET Bottles.
By distribution channel: Supermarkets & Hypermarkets, Convenience Stores & Gas Stations, Online Retail & Subscription, and Food Service & Cafes.
Why Does Flavored / Botanical Infusion Lead the Prebiotic Soda Market by Product Variety / Flavor?
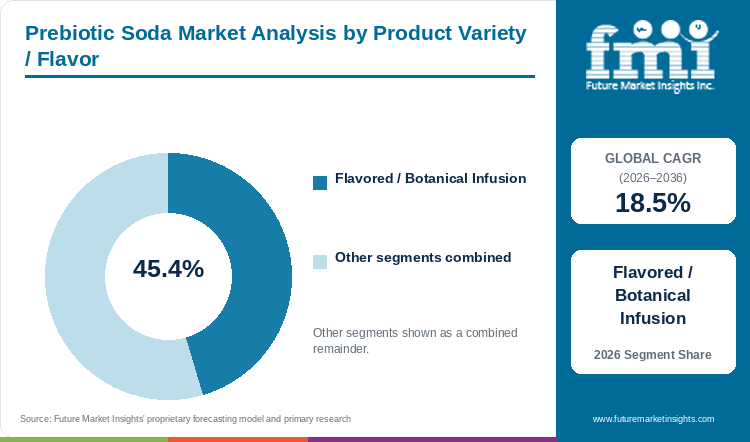
Flavored / Botanical Infusion is projected to hold 45.4% of product variety / flavor demand in 2026, supported by fruit-acid masking.
Table 5: Product Variety / Flavor Share for the Prebiotic Soda Market (percentage share), 2026
| Product Variety / Flavor | Share (2026) |
|---|---|
| Flavored / Botanical Infusion | 45.4% |
| Classic Nostalgic Soda Profiles | 32.8% |
| Zero-Sugar / Sugar-Free Variant | 21.8% |
| Total | 100.0% |
*Calculated across mutually exclusive product variety / flavor formulations totaling 100.0% of 2026 category demand.
Table 6: Product Variety / Flavor Leadership and Market Growth for the Prebiotic Soda Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 18.5% |
| Leading Segment | Flavored / Botanical Infusion |
Flavored / Botanical Infusion captures the largest variety share because cold-pressed berry, citrus, watermelon, and ginger distillates harmonize with the natural organic acidity of apple cider vinegar and chicory root extracts. Unlike dark caramel cola profiles that require heavy spice-oil dosing to replicate high-fructose syrup viscosity, fruit-botanical infusions deliver a crisp mouthfeel at 25 to 45 calories per can. Classic nostalgic soda profiles hold 32.8% of demand among shoppers replacing conventional root beer and vanilla cream sodas, while zero-sugar variants capture 21.8% through allulose and stevia leaf sweetening.
- Flavored / Botanical Infusion is projected to account for 45.4% of product variety / flavor revenue in 2026, supported by high repeat purchase velocity across fruit-forward multipacks.
- In May 2025, PepsiCo, Inc. completed its USD 1.95 billion acquisition of poppi, integrating fruit-forward prebiotic soda varieties such as Strawberry Lemon, Orange, and Raspberry Rose into its national refreshment portfolio [3].
What Makes Slim Aluminum Cans Central to the Packaging Format Category?
Slim Aluminum Cans are estimated to represent 39.3% of packaging format demand in 2026, reflecting hermetic barrier protection.
Slim Aluminum Cans lead packaging format demand because sleek 355 ml cans visually separate premium gut-health sodas from commodity soft drinks while fitting 25% more facings per linear foot on refrigerated convenience shelves. Aluminum walls provide a complete oxygen and ultraviolet light barrier that protects sensitive botanical anthocyanins and soluble prebiotic ingredients during tunnel pasteurization and warm warehouse storage. Standard squat 355 ml aluminum cans follow in high-volume club-store cases, whereas glass bottles and PET containers remain limited by higher freight weight and carbonation loss over extended shelf life.
- Slim Aluminum Cans are estimated to hold 39.3% of packaging format demand in 2026, reflecting superior cold-vault shelf density and zero light transmission.
- In March 2025, The Aluminum Association and the Can Manufacturers Institute published lifecycle circularity research confirming that recycled aluminum beverage cans return to retail shelves as newly formed cans in less than 60 days [4].
Why Do Supermarkets & Hypermarkets Anchor the Distribution Channel Category?
Supermarkets & Hypermarkets are forecast to capture 43.9% of distribution channel sales in 2026, driven by center-aisle resets.
Supermarkets & Hypermarkets generate the largest channel turnover because national grocery chains have expanded prebiotic sodas from four-foot refrigerated produce endcaps into ambient center-store carbonated beverage aisles. Stocking 4-can and 12-can paperboard multipacks alongside probiotic wellness drinks lowers the retail unit price from USD 2.79 per single cold can to USD 1.99 to USD 2.25 per can in family pantry packs. Convenience stores and gas stations capture immediate single-serve impulse trials, while direct-to-consumer online subscriptions serve flavor-discovery buyers in secondary postal codes.
- Supermarkets & Hypermarkets are anticipated to represent 43.9% of distribution channel sales in 2026, driven by ambient multipack merchandising and grocery loyalty promotions.
- In February 2025, The Coca-Cola Company launched Simply Pop, its first prebiotic soda formulated with 6 grams of chicory root fiber and real fruit juice, rolling out across major regional grocery supermarkets and online retail in the United States [5].
What are the drivers, restraints, and opportunities in the prebiotic soda market?
In the Prebiotic Soda Market, public dietary-fiber deficits and sugar-reduction mandates accelerate retail adoption, whereas rapid colonic fructan fermentation limits high-dose intake among sensitive drinkers, and multi-fiber blends plus fountain partnerships unlock foodservice scale through 2036.
- Driver:Widespread dietary fiber shortfalls and front-of-package added-sugar warnings push households to swap full-sugar colas for fiber-fortified sparkling refreshments.
- Restraint:Rapid colonic fermentation of short-chain fructans above 8 to 10 grams per serving can trigger transient osmotic gas in FODMAP-sensitive consumers and stricter EU health-claim scrutiny.
- Opportunity:Formulating slow-fermenting resistant dextrin and acacia-fiber complexes alongside fast-casual restaurant fountain syrups expands daily consumption occasions.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Public health nutrition guidance targeting chronic dietary fiber deficits and free-sugar overconsumption serves as the primary structural catalyst for prebiotic soda adoption. In January 2026, the World Health Organization updated its Healthy Diet guidance confirming that adult diets should restrict free sugars to below 10% of total energy intake, and ideally under 5%, while consuming at least 25 grams of naturally occurring dietary fiber daily [6]. Because legacy 355 ml soft drinks contain 35 to 40 grams of added sugar and zero fiber, beverage shoppers increasingly purchase low-calorie prebiotic sodas and fermented probiotic beverages to close up to one-third of their daily fiber gap during routine lunch and dinner occasions.
Risk Assessment of the Prebiotic Soda Market: Operational and Supply Friction
Gastrointestinal tolerance ceilings on short-chain inulin-type fructans and strict regulatory health-claim thresholds constrain aggressive single-can fiber dosing and on-pack marketing. Under the European Food Safety Authority's scientific opinion pursuant to Article 13.5 of Regulation (EC) No 1924/2006, native chicory inulin substantiates a normal-defecation health claim only when consumers ingest at least 12 grams daily [7]. However, formulating 12 grams of fast-fermenting chicory oligofructose into a single 355 ml carbonated can causes luminal gas accumulation and abdominal distension in consumers with irritable bowel sensitivity, while low-pH storage below pH 3.2 slowly hydrolyzes fructan chains into fructose during warm summer transit. Consequently, beverage chemists blending cognitive performance functional beverage additive systems with prebiotics must cap short-chain inulin doses or buffer beverage acidity.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Beverage formulators are unlocking repeat daily consumption by replacing single-source chicory inulin with multi-stage fiber complexes, pairing slow-fermenting resistant tapioca dextrin and acacia gum with botanical extracts, while expanding into foodservice fountain dispensing and convenience coolers. In June 2025, Keurig Dr Pepper's inaugural State of Beverages Trend Report documented that 44% of Americans and 72% of Generation Z consumers actively try new functional and dirty-soda flavor combinations each month [8]. Furthermore, Keurig Dr Pepper's May 2026 State of Beverages Trend Report confirmed that younger beverage buyers treat functional drink customization as a primary daily ritual across both retail and quick-service foodservice outlets [9]. Co-packers that engineer low-viscosity prebiotic syrups compatible with post-mix restaurant fountain valves and non-dairy probiotic drinks or sparkling kombucha lines can capture high-volume foodservice contracts through 2036.
Prebiotic Soda Market by Country (2026 to 2036)
In the FMI report, Japan posts the fastest growth among the six evaluated countries at a 22.4% CAGR from 2026 to 2036, followed by the USA at 20.9%, South Korea at 19.4%, Canada at 17.6%, and Sweden at 16.1%, while New Zealand records a 15.2% CAGR. Across these national markets, expansion rates reflect functional food regulatory pathways, front-of-package sugar labeling enforcement, convenience-store cold-vault density, and multinational direct-store-delivery distribution.
Table 7: Country CAGR and Primary Growth Levers for the Prebiotic Soda Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 22.4% | Foods with Function Claims (FFC) indigestible-dextrin sodas and nationwide vending and konbini distribution |
| USA | 20.9% | Multinational bottler M&A (PepsiCo-poppi, Coca-Cola Simply Pop) and ambient supermarket center-aisle resets |
| South Korea | 19.4% | MFDS functional food labeling reforms and convenience-store zero-sugar sparkling fiber drink velocity |
| Canada | 17.6% | Mandatory January 2026 Health Canada front-of-package high-sugar warning symbols accelerating shelf swaps |
| Sweden | 16.1% | Livsmedelsverket low-sugar dietary guidelines and closed-loop Returpack slim aluminum can circularity |
| New Zealand | 15.2% | Indigenous kiwifruit and botanical soluble fiber integration and trans-Tasman grocery export canning |
Source: Future Market Insights analysis
Japan Prebiotic Soda Market Outlook (2026 to 2036)
Decades of regulatory familiarity with Foods for Specified Health Uses (FOSHU) and dense street-level vending machine infrastructure distinguish Japan's functional carbonated beverage sector from Western grocery markets. On October 1, 2025, Japan's Consumer Affairs Agency enforced updated notification and PRISMA-2020 systematic-review rules for Foods with Function Claims (FFC), standardizing post-prandial triglyceride and bowel-regularity claims for beverages formulated with indigestible dextrin [10]. Sales of prebiotic soda in Japan are forecast to expand at a 22.4% CAGR through 2036 as convenience chains stock zero-calorie fiber colas and yuzu spritzers. While a shrinking working-age population and higher aluminum coil import costs squeeze domestic canning margins, Japanese beverage groups are reformulating iconic legacy sodas with resistant dextrin to capture daily commuter purchases.
Key takeaway: In Japan, updated Consumer Affairs Agency functional-claim rules and high-turnover convenience and vending channels drive the fastest national expansion globally through 2036.
USA Prebiotic Soda Market Outlook (2026 to 2036)
Billion-dollar soft-drink acquisitions and nationwide direct-store-delivery cold networks make the United States the largest revenue anchor for commercial prebiotic sodas. By 2036, the USA is projected to grow at a 20.9% CAGR as national grocers and club stores allocate full center-aisle bays to 12-can functional variety packs. Under the U.S. Food and Drug Administration's dietary fiber science review (21 CFR 101.9(c)(6)(i)), eight isolated non-digestible carbohydrates, including inulin and resistant maltodextrin, carry authorized Nutrition Facts fiber status for beverage formulators [11]. Yet commercial uptake faces friction from class-action consumer litigation challenging gut-health efficacy on low-fiber cans and USD 2.49 single-can price points. American beverage conglomerates are consequently blending multi-source prebiotic fibers and scaling high-speed co-packing lines to narrow retail price gaps.
Key takeaway: In the USA, multinational bottler buyouts and FDA-recognized dietary fiber labeling propel prebiotic sodas from natural perimeter coolers into mainstream center-store aisles.
South Korea Prebiotic Soda Market Outlook (2026 to 2036)
Round-the-clock urban convenience store merchandising and the domestic 'helth-pleasure' zero-sugar movement shape South Korea's functional sparkling drink landscape. According to the April 2026 USDA Foreign Agricultural Service and Ministry of Food and Drug Safety (MFDS) market brief (Report KS2026-0003), South Korea's health functional food sector exceeded USD 4.18 billion in baseline retail turnover as regulators expanded functional ingredient permissions inside general packaged beverages [12]. The South Korea prebiotic soda sector is projected to record a 19.4% CAGR from 2026 to 2036. However, fierce cooler-door competition from zero-calorie carbonated teas and imported allulose and chicory inulin customs duties compress independent brand margins. Korean beverage formulators are therefore pairing polydextrose with domestic Jeju citrus and Maesil plum extracts to win convenience-chain exclusives.
Key takeaway: In South Korea, MFDS functional-labeling flexibility for general beverages and dense urban convenience retail sustain rapid youth adoption of zero-sugar prebiotic sodas.
Canada Prebiotic Soda Market Outlook (2026 to 2036)
Mandatory federal front-of-package warning symbols on high-sugar beverages fundamentally alter retail category management across Canadian provinces. As enforced by Health Canada under the Food and Drug Regulations effective January 1, 2026, prepackaged beverages reaching or exceeding 15% of the Daily Value for sugars must display a black-and-white magnifying glass 'High in Sugars' symbol on the principal display panel [13]. Demand across the Canada prebiotic soda sector is expected to increase at a 17.6% CAGR through 2036 as grocery banners swap flagged legacy sodas for low-sugar fiber drinks. Nonetheless, bilingual English-French labeling compliance and long refrigerated cross-country freight corridors raise landed unit costs. Canadian beverage brands are partnering with Ontario and Quebec contract canners to localize organic agave-inulin soda production.
Key takeaway: In Canada, Health Canada's January 2026 front-of-package sugar symbol enforcement accelerates supermarket shelf reallocation toward low-sugar prebiotic sodas.
Sweden Prebiotic Soda Market Outlook (2026 to 2036)
Nordic public-health sugar curtailment and closed-loop deposit-return can recycling govern functional beverage procurement across Sweden. In January 2026, the Swedish National Food Agency (Livsmedelsverket) reinforced its national adult dietary guidelines advising citizens to sharply limit sugar-sweetened soft drinks while prioritizing fiber-rich plant nutrition to curb metabolic disease [14]. In Sweden, demand for prebiotic soda is predicted to advance at a 16.1% CAGR through 2036 as urban grocery shoppers adopt clean-label lingonberry, elderflower, and citrus fiber spritzers. The central commercial obstacle involves strict European Union nutrition-claim prohibitions on using the term 'prebiotic' as an unauthorized health claim on retail labels. Swedish beverage startups navigate this rule by highlighting exact grams of chicory root fiber per Returpack-registered slim aluminum can.
Key takeaway: In Sweden, Livsmedelsverket sugar-reduction guidelines and high-return aluminum can deposit loops support steady supermarket adoption of botanical fiber sodas.
New Zealand Prebiotic Soda Market Outlook (2026 to 2036)
Export-focused horticultural bioactives and high per-capita craft beverage innovation distinguish New Zealand's functional soda sector within Oceania. In January 2026, Stats NZ Tatauranga Aotearoa reported that New Zealand's annual goods exports reached NZD 80.0 billion in 2025, led by primary food, kiwifruit, and horticultural commodities that supply domestic beverage processors with gold and green kiwifruit soluble fibers [15]. New Zealand's prebiotic soda outlook is anticipated to advance at a 15.2% CAGR over the assessment period as local canners scale feijoa, boysenberry, and kiwifruit-pectin sparkling sodas. Nevertheless, a compact domestic population of 5.3 million and concentrated supermarket duopoly buying power cap standalone domestic volume. Consequently, Auckland and Bay of Plenty functional beverage makers target trans-Tasman supermarket chains across eastern Australia.
Key takeaway: In New Zealand, domestic kiwifruit-fiber valorization and trans-Tasman export canning agreements anchor a 15.2% annual growth trajectory through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the prebiotic soda market?
PepsiCo, Inc. (poppi), OLIPOP Inc., The Coca-Cola Company (Simply Pop), Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Constellation Brands, Inc., and wildwonder are the notable companies in the prebiotic soda market.
Competitive positioning in the prebiotic soda sector is defined by multi-fiber formulation stability, nostalgic flavor accuracy, high-speed slim-can co-packing capacity, and direct-store-delivery cold-vault access. Category pioneers OLIPOP Inc. and poppi (acquired by PepsiCo, Inc. in May 2025) established the modern center-aisle functional soda tier by combining chicory root inulin, cassava dextrin, and apple cider vinegar with sub-5-gram sugar profiles. Multinational soft drink leaders The Coca-Cola Company (via Simply Pop) and Keurig Dr Pepper Inc. deploy nationwide bottling and cold-drink distribution networks to scale functional sparkling lines across supermarkets and convenience stores. Meanwhile, Suntory Holdings Limited leads FOSHU and FFC dextrin-fortified sparkling drinks across Asia-Pacific, while Molson Coors Beverage Company, Constellation Brands, Inc., and synbiotic pioneer wildwonder expand specialty and beyond-beer distribution.
- Multinational Soft Drink & Acquired Category Leaders: PepsiCo, Inc. (poppi), The Coca-Cola Company (Simply Pop), and Keurig Dr Pepper Inc. pair national grocery and convenience cold-vault distribution with dedicated functional soda brands.
- Dedicated Prebiotic & Synbiotic Soda Pioneers: OLIPOP Inc. and wildwonder formulate multi-botanical prebiotic and probiotic sparkling beverages with clinical microbiome research and omnichannel club-store reach.
- Global Brewing & Functional Beverage Conglomerates: Suntory Holdings Limited, Molson Coors Beverage Company, and Constellation Brands, Inc. leverage FOSHU dextrin science, non-alcoholic incubator investments, and beer distributor networks.
Competitive Benchmarking: Prebiotic Soda Market
Table 8: Competitive Benchmarking for the Prebiotic Soda Market (qualitative capability ratings), 2026
| Company | Prebiotic Fiber Formulation | Nostalgic Flavor Parity | Slim-Can Co-Packing Scale | Global Retail Distribution |
|---|---|---|---|---|
| PepsiCo, Inc. (poppi) | High | High | High | High |
| OLIPOP Inc. | High | High | High | Medium |
| The Coca-Cola Company (Simply Pop) | High | High | High | High |
| Keurig Dr Pepper Inc. | Medium | High | High | High |
| Suntory Holdings Limited | High | Medium | High | High |
| Molson Coors Beverage Company | Medium | Medium | High | High |
| Constellation Brands, Inc. | Medium | Medium | High | Medium |
| wildwonder | High | Medium | Medium | Medium |
Scoring basis: Prebiotic Fiber Formulation is rated High for validated multi-fiber or resistant-dextrin blends delivering 5 to 9 grams of soluble fiber per 355 ml serving with ambient pH stability. Nostalgic Flavor Parity reflects documented sensory matching of classic cola, root beer, and citrus profiles at under 5 grams of sugar. Slim-Can Co-Packing Scale and Global Retail Distribution evaluate annual multi-million-case canning throughput and direct-store-delivery grocery and convenience reach.
Key Developments in the Prebiotic Soda Market
- In February 2026, Keurig Dr Pepper Inc. unveiled its 2026 refreshment innovation slate, expanding zero-sugar and functional dirty-soda and fruit-inspired beverage varieties across North American retail channels [16].
- In March 2025, PepsiCo, Inc. entered into a definitive agreement to acquire prebiotic soda brand poppi for USD 1.95 billion (net purchase price USD 1.65 billion after anticipated tax benefits), closing the transaction in May 2025 [17].
- In February 2025, OLIPOP Inc. secured USD 50 million in Series C financing led by J.P. Morgan Private Capital Growth Equity Partners at a USD 1.85 billion valuation to expand ambient multipack distribution and convenience-store cold coolers [18].
Key Players in the Prebiotic Soda Market
Multinational Soft Drink & Acquired Category Leaders
- PepsiCo, Inc. (poppi)
- The Coca-Cola Company (Simply Pop)
- Keurig Dr Pepper Inc.
Dedicated Prebiotic & Synbiotic Soda Pioneers
- OLIPOP Inc.
- wildwonder
Global Brewing & Functional Beverage Conglomerates
- Suntory Holdings Limited
- Molson Coors Beverage Company
- Constellation Brands, Inc.
Prebiotic Soda Market - Report Scope
Table 9: Report Scope for the Prebiotic Soda Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety / Flavor; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Million |
| Market Definition | Encompasses global manufacturer and brand-owner wholesale revenues from commercial packaged carbonated non-alcoholic soft drinks formulated with verified prebiotic dietary fibers (inulin, oligofructose, resistant dextrins, galactooligosaccharides, and botanical soluble fibers) designed to selectively nourish beneficial gastrointestinal microbiota. Category Scope Note: Market valuation reflects finished commercial packaged carbonated prebiotic soft drinks sold across retail, convenience, foodservice, and direct-to-consumer channels; upstream business-to-business sales of bulk prebiotic fiber powders and syrups to beverage co-packers represent an ingredient input tier tracked separately outside finished beverage valuation to prevent double-counting. Excludes uncarbonated prebiotic juices, dry fiber supplement powders, dairy drinking yogurts, and standard high-sugar carbonated soft drinks. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, USA, South Korea, Canada, Sweden, New Zealand, and additional countries in the full report |
| Key Companies Covered | PepsiCo, Inc. (poppi), OLIPOP Inc., The Coca-Cola Company (Simply Pop), Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Constellation Brands, Inc., wildwonder |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Prebiotic Soda Market - Research Methodology
Table 10: Research Methodology for the Prebiotic Soda Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with functional beverage formulation chemists, contract cannery operations directors, soluble fiber ingredient suppliers, supermarket beverage category buyers, and direct-store-delivery distributors to validate per-can fiber dosing, pH hydrolysis stability, wholesale realization, and center-aisle scan velocities. |
| Secondary Research | Secondary research included analysis of U.S. FDA, Health Canada, EFSA, Japan CAA, and South Korea MFDS dietary fiber and functional labeling regulations, WHO nutrition guidelines, Aluminum Association recycling reports, corporate M&A disclosures, and peer-reviewed microbiome studies. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using bottom-up contract canning volume and retail door-count modeling integrated with top-down carbonated soft drink substitution rates across evaluated regions. |
| Data Triangulation and Validation | Data points were cross-verified against commercial chicory inulin and resistant dextrin beverage shipments, sleek aluminum can deliveries, supermarket multi-pack scanner disclosures, and corporate financial filings without double-counting upstream ingredient sales. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's functional beverage econometric model, calibrating national trajectories against the 18.5% global baseline using national functional-claim regulatory elasticity (Japan FFC/FOSHU, South Korea MFDS), mandatory sugar warning policies (Health Canada FOP 2026), and convenience/grocery cold-vault penetration. |
| Operational Benchmark Traceability | Operational benchmarks (packaged 355 ml unit volumes, formulated soluble fiber tonnage, and average wholesale realization per can in Tables 2, 3, and 4) are synthesized from FDA 21 CFR 101.9 dietary fiber dosing standards, Aluminum Association container data, and corporate transaction disclosures. |
Prebiotic Soda Market by Segments
Prebiotic Soda Market segmented by Product Variety / Flavor:
- Flavored / Botanical Infusion
- Classic Nostalgic Soda Profiles (Cola, Root Beer & Ginger Ale)
- Zero-Sugar / Sugar-Free Variant
Prebiotic Soda Market segmented by Packaging Format:
- Slim Aluminum Cans
- Standard 355ml Aluminum Cans
- Glass Bottles
- Recyclable PET Bottles
Prebiotic Soda Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Prebiotic Soda Market by Region
- North America
- USA
- Canada
- East Asia
- Japan
- South Korea
- China
- Western Europe
- Sweden
- UK
- Germany
- France
- Netherlands
- South Asia and Pacific
- New Zealand
- Australia
- Singapore
- Latin America
- Brazil
- Mexico
- Eastern Europe
- Poland
- Czechia
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Gibson, G. R., Hutkins, R., Sanders, M. E., Prescott, S. L., Reimer, R. A., Salminen, S. J., Scott, K., Stanton, C., Swanson, K. S., Cani, P. D., Verbeke, K., & Reid, G. (2025, June 21). Expert consensus document: The International Scientific Association for Probiotics and Prebiotics (ISAPP) consensus statement on the definition and scope of prebiotics. International Scientific Association for Probiotics and Prebiotics (ISAPP).
- [2] U.S. Food and Drug Administration (FDA). (2024, July 25). Questions and Answers on Dietary Fiber. U.S. Food and Drug Administration.
- [3] PepsiCo, Inc. (2025, May 19). PepsiCo Completes Acquisition of poppi, Accelerating Strategic Portfolio Transformation. PepsiCo Newsroom.
- [4] The Aluminum Association & Can Manufacturers Institute. (2025, March 18). Aluminum Beverage Can Moves from Recycling Bin to Newly Formed Can in Less than 60 Days. The Aluminum Association.
- [5] The Coca-Cola Company. (2025, February 18). Simply Brings a Juicy Pop to Booming Prebiotic Soda Category. The Coca-Cola Company Media Center.
- [6] World Health Organization (WHO). (2026, January 26). Healthy diet. World Health Organization Fact Sheets.
- [7] EFSA Panel on Dietetic Products, Nutrition and Allergies (NDA). (2015, January 09). Scientific Opinion on the substantiation of a health claim related to “native chicory inulin” and maintenance of normal defecation by increasing stool frequency pursuant to Article 13.5 of Regulation (EC) No 1924/2006. EFSA Journal.
- [8] Keurig Dr Pepper Inc. (2025, June 11). Keurig Dr Pepper Unveils First-Ever State of Beverages Report. Keurig Dr Pepper Newsroom.
- [9] Keurig Dr Pepper Inc. (2026, May 06). Keurig Dr Pepper's 2026 State of Beverages Trend Report Reveals Gen Z's Drink Choice Is Now a Form of Self-Expression. Keurig Dr Pepper Newsroom.
- [10] Consumer Affairs Agency, Government of Japan (CAA). (2025, November 07). A Complete Overview of the Latest Notices on Foods with Function Claims in Japan. ChemLinked Food Regulatory Database / Consumer Affairs Agency (CAA).
- [11] U.S. Food and Drug Administration (FDA). (2018, June 14). FDA Issues Guidance, Science Review, and Citizen Petition Responses on Dietary Fiber. U.S. Food and Drug Administration.
- [12] USDA Foreign Agricultural Service (FAS) & Ministry of Food and Drug Safety (MFDS). (2026, April 06). Report Name: Health Functional Food and Supplements - Market Brief for the Republic of Korea. USDA Foreign Agricultural Service GAIN System (KS2026-0003).
- [13] Health Canada. (2026, August 14). Nutrition labelling: Front-of-package nutrition symbol. Government of Canada.
- [14] Swedish National Food Agency (Livsmedelsverket). (2026, January 26). Food that makes a difference for your health - simple advice for a healthier life. Livsmedelsverket.
- [15] Stats NZ Tatauranga Aotearoa. (2026, January 29). New Zealand's annual exports reach $80 billion. Stats NZ.
- [16] Keurig Dr Pepper Inc. (2026, February 18). Keurig Dr Pepper Announces Flavorful New Innovation Across Its Refreshment Portfolio. Keurig Dr Pepper Newsroom.
- [17] PepsiCo, Inc. (2025, March 17). PepsiCo to Acquire poppi. PepsiCo Newsroom.
- [18] OLIPOP Inc. (2025, February 13). Olipop Valued at $1.85 Billion, Secures $50 Million in Series C Funding. Nutraceuticals World.
- [19] Container Recycling Institute (CRI). (2025, January 09). Improving Efficiency and Sustainability in Aluminum Beverage Can Recycling. Container Recycling Institute.
- [20] Molson Coors Beverage Company. (2025, January 09). From beer to energy: checking in on Molson Coors' non-alc portfolio. Molson Coors Beer & Beyond.
- [21] Suntory Beverage & Food Limited. (2026, August 06). Suntory Beverage & Food: Financial Results for FY2026 Q2. Suntory Holdings News Release.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the prebiotic soda market in 2026 and what is forecast for 2036?
- Which dietary fiber and sugar-reduction pressures support demand for prebiotic sodas?
- Why does Flavored / Botanical Infusion lead the product variety / flavor category?
- Why do Slim Aluminum Cans lead the packaging format category globally?
- How do growth rates differ across Japan, the USA, South Korea, Canada, Sweden, and New Zealand?
- Which leading beverage companies formulate and distribute prebiotic sodas today?
- What limits high-dose fiber formulation or health-claim labeling in the prebiotic soda market?
- What should grocery and foodservice buyers evaluate before authorizing a prebiotic soda supplier?
Frequently Asked Questions
How big is the prebiotic soda market in 2026, and what is forecast for 2036?
Global prebiotic soda sales are estimated to reach USD 850.0 million in 2026, rising from USD 717.3 million in 2025. The sector is projected to expand further and attain USD 4,640.9 million by 2036 as supermarkets move fiber-fortified sparkling drinks into ambient center-store aisles.
What CAGR is forecast for the Prebiotic Soda Market through 2036?
As per FMI, the prebiotic soda market is projected to grow at an 18.5% CAGR from 2026 to 2036. Expansion is supported by multinational soft-drink acquisitions, front-of-package added-sugar warnings, and rising consumer intake of soluble dietary fiber.
Which product variety / flavor holds a notable prebiotic soda demand share in 2026?
Flavored / Botanical Infusion is projected to hold 45.4% of product variety / flavor demand in 2026. The segment benefits from natural fruit-acid balance that complements chicory root inulin and apple cider vinegar at under 5 grams of sugar.
Which packaging format segment holds a notable prebiotic soda share in 2026?
Slim Aluminum Cans are estimated to account for 39.3% of packaging format revenue in 2026. Demand is supported by high cold-cooler facing density, hermetic oxygen protection, and closed-loop aluminum can recycling.
Which country has a notable prebiotic soda expansion outlook during the forecast period?
FMI finds that Japan is forecast to expand at a 22.4% CAGR during the 2026 to 2036 assessment period. Growth is supported by Consumer Affairs Agency Foods with Function Claims (FFC) notifications for indigestible-dextrin sodas and dense vending machine distribution.
Which companies are active in the Prebiotic Soda Market during 2026?
Notable market participants include PepsiCo, Inc. (poppi), OLIPOP Inc., The Coca-Cola Company (Simply Pop), Keurig Dr Pepper Inc., Suntory Holdings Limited, Molson Coors Beverage Company, Constellation Brands, Inc., and wildwonder. These producers focus on multi-fiber pH stability, nostalgic low-sugar flavor replication, and national grocery multipack distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety / Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Variety / Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Variety / Flavor, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Nostalgic Soda Profiles (Cola, Root Beer & Ginger Ale)
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety / Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety / Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- Standard 355ml Aluminum Cans
- Glass Bottles
- Recyclable PET Bottles
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- East Asia
- Western Europe
- South Asia and Pacific
- Latin America
- Eastern Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Sweden
- UK
- Germany
- France
- Netherlands
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- New Zealand
- Australia
- Singapore
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czechia
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- PepsiCo, Inc. (poppi)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- OLIPOP Inc.
- The Coca-Cola Company (Simply Pop)
- Keurig Dr Pepper Inc.
- Suntory Holdings Limited
- Molson Coors Beverage Company
- Constellation Brands, Inc.
- wildwonder
- PepsiCo, Inc. (poppi)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


