
- Market Size (2026)
- USD 99.5 Bn
- Forecast (2036)
- USD 160.6 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Starch Derivatives Market in 2026?
Demand for starch derivatives is projected to expand at 4.9% CAGR between 2026 and 2036. Industry value grows from USD 94.9 billion in 2025 to USD 99.5 billion in 2026 and is projected to reach USD 160.6 billion by 2036.
Increasing production of processed food, beverages, paper and fermentation products is surging the demand for starch derivatives across the globe. In May 2026, the U.S. Department of Agriculture reported that corn supplies more than 95% of U.S. feed-grain production and use. Wet milling of this large corn base produces glucose, dextrose, starch, corn oil and alcohol which are used across food and industrial applications. Availability of established wet-milling facilities is supporting regular supply of standard grades. Apart from that, demand for clean-label and process-tolerant grades is increasing as manufacturers are looking for ingredients that can maintain texture and stability during processing. However, buyers generally require consistent batches, documents and formulation support before replacing an approved ingredient, which makes technical service an important factor in the market.
Regional demand trajectories diverge across geographies based on feedstock availability and end-use manufacturing presence. Germany is projected to grow at 6.1% CAGR, while the USA is forecast at 5.7% through 2036. In January 2026, Destatis reported 2025 German harvests of 23.152 million tonnes of wheat and 4.945 million tonnes of grain maize. In February 2025, Ingredion announced more than USD 100 million for its Indianapolis texture facility. Availability of different starch crops is supporting source flexibility in Germany, whereas large wet-milling base and increasing specialty capacity is driving the USA market. In both the countries, consistent quality and suitability with the production process remains a major requirement for purchasing.
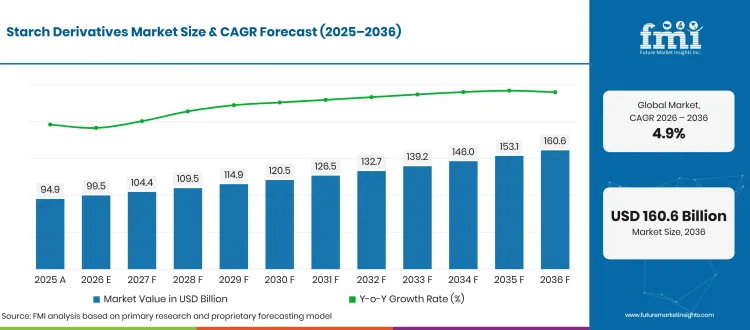
Key Takeaways of Starch Derivatives Market
- Repeated food and industrial use supports demand because starch derivatives perform recurring sweetening, bulking, binding, and texture functions.
- Based on product type, glucose syrup is projected to account for 69.0% in 2026, driven by bulk sweetening and fermentation uses.
- By function, thickener is estimated to hold 33.2% in 2026, supported by recurring viscosity and water-control needs.
- In 2026, corn is expected to lead source revenue with 39.8% share, owing to established wet-milling infrastructure.
- Germany is projected at 6.1% CAGR, while the USA is forecast at 5.7% through 2036 because their processing bases differ.
- Notable companies include Ingredion, Cargill, ADM, Roquette, Tate & Lyle, Avebe, Emsland Group, AGRANA, and Grain Processing Corporation.
Analyst Perspective
“Increasing food and industrial use will continue to support starch derivatives demand. In my experience, clean-label starches are expected to create new growth opportunities for manufacturers.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Starch Derivatives Market segmented?
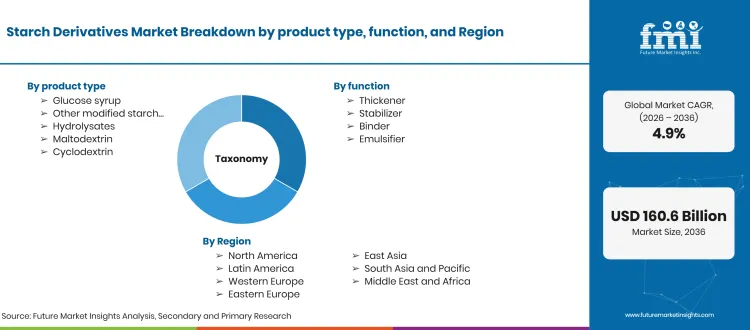
Starch derivatives market is segmented by four primary commercial axes and region: product type, function, source, application, and region. Glucose syrup, thickener, corn, and food and beverages are projected to hold their respective leading shares in 2026.
- By product type: glucose syrup, other modified starches, hydrolysates, maltodextrin, and cyclodextrin.
- By function: thickener, stabilizer, binder, and emulsifier.
- By source: corn, wheat, potato, tapioca, others, and sorghum.
- By application: food and beverages, pharmaceuticals, cosmetics, paper, bio-ethanol, others, and animal feed.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does glucose syrup retain notable product type demand?
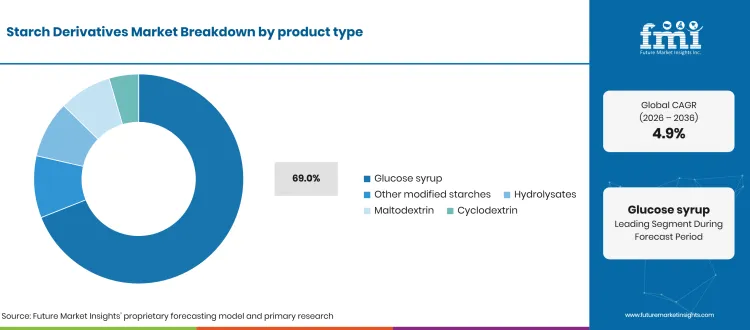
Based on product type, glucose syrup is projected to account for 69.0% in 2026, driven by bulk sweetening and fermentation demand.
Glucose syrup is one of the major products obtained from starch hydrolysis and is highly used for sweetening, fermentation and providing solids in several formulations. Buyers can select glucose syrup on the basis of solids and dextrose equivalent without changing the main conversion process. Japan’s February 2026 starch outlook placed saccharification demand at 1.655 million tonnes for the 2025 starch year. This large demand for saccharification is expected to support the consumption of glucose syrup during the forecast period. Dextrose and glucose streams are also supplied as fermentation ingredients for cultured products and industrial bioprocessing.
- Glucose syrup is projected at 69.0% because bulk liquid supply fits continuous processing.
- Saccharification demand shows the operating scale available to hydrolyzed starch products.
What supports thickener as the preferred functional category?
By function, thickener is estimated to hold 33.2% in 2026, supported by repeated viscosity and water-management requirements.
Increasing requirement for controlling viscosity, water and final texture in food and industrial products is boosting the demand for starch derivatives as thickeners. Food manufacturers test the grades against temperature, shear and storage conditions before using them in production. Functional starches compete within food texturizing agents when viscosity must survive heating and filling.
- Thickener is estimated at 33.2% because viscosity control is tested directly on production lines.
- In February 2025, Ingredion announced USD 50 million for specialized industrial starch capacity at Cedar Rapids. Expansion of starch capacity for paper and packaging applications is also expected to support the thickener segment.
How does corn meet changing source requirements in this market?
In 2026, corn is expected to lead source revenue with 39.8% share, owing to established wet-milling conversion capacity.
Corn is widely used for the production of starch derivatives as it can be processed through an integrated wet-milling chain. The starch separated from corn is further converted into glucose, dextrose and several other derivatives used in food, fermentation, paper and industrial products. USDA reported that food, seed and industrial uses represent nearly 60% of U.S. domestic corn use. Availability of large corn processing facilities and several derivative streams from the same feedstock is anticipated to keep corn as the leading source in the market. Bio-ethanol connects corn conversion with fuel production while remaining a separate application route.
- Corn is expected to hold 39.8% because one milling base supplies several derivative streams.
- Integrated wet milling reduces the need for separate upstream systems for each derivative.
Why are food and beverages central to application demand?
By application, food and beverages are forecast to represent 54.1% in 2026, due to recurring formulation and processing use.
Food and beverage manufacturers are increasingly using starch derivatives for sweetness, texture, stability, bulking and carrier functions. A single processing facility may use different starch derivatives according to the requirement of the final product. Sweetening demand also connects starch hydrolysis with broader food ingredients demand across beverages and confectionery. In July 2026, ONS reported that food manufacturing represented 22.9% of UK manufacturers’ sales during 2025. Large production of processed food and beverages is creating repeated requirement for qualified starch ingredients, which is expected to drive the application segment. Maltodextrins support carrier and bulking needs within food processing ingredients used in dry and liquid systems.
- Food and beverages are forecast at 54.1% because several functions enter routine formulations.
- Large food output keeps ingredient qualification and replenishment activity in regular production.
What are the drivers, restraints, and opportunities in the Starch Derivatives Market?
In the starch derivatives market, the key driver is processed-food output, the key restraint is qualification and feedstock variation, and the key opportunity is clean-label functionality.
- Driver: High-throughput food and industrial processing expands repeat demand for sweetening, binding, bulking, and texture functions.
- Restraint: Source variation and production-line qualification can delay substitution and increase the effective cost of switching.
- Opportunity: Functional native starches can replace selected modified starches or hydrocolloids when they preserve process performance.
Food Output Sustains Routine Ingredient Use
Increasing production of processed food is one of the prominent factors driving the starch derivatives market. These ingredients are consumed in every production cycle for sweetening, bulking, binding and texture purposes. In May 2026, South Korea’s Ministry of Food and Drug Safety reported that 2025 food-industry production increased 4.3% from the prior year. Large food production is supporting regular use of glucose syrups, maltodextrins and functional starches. Once the product is approved and provides required result in every batch, it generally remains in the regular purchasing schedule of food manufacturers. Plant-based foods create additional texture work for starch systems used in dairy alternatives and confectionery.
Crop Variation Extends Qualification Work
Variation in corn, wheat, potato or tapioca can change the viscosity, clarity and tolerance of starch during heat and shear. In April 2025, Avebe reported 20.4% average starch content for potatoes processed at its Dutch sites, while the campaign recorded 4.7% average tare percentage. Such variation can affect available specification and processing behavior of starch. Therefore, manufacturers may have to test the replacement grade again before commercial adoption, which increases qualification time and can restrain fast switching between suppliers. Technical starch demand also overlaps with paper chemicals used for coating, binding, and surface strength.
Clean Labels Open Replacement Routes
Growing preference for clean-label food products is creating new opportunities for functional native starches. These starches can simplify the ingredient declaration while maintaining texture and stability in selected applications. In January 2026, Emsland Group introduced Emjel LC 15 for vegan and vegetarian jellies and gums. The starch supports atmospheric cooking and protects sensitive ingredients from higher processing temperatures. However, the finished product is required to maintain shape, clarity and storage stability, due to which application testing remains important before adoption. The replacement route connects functional native starch with clean-label ingredients used in reformulated foods.
Which country CAGRs are profiled in the Starch Derivatives Market?
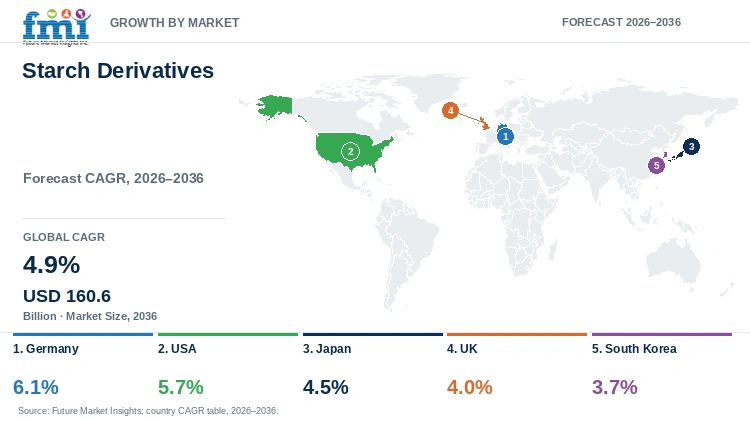
| Country | CAGR |
|---|---|
| Germany | 6.1% |
| USA | 5.7% |
| Japan | 4.5% |
| UK | 4.0% |
| South Korea | 3.7% |
How do country-level CAGRs compare in the starch derivatives market?
Starch derivatives demand varies according to availability of corn, wheat and potato along with the presence of food and technical processing industries. Germany and the USA has broader conversion base, whereas Japan, the UK and South Korea are supported by their specific food and industrial applications. Countries having domestic feedstock and wet-milling capacity can support larger production, while import-dependent countries remain more affected by international grain supply and freight conditions.
- Germany combines several starch crops with food and technical processing.
- USA demand benefits from corn wet milling and specialty capacity investment.
- Japan publishes a formal starch supply-demand outlook for major uses.
- UK demand is supported by a large food-manufacturing base.
- South Korea links ingredient demand to food production and exports.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- By 2036, Germany is projected to grow at 6.1% CAGR, supported by availability of wheat, maize and potato for starch production. In January 2026, Destatis reported that Germany harvested 13.871 million tonnes of potatoes and 23.152 million tonnes of wheat during 2025. Availability of different starch crops gives manufacturers options for food, paper and adhesive applications. Presence of food and technical processing industries is expected to support Germany starch derivatives market during the forecast period.
- Starch derivative demand in the USA is forecast to rise at 5.7% CAGR over the forecast period, driven by established corn wet-milling industry. In May 2026, USDA reported that ethanol accounts for nearly 45% of U.S. corn use, while food, seed and industrial uses account for close to 60% of domestic corn use. The same processing base produces starch, glucose, dextrose, corn oil and alcohol. Expansion of specialty food and industrial grades is expected to propel the USA market growth.
- Japan’s starch derivatives outlook is anticipated to advance at 4.5% CAGR over the assessment period, supported by planned starch supply and demand. In February 2026, MAFF forecast total starch demand of 2.399 million tonnes for the 2025 starch year. Modified starch was forecast at 240,000 tonnes and other uses at 505,000 tonnes. Large saccharification demand along with paper and food applications is expected to support starch derivatives demand in Japan.
- Adoption of starch derivatives in the UK is estimated to expand at 4.0% CAGR through 2036, owing to large food-manufacturing activity. In July 2026, ONS reported total manufacturers’ product sales of GBP 452.0 billion during 2025, of which food manufacturing accounted for 22.9%. Glucose syrups, maltodextrins and texturizing starches are used in several high-volume food formulations. Expansion of prepared food and beverage production is anticipated to support the UK market growth.
- Starch derivative sales in South Korea are forecast to expand at 3.7% CAGR by 2036, supported by food production and export-oriented manufacturing. In May 2026, the Ministry of Food and Drug Safety reported that 2025 food-industry production increased by 4.3%. Starch derivatives are used for sweetness, body, binding and shelf stability in processed food products. Growing food production is expected to upkeep starch derivative demand, although imported grain prices may affect the market growth. Selected pharmaceutical uses connect starch derivatives with pharmaceutical excipients requiring controlled quality and documented consistency, while animal feed remains another outlet where starch supports binding, carrier, and energy functions.
Who are the notable companies in the Starch Derivatives Market?
Notable companies include Ingredion Incorporated, Cargill Inc., Archer Daniels Midland Company, Roquette Freres, Tate & Lyle PLC, Avebe U.A., Emsland Group, AGRANA Group, and Grain Processing Corporation.
Starch derivatives market is moderately fragmented with the presence of integrated grain processors and specialty starch manufacturers. Ingredion, Cargill and ADM has broad corn-processing and ingredient operations, while Avebe and Emsland Group are mainly focused towards potato-based functionality. Roquette, Tate & Lyle and Grain Processing Corporation offers specialty starches, maltodextrins, syrup solids and excipient grades. Key manufacturers are increasing capacity, application testing and regional distribution in order to cater to the growing demand from food, paper, pharmaceutical and other technical applications.
- Integrated conversion platforms: Ingredion, Cargill, and ADM combine starch conversion with broad ingredient infrastructure.
- Specialty formulation groups: Roquette, Tate & Lyle, and Grain Processing Corporation focus on texture, maltodextrins, syrup solids, or excipients.
- Potato and multi-source specialists: Avebe, Emsland Group, and AGRANA use source expertise and regional processing positions.
Competitive Benchmarking: Starch Derivatives Market
| Company | Conversion breadth | Functional starch depth | Technical depth | Geographic reach |
|---|---|---|---|---|
| Ingredion Incorporated | High | High | High | High |
| Cargill Inc. | High | High | Medium | High |
| Archer Daniels Midland Company | High | High | High | High |
| Roquette Freres | High | High | High | High |
| Tate & Lyle PLC | Medium | High | Medium | High |
| Avebe U.A. | Low | High | High | Medium |
| Emsland Group | Low | High | Medium | Medium |
| AGRANA Group | High | High | Medium | Medium |
| Grain Processing Corporation | High | Medium | Medium | Medium |
High indicates broad current evidence, Medium indicates narrower documented coverage, and Low indicates limited breadth. Ratings describe public capability and do not measure quality or market share.
Key Developments in the Starch Derivatives Market
- In July 2026, Ingredion advanced its recommended acquisition of Tate & Lyle after shareholder approval. Completion remained subject to antitrust and court conditions.
- In March 2026, Roquette inaugurated a starch and polyol pilot center at Lianyungang. The facility brings together physicochemical analysis, laboratory research, and pilot-scale industrial transformation in a unified platform.
- In April 2026, Emsland Group launched Empet SmartBind for wet pet food. The starch system was developed to simplify texture formulation.
Key Players in the Starch Derivatives Market
Integrated Grain-Processing Platforms
- Ingredion Incorporated
- Cargill Inc.
- Archer Daniels Midland Company
Specialty Derivative and Excipient Formulators
- Roquette Freres
- Tate & Lyle PLC
- Avebe U.A.
Regional and Multi-Source Starch Specialists
- Emsland Group
- AGRANA Group
- Grain Processing Corporation
Starch Derivatives Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type, function, source, application, and region |
| Quantitative units | USD billion |
| Market definition | Revenue from glucose syrup, modified starch derivatives, hydrolysates, maltodextrin, and cyclodextrin sold into listed applications. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | Germany; USA; Japan; UK; South Korea |
| Forecast period | 2026 to 2036 |
| Approach | The Future Market Insights report covers segment structure, country conditions, company participation, and forecast estimates. |
Starch Derivatives Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, distributors, end users, procurement teams, and subject-matter experts. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, technical literature, filings, and official announcements. |
| Market Sizing and Forecasting | The market model combined baseline value, historical performance, segment structure, pricing, volume, adoption, and country demand. |
| Data Validation | Estimates were checked against public data, company activity, trade patterns, and industry developments. Forecasts are FMI proprietary estimates. |
Starch Derivatives Market by Segments
Starch derivatives market segmented by product type:
- Glucose syrup
- Other modified starches
- Hydrolysates
- Maltodextrin
- Cyclodextrin
Starch derivatives market segmented by function:
- Thickener
- Stabilizer
- Binder
- Emulsifier
Starch derivatives market segmented by source:
- Corn
- Wheat
- Potato
- Tapioca
- Others
- Sorghum
Starch derivatives market segmented by application:
- Food and beverages
- Pharmaceuticals
- Cosmetics
- Paper
- Bio-ethanol
- Others
- Animal feed
Starch Derivatives Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2026, May 7). Corn and Other Feed Grains: Feed Grains Sector at a Glance.
- [2] Statistisches Bundesamt. (2026, January 21). Anbauflächen, Hektarerträge und Erntemengen ausgewählter Anbaukulturen im Zeitvergleich.
- [3] Ingredion Incorporated. (2025, February 4). Ingredion invests USD 100 million in Indianapolis plant.
- [4] Ministry of Agriculture, Forestry and Fisheries, Japan. (2026, February 10). 2025 starch year supply and demand outlook.
- [5] Ingredion Incorporated. (2025, February 27). Ingredion invests USD 50 million in Cedar Rapids industrial starch capacity.
- [6] U.S. Department of Agriculture, Economic Research Service. (2026). U.S. domestic corn use and industrial processing.
- [7] Office for National Statistics. (2026, July 24). UK manufacturers’ sales by product: 2025.
- [8] Ministry of Food and Drug Safety, Republic of Korea. (2026, May 29). 2025 food-industry production results.
- [9] Avebe U.A. (2025, April 23). End of potato campaign 2024-2025.
- [10] Emsland Group. (2026, January 21). Emjel LC 15 sets a new standard for vegan and vegetarian jellies and gums.
- [11] Tate & Lyle PLC. (2026, July 28). Results of shareholder meetings for the recommended Ingredion acquisition.
- [12] Roquette Freres. (2026, April 6). Roquette inaugurates its starch and polyol pilot center at Lianyungang.
- [13] Emsland Group. (2026, April 2). Emsland Group enters wet pet-food market with Empet SmartBind.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Starch Derivatives Market during 2026?
- What value is the Starch Derivatives Market projected by 2036?
- Which product type holds notable Starch Derivatives Market share?
- Which function holds notable Starch Derivatives Market share?
- Which country has notable Starch Derivatives Market growth?
- Which companies are notable in Starch Derivatives Market today?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By product type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By product type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By product type, 2026 to 2036
- Glucose syrup
- Other modified starches
- Hydrolysates
- Maltodextrin
- Cyclodextrin
- Y-o-Y Growth Trend Analysis By product type, 2021 to 2025
- Absolute $ Opportunity Analysis By product type, 2026 to 2036
- Global Market Analysis and Forecast, By function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By function, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By function, 2026 to 2036
- Thickener
- Stabilizer
- Binder
- Emulsifier
- Y-o-Y Growth Trend Analysis By function, 2021 to 2025
- Absolute $ Opportunity Analysis By function, 2026 to 2036
- Global Market Analysis and Forecast, By source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By source, 2026 to 2036
- Corn
- Wheat
- Potato
- Tapioca
- Others
- Sorghum
- Y-o-Y Growth Trend Analysis By source, 2021 to 2025
- Absolute $ Opportunity Analysis By source, 2026 to 2036
- Global Market Analysis and Forecast, By application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By application, 2026 to 2036
- Food and beverages
- Pharmaceuticals
- Cosmetics
- Paper
- Bio-ethanol
- Others
- Animal feed
- Y-o-Y Growth Trend Analysis By application, 2021 to 2025
- Absolute $ Opportunity Analysis By application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By product type
- By function
- By source
- By application
- By Country
- Market Attractiveness Analysis
- By Country
- By product type
- By function
- By source
- By application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By product type
- By function
- By source
- By application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By product type
- By function
- By source
- By application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ingredion Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill Inc.
- Archer Daniels Midland Company
- Roquette Freres
- Tate & Lyle PLC
- Avebe U.A.
- Emsland Group
- AGRANA Group
- Grain Processing Corporation
- Ingredion Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by application, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by product type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by function, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by source, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by product type
- Figure 6: Global Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by function
- Figure 9: Global Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by source
- Figure 12: Global Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by application
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by product type
- Figure 29: North America Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by function
- Figure 32: North America Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by source
- Figure 35: North America Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by application
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by product type
- Figure 42: Latin America Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by function
- Figure 45: Latin America Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by source
- Figure 48: Latin America Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by application
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by product type
- Figure 55: Western Europe Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by function
- Figure 58: Western Europe Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by source
- Figure 61: Western Europe Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by application
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by product type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by function
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by source
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by application
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by product type
- Figure 81: East Asia Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by function
- Figure 84: East Asia Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by source
- Figure 87: East Asia Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by application
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by product type
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by function
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by source
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by application
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by product type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by product type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by product type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by function, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by function, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by function
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by source, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by source, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by source
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by application, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by application, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by application
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Starch Derivatives Market expected to be in 2026?
Future Market Insights estimates that the starch derivatives market will reach USD 99.5 billion in 2026. The market is projected to expand further and reach USD 160.6 billion by 2036.
What CAGR is forecast for the Starch Derivatives Market through 2036?
As per FMI, the starch derivatives market is projected to grow at a 4.9% CAGR from 2026 to 2036. Growth is supported by repeated food and industrial formulation demand.
Which product type holds a notable starch derivatives demand share in 2026?
Future Market Insights projects glucose syrup to hold 69.0% of product type revenue in 2026. The segment benefits from bulk sweetening and fermentation demand.
Which function holds a notable starch derivatives share in 2026?
FMI finds that thickener will hold 33.2% of function revenue in 2026. Demand is supported by recurring viscosity and water-control requirements.
Which country has a notable starch derivatives expansion outlook?
Future Market Insights predicts Germany to expand at a 6.1% CAGR during the 2026 to 2036 assessment period. Growth is supported by source diversity and established industrial processing.
Which companies are active in the Starch Derivatives Market during 2026?
As per FMI analysis, notable companies include Ingredion, Cargill, ADM, Roquette, Tate & Lyle, Avebe, Emsland Group, AGRANA, and Grain Processing Corporation. These companies are focusing on specialty capacity, application support, and regional supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
