
- Market Size (2026)
- USD 389.2 Bn
- Forecast (2036)
- USD 646.2 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Winter Wear Market in 2026?
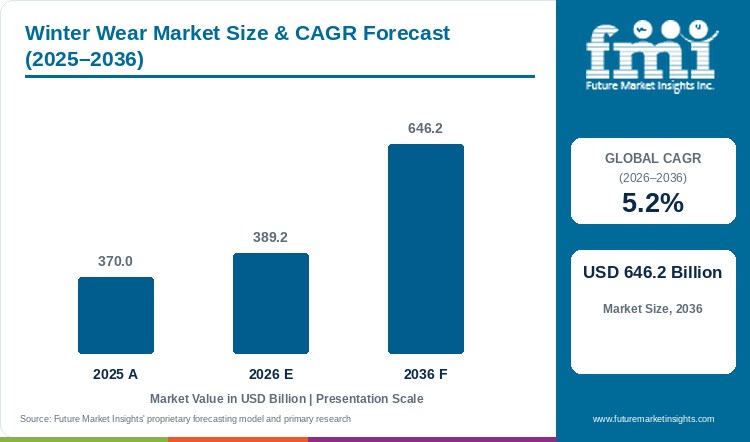
The winter wear market is estimated at USD 370.0 billion in 2025 and is likely to reach USD 389.2 billion in 2026. Winter wear sales are projected to grow at a 5.2% CAGR and reach USD 646.2 billion by 2036.
Winter wear market share is moving toward technical and premium outerwear, as shoppers pay more for jackets that last several seasons. Winter wear purchases are estimated at USD 370.0 billion for 2025, and repeat parka and shell buying is likely to take the total to USD 389.2 billion in 2026. FMI analysts expect a 5.2% CAGR to carry the winter wear market to USD 646.2 billion by 2036. Led by Arc'teryx, Technical Apparel at Amer Sports grew 32% in the June quarter of 2026, to USD 674 million.[1] Strong shell and fleece sales in a summer quarter show outdoor clothing selling all year.
On a buyer heat map, outdoor enthusiasts and premium city shoppers are hot. Jackets and coats, expected at 34.6% of 2026 sales by product type, sell mostly to these shoppers, who replace a technical shell or down parka every two to three seasons at full price. Families buying school coats, gloves and thermals fall in the warm zone, shopping once a season and often on promotion. Price-led buyers of hoodies and scarves are cool and buy mainly in winter sales. Moncler grew brand DTC sales 10% at constant exchange rates in H1 2026, and comparable store sales rose 7%.[2] Owned stores and full-price selling pay off in the hot zone, so brands chasing that full-price buyer are putting money into flagships and direct channels.
Key Market Trends & Insights
- Demand for parkas, puffers, wool coats and shell jackets gives jackets and coats an expected 34.6% in 2026, nearly 15 points ahead of sweaters and cardigans.
- Down and synthetic fills are likely to remain the top material, at 29.4% in 2026. Outerwear sales at Burberry grew by double digits over April to June 2026, across heritage rainwear, lightweight jackets and seasonal products.[3]
- Specialty stores are projected at 31.5% of sales channel sales in 2026, and online stores at about 27.8%, as brands add direct websites and apps.
Regional Highlights
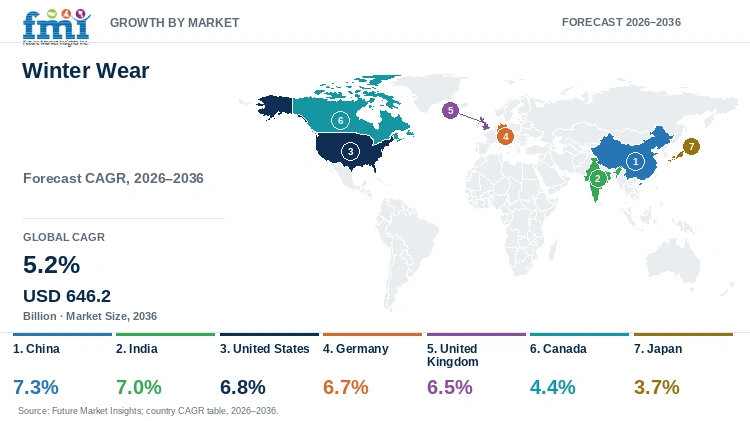
- Per FMI's country model, China leads at 7.3%, faster than the winter wear market average of 5.2%, as premium outerwear brands open stores in more cities.
- India is next at 7%. American outdoor brands give the United States 6.8%, with Germany and the United Kingdom only a fraction behind and the British rate at 6.5%. Canada, with high spend per person already, and Japan, with an ageing population, grow slowest, and Japan has the lowest rate at 3.7%.
- Comparable retail sales at Burberry rose 12% in the Americas and 9% in Greater China over the 13 weeks to 27 June 2026.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Winter Wear Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 370.0 billion |
| Estimated Market Size in 2026 | USD 389.2 billion |
| Projected Market Size by 2036 | USD 646.2 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 257.0 billion |
| Market Expansion Multiple | 1.7x |
Orders for winter wear arrive late in the calendar. Brands collect wholesale orders for fall in spring and ship most goods between August and November, so a cold or mild start to winter decides discounting. Columbia Sportswear expects more of the Fall 2026 shipments to land in the fourth quarter, with third-quarter guidance set at USD 929 million to USD 943 million.[4] Kontoor Brands assumes a 15% reciprocal tariff rate for the second half of 2026, and new Section 301 tariffs of 10% to 12.5% came into force in July 2026.[5] Heated layers are a fast-growing niche, and the heated jacket market is forecast to increase at a 12.6% CAGR. FMI analysts expect the decade to add about USD 257.0 billion to the winter wear market, so 2036 sales are 1.7 times the 2026 size. A mild winter in Europe or North America is the main near-term risk, as unsold stock leads to markdowns.
Tariffs, Direct Channels and Premium Outerwear
Tariff costs are shifting the economics of imported coats and jackets into the United States. IEEPA tariff refunds of about USD 78 million reached Columbia Sportswear in the June quarter, and the company's outlook assumes current tariff rates stay in place through year-end.[4] More than 80% of the Bangladesh-sourced products of Kontoor Brands use US-grown cotton, which may qualify for a duty exemption.[5] Brands will move sourcing between Bangladesh, Vietnam and Mexico to protect margins on fall ranges.
Premium brands are investing in large stores to sell outerwear at full price. Moncler opened a 23,680 sq ft flagship on Fifth Avenue in New York on 10 September 2026, with Moncler Grenoble mountain wear on the second floor and an AI Outerwear Guide online.[6] Burberry opened 9 stores and closed 21 in FY26, and outerwear outperformed in all regions.[7] A shopper trying a parka in a flagship will often buy the second jacket online, so brands will link stores and apps.
Table 2: Brand Sales, Channel and Tariff Indicators for the Winter Wear Market (sales, growth and rates), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Amer Sports Technical Apparel sales, Q2 2026 | USD 674 million; up 32% | Technical outerwear sells across seasons. | [1] |
| Moncler brand DTC revenues, H1 2026 | EUR 933.2 million; up 10% at constant exchange | Owned stores lead premium sales. | [2] |
| Burberry comparable retail sales, Q1 FY27 | Up 5% | Outerwear grows by double digits. | [3] |
| Columbia Sportswear net sales, Q2 2026 | USD 614.4 million; up 2% | Mass outdoor brands grow slowly. | [4] |
| Helly Hansen revenue, Q2 2026 | USD 114 million | Ski and sailing wear add volume. | [5] |
| Section 301 tariffs, July 2026 | 10% to 12.5% | Import costs rise for US brands. | [5] |
Analyst Perspective
“Winter wear buyers are splitting into two groups, the shopper who spends heavily on one technical or premium jacket and the shopper who waits for the January sale. I expect brands with owned stores and strong outerwear credentials to gain share through 2036, as full-price selling of a few hero products now funds the wider range. Mild winters and heavy discounting show the shifting balance between supply and demand, and stock discipline decides who keeps margin.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the winter wear market segmented?
The market is segmented into product type, material type, sales channel, and region. Jackets and coats are expected to lead product type with 34.6% share in 2026, and down and synthetic insulation leads material type with 29.4%.
By product type: jackets and coats, sweaters and cardigans, thermal wear, scarves and gloves, hoodies and sweatshirts, and others.
By material type: wool, fleece, down and synthetic insulation, cotton, and others.
By sales channel: supermarkets and hypermarkets, specialty stores, online, departmental stores, and others.
By region: shoppers and retailers in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do jackets and coats lead winter wear sales by product type?
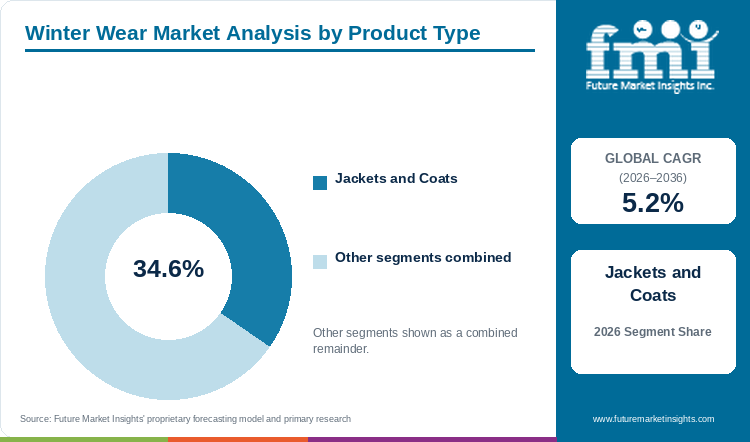
Jackets and coats are expected to lead product type sales with 34.6% share in 2026, ahead of sweaters and cardigans at about 19.8% and hoodies and sweatshirts at roughly 16.2%.
Table 3: Product Type Share for the Winter Wear Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Jackets and Coats | 34.6% |
| Sweaters and Cardigans | 19.8% |
| Hoodies and Sweatshirts | 16.2% |
| Thermal Wear | 12.4% |
| Scarves and Gloves | 9.7% |
| Others | 7.3% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Winter Wear Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Jackets and Coats |
Jackets and coats lead product type, and the 2026 share is expected at 34.6%. An insulated outer layer is the one item every buyer needs in cold weather and carries the highest price per piece. Sweaters and cardigans, about 19.8%, sell in more units at lower prices. Hoodies and sweatshirts, near 16.2%, are worn across seasons and compete with casual wear. Thermal wear, an estimated 12.4%, is a base layer bought in packs. Scarves and gloves, close to 9.7%, are low-cost add-ons, and other items are estimated at 7.3%. Burberry said outerwear and scarves both grew by double digits in the second half of FY26.[7] A shopper with a fixed budget will spend most on the coat and fill out the wardrobe at lower prices.
- Down parkas, puffer jackets, wool overcoats, rainwear and technical shells make up the leading segment.
- The LoveFrom collection of four outerwear silhouettes was due at selected Moncler boutiques and online on 1 October 2026, the company said in September.[6]
Why does down and synthetic insulation lead winter wear sales by material type?
Down and synthetic insulation is likely to hold 29.4% of material type sales in 2026, with wool at about 22.1% and cotton at roughly 21.6%.
Table 5: Material Type Share for the Winter Wear Market (percentage share), 2026
| Material Type | Estimated Share (2026) |
|---|---|
| Down and Synthetic Insulation | 29.4% |
| Wool | 22.1% |
| Cotton | 21.6% |
| Fleece | 18.3% |
| Others | 8.6% |
| Total | 100.0% |
Puffers and parkas use down or synthetic fills, so this material group leads with a projected 29.4% share in 2026, and each jacket sells at a high price. Wool, an estimated 22.1%, goes into coats, sweaters and base layers and carries a premium for natural fibre. Cotton, near 21.6%, dominates hoodies, sweatshirts and lined casual wear. Fleece, about 18.3%, is light and cheap, so outdoor and mass brands use fleece for mid-layers. Other materials, close to 8.6%, include cashmere and blends. Amer Sports reported 30% constant-currency growth in Technical Apparel in Q2 2026, a segment built on insulated and shell jackets.[1] Buyers facing very cold weather will pay for insulated fills, and mild-climate buyers will choose wool or fleece layers.
- Most insulated jackets use goose and duck down, recycled polyester fill or synthetic insulation panels.
- Helly Hansen holds leadership positions in wintersports and sailing, Kontoor Brands said in September 2026.[8]
Why do specialty stores lead winter wear sales by sales channel?
Specialty stores are estimated at 31.5% of sales channel sales in 2026, against about 27.8% for online and 17.6% for departmental stores.
Table 6: Sales Channel Share for the Winter Wear Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Specialty Stores | 31.5% |
| Online | 27.8% |
| Departmental Stores | 17.6% |
| Supermarkets and Hypermarkets | 15.2% |
| Others | 7.9% |
| Total | 100.0% |
Outdoor shops and brand stores let shoppers try fit and warmth before paying full price for a coat, which gives specialty stores the lead at a likely 31.5% in 2026. Online, about 27.8%, grows fastest as brands sell direct and use size tools, and returns are high for outerwear. Departmental stores, near 17.6%, carry many brands and discount heavily at season end. Supermarkets and hypermarkets, an estimated 15.2%, sell low-priced fleece, thermals and gloves. Other channels are estimated at 7.9%. Physical stores outperformed online at Moncler in H1 2026.[2] Shoppers buying an expensive jacket will keep visiting a store, and repeat buyers of basics will order online.
- Brand stores, outdoor specialists and ski shops form the specialty channel.
- Owned channels brought Moncler EUR 933.2 million in the first half of 2026, or 85.6% of brand revenues.[2]
What are the drivers, restraints, and opportunities in the winter wear market?
Outdoor activity and premium fashion keep shoppers buying technical and designer outerwear. Mild winters and tariffs squeeze margins, and direct channels and growing Asian demand open new sales.
- Driver: More people hiking, skiing and travelling to cold places want warm, light and weatherproof clothing, which raises the average spend per jacket.
- Restraint: A mild start to winter or higher import duties leave retailers with unsold stock and force markdowns that cut brand margins.
- Opportunity: Brands selling direct through stores and apps can sell at full price and reach new buyers in fast-growing Asian cities.
Outdoor Activity and Premium Fashion Raise Spend per Jacket
Popularity of outdoor sport and premium outerwear is setting a higher price point for winter wear. For the full year, Amer Sports now guides Technical Apparel growth of 25% to 26%.[1] Burberry drew 19% more new Rainwear customers in Q1 FY27 with the Portraits of an Icon campaign.[3] A buyer moving up to a technical or designer jacket will keep paying at that level on the next purchase.
Mild Winters and Tariffs Squeeze Margins
Producers of winter wear face weather risk and import costs. Columbia Sportswear said the second-half outlook had incrementally moderated, and the company expects gross margin to contract in Q3 2026 due to accommodations to factory partners.[4] Kontoor Brands is planning for a 15% reciprocal tariff rate from July to December 2026.[5] Brands will order closer to the season and hold less stock, which reduces markdowns and limits sales in a cold winter.
Direct Channels and Asian Demand Open New Sales
New sales of winter wear are expected from direct channels and Asian cities. Direct-to-consumer sales at Amer Sports reached USD 897 million in the June quarter, 39.9% above the prior year, and Asia Pacific grew 60.3%.[1] Clothing rental is a small new channel, and the sportswear rental and rotation market is predicted to increase at an 11.8% CAGR. New stores in Asian cities will reach first-time buyers of premium outerwear.
Which country CAGRs are profiled in the winter wear market?
Table 7: Country CAGR Comparison for the Winter Wear Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 7.3% |
| India | 7% |
| United States | 6.8% |
| Germany | 6.7% |
| United Kingdom | 6.5% |
| Canada | 4.4% |
| Japan | 3.7% |
How do country-level CAGRs compare in the winter wear market?
Greater China revenue at Amer Sports grew 35.5% in the June 2026 quarter, as premium outerwear brands expand in Chinese cities, and per FMI's country model China leads at 7.3%.[1] India grows at 7% as winter tourism and northern city demand rise. A spread of only 0.3 points covers the United States, Germany and the United Kingdom, as premium and outdoor brands drive all three. Canada already has a high spend per person on winter clothing, so growth there is 4.4%. An ageing population buys fewer new coats in Japan, the slowest market at 3.7%. Slower growth in Japan, Canada and smaller mature markets offsets the faster rates of the five large countries, which holds the winter wear market at 5.2%.
- Premium brand stores in Chinese cities are adding new buyers.
- Winter tourism and northern cities in India are raising demand.
- Flagship stores and outdoor brands in the United States sell at full price.
- Alpine sports and outdoor brands support German demand.
- Heritage rainwear and outerwear brands lead British buying.
- High spend per person leaves Canada with less room to grow.
- An ageing population in Japan buys fewer coats.
Full report country CAGRs cover: Store openings in China, a young urban buyer base in India and outdoor brands in the United States head the five profiled countries growing over 5.2% in FMI's full report. Germany and the United Kingdom are the other two. High existing spend per person in Canada and an ageing Japan leave those two under the line, with separate regional estimates for Latin America, Eastern Europe and Middle East and Africa.
Country-wise Analysis
China Winter Wear Market Outlook (2026 to 2036)
Sales of winter wear in China are moving to premium and technical brands. Moncler said China and Korea outperformed other Asian markets in Q2 2026.[2] Greater China comparable sales at Burberry grew 9% in the 13 weeks to June.[3] Domestic down jacket brands compete on price in the mass segment. China's rate of 7.3% is the highest covered.
Key takeaway: Premium outerwear demand gives China the highest growth.
India Winter Wear Market Outlook (2026 to 2036)
Demand for winter wear in India comes from the northern plains and hill states with cold winters, and from travellers visiting ski resorts and the Himalayas. Domestic brands such as Monte Carlo and Woodland sell sweaters and jackets, and Decathlon sells technical layers at low prices. Rising incomes and travel will keep demand growing, and the outlook for India is 7%.
Key takeaway: Northern winters and travel demand give India strong growth.
United States Winter Wear Market Outlook (2026 to 2036)
Large flagship stores are opening in the United States. Moncler opened the largest Moncler flagship anywhere, 23,680 sq ft on Fifth Avenue, in September 2026.[6] Columbia Sportswear reported US net sales down 4% to USD 320.1 million in Q2 2026 on lower Spring wholesale orders.[4] Premium brands are gaining as mass outdoor brands slow. Forecast growth for the United States is 6.8%.
Key takeaway: Premium flagships carry growth in the United States.
Germany Winter Wear Market Outlook (2026 to 2036)
German buyers favour outdoor and alpine clothing for hiking and skiing. Kontoor Brands plans to strengthen the position of Helly Hansen in the Alps.[8] EMEA sales at Columbia Sportswear were USD 143.1 million in the June quarter, 10% higher.[4] Outdoor brands will add products for the Alpine ski season. Germany follows at 6.7%.
Key takeaway: Alpine sport carries German demand for technical wear.
United Kingdom Winter Wear Market Outlook (2026 to 2036)
British shoppers buy rainwear and light jackets for wet, mild winters. Burberry earned GBP 203 million from UK customers in FY26.[7] Rainwear is a British staple, and new Rainwear customers at Burberry rose 19% in Q1 FY27.[3] Heritage brands such as Barbour and Burberry lead the premium end. Rainwear and heritage outerwear give the United Kingdom a projected 6.5% CAGR.
Key takeaway: Rainwear and heritage brands set the British pace.
Canada Winter Wear Market Outlook (2026 to 2036)
Canadians spend more per person on winter clothing than shoppers in Germany, the United States or Japan, so growth comes from replacement and upgrades. Canadian net sales at Columbia Sportswear fell 7% in the June quarter, to USD 25.2 million.[4] Canada Goose and outdoor retailers serve a mature buyer base. FMI's table of country rates gives Canada 4.4%.
Key takeaway: A mature buyer base with high spend per person slows Canada.
Japan Winter Wear Market Outlook (2026 to 2036)
Japanese shoppers buy functional base layers and light down at low prices from domestic chains. Comparable retail sales at Burberry in Japan fell 2% in Q1 FY27.[3] An ageing population and milder winters reduce the number of new coats bought each year. Japan is expected at 3.7%.
Key takeaway: Ageing buyers and low-price chains keep Japan slow.
Who are the notable companies in the winter wear market?
Canada Goose, Columbia Sportswear, VF Corporation, Patagonia, Moncler, Amer Sports, Marmot, Eddie Bauer, Kontoor Brands, Bosideng, Fast Retailing, Adidas, Burberry, Barbour, Decathlon, Mammut, Monte Carlo and Woodland are the profiled companies.
Luxury outerwear houses, outdoor groups and mass retailers compete for winter wear buyers. FMI profiles eighteen companies. Moncler Group revenues were EUR 1,289.9 million in H1 2026, 9% higher at constant exchange rates.[2] Quarterly revenue at Amer Sports was USD 1,633 million in Q2 2026, a 32% increase.[1] Columbia Sportswear, VF Corporation, Patagonia and Kontoor Brands sell outdoor wear, and Fast Retailing, Decathlon and Bosideng sell at mass prices.
- Luxury and premium outerwear houses: Moncler, Canada Goose, Burberry and Barbour.
- Outdoor and sports groups: Amer Sports, Columbia Sportswear, VF Corporation, Patagonia, Kontoor Brands, Marmot, Mammut and Adidas.
- Mass and value retailers: Fast Retailing, Decathlon, Bosideng and Eddie Bauer.
- Regional knitwear and outdoor brands: Monte Carlo and Woodland.
Competitive Benchmarking: Winter Wear Market
Table 8: Competitive Benchmarking for the Winter Wear Market (qualitative documentation ratings), 2026
| Company | Premium Outerwear | Technical Outdoor | Direct Channel | Recency |
|---|---|---|---|---|
| Moncler | High | Medium | High | High |
| Amer Sports | Medium | High | High | High |
| Burberry | High | Low | High | High |
| Columbia Sportswear | Low | High | Medium | High |
| Kontoor Brands | Medium | High | Low | High |
Ratings follow the depth of quarterly and half-year winter wear disclosures FMI could find for each brand owner, and are not a share ranking.
Key Developments in the Winter Wear Market
- On 10 September 2026, Moncler opened a 23,680 sq ft flagship on Fifth Avenue in New York.[6]
- On 2 September 2026, Kontoor Brands set 2030 targets of more than USD 1.1 billion in Helly Hansen revenue.[8]
- On 18 August 2026, Arc'teryx shells and fleece drove a 32% rise in Technical Apparel sales at Amer Sports for the June quarter.[1]
- On 12 August 2026, Kontoor Brands said Helly Hansen beat expectations in the second quarter, with USD 114 million of revenue.[5]
- On 30 July 2026, Columbia Sportswear kept full-year sales guidance at USD 3.43 billion to USD 3.50 billion.[4]
- On 22 July 2026, Moncler said January to June 2026 sales grew 9% at constant exchange rates, led by direct stores.[2]
- On 17 July 2026, outerwear grew by double digits at Burberry, inside 5% comparable retail sales growth for Q1 FY27.[3]
- On 14 May 2026, Burberry said outerwear outperformed in all regions in FY26.[7]
Key Players in the Winter Wear Market
Luxury and Premium Outerwear Houses
- Moncler
- Canada Goose
- Burberry
- Barbour
Outdoor and Sports Groups
- Amer Sports
- Columbia Sportswear
- VF Corporation
- Patagonia
- Kontoor Brands
- Marmot
- Mammut
- Adidas
Mass and Value Retailers
- Fast Retailing
- Decathlon
- Bosideng
- Eddie Bauer
Regional Knitwear and Outdoor Brands
- Monte Carlo
- Woodland
Winter Wear Market - Report Scope
Table 9: Report Scope for the Winter Wear Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; material type; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Cold-weather clothing and accessories, including jackets and coats, sweaters and cardigans, thermal wear, scarves and gloves and hoodies and sweatshirts, made from wool, fleece, down and synthetic insulation, cotton and other materials, sold through store and online channels. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Canada Goose, Columbia Sportswear, VF Corporation, Patagonia, Moncler, Amer Sports, Marmot, Eddie Bauer, Kontoor Brands, Bosideng, Fast Retailing, Adidas, Burberry, Barbour, Decathlon, Mammut, Monte Carlo, Woodland |
| Forecast period | 2026 to 2036 |
Winter Wear Market - Research Methodology
Table 10: Research Methodology for the Winter Wear Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Brand results, trading updates, store opening releases and strategy presentations from apparel and outdoor groups published from May 2025 onward. |
| Desk Research | Desk research covers outerwear sales, channel mix, regional growth, tariffs and store openings. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 389.2 billion and the 5.2% CAGR for 2026 to 2036. |
| Data Validation | Sales, growth and tariff figures were checked against the company release that reported each one. |
Winter Wear Market by Segments
Winter Wear Market segmented by Product Type:
- Jackets and Coats
- Sweaters and Cardigans
- Thermal Wear
- Scarves and Gloves
- Hoodies and Sweatshirts
- Others
Winter Wear Market segmented by Material Type:
- Wool
- Fleece
- Down and Synthetic Insulation
- Cotton
- Others
Winter Wear Market segmented by Sales Channel:
- Supermarkets and Hypermarkets
- Specialty Stores
- Online
- Departmental Stores
- Others
Winter Wear Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Amer Sports. (2026, August 18). Amer Sports Reports Second Quarter 2026 Financial Results, Raises Full-Year Revenue, Margin and EPS Guidance. https://investors.amersports.com/financial-news/news-details/2026/Amer-Sports-Reports-Second-Quarter-2026-Financial-Results-Raises-Full-Year-Revenue-Margin-and-EPS-Guidance/default.aspx
- [2] Moncler S.p.A. (2026, July 22). H1 2026 Financial Results. https://www.monclergroup.com/v3/assets/blt61bda6b71f29a239/blt6651b04f18f67307/6a60e7584e8afd132530f0c6/Moncler-Group-Press-Release-H1-2026.pdf
- [3] Burberry Group plc. (2026, July 17). First Quarter Trading Update (Q1 FY27). https://www.burberryplc.com/content/dam/burberryplc/corporate/documents/investors/results-reports/2026/q1/Burberry%20Q1%20FY27%20Trading%20Update%20Press%20Release%20.pdf.downloadasset.pdf
- [4] Columbia Sportswear Company. (2026, July 30). Columbia Sportswear Company Reports Second Quarter 2026 Financial Results; Updates Full Year 2026 Financial Outlook. https://investor.columbia.com/news-events/press-releases/detail/389/columbia-sportswear-company-reports-second-quarter-2026
- [5] Kontoor Brands. (2026, August 12). Kontoor Brands Reports 2026 Second Quarter Results. https://www.kontoorbrands.com/investors/news-events/press-releases/detail/241/kontoor-brands-reports-2026-second-quarter-results-and
- [6] Moncler S.p.A. (2026, September 10). Moncler celebrates its enduring bond with New York through the opening of its largest-ever global flagship. https://www.monclergroup.com/v3/assets/blt61bda6b71f29a239/blt0e349c903258f3a9/6aa25fe165f534e415887084/MONCLER_5TH_AVENUE_STORE_OPENING_PRESS_RELEASE_ENG.pdf
- [7] Burberry Group plc. (2026, May 14). Preliminary Results 2025/26. https://www.burberryplc.com/content/dam/burberryplc/corporate/documents/investors/results-reports/2026/prelims/Burberry%20FY26%20Preliminary%20Results%20Press%20Release%20v2.pdf.downloadasset.pdf
- [8] Kontoor Brands. (2026, September 2). Kontoor Brands Unveils Helly Hansen Growth Strategy and 2030 Financial Targets. https://www.kontoorbrands.com/investors/news-events/press-releases/detail/243/kontoor-brands-unveils-helly-hansen-growth-strategy-and
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the winter wear market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which material type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Jackets and Coats
- Sweaters and Cardigans
- Thermal Wear
- Scarves and Gloves
- Hoodies and Sweatshirts
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Wool
- Fleece
- Down and Synthetic Insulation
- Cotton
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Specialty Stores
- Online
- Departmental Stores
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Material Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Moncler
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Amer Sports
- Burberry
- Columbia Sportswear
- Kontoor Brands
- Canada Goose
- Barbour
- VF Corporation
- Patagonia
- Marmot
- Mammut
- Adidas
- Fast Retailing
- Decathlon
- Bosideng
- Eddie Bauer
- Monte Carlo
- Woodland
- Moncler
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material Type, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Type
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Type
- Figure 29: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sales Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material Type
- Figure 39: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material Type
- Figure 49: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material Type
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material Type
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material Type, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material Type, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material Type
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the winter wear market expected in 2026?
FMI's 2026 estimate for the winter wear market is USD 389.2 billion, against USD 370.0 billion in 2025. Winter wear sales are projected to reach USD 646.2 billion by 2036.
What CAGR is projected for the winter wear market through 2036?
Growth in the winter wear market from 2026 to 2036 is forecast at a 5.2% CAGR. Premium outerwear, outdoor sport and direct selling carry that growth.
Which product type holds a notable market share in 2026?
The largest product type is jackets and coats, expected at 34.6% share in 2026. Sweaters and cardigans follow at an estimated 19.8%.
Which material type holds a notable market share in 2026?
The leading material type is down and synthetic insulation, likely to hold 29.4% share in 2026. Wool follows at an estimated 22.1%.
Which country has a notable expansion outlook through 2036?
China has the strongest rate in the FMI country table, a 7.3% CAGR. India follows at 7%.
Who are the key companies in the winter wear market?
Moncler, Canada Goose, Burberry and Barbour lead the premium end, alongside outdoor groups including Amer Sports, Columbia Sportswear, VF Corporation, Patagonia and Kontoor Brands. Marmot, Mammut, Adidas, Fast Retailing, Decathlon, Bosideng, Eddie Bauer, Monte Carlo and Woodland complete the profiled group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
