

- Market Size (2026)
- USD 68.3 Bn
- Forecast (2036)
- USD 135.7 Bn
- CAGR (2026 to 2036)
- 7.1%
How big is the workstation market in 2026?
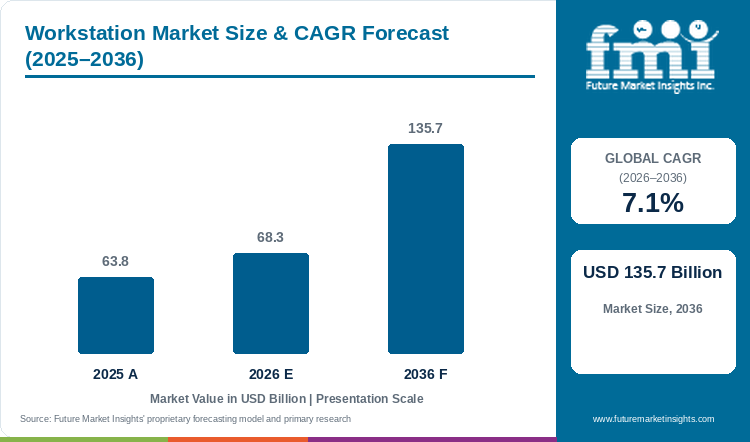
Demand is projected to expand at 7.1% CAGR from 2026 to 2036. Market value rises from USD 63.8 billion in 2025 to USD 68.33 billion in 2026 and USD 135.7 billion by 2036. [1]
Demand is estimated at USD 68.33 billion in 2026 and projected to reach USD 135.7 billion by 2036, at a CAGR of 7.1% from 2026 to 2036. [1] A workstation is purchased to support a particular professional workload, making application compatibility and sustained performance useful starting points for comparison. Engineers handling large models need a configuration that keeps interaction responsive, while creative users may place different demands on graphics and memory. [2][3][4][5] The relationship with computer-aided engineering illustrates why a processor specification alone cannot define suitability, as the model, solver and graphics environment can create different bottlenecks. Desktop systems give buyers configuration flexibility, while mobile workstations serve users who need to carry the same professional environment between locations. Demand therefore reflects both new workload requirements and replacement decisions within established enterprise fleets, with support and application certification affecting the cost of keeping those machines productive. [1] Over the forecast period, suppliers can compete through complete configurations and manageable ownership rather than isolated benchmark claims. Buyers still need to distinguish locally interactive work from processing better suited to shared or remote computing, ensuring that the chosen system fits how the project is delivered. [2][3][4][5]
Key Market Trends and Insights
- Professional application certification remains useful in workstation selection, helping buyers compare supported hardware configurations for the modeling and analysis tools they intend to use. [2][4]
- Graphics capability is increasingly relevant to visualization and accelerated workloads, while memory and storage still determine whether a configuration fits the actual project. [5]
- Mobile workstations address the need to carry a professional environment between sites, although buyers must compare sustained performance and support alongside portability. [1][3]
Regional Highlights
- India's growth outlook includes engineering education and professional computing demand, with institution-level selection influenced by application fit and practical service arrangements. [1]
- Germany's engineering environment favors application-specific workstation assessment, making software certification and a reliable support route relevant to professional replacement decisions. [1][2][4]
- US buyers can compare established hardware suppliers and professional graphics options, with specialized workloads separating workstation purchases from routine office-PC spending. [1][3][5]
Market Size and Forecast
Table 1: Value outlook for the workstation market
| Metric | Value |
|---|---|
| 2025 market value | USD 63.8 billion [1] |
| 2026 market value | USD 68.33 billion [1] |
| 2036 market value | USD 135.7 billion [1] |
| CAGR 2026 to 2036 | 7.1% [1] |
| Revenue increase 2026 to 2036 | USD 67.37 billion [1] |
| Market expansion 2026 to 2036 | 1.99 times [1] |
The 7.1% CAGR from 2026 to 2036 outlook is supported by design, visualization and analysis that require a dependable professional computing environment. Workstation buyers can combine local interaction with shared processing where appropriate, but the desktop or mobile machine must remain responsive for the tasks assigned to its user. Data center GPUs serve a related accelerated-computing role at a different operating scale, making the distinction between an individual workstation and shared infrastructure useful when enterprises plan their computing resources. [1][3][4][5]
What does application certification show about workstation selection?
Dell and Lenovo maintain application-certification references, showing that workstation comparison extends beyond a general specification list. HP offers professional desktop and mobile configurations, while NVIDIA describes graphics intended for professional visualization and computing. Together, these sources support a workload-led purchasing approach in which the model size, supported software, graphics environment and maintenance arrangement help determine the suitability of a particular system. [2][3][4][5]
Table 2: Industry evidence relevant to the workstation market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Application certification | Dell lists system-level ISV certifications | Supported software informs configuration selection | [2] |
| Professional form factors | HP offers desktop and mobile workstations | Mobility and configuration flexibility address different tasks | [3] |
| Professional graphics | NVIDIA provides workstation graphics products | Visualization requirements shape hardware choice | [5] |
Analyst Perspective
"Cybersecurity concerns are lifting demand for secure enterprise-grade computing systems. Buyers also need to match workstation capability with the applications and tasks their teams perform, so that processing capacity, support arrangements and operating costs fit the intended working environment." [1]
— Sudip Saha, Senior Consultant, FMI
How is the workstation market segmented?
The market is segmented by Type, Cores, Industry, and Region.
By type, coverage includes Rack Workstation, Desktop Workstation, Mobile Workstation, Tower Workstation. By cores, coverage includes 6 Cores, 8 Cores, 12 Cores, 18 Cores, 28 Cores, 32 Cores, 56 Cores, Other. By industry, coverage includes Healthcare, Education, BFSI, Manufacturing, Media & Entertainment, Engineering & Design, Other Industry. Regional coverage follows the report's defined geographic markets. [1]
Why does the Desktop workstation segment lead demand within the type category?
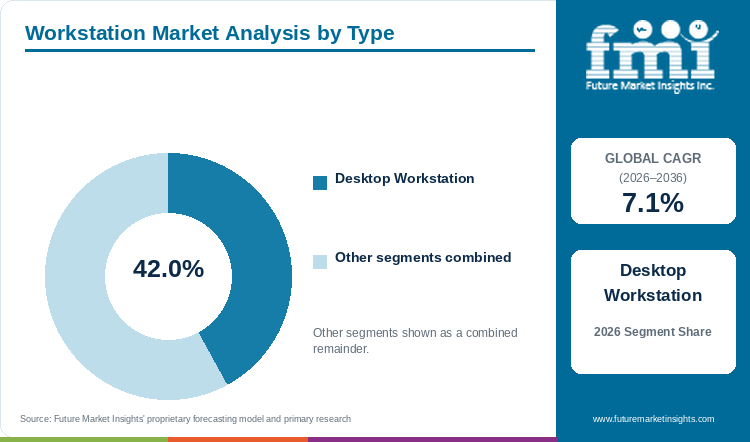
The Desktop workstation segment accounts for 42.0% of type demand in 2026. [1]
Desktop workstations give buyers room to match graphics, memory and storage with a professional workload while keeping the user's computing environment at a fixed location. This flexibility supports design teams that work on large models or visualization projects and need a dependable configuration throughout the day. Supplier portfolios and certification references show how professional systems are organized around application requirements rather than ordinary office use. [2][3][4][5] Demand related to 3D printing can add design and preparation tasks to the same development environment, although the workstation specification still needs to follow the chosen software and model complexity. The segment's position therefore rests on configuration and support, with the ownership decision extending beyond the initial purchase price. [1]
- The Desktop workstation segment is estimated to account for 42.0% of type demand in 2026, reflecting demand for configurable professional systems used at a fixed design, visualization or analysis workstation. [1]
- Professional graphics and application certification help buyers assess suitability, while memory capacity and support remain necessary parts of the configuration decision. [2][3][4][5]
Table 3: Leading type share in 2026
| Segment | Share of demand |
|---|---|
| Desktop workstation | 42.0% [1] |
| Other type segments | 58.0% [1] |
| Total | 100.0% |
Why does the 6 cores segment lead demand within the cores category?
The 6 cores segment accounts for 29.1% of cores demand in 2026. [1]
Six-core configurations provide a defined processor category within the workstation taxonomy, but the practical value of that configuration depends on the application and the rest of the system. A user whose task emphasizes interactive modeling may have different requirements from one running highly parallel simulation or rendering, so core count needs to be assessed alongside memory, graphics and the software's behavior. [2][3][4][5] The estimated share reflects demand for this category without implying that it is sufficient for every professional workload. Buyers can compare certified configurations and realistic project requirements before selecting a machine, while supplier support remains relevant when driver updates, storage changes or application versions affect the established computing environment. [1]
- The 6 cores segment is estimated to account for 29.1% of cores demand in 2026, as buyers match a defined processor configuration with the responsiveness and application requirements of their professional workload. [1]
- Core count should be considered alongside graphics and memory, because different software tasks place different demands on the complete workstation system. [2][3][4][5]
What are the drivers, restraints, and opportunities in the workstation market?
Driver
Professional workloads require a stable computing environment that can handle larger models and more demanding visualization without interrupting the user's interaction. That need supports workstation refresh decisions when the existing machine becomes a constraint on the project rather than simply reaching a particular age. Application certification and support help buyers evaluate the full configuration, while growing use of accelerated graphics adds another reason to align the machine with the actual development or analysis workflow. [1][2][3][4][5]
Restraint
A premium workstation can be difficult to justify when the selected application cannot use its additional capability or when the workload could run more economically on shared resources. Buyers also face configuration trade-offs involving portability, sustained performance and upgrade flexibility, while new hardware may require driver or software changes. These conditions encourage careful assessment of the complete environment, since purchasing a faster component alone may leave the original graphics, memory or storage bottleneck unresolved. [2][3][4][5]
Opportunity
Suppliers can make professional selection easier by linking configurations with supported applications and representative workloads, giving buyers a clearer basis for comparing desktop and mobile systems. Organizations using cloud computing alongside local machines also need guidance on which tasks require responsive interaction at the workstation and which can move to remote resources. The opportunity lies in a coordinated computing environment that remains manageable for users and support teams, rather than treating every workload as a hardware upgrade. [2][3][4][5]
Which country CAGRs are profiled in the workstation market?
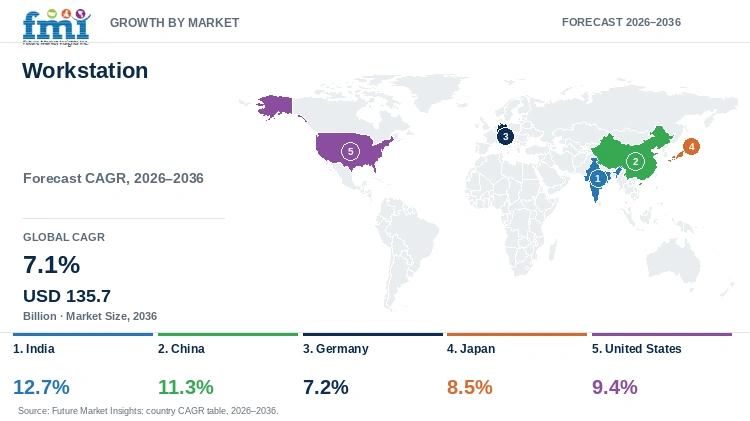
Table 4: Country CAGR comparison for the workstation market
| Country or market | CAGR 2026 to 2036 |
|---|---|
| India | 12.7% [1] |
| China | 11.3% [1] |
| Germany | 7.2% [1] |
| Japan | 8.5% [1] |
| United States | 9.4% [1] |
Country-wise Analysis
India
Engineering education and design-oriented enterprises give India's workstation market several different purchasing settings, ranging from shared learning laboratories to dedicated machines for professional users. Buyers in those settings need to match the computer with the application rather than choosing solely by the processor's name, since graphics, memory and storage can influence the usefulness of a configuration. [1][2][3][4] The market is projected at a CAGR of 12.7% from 2026 to 2036, with demand supported by advanced computing adoption in education, healthcare and engineering. Service availability and application certification can also affect institutional selection, while upgrade planning needs to consider how many users will share a machine and which project workloads must remain responsive throughout the working day. [2][4]
China
China's engineering and manufacturing enterprises need workstations that support design changes, visualization and data-intensive analysis within a broader production-development workflow. A system that fits the selected software can help designers work consistently, while procurement teams compare graphics capability and memory against the actual model or simulation they expect staff to handle. [1][4][5] Growth is projected at a CAGR of 11.3% from 2026 to 2036, with local AI and engineering workloads supporting the demand outlook. Buyers also need a manageable refresh strategy, because a new processor does not automatically resolve a bottleneck in storage or graphics, and configuration decisions should remain connected to the application certification and support arrangements relevant to the organization's chosen development tools. [2][3]
Germany
Germany's manufacturing and engineering users give workstation procurement a strong application-specific emphasis, particularly where designers rely on professional modeling and visualization software throughout the development process. Independent software vendor certification provides a useful reference for comparing supported systems, while the configuration still needs enough memory and graphics capability for the models being used. [2][4] A 7.2% CAGR from 2026 to 2036 is projected for the market, supported by engineering refresh demand rather than ordinary office-PC replacement alone. Buyers can examine the relationship between local workstations and shared computing resources, retaining responsive interaction at the desk while moving suitable batch jobs elsewhere, and they need to consider support and operating continuity when a machine is assigned to critical design work. [1][3][5]
Japan
Japanese workstation demand is linked to precision development and professional computing environments in which a stable application setup can be as consequential as peak benchmark performance. Engineers and creative users need a machine that handles their actual models consistently, while enterprise support teams require a manageable configuration and a clear route for addressing hardware or driver issues. [1][2][3][4] The forecast projects a CAGR of 8.5% from 2026 to 2036, with purchasing influenced by engineering, manufacturing and specialized visualization workloads. Portable systems can serve users who move between sites, although the buyer must assess sustained performance and external-display requirements alongside mobility, while desktop systems retain room for configurations tailored to demanding graphics and memory needs. [3][5]
United States
The United States workstation market serves engineering, media and professional analysis users who can choose among several established system suppliers and graphics configurations. That breadth makes application fit central to procurement, because a certified machine used for modeling has a different operating requirement from a general office computer or a server handling remote batch processing. [1][2][4] Demand is projected to advance at a CAGR of 9.4% from 2026 to 2036, supported by specialized workloads and refresh activity. Professional graphics documentation illustrates the role of visualization and accelerated computing, while users deciding between mobile and desktop systems need to compare sustained workload performance, memory capacity and service support against the way their projects are actually completed. [3][5]
Who are the notable companies in the workstation market?
Dell Technologies; HP; Lenovo; Apple; Fujitsu
Competitive Benchmarking
Dell, HP and Lenovo combine workstation portfolios with application-oriented support and configuration choices, while Apple and Fujitsu address professional computing through their own system environments. NVIDIA's graphics products form part of the hardware context rather than representing an interchangeable complete-system supplier. Buyers can compare operating environments, form factors and certified configurations against the intended task, making the relationship between the machine and professional software more useful than a general ranking by processor specification. [1][2][3][4][5]
Table 5: Competitive positioning for the workstation market
| Company | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Dell Technologies | Professional workstations | ISV certification database supports application-specific system selection. [2] |
| HP | Z workstations | Desktop and mobile systems for professional workloads. [3] |
| Lenovo | ThinkStation and ThinkPad P workstations | ISV-certified configurations for professional applications. [4] |
| Apple | Professional desktop computing | Professional computing systems addressing creative workflows. [1] |
| Fujitsu | Enterprise workstation systems | Professional systems within the workstation supplier landscape. [1] |
Key Developments in the Workstation Market
- Dell's current workstation certification database provides system-level application references, giving professional buyers a direct way to check configurations against the software they intend to use. [2]
- NVIDIA's current RTX PRO desktop graphics offering emphasizes professional visualization and computing, reflecting the role of accelerated graphics within specialized workstation configurations. [5]
- HP and Lenovo continue to present professional workstation portfolios and application-support references, maintaining distinct configuration choices for mobile users and fixed professional computing environments. [3][4]
Key Players in the Workstation Market
- Dell Technologies
- HP
- Lenovo
- Apple
- Fujitsu
Workstation Market Report Scope
Table 6: Report coverage for the workstation market
| Attribute | Coverage |
|---|---|
| Market | Workstation Market |
| Currency and unit | USD billion; market revenue |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Segmentation | Type, Cores, Industry |
| Country profiles | India; China; Germany; Japan; United States |
| Competitive coverage | Dell Technologies; HP; Lenovo; Apple; Fujitsu |
| Geographic coverage | North America, Latin America, Europe, East Asia, South Asia and Pacific, Middle East and Africa |
Workstation Market Research Methodology
Table 7: Research methods for the workstation market
| Method | Approach |
|---|---|
| Market definition | Revenue coverage is defined around workstation offerings and their related commercial services, with adjacent markets retained as context. |
| Desk research | Public FMI outlooks, direct product documentation, institutional publications and official guidance provide the source base. |
| Segment assessment | Categories are assessed against their functional role, purchasing decisions and reported market structure, with shares kept within their own segmentation axes. |
| Country assessment | Country demand is examined through local customer requirements, industry composition and implementation conditions, with a consistent 2026 to 2036 forecast period. |
| Competitive comparison | Participants are compared through documented offerings and business roles; product features and service models are distinguished from market-share rankings. |
| Forecast assessment | The outlook considers adoption, replacement, integration effort and commercial constraints, expressing monetary forecasts and segment estimates in consistent units. |
Workstation Market by Segments
Workstation Market segmented by Type:
- Rack Workstation
- Desktop Workstation
- Mobile Workstation
- Tower Workstation
Workstation Market segmented by Cores:
- 6 Cores
- 8 Cores
- 12 Cores
- 18 Cores
- 28 Cores
- 32 Cores
- 56 Cores
- Other
Workstation Market segmented by Industry:
- Healthcare
- Education
- BFSI
- Manufacturing
- Media & Entertainment
- Engineering & Design
- Other Industry
Workstation Market by Region
North America
- United States
- Canada
- Mexico
Latin America
- Brazil
- Chile
- Rest of Latin America
Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
East Asia
- China
- Japan
- South Korea
South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
[1] Future Market Insights. Accessed 14 October 2026. Workstation Market
[2] Dell Technologies. Accessed 14 October 2026. Workstation ISV certification
[3] HP. Accessed 14 October 2026. Professional workstations
[4] Lenovo. Accessed 14 October 2026. ISV-certified workstations for manufacturing
[5] NVIDIA. Accessed 14 October 2026. RTX PRO professional desktop GPUs
This Report Answers
- How big is the workstation market in 2026?
- What is the outlook for the workstation market through 2036?
- Which type segment is highlighted?
- Which markets are included in the growth comparison?
- Which participants are included in the competitive assessment?
Frequently Asked Questions
How big is the workstation market in 2026?
The market is estimated at USD 68.33 billion in 2026, compared with USD 63.8 billion in 2025. [1]
What is the outlook for the workstation market through 2036?
Revenue is projected to reach USD 135.7 billion by 2036, with a CAGR of 7.1% from 2026 to 2036. [1]
Which type segment is highlighted?
The Desktop workstation segment accounts for an estimated 42.0% share in 2026, reflecting the purchasing conditions described in the segment analysis. [1]
Which markets are included in the growth comparison?
The comparison profiles India, China, Germany, Japan, United States and presents their demand outlooks for 2026 to 2036. [1]
Which participants are included in the competitive assessment?
The assessment includes Dell Technologies, HP, Lenovo, Apple, Fujitsu, with positioning based on each participant's documented business role. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Rack Workstation
- Desktop Workstation
- Mobile Workstation
- Tower Workstation
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Cores, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Cores, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Cores, 2026 to 2036
- 6 Cores
- 8 Cores
- 12 Cores
- 18 Cores
- 28 Cores
- 32 Cores
- 56 Cores
- Other
- Y-o-Y Growth Trend Analysis By Cores, 2021 to 2025
- Absolute $ Opportunity Analysis By Cores, 2026 to 2036
- Global Market Analysis and Forecast, By Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Industry, 2026 to 2036
- Healthcare
- Education
- BFSI
- Manufacturing
- Media & Entertainment
- Engineering & Design
- Other Industry
- Y-o-Y Growth Trend Analysis By Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Type
- By Cores
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Cores
- By Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Cores
- By Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Cores
- By Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Dell Technologies
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- HP
- Lenovo
- Apple
- Fujitsu
- Dell Technologies
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


