
- Market Size (2026)
- USD 54.0 Bn
- Forecast (2036)
- USD 114.4 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is the Advanced Packaging Market in 2026?
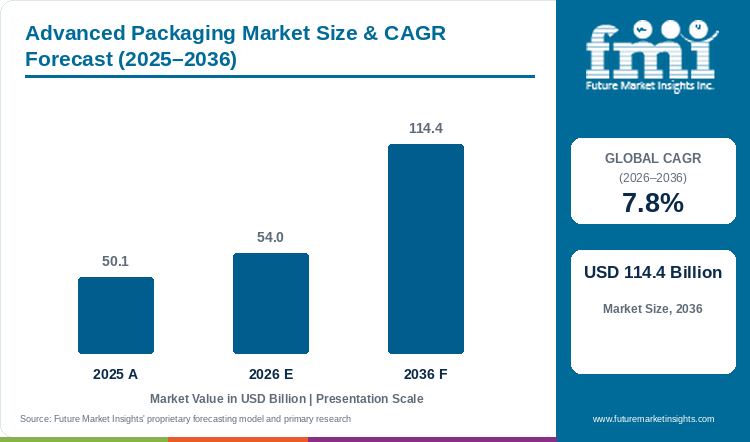
The market is forecast to reach USD 54.0 billion in 2026 and USD 114.4 billion by 2036, advancing at 7.8% CAGR.
According to Future Market Insights analysis, the global advanced packaging market stands at USD 50.1 billion in 2025. Industry valuation is projected to reach USD 114.4 billion by 2036, expanding at a 7.8% CAGR. That trajectory generates USD 60.4 billion in added revenue across the 2026 to 2036 assessment period. Brand owners now judge packs on product protection and recovery outcomes rather than purchase price alone. In June 2026, the U.S. Environmental Protection Agency updated its life-cycle materials guidance for packaging choices [1]. That guidance turns material selection from a cost decision into a line qualification requirement for converters. Rigid containers and bottles hold 50.2% of format revenue in 2026, since sustainable packaging demand keeps stacking strength central to supply. Growth across evaluated economies spans 6.2% in Japan to 9.5% in Italy, though mixed-material recovery limits continue to restrict wider adoption.
Key Market Trends & Insights
- Based on packaging format, rigid containers and bottles are projected to account for 50.2% in 2026, driven by stack protection and resealable dispensing.
- By material substrate, recycled paperboard is estimated to hold 38.3% in 2026, supported by established fiber collection and converting capacity.
- In 2026, food and beverage is expected to lead the end-use sector with 44.7% share, reflecting shelf-life control across high-volume retail supply.
Regional Highlights
- Italy records a circular material use rate of 21.6% against a European average of 12.2%, which widens domestic recovery supply [2]
- Spain, the United Kingdom, the USA, Australia, and Japan advance on producer fees, lightweighting programs, and packaging reform agendas.
Market Size & Forecast
Table 1: Market Size and Forecast for the Advanced Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 50.1 billion |
| Estimated Market Size in 2026 | USD 54.0 billion |
| Projected Market Size by 2036 | USD 114.4 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 60.4 billion |
FMI research indicates that converters face margin pressure as producer fees start pricing recyclability into packaging choices. In October 2025, U.S. Environmental Protection Agency data documented 82.2 million tons of packaging at 28.1% of municipal waste [3]. That weight burden pushes buyers toward flexible packaging formats qualified for recovery streams and shelf performance.
Installed Base and Pack-Volume Sizing
Table 2: Installed Base and Pack-Volume Sizing for the Advanced Packaging Market (USD billion and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 50.1 | 54.0 | 114.4 |
| Rigid containers revenue (USD billion) | 25.2 | 27.1 | 57.4 |
| Recycled paperboard revenue (USD billion) | 19.2 | 20.7 | 43.8 |
| Food and beverage revenue (USD billion) | 22.4 | 24.1 | 51.1 |
Per-Unit and Facility Spending Indicators
Table 3: Per-Unit and Facility Spending Indicators for the Advanced Packaging Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Converting facilities worldwide (thousand) | 17.5 | 18.0 | 21.5 |
| Market spend per facility (USD million) | 2.9 | 3.0 | 5.3 |
| Food and beverage spend per facility (USD million) | 1.3 | 1.3 | 2.4 |
| Rigid container spend per facility (USD million) | 1.4 | 1.5 | 2.7 |
Table 4: Facility and Channel Spend Concentration for the Advanced Packaging Market (USD billion and shares), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 54.0 billion | Report value |
| Rigid containers revenue, 2026 | USD 27.1 billion | 50.2% share |
| Recycled paperboard revenue, 2026 | USD 20.7 billion | 38.3% share |
| Food and beverage revenue, 2026 | USD 24.1 billion | 44.7% share |
Analyst Perspective
"Material reduction holds only where packs still protect products through filling and transport to retail handling. Converters that prove barrier strength and recovery grades will secure longer supply agreements with brand owners."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Advanced Packaging Market segmented?
Advanced packaging market is segmented by three primary commercial axes and region.
By packaging format: rigid containers and bottles, flexible wraps and bags, and secondary bulk packaging.
By material substrate: recycled paperboard, thermoplastic polymers, sustainable plant fibers, and specialty alloys.
By end-use sector: food and beverage, pharmaceuticals and healthcare, personal care and homecare, and industrial manufacturing.
Why do rigid containers retain a notable packaging format share?
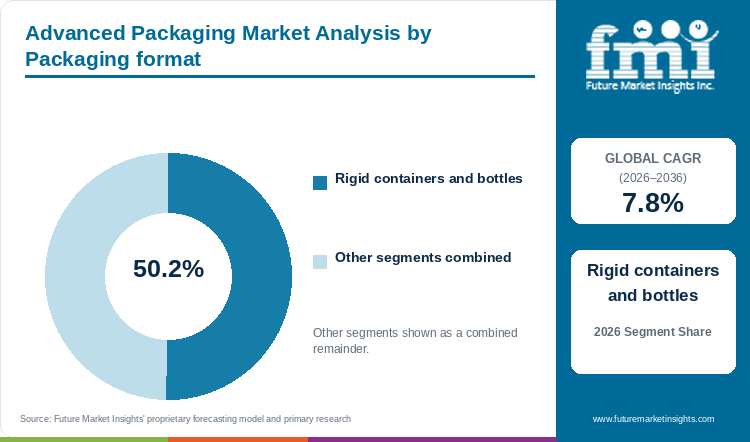
Rigid containers and bottles represent 50.2% of packaging format in 2026, balancing stack protection with standardized dispensing performance.
Table 5: Packaging Format Share for the Advanced Packaging Market (percentage share), 2026
| Packaging Format | Share, 2026 |
|---|---|
| Rigid containers and bottles | 50.2% |
| Other formats combined | 49.8%* |
Table 6: Packaging Format Leadership and Market Growth for the Advanced Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Leading packaging format, 2026 | Rigid containers and bottles, 50.2% |
| Market CAGR, 2026 to 2036 | 7.8% |
| Added market revenue, 2026 to 2036 | USD 60.4 billion |
Rigid packs keep shape under stacking and support closures and controlled dispensing. Food and beverage lines favor the structure, and demand for food packaging keeps qualification volumes steady across retail programs.
- By packaging format, rigid containers and bottles are forecast to represent 50.2% in 2026, underpinned by refill and reuse trials.
- In January 2026, Mondi Group received nine WorldStar Packaging Awards for fiber-based protective formats entering retail supply [4]
What supports recycled paperboard as the preferred material substrate?
Material substrate demand is forecast to be led by recycled paperboard at 38.3% share in 2026, supported by curbside recovery.
Recycled paperboard converts into cartons, sleeves, and dividers without new collection routes. Coating and caliper adjustments extend the grade, and paper packaging investment follows mill recovery performance across regulated regions.
- Recycled paperboard is set to lead the material substrate with 38.3% share in 2026, linked to predictable fiber supply contracts.
- In October 2025, the U.S. Environmental Protection Agency reported corrugated boxes recycling at 96.5%, which steadies fiber input planning [5]
How does food and beverage sustain end-use sector demand?
Food and beverage is projected to hold 44.7% share in 2026, driven by chilled distribution needs and date-label turnover.
Food and beverage packs combine barrier control with high line speeds and frequent format changes. Seal integrity testing governs supplier approval, while pharmaceutical packaging lines show how validation discipline transfers across regulated filling.
- Food and beverage is likely to capture 44.7% share in 2026, attributed to waste reduction targets across retail chains.
- In June 2025, PackUK confirmed packaging producer base fees, with modulation from 2026 that rewards more recyclable formats [6]
What are the drivers, restraints, and opportunities in the Advanced Packaging Market?
In the advanced packaging market, the key driver is product protection, the key restraint is material complexity, and the key opportunity is recyclable redesign.
- Driver: Shelf-life control and transport protection expand adoption where damaged products cost more than the package.
- Restraint: Multilayer and mixed-material structures can limit sorting or recycled-content use despite preserving the product.
- Opportunity: Recyclability-linked fees and recycled-material targets open demand for mono-material and fiber-based formats.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Eurostat data extracted in October 2025 put EU packaging waste at 177.8 kg per inhabitant in 2023, down 8.7 kg per person from 2022, which keeps reduction mandates on legislative agendas [7]. Food brands therefore specify barrier layers and closures that extend saleable life across long chilled distribution routes. In November 2025, Amcor announced expanded high-barrier flexible packaging capacity in North America for food and healthcare programs [8]. That capacity protects perishable shipments where protective packaging performance decides whether goods arrive saleable or written off. Procurement teams then convert successful line trials into multi-year supply agreements with qualified regional converters. Volume growth follows since waste avoidance now carries a measurable cost benefit for retailers. Reorder rates climb where damage claims fall quarter over quarter.
Risk Assessment of the Advanced Packaging Market: Operational and Material Friction
Multilayer films and mixed-material closures complicate sorting where recovery plants run single-stream separation lines. Heat-sealed barrier layers delaminate under repulping, which lowers recycled fiber yield and raises reject volumes. In July 2025, Japan's trade ministry reviewed plastic packaging recycling and reported quality limits across 57% of collected volumes [9]. European rules require all packaging to be recyclable from 2030, which pressures mixed-material structures directly [10]. Suppliers answer with metal packaging components and mono films that pass sorting trials without losing barrier function. Qualification teams then set recycled-content thresholds that mixed structures struggle to meet at scale. Converters that simplify structures early protect their approved vendor positions with large brand owners.
Commercial Opportunity Analysis: Material Differentiation and Value-Add Formats
FMI analysis finds that recyclability-linked fees turn pack design into a recurring cost decision for brand owners. Mono-material films and fiber-based trays gain where they hold barriers and still pass recovery screens. In May 2026 Smurfit Westrock published 2030 targets cutting emissions 28%, water intake 22% and landfill waste 24% [11]. In January 2026, Tetra Pak announced an investment of EUR 60 million to establish a new paper-based barrier pilot plant at its facility in Lund, Sweden, with production planned to begin in the first quarter of 2027 [12]. These moves show how recyclable packaging suppliers convert compliance pressure into qualified commercial volumes.
Advanced Packaging Market by Country (2026 to 2036)
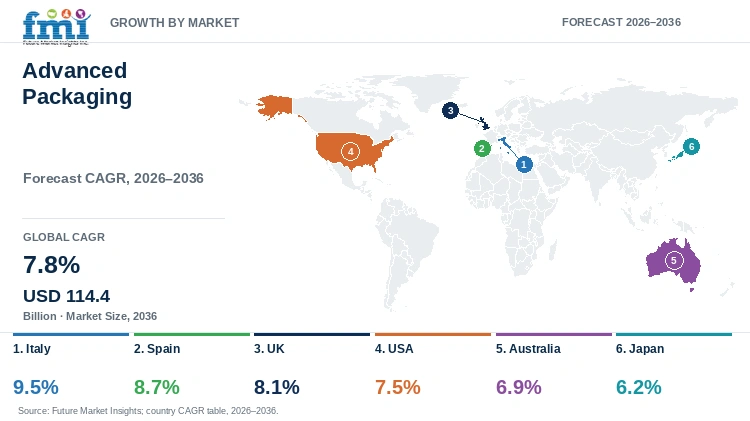
As per Future Market Insights, Italy leads six evaluated countries at 9.5% CAGR, while Japan trails at 6.2%. Across all six covered economies commercial success depends on navigating producer fees and sustaining barrier performance and overcoming sorting limits through 2036.
Table 7: Country CAGR and Primary Growth Levers for the Advanced Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 9.5% | Circular material use and EU packaging compliance |
| Spain | 8.7% | Circular-economy financing and producer registration |
| UK | 8.1% | Producer fees rewarding recyclable packaging |
| USA | 7.5% | Lightweighting and material recovery scale |
| Australia | 6.9% | Packaging reform and design standards |
| Japan | 6.2% | Advanced sorting and food-contact controls |
Italy Advanced Packaging Market Outlook (2026 to 2036)
Italy's packaging market runs on circular-economy compliance, where converters prove recovery grades before volume talks begin. In 2025, Italy's national packaging consortium advanced prevention and recovery programs across paper, plastic and metal streams [13]. By 2036, Italy is projected to grow at 9.5% CAGR, linked to closed-loop fiber capacity and steady retail demand. While municipal collection coverage varies by region, northern converting hubs offset gaps with imported recovered fiber. Suppliers respond with lightweight corrugated grades that hold stacking strength and meet fee modulation thresholds. Brand owners then place repeat orders where documented recovery grades lower their producer fee exposure. That loop keeps Italian lines running at high utilization through the assessment period.
Key takeaway: In Italy, circular compliance spending converts directly into repeat converter volumes.
Spain Advanced Packaging Market Outlook (2026 to 2036)
Public circular-economy financing sets Spain apart, pulling converter investment toward ecodesign and plastics recovery. During 2025, Spain's recovery and transformation instrument channelled funding into reuse pilots and waste-management upgrades [14]. Spain is estimated to post 8.7% CAGR over the forecast period, supported by funded sorting upgrades and producer registration. Yet commercial uptake faces friction from uneven regional collection, which slows feedstock consistency for recyclers. Suppliers counter with mono-material pouches and trays tuned to domestic sorting screens and retail private-label needs. Successful pilots convert into provincial supply contracts once recovery yields stabilize across seasons. Momentum therefore builds project by project rather than through sudden national line conversion.
Key takeaway: In Spain, funded circular projects turn pilot lines into provincial supply contracts.
UK Advanced Packaging Market Outlook (2026 to 2036)
Producer responsibility economics dominate the UK, where fees move household disposal costs onto packaging decisions. In 2025, the UK packaging producer register brought obligated brands into a single reporting and payment system [15]. Advanced packaging demand in the UK is forecast to rise at 8.1% CAGR over the forecast period, driven by fee modulation rewards. However, small brands face reporting burdens that delay format switches until fee differentials widen further. Suppliers ease the shift with recyclability audits and pack redesigns that lift grades without hurting shelf presence. Retailers then list compliant formats faster, which shortens the path from trial to national rollout. Fee savings fund the next redesign cycle for early movers.
Key takeaway: In the UK, fee modulation turns recyclability grades into listing advantages.
USA Advanced Packaging Market Outlook (2026 to 2036)
Sheer consumption scale defines the USA, where converting capacity and e-commerce volumes dwarf other evaluated markets. Federal packaging data recorded 33.3 million tons of corrugated boxes for 2018, with the series refreshed online in October 2025 [16]. The USA advanced packaging outlook is anticipated to advance at 7.5% CAGR over the assessment period, carried by lightweighting programs. The central commercial obstacle involves freight-driven cost pressure, which punishes overweight or damage-prone formats. Suppliers answer with right-sized corrugated systems and high-strength lightweight films validated for parcel networks. National retailers then consolidate vendors that prove damage-rate cuts across distribution centers. Scale advantages compound once a format clears qualification with two or more national accounts.
Key takeaway: In the USA, parcel-scale qualification turns lightweight formats into national contracts.
Australia Advanced Packaging Market Outlook (2026 to 2036)
National packaging reform gives Australia its tempo, as governments align design standards with recovery targets. In 2025, the federal environment department progressed national packaging reform toward stronger design and recovery rules [17]. Adoption of advanced packaging in Australia is estimated to expand at 6.9% CAGR through 2036, steered by standards alignment. Nonetheless, long transport distances raise delivered costs for regional buyers outside eastern seaboard hubs. Suppliers respond with concentrated regional stocking and formats rated for extended road and rail handling. Grocery and healthcare buyers then standardize approved packs that survive the journey without extra overwraps. Compliance readiness becomes the commercial edge as reform timelines tighten across states.
Key takeaway: In Australia, reform readiness turns compliant packs into preferred supply.
Japan Advanced Packaging Market Outlook (2026 to 2036)
Recycled-material quality discipline sets Japan apart, where food-contact controls keep sorting and washing central. In 2025, Japan's trade and industry ministry continued reviews of plastic packaging recycling quality and supply barriers [18]. The Japan advanced packaging sector is projected to record 6.2% CAGR during the assessment period, held to steady replacement cycles. Nevertheless, strict quality thresholds reject mixed bales that other markets still accept for processing. Suppliers adapt with high-purity mono films and washed recycled grades certified for sensitive applications. Domestic converters then lock in annual volumes once grades clear customer acceptance protocols. Precision supply beats low price in a market that pays for consistency.
Key takeaway: In Japan, certified material purity turns strict thresholds into durable supply positions.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Advanced Packaging Market?
Future Market Insights analysis indicates that competition splits across fiber systems plus flexible, rigid packaging, metal and protective formats. Scale in mono material packaging development separates integrated groups from regional converters serving nearby filling lines. Buyers reviewing pharmaceutical contract packaging share analysis work apply the same qualification logic to regulated food and healthcare packs.
- Fiber and paper systems: Smurfit Westrock plc, Mondi plc, Sonoco Products Company, and Huhtamaki Oyj serve cartons, corrugated, molded fiber, and flexible paper formats.
- Flexible and protective packaging: Sealed Air Corporation and Amcor plc compete through films, protective systems, and application engineering. Berry Global Group, Inc. was acquired by Amcor plc and completed its merger on April 30, 2025.
- Metal and rigid containers: Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. supply beverage, food, aerosol, closure, and specialty container systems.
Notable companies include Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company, Amcor plc, and Berry Global Group, Inc. These companies operate across fiber, flexible, rigid, metal, and protective packaging.
Competitive Benchmarking: Advanced Packaging Market
Table 8: Competitive Benchmarking for the Advanced Packaging Market (qualitative capability ratings), 2026
| Company | Portfolio breadth | Current activity | Geographic reach |
|---|---|---|---|
| Smurfit Westrock plc | High | High | High |
| Sealed Air Corporation | Medium | Medium | High |
| Ball Corporation | Medium | High | High |
| Crown Holdings, Inc. | Medium | High | High |
| Silgan Holdings Inc. | Medium | Medium | Medium |
| Huhtamaki Oyj | High | Medium | Medium |
| Mondi plc | High | Medium | High |
| Sonoco Products Company | Medium | Medium | Medium |
| Amcor plc | High | High | High |
| Berry Global Group, Inc. | High | High | High |
Scoring basis: High indicates broad evidence across the rated aspect; Medium indicates a focused or regional position; Low indicates limited public evidence. Ratings do not represent quality or market share.
Key Developments in the Advanced Packaging Market
- In March 2026, Sealed Air advanced automated protective packaging systems for fulfillment centers handling fragile goods [19]
- In November 2025, Ball Corporation expanded aluminum can supply programs linked to recycled-content goals [20]
- In June 2025, Amcor developed recyclable flexible films for personal care refill and reuse packaging formats [22]
Key Players in the Advanced Packaging Market
Fiber and Paper Systems
- Smurfit Westrock plc
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
Flexible and Protective Systems
- Sealed Air Corporation
- Amcor plc
- Berry Global Group, Inc.
Metal and Rigid Container Systems
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
Advanced Packaging Market - Report Scope
Table 9: Report Scope for the Advanced Packaging Market (coverage fields and definitions), 2026 to 2036
| Scope item | Coverage |
|---|---|
| Base year | 2025 |
| Forecast start | 2026 |
| Forecast end | 2036 |
| Market unit | USD billion |
| Commercial axes | Packaging format; material substrate; end-use sector |
| Regions | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Included | Rigid, flexible, secondary bulk, fiber, polymer, metal, and plant-fiber packaging within the defined applications |
| Excluded | Packaging machinery, labels sold separately, logistics services, and waste-management revenue |
Advanced Packaging Market - Research Methodology
Table 10: Research Methodology for the Advanced Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers and distributors plus procurement teams and subject-matter experts across converting and filling operations. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other publicly available sources relevant to the market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches across format, substrate, and end-use demand. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, packaging demand drivers, regulatory timelines, and historical trend analysis to support accuracy without double counting adjacent categories. |
Advanced Packaging Market by Segments
Packaging format
- Rigid containers and bottles
- Flexible wraps and bags
- Secondary bulk packaging
Material substrate
- Recycled paperboard
- Thermoplastic polymers
- Sustainable plant fibers
- Specialty alloys
End-use sector
- Food and beverage
- Pharmaceuticals and healthcare
- Personal care and homecare
- Industrial manufacturing
Advanced Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Environmental Protection Agency. (2026, June 23). Sustainable materials management basics. U.S. EPA Sustainable Materials Management.
- [2] Eurostat. (2025). Circular material use rate by member state, 2024 reporting year. European Commission Data Browser.
- [3] U.S. Environmental Protection Agency. (2025, October 23). Containers and packaging: Product-specific data. U.S. EPA Facts and Figures.
- [4] Mondi Group. (2026, January). Nine WorldStar Packaging Awards 2026 for sustainable packaging innovations. Mondi Corporate News.
- [5] U.S. Environmental Protection Agency. (2025, October 23). Corrugated box recovery statistics within containers and packaging data. U.S. EPA Facts and Figures.
- [6] PackUK. (2025, June). Extended producer responsibility for packaging: Base fees and modulation policy. UK Government Packaging Scheme Administrator.
- [7] Eurostat. (2025, October 10). Packaging waste statistics (data extracted 10 October 2025). Statistics Explained.
- [8] Amcor plc. (2025, November 15). Strategic expansion of high-barrier flexible packaging capabilities in North America. Amcor Press Releases.
- [9] Ministry of Economy, Trade and Industry, Japan. (2025, July). Plastic container and packaging recycling: Challenges and measures. METI Policy Reviews.
- [10] European Parliament and Council. (2025, February 11). Regulation (EU) 2025/40 on packaging and packaging waste. Official Journal of the European Union.
- [11] Smurfit Westrock plc. (2026, May 12). Better Planet 2030 targets: Emissions, water intake, and landfill waste. Smurfit Westrock Press Releases.
- [12] Tetra Pak. (2026, January 26). Tetra Pak invests EUR 60 million in owned pilot plant to advance its paper-based barrier technology development. Tetra Pak Press Releases.
- [13] CONAI. (2025). Packaging recovery program results and prevention plan. Italian National Packaging Consortium.
- [14] Ministry for the Ecological Transition and the Demographic Challenge, Spain. (2025). PERTE for the circular economy: Project calls and funding lines. Government of Spain.
- [15] PackUK. (2025). Producer registration guidance under packaging extended producer responsibility. UK Government Packaging Scheme Administrator.
- [16] U.S. Environmental Protection Agency. (2025, October 23). Corrugated box generation volumes within containers and packaging data. U.S. EPA Facts and Figures.
- [17] Department of Climate Change, Energy, the Environment and Water, Australia. (2025). Packaging regulation reform: National design standards. Australian Government.
- [18] Ministry of Economy, Trade and Industry, Japan. (2025). Resource circulation and containers and packaging recycling updates. METI Policy Reviews.
- [19] Sealed Air Corporation. (2026, March). Automated protective packaging systems for fulfillment operations. Sealed Air News.
- [20] Ball Corporation. (2025, November). Aluminum can supply programs supporting recycled-content goals. Ball News Releases.
- [21] Crown Holdings, Inc. (2025, September). Beverage can lightweighting trials across European lines. Crown News.
- [22] Amcor plc. (2025, June). Recyclable flexible films for personal care refill and reuse applications. Amcor Press Releases.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the advanced packaging market in 2026 and what is forecast for 2036?
- Which protection and recovery pressures support demand for advanced packaging?
- Why do rigid containers and bottles lead the packaging format category?
- Why does recycled paperboard lead the material substrate category?
- How do growth outlooks differ across Italy, Spain, the UK, and the USA?
- Which leading companies supply relevant packaging categories today?
- What limits adoption or supplier switching in the advanced packaging market?
- What should buyers evaluate before purchasing advanced packaging systems?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging format, 2026 to 2036
- Rigid containers and bottles
- Flexible wraps and bags
- Secondary bulk packaging
- Y-o-Y Growth Trend Analysis By Packaging format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging format, 2026 to 2036
- Global Market Analysis and Forecast, By Material substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material substrate, 2026 to 2036
- Recycled paperboard
- Thermoplastic polymers
- Sustainable plant fibers
- Specialty alloys
- Y-o-Y Growth Trend Analysis By Material substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-use sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use sector, 2026 to 2036
- Food and beverage
- Pharmaceuticals and healthcare
- Personal care and homecare
- Industrial manufacturing
- Y-o-Y Growth Trend Analysis By End-use sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging format
- By Material substrate
- By End-use sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging format
- By Material substrate
- By End-use sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging format
- By Material substrate
- By End-use sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging format
- By Material substrate
- By End-use sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Smurfit Westrock plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sealed Air Corporation
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
- Amcor plc
- Berry Global Group, Inc.
- Smurfit Westrock plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 19: East Asia Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 20: East Asia Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 23: South Asia and Pacific Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 24: South Asia and Pacific Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
- Table 25: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Middle East and Africa Market Value (USD Billion) Forecast by Packaging format, 2021 to 2036
- Table 27: Middle East and Africa Market Value (USD Billion) Forecast by Material substrate, 2021 to 2036
- Table 28: Middle East and Africa Market Value (USD Billion) Forecast by End-use sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging format
- Figure 6: Global Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-use sector
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 22: North America Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 23: North America Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 24: North America Market Attractiveness Analysis by Packaging format
- Figure 25: North America Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 26: North America Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 27: North America Market Attractiveness Analysis by Material substrate
- Figure 28: North America Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 29: North America Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 30: North America Market Attractiveness Analysis by End-use sector
- Figure 31: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: Latin America Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 33: Latin America Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 34: Latin America Market Attractiveness Analysis by Packaging format
- Figure 35: Latin America Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 36: Latin America Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 37: Latin America Market Attractiveness Analysis by Material substrate
- Figure 38: Latin America Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 39: Latin America Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 40: Latin America Market Attractiveness Analysis by End-use sector
- Figure 41: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: Western Europe Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 43: Western Europe Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 44: Western Europe Market Attractiveness Analysis by Packaging format
- Figure 45: Western Europe Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 46: Western Europe Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 47: Western Europe Market Attractiveness Analysis by Material substrate
- Figure 48: Western Europe Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 49: Western Europe Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 50: Western Europe Market Attractiveness Analysis by End-use sector
- Figure 51: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: East Asia Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 53: East Asia Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 54: East Asia Market Attractiveness Analysis by Packaging format
- Figure 55: East Asia Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 56: East Asia Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 57: East Asia Market Attractiveness Analysis by Material substrate
- Figure 58: East Asia Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 59: East Asia Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 60: East Asia Market Attractiveness Analysis by End-use sector
- Figure 61: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: South Asia and Pacific Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 63: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 64: South Asia and Pacific Market Attractiveness Analysis by Packaging format
- Figure 65: South Asia and Pacific Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 66: South Asia and Pacific Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 67: South Asia and Pacific Market Attractiveness Analysis by Material substrate
- Figure 68: South Asia and Pacific Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 69: South Asia and Pacific Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 70: South Asia and Pacific Market Attractiveness Analysis by End-use sector
- Figure 71: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 72: Middle East and Africa Market Value Share and BPS Analysis by Packaging format, 2026 and 2036
- Figure 73: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging format, 2026-2036
- Figure 74: Middle East and Africa Market Attractiveness Analysis by Packaging format
- Figure 75: Middle East and Africa Market Value Share and BPS Analysis by Material substrate, 2026 and 2036
- Figure 76: Middle East and Africa Market Y-o-Y Growth Comparison by Material substrate, 2026-2036
- Figure 77: Middle East and Africa Market Attractiveness Analysis by Material substrate
- Figure 78: Middle East and Africa Market Value Share and BPS Analysis by End-use sector, 2026 and 2036
- Figure 79: Middle East and Africa Market Y-o-Y Growth Comparison by End-use sector, 2026-2036
- Figure 80: Middle East and Africa Market Attractiveness Analysis by End-use sector
- Figure 81: Global Market - Tier Structure Analysis
- Figure 82: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the advanced packaging market in 2026, and what is forecast for 2036?
The market is forecast at USD 54.0 billion in 2026 and USD 114.4 billion by 2036, advancing at 7.8% CAGR.
What is the CAGR for the advanced packaging market from 2026 to 2036?
FMI finds the market expanding at 7.8% CAGR over the assessment period, generating USD 60.4 billion in added revenue.
Which packaging format segment leads the advanced packaging market?
Future Market Insights projects rigid containers and bottles at 50.2% of format revenue in 2026.
Which material substrate segment leads the advanced packaging market?
Recycled paperboard is estimated at 38.3% of substrate revenue in 2026, linked to fiber recovery networks.
Which country has a notable growth outlook during the assessment period?
Italy is projected at 9.5% CAGR through 2036, while Japan records 6.2% amid sorting quality constraints.
Who are the key players in the market?
Key participants include Smurfit Westrock, Sealed Air, Ball, Crown, Silgan, Huhtamaki, Mondi, Sonoco, Amcor, and Berry Global. Suppliers compete on barrier performance, recovery grades, and line qualification support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
