
- Industry Size (2026)
- USD 5.47 Bn
- Forecast (2036)
- USD 8.99 Bn
- CAGR (2026 to 2036)
- 5.1%
How Big Is the Alimentary Tract Implant Market in 2026?
The global alimentary tract implant market is valued at USD 5.47 billion in 2026, up from USD 5.21 billion in 2025, and is projected by Future Market Insights (FMI) to reach USD 8.99 billion by 2036, expanding at a 5.1% CAGR from 2026 to 2036 and generating USD 3.52 billion in incremental revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 5.21 billion |
| 2026 Market Size (Estimated) | USD 5.47 billion |
| 2036 Market Size (Projected) | USD 8.99 billion |
| Compound Annual Growth Rate (2026 to 2036) | 5.1% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 3.52 billion |
| Dominant Product Type (2026 to 2036 Share) | Bariatric Restriction and Balloons (32.0% in 2026, falling to 29.0% by 2036) |
| Leading & Fastest-Growing Variants | Obesity and Metabolic Control (40.0% share in 2026; 4.6% CAGR) | Strictures and Leaks (5.9% CAGR) |
| Leading & Fastest-Growing Channels | Hospitals (58.0% share in 2026; 4.5% CAGR) | Ambulatory Surgery Centers (6.4% CAGR) |
| Largest Country Markets (2026 Global Share) | United States (37.0%), China (9.0%), Germany (7.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | China (6.3% CAGR), Brazil (5.9% CAGR), United States (4.8% CAGR) |
| Leading Tier-1 Companies | Boston Scientific Corporation, Medtronic plc, Enterra Medical, Inc., Johnson & Johnson MedTech (Ethicon, including Torax Medical), Coloplast A/S, Cook Medical, B. Braun SE, Micro-Tech Endoscopy (Hangzhou) Co., Ltd., EndoStim, Inc. |
Source: Future Market Insights analysis of the alimentary tract implant market, 2026.
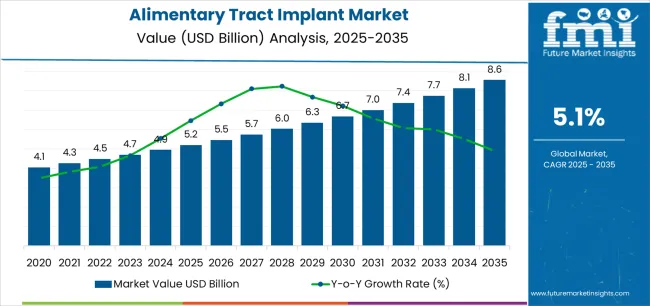
Executive Market Overview
Revenue from alimentary tract implants comes from devices placed in or around the gastrointestinal tract: intragastric balloons and bariatric restriction systems, GI stents and scaffolds, gastric stimulators and sphincter support implants. Bariatric restriction devices and balloons take about 32% of sales and obesity or metabolic control accounts for roughly 40% of use by indication, with bariatric centers and advanced endoscopy units as the main buyers. Country outlooks diverge widely, from 6.3% a year in China and 5.9% in Brazil down to 3.6% in Japan, where cautious guideline changes slow new indications; the United States sits just under the global pace at 4.8%.
Product ownership has consolidated around large GI and surgical device companies. Boston Scientific now sells the Orbera intragastric balloon after buying Apollo Endosurgery, and Ethicon has owned Torax Medical and its LINX reflux implant since March 2017. In August 2024 Johnson & Johnson MedTech announced a US labeling update that opens LINX to reflux patients with Barrett's esophagus. Enterra Medical has added the ReliaStim lead for gastric electrical stimulation, and its Enterra II system permits certain 1.5T MRI scans. This report covers implanted gastrointestinal and continence devices only and excludes obesity drugs, endoscopy capital equipment, surgical staples and non-implant consumables such as clips and sutures.
Analyst Perspective
"Obesity drugs have not removed the case for implants, but they have changed who gets referred, and balloon makers now have to argue for a place alongside medication instead of ahead of surgery. The steadier money is in stents and stimulators, where the patient has a mechanical problem that no injection will fix."
Anurag Sharma, Principal Consultant, Future Market Insights (FMI)
Alimentary Tract Implant Market Definition
Alimentary tract implants are medical devices placed in the gastrointestinal tract or adjacent anatomy to treat obesity, motility disorders, strictures or leaks, and continence dysfunction. Products include endoscopic gastric balloons, bariatric restriction systems, GI stents and scaffolds, and neuromodulation or sphincter support implants. Buyers include bariatric and metabolic centers, advanced endoscopy units, and colorectal pelvic floor programs that use these implants to reduce symptoms, restore function, and avoid higher-risk open surgery when minimally invasive options are clinically appropriate.
Market Inclusions
Report scope covers global and regional market sizing with a 10-year forecast from 2026 to 2036, with segmentation by implant type, indication, procedure approach, care setting, and geography. Coverage includes selected country outlooks, adoption drivers tied to clinical pathways, and competitive assessment across GI endoscopy and bariatric platforms. According to FMI’s estimates, segment sizing reflects procedure volumes, device ASPs, and setting shift from inpatient to outpatient across core markets.
Market Exclusions
Scope excludes pharmaceutical obesity therapies, endoscopy capital equipment, and non-implant consumables such as clips, sutures, and standard endoscopic accessories unless bundled within an implant system offering. Coverage also omits general surgical staples and non-GI urology implants not intended for alimentary tract or continence restoration use cases. Standalone diagnostic endoscopy, imaging, and unrelated hospital services remain outside scope.
Alimentary Tract Implant Market Research Methodology
- Primary Research: Interviews were conducted with bariatric surgeons, interventional gastroenterologists, colorectal specialists, hospital procurement directors, and medical device distributors across major markets. Reimbursement specialists and patient pathway coordinators clarified adoption barriers and follow-up requirements.
- Desk Research: Obesity prevalence data from WHO, FDA device approval and post-market surveillance documents, company investor relations disclosures, SEC merger filings, and peer-reviewed clinical safety literature supported validation and context development.
- Market-Sizing and Forecasting: A hybrid top-down and bottom-up model was developed. Demand was reconstructed from procedure volumes by indication category, device average selling prices, care setting mix shifts, and validated against manufacturer revenue disclosures and hospital procurement spending patterns.
- Data Validation and Update Cycle: Outputs undergo segment reconciliation checks, anomaly screening against clinical guideline constraints, and periodic refresh when regulatory approvals, reimbursement decisions, or device safety signals affect eligible patient populations.
Segmental Analysis
Alimentary Tract Implant Market Analysis by Implant type
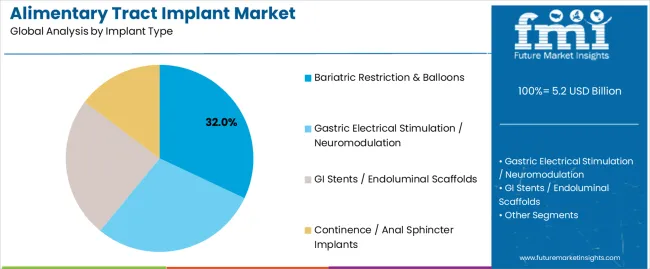
Based on FMI's alimentary tract implant market report, consumption of Bariatric Restriction & Balloons is estimated to hold 32% share in 2025. Category leadership stems from broad patient eligibility spanning BMI thresholds lower than surgical bariatric requirements, endoscopic placement avoiding surgical risk exposure, and temporary device nature enabling trial-and-escalation strategies within stepwise obesity treatment protocols that align with payer preferences for conservative intervention sequencing.
- M&A Platform Consolidation: Boston Scientific completed acquisition of Apollo Endosurgery in February 2023, consolidating endoluminal bariatric capability under integrated GI device portfolio supporting multi-site contracting and training continuity [2].
- Safety Evidence Base: Peer-reviewed analysis of FDA MAUDE adverse event data for intragastric balloons documents device types and complication patterns, reinforcing hospital requirements for defined monitoring protocols and early warning systems [3].
- Clinical Epidemiology: WHO obesity statistics indicate 1 in 8 people globally lived with obesity in 2022, strengthening case volumes for less invasive interventions where surgical capacity constraints limit access [4].
Alimentary Tract Implant Market Analysis by indication
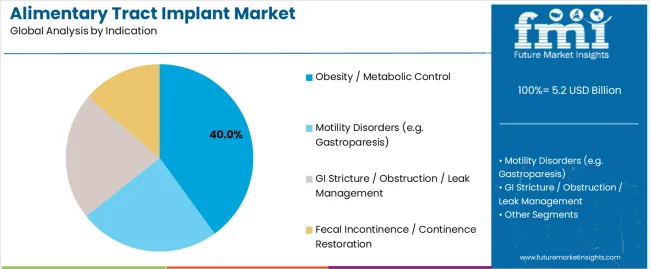
Based on FMI's alimentary tract implant market report, consumption for Obesity/Metabolic Control is estimated to hold 40% share in 2025. Indication dominance reflects concentrated procedure infrastructure within bariatric and metabolic centers, payer preference for stepwise treatment escalation beginning with endoscopic options, and volume concentration enabling specialized training and protocol standardization that reduce adoption friction versus dispersed indications requiring diverse specialist expertise across multiple service lines.
- Epidemiology Foundation: WHO reports document rising global obesity burden with prevalence doubling since 1990, sustaining clinical demand for weight management pathways [4].
- Regulatory Oversight Model: FDA post-market documentation for Enterra Therapy gastric electrical stimulation system operates under humanitarian device exemption pathway requiring annual safety reviews, illustrating specialized regulatory frameworks for complex motility indications [5].
- Device Evolution: Enterra Medical received FDA MR Conditional approval for Enterra II System in March 2024, supporting ongoing product lifecycle improvements addressing clinical usability requirements [6].
Alimentary Tract Implant Market Drivers, Restraints, Opportunities
Future Market Insights analysis links this market's size to the dual reality that obesity prevalence continues rising globally while healthcare systems simultaneously emphasize minimally invasive interventions reducing surgical risk and hospital length of stay. Alimentary tract implants are purchased because bariatric centers require devices enabling stepwise treatment escalation, advanced endoscopy units need stricture management alternatives to repeat dilation procedures, and colorectal programs seek continence restoration options addressing quality of life for fecal incontinence patients. Adoption depends on reimbursement pathway clarity, clinical evidence supporting patient selection criteria, and hospital capacity for post-procedure monitoring addressing device-specific follow-up requirements.
FMI analysts observe structural shift toward outpatient procedure settings where implants with predictable safety profiles, scheduled removal timelines, and clear adverse event management protocols gain adoption preference over devices requiring intensive monitoring or frequent revision procedures. Pricing dynamics reflect tension between device innovation commanding premium positioning and payer resistance to cost increases without demonstrated outcome improvements. Successful market penetration requires manufacturers supporting hospitals with training programs, registry participation, and safety documentation addressing committee approval requirements beyond traditional sales force engagement.
- Outpatient Pathway Pull: Care setting migration favors implants aligned with day-case workflows, predictable removal scheduling, and post-procedure monitoring supporting adoption in GI endoscopy suites and metabolic centers.
- Safety Surveillance Discipline: Post-market review cycles and adverse event reporting encourage procurement concentration on platforms with transparent real-world evidence and risk mitigation clarity [3].
- Asia Capacity Build-out: China and Brazil benefit from expanding procedure capacity and private hospital investments while mature markets grow through replacement and protocol-led adoption [1][4].
Regional Analysis
Based on the regional analysis, alimentary tract implant market is segmented into North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa across 40+ countries. Full report also offers market attractiveness analysis based on regional trends and setting-level adoption shifts.
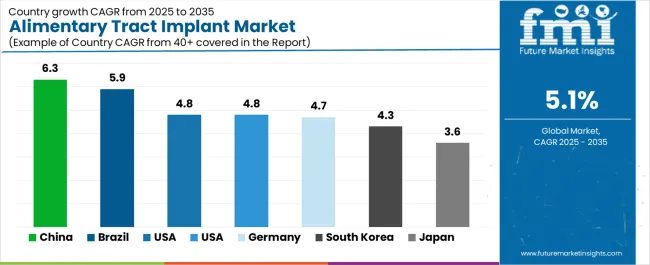
| Countries | CAGR (2026 to 2036) |
|---|---|
| China | 6.3% |
| Brazil | 5.9% |
| USA | 4.8% |
| UK | 4.8% |
| Germany | 4.7% |
| South Korea | 4.3% |
| Japan | 3.6% |
Source: Future Market Insights (FMI) analysis, based on proprietary forecasting model and primary research
North America Alimentary Tract Implant Market Analysis
North America operates as an outcomes-accountability market where reimbursement requirements, bariatric center accreditation standards, and post-market surveillance expectations shape device adoption. Boston Scientific and Medtronic maintain dominant positions through comprehensive GI portfolios supporting integrated contracting across hospital systems.
- United States: Demand for alimentary tract implants in the United States is projected to rise at 4.8% CAGR through 2036. Growth is supported by mature bariatric surgery networks comprising over 900 accredited centers capable of structured patient follow-up and safety monitoring aligned with device requirements [1]. Market expansion is driven by obesity prevalence, with WHO statistics documenting sustained high-BMI populations requiring weight management interventions where endoscopic and surgical options address clinical need [4]. FDA post-market surveillance framework influences hospital procurement decisions, with committee preferences for devices demonstrating transparent adverse event documentation and risk management protocols supporting internal program approvals [5].
FMI's analysis of alimentary tract implant market in North America consists of country-wise assessment that includes the United States and Canada. Readers can find outpatient procedure trends, reimbursement framework evolution, and competitive positioning by device category.
Europe Alimentary Tract Implant Market Analysis
Europe functions as protocol-governed market where clinical society guidelines, structured hospital procurement committees, and post-market registry requirements influence adoption. Multinational device manufacturers compete through evidence packages and training infrastructure supporting specialist education.
- Germany: Demand for alimentary tract implants in Germany is projected to rise at 4.7% CAGR through 2036. Growth tracks bariatric center expansion within quality assurance framework requiring procedure volume thresholds and outcome documentation supporting continued accreditation [4]. Committee-led procurement emphasizes safety monitoring discipline, with hospital approval processes requiring manufacturers to demonstrate post-market surveillance capabilities addressing adverse event management and patient tracking [3].
- United Kingdom: Demand for alimentary tract implants in the UK is projected to rise at 4.8% CAGR through 2036. Adoption is supported by NHS England bariatric surgery commissioning policies establishing clinical criteria and center accreditation requirements that concentrate procedures in qualified facilities capable of comprehensive patient pathway management [4].
FMI's analysis of alimentary tract implant market in Europe consists of country-wise assessment that includes Germany, United Kingdom, France, Italy, Spain, and Rest of Europe. Readers can find regulatory framework impacts, clinical guideline influences, and care setting adoption dynamics.
Asia-Pacific Alimentary Tract Implant Market Analysis
Asia-Pacific represents capacity-expansion market where procedure infrastructure development, private hospital network growth, and endoscopy utilization increases create adoption opportunities despite reimbursement heterogeneity across countries. Global device companies compete with regional distributors influencing hospital procurement decisions.
- China: Demand for alimentary tract implants in China is projected to rise at 6.3% CAGR through 2036. Growth is driven by expanding bariatric surgery capacity and advanced endoscopy program development supporting minimally invasive GI interventions [4]. Market expansion benefits from rising obesity prevalence in urban populations creating clinical demand for weight management pathways where hospital investments in specialist services enable implant program launches [1]. Device adoption requires training infrastructure and follow-up protocol development, with hospitals prioritizing platforms offering comprehensive physician education and safety monitoring guidance addressing adverse event management requirements [3].
- South Korea: Demand for alimentary tract implants in South Korea is projected to rise at 4.3% CAGR through 2036. Growth is supported by high endoscopy utilization rates and rapid adoption of minimally invasive GI procedures, though expansion remains disciplined by clinical protocols and patient selection criteria limiting broad indication expansion.
- Japan: Demand for alimentary tract implants in Japan is projected to rise at 3.6% CAGR through 2036. Growth faces constraints from conservative clinical guideline evolution and slower indication expansion resulting in replacement-driven rather than procedure-volume-driven adoption profile.
FMI's analysis of alimentary tract implant market in Asia-Pacific consists of country-wise assessment that includes China, Japan, South Korea, India, Australia, and Rest of Asia Pacific. Readers can find procedure capacity development patterns, training infrastructure requirements, and regulatory pathway variations.
Latin America Alimentary Tract Implant Market Analysis
Latin America grows through private hospital expansion and bariatric surgery center development in metropolitan areas where patient volume and follow-up infrastructure support implant program sustainability. Device manufacturers compete through distributor networks providing training and service coverage.
- Brazil: Demand for alimentary tract implants in Brazil is projected to rise at 5.9% CAGR through 2036. Growth is supported by private sector procedure capacity expansion and rising obesity burden feeding bariatric referral pathways across major metropolitan hospital networks [4]. Adoption depends on center capability for structured follow-up and complication management, reinforcing procurement preference for established platforms with documented safety profiles and clear adverse event mitigation protocols [3].
FMI's analysis of alimentary tract implant market in Latin America consists of country-wise assessment that includes Brazil, Argentina, Mexico, and Rest of Latin America. Readers can find private hospital network development, procedure volume trends, and device distribution dynamics.
Competitive Aligners for Market Players
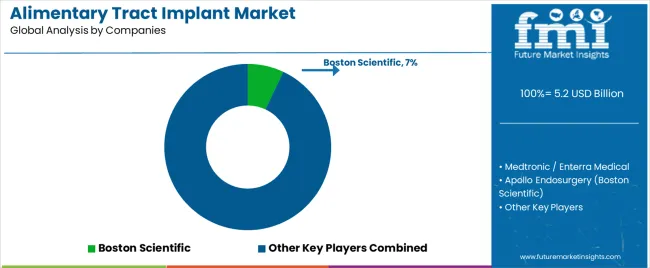
Market structure demonstrates concentration among diversified medical device companies with comprehensive GI portfolios, supplemented by specialist manufacturers focusing on specific implant categories including endoluminal bariatrics, neuromodulation, and pelvic floor devices. Competition is determined by safety governance capabilities, training infrastructure reach, and reimbursement support rather than broad product catalog expansion. Vendors aligning with hospital committee requirements for evidence documentation and post-market surveillance transparency retain pricing resilience while transaction-focused suppliers face margin pressure from protocol-driven procurement.
Structural advantages accrue to platform breadth and service infrastructure. Large manufacturers can bundle implants with procedural training, physician education, and post-procedure monitoring support reducing hospital friction for program launches. Transaction consolidation capabilities enable acquisition of specialized technologies integrating them within broader commercial infrastructure, as demonstrated by Boston Scientific's acquisition of Apollo Endosurgery consolidating endoluminal bariatric offerings under unified GI platform supporting multi-site contracting [2].
Buyer leverage concentrates in large hospital systems and bariatric networks implementing standardized procurement across facilities. Procurement committees demand outcome documentation, safety pathway transparency, and post-market evidence utilizing adverse event databases and published literature to inform approval decisions [3]. Pricing power improves when manufacturers link platforms to reduced revision rates, predictable follow-up requirements, and simplified compliance documentation addressing operational priorities for center administrators managing program economics and risk exposure.
Recent Developments
- In March 2024, Enterra Medical received FDA MR Conditional approval for Enterra II System, enhancing clinical usability in gastric electrical stimulation applications.
- In February 2023, Boston Scientific completed acquisition of Apollo Endosurgery through merger transaction documented in SEC filings, consolidating endoluminal bariatric device portfolio.
Key Players in the Alimentary Tract Implant Market
- Boston Scientific Corporation
- Medtronic plc
- Enterra Medical, Inc.
- Johnson & Johnson Services, Inc. (Ethicon)
- Coloplast A/S
- Cook Group Incorporated (Cook Medical)
- B. Braun SE
- Micro-Tech Endoscopy (Hangzhou) Co., Ltd.
- EndoStim, Inc.
- Torax Medical, Inc.
Scope of Report
| Metric | Value |
|---|---|
| Quantitative Units | USD 5.47 billion (2026) to USD 8.99 billion (2036), at a CAGR of 5.1% |
| Market Definition | Market covers implantable medical devices used within the alimentary tract and adjacent anatomy for obesity/metabolic control, motility disorders, GI obstruction/leak management, and continence restoration across endoscopic, laparoscopic, and surgical care pathways. |
| Implant Type | Bariatric Restriction & Balloons, Gastric Electrical Stimulation/Neuromodulation, GI Stents/Endoluminal Scaffolds, Continence/Anal Sphincter Implants |
| Indication | Obesity/Metabolic Control, Motility Disorders, GI Stricture/Obstruction/Leak Management, Fecal Incontinence/Continence Restoration |
| Procedure Approach | Endoscopic/Transoral, Laparoscopic Bariatric, Open/Revision Surgery, Colorectal/Perineal Implantation |
| Care Setting | Bariatric & Metabolic Centers, GI & Advanced Endoscopy Suites, Colorectal/Pelvic Floor Centers, Hospital OR/Other Acute Care |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | USA, UK, Germany, France, Japan, South Korea, China, Brazil, and 40+ countries |
| Key Companies Profiled | Boston Scientific Corporation, Medtronic plc, Enterra Medical, Inc., Johnson & Johnson Services, Inc. (Ethicon), Coloplast A/S, and other leading alimentary tract implant companies |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up modelling validated through primary interviews with clinicians and procurement teams, triangulated with regulator documents, company filings, and peer-reviewed clinical evidence |
Alimentary Tract Implant Market Analysis by Segments
Implant Type:
- Bariatric Restriction & Balloons
- Gastric Electrical Stimulation/Neuromodulation
- GI Stents/Endoluminal Scaffolds
- Continence/Anal Sphincter Implants
Indication:
- Obesity/Metabolic Control
- Motility Disorders
- GI Stricture/Obstruction/Leak Management
- Fecal Incontinence/Continence Restoration
Procedure Approach:
- Endoscopic/Transoral
- Laparoscopic Bariatric
- Open/Revision Surgery
- Colorectal/Perineal Implantation
Care Setting:
- Bariatric & Metabolic Centers
- GI & Advanced Endoscopy Suites
- Colorectal/Pelvic Floor Centers
- Hospital OR/Other Acute Care
Region:
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- Kingdom of Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East & Africa
Bibliography
- Boston Scientific. (2025). Orbera Intragastric Balloon System. https://www.bostonscientific.com/en-US/products/endoluminal-surgery-devices/orbera-intragastric-balloon-system.html
- EndoStim. (2022, October 25). EndoStim Receives FDA Breakthrough Device Designation. http://endostim.com/endostim-receives-fda-breakthrough-device-designation/
- Enterra Medical, Inc. (2025). Newsroom Archive. https://www.enterramedical.com/newsroom/
- Johnson & Johnson. (2024, August 7). Johnson & Johnson MedTech Announces Labeling Amendment of LINX Reflux Management System in the U.S. to Include Patients with Barrett's Esophagus Experiencing Gastroesophageal Reflux Disease. https://www.jnj.com/media-center/press-releases/johnson-johnson-medtech-announces-labeling-amendment-of-linx-reflux-management-system-in-the-u-s-to-include-patients-with-barretts-esophagus-experiencing-gastroesophageal-reflux-disease
- U.S. Food and Drug Administration. (2015). ORBERA Intragastric Balloon System: Summary of Safety and Effectiveness Data (P140008). https://www.accessdata.fda.gov/cdrh_docs/pdf14/P140008c.pdf
This Report Addresses
- Market intelligence to support strategic planning across bariatric, endoscopy, and colorectal implant pathways
- Market size estimation and 10-year revenue forecast from 2026 to 2036 using validated modelling inputs
- Growth opportunity mapping by implant type, indication, procedure approach, and care setting adoption
- Regional and country outlooks covering North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa
- Competitive strategy assessment covering portfolio positioning, training coverage, and evidence-based procurement drivers
- Product and safety monitoring tracking using regulator documents and published safety literature where relevant
- Regulatory and policy impact framing for device adoption pathways and hospital approval requirements
- Report delivery formats suitable for executive and operational use, including PDF, Excel tables, and presentation-ready extracts
Table of Content
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
Read More...
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Company Annual and Sustainability Reports
- Peer-reviewed Journals and Academic Literature
- Corporate Websites, Product Literature, and Technical Notes
- Earnings Decks and Investor Briefings
- Statutory Filings and Regulatory Disclosures
- Technical White Papers and Standards Notes
- Trade Journals, Industry Magazines, and Analyst Briefs
- Conference Proceedings, Webinars, and Seminar Materials
- Government Statistics Portals and Public Data Releases
- Press Releases and Reputable Media Coverage
- Specialist Newsletters and Curated Briefings
- Sector Databases and Reference Repositories
- FMI Internal Proprietary Databases and Historical Market Datasets
- Subscription Datasets and Paid Sources
- Social Channels, Communities, and Digital Listening Inputs
- Additional Desk Sources
- Expert Input and Fieldwork (Primary Evidence)
- Primary Modes
- Qualitative Interviews and Expert Elicitation
- Quantitative Surveys and Structured Data Capture
- Blended Approach
- Why Primary Evidence is Used
- Field Techniques
- Interviews
- Surveys
- Focus Groups
- Observational and In-context Research
- Social and Community Interactions
- Stakeholder Universe Engaged
- C-suite Leaders
- Board Members
- Presidents and Vice Presidents
- R&D and Innovation Heads
- Technical Specialists
- Domain Subject-matter Experts
- Scientists
- Physicians and Other Healthcare Professionals
- Governance, Ethics, and Data Stewardship
- Research Ethics
- Data Integrity and Handling
- Primary Modes
- Tooling, Models, and Reference Databases
- Desk Research Programme (Secondary Evidence)
- Data Engineering and Model Build
- Data Acquisition and Ingestion
- Cleaning, Normalisation, and Verification
- Synthesis, Triangulation, and Analysis
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics
- Drivers
- Restraints
- Opportunity
- Trends
- Scenario Forecast
- Demand in Optimistic Scenario
- Demand in Likely Scenario
- Demand in Conservative Scenario
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter’s Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Market Dynamics
- Global Market Analysis 2021 to 2025 and Forecast, 2026 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis 2021 to 2025 and Forecast 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Implant type
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Implant type , 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Implant type , 2026 to 2036
- Bariatric Restriction & Balloons
- Gastric Electrical Stimulation/Neuromodulation
- GI Stents/Endoluminal Scaffolds
- Continence/Anal Sphincter Implants
- Bariatric Restriction & Balloons
- Y-o-Y Growth Trend Analysis By Implant type , 2021 to 2025
- Absolute $ Opportunity Analysis By Implant type , 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Indication
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Indication, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Indication, 2026 to 2036
- Obesity/Metabolic Control
- Motility Disorders
- GI Stricture/Obstruction/Leak Management
- Fecal Incontinence/Continence Restoration
- Obesity/Metabolic Control
- Y-o-Y Growth Trend Analysis By Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Indication, 2026 to 2036
- Global Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Region
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- Latin America Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- Western Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- Eastern Europe Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- East Asia Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- South Asia and Pacific Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- Middle East & Africa Market Analysis 2021 to 2025 and Forecast 2026 to 2036, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Implant type
- By Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Implant type
- By Indication
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- Turkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Implant type
- By Indication
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Implant type
- By Indication
- Competition Analysis
- Competition Deep Dive
- Boston Scientific Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments (Product/Age /Sales Channel/Region)
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Medtronic plc
- Enterra Medical, Inc.
- Johnson & Johnson Services, Inc. (Ethicon)
- Coloplast A/S
- Cook Group Incorporated (Cook Medical)
- B. Braun SE
- Boston Scientific Corporation
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 4: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 7: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 10: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 12: Western Europe Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 22: Middle East & Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 23: Middle East & Africa Market Value (USD Million) Forecast by Implant type , 2021 to 2036
- Table 24: Middle East & Africa Market Value (USD Million) Forecast by Indication, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Implant type
- Figure 6: Global Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Indication
- Figure 9: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Implant type
- Figure 23: North America Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Indication
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Implant type
- Figure 30: Latin America Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Indication
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Implant type
- Figure 37: Western Europe Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Indication
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Implant type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Indication
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Implant type
- Figure 51: East Asia Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Indication
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Implant type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Indication
- Figure 61: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East & Africa Market Value Share and BPS Analysis by Implant type , 2026 and 2036
- Figure 63: Middle East & Africa Market Y-o-Y Growth Comparison by Implant type , 2026-2036
- Figure 64: Middle East & Africa Market Attractiveness Analysis by Implant type
- Figure 65: Middle East & Africa Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 66: Middle East & Africa Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 67: Middle East & Africa Market Attractiveness Analysis by Indication
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the alimentary tract implant market in 2026?
Future Market Insights estimates the global alimentary tract implant market at USD 5.47 billion in 2026, up from USD 5.21 billion in 2025.
How fast is the alimentary tract implant market expected to grow through 2036?
FMI projects a 5.1% CAGR from 2026 to 2036, taking the global alimentary tract implant market to USD 8.99 billion by 2036 and generating USD 3.52 billion in incremental revenue.
Which implant type leads the alimentary tract implant market?
Bariatric restriction devices and balloons are the largest implant type at about 32% of sales. Balloons are placed endoscopically, are open to patients below the weight thresholds set for surgery, and are removed after a set period, so physicians can use them as a first step before escalating treatment. GI stents and scaffolds, neuromodulation systems and sphincter support implants share the rest.
Which indication generates the most demand for alimentary tract implants?
Obesity and metabolic control accounts for roughly 40% of demand, reflecting the procedure volumes concentrated in accredited bariatric and metabolic centers and payer preference for stepwise treatment. Implants for strictures and leaks are expanding more quickly, near 5.9% a year, as therapeutic endoscopy takes over cases once sent to open surgery. Motility disorders and continence make up smaller, specialist-led indications.
Where are alimentary tract implants placed?
Hospitals handle most placements, an estimated 58% of 2026 revenue, because stenting, stimulator implantation and sphincter procedures need anesthesia cover, imaging and the ability to manage complications. Ambulatory surgery centers are gaining share at about 6.4% a year as balloon placement and other endoscopic procedures move to outpatient settings with lower facility costs.
Which country is the largest alimentary tract implant market?
The United States leads the alimentary tract implant market, capturing 37.0% of global revenue in 2026 (USD 2.02 billion), followed by China at 9.0% (USD 492.3 million) and Germany at 7.0% (USD 382.9 million).
Which countries are expected to grow fastest in the alimentary tract implant market?
China and Brazil are projected to grow fastest, expanding at 6.3% and 5.9% CAGRs from 2026 to 2036, followed by the United States at 4.8%.
What drives demand for alimentary tract implant?
Rising obesity prevalence, the move of bariatric and endoscopic procedures to outpatient settings, wider use of endoscopic stenting for strictures and leaks, and expanding private hospital capacity in China and Brazil all support demand. Working against these are reimbursement scrutiny that holds prices down, competition from obesity drugs for the same patients, safety reporting requirements that follow balloon and stimulator devices after approval, and slow guideline change in markets such as Japan.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
