

- Market Size (2026)
- USD 32.1 Bn
- Forecast (2036)
- USD 58.6 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Automotive Lighting Market in 2026?
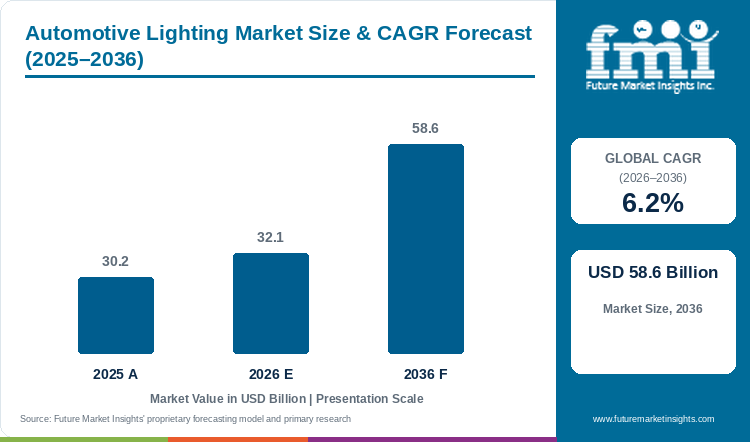
The automotive lighting market is estimated at USD 30.2 billion in 2025 and is likely to reach USD 32.1 billion in 2026. Sales of automotive lighting are projected to grow at a 6.2% CAGR and reach USD 58.6 billion by 2036.
Adoption of automotive lighting with LED and digital functions is raising the value of every lamp set, even in years of flat vehicle output. FMI expects the automotive lighting market to reach USD 32.1 billion in 2026 against USD 30.2 billion estimated for 2025, rising to USD 58.6 billion in 2036 as sales grow at a 6.2% CAGR. Within that growth, carmakers are fitting LED first in headlamps and rear signature lamps, then in cabin and ambient lighting, and headlamp makers are investing ahead of the shift. Valeo said in July 2026 that the Angers and Blois operations in France make 9,000 headlights and 22,000 complex modules a day after a modernisation of more than EUR 45 million.[1] Plants of that scale show headlamp makers betting on higher-content modules ahead of new programmes due in 2027 and 2028.
Competition is turning on cost per module, and margins are under strain. FORVIA HELLA said H1 2026 Lighting sales fell 5.3% to EUR 1,765 million, with an operating margin of 0.4% after series projects phased out.[2] A margin that thin leaves lamp makers chasing new programmes to fill plants, which strengthens carmakers in price talks. By comparison, Valeo is investing in heavy-duty headlights at Angers, and truck lamps there are expected to rise from 20% to 40% of output.[1] In turn, large lamp makers are moving capacity toward trucks and digital modules. Second-tier suppliers without LED electronics in house face the hardest squeeze, as carmakers award fewer, larger lamp programmes.
Key Market Trends & Insights
- Headlamps are expected to lead lighting type sales at 38% in 2026, as each one carries the most optics and electronics, with rear lamps near 24% and signal and indicator lamps at about 14.5%.
- LED light sources are likely to reach 61% of technology sales in 2026, more than twice the estimated 27.5% for halogen. For instance, Lumax Industries said LED products made up 63% of revenue in the June 2026 quarter.[3] Emerging-market suppliers are converting faster than the global average, which pulls halogen out of entry models.
- By vehicle type, passenger cars are projected at 72% in 2026, LCVs at about 18% and HCVs near 10%.
- First fit OEM supply is estimated to hold 83% of 2026 channel sales, as lamps are fitted on the assembly line, and the aftermarket 17%. Workshop service is changing with the lamps. On the service side, Hella Gutmann Solutions launched camera-based SEG-Tool PRO headlight alignment for workshops in September 2026.[4] Camera-based alignment lets workshops service matrix and adaptive headlamps, which keeps more repair work in the independent aftermarket.
Regional Highlights
- LED lamps reaching compact cars and two-wheelers set up the fastest country pace in India, at 8.2% in FMI's outlook, 2 points over the market rate of 6.2%.
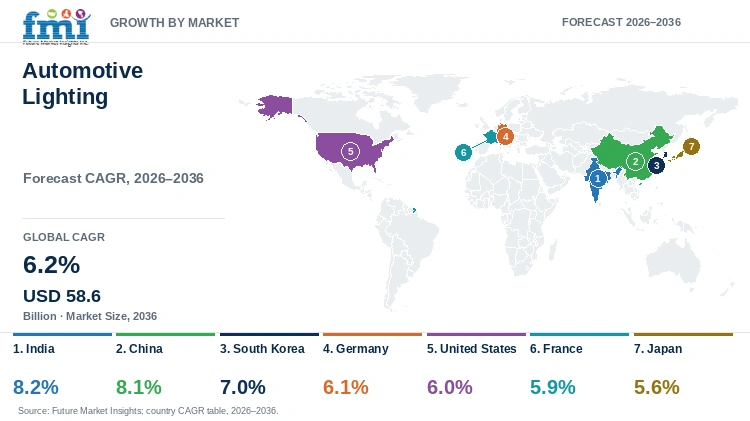
- China is 0.1 points behind India at 8.1%. After these, South Korea, at 7%, is the only other country over the global figure. Germany, the United States and France are just under the global figure, and Japan grows slowest, at 5.6%.
- Indian lamp makers are filling order pipelines with LED work. In August 2026, Lumax Industries put LED lighting at about 90% of a Rs 2,500 crore order pipeline.[3] An order mix that heavy in LED points to halogen lines closing at Indian suppliers within a few model cycles.
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Lighting Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 30.2 billion |
| Estimated Market Size in 2026 | USD 32.1 billion |
| Projected Market Size by 2036 | USD 58.6 billion |
| CAGR, 2026 to 2036 | 6.2% |
| Added Revenue, 2026 to 2036 | USD 26.5 billion |
| Market Expansion Multiple | 1.8x |
Demand for automotive lighting is moving toward fewer, larger programmes, and lamp makers are feeling the gaps between awards. For example, FORVIA HELLA cited the phase-out of series projects and lower call-offs on existing programmes for the drop in H1 2026 Lighting sales.[2] Gaps between awards therefore weigh on lamp maker volumes even when vehicle output holds. On the light source side, ams OSRAM reported automotive semiconductor revenue of EUR 231 million in Q2 2026, up 6% on the previous quarter.[5] Rising LED chip sales point to firmer lamp orders later in 2026. Beam control is spreading, and the adaptive front lighting market carries a projected 12% CAGR. Across the decade, FMI sees about USD 26.5 billion of added sales for the automotive lighting market, taking 2036 sales to roughly 1.8 times the 2026 level. However, price pressure on mass-market platforms is the main risk.
Digital Headlamps, Cabin Light and Workshop Alignment
Digital and pixel headlamps are moving from concept to quotation. For instance, Marelli presented an h-Digi microLED headlamp module in 25K and 40K pixel versions for adaptive driving beam and projection at Auto China 2026.[6] Pixel counts at that level let carmakers sell glare-free high beam and road projection as paid features. Marelli also showed a thin corner-to-corner headlamp with 15 mm by 120 mm modules.[6] At the same time, carmakers in China and Europe are asking for full-width light bars, which raises module count per vehicle.
Cabin lighting and service work are opening a second revenue stream. Inside the cab, FORVIA HELLA presented adaptive RGB interior lighting for commercial vehicle cabs in September 2026, and a major European commercial vehicle maker is using the RGB module technology in a future programme.[7] A series programme at a truck maker moves cab lighting from show feature to production volume. Meanwhile, Hella Gutmann Solutions priced the SEG-Tool PRO headlight aligner at EUR 4,590 for workshops that service matrix LED and adaptive lamps.[4] Each new lamp generation therefore brings a round of tool purchases by workshops, a recurring sale for service equipment makers.
Table 2: Digital Headlamp, Cabin Lighting and Service Indicators for the Automotive Lighting Market (sales, capacity and products), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| FORVIA HELLA Lighting sales, H1 2026 | EUR 1,765 million; down 5.3% | Margin pressure in lamp supply | [2] |
| Valeo Angers daily output, 2026 | 9,000 headlights; 22,000 complex modules | Headlamp production scale in France | [1] |
| ams OSRAM automotive semiconductor revenue, Q2 2026 | EUR 231 million; up 6% on Q1 | LED and light source demand | [5] |
| Lumax Industries LED share of revenue, Q1 FY27 | 63% | LED shift in India | [3] |
| Marelli h-Digi microLED module, 2026 | 25K and 40K pixel versions | Digital adaptive headlamps | [6] |
| Hella Gutmann SEG-Tool PRO, 2026 | EUR 4,590 | Workshop headlight alignment | [4] |
| Kia electrified share of sales, Q2 2026 | 35.3% | LED-rich electrified models | [8] |
Analyst Perspective
“Light is turning into a styling and safety signature for every carmaker, and that shift keeps value per vehicle rising faster than vehicle output. The margin, though, is moving to whoever controls the LED driver electronics and the software that animates them. I expect lamp makers with in-house electronics and pixel headlamp capability to hold the premium programmes, and plastic-and-optics assemblers to compete mainly on cost.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive lighting market segmented?
The market is segmented into lighting type, technology, vehicle type, sales channel, and region. Headlamps are expected to lead lighting type with 38% share in 2026, and LED leads technology with 61%.
By lighting type: headlamps, rear lamps, signal and indicator lamps, interior lighting, and ambient and other lighting.
By technology: LED, halogen, xenon or HID, and laser and advanced lighting.
By vehicle type: passenger cars, LCV, and HCV.
By sales channel: first fit OEM and aftermarket.
By region: vehicle assembly and service markets in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do headlamps lead automotive lighting sales by lighting type?
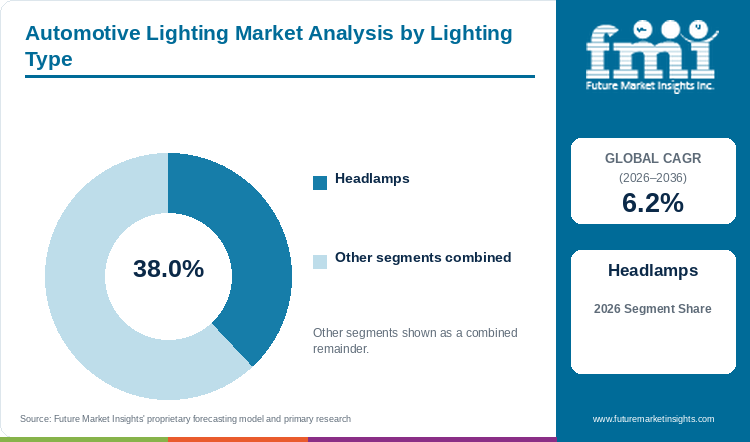
Headlamps are expected to lead lighting type sales with 38% share in 2026, ahead of rear lamps at about 24% and signal and indicator lamps at an estimated 14.5%.
Table 3: Lighting Type Share for the Automotive Lighting Market (percentage share), 2026
| Lighting Type | Estimated Share (2026) |
|---|---|
| Headlamps | 38% |
| Rear Lamps | 24% |
| Signal and Indicator Lamps | 14.5% |
| Interior Lighting | 12% |
| Ambient and Other Lighting | 11.5% |
| Total | 100.0% |
Table 4: Lighting Type Leadership and Market Growth for the Automotive Lighting Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.2% |
| Leading Segment | Headlamps |
A modern headlamp combines LED or pixel light sources, lenses, cooling, levelling motors and a control unit, so headlamps are projected to keep the lead in 2026 at 38%. Rear lamps, about 24%, are growing as carmakers fit full-width light bars, but each unit holds less electronics than a headlamp. By comparison, signal and indicator lamps, near 14.5%, are small and cheap per piece. Meanwhile, interior lighting (12%) and ambient and other lighting (11.5%) are the fastest-changing groups, though value per car is still lower. European lamp makers are concentrating headlamp output in large modernised plants. On the supply side, Valeo's Angers and Blois operations produce 9,000 headlights a day for European carmakers and truck makers.[1] Carmakers spend the most engineering time on the front lamp, so headlamps keep the value lead.
- LED reflector, projector, matrix and pixel modules make up most headlamp sales.
- New client awards are still coming for premium headlamps. Valeo expects two major headlamp launches for new clients at Angers in 2027 and 2028.[1] Launches for new clients add headlamp volume beyond existing programmes.
Why does LED lead automotive lighting sales by technology?
LED is likely to lead technology sales with 61% share in 2026, with halogen at about 27.5%, xenon or HID at an estimated 6% and laser and advanced lighting near 5.5%.
Table 5: Technology Share for the Automotive Lighting Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| LED | 61% |
| Halogen | 27.5% |
| Xenon or HID | 6% |
| Laser and Advanced Lighting | 5.5% |
| Total | 100.0% |
LED lamps use less power, last the life of the car and let designers shape thin light signatures, so LED is likely to hold 61% in 2026. Halogen, near 27.5%, survives on entry cars and in replacement bulbs, as each bulb costs a fraction of an LED module. Xenon or HID, about 6%, is fading as carmakers move to LED. At the top end, laser and advanced lighting, an estimated 5.5%, covers microLED, pixel and laser high beams on premium models. This shift is visible at Lumax Industries, which reported LED at 63% of Q1 FY27 revenue and about 90% of Rs 2,500 crore in orders.[3] Order mixes of that kind show LED replacing halogen first in emerging-market cars. Beyond LED, OLED rear lamps are entering production, and the OLED display market, with a projected 20.1% CAGR, will keep OLED panel costs falling. Over the forecast period, LED will keep the lead as halogen fades from new models.
- Within LED, the main products are matrix headlamps, LED tail lamps, daytime running lights and LED interior modules.
- OLED rear lamps are close to series fitment. Marelli said the Flat Lit Surface rear lamp combines OLED and Folia-LED and is ready for mass production.[6] Mass-production readiness gives carmakers a thin rear signature option for 2027 and 2028 models.
Why do passenger cars lead automotive lighting sales by vehicle type?
Passenger cars are projected to lead vehicle type sales with 72% share in 2026, with LCVs at about 18% and HCVs at an estimated 10%.
Table 6: Vehicle Type Share for the Automotive Lighting Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Cars | 72% |
| LCV | 18% |
| HCV | 10% |
| Total | 100.0% |
Cars make up most new vehicles, and carmakers use lighting to set models apart, so passenger cars are projected to lead with 72% in 2026. LCVs, about 18%, by comparison use simpler lamps on vans and pickups, and buyers choose on cost. HCVs, an estimated 10%, need heavy-duty headlamps and cab lighting on far fewer units. On the truck side, FORVIA HELLA presented RGB interior lighting for commercial vehicle cabs at IAA Transportation 2026.[7] Cab lighting of that kind adds value on trucks that sell in small numbers. Electrification is also raising lamp content in cars. Among passenger car brands, Kia's electrified models reached 35.3% of Q2 2026 sales.[8] Those models usually carry full-LED lighting. Car buyers will hold passenger vehicles in the lead, and the passenger vehicles market, projected at a 9% CAGR, supports the same lamp volume.
- SUVs, sedans and hatchbacks with LED front and rear lamps drive passenger car demand.
- Truck headlamps are gaining weight at European plants. Valeo plans to raise heavy-duty vehicle headlamps from 20% to 40% of Angers production.[1] Doubling the truck share moves Angers toward lower-volume, higher-value lamps.
Why does first fit OEM supply lead automotive lighting sales by sales channel?
First fit OEM supply is expected to lead sales channel demand with 83% share in 2026, and the aftermarket holds about 17%.
Table 7: Sales Channel Share for the Automotive Lighting Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| First Fit OEM | 83% |
| Aftermarket | 17% |
| Total | 100.0% |
Each lamp is designed for one model and fitted on the assembly line, so first fit OEM supply is likely to lead, with 83% of 2026 sales. By contrast, the aftermarket, near 17%, sells replacement bulbs, crash-repair lamps and accessories, and LED units that last the life of the car will slowly shrink bulb replacement. Repair of complex lamps needs new tools, and Hella Gutmann Solutions launched the SEG-Tool PRO and SEG-Tool PLUS aligners at Automechanika 2026.[4] Aligners of this kind keep crash-repair lamp work in independent workshops. More broadly, lamp electronics are part of the wider automotive electronics market, forecast at a 4.6% CAGR. OEM supply will therefore keep the lead as lamps become model-specific.
- Factory-fitted headlamps, rear lamps, signal lamps and interior modules for new vehicles make up first fit OEM supply.
- Lower-cost tools are opening alignment work to smaller shops. The SEG-Tool PLUS analog aligner is priced at EUR 2,090 for repair shops and dealerships.[4] Pricing at that level brings smaller garages into adaptive lamp service.
What are the drivers, restraints, and opportunities in the automotive lighting market?
LED and digital lamps raise lighting value per car. Cost pressure on mass-market platforms squeezes lamp makers, and pixel headlamps and cabin lighting open higher-value programmes.
- Driver: Carmakers use LED light signatures and full-width light bars to brand new models, which raises lamp content per vehicle.
- Restraint: Mass-market carmakers push lamp prices down as programme volumes fall, which compresses lamp maker margins.
- Opportunity: Pixel headlamps, OLED rear lamps and RGB cabin lighting let suppliers sell software-controlled functions at higher prices.
Light Signatures Raise Content per Car
Consumer preference for distinctive front and rear lighting is pushing carmakers to fit more LED per model. For example, Marelli showed a corner-to-corner headlamp with touch and voice control at Auto China 2026.[6] Features of that kind move headlamps into the electronics budget of the car. Likewise, Lumax Industries launched a new Tata Motors Tiago headlamp and a Skoda and Volkswagen Taigun rear lamp in the June 2026 quarter.[3] In turn, each new signature design replaces a cheaper lamp with a more complex one.
Programme Phase-Outs Squeeze Lamp Margins
Key challenges in the automotive lighting market include falling call-offs and hard price targets. For instance, FORVIA HELLA's Lighting operating income fell to EUR 7 million in H1 2026 from EUR 63 million.[2] In FMI's reading, mass-market headlamps and halogen replacement lines carry the heaviest price pressure. As a result, lamp makers will close older lines and move work to lower-cost plants.
Pixel Headlamps and Cabin Light Open New Programmes
Digital light functions are the next source of value per car. At the front, Marelli offers h-Digi microLED modules with up to 40K pixels for adaptive driving beam.[6] Higher pixel counts carry higher module prices, which raises value per headlamp. Likewise, FORVIA HELLA's RGB cabin lighting signals distance warnings, battery charge status and incoming calls.[7] Functions tied to vehicle software give lamp makers a share of feature pricing. Beyond this, battery-electric cars carry more lighting electronics, and growth of the battery electric vehicle market at a 15% CAGR adds more of those cars each year, widening the field for software-driven lamp functions.
Which country CAGRs are profiled in the automotive lighting market?
Table 8: Country CAGR Comparison for the Automotive Lighting Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 8.2% |
| China | 8.1% |
| South Korea | 7% |
| Germany | 6.1% |
| United States | 6% |
| France | 5.9% |
| Japan | 5.6% |
How do country-level CAGRs compare in the automotive lighting market?
Supplier results in India point to rapid LED conversion. Lumax Industries grew Q1 FY27 revenue 32.6%, faster than broader industry trends, and FMI projects the fastest growth for India, at 8.2%.[3] Growth at that pace at a local lamp maker reflects LED moving into entry cars. China follows at 8.1%, as local carmakers fit full-width light bars and pixel headlamps on new electric models. South Korea is expected at 7% on electrified exports. Behind them, Germany and the United States, at 6.1% and 6%, are within 0.2 points of France on 5.9%, all just under the global rate. Japan, with flat output, ranks last at 5.6%.
- LED is moving from premium cars into compact models and scooters in India, multiplying lamp value per vehicle at the low end. Local suppliers with LED electronics in house, such as Lumax Industries, gain most of the new orders.
- Chinese electric car brands use light bars and projection to stand out, so lamp content per car is rising fastest in new models. For lamp makers, quick design cycles and local engineering decide programme awards in China.
- Full-LED lamps front and rear come standard on electrified Korean exports, keeping lamp value per vehicle high for Hyundai Mobis and SL Corporation, the suppliers closest to these platforms.
- German premium brands fit matrix and pixel headlamps across many models, though volume is flat. Margin pressure at domestic lamp makers points to restructuring instead of capacity growth.
- Large LED headlamps on US pickups and SUVs raise lamp value per vehicle, and collision repair adds steady replacement sales. For suppliers, aftermarket reach therefore carries extra weight in the United States.
- As the European centre for heavy-duty headlights, Valeo's Angers site is shifting French output toward truck lamps, which gives French plants steadier, lower-volume work.
- LED fitment is already high in Japan and vehicle output is flat, leaving model replacement as the main source of growth. Koito and Stanley Electric lean more on export platforms as a result.
Full report country CAGRs cover: three countries over the 6.2% global figure (India, China and South Korea), three just under (Germany, the United States and France), Japan at the bottom, and all other standard countries by region.
Country-wise Analysis
India Automotive Lighting Market Outlook (2026 to 2036)
Among the seven countries, India has the top rate, an 8.2% CAGR for automotive lighting demand. Evidence of this pace comes from Lumax Industries, which reported Q1 FY27 revenue of Rs 1,223.2 crore, up 32.6%, and runs twelve plants in India.[3] Capacity of that size lets Indian lamp makers bid for LED programmes across car and scooter platforms. At the same time, LED lamps are moving from premium models to entry cars and scooters.
Key takeaway: LED in volume models sets the Indian pace.
China Automotive Lighting Market Outlook (2026 to 2036)
Chinese carmakers are pushing lamp suppliers toward low-cost digital lighting. Marelli said the lighting shown at Auto China 2026 targets affordable, scalable solutions for customers in China and globally.[6] Affordable digital lamps widen the Chinese market for pixel and projection functions beyond premium brands. Chinese electric car brands, in particular, use light bars and projection functions to stand out. As a result, China, at 8.1% on FMI's forecast, is almost level with India.
Key takeaway: Electric car styling raises Chinese lamp value.
South Korea Automotive Lighting Market Outlook (2026 to 2036)
Korean carmakers are moving more of the range to electrified models. Kia reported Q2 2026 wholesale sales of 851,639 units and electrified retail sales of 296,000 units.[8] These electrified models carry full-LED front and rear lamps. South Korean lamp demand is therefore expected to expand 7% a year.
Key takeaway: Electrified models raise Korean lamp content.
Germany Automotive Lighting Market Outlook (2026 to 2036)
German lamp makers are restructuring as programme volumes fall. FORVIA HELLA, based in Lippstadt, reported a 5.3% fall in H1 2026 Lighting sales and said the Lighting transformation is being accelerated.[2] Faster restructuring at a domestic lamp maker means fewer German lines for mass-market lamps. Even so, German premium carmakers fit matrix and pixel headlamps on many models. Taken together, a 6.1% CAGR is projected for Germany, 0.1 points short of the global figure.
Key takeaway: Premium headlamps offset German restructuring.
United States Automotive Lighting Market Outlook (2026 to 2036)
US pickups and SUVs carry large LED headlamps and tail lamps, and replacement after collisions adds aftermarket demand. On the semiconductor side, ams OSRAM reported automotive semiconductor revenue of EUR 231 million in Q2 2026.[5] Firmer LED chip sales feed the large headlamp and tail lamp sets on US trucks. US lamp sales are on course for 6% annual growth over the decade.
Key takeaway: Large vehicles keep lamp value high in the United States.
France Automotive Lighting Market Outlook (2026 to 2036)
French lamp output is concentrated in a few large engineering sites. Valeo's Angers and Blois sites employ more than 1,200 people, and Angers is the group's European competence centre for heavy-duty vehicle headlights.[1] A centre of that kind steers French output toward heavy-duty lamps. In addition, French carmakers buy LED headlamps for compact and electric models. With these buyers, French growth runs just under the global rate, at 5.9%.
Key takeaway: Truck headlamps shape French output.
Japan Automotive Lighting Market Outlook (2026 to 2036)
Japanese lamp makers such as Koito and Stanley Electric supply domestic carmakers and export platforms, and LED fitment is already high. However, domestic vehicle output is flat. Consequently, FMI projects the slowest growth of the seven countries for Japan, at 5.6%.
Key takeaway: High LED fitment and flat output slow Japan.
Who are the notable companies in the automotive lighting market?
Koito, Valeo, Marelli, FORVIA HELLA, Stanley Electric, Varroc, Hyundai Mobis, SL Corporation, ams OSRAM and Lumax Industries are the profiled companies.
In FMI analysis, Japanese, European, Korean and Indian lamp makers and one light source specialist make up the field, and scale in LED electronics separates the leaders. Among them, FORVIA HELLA confirmed 2026 guidance of currency-adjusted sales of around EUR 7.4 billion to EUR 7.9 billion.[2] Guidance held at that level shows Lighting weakness offset elsewhere in the group. In light sources, ams OSRAM reported Q2 2026 revenue of EUR 805 million, up 4%.[5] Revenue of that size funds the microLED work lamp makers will buy in. Meanwhile, Lumax Industries held orders of Rs 2,500 crore.[3] That pipeline gives Lumax multi-year visibility on Indian LED programmes. Koito, Valeo, Marelli, Stanley Electric, Varroc, Hyundai Mobis and SL Corporation complete the group.
- Japanese lamp makers: Koito and Stanley Electric.
- European lamp makers: Valeo, FORVIA HELLA and Marelli.
- Korean and Indian lamp makers: Hyundai Mobis, SL Corporation, Varroc and Lumax Industries.
- Light source specialist: ams OSRAM.
Competitive Benchmarking: Automotive Lighting Market
Table 9: Competitive Benchmarking for the Automotive Lighting Market (qualitative ratings), 2026
| Company | Headlamp Modules | Rear and Signature Lamps | Digital and Pixel Light | Aftermarket and Service |
|---|---|---|---|---|
| FORVIA HELLA | High | Medium | Medium | High |
| Valeo | High | Low | Low | Low |
| Marelli | High | High | High | Low |
| Lumax Industries | Medium | Medium | Low | Low |
| ams OSRAM | Low | Low | Medium | Medium |
Ratings compare the companies on headlamp modules, rear and signature lamps, digital and pixel light, and aftermarket and service.
Key Developments in the Automotive Lighting Market
- Hella Gutmann Solutions launched the SEG-Tool PRO and SEG-Tool PLUS headlight aligners on 8 September 2026, giving workshops tools for matrix and adaptive lamps.[4]
- Adaptive RGB interior lighting for commercial vehicles was presented by FORVIA HELLA on 3 September 2026, a sign that cab lighting is moving into truck programmes.[7]
- In the 8 August 2026 results, Lumax Industries listed new Tiago, Taigun, Burgman Street and Traveller lamps launched in Q1 FY27, which shows LED reaching volume cars, scooters and vans in India.[3]
- Automotive semiconductor revenue at ams OSRAM was reported up 6% sequentially at EUR 231 million on 5 August 2026; for lamp makers this means firmer LED chip supply.[5]
- On 30 July 2026, FORVIA HELLA said the Lighting transformation would be accelerated after operating income fell to EUR 7 million, which signals plant and cost cuts in lamps.[2]
- Kia results of 24 July 2026 showed electrified models at 35.3% of Q2 2026 sales, adding full-LED lamp sets to a larger share of output.[8]
- On 2 July 2026, Valeo detailed a modernisation of more than EUR 45 million at the Angers lighting plant, a bet on heavy-duty and high-content headlamps.[1]
- Marelli announced h-Digi microLED, Flat Lit Surface and thin corner-to-corner headlamp technologies for Auto China 2026 on 2 April 2026, aiming digital light at Chinese and global carmakers.[6]
Key Players in the Automotive Lighting Market
Japanese Lamp Makers
- Koito
- Stanley Electric
European Lamp Makers
- Valeo
- FORVIA HELLA
- Marelli
Korean and Indian Lamp Makers
- Hyundai Mobis
- SL Corporation
- Varroc
- Lumax Industries
Light Source Specialist
- ams OSRAM
Automotive Lighting Market - Report Scope
Table 10: Report Scope for the Automotive Lighting Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Lighting type; technology; vehicle type; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Headlamps, rear lamps, signal and indicator lamps, interior and ambient lighting with LED, halogen, xenon or HID, laser and other light sources, fitted to new passenger cars and commercial vehicles or sold as replacement parts. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Koito, Valeo, Marelli, FORVIA HELLA, Stanley Electric, Varroc, Hyundai Mobis, SL Corporation, ams OSRAM, Lumax Industries |
| Forecast period | 2026 to 2036 |
Automotive Lighting Market - Research Methodology
Table 11: Research Methodology for the Automotive Lighting Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers LED and digital headlamp programmes, plant investment, cabin lighting and workshop alignment tools. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 32.1 billion and the 6.2% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Automotive Lighting Market by Segments
Automotive Lighting Market segmented by Lighting Type:
- Headlamps
- Rear Lamps
- Signal and Indicator Lamps
- Interior Lighting
- Ambient and Other Lighting
Automotive Lighting Market segmented by Technology:
- LED
- Halogen
- Xenon or HID
- Laser and Advanced Lighting
Automotive Lighting Market segmented by Vehicle Type:
- Passenger Cars
- LCV
- HCV
Automotive Lighting Market segmented by Sales Channel:
- First Fit OEM
- Aftermarket
Automotive Lighting Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Valeo. (2026, July 2). Valeo Accelerates Future Lighting at its Angers Plant. https://www.valeo.com/en/valeo-accelerates-future-lighting-at-its-angers-plant/
- [2] FORVIA HELLA. (2026, July 30). Half-year results for 2026: Business development in line with expectations, guidance confirmed. https://www.hella.com/en/Newsroom/Press-Releases/2026-07-30-Half-year-results-for-2026-9541/
- [3] Lumax Industries Limited. (2026, August 8). Lumax Industries begins FY27 on a strong note with strong revenue and profitability growth. https://nsearchives.nseindia.com/corporate/LUMAXIND_08082026172412_PressRelease.pdf
- [4] FORVIA HELLA. (2026, September 8). Automechanika 2026: Hella Gutmann Solutions Sets New Standards with the SEG-Tool PRO and SEG-Tool PLUS. https://www.hella.com/en/Newsroom/Press-Releases/2026-09-08-Automechanika-2026-Hella-Gutmann-Solutions-Sets-New-Standards-with-the-SEG-Tool-PRO-and-SEG-Tool-9678/
- [5] eeNews Europe. (2026, August 5). ams OSRAM reports solid Q2, accelerates microLED arrays for AR smart glasses. https://www.eenewseurope.com/en/ams-osram-reports-solid-q2-accelerates-microled-arrays-for-ar-smart-glasses/
- [6] Marelli. (2026, April 2). Marelli presents lighting technologies for the software-defined age at Auto China 2026. https://www.marelli.com/content/marelli/en/news/marelli-presents-lighting-technologies-for-the-software-defined-age-at-auto-china-2026.html
- [7] FORVIA HELLA. (2026, September 3). IAA Transportation 2026: FORVIA HELLA presents adaptive RGB interior lighting technology for commercial vehicles. https://www.hella.com/en/Newsroom/Press-Releases/2026-09-03-IAA-Transportation-2026-9668/
- [8] The Financial News. (2026, July 24). Kia posts record quarterly sales and revenue in Q2, but operating profit falls 4.9%. https://en.fnnews.com/news/202607241424065696
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive lighting market during 2026?
- What market size is projected by 2036?
- Which lighting type holds notable share?
- Which technology holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the automotive lighting market expected in 2026?
FMI's forecast places the automotive lighting market at USD 32.1 billion in 2026, against USD 30.2 billion in 2025. Sales of automotive lighting are projected to reach USD 58.6 billion by 2036.
What CAGR is projected for the automotive lighting market through 2036?
The automotive lighting market is expected to grow at a 6.2% CAGR from 2026 to 2036. LED and digital headlamps, light signatures and cabin lighting raise value per vehicle.
Which lighting type holds a notable market share in 2026?
Headlamps are expected to lead with 38% share in 2026. Rear lamps follow at about 24%.
Which technology holds a notable market share in 2026?
LED is likely to lead with 61% share in 2026. Halogen holds an estimated 27.5%.
Which country has a notable expansion outlook through 2036?
FMI projects India to grow fastest, at an 8.2% CAGR. China follows at 8.1%.
Who are the key companies in the automotive lighting market?
Koito, Valeo, Marelli, FORVIA HELLA and Stanley Electric lead the lamp makers. Varroc, Hyundai Mobis, SL Corporation, ams OSRAM and Lumax Industries complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Lighting Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Lighting Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Lighting Type, 2026 to 2036
- Headlamps
- Rear Lamps
- Signal and Indicator Lamps
- Interior Lighting
- Ambient and Other Lighting
- Y-o-Y Growth Trend Analysis By Lighting Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Lighting Type, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- LED
- Halogen
- Xenon or HID
- Laser and Advanced Lighting
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- LCV
- HCV
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- First Fit OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Lighting Type
- By Technology
- By Vehicle Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- FORVIA HELLA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Valeo
- Marelli
- Lumax Industries
- ams OSRAM
- Koito
- Stanley Electric
- Hyundai Mobis
- SL Corporation
- Varroc
- FORVIA HELLA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


