
- Market Size (2026)
- USD 24.0 Bn
- Forecast (2036)
- USD 56.2 Bn
- CAGR (2026 to 2036)
- 8.9%
How big is Automotive Sensors Market in 2026?
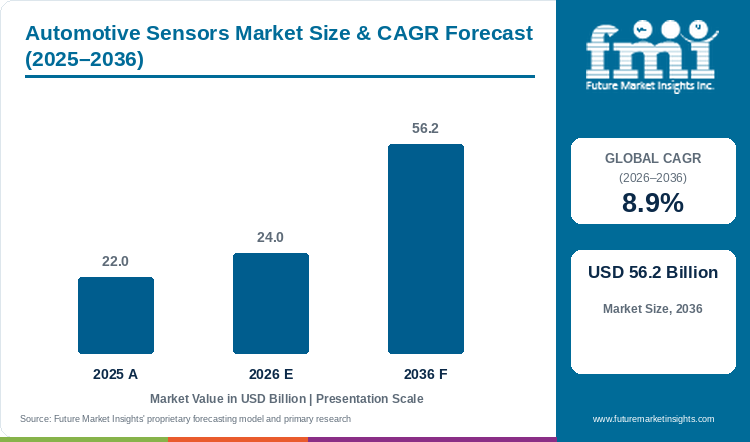
An 8.9% CAGR from 2026 to 2036 drives automotive sensor sales. The 2025 total of USD 22 billion grows to an estimated USD 24.0 billion in 2026 and a projected USD 56.2 billion in 2036.
Key drivers of the automotive sensors market include radar-based safety functions moving into entry-level cars, battery monitoring on electric platforms and emission rules for combustion engines. Automotive sensors market size stood at USD 22 billion in 2025, is estimated at USD 24.0 billion in 2026 and is projected to reach USD 56.2 billion by 2036 in FMI's forecast, at an 8.9% CAGR from 2026 to 2036.
Adoption of L2 driver assistance in budget cars is the key opportunity, and that opportunity is concentrated in radar and camera modules for mainstream platforms. NXP launched the SAF8444 single-chip radar in June 2026 for entry-level L2 and L2+ systems, with ADAS processing on the sensor to cut system cost.[1] Due to this, carmakers planning entry-level programs can price adaptive cruise control and emergency braking into lower trims, unlocking the next wave of market growth. Growth of the automotive active safety system market is projected at an 11.3% CAGR from 2026 to 2036, so safety sensors, an estimated 21.8% of 2026 sensor type sales, will gain share on position sensors at 24.6%.
Sensor makers are buying more interface and processing chips for each module, and the automotive semiconductor market is expected to grow at a 6.8% CAGR between 2026 and 2036. A small group of fabs supplies those chips, so module makers are qualifying second sources to protect delivery dates. The automotive electronics market is estimated to grow at a 4.6% CAGR for 2026 to 2036, below the sensor rate. As a result, sensors will take a larger slice of the electronics bill in each new model launched before 2036.
Key Market Trends & Insights
- Crankshaft, camshaft and steering angle readings keep position sensors first among sensor types, at an estimated 24.6% in 2026.
- Demand for sensors in passenger cars comes to about 71.4% (estimated) of 2026 vehicle type sales, as compact cars, sedans and SUVs outnumber vans and trucks on every assembly line.
- Carmakers buy sensors at the assembly line for each new model, giving line-fit orders an estimated 78.5% of 2026 channel volume.
Regional Highlights
- ADAS fitment on new cars gives the USA the top profiled CAGR, 9.1% from 2026 to 2036, and NHTSA cleared up to 2,500 Zoox robotaxis a year in July 2026.
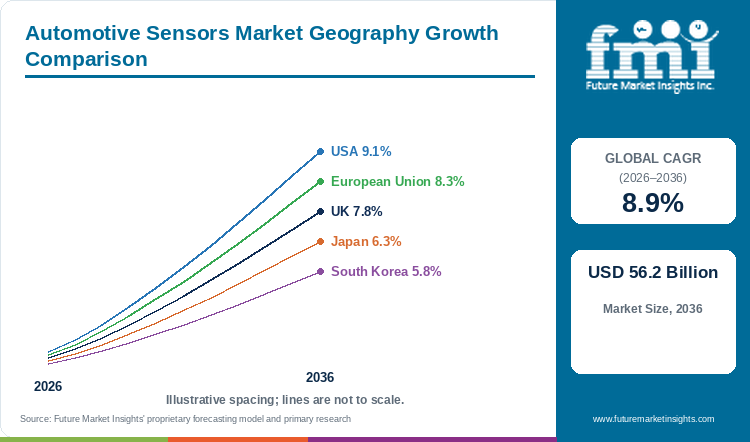
- European Union buyers follow at 8.3%, then the UK at 7.8% and Japan at 6.3%, with South Korea lowest at 5.8%.
- SMMT counted 40,872 vehicles built in the UK in August 2026, up 5.7%, and electrified models made up 43.6% of car output.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Sensors Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 22 billion |
| Estimated Market Size in 2026 | USD 24.0 billion |
| Projected Market Size by 2036 | USD 56.2 billion |
| CAGR, 2026 to 2036 | 8.9% |
| Added Revenue, 2026 to 2036 | USD 32.2 billion |
| Market Expansion Multiple | 2.3x |
From a 2025 base of USD 22 billion, FMI expects an 8.9% CAGR for sensor sales from 2026 to 2036. Growth comes from more sensors per vehicle, since global light vehicle volume grows slowly. Camera suppliers and lidar makers compete with radar for the same ADAS sensor slots. Carmakers compare radar, camera and lidar quotes for each ADAS slot, so growth of the automotive camera market and the solid-state lidar sensor market will bring more rival quotes against radar. NXP pitched the SAF8444 radar chip on lower system cost for mainstream cars.[1]
Sensor Content Gains Against Flat Vehicle Output
Suppliers are adding value per car faster than carmakers add cars. First-half 2026 Mobility sales at Bosch slipped 0.5% to 27.8 billion euros on stagnant automotive production.[3] Aptiv reported second-quarter 2026 sales of $1,501 million in Intelligent Systems, flat on the year.[4] Flat output pushes supplier investment toward sensor content per vehicle. NXP moved ADAS processing onto the radar chip for entry-level and electric platforms in June 2026.[1] Nexperia stabilised supply and grew second-quarter 2026 revenue 18.4% from the first quarter to $355.6 million.[5] Sensor content per car will keep sales growing ahead of vehicle production through 2036.
Table 2: Vehicle Output and Sensor Content Indicators for the Automotive Sensors Market (euros, USD, units and percentage), mixed reporting periods from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Bosch Mobility sales, H1 2026 | 27.8 billion euros, down 0.5% | Flat output at a large sensor supplier. | [3] |
| Bosch impairments on production facilities, H1 2026 | 270 million euros | Slower electromobility ramp-up. | [3] |
| Aptiv Intelligent Systems sales, Q2 2026 | $1,501 million, flat | Sensor and electronics demand at one supplier. | [4] |
| NXP SAF8444 radar SoC, June 2026 | 76 to 81 GHz band, pre-production | Single-chip radar for mainstream ADAS. | [1] |
| Nexperia revenue, Q2 2026 | $355.6 million, up 18.4% on Q1 | Recovery in chip supply to car electronics. | [5] |
| China vehicle production, 2025 | 34.531 million units | Largest pool of sensor fitment. | [6] |
| UK vehicle output, August 2026 | 40,872 units, up 5.7% | UK assembly volume for sensor fitment. | [2] |
Analyst Perspective
“Sensor suppliers should sign multi-year supply agreements for radar chips and interface ICs now, before L2 functions reach entry-level cars at volume. I expect the strongest suppliers to buy or build sensor fusion software teams, because carmakers increasingly award the sensor, the chip and the code as one module.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automotive sensors market segmented?
The automotive sensors split covers region, sales channel, vehicle type and sensor type. Estimated 2026 leaders are position sensors at 24.6%, passenger cars at 71.4% and OEM fitment at 78.5%.
By sensor type: position, safety, pressure, temperature, speed, oxygen and level sensors.
By vehicle type: passenger cars (compact, midsize, luxury, SUVs), LCVs, HCVs.
By sales channel: original equipment manufacturers, OES spare parts, independent aftermarket.
By region: five regional blocks.
Why do position sensors lead sensor type sales?
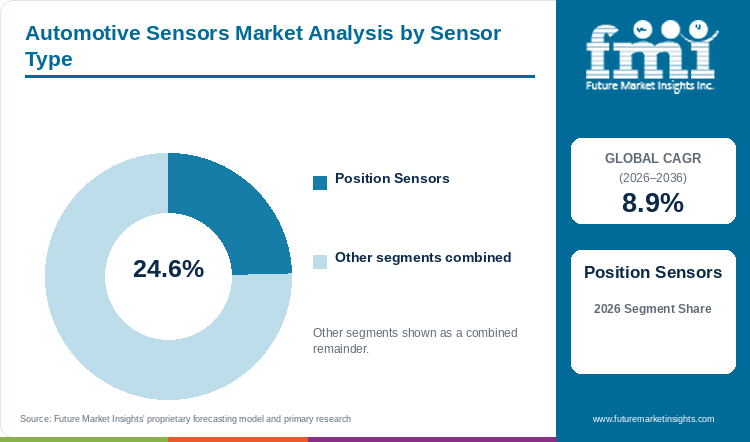
An estimated 24.6% of 2026 sensor type sales makes position sensors the top group, with safety and pressure sensors next.
Table 3: Sensor Type Share for the Automotive Sensors Market (percentage share), 2026
| Sensor Type | Estimated Share (2026) |
|---|---|
| Position Sensors | 24.6% |
| Safety Sensors | 21.8% |
| Pressure Sensors | 15.2% |
| Temperature Sensors | 13.4% |
| Speed Sensors | 11.3% |
| Oxygen Sensors | 8.1% |
| Level Sensors | 5.6% |
| Total | 100.0% |
Table 4: Sensor Type Leadership and Market Growth for the Automotive Sensors Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.9% |
| Leading Segment | Position Sensors |
Every engine, gearbox, throttle and steering column needs a position reading, so position sensors hold an estimated 24.6% of 2026 sensor type sales. Safety sensors, at about 21.8% (estimated), come close, though radar and camera units still reach mainly mid and premium trims. Pressure sensors, an estimated 15.2%, serve fewer points per car, mostly tyres, brakes and fuel lines. Temperature sensors at roughly 13.4% (estimated) and speed sensors at about 11.3% (estimated) are low-cost parts with a small unit value. Oxygen sensors, an estimated 8.1%, fit only combustion engines, and level sensors at about 5.6% (estimated) cover fuel, oil and washer tanks. Analysts at FMI see powertrain control and safety functions keeping position sensors in front, though the June 2026 SAF8444 radar will help safety sensors close the gap.[1]
Why do passenger cars lead vehicle type sales?
Passenger cars, at about 71.4% (estimated) of 2026 vehicle demand for sensors, lead vans and trucks.
Table 5: Vehicle Type Share for the Automotive Sensors Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Cars | 71.4% |
| Light Commercial Vehicles | 19.2% |
| Heavy Commercial Vehicles | 9.4% |
| Total | 100.0% |
About 71.4% (estimated) of 2026 vehicle type sales goes into passenger cars, from compact hatchbacks to SUVs. Light commercial vehicles hold an estimated 19.2%, as van output is far smaller and fleet buyers often order base trims with fewer driver aids. Heavy commercial vehicles come to roughly 9.4% (estimated), because truck and bus output is small even with emission and braking sensors on each unit. Chinese plants built 34.531 million vehicles in 2025, Gasgoo said, citing CAAM, and NEVs took over half of domestic new-car sales.[6]
- Luxury models and SUVs carry the most sensors per car, which keeps passenger car value high through 2036.
Why does OEM fitment lead sales channel volume?
Carmaker fitment ranks first among channels, estimated at 78.5% for 2026, and replacement buyers split the balance between OES parts and independent shops.
Table 6: Sales Channel Share for the Automotive Sensors Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Original Equipment Manufacturers | 78.5% |
| Original Equipment Supplier Spare Parts | 9.7% |
| Independent Aftermarket | 11.8% |
| Total | 100.0% |
Sales of sensors through carmaker assembly lines take an estimated 78.5% of 2026 channel volume, because each sensor is fitted once at the factory. Independent workshops, at about 11.8% (estimated), buy only when a unit fails, mostly oxygen, pressure and wheel speed sensors. OES spare parts come to roughly 9.7% (estimated), as dealer prices are higher and older cars leave dealer service once warranties end. Denso kept the exhaust gas sensor business in October 2026, citing longer demand for diverse powertrains, so replacement oxygen sensors will keep independent workshops busy.[7]
- Wheel speed and tyre pressure sensors fail with road damage and add replacement volume.
What are the drivers, restraints, and opportunities in the automotive sensors market?
Single-chip radar for entry-level L2 cars, 16 million NEVs built in China in 2025 and robotaxi exemptions in the USA drive demand for automotive sensors. Integration cost in entry-level cars and the 2025 Nexperia supply split hold back sensor makers.
- Driver: NHTSA exemptions and AV standards for robotaxi fleets.
- Restraint: Interface chip supply after the Nexperia split and integration cost in mid-range cars.
- Opportunity: Battery current and temperature sensing on 400V and 800V platforms.
Automated Vehicle Rules Open a Path for Robotaxis
NHTSA granted Zoox a temporary exemption in July 2026 for commercial deployment of up to 2,500 vehicles in each of two years.[8] NHTSA also funded a three-year, $5 million A2SCEND data effort toward the first AV performance standards.[8] Robotaxis carry far denser radar, lidar and camera suites than private cars. Due to this, FMI predicts that each approved robotaxi fleet will add to US demand for sensors.
Chip Supply Concentration Keeps Costs High
Sensor modules rely on customised ICs from a small group of fabs. Nexperia deconsolidated several Chinese entities from 1 October 2025 after the loss of actual control over them.[5] Nexperia said in August 2026 that the company continues to make progress in stabilising the supply chain and ramping up capacity.[5] Key challenges faced by manufacturers include chip sourcing and integration cost in mid-range cars. Sensor suppliers will qualify second sources for interface chips before 2028.
Electric Platforms Add Battery and Current Sensing
Gasgoo reported over 16 million NEVs produced and sold in China during 2025.[6] Every battery pack needs cell temperature and current sensing. New sales of battery temperature, current and voltage sensors are expected from 400V and 800V platforms, and battery sensor volume will rise with each electric car built.
Which country CAGRs are profiled in the automotive sensors market?
Table 7: Country CAGR Comparison for the Automotive Sensors Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| USA | 9.1% |
| European Union | 8.3% |
| UK | 7.8% |
| Japan | 6.3% |
| South Korea | 5.8% |
How do country-level CAGRs compare in the automotive sensors market?
Federal exemptions for robotaxi fleets and fast ADAS fitment give US demand for sensors a 9.1% CAGR from 2026 to 2036, ahead of the 8.9% global CAGR, FMI's analysis indicates. Emission and safety rules hold the European Union at 8.3%, and electrified car exports keep the UK at 7.8%. Japan, at 6.3%, and South Korea, at 5.8%, both build cars on mature domestic volume.
- NHTSA opened a docket in July 2026 for the first AV guidance update since 2017, and the USA leads at 9.1%.
- A slower electromobility ramp-up cost Bosch 270 million euros of impairments in H1 2026, so EU engine sensor lines will run longer.
- Electrified models made up 43.6% of UK car output in August 2026.
- Hybrid output keeps Japanese engine sensor lines busy.
- Mature domestic output leaves South Korea with the slowest rate of the five.
Full report country CAGRs cover: Brazil and Mexico, noted for oxygen and temperature sensor use, plus country markets across the Asia Pacific, European, North American, Latin American, and Middle East and African blocks.
Country-wise Analysis
USA Automotive Sensors Market Outlook (2026 to 2036)
NHTSA opened a docket in July 2026 for updated automated vehicle guidance, the first update since 2017.[8] The Zoox exemption allows up to 2,500 sensor-heavy robotaxis a year on US roads. The FMI study links North American growth to ADAS fitment on new cars. US demand records a 9.1% CAGR from 2026 to 2036, the top profiled rate.
Key takeaway: ADAS fitment and robotaxi fleets cleared under federal exemptions will carry US sensor growth.
European Union Automotive Sensors Market Outlook (2026 to 2036)
Bosch booked 270 million euros of impairments on production facilities during January to June 2026, citing a slower electromobility ramp-up.[3] FMI ties European sensor demand to emission norms and decarbonisation targets for new cars. Sales of sensors in the European Union are projected at an 8.3% CAGR from 2026 to 2036, second among the five. A slower electric ramp-up will keep German engine sensor lines running longer, and ADAS sensors will add the new volume.
Key takeaway: Engine sensors will hold up longer in the EU as the electric ramp-up slows.
UK Automotive Sensors Market Outlook (2026 to 2036)
Battery electric and hybrid cars formed 43.6% of British car production in August 2026, and exports took 77.1% of output.[2] Every pack in those cars carries current and temperature sensors. Stricter rules of origin from 1 January 2027 could add tariffs on most UK-built electric cars sold in the EU, SMMT warned.[2] Adoption of sensors in the UK grows at a 7.8% CAGR over 2026 to 2036, and rules of origin from 2027 will decide the share of those packs shipped to EU buyers.
Key takeaway: Export terms with the EU will decide UK sensor volume.
Japan Automotive Sensors Market Outlook (2026 to 2036)
Hybrid-heavy Japanese output carries a 6.3% CAGR from 2026 to 2036, with engine sensors still in steady demand. Denso cited demand for diverse powertrains lasting longer than expected when the company dropped a planned sale of the exhaust gas sensor business on 2 October 2026.[7] The business covers oxygen sensors and air-fuel ratio sensors.[7]
Key takeaway: Japanese oxygen and air-fuel ratio sensor lines will run longer than lines in electric-only markets, owing to hybrid output.
South Korea Automotive Sensors Market Outlook (2026 to 2036)
Mature domestic vehicle output holds South Korea to a 5.8% CAGR from 2026 to 2036, the slowest profiled rate. Battery sensors for Korean electric car exports will add new volume as home output stays mature.
Key takeaway: Electric car exports will carry demand for sensors in South Korea.
Who are the notable companies in the automotive sensors market?
Bosch, Denso Corporation, Continental AG, Aptiv and Infineon Technologies are the key suppliers, alongside NXP Semiconductors, Texas Instruments, Sensata Technologies, Valeo, Murata Manufacturing, HELLA, TE Connectivity, ZF Friedrichshafen and Autoliv.
Carmakers award most sensor volume to a short list of system suppliers. Top companies operating in the automotive sensors market include Bosch at an estimated 17 to 22%, Denso at 14 to 18% and Continental at 10 to 14%, with Aptiv at 7 to 10% and Infineon at 5 to 8%, and other companies hold 30 to 40% together, FMI estimates. NXP moved ADAS processing onto the radar chip in June 2026, and under the changing rules of competition carmakers award the sensor, chip and software as one module.[1]
Aptiv and Denso changed supplier scope in 2026, in opposite directions. Aptiv completed the separation of the Electrical Distribution Systems business as Versigent PLC on 1 April 2026.[4] Denso kept the exhaust gas sensor business after ending the planned Niterra transfer.[7] Bosch confirmed 2026 Group forecasts in September 2026.[3]
- System suppliers: Bosch, Denso Corporation, Continental AG, Aptiv, Valeo, HELLA GmbH and Co. KGaA, ZF Friedrichshafen AG, and Autoliv Inc.
- Chip and component makers: Infineon Technologies, NXP Semiconductors, Texas Instruments, Murata Manufacturing, Sensata Technologies, and TE Connectivity.
Competitive Benchmarking: Automotive Sensors Market
Table 8: Competitive Benchmarking for the Automotive Sensors Market (qualitative documentation ratings), 2026
| Company | ADAS Sensors | Powertrain Sensors | Chip Supply | Portfolio Moves |
|---|---|---|---|---|
| Bosch | High | High | Medium | Medium |
| Denso Corporation | Medium | High | Medium | High |
| Aptiv | Medium | Low | Low | High |
| NXP Semiconductors | High | Low | High | Low |
| Nexperia | Low | Low | High | Medium |
Each rating counts the dated releases on the item for 2025 and 2026, from Low to High.
Key Developments in the Automotive Sensors Market
- In October 2026, Denso decided not to proceed with the transfer of the spark plug and exhaust gas sensor business to Niterra.[7]
- In September 2026, Bosch reported Mobility sales of 27.8 billion euros for the first half.[3]
- In September 2026, SMMT reported UK vehicle output up 5.7% for August.[2]
- In August 2026, Nexperia reported second-quarter revenue of $355.6 million.[5]
- In August 2026, Aptiv reported second-quarter revenue of $3.3 billion, up 2%.[4]
- In July 2026, NHTSA granted Zoox a temporary exemption for up to 2,500 vehicles per year.[8]
- In June 2026, NXP introduced the SAF8444 single-chip radar for L2 and L2+ ADAS.[1]
- In January 2026, CAAM put 2025 Chinese vehicle output at 34.531 million units, Gasgoo reported.[6]
Key Players in the Automotive Sensors Market
System Suppliers
- Bosch
- Denso Corporation
- Continental AG
- Aptiv PLC
- Valeo
- HELLA GmbH and Co. KGaA
- ZF Friedrichshafen AG
- Autoliv Inc.
Chip and Component Makers
- Infineon Technologies
- NXP Semiconductors
- Texas Instruments
- Murata Manufacturing
- Sensata Technologies
- TE Connectivity
Automotive Sensors Market - Report Scope
Table 9: Report Scope for the Automotive Sensors Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Sensor type; vehicle type; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Automotive sensors market covering position, safety, level, oxygen, pressure, temperature and speed sensors for passenger cars and commercial vehicles, sold to carmakers, OES spare parts channels and the independent aftermarket. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East and Africa |
| Countries covered | USA; European Union; UK; Japan; South Korea |
| Key companies profiled | Bosch, Denso Corporation, Continental AG, Aptiv, Infineon Technologies, NXP Semiconductors, Texas Instruments, Sensata Technologies, Valeo, Murata Manufacturing, HELLA, TE Connectivity, ZF Friedrichshafen AG, Autoliv Inc. |
| Forecast period | 2026 to 2036 |
Automotive Sensors Market - Research Methodology
Table 10: Research Methodology for the Automotive Sensors Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Supplier results, chip maker releases, safety regulator notices and vehicle industry data dated May 2025 or later. |
| Desk Research | Desk work covers sensor launches, supplier portfolio moves, chip supply, vehicle output and automated vehicle rules. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 22 billion and the 8.9% CAGR. |
| Data Validation | Supplier figures were matched to the half-year or quarter named in each release. |
Automotive Sensors Market by Segments
Automotive Sensors Market segmented by Sensor Type:
- Position Sensors
- Safety Sensors
- Pressure Sensors
- Temperature Sensors
- Speed Sensors
- Oxygen Sensors
- Level Sensors
Automotive Sensors Market segmented by Vehicle Type:
- Passenger Cars (Compact, Midsize, Luxury, SUVs)
- Light Commercial Vehicles
- Heavy Commercial Vehicles
Automotive Sensors Market segmented by Sales Channel:
- Original Equipment Manufacturers
- Original Equipment Supplier Spare Parts
- Independent Aftermarket
Automotive Sensors Market by Region
- North America
- Latin America
- Europe
- Asia Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] NXP Semiconductors. (2026, June 9). NXP's Latest Single-Chip Radar Solution Brings On-Sensor L2/L2+ ADAS Processing to Mainstream Vehicle Platforms. https://www.nxp.com/company/about-nxp/newsroom/NW-NXP-LATEST-SINGLE-CHIP-RADAR-SENSOR-L2-ADAS
- [2] SMMT. (2026, September 30). Vehicle manufacturing grows alongside £1bn investment boost but EU trade threats loom. https://www.smmt.co.uk/vehicle-manufacturing-grows-alongside-1bn-investment-boost-but-eu-trade-threats-loom/
- [3] Robert Bosch GmbH. (2026, September 23). Half-year figures 2026: Bosch reaffirms outlook. https://www.bosch-presse.de/pressportal/de/en/half-year-figures-2026-bosch-reaffirms-outlook-285632.html
- [4] Aptiv PLC. (2026, August 4). Aptiv Reports Second Quarter 2026 Financial Results. https://s21.q4cdn.com/440699111/files/doc_financials/2026/q2/Aptiv-Reports-Second-Quarter-2026-Financial-Results-2026.pdf
- [5] Nexperia. (2026, August 28). Nexperia delivers strong Q2 2026 performance and accelerates recovery progress. https://www.nexperia.com/about/news-events/press-releases/Nexperia-delivers-strong-Q2-2026-performance-and-accelerates-recovery-progress
- [6] Gasgoo. (2026, January 15). China's auto sales reach 34.40 million in 2025, 2026 expected to edge up 1%. https://autonews.gasgoo.com/articles/market-industry/chinas-auto-sales-reach-3440-million-in-2025-2026-expected-to-edge-up-1-2011759388677484544
- [7] DENSO Corporation. (2026, October 2). DENSO to Discontinue the Transfer of Its Spark Plug and Exhaust Gas Sensor Business to Niterra. https://www.denso.com/global/en/newsroom/news/2026/20261002-g01
- [8] National Highway Traffic Safety Administration. (2026, July 30). Trump's Transportation Department Cuts Red Tape to Safely Fast-Track Automated Vehicle Innovation. https://www.nhtsa.gov/press-releases/cutting-red-tape-safely-fast-track-automated-vehicle
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will automotive sensor sales total in 2026 and 2036?
- What CAGR will automotive sensor sales record from 2026 to 2036?
- Which sensor type will hold the largest share?
- Will carmaker fitment stay ahead of the aftermarket?
- Which countries will grow fastest?
- Which suppliers will shape competition through 2036?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Sensor Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sensor Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sensor Type, 2026 to 2036
- Position Sensors
- Safety Sensors
- Pressure Sensors
- Temperature Sensors
- Speed Sensors
- Oxygen Sensors
- Level Sensors
- Y-o-Y Growth Trend Analysis By Sensor Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sensor Type, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars (Compact, Midsize, Luxury, SUVs)
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Original Equipment Manufacturers
- Original Equipment Supplier Spare Parts
- Independent Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Asia Pacific
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Sensor Type
- By Vehicle Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Bosch
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Denso Corporation
- Aptiv
- NXP Semiconductors
- Nexperia
- Continental AG
- Aptiv PLC
- Valeo
- HELLA GmbH and Co. KGaA
- ZF Friedrichshafen AG
- Autoliv Inc.
- Infineon Technologies
- Texas Instruments
- Murata Manufacturing
- Sensata Technologies
- TE Connectivity
- Bosch
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Europe Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 15: Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 16: Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 17: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Middle East and Africa Market Value (USD Billion) Forecast by Sensor Type, 2021 to 2036
- Table 19: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 20: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Sensor Type
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Sensor Type
- Figure 23: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Vehicle Type
- Figure 26: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Sales Channel
- Figure 29: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 30: Latin America Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Sensor Type
- Figure 33: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 39: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 40: Europe Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 41: Europe Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 42: Europe Market Attractiveness Analysis by Sensor Type
- Figure 43: Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 44: Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 45: Europe Market Attractiveness Analysis by Vehicle Type
- Figure 46: Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 47: Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 48: Europe Market Attractiveness Analysis by Sales Channel
- Figure 49: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 50: Middle East and Africa Market Value Share and BPS Analysis by Sensor Type, 2026 and 2036
- Figure 51: Middle East and Africa Market Y-o-Y Growth Comparison by Sensor Type, 2026-2036
- Figure 52: Middle East and Africa Market Attractiveness Analysis by Sensor Type
- Figure 53: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 54: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 55: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 56: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 57: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 58: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 59: Global Market - Tier Structure Analysis
- Figure 60: Global Market - Company Share Analysis
Frequently Asked Questions
What is the size of the automotive sensors market in 2026?
Sensor sales are estimated at USD 24.0 billion in 2026, up from USD 22 billion in 2025, and FMI expects USD 56.2 billion by 2036.
Which forces will move automotive sensor growth?
Budget-car ADAS, battery monitoring and emission rules will carry an 8.9% CAGR from 2026 to 2036.
Which sensor type will lead in 2026?
An estimated 24.6% keeps position sensors first, and safety sensors follow at about 21.8%. Will carmaker fitment stay ahead of the aftermarket? Yes. Factory fitment holds an estimated 78.5% in 2026, and independent workshops take near 11.8%.
Which country will post the fastest growth?
American sensor sales will rise fastest, at a 9.1% CAGR from 2026 to 2036 in FMI's projection.
Which companies will matter most in this market?
Expect Bosch, Denso, Continental, Aptiv and Infineon to stay central, with chip makers like NXP adding radar and processing content.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
