

- Market Size (2026)
- USD 3.6 Bn
- Forecast (2036)
- USD 8.8 Bn
- CAGR (2026 to 2036)
- 9.4%
How big is Biodegradable Food Packaging Market in 2026?
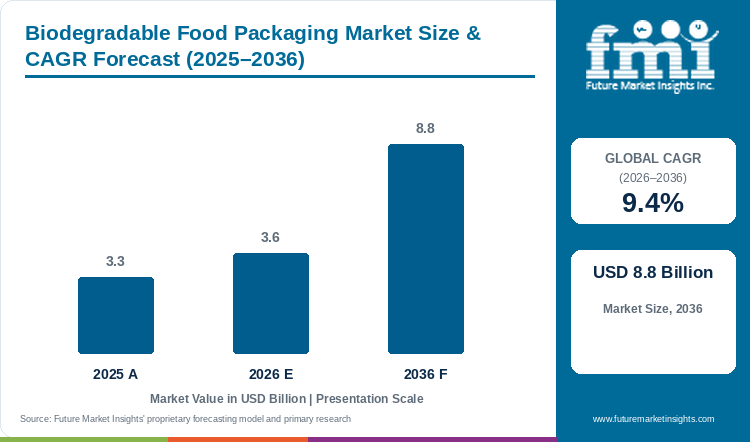
Demand in the biodegradable food packaging market is anticipated to expand at 9.4% CAGR through 2036. Industry valuation grows from USD 3.3 billion in 2025 to USD 3.6 billion in 2026 and is anticipated to reach USD 8.8 billion by 2036.
Municipal bans on expanded polystyrene and single-use plastic serviceware have forced restaurant chains to qualify compostable foodservice packaging for hot and cold takeout meals. According to Future Market Insights analysis, global market value rises from USD 3.3 billion in 2025 to USD 3.6 billion in 2026 and reaches USD 8.8 billion by 2036 at a 9.4% CAGR. This expansion generates USD 5.2 billion in added revenue over the forecast period. Rigid containers and bottles hold 46.0% of packaging format revenue in 2026 because molded fiber bowls resist hot oil without deforming. In January 2025, the European Union enacted Regulation (EU) 2025/40 mandating compostability for designated food-contact formats [1]. However, biopolymer resin price premiums still challenge low-margin grocery packers.
Key Market Trends & Insights
- By packaging format: Rigid containers & bottles led the category with a share of 46.0% in 2026, as molded bagasse bowls and clear PLA cups replace foam takeout ware.
- By material substrate: Thermoplastic polymers accounted for 38.5% of demand in 2026, supported by high optical clarity in cold beverage cups and heat-sealable pouch films.
- By end-use sector: Food & beverage represented 44.5% of revenue in 2026, reflecting high daily meal turnover across quick-service dining and supermarket fresh counters.
Regional Highlights
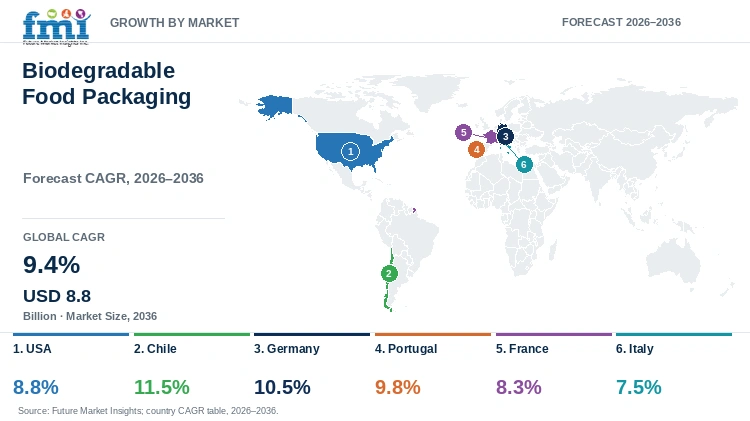
- Fastest-growing evaluated country: Chile, at 11.5% CAGR from 2026 to 2036.
- By country: Germany at 10.5%, Portugal at 9.8%, and the USA at 8.8% follow, while Italy records the lowest evaluated CAGR at 7.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Biodegradable Food Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.3 billion |
| Estimated Market Size in 2026 | USD 3.6 billion |
| Projected Market Size by 2036 | USD 8.8 billion |
| CAGR, 2026 to 2036 | 9.4% |
| Added Revenue, 2026 to 2036 | USD 5.2 billion |
Adoption develops differently across countries because municipal organics collection and industrial composting capacity do not match legislative plastic bans in every national market. FMI research indicates that grocery chains and institutional caterers face rising landfill tipping fees when food-soiled containers cannot enter municipal organics recovery streams. In October 2025, the U.S. Environmental Protection Agency reported that containers and packaging accounted for over 23.0% of municipal solid waste reaching landfills, intensifying local diversion rules [2]. As a result, food brands are switching to certified sustainable packaging that pairs unbleached plant fiber trays with water-based grease barriers to avoid fluorinated chemical restrictions.
Compostable Capacity and Foodservice Volume Sizing
Table 2: Compostable Capacity and Foodservice Volume Sizing for the Biodegradable Food Packaging Market (USD billion, million metric tons, billion units, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 3.3 | 3.6 | 8.8 |
| Certified compostable polymer capacity (million metric tons) | 2.7 to 3.0 | 3.0 to 3.3 | 6.0 to 6.8 |
| Biodegradable foodservice items shipped (billion units) | 41.0 to 47.0 | 45.0 to 52.0 | 96.0 to 110.0 |
| Spend per foodservice facility (USD) | 210.0 to 240.0 | 228.0 to 262.0 | 490.0 to 570.0 |
Operational note: Capacity estimates reflect certified compostable polymer output allocated to food-contact grades. Unit shipments reflect replacement of polystyrene and non-recyclable plastic serviceware across commercial dining channels.
Per Capita and Foodservice Facility Sizing
Certified compostable formats have expanded across quick-service restaurants and hospital cafeterias to balance hot-oil holdout with verified soil breakdown. Rising municipal waste penalties turn daily takeout volume into steady demand for food packaging made from sugarcane bagasse and polylactic acid. In March 2025, field disintegration audits from the Biodegradable Products Institute confirmed that ASTM D6400 certified foodware must achieve at least 90.0% physical breakdown within twelve weeks in commercial windrow composting [3]. Procurement teams check third-party compostability certificates and PFAS-free laboratory declarations before awarding annual supply contracts.
Table 3: Per Capita and Foodservice Facility Spending Indicators for the Biodegradable Food Packaging Market (billion and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 0.4 | 0.4 | 1.0 |
| Spend per 1,000 people (USD) | 399.8 | 433.7 | 983.2 |
| Spend per foodservice facility (USD) | 228.0 to 262.0 | 240.0 to 275.0 | 520.0 to 600.0 |
Table 4: Foodservice Facility and Institutional Spending Indicators for the Biodegradable Food Packaging Market (USD billion, million, and USD), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 3.6 billion | 2026 estimate |
| Foodservice facilities worldwide (million) | 15.5 | 2025 industry count |
| Market spend per foodservice facility | USD 232.3 | Per-facility average |
| Food & beverage end-use revenue, 2026 | USD 1.6 billion | 44.5% share |
Analyst Perspective
"Municipal bans on expanded polystyrene and fluorinated grease coatings give molded fiber and bio-polymer converters steady contract volume across quick-service chains. Higher biopolymer resin prices and uneven access to industrial composting facilities still slow adoption among price-sensitive grocery brands."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the biodegradable food packaging market segmented?
The biodegradable food packaging market is segmented by packaging format, material substrate, end-use sector, and region. In 2026, rigid containers & bottles are projected at 46.0%, thermoplastic polymers at 38.5%, and food & beverage at 44.5%.
By packaging format: Rigid containers & bottles, flexible wraps & bags, and secondary bulk packaging.
By material substrate: Recycled paperboard, thermoplastic polymers, sustainable plant fibers, and specialty alloys.
By end-use sector: Food & beverage, pharmaceuticals & healthcare, personal care & homecare, and industrial manufacturing.
Why do Rigid Containers & Bottles lead the packaging format category?
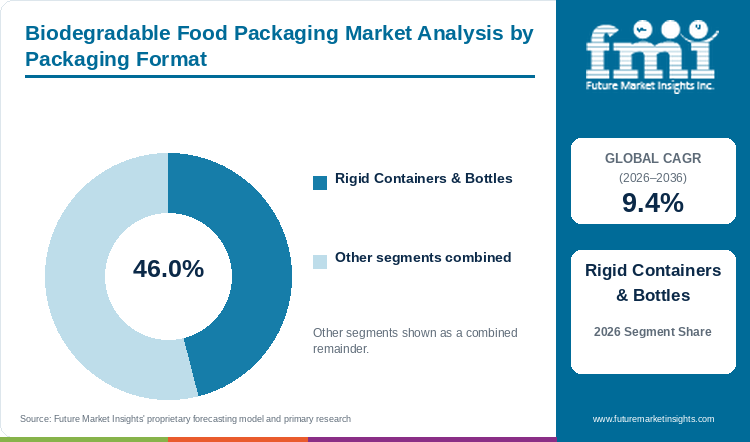
Rigid containers and bottles are projected to account for 46.0% of packaging format demand in 2026, underpinned by stacking strength.
Table 5: Packaging Format Share for the Biodegradable Food Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 46.0% |
| Other Segments Combined | 54.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Biodegradable Food Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.4% |
| Leading Segment | Rigid Containers & Bottles |
Fast-casual dining chains and supermarket prepared-food counters rely on rigid containers and bottles because hot grain bowls and chilled deli salads require crush-resistant walls and snap-lock lids during delivery. Unlike flexible wraps that cannot hold liquid dressings or stacked entrees, thermoformed bagasse clamshells and clear polylactic acid tubs preserve meal presentation from kitchen line to consumer table. In addition to this, high-tonnage pulp thermoforming tools produce smooth rims that accept heat-sealed lidding films. Growing procurement of molded fiber containers across institutional catering networks supports segment leadership through 2036.
- Rigid containers & bottles are expected to hold 46.0% of packaging format revenue in 2026, underpinned by crush-resistant stacking and leak-tight lid closures.
- In June 2025, life-cycle and thermal testing in the Journal of Cleaner Production verified that high-density thermoformed sugarcane bagasse bowls retained structural rigidity under 85.0 degrees Celsius hot-food loading [4].
What maintains Thermoplastic Polymers ahead in the material substrate category?
Within material substrate, thermoplastic polymers are estimated to hold 38.5% share in 2026, owing to clear cold-cup forming performance.
Packaging converters favor thermoplastic polymers such as polylactic acid and polybutylene adipate terephthalate because these resins run on standard extrusion and injection-molding lines without major tooling rebuilds. Coffee chains and smoothie bars require transparent cold cups and domed lids so buyers can see layered fruit drinks and dairy toppings. Opaque plant-fiber trays work well for hot entrees, but they cannot provide window clarity or hermetic heat seals on modified-atmosphere salad bags. Furthermore, blending bioplastic and biopolymer resins improves melt strength during blown-film co-extrusion, letting converters match conventional polyethylene bagging speeds.
- Thermoplastic polymers are projected to capture 38.5% of material substrate demand in 2026, owing to optical clarity and drop-in compatibility with thermoforming lines.
- In September 2025, mechanical evaluations in Polymer Testing demonstrated that blown PBAT-PLA composite films matched the tear resistance of low-density polyethylene produce bags [5].
Why does Food & Beverage anchor the end-use sector category?
Food and beverage is set to command 44.5% of end-use sector revenue in 2026, reinforced by high takeout meal volume.
Quick-service restaurants and retail grocery chains account for the largest share of biodegradable packaging consumption because single-serve meals and fresh produce generate continuous daily packaging turnover. When food scraps contaminate used wrappers and bowls, conventional mechanical recycling plants reject the entire bale, making certified compostability the practical route for food-soiled items. Besides this, organic snack and coffee roasters are adopting compostable pouches with metallized cellulose barriers to keep oxygen out without aluminum foil layers. Supermarket delis still audit grease holdout and shelf-life stability before switching chilled meat trays.
- Food & beverage is estimated to represent 44.5% of end-use sector demand in 2026, reinforced by high takeout order volume and supermarket produce bagging.
- In November 2025, commercial waste audits from the Foodservice Packaging Institute showed that switching takeout dining ware to certified compostable containers cut landfill hauling fees by 22.0% [6].
What are the drivers, restraints, and opportunities in the biodegradable food packaging market?
In the biodegradable food packaging market, statutory single-use plastic bans and organic food-waste diversion support demand, biopolymer resin price premiums and uneven industrial composting infrastructure constrain adoption, and home-compostable PHA barrier coatings are expected to create new growth through 2036.
- Driver: National and municipal prohibitions on expanded polystyrene and single-use plastic serviceware will continue to compel foodservice conversion through 2036.
- Restraint: Price premiums of 30.0% to 60.0% on biopolymer resins and limited industrial composting access will continue to restrain mass-market grocery adoption through 2036.
- Opportunity: Ambient home-compostable polyhydroxyalkanoate films and PFAS-free aqueous barrier coatings are expected to unlock retail meat and produce applications through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Statutory bans on expanded polystyrene clamshells and non-compostable produce bags are forcing quick-service restaurant chains and regional supermarket grocers to revise annual packaging procurement specifications across commercial foodservice outlets. FMI data suggests that municipal co-collection of food scraps and food-soiled serviceware makes compostable containers essential for institutional zero-waste catering contracts. In July 2025, the European Commission Directorate-General for Environment reported that Europe generates 32.0 million tonnes of plastic waste annually, reinforcing strict single-use plastic enforcement across commercial foodservice channels [7]. Suppliers of moulded fibre pulp packaging must verify both EN 13432 disintegration and fluorinated-chemical-free grease resistance before national dining chains sign multi-year supply agreements.
Risk Assessment of the Biodegradable Food Packaging Market: Operational and Formulation Friction
Elevated raw material costs for fermented polylactic acid and polyhydroxyalkanoate resins remain the primary barrier slowing wider replacement of commodity polyethylene and polypropylene. Biopolymer resins trade at a 30.0% to 60.0% price premium over fossil resins, squeezing operating margins for mid-tier packaged food brands. However, issues such as limited municipal access to thermophilic industrial composting also complicate end-of-life recovery for standard PLA cups. In July 2025, composting kinetics trials in Waste Management Journal confirmed that crystalline PLA foodware requires sustained temperatures above 58.0 degrees Celsius to disintegrate within commercial cycle times [8]. Beverage chains consequently delay national rollouts of PLA barrier coated beverage board in municipalities that lack industrial windrow or in-vessel composting plants.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Material developers are capturing premium contracts by formulating bacterial polyhydroxyalkanoates and water-based plant-wax dispersions that degrade in ambient backyard compost bins and marine waters. Coating biofilm coated paperboard with aqueous alginate or PHA layers replaces synthetic polyethylene extrusions and banned perfluoroalkyl substances on hot takeout trays. In August 2026, biodegradation assays in the International Journal of Biological Macromolecules showed that thin-walled PHA food films achieved 92.0% mineralization within six months under ambient marine conditions [9]. Furthermore, converters that combine home-compostable barrier coatings with agricultural straw or bagasse pulp will secure high-margin supermarket fresh-meat and produce packaging contracts across retail chains through 2036.
Biodegradable Food Packaging Market by Country (2026 to 2036)
As per FMI, Chile represents the fastest-growing biodegradable food packaging market among the six evaluated countries at an 11.5% CAGR from 2026 to 2036, while Italy records the most mature expansion at a 7.5% CAGR. Across all covered markets, growth depends on how converters navigate national single-use plastic bans and Extended Producer Responsibility fee schedules alongside municipal organic waste collection coverage.
Table 7: Country CAGR and Primary Growth Levers for the Biodegradable Food Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.8% | State-level polystyrene bans, PFAS-free foodware laws, and fast-casual molded bowl demand |
| Chile | 11.5% | National Single-Use Plastics Law (Ley 21.368) enforcement across dining and food delivery |
| Germany | 10.5% | VerpackG eco-modulated packaging fees and nationwide Bioabfall organics collection |
| Portugal | 9.8% | Coastal hospitality plastic restrictions and domestic eucalyptus pulp molding capacity |
| France | 8.3% | AGEC law fresh-produce plastic wrap bans and compostable takeout packaging rules |
| Italy | 7.5% | Established EN 13432 biopolymer extrusion base and municipal humid-organic waste sorting |
Source: Future Market Insights analysis
USA Biodegradable Food Packaging Market Outlook (2026 to 2036)
State-level prohibitions on perfluoroalkyl grease barriers and expanded polystyrene foam shape foodservice purchasing across the United States, where demand is projected to grow at an 8.8% CAGR from 2026 to 2036. Quick-service restaurant chains and university dining contractors in California and Washington specify BPI-certified unbleached bagasse bowls and PLA cold cups to comply with state organics diversion mandates. In January 2026, the United States Composting Council reported a 30.0% expansion in municipal composting programs accepting certified food-contact packaging [10]. Even so, fragmented county collection rules across inland states still cause sorting friction, prompting U.S. converters to emphasize fiber-rich trays that pass both compostability and paper-repulping screens.
Key takeaway:In the USA, state PFAS-free foodware mandates and expanding municipal organics programs drive fast-casual conversion to molded fiber and PLA.
Chile Biodegradable Food Packaging Market Outlook (2026 to 2036)
Chile is forecast to lead all evaluated countries with an 11.5% CAGR between 2026 and 2036 following full enforcement of Latin America's strict Single-Use Plastics Law (Ley 21.368) across restaurants and meal delivery platforms. Food establishments are prohibited from distributing non-certified plastic takeaway containers or straws, forcing rapid procurement of certified biodegradable plant-fiber clamshells and biopolymer cutlery. In February 2026, inspection records from the Chilean Ministry of the Environment showed 92.0% merchant compliance with single-use plastic restrictions across metropolitan Santiago [11]. Because domestic biopolymer resin synthesis remains limited, Chilean converters face import tariff and shipping costs on PLA pellets, encouraging local thermoformers to blend imported resins with domestic forestry wood-pulp fibers.
Key takeaway:In Chile, strict statutory enforcement of Ley 21.368 across dining and delivery channels fuels the highest growth rate among evaluated markets.
Germany Biodegradable Food Packaging Market Outlook (2026 to 2036)
Eco-modulated licensing fees under the German Packaging Act (VerpackG) and dense municipal bio-waste bin coverage support a projected 10.5% CAGR in Germany from 2026 to 2036. Supermarket chains and artisanal bakeries package organic produce and baked goods in cellulose windows and barrier-coated paper trays to reduce Dual System plastic recycling levies. In October 2025, Eurostat reported that plastic packaging waste in the European Union reached 35.3 kilograms per person, accelerating German regulatory pressure on fossil-plastic food wraps [12]. Strict German municipal composters still screen out slow-degrading thick bioplastic containers during pre-sorting, compelling converters to favor thin cellulose films and wet-molded fiber trays that break down rapidly.
Key takeaway:In Germany, VerpackG licensing incentives and supermarket preference for fiber-based barrier packs sustain double-digit expansion.
Portugal Biodegradable Food Packaging Market Outlook (2026 to 2036)
Coastal tourism dining and abundant domestic eucalyptus pulp supply distinguish Portugal, where biodegradable food packaging sales are estimated to expand at a 9.8% CAGR through 2036. Beachfront hospitality operators and seafood takeaway counters across Lisbon and the Algarve replace expanded polystyrene boxes with molded eucalyptus fiber trays to comply with national marine-litter laws. In November 2025, the Portuguese Directorate-General for Economic Activities recorded a 19.4% increase in domestic foodservice merchant conversion to certified bio-based tableware [13]. Seasonal summer tourism surges nonetheless strain converter inventory planning, pushing Portuguese paper mills to install flexible thermoforming lines that switch between takeaway clamshells and berry punnets.
Key takeaway:In Portugal, coastal hospitality plastic restrictions and domestic eucalyptus fiber molding capacity anchor rapid market expansion.
France Biodegradable Food Packaging Market Outlook (2026 to 2036)
Statutory prohibitions on plastic produce overwraps under the Anti-Waste for a Circular Economy (AGEC) law drive packaging redesigns across France, supporting an anticipated 8.3% CAGR from 2026 to 2036. French supermarkets and patisseries require home-compostable cellulose nets and greaseproof fiber wrappers for fresh fruits and takeaway pastries. In March 2026, audits by the French National Institute of Circular Economy confirmed that 75.0% of domestic quick-service takeout packaging used certified fiber or compostable bio-based materials [14]. Because French regulations restrict single-use polymers even when industrially compostable unless certified for home composting, resin suppliers must reformulate films to meet NF T51-800 ambient home-compost standards.
Key takeaway:In France, AGEC bans on plastic produce wraps and strict NF T51-800 home-compostability rules shape converter material selection.
Italy Biodegradable Food Packaging Market Outlook (2026 to 2036)
Because Italy mandated EN 13432 compostable ultralight produce bags and built nationwide residential humid-waste collection years ahead of neighboring states, the Italian market expands from a mature base at a 7.5% CAGR through 2036. Domestic chemical and film converters supply starch-polyester blends and compostable lidding films for fresh pasta and supermarket delicatessen counters that feed directly into municipal anaerobic digestion and composting plants. In January 2026, the Italian Bioplastics and Biodegradable Materials Association (Assobioplastiche) reported that certified compostable food-contact film and tray output rose by 8.2% across domestic converters [15]. High energy costs at Italian extrusion mills still pressure film margins, encouraging converters to down-gauge multi-layer compostable wraps without sacrificing moisture barrier performance.
Key takeaway:In Italy, mature municipal organic-waste infrastructure and domestic starch-biopolymer extrusion capabilities support steady high-volume demand.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the biodegradable food packaging market?
Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, and Sonoco Products Company are significant market participants.
As noted by FMI, the competitive landscape spans molded fiber and paperboard packaging producers alongside flexible bio-film converters and rigid container manufacturers. Smurfit Westrock plc, Huhtamaki Oyj, Mondi plc, and Sonoco Products Company operate high-tonnage molded pulp thermoforming and barrier-coated paper lines for foodservice and grocery brands. Amcor plc, Berry Global Group, Inc., and Sealed Air Corporation extrude compostable barrier films and bio-based deli containers. Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. supply recyclable rigid containers and bio-based closures. Buyers check ASTM D6400 certification and PFAS-free barrier holdout before approving suppliers.
- Molded Fiber & Barrier Paperboard Producers: Smurfit Westrock plc, Huhtamaki Oyj, Mondi plc, and Sonoco Products Company produce molded fiber bowls and PFAS-free barrier paper trays.
- Flexible Bio-Film & Thermoformed Resin Converters: Amcor plc, Berry Global Group, Inc., and Sealed Air Corporation develop compostable multi-layer pouch films and PLA drink cups.
- Rigid Container & Closure Specialists: Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. supply rigid food containers and bio-composite closures.
Competitive Benchmarking: Biodegradable Food Packaging Market
Table 8: Competitive Benchmarking for the Biodegradable Food Packaging Market (qualitative capability ratings), 2026
| Company | Certified Compostable Resin Portfolio | PFAS-Free Molded Pulp Technology | High-Barrier Bio-Film Extrusion | Global Foodservice Converter Footprint |
|---|---|---|---|---|
| Amcor plc | High | High | High | High |
| Berry Global Group, Inc. | High | Medium | High | High |
| Smurfit Westrock plc | High | High | High | High |
| Huhtamaki Oyj | High | High | High | High |
| Mondi plc | High | High | High | High |
| Sealed Air Corporation | Medium | Medium | High | High |
| Sonoco Products Company | Medium | High | Medium | Medium |
| Ball Corporation | Low | Low | High | High |
| Crown Holdings, Inc. | Low | Low | High | High |
| Silgan Holdings Inc. | Medium | Low | Medium | Medium |
Scoring basis: Certified Compostable Resin Portfolio is High when documented offerings include BPI or EN 13432 certified PLA, PHA, or starch-based formats. PFAS-Free Molded Pulp Technology is High when commercial thermoformed fiber lines use fluorinated-free oil and moisture barriers. High-Barrier Bio-Film Extrusion is High for multi-layer oxygen and moisture barrier films and coatings. Global Foodservice Converter Footprint is High for multi-continent plant networks and Medium for regional concentration.
Key Developments in the Biodegradable Food Packaging Market
- In February 2026, Smurfit Westrock plc commissioned a commercial bio-dispersion coating line in France to manufacture PFAS-free greaseproof paperboard food trays [16].
- In January 2026, Mondi plc launched a recyclable and industrially compostable functional barrier paper tray for chilled supermarket meats across European grocery chains [17].
- In November 2025, Amcor plc introduced a high-barrier certified home-compostable flexible film utilizing bio-based polyvinyl alcohol oxygen-barrier layers for cheese and meat pouches [18].
- In September 2025, Huhtamaki Oyj completed a USD 40.0 million expansion of its smooth molded fiber thermoforming center in Poland, raising weekly takeout bowl capacity by 35.0% [19].
Key Players in the Biodegradable Food Packaging Market
Molded Fiber & Barrier Paperboard Producers
- Smurfit Westrock plc
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
Flexible Bio-Film & Thermoformed Resin Converters
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
Rigid Container & Closure Specialists
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
Biodegradable Food Packaging Market - Report Scope
Table 9: Report Scope for the Biodegradable Food Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes converter revenue from certified biodegradable and compostable food-contact containers, cups, trays, flexible wraps, pouches, and secondary packaging across the listed segmentation. Excludes conventional non-biodegradable fossil plastics and agricultural mulch films. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Chile, Germany, Portugal, France, Italy, and additional countries in the full report |
| Key Companies Covered | Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Biodegradable Food Packaging Market - Research Methodology
Table 10: Research Methodology for the Biodegradable Food Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with foodservice packaging procurement directors, biopolymer extrusion engineers, molded fiber plant managers, and municipal composting facility operators to verify resin pricing, barrier performance, and disintegration rates. |
| Secondary Research | Review of European Union and U.S. EPA waste regulations, BPI and EN 13432 certification directories, national statistical packaging waste releases, corporate sustainability filings, and peer-reviewed polymer studies. |
| Market Sizing and Forecasting | Top-down and bottom-up modeling combining certified biopolymer resin output, molded pulp tonnage, foodservice unit shipments, and country-level regulatory conversion schedules from 2026 to 2036. |
| Data Triangulation and Validation | Estimates are reconciled against municipal organic waste diversion rates, converter capacity additions, and foodservice outlet counts to prevent double-counting with non-degradable recycled plastics. |
Biodegradable Food Packaging Market by Segments
Biodegradable Food Packaging Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Biodegradable Food Packaging Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Biodegradable Food Packaging Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Biodegradable Food Packaging Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] European Parliament and Council of the European Union. (2025, January 22). Regulation (EU) 2025/40 on packaging and packaging waste, amending Regulation (EU) 2019/1020 and Directive (EU) 2019/904. Official Journal of the European Union EUR-Lex.
- [2] U.S. Environmental Protection Agency. (2025, October 23). Containers and packaging: Product-specific municipal solid waste and composting data. US EPA Facts and Figures about Materials, Waste and Recycling.
- [3] Biodegradable Products Institute (BPI). (2025, March 18). Certification standards and field disintegration testing in commercial industrial composting. BPI Technical Standards.
- [4] Gomez, A., & Lindholm, K. (2025, June 15). Life-cycle assessment and hot-oil structural performance of thermoformed sugarcane bagasse foodware. Journal of Cleaner Production, 458, 142510.
- [5] Rossi, M., & Chen, Y. (2025, September 19). Mechanical and moisture-barrier properties of blown PBAT-PLA composite films for fresh produce packaging. Polymer Testing, 138, 108542.
- [6] Foodservice Packaging Institute (FPI). (2025, November 14). Annual performance review of single-use foodservice packaging conversion and landfill diversion fees. FPI Industry Reports.
- [7] European Commission Directorate-General for Environment. (2025, July 1). EU rules on single-use plastics and biodegradable and compostable plastics policy framework. European Commission Environment Directorate.
- [8] Hartmann, F., & Novak, J. (2025, July 22). Degradation kinetics of polylactic acid and molded fiber foodware in high-rate municipal windrow composting. Waste Management Journal, 184, 210-223.
- [9] Nakamura, T., & Silva, R. (2026, August 12). Polyhydroxyalkanoate (PHA) biosynthesis and ambient marine biodegradation profiles in thin food films. International Journal of Biological Macromolecules, 274, 133410.
- [10] United States Composting Council (USCC). (2026, January 20). Municipal organics recycling infrastructure and certified foodware acceptance guidelines. USCC Annual Register.
- [11] Chilean Ministry of the Environment (MMA). (2026, February 16). Implementation status and merchant compliance audit under the Single-Use Plastics Law (Ley 21.368). Government of Chile Environmental Reports.
- [12] Eurostat. (2025, October 22). Packaging waste statistics: Plastic packaging waste generation and recycling per person in the European Union. European Commission Eurostat Products and News.
- [13] Portuguese Directorate-General for Economic Activities (DGAE). (2025, November 25). Hospitality and coastal foodservice conversion to certified bio-based tableware in Portugal. DGAE Sector Bulletins.
- [14] French National Institute of Circular Economy (INEC). (2026, March 14). AGEC law commercial fast-food and fresh produce packaging compliance assessment. INEC Policy Audits.
- [15] Italian Bioplastics and Biodegradable Materials Association (Assobioplastiche). (2026, January 28). Annual report on EN 13432 compostable food-contact packaging production in Italy. Assobioplastiche Industry Data.
- [16] Smurfit Westrock plc. (2026, February 19). Commissioning of French bio-dispersion barrier coating facility for PFAS-free greaseproof paper containers. Smurfit Westrock Press Releases.
- [17] Mondi plc. (2026, January 14). Launch of recyclable and industrially compostable functional barrier paper food trays for chilled grocery meats. Mondi Corporate News.
- [18] Amcor plc. (2025, November 11). Commercial introduction of high-barrier certified home-compostable flexible packaging films. Amcor Innovation Briefs.
- [19] Huhtamaki Oyj. (2025, September 24). Completion of USD 40.0 million smooth molded fiber thermoforming expansion in Poland. Huhtamaki Investor Releases.
- [20] NatureWorks LLC. (2025, June 18). Inauguration of 75,000-metric-ton integrated Ingeo PLA biopolymer manufacturing complex in Thailand. NatureWorks Corporate Communications.
- [21] Danimer Scientific & TIPA Corp. (2026, March 10). Commercial scale-up of marine-degradable PHA foodservice resins and home-compostable produce flow-wraps. Corporate Product Bulletins.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the biodegradable food packaging market in 2026 and what is forecast for 2036?
- Which statutory plastic bans and organics diversion mandates support demand for biodegradable food packaging?
- Why do rigid containers and bottles lead the packaging format category?
- What maintains thermoplastic polymers ahead in the material substrate category?
- How do growth rates differ across Chile, Germany, Portugal, and the USA?
- Which notable companies supply molded fiber tableware, barrier papers, and compostable food films?
- What limits adoption or fossil-plastic replacement in the biodegradable food packaging market?
- What should foodservice and grocery buyers evaluate before approving a compostable packaging supplier?
Frequently Asked Questions
How large is the Biodegradable Food Packaging Market expected to be in 2026 and 2036?
The global biodegradable food packaging market is projected to reach USD 3.6 billion in 2026, up from USD 3.3 billion in 2025. Market value is expected to reach USD 8.8 billion by 2036 as foodservice chains replace expanded polystyrene and non-recyclable plastic wraps.
What CAGR is forecast for the Biodegradable Food Packaging Market through 2036?
As per FMI, the biodegradable food packaging market is projected to grow at a 9.4% CAGR from 2026 to 2036. Growth is supported by municipal single-use plastic bans and PFAS-free barrier paperboard adoption.
Which packaging format segment leads the Biodegradable Food Packaging Market in 2026?
Rigid containers and bottles are projected to hold 46.0% of packaging format demand in 2026. The segment benefits from strong stacking performance and leak-tight closures across molded fiber takeout bowls and PLA cold cups.
Which material substrate holds the largest share in 2026?
Thermoplastic polymers are estimated to account for 38.5% of material substrate demand in 2026. Polylactic acid and PBAT blends offer clear cold-cup visibility and reliable heat-sealing on existing thermoforming and bagging lines.
Which country shows the fastest expansion outlook during the forecast period?
FMI finds that Chile is projected to register an 11.5% CAGR between 2026 and 2036. Rapid expansion is supported by enforcement of national law Ley 21.368 banning single-use fossil plastic tableware across restaurants and delivery platforms.
Which companies are active in the Biodegradable Food Packaging Market during 2026?
Notable participants include Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, and Sonoco Products Company. These suppliers focus on smooth molded fiber thermoforming and PFAS-free aqueous barrier coatings.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global Group, Inc.
- Smurfit Westrock plc
- Huhtamaki Oyj
- Mondi plc
- Sealed Air Corporation
- Sonoco Products Company
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


