

- Market Size (2026)
- USD 396.2 Mn
- Forecast (2036)
- USD 1125.0 Mn
- CAGR (2026 to 2036)
- 11.0%
How big is Cannoli Market in 2026?
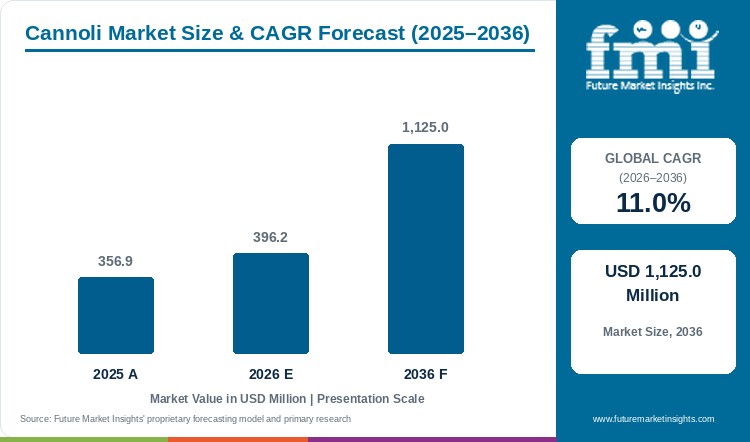
Starting from USD 356.9 million in 2025, the cannoli market valuation advanced to USD 396.2 million in 2026, with projections pointing toward USD 1,125.0 million by 2036 at a CAGR of 11.0%.
Supermarket bakeries and casual restaurant chains are increasing their orders for factory-filled cannoli because kitchen staffing shortages make daily hand piping too costly to sustain. This shift toward ready-to-serve pastries aligns with an August 2025 UK Office for National Statistics survey showing that 61.0% of foodservice and hospitality businesses faced higher staffing costs [1]. To cut store preparation time while keeping pastry cases full, grocery buyers rely on Classic / original varieties, which are expected to hold a 40.0% share of the product type segment in 2026 and grow faster than frozen pastries at a 5.4% CAGR. Future Market Insights estimates that global cannoli demand will rise from USD 356.9 million in 2025 to USD 396.2 million in 2026 and reach USD 1,125.0 million by 2036, advancing at an 11.0% CAGR to add USD 728.8 million in industry value. Even with strong buyer adoption, moisture seeping from sweet ricotta cream into fried pastry shells after two days in chilled cases and strict milk and tree-nut allergen rules still limit long-distance distribution.
Key Market Trends & Insights
- By product type: Classic / original is expected to hold a 40.0% share in 2026 because recognizable fried pastry tubes filled with sweet ricotta establish the reference taste for retail bakery cases.
- By claim / nature: Conventional is estimated to hold a 59.0% share in 2026 as established wheat-flour shells and dairy fillings maintain predictable blister formation and cream viscosity.
- By format: Fresh is projected to account for a 32.0% share in 2026 owing to short-cycle counter filling that preserves crisp pastry walls against moist ricotta.
- By packaging format: Multipack is predicted to record a 29.0% share in 2026 driven by two-count and four-count clamshells that lift household take-home basket value.
- By sales channel: Supermarkets & hypermarkets are anticipated to hold a 29.0% share in 2026 supported by refrigerated perimeter bakery displays that capture planned grocery traffic.
Regional Highlights
- Top national expansion: The UAE is projected to lead country growth at a 12.4% CAGR through 2036 owing to luxury hotel dessert buffets and chilled patisserie counters.
- Broader country progression: Saudi Arabia is expected to expand at a 12.1% CAGR ahead of South Korea at 11.7% and the USA at 11.4%, while Japan is forecast to advance at a 10.1% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Cannoli Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 356.9 million |
| Estimated Market Size in 2026 | USD 396.2 million |
| Projected Market Size by 2036 | USD 1,125.0 million |
| CAGR, 2026 to 2036 | 11.0% |
| Added Revenue, 2026 to 2036 | USD 728.8 million |
In-store supermarket bakeries and casual-dining chains face persistent pastry-finishing labor shortages that limit on-demand shell piping during peak evening hours. Manual back-of-house filling frequently causes uneven portion weights and premature shell softening when trays sit in humid display cases. Data published by the USDA Economic Research Service in June 2026 show that United States food-away-from-home expenditure reached USD 1.41 trillion in 2025 to represent 56.3% of total food spending, expanding the commercial restaurant and retail bakery counter footprint for portioned Italian desserts [2]. As a result, retail bakery directors are shifting orders toward frozen baked goods and chocolate-lined cannoli shells that maintain structural crunch across 48-hour chilled merchandising windows.
Bakery-Counter and Portion-Volume Sizing
Table 2: Bakery-Counter and Portion-Volume Sizing for the Cannoli Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 356.9 | 396.2 | 1,125.0 |
| Commercial cannoli portions sold (million units) | 148.0 to 165.0 | 162.0 to 182.0 | 430.0 to 480.0 |
| Refrigerated bakery display doors stocking cannoli (thousand) | 84.0 to 96.0 | 92.0 to 105.0 | 210.0 to 240.0 |
| Average wholesale realization per portion (USD) | 2.15 to 2.40 | 2.20 to 2.45 | 2.35 to 2.60 |
Operational note: Portion-volume ranges reconcile wholesale shell-and-cream case shipments against two-piece retail clamshell pricing and foodservice dessert plate allocations across covered markets.
Supermarket perimeter bakeries require predictable shell blister density and controlled cream water activity to prevent soggy pastry returns before the printed sell-by date. Wholesale pastry manufacturers now pair lipid-coated tube interiors with bake-stable chocolate fillings to extend refrigerated case life without sacrificing the signature snap.
Per Capita & Retail Bakery Outlet Sizing
Table 3: Per Capita and Outlet Spending Indicators for the Cannoli Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 43.5 | 47.7 | 125.0 |
| Annual cannoli procurement per stocking bakery outlet (USD) | 1,650 to 1,920 | 1,780 to 2,080 | 3,850 to 4,420 |
| Prefilled and component-kit contract share (%) | 52.0% to 56.0% | 55.0% to 59.0% | 68.0% to 72.0% |
Table 4: Retail & Foodservice Bakery Outlet Indicators for the Cannoli Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 396.2 million | 2026 global cannoli valuation baseline |
| Commercial bakery and patisserie outlets | 215.0 thousand | Global supermarket in-store and specialty bakery registry |
| Market spend per outlet | USD 1,842.8 | Annualized wholesale pastry and filling expenditure |
| Supermarkets & hypermarkets allocation, 2026 | USD 114.9 million | 29.0% sales channel segment share |
Careful control of shell crispness and smooth dairy mouthfeel governs repeat retailer orders across chilled grab-and-go cases. Commercial bakeries combine high-fat ricotta blends with confectionery fillings and chocolate-dipped shell ends to lock out ambient humidity during store display.
Analyst Perspective
"Retail bakery expansion for cannoli depends less on consumer familiarity with Italian pastry than on controlling moisture transfer between sweet ricotta cream and fried dough shells during chilled holding. Manufacturers that supply chocolate-lined prefilled units and thawed-on-demand pastry bags with verified 48-hour crunch retention are securing national supermarket listings."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the cannoli market segmented?
The cannoli market is segmented by product type, claim / nature, format, packaging format, and sales channel. In 2026, Classic / original is projected at 40.0%, Conventional at 59.0%, Fresh at 32.0%, Multipack at 29.0%, and Supermarkets & hypermarkets at 29.0%.
By product type: Classic / original, Whole grain & seeded, Flavored & filled, Mini & snacking formats, and Premium / artisan.
By claim / nature: Conventional, Clean label, Organic, Gluten-free, and High-protein / fortified.
By format: Fresh, Frozen, Ambient packaged, Chilled, and Par-baked / thaw-and-serve.
By packaging format: Multipack, Single-serve, Family / loaf pack, and Bulk foodservice.
By sales channel: Supermarkets & hypermarkets, Artisan & specialty bakeries, Convenience & forecourt, Online & DTC, and Foodservice distributors.
Why does Classic / original anchor the Product Type category?
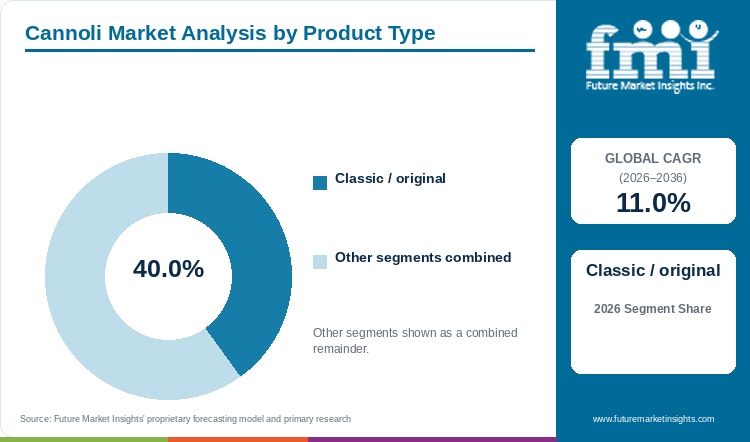
Classic / original is expected to hold a 40.0% share of the product type segment in 2026, supported by recognizable ricotta-and-shell construction.
Table 5: Product Type Share for the Cannoli Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Classic / original | 40.0% |
| Other Segments Combined* | 60.0% |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Cannoli Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.0% |
| Leading Segment | Classic / original |
Supermarket bakery buyers rely on Classic / original cannoli to anchor Italian pastry sets because shoppers immediately recognize a blistered fried tube filled with sweet impastata ricotta and chocolate chips. Standardized shell diameters and cream viscosities simplify automated depositing with chocolate inclusions and decorations across regional commissaries.
- Classic / original is expected to hold a 40.0% share of the product type segment in 2026 owing to predictable consumer repeat rates and standardized shell-to-cream ratios.
- Publix Super Markets expanded its seasonal in-store bakery assortment in June 2026 with specialty crunch and cream-filled pastry items built around established refrigerated case workflows [3].
How does Conventional retain its Claim / Nature lead?
Conventional is estimated to hold a 59.0% share of the claim / nature segment in 2026, driven by predictable frying blister mechanics and dairy stability.
Conventional wheat-gluten shells and full-fat dairy fillings remain the commercial baseline because alternative flours alter dough extensibility during hot-oil frying and increase shell breakage in transit. Producers formulating specialty variants must also validate allergen segregation protocols and cake flour specifications before supermarket quality teams approve line extensions.
- Conventional is estimated to hold a 59.0% share of the claim / nature segment in 2026 attributed to lower ingredient qualification costs and reliable frying tolerance.
- The UK Food Standards Agency published updated best-practice guidance in February 2025 requiring out-of-home bakeries and cafes to provide written allergen declarations with verbal confirmation for non-prepacked foods [4].
What explains Fresh leadership within Format?
Fresh is projected to account for a 32.0% share of the format segment in 2026, enabled by short-hold counter piping that protects shell crispness.
On-demand shell piping close to the moment of purchase prevents moisture in the ricotta cream from softening the fried pastry shell and dulling its crisp bite. While blast-frozen kits and frozen bakery shipments widen geographic reach, artisan counters and hotel patisseries still command higher per-unit prices by piping thawed ricotta into crisp shells on site.
- Fresh is projected to account for a 32.0% share of the format segment in 2026 supported by immediate-consumption counter service across specialty bakeries and restaurants.
- Golden Cannoli's commercial foodservice specifications in 2025 instruct operators to ship traditional ricotta pastry bags frozen and thaw under refrigeration prior to on-site shell piping [5].
Why are Multipacks the leading Packaging Format?
Multipack is predicted to record a 29.0% share of the packaging format segment in 2026, associated with household sharing and protective clamshell cavity design.
Rigid two-count and four-count PET clamshells allow grocery bakeries to raise average transaction values while isolating individual pastry tubes inside molded cavities that prevent crushing. Single-serve wraps target convenience forecourts and bulk foodservice cases serve banquet caterers, whereas retail multipacks capture weekend dinner-party demand near yule logs and festive bakery platters.
- Multipack is predicted to record a 29.0% share of the packaging format segment in 2026 linked to portioned family packs that minimize shell-to-shell abrasion.
- Sara Lee Frozen Bakery extended its retail Sweet Moments single-serve dessert program in September 2026 to capture portioned everyday indulgence demand [6].
What makes Supermarkets & hypermarkets the largest Sales Channel?
Supermarkets & hypermarkets are anticipated to hold a 29.0% share of the sales channel segment in 2026, reinforced by refrigerated perimeter bakery merchandising.
Supermarket perimeter bakeries combine high weekly footfall with multi-deck refrigerated cases that display filled cannoli beside specialty cakes and fruit tarts. Digital B2B portals and wholesale distributors complement grocery chains by supplying independent cafes with shelf-stable shells and frozen cream bags.
- Supermarkets & hypermarkets are anticipated to hold a 29.0% share of the sales channel segment in 2026 stemming from recurring household grocery trips and visible chilled merchandising.
- LaRosa's Wholesale Bakery launched a dedicated direct-to-trade online wholesale ordering portal in June 2025 to ship cannoli and Italian cookies nationwide to independent grocers and foodservice accounts [7].
What are the drivers, restraints, and opportunities in the cannoli market?
In the cannoli market, retail and hospitality demand for portioned Italian pastries drives volume expansion whereas shell moisture migration restrains shelf life and prefilled chocolate-lined formats open up labor-saving grocery distribution.
- Driver: Rising foodservice dining and supermarket perimeter bakery upgrades convert traditional Sicilian cannoli into year-round portioned dessert SKUs.
- Restraint: Moisture moving from ricotta cream into fried dough softens shells within hours unless inner chocolate coatings and cold storage are maintained.
- Opportunity: Factory-prefilled refrigerated cannoli and thaw-and-pipe component kits allow labor-constrained grocery chains to stock authentic Italian pastries without skilled decorators.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Supermarket in-store bakeries and full-service restaurant groups are expanding portioned European pastry menus to lift dessert attachment rates without adding scratch-baking ovens. Cannoli provide a high-margin plated or clamshell item because the blistered shell and visible pistachio or chocolate-chip garnish signal craft preparation at the counter. Future Market Insights notes that operators pairing Italian pastries with broader bakery products capture both impulse single-serve buyers and planned weekend entertaining baskets. Dessert Holdings maintains an expanded multi-brand retail and foodservice dessert platform targeting grocers upgrading refrigerated bakery cases [8]. Foodservice distributors that bundle pre-fried shells with pre-sweetened impastata ricotta bags allow multi-unit restaurant chains to standardize portion cost and visual presentation across locations.
Risk Assessment of the Cannoli Market: Operational and Formulation Friction
Moisture seeping from sweet ricotta cream into crisp fried pastry shells remains the main hurdle limiting packaged cannoli distribution. When unlined shells are filled more than six hours before sale, liquid from the dairy cream softens the pastry crust and leads to store waste. In March 2025, the U.S. Food and Drug Administration updated Edition 5 of its final Food Allergen Labeling Guidance covering milk and wheat as well as tree nut and sesame declarations across retail bakery packs [9]. Dairy fillings also require uninterrupted refrigeration below 5 degrees Celsius and strict cross-contact sanitation for pistachio and hazelnut garnishes. Retailers comparing short-coded fresh cannoli against longer-life pound and loaf cakes frequently restrict fresh cannoli listings to high-turnover urban stores.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Pastry manufacturers that keep shells crisp without store-level hand filling are winning regional supermarket and convenience-store accounts that lack decorator staff. A thin inner layer of chocolate or cocoa butter inside fried cannoli shells blocks dairy moisture from soaking into the pastry during chilled shipping. Suppliers also prepare thicker mascarpone and ricotta blends that hold their texture in freezer-to-thaw retail cases. In February 2025, Rich Products published its 2025 Foodservice and In-Store Bakery Trends report identifying labor-saving thaw-and-serve pastries and portioned mini indulgences as top procurement priorities for grocery bakery buyers [10]. Seven-day chilled crunch retention in two-piece clamshells enables specialist bakers to transition cannoli from service-counter deli trays into self-serve refrigerated grab-and-go doors.
Cannoli Market by Country (2026 to 2036)
Future Market Insights projects the UAE to pace national cannoli expansion at a 12.4% CAGR through 2036, while Japan advances at a 10.1% CAGR across specialty hotel and convenience channels. Commercial realization of these national growth rates depends on refrigerated delivery density and how quickly grocery and restaurant kitchens replace manual pastry piping.
Table 7: Country CAGR and Primary Growth Levers for the Cannoli Market (CAGR percentage and operational drivers), 2026 to 2036
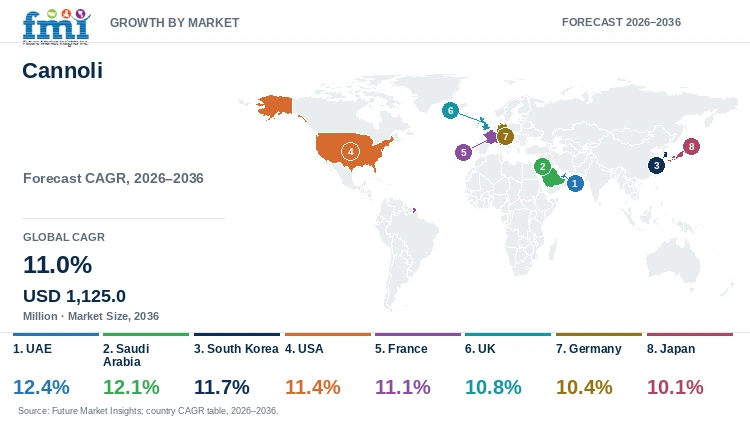
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 12.4% | International hotel patisserie buffets and premium chilled cafe dessert programs |
| Saudi Arabia | 12.1% | Destination hospitality expansion and central-kitchen frozen pastry distribution |
| South Korea | 11.7% | Mobile gourmet dessert gifting and cold-chain cafe bakery fulfillment |
| USA | 11.4% | Supermarket perimeter refrigerated bakery cases and prefilled retail clamshells |
| France | 11.1% | Hotel and restaurant Italian dining menus with specialty patisserie counters |
| UK | 10.8% | In-store bakery labor-saving prefilled formats and PPDS allergen-compliant packs |
| Germany | 10.4% | Cost-controlled separate shell-and-cream foodservice kits reducing restaurant waste |
| Japan | 10.1% | Inbound hotel cafe sampling and precision-portioned mini ricotta pastry formats |
Source: Future Market Insights analysis
UAE Cannoli Market Outlook (2026 to 2036)
The UAE cannoli market is projected to register a 12.4% CAGR between 2026 and 2036, representing the fastest expansion among covered countries. Unlike Western grocery-led markets where take-home clamshells dominate volume, demand in the UAE is anchored by five-star hotel banquet kitchens and mall patisserie counters serving international travelers. Dubai Department of Economy and Tourism figures released in January 2026 show that Dubai welcomed a record 19.59 million international overnight visitors in 2025, expanding the daily hospitality dining pool for plated Mediterranean pastries [11]. High ambient temperatures and air-freighted dairy costs nonetheless require distributors to supply blast-frozen ricotta piping bags and moisture-lined shells that survive central commissary transport across Dubai and Abu Dhabi.
Key takeaway: In the UAE, record international hotel occupancy and premium cafe dining are projected to drive foodservice procurement of frozen cannoli shells and stabilized ricotta fillings.
Saudi Arabia Cannoli Market Outlook (2026 to 2036)
Mega-project hotel openings and casual-dining franchise rollouts across Riyadh and Jeddah distinguish Saudi Arabia from mature European bakery markets by creating greenfield foodservice accounts for imported Italian desserts. Commercial cannoli demand in Saudi Arabia is forecast to expand at a 12.1% CAGR from 2026 to 2036 across hospitality caterers and gourmet supermarket bakeries. In June 2026, the Saudi Ministry of Tourism reported a record 123 million domestic and inbound tourists generating SAR 304 billion in 2025 tourism expenditure, supporting new restaurant and cafe menu investments [12]. Mandatory Arabic ingredient labeling and halal dairy certification across long-haul refrigerated desert freight routes compel importers to qualify extended-shelf-life frozen component kits.
Key takeaway: In Saudi Arabia, hospitality sector investment and central-kitchen catering contracts are forecast to accelerate imports of halal-certified frozen cannoli components.
South Korea Cannoli Market Outlook (2026 to 2036)
What sets South Korea apart from traditional Italian diaspora markets is the rapid commercialization of European pastries through mobile gifting platforms and specialty espresso chains. The USDA Foreign Agricultural Service reported in October 2026 that South Korea imported USD 47,000 million in agricultural and food products while omnichannel and dawn-delivery e-commerce expanded nationwide reach for imported bakery items [13]. The South Korea cannoli market is estimated to grow at an 11.7% CAGR over the 2026 to 2036 forecast period through cafe counters and chilled courier apps. Because parcel condensation softens uncoated pastry shells during overnight delivery, local bakers formulate internal white-chocolate moisture barriers and compact snacking tubes.
Key takeaway: In South Korea, dawn-delivery food e-commerce and specialty coffee chains are estimated to propel demand for moisture-sealed mini cannoli multipacks.
USA Cannoli Market Outlook (2026 to 2036)
In the USA, large-format supermarket in-store bakeries and East Coast wholesale commissaries form the primary commercial backbone, contrasting sharply with hospitality-led Gulf markets. Regional grocery chains merchandise two-count and four-count refrigerated cannoli clamshells beside specialty cakes to capture weekend family dessert purchases, while independent pizzerias buy bulk shells and frozen impastata cream bags. In June 2025, fifth-generation Italian baker LaRosa's Wholesale Bakery launched nationwide free-shipping wholesale distribution to supply independent grocers and foodservice operators that fall below broadline distributor minimums [14]. Supported by prefilled retail formats that eliminate store decorator labor, the USA cannoli market is anticipated to advance at an 11.4% CAGR through 2036.
Key takeaway: In the USA, supermarket perimeter bakery conversion toward prefilled chilled clamshells is anticipated to sustain high-volume retail expansion.
France Cannoli Market Outlook (2026 to 2036)
The France cannoli market is predicted to record an 11.1% CAGR between 2026 and 2036 across trattoria restaurant chains, hotel dining rooms, and Italian specialty delicatessens. Unlike grocery aisles in North America where prefilled clamshells lead, buyers in France evaluate cannoli against domestic choux and tart patisserie standards that demand freshly piped filling and artisanal shell blister texture. INSEE hospitality data published in February 2026 show that collective tourist overnight stays in France rose by 2.2% year-on-year in the fourth quarter of 2025, expanding commercial restaurant dessert covers [15]. Intense shelf competition from domestic butter pastries nonetheless restricts supermarket space, pushing Italian suppliers to target commercial catering distributors and Sicilian street-food concepts.
Key takeaway: In France, expanding Italian restaurant chains and tourist hotel dining are predicted to anchor foodservice demand for artisan cannoli shells and sheep-milk ricotta fillings.
UK Cannoli Market Outlook (2026 to 2036)
Severe kitchen staffing pressures and statutory prepacked-for-direct-sale allergen rules shape procurement in the UK, making labor-free thaw-and-serve formats far more critical than in southern Europe. The UK cannoli market is slated to expand at a 10.8% CAGR from 2026 to 2036 across supermarket dine-in meal deals and casual-dining trattoria groups. According to the July 2026 Defra Food Statistics Pocketbook, consumer expenditure on food and drink in the UK reached GBP 303.3 billion in 2025 across 4.1 million agri-food employees, sustaining premium grocery meal-deal dessert demand [16]. Suppliers therefore win grocery listings by delivering chocolate-lined prefilled cannoli in barcoded twin-packs with full ingredient and emphasized nut and dairy allergen declarations.
Key takeaway: In the UK, foodservice wage inflation and strict allergen labeling rules are slated to favor factory-prefilled retail cannoli packs.
Germany Cannoli Market Outlook (2026 to 2036)
Real-term contraction across commercial restaurant dining in Germany forces foodservice buyers to prioritize zero-waste component systems over short-life prefilled chilled pastries. Federal Statistical Office (Destatis) figures released in February 2026 show that hospitality turnover in Germany declined by 2.1% in real terms in 2025, heightening operator sensitivity to unsold chilled dessert shrink [17]. Demand in the Germany cannoli market is expected to progress at a 10.4% CAGR over the 2026 to 2036 period through Italian ice-cream parlors, system-catering buffets, and discount grocery Italian-week promotions. Wholesale distributors succeed by pairing ambient-stable blistered shells with portion-controlled frozen mascarpone-ricotta cartridges that kitchen staff thaw per order.
Key takeaway: In Germany, restaurant margin discipline and waste-reduction targets are expected to drive demand for separate ambient shells and portioned frozen cream bags.
Japan Cannoli Market Outlook (2026 to 2036)
Department-store basement food halls and convenience-store chilled dessert counters govern pastry distribution in Japan, requiring smaller portion weights and lower sugar intensity than Western benchmarks. Japan National Tourism Organization statistics released in September 2026 recorded 38.96 million international visitor arrivals in 2025 and 25.87 million through August 2026, broadening hotel and cafe exposure to European pastries [18]. Stringent retail date-code tolerances and humid summer distribution require internal cocoa-butter shell coatings that prevent moisture softening during convenience-store display. Supported by bite-sized mini formats and specialty coffee pairings, the Japan cannoli market is forecast to register a 10.1% CAGR through 2036.
Key takeaway: In Japan, precision portioning and inbound hotel cafe traffic are forecast to support steady adoption of moisture-protected mini cannoli.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the cannoli market?
Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Mademoiselle Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess Brands, Bauli, and Dr. Oetker are the notable companies covered in this market.
Supplier competition across the cannoli market covers frozen foodservice bakery platforms, branded retail sweet-goods manufacturers, and European patisserie specialists in addition to dedicated Italian pastry makers such as Golden Cannoli and LaRosa's Wholesale Bakery. Frozen bakery platforms supply thaw-and-serve desserts and bakery components to supermarket in-store counters, whereas branded snack-cake groups control ambient and chilled grocery shelf space. Because broad dessert corporations do not publicly break out standalone cannoli SKU revenues, procurement teams evaluate suppliers on cold-chain distribution reach and internal shell lipid-coating capability.
- Frozen Foodservice and In-Store Bakery Platforms: Rich Products and Sara Lee Frozen Bakery along with Dessert Holdings and Mademoiselle Desserts operate temperature-controlled bakery manufacturing and retail perimeter supply networks.
- Branded Retail Bakery and Portioned Snack Groups: Finsbury Food Group and Premier Foods as well as McKee Foods and Hostess Brands manage high-velocity supermarket multipack merchandising and portioned sweet-treat distribution.
- Continental Italian and European Sweet-Bakery Specialists: Bauli and Dr. Oetker maintain established Italian pastry heritage, dessert fillings, and decorative inclusion capabilities across European and international retail channels.
Competitive Benchmarking: Cannoli Market
Table 8: Competitive Benchmarking for the Cannoli Market (qualitative capability ratings), 2026
| Company | Cannoli SKU Proof | Frozen / Chilled Dessert Handling | Bakery Channel Access | Geographic Reach |
|---|---|---|---|---|
| Rich Products | Unscored | High | High | United States and international foodservice bakery markets |
| Sara Lee Frozen Bakery | Unscored | High | Medium | United States foodservice and supermarket in-store bakeries |
| Dessert Holdings | Unscored | High | Medium | North America retail perimeter and foodservice chains |
| Mademoiselle Desserts | Unscored | High | High | United Kingdom, France, Netherlands, and export foodservice |
| Finsbury Food Group | Unscored | Medium | High | United Kingdom and European retail bakery channels |
| Premier Foods | Unscored | Unscored | High | United Kingdom grocery and international branded sweet treats |
| McKee Foods | Unscored | Unscored | High | United States supermarket and convenience snack aisles |
| Hostess Brands | Unscored | Unscored | High | North America retail multipack and convenience channels |
| Bauli | Unscored | Medium | High | Italy and over 70 international packaged bakery markets |
| Dr. Oetker | Unscored | Medium | Medium | Europe and international retail dessert and bakery inclusions |
Scoring basis: Cannoli SKU Proof evaluates publicly verified standalone cannoli pastry commercialization among the ten corporate platforms (while specialist benchmarks Golden Cannoli and LaRosa's Wholesale Bakery provide direct SKU proof in the text). Frozen / Chilled Dessert Handling rates temperature-controlled dairy and pastry logistics, and Bakery Channel Access reflects verified supermarket in-store bakery and foodservice distributor contracts.
Key Developments in the Cannoli Market
- Golden Cannoli scaled its SQF-certified Original Cannoli Chips and retail-ready cannoli snack line in 2026 in 5.1-ounce resealable gusseted bags to capture supermarket dipped-snack and dessert-board demand [19].
- Mademoiselle Desserts completed its integration into the Emmi Group premium dairy and patisserie platform in May 2026, combining European frozen pastry manufacturing with Swiss dairy filling expertise across retail and foodservice channels [20].
- Rich Products published its Responsible Business Report in April 2026 detailing supply-chain traceability and in-store bakery customer qualification programs across global foodservice and retail accounts [21].
Key Players in the Cannoli Market
Frozen Dessert and Foodservice Bakery Platforms
- Rich Products
- Sara Lee Frozen Bakery
- Dessert Holdings
- Mademoiselle Desserts
Branded Retail Bakery and Packaged Snacks
- Finsbury Food Group
- Premier Foods
- McKee Foods
- Hostess Brands
Continental Sweet Bakery and Dessert Categories
- Bauli
- Dr. Oetker
Cannoli Market - Report Scope
Table 9: Report Scope for the Cannoli Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Claim / Nature; Format; Packaging Format; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Commercial wholesale and retail supplier value from genuine cannoli pastries and qualifying fresh, chilled, frozen, and component-kit cannoli products. Excludes ordinary bread loaves, cake slices, cookies, cannoli-flavored ice cream, and unattributed bulk ricotta sold for non-cannoli culinary uses. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, Saudi Arabia, South Korea, USA, France, UK, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Mademoiselle Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess Brands, Bauli, Dr. Oetker |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Cannoli Market - Research Methodology
Table 10: Research Methodology for the Cannoli Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with supermarket in-store bakery buyers, Italian pastry commissary directors, foodservice dessert distributors, and cold-chain packaging technologists to validate shell moisture-barrier performance, thaw-and-pipe labor hours, and per-case pricing. |
| Secondary Research | Analysis of USDA Economic Research Service food-away-from-home expenditure data, UK ONS hospitality labor surveys, Destatis restaurant turnover releases, FDA Edition 5 allergen guidance, and corporate bakery filings. |
| Market Sizing and Forecasting | Top-down supermarket perimeter bakery and Italian foodservice dessert budgets reconciled against bottom-up wholesale cannoli shell case shipments, ricotta pastry-bag volumes, and two-count retail clamshell velocity from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight commercial restaurant and hotel dining growth, retail refrigerated bakery door density, labor cost inflation, and imported dairy-and-pastry compliance across eight covered countries. |
| Operational Benchmark Traceability | Portion-volume and bakery-outlet spending indicators in Tables 2, 3, and 4 trace to USDA ERS foodservice expenditure series, UK FSA allergen compliance records, and commercial cannoli wholesale catalog specifications. |
| Data Triangulation and Validation | Demand estimates are cross-checked against specialist cannoli manufacturer capacities and supermarket bakery display allocations while excluding unrelated loaf cakes, sweet biscuits, and standalone dairy tub sales. |
Cannoli Market by Segments
Cannoli Market segmented by Product Type:
- Classic / original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
Cannoli Market segmented by Claim / Nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
Cannoli Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
Cannoli Market segmented by Packaging Format:
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
Cannoli Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Cannoli Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] UK Office for National Statistics. (2025, August 21). Business insights and impact on the UK economy: 21 August 2025. Office for National Statistics Statistical Bulletin.
- [2] USDA Economic Research Service. (2026, June 11). Total U.S. food spending reached USD 2.51 trillion in 2025 with food away from home at 56.3 percent. United States Department of Agriculture.
- [3] Publix Super Markets, Inc. (2026, June 16). New bakery treat has a pop of color and a satisfying crunch across Publix in-store bakeries. Publix Corporate Newsroom.
- [4] UK Food Standards Agency. (2025, February 24). Allergen Information for Non-Prepacked Foods Best Practice Guidance for Food Businesses. Food Standards Agency GOV.UK.
- [5] Golden Cannoli Shells Co., Inc. (2025, May 14). Wholesale Cannoli Shells and Traditional Ricotta Pastry Cream Handling Specifications. Golden Cannoli Commercial Catalog.
- [6] Sara Lee Frozen Bakery. (2026, September 8). Retail Program: Sara Lee Single-Serve and Multi-Serve Desserts. Sara Lee Frozen Bakery.
- [7] LaRosa's Wholesale Bakery. (2025, June 12). LaRosa's Famous Cannoli and Cookies Launches New Wholesale Website to Serve Nationwide Customers. Specialty Food Association.
- [8] Dessert Holdings US Co. (2025). Our Brands: Seven Dessert Brands Serving Retail and Foodservice Channels. Dessert Holdings US Co.
- [9] U.S. Food and Drug Administration. (2025, March 26). Frequently Asked Questions: Food Allergen Labeling Guidance for Industry Edition 5. U.S. Department of Health and Human Services.
- [10] Rich Products Corporation. (2025, February 5). Rich Products Reveals Top Foodservice and In-Store Bakery Trends for Commercial Operators. Rich Products Insights.
- [11] Dubai Department of Economy and Tourism. (2026, January 7). Tourism Performance Report January to December 2025: Dubai Welcomes 19.59 Million Overnight Visitors. Government of Dubai.
- [12] Saudi Ministry of Tourism. (2026, June 18). Ministry of Tourism Releases 2025 Annual Statistical Report Announcing Record SAR 304 Billion in Total Tourism Spending. Saudi Press Agency.
- [13] USDA Foreign Agricultural Service. (2026, October 5). South Korea Retail Foods Annual: E-Commerce and Omnichannel Retailing Expand Imported Bakery Opportunities. United States Department of Agriculture GAIN Report.
- [14] Perishable News Bakery & Deli. (2025, June 12). LaRosa's Famous Cannoli and Cookies Scales Nationwide Direct Wholesale Distribution for Grocers and Foodservice. Perishable News Trade Report.
- [15] Institut national de la statistique et des études économiques. (2026, February 19). In Q4 2025, collective tourist attendance except in campsites increased by 2.2 percent over a year. INSEE Informations Rapides.
- [16] UK Department for Environment, Food & Rural Affairs. (2026, July 29). Food Statistics in Your Pocket: UK Consumer Food and Drink Expenditure Reaches GBP 303.3 Billion. Defra National Statistics GOV.UK.
- [17] Statistisches Bundesamt (Destatis). (2026, February 19). Gastgewerbeumsatz 2025 real 2,1 Prozent niedriger als im Vorjahr. Destatis Press Release No. 054.
- [18] Japan National Tourism Organization. (2026, September 16). 2026 Visitor Arrivals to Japan and Overseas Travelers Statistical Report. Japan National Tourism Organization Official Release.
- [19] Golden Cannoli Shells Company. (2026, June 10). The Original Cannoli Chips and SQF-Certified Packaged Cannoli Retail Line. Golden Cannoli Product Portfolio.
- [20] Mademoiselle Desserts Group. (2026, May 15). Joining Forces with Emmi Group to Expand European Premium Patisserie and Frozen Dessert Reach. Mademoiselle Desserts Corporate Journal.
- [21] Rich Products Corporation. (2026, April 20). Rich Products Launches First Responsible Business Report Reflecting Values-Driven Bakery Growth. Rich Products Corporate Release.
- [22] Finsbury Food Group. (2025, July 16). Finsbury Food Group and Nadiya Hussain Launch New Branded Retail Bakery Range Across UK Supermarkets. Finsbury Food Group Release.
- [23] McKee Foods Corporation. (2026, June 3). Little Debbie Mocha Swiss Rolls. Little Debbie.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cannoli market in 2026 and what is forecast for 2036?
- Which retail bakery labor and foodservice pressures support demand for cannoli?
- Why does Classic / original lead the Product Type category?
- Why does Conventional command the largest share in Claim / Nature?
- How do growth rates differ across the UAE and Saudi Arabia as well as South Korea and the USA?
- Which leading companies supply relevant frozen dessert, bakery, or cannoli lines today?
- What moisture-migration and allergen factors restrict cannoli shelf life and distribution?
- What should supermarket and foodservice buyers test before qualifying a cannoli supplier?
Frequently Asked Questions
How big is the cannoli market in 2026, and what is forecast for 2036?
Global cannoli demand reaches an estimated USD 396.2 million in 2026 from USD 356.9 million in 2025. Category valuation is projected to hit USD 1,125.0 million by 2036 as supermarkets and restaurant groups adopt prefilled and thaw-and-pipe pastry formats.
What is the CAGR for the cannoli market from 2026 to 2036?
Future Market Insights calculates an 11.0% compound annual growth rate between 2026 and 2036, adding USD 728.8 million in new industry value across retail perimeter bakeries and foodservice channels.
Which product type segment leads the cannoli market?
Classic / original is expected to hold a 40.0% share of the product type segment in 2026 because blistered fried pastry tubes filled with sweet ricotta establish the benchmark flavor and texture profile for shoppers.
Which claim / nature segment leads the cannoli market?
Conventional is estimated to hold a 59.0% share of the claim / nature segment in 2026 as traditional wheat-flour shells and dairy fillings provide consistent frying blister formation and predictable ingredient costs.
Which country has the fastest growth outlook during the assessment period?
The UAE is projected to lead national growth at a 12.4% CAGR through 2036, followed by Saudi Arabia at 12.1%, supported by international hotel patisserie counters and premium cafe dining.
Who are the key players in the cannoli market?
Rich Products, Sara Lee Frozen Bakery, Dessert Holdings, Mademoiselle Desserts, Finsbury Food Group, Premier Foods, McKee Foods, Hostess Brands, Bauli, and Dr. Oetker represent the leading bakery and dessert platforms in addition to specialist producers Golden Cannoli and LaRosa's Wholesale Bakery.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic / original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Rich Products
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sara Lee Frozen Bakery
- Dessert Holdings
- Mademoiselle Desserts
- Finsbury Food Group
- Premier Foods
- McKee Foods
- Hostess Brands
- Bauli
- Dr. Oetker
- Rich Products
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


