

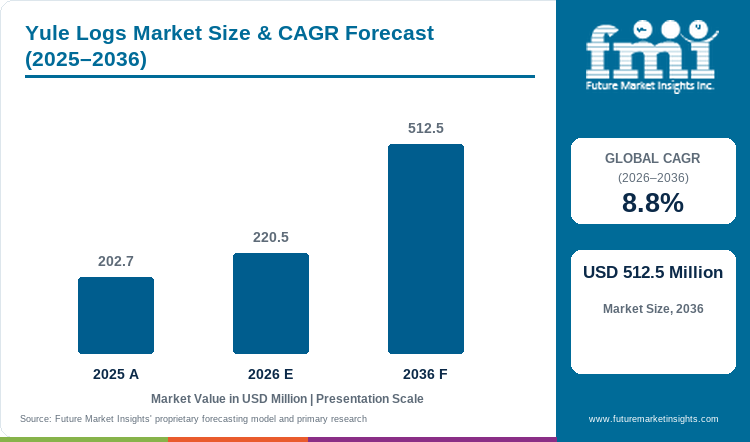
- Market Size (2026)
- USD 220.5 Mn
- Forecast (2036)
- USD 512.5 Mn
- CAGR (2026 to 2036)
- 8.8%
How big is the Yule Logs Market in 2026?
USD 220.5 Million in 2026, rising to USD 512.5 Million by 2036 at an 8.8% CAGR.
The Yule Logs Market was valued at USD 202.7 Million in 2025. Growth rests on a seasonal product with a defined purchase occasion rather than on the creation of a new dessert habit. France's Ministry of Agriculture described the bûche de Noël in November 2021 as a fixture of year-end celebrations. That cultural anchor supports planned listings by grocery category teams and preorder programs by bakeries. Revenue expands when suppliers translate the traditional rolled sponge into premium mousse-based logs, frozen thaw-and-serve formats, and smaller portions that fit more price points. Manufacturers also gain when one production platform can serve retail, in-store bakery, and foodservice accounts. The commercial test is execution during a narrow demand peak. Retailers will allocate space to suppliers that confirm festive availability, protect presentation in transit, and offer pack sizes that limit markdown exposure.
A seasonal programme is decided long before the peak. Grocery category teams lock listings and planogram space in the summer, so a supplier earns its place by confirming volumes, delivery windows and presentation standards early. Hospitality buyers work to the same calendar through festive menus and banquet dessert lists. The price ladder that works in practice runs from supermarket multipacks through in-store bakery centrepieces to premium patisserie logs for gifting and hotel service. Suppliers able to serve two or three of those tiers from one production platform carry the lowest seasonal risk.
Key Takeaways
- The market is valued at USD 220.5 Million in 2026 and is forecast to reach USD 512.5 Million by 2036 at an 8.8% CAGR.
- Classic / original accounts for 34.0% of Product Type demand in 2026.
- Conventional accounts for 55.0% of Claim / Nature demand in 2026.
- Fresh accounts for 32.0% of Format demand in 2026.
- Growth rates rise fastest where hospitality, digital ordering, or premium bakery capacity deepen access. UAE at 10.2% and Saudi Arabia at 9.8% reflect hospitality-led channel expansion.
- Competition spans frozen dessert specialists, diversified bakery platforms, and branded cake owners. Mademoiselle Desserts, Dessert Holdings, Bindi Dessert, and Sara Lee Frozen Bakery compete through premium frozen dessert execution.
Analyst Perspective
Commercial performance will depend on precision across the full seasonal operating cycle. Buyers will reward shorter lead-time commitments and stable cold-chain service. Modular decoration and portion formats can support localization without excessive SKU complexity. Preorders and retailer sell-through data should guide production before the peak.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the yule logs market segmented?
The market is segmented by Product Type, Claim / Nature, Format, Packaging Format, Sales Channel, and Region.
Product Type distinguishes traditional recognition from recipe and occasion innovation. Claim / Nature captures the trade-off between broad affordability and differentiated dietary positioning. Format describes when the product is finished, stored, and presented. Packaging Format controls serving size and inventory exposure. Sales Channel separates high-volume retail discovery from specialist bakery service and digital preorder, and it also captures convenience and distributor-led foodservice access. Each axis changes the buyer's operating model. A fresh artisan log can command theater but has a short selling life. A frozen multipack can travel farther and be released closer to demand. Clean-label or gluten-free variants can widen eligibility, though they also require credible formulation and clear labeling. Leadership therefore reflects category recognition, production scale, and retail execution rather than one common driver.
What makes Classic / original central to the Product Type category?
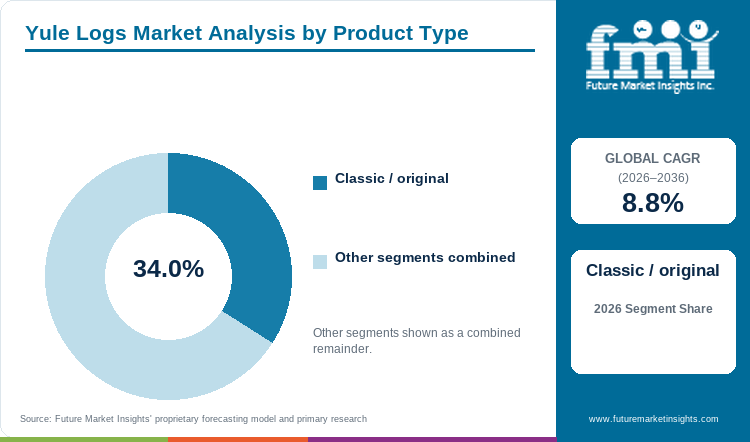
Classic / original products give shoppers the fastest visual and flavour cue that an item belongs to the Yule log occasion. The rolled sponge and cream filling run on established bakery equipment, and chocolate coating with bark-style decoration fits familiar finishing workflows. Producers can vary fillings, coatings and decoration without rebuilding the base process.
- Classic / original holds 34.0% of the Product Type category in 2026 because it combines immediate seasonal recognition with repeatable production.
- France's Ministry of Agriculture stated in November 2021 that the modern pastry commonly uses a rolled sponge with vanilla or hazelnut. Chocolate and more exotic flavors are also used.
Why does Conventional lead the Claim / Nature category?
Conventional recipes support the broadest price ladder because they can use established cake and cream systems, and coating and decoration supply is widely available. Retailers can place them in mainstream seasonal sets without asking shoppers to understand a specialist claim. Claim-led variants stay narrower, because clean-label and better-for-you positions depend on ingredient work of the kind tracked in the wider enzyme-active soy flour market, where functional ingredients have to hold performance alongside the claim.
- Conventional holds 55.0% of the Claim / Nature category in 2026 because it serves the widest retailer specification and consumer price range.
- Volume-price promotion restrictions for products high in fat, sugar or salt took effect in England on 1 October 2025, which makes recipe and claim positioning a planning variable for retailers building seasonal displays.
How does Fresh retain the lead in the Format category?
Fresh Yule logs deliver immediate sensory cues through soft sponge and moist fillings, and glossy finishes with hand-applied decoration strengthen the effect. Those qualities support in-store bakery theatre and artisan differentiation, and they let buyers protect margin through local collection windows and preorders. Frozen and chilled formats follow the same thaw-and-serve pattern already established in the wider fruit and savory turnovers market, which lets production move earlier in the season while service stays local.
- Fresh holds 32.0% of the Format category in 2026 because sensory quality and visible craftsmanship carry unusual weight in a festive centerpiece.
- France.fr reported in December 2024 that pastry chefs continue to reinvent the Yule log each festive season, which reinforces demand for fresh visual differentiation.
Why does Multipack lead demand within the Packaging Format category?
Multipacks balance household sharing with portion control. They let retailers offer several smaller pieces at one price point and reduce the commitment attached to a full centrepiece. Variety packs and mixed flavours fit the same trays and cartons while decoration changes. Packaging carries more weight here than in most bakery categories, because the item has to survive transport and hold its festive appearance on shelf, requirements close to those tracked in the wider food packaging market.
- Multipack holds 31.0% of the Packaging Format category in 2026 because it combines shareability with manageable portions and retail-friendly price points.
- Premier Foods reported in May 2026 that Mr Kipling cake bites tubs supported strong Sweet Treats innovation, illustrating the appeal of portionable share-pack formats.
What drives Supermarkets & hypermarkets in the Sales Channel category?
Supermarkets & hypermarkets control the broadest seasonal discovery window because the product can sit inside the main grocery trip. These chains also coordinate festive planograms and in-store bakery counters, and they manage private-label tenders and online grocery listings as well. That creates volume but raises the service threshold. Suppliers must meet fixed delivery dates and packaging rules. They must also support promotional photography and store-level availability. Artisan & specialty bakeries compete through freshness and customization. Online & DTC channels improve preorders. Foodservice distributors reach hotels and restaurants. Supermarkets & hypermarkets lead because they combine audience scale with the ability to merchandise several price tiers in one location.
- Supermarkets & hypermarkets hold 43.0% of the Sales Channel category in 2026 because seasonal visibility and one-stop shopping concentrate consumer traffic.
- The German frozen food institute reported in April 2026 that frozen baked goods grew 3.9% in 2025, showing that cold-chain retail already carries bakery volume outside the fresh counter.
What are the drivers, restraints, and opportunities in the yule logs market?
Premium year-end celebration demand supports planned listings, while the short selling window raises waste risk and frozen or preorder models improve control.
- Driver: Premium year-end celebration demand draws retailers and hospitality buyers into planned seasonal programs.
- Restraint: A short selling window magnifies forecast error, cold-chain cost, and markdown exposure.
- Opportunity: Frozen or mini formats paired with preorder data can extend reach while limiting waste.
The demand driver is a fixed social occasion with a clear centerpiece role. France's Ministry of Agriculture described the bûche de Noël in November 2021 as an essential year-end pastry. That recognition gives grocery buyers and specialist bakeries a reason to reserve seasonal space before final consumer orders are known. Premium finishes then lift the value of each listing. Hotels and restaurants use the same format to create a visible festive menu item without developing an entirely new dessert category. Spending rises when suppliers connect tradition with reliable production and a price ladder that covers family, gifting, and hospitality needs.
The main restraint appears between forecast approval and final sell-through. Production must often be committed before retailers know the exact shape of the holiday peak. Fresh products can lose value quickly if demand arrives late or shifts by store. Frozen products reduce that exposure but add cold storage and handling costs. FamilyMart reported in January 2020 that reservation-only Christmas cakes reduced wastage value by 50% and lifted franchise income by 30% year on year. The result shows that demand can exist while poor allocation still destroys margin. Buyers therefore scrutinize minimum order quantities, shelf life, and replenishment flexibility.
The most credible opportunity is an operating redesign. Frozen and par-baked products can move production earlier, mini formats can serve office sharing and impulse occasions, and preorders can convert digital interest into a production signal. Germany's frozen food institute reported in April 2026 that frozen baked goods increased 3.9% in 2025, which demonstrates channel acceptance for bakery products that separate production from final service. Adjacent bakery categories show the same pattern, with compact and shareable formats scaling in the pita bread market and the panko breadcrumbs market, where everyday volume carries the format between seasonal peaks.
Which country CAGRs are profiled in the yule logs market?
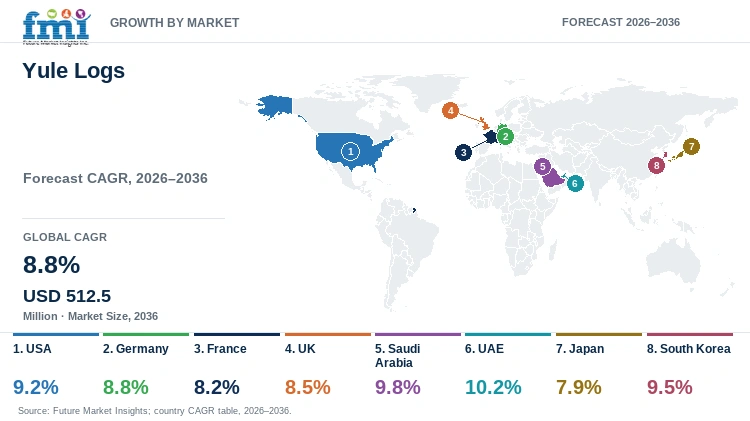
| Country | CAGR |
|---|---|
| USA | 9.2% |
| Germany | 8.8% |
| France | 8.2% |
| UK | 8.5% |
| Saudi Arabia | 9.8% |
| UAE | 10.2% |
| Japan | 7.9% |
| South Korea | 9.5% |
How do country-level CAGRs compare in the yule logs market?
The eight profiled countries span a 2.3 percentage-point range. UAE leads at 10.2%, followed by Saudi Arabia at 9.8% and South Korea at 9.5%. USA forms the upper middle at 9.2%, while Germany follows at 8.8%. UK at 8.5%, France at 8.2%, and Japan at 7.9% form an established-market band. The top group benefits from expanding hospitality or digital access. The lower band faces mature cake choices and stronger differentiation requirements. These rates describe forecast pace. They do not establish the absolute size of any national market.
- UAE is 0.4 percentage points ahead of Saudi Arabia. The gap favors earlier investment in hotel accounts and local premium-grocery warehousing in the UAE.
- Saudi Arabia is 0.3 percentage points ahead of South Korea. Gulf growth depends more on hospitality distribution, while Korean growth rewards mobile preorder and rapid product refresh.
- South Korea is 0.3 percentage points ahead of USA. Similar growth pace masks different routes to market because Korean buyers emphasize digital discovery and US buyers emphasize grocery scale.
- USA is 0.4 percentage points ahead of Germany. Germany and UK are followed by France and Japan in 0.3-point steps. This pattern raises the value of localization over broad capacity expansion.
CAGR should be weighed against the number of addressable accounts and seasonal basket size. Channel margins, import requirements, and service complexity also affect opportunity. A slower market with established grocery or bakery infrastructure can still produce more near-term revenue than a faster market with a narrower buyer base. The full outlook therefore evaluates country growth alongside channel structure and product fit. It also considers regulatory friction and supplier economics across more than thirty countries.
Country-wise Analysis
- USA: National grocery chains, frozen dessert distributors and foodservice programmes set the buying pattern. US demand is forecast at 9.2% CAGR over 2026 to 2036. In May 2026, Cal-Maine Foods completed its acquisition of the Van's Foods business assets from Sara Lee Frozen Bakery, and Sara Lee described the divestiture as sharpening focus on its core brands. Portfolio moves of that kind keep branded frozen bakery capacity under review. Listing costs and strict holiday service levels remain the practical barrier, so display-ready formats, regional cold-chain coverage and production plans tied to retailer forecasts decide who keeps the space.
- Germany: Frozen cakes and structured thaw-and-serve workflows are already familiar to grocery and foodservice buyers. German demand is forecast at 8.8% CAGR over 2026 to 2036. The German frozen food institute reported in April 2026 that frozen baked goods grew 3.9% during 2025 and that total frozen-food volume reached 4.238 million tonnes. A mature torte and bakery offer sets a high quality benchmark, while energy and freezer-space costs add pressure. Consistent slice quality, clear German labelling and formats that move efficiently from freezer to display are the working requirements.
- France: Artisan patisseries and specialist chains carry most Yule log buying, with supermarkets and restaurant menus widening access. French demand is forecast at 8.2% CAGR over 2026 to 2036. France.fr reported in December 2024 that pastry chefs continue to reinvent the log each festive season. That reinvention raises the bar on visual differentiation and keeps hand-finished quality relevant alongside scaled production.
- UK: Centralised seasonal ranges and large retail resets shape grocery planning. UK demand is forecast at 8.5% CAGR over 2026 to 2036. Volume-price restrictions for products high in fat, sugar or salt took effect in England on 1 October 2025, which changes how seasonal displays can be built and promoted. Suppliers need pack architecture and recipe positioning that work inside those rules while still supporting gifting and family sharing.
- Saudi Arabia: Hotels and premium grocers form the addressable core, with restaurant groups and distributors adding volume in the major cities. Saudi demand is forecast at 9.8% CAGR over 2026 to 2036. The General Authority for Statistics reported continued growth in tourism establishments for the fourth quarter of 2025. Hospitality-led demand puts weight on presentation, delivery reliability and import documentation.
- UAE: Hotel banquet programmes, premium food retail and foodservice distributors decide seasonal placement. UAE demand is forecast at 10.2% CAGR over 2026 to 2036. The Dubai Department of Economy and Tourism reported continued visitor growth for 2025, which supports festive dessert programming across hotels and destination dining. Tourism volume alone does not place a supplier, though, so buyers respond to confirmed availability, cold-chain discipline and formats built for high-turnover service.
- Japan: Department stores and convenience chains are the main routes, and reservation-led Christmas cake programmes remain important. Japanese demand is forecast at 7.9% CAGR over 2026 to 2036. FamilyMart reported in January 2020 that reservation-only Christmas cakes cut wastage value by 50% and lifted franchise income by 30% year on year. Preorder discipline therefore carries proven commercial weight in this market.
- South Korea: Department stores and cafe culture drive discovery, with social media and mobile commerce shaping the path to purchase. South Korean demand is forecast at 9.5% CAGR over 2026 to 2036. The Ministry of Data and Statistics reported growth in December 2025 online shopping. Rapid refresh and strong visual presentation matter more here than long shelf-life ranges.
Who are the notable companies in the yule logs market?
Mademoiselle Desserts, Dessert Holdings, Finsbury Food Group, Bindi Dessert, Rich Products, Sara Lee Frozen Bakery, Vandemoortele, Dr. Oetker, Bauli, and Premier Foods are the notable companies profiled in this market.
Competition is organized around three operating positions. Frozen dessert platforms focus on finished cakes that can move through retail and foodservice with controlled thawing. Broad bakery manufacturers use plant scale, in-store bakery relationships, and distributor networks to manage seasonal volume. Consumer cake brands use packaging, recognition, and grocery shelf access to capture planned household purchases. Mademoiselle Desserts and Dessert Holdings have strong premium dessert platforms. Bindi Dessert and Sara Lee Frozen Bakery add frozen-format depth. Finsbury Food Group, Rich Products, and Vandemoortele combine bakery manufacturing with channel coverage. Dr. Oetker, Bauli, and Premier Foods bring branded cake or festive sweet-bakery capabilities. The competitive test is not product availability alone. It is the ability to deliver a decorated seasonal item at the required time with low waste and consistent presentation.
- Frozen dessert platforms: Mademoiselle Desserts, Dessert Holdings, Bindi Dessert, and Sara Lee Frozen Bakery compete through premium finished formats and cold-chain execution.
- Broad bakery and foodservice manufacturers: Finsbury Food Group, Rich Products, and Vandemoortele compete through production scale, in-store bakery access, and distributor relationships.
- Packaged consumer cake brands: Dr. Oetker, Bauli, and Premier Foods compete through brand recognition, seasonal sweet-bakery portfolios, and retail shelf access.
Competitive Benchmarking: Yule Logs Market
| Company | Seasonal Cake and Log-Format Capability | Frozen / Thaw-and-Serve Execution | Retail and Foodservice Channel Access | Geographic Reach |
|---|---|---|---|---|
| Mademoiselle Desserts | High | High | High | France, UK, Belgium, and the Netherlands |
| Dessert Holdings | High | High | High | North America with selected international accounts |
| Finsbury Food Group | High | Medium | High | UK and Europe |
| Bindi Dessert | Medium | High | High | Europe, North America, and selected export markets |
| Rich Products | Medium | High | High | North America and international foodservice markets |
| Sara Lee Frozen Bakery | Medium | High | High | USA and Canada |
| Vandemoortele | Medium | High | High | Europe and North America |
| Dr. Oetker | Medium | High | High | More than 40 countries |
| Bauli | High | Medium | High | Europe with international retail distribution |
| Premier Foods | Medium | Unscored | High | UK, Australia, USA, and Canada |
Scoring basis: Seasonal Cake and Log-Format Capability measures documented production of celebration cakes, premium pâtisserie, or festive sweet bakery across multiple formats. Frozen / Thaw-and-Serve Execution measures documented frozen manufacturing, freezer-to-oven systems, or controlled thawing expertise. Retail and Foodservice Channel Access measures evidenced coverage across both customer types. High indicates broad documented capability, while Medium indicates credible but narrower coverage. Low is reserved for a documented limitation. Unavailable public information is shown as Unscored rather than treated as a weakness.
Key Developments in the Yule Logs Market
- In August 2026, Vandemoortele completed the final phase of its acquisition of New Jersey-based Banneton Bakery, extending its United States bakery manufacturing footprint. The move matters here because it adds frozen and thaw-and-serve capacity in a market that buys seasonal dessert formats through grocery and foodservice channels.
- In May 2026, Cal-Maine Foods completed its acquisition of the Van's Foods business assets from Sara Lee Frozen Bakery. Sara Lee described the divestiture as sharpening focus on its core brands, which leaves branded frozen bakery capacity under active review and keeps competitive positions in seasonal desserts moving.
- In October 2024, Emmi completed its acquisition of the Mademoiselle Desserts Group, adding premium patisserie capability across in-store bakery and foodservice channels in several European markets. The combination broadens the operating platform available for seasonal cake development and cross-border customer service.
Key Players in the Yule Logs Market
Frozen Dessert Platforms
- Mademoiselle Desserts
- Dessert Holdings
- Bindi Dessert
- Sara Lee Frozen Bakery
Broad Bakery and Foodservice Manufacturers
- Finsbury Food Group
- Rich Products
- Vandemoortele
Packaged Consumer Cake Brands
- Dr. Oetker
- Bauli
- Premier Foods
Yule Logs Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type, Claim / Nature, Format, Packaging Format, Sales Channel, and Region. |
| Quantitative Units | USD Million |
| Market Definition | Revenue from finished Yule log cakes and log-shaped seasonal bakery desserts at the manufacturer or brand-owner sale. Retail markup, restaurant menu value, upstream ingredients, separate decorations, ordinary roulades not marketed as Yule logs, and adjacent Christmas cakes or pastries are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, Germany, France, UK, Saudi Arabia, UAE, Japan, South Korea, and more than twenty-five additional countries in the full report. |
| Key Companies Profiled | Mademoiselle Desserts, Dessert Holdings, Finsbury Food Group, Bindi Dessert, Rich Products, Sara Lee Frozen Bakery, Vandemoortele, Dr. Oetker, Bauli, and Premier Foods. |
| Forecast Period | 2026 to 2036 |
| Approach | FMI applies a hybrid bottom-up and top-down sizing approach that triangulates manufacturer revenue, channel volumes, product pricing, and country-level demand indicators. |
Yule Logs Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI engages manufacturers, bakery distributors, retail category managers, foodservice buyers, and subject-matter experts to test product scope, channel economics, seasonality, pricing, purchase criteria, and forecast assumptions. |
| Desk Research | Official statistics, regulations, company filings, product documentation, trade information, and industry sources are reviewed. Only evidence relevant to the defined revenue boundary is used. |
| Market Sizing and Forecasting | Manufacturer revenue, product availability, channel mix, price positioning, seasonality, country demand signals, and macroeconomic assumptions are reconciled through bottom-up and top-down models. |
| Data Validation | Findings are cross-checked across independent source types. Duplicate revenue, unsupported claims, retail markup, restaurant menu value, and adjacent dessert categories are excluded. |
Yule Logs Market by Segments
Yule Logs Market segmented by Product Type:
- Classic / original
- Fruit- or cream-filled logs
- Specialty flavored logs
- Mini / individual logs
- Premium pâtisserie logs
Yule Logs Market segmented by Claim / Nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- Vegan / plant-based
Yule Logs Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Thaw-and-serve
Yule Logs Market segmented by Packaging Format:
- Multipack
- Single-serve
- Whole-log presentation box
- Bulk foodservice
Yule Logs Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Yule Logs Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- French Ministry of Agriculture and Food Sovereignty (2021, November 25). D'où vient la tradition de la bûche de Noël?
- France.fr (2024, December 4). Christmas Log in Paris.
- Deutsches Tiefkühlinstitut e. V. (2026, April 23). dti-Absatzstatistik 2025: Tiefkühlkost weiter auf Wachstumskurs.
- UK Department of Health and Social Care (2023, September 29). Restricting promotions of products high in fat, sugar or salt by location and by volume price: implementation guidance.
- General Authority for Statistics, Saudi Arabia (2026, April 12). Tourism Establishments Statistics - Q4 of 2025.
- Dubai Department of Economy and Tourism (2026, January 6). Tourism Performance Report January - December 2025.
- FamilyMart Co., Ltd. (2020, January 10). Financial Review for the Third Quarter of FY2019: Reservation-only Christmas cake results.
- Ministry of Data and Statistics, Republic of Korea (2026, February 2). Online Shopping in December 2025.
- Cal-Maine Foods, Inc. (2026, May 12). Cal-Maine Foods completes acquisition of Van's Foods business assets from Sara Lee Frozen Bakery.
- Emmi Group (2024, October 4). Emmi completes acquisition of the Mademoiselle Desserts Group.
- Dessert Holdings (2024, May 15). Dessert Holdings acquires Kenny's Great Pies.
- Vandemoortele (2026, August 3). Vandemoortele USA completes final phase of acquisition of New Jersey-based Banneton Bakery.
- Dr. Oetker (2025, April 30). Dr. Oetker Financial Year 2024.
- Premier Foods (2026, May 14). Full Year Results for the 52 weeks ending 28 March 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is the Yule Logs Market size in 2026 and what value is forecast for 2036?
- Which cultural, retail, and hospitality pressures support demand for yule logs?
- Why does Classic / original hold the leading position within Product Type?
- How does Conventional influence price coverage and downstream seasonal demand?
- Why does Fresh hold the leading position within Format?
- How do growth rates differ across USA, Germany, France, UK, Saudi Arabia, UAE, Japan, and South Korea?
- Which companies provide frozen dessert, bakery manufacturing, or branded cake capabilities?
- How does the short seasonal selling window limit adoption and profitability?
Frequently Asked Questions
What is driving growth in the Yule Logs Market?
Growth rests on a fixed year-end celebration occasion and on wider retail or hospitality access to premium seasonal cakes. Frozen formats, preorders and flexible pack sizes help suppliers convert that occasion into repeatable revenue while controlling waste.
Who are the key players in the Yule Logs Market?
The profiled set includes Mademoiselle Desserts and Dessert Holdings as frozen-dessert specialists. Finsbury Food Group, Rich Products and Vandemoortele add bakery scale. Branded cake companies are included only where seasonal product evidence is direct.
What is a notable restraint in the Yule Logs Market?
The most binding restraint is the short selling window, which forces production commitments before final demand is known. Forecast error can create markdowns, waste, or missed availability even when consumer interest remains healthy.
Why should executives track the Yule Logs Market?
The market shows how seasonal ritual, premiumization, and cold-chain execution combine inside a concentrated revenue window. Executives can use it to test assortment discipline and production flexibility while also testing channel readiness across retail, bakery, and hospitality accounts.
What business problem does the Yule Logs Market address?
Yule log suppliers give retailers and foodservice operators a recognizable festive centerpiece without requiring each buyer to develop the product from scratch. Scaled formats reduce recipe development, labor pressure, and presentation variability during the busiest holiday period.
What should retail category managers evaluate in the Yule Logs Market?
Retail category managers should evaluate sell-through history and shelf life alongside cold-chain needs and pack architecture. They should test decoration resilience, replenishment lead times, and whether preorder data or store-level forecasting can reduce unsold seasonal inventory.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic / original
- Fruit- or cream-filled logs
- Specialty flavored logs
- Mini / individual logs
- Premium pâtisserie logs
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- Vegan / plant-based
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Thaw-and-serve
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Whole-log presentation box
- Bulk foodservice
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mademoiselle Desserts
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Dessert Holdings
- Finsbury Food Group
- Bindi Dessert
- Rich Products
- Sara Lee Frozen Bakery
- Vandemoortele
- Dr. Oetker
- Bauli
- Premier Foods
- Mademoiselle Desserts
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


