

- Market Size (2026)
- USD 51.5 Bn
- Forecast (2036)
- USD 82.6 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Cat Food Market in 2026?
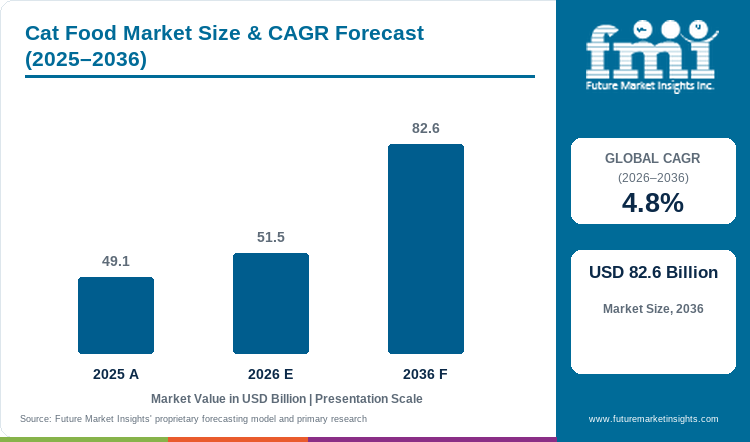
USD 51.5 billion in 2026 and USD 82.6 billion by 2036 at a 4.8% CAGR.
Demand for cat food is projected to expand at 4.8% CAGR between 2026 and 2036. Valuation rises from an estimated USD 49.1 billion in 2025 to USD 51.5 billion in 2026 before reaching USD 82.6 billion by 2036. Repeat feeding is turning household ownership into regular purchases, but premium growth is still dependent on benefits owners can justify at every replenishment. Nestlé Purina Petcare Europe relaunched and expanded the Gourmet Perle wet cat food range in June 2026 across nearly 30 European markets, citing approximately 6% global value growth in premium wet cat food as the category context for the expansion. Sensory variety is supporting repeat purchase by giving households more feeding options without changing the core nutrition proposition.
Country growth rates require a different reading because forecast pace does not establish current revenue or installed feeding volume. Japan is projected at 5.8% CAGR, and Germany is forecast at 5.5% from 2026 to 2036. ZZF and IVH reported in April 2026 that 43% of German cat-owning households kept at least two cats during 2025. Multi-cat ownership is raising household food throughput and supporting regular replenishment in Germany. Japan's higher rate is influenced by recipe mix and value per feeding occasion rather than rapid expansion in the national cat population.
Key Takeaways of Cat Food Market
- Daily feeding converts a large household cat base into frequent purchases because nutrition and palatability sustain continued acceptance.
- Conventional is projected to account for 79.1% of nature demand in 2026, supported by broad recipe availability and familiar feeding routines.
- Animal derived is estimated to hold 43.2% of source demand in 2026, driven by widespread use of meat or fish proteins in complete feline diets.
- Kibble - dry is expected to lead product type with 24.2% share in 2026, influenced by practical storage and portion control.
- Household value seeking and feeding-transition risk can delay movement into higher-priced recipes despite clear nutritional benefits for owners.
- Some of the key players in this market include Mars Petcare, Nestlé Purina PetCare, General Mills (Blue Buffalo), Hill's Pet Nutrition (a Colgate-Palmolive company), The J.M. Smucker Co., Diamond Pet Foods, Wellness Pet Company, Simmons Pet Food, and Champion Petfoods.
Analyst Perspective
"Cat food revenue depends on repeat acceptance because a recipe that fails palatability or household value tests loses its replenishment cycle. Suppliers retain more households when nutrition claims match a feeding format that owners can serve consistently without forcing an abrupt diet change."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Cat Food Market segmented?
The cat food market is segmented by nature, source, product type, pet type, packaging type and distribution channel.
Source includes animal derived, plant-derived, chicken, beef, lamb, fish, insect-derived and pork. Product type covers kibble - dry, treats and chews, freeze-dried raw, wet food, extruded, coated, frozen and dehydrated food. Pet type covers senior and kitten. Packaging includes bags, pouches, folding cartons, can, tubs & cups and bottles & jars. Distribution channel includes store-based retailing, hypermarkets - supermarkets, pet stores, online retailers, discounters, independent grocery retailers, convenience stores and mom and pop stores.
How does conventional feeding support routine nature-category purchasing?
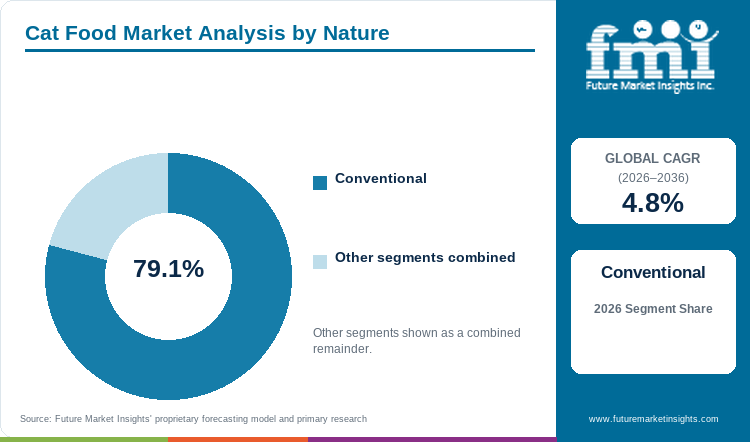
Conventional recipes serve households that want complete daily nutrition without a sourcing claim that narrows ingredient or price choices. AAFCO published its updated Pet Food and Specialty Pet Food Nutrition Facts Calculator in June 2025 for current nutrition-label calculations. Standardized nutrient presentation supports objective comparison among routine formulas sold within the pet food category. Organic and monoprotein recipes answer narrower sourcing or sensitivity preferences that can justify a different price point. Familiar complete diets reduce switching friction and keep conventional products easy to replenish during regular household shopping.
- Conventional is projected to account for 79.1% of nature demand in 2026, attributable to broad recipe choice that supports repeat household purchasing.
- Organic and monoprotein alternatives draw demand from households that accept narrower choice and higher formulation costs for a specific sourcing or sensitivity benefit.
What keeps animal-derived inputs central to source selection?
Cat formulations must satisfy species-specific amino acid and protein requirements before ingredient positioning can influence purchase choice. FEDIAF published its 2025 nutritional guidelines with recommended nutrient levels for complete cat food. Those requirements keep protein quality and digestibility central to formulation decisions. Pet food ingredients need to provide required nutrients together with acceptable cost and palatability. Manufacturers are evaluating plant-derived or fermentation-based inputs against amino acid coverage and feeding acceptance requirements. Animal-derived inputs retain a central role because meat or fish provides familiar protein delivery within complete commercial recipes.
- Animal derived is estimated to hold 43.2% of source demand in 2026, reinforced by continued use of meat or fish proteins in complete commercial recipes.
- Alternative protein routes are gaining consideration as manufacturers protect amino acid coverage and feeding acceptance without raising formulation complexity beyond the target price point.
Why does kibble - dry retain a practical product-type role?
Kibble - dry supports controlled portions and longer storage without refrigeration until opening. General Mills launched BLUE Tastefuls Irresistible Gravy Experience in March 2026 as a dry cat food that can also be served with added water. The format lets households change texture at serving time without abandoning dry-food storage or portioning. Pet food processing requires shape and nutrient consistency during commercial production. Wet and freeze-dried formats compete on moisture delivery and sensory variety, which can justify different handling. Storage simplicity keeps dry food practical for repeated household feeding.
- Kibble - dry is forecast to represent 24.2% of product type demand in 2026, influenced by practical storage and portion control.
- Households and retailers are comparing moisture and texture benefits against the handling changes required by wet or freeze-dried formats.
How do senior feeding needs change pet-type selection?
Senior cat diets address an age band in which weight control and chronic health management become more visible during feeding decisions. Hill’s enhanced its adult and senior dry dog and cat portfolio in April 2025 with ActivBiome+ Multi-Benefit technology. The change links age positioning with digestive and organ-health support instead of relying on a simple age label. Kitten nutrition follows a different growth requirement and can involve pet milk replacers for animals needing an appropriate early-life feeding route. Mature-cat products retain commercial weight as owners seek daily nutrition aligned with age-related concerns. Suppliers need palatability and clear feeding guidance because long-term use depends on routine household acceptance.
- Senior is expected to hold 72.8% of pet type demand in 2026, tied to mature-cat health concerns and age-specific daily feeding choices.
- Kitten products remain distinct because growth-stage nutrient requirements and early feeding routines differ from adult maintenance decisions.
What makes bags practical within packaging type?
Bags support dry-food handling because they carry multi-meal quantities without the weight or rigidity of cans and tubs. Mars launched mono-material recyclable WHISKAS pouches in the United Kingdom and Germany during July 2025 and reported a 46% lower packaging carbon footprint. The pouch redesign lowers packaging impact without changing the wet pet food serving occasion. Dry-food bags answer a different requirement by keeping large quantities easy to store between meals. Resealable closures reduce exposure once a pack is opened and support household use over several feeding occasions. Kibble volume and storage economics support bag demand over single-serve portioning during routine household feeding.
- Bags are set to lead packaging type with 34.8% share in 2026, supported by dry-food volumes that suit resealable multi-meal packs.
- Pouches and cans retain an important role for products that sell on portioning and moisture as part of the feeding proposition.
How does store-based retailing support routine replenishment?
Cat food is purchased frequently enough that immediate replacement matters alongside planned online replenishment. Champion Petfoods announced nationwide ORIJEN and ACANA distribution in Mexico during October 2025 using Petco stores and online channels. The expansion documents a hybrid retail route that keeps physical and digital access relevant to routine feeding. Physical stores give households immediate access during unplanned staple-food shortages. Online channels secure repeat deliveries for households with predictable feeding schedules and preferred pack sizes. Pet care spending requires consistent assortment and pack economics between physical shelves and digital listings.
- Store-based retailing is projected to hold 48.5% of distribution-channel demand in 2026, reinforced by households' need for immediate staple-food replacement.
- Online retailers gain repeat orders because subscriptions and assortment depth offset delivery timing for households with predictable feeding schedules.
What are the drivers, restraints and opportunities in the Cat Food Market?
Repeat feeding supports differentiated formats while household value pressure slows trade-up and qualified ingredient systems open future formulation routes.
- Driver: Daily replenishment gives differentiated recipes repeated purchase opportunities once texture or nutrition benefits earn household acceptance.
- Restraint: Abrupt price or palatability changes can interrupt premium repeat purchases despite an established household feeding routine.
- Opportunity: New ingredient systems and targeted formats can widen nutrition choices following successful safety and feeding-performance qualification.
Driver: Repeat feeding rewards formats that earn routine household acceptance
Routine feeding gives an accepted format repeated opportunities to earn household spending during normal replenishment. Nestlé expanded its pyramid-shaped wet cat food in February 2025 with a new jelly version for 15 European markets and broader U.S. distribution. The launch added texture choice inside a complete wet-food format that households can replenish repeatedly. Functional recipes are increasing use of pet food additives when the added nutrition role is clear during normal feeding. Manufacturers convert initial trial into durable volume by making a new format part of the normal feeding routine. Repeat acceptance carries more commercial weight than novelty once households begin replenishing the same product.
Restraint: Household value seeking raises the retention test for premium recipes
Higher-priced recipes lose momentum when households cannot connect the premium to a repeatable feeding benefit. UK Pet Food reported in April 2026 that Battersea research found almost one-third of dog and cat owners had cut essential costs to feed their pets. Household budget pressure reaches repeat purchasing because owners must fund the same diet during every grocery cycle. A price-led switch also raises palatability risk and can push owners back toward familiar recipes. Pet food palatants can reduce sensory friction by matching flavor systems to the intended formulation without replacing nutritional adequacy. Premium products need a price and feeding experience that remain acceptable throughout repeated household use.
Opportunity: New protein and nutrient systems can broaden qualified recipe options
Ingredient innovation is widening sourcing options for manufacturers that preserve nutritional performance and regulatory acceptance. Colgate-Palmolive reported in July 2026 that Hill's received an FDA no-objection letter during May for a lamb protein yeast developed with Bond Pet Foods for dog food. The action establishes an immediate pet-food-family ingredient route but does not authorize feline use. Pet food premix systems can keep micronutrient delivery consistent as protein inputs change during commercial formulation. Cat-food suppliers gain commercial value once a new ingredient clears the relevant safety route and performs inside a nutritionally complete feline recipe. The opportunity depends on qualified formulation flexibility for commercial recipes instead of novelty alone as a purchase reason.
Which country CAGRs are profiled in the Cat Food Market?
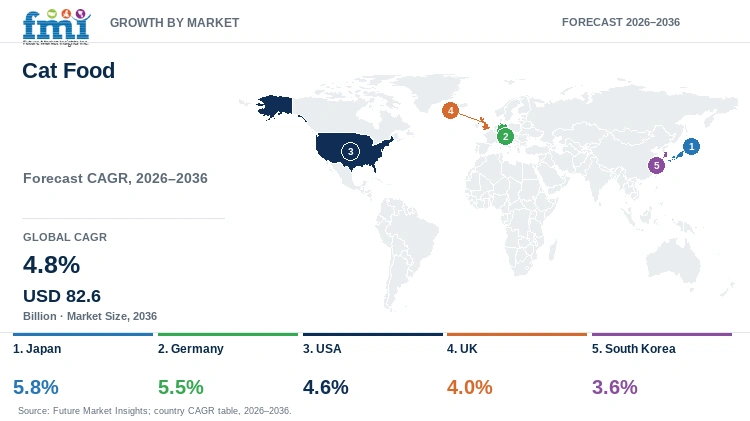
| Country | CAGR |
|---|---|
| Japan | 5.8% |
| Germany | 5.5% |
| USA | 4.6% |
| UK | 4.0% |
| South Korea | 3.6% |
How do country-level CAGRs compare in the Cat Food Market?
Japan and Germany form the upper portion of the five-country forecast range during the 2026 to 2036 assessment period. The USA aligns more closely with the global rate whereas the UK and South Korea record slower forecast growth.
- Japan’s mature cat population makes recipe mix and value per feeding occasion more important than pet-count expansion.
- Germany’s frequent multi-cat ownership raises household feeding volume inside an already substantial national feline population.
- USA demand draws on a broad household base but value seeking limits how quickly premium recipes become routine.
- UK cat ownership supports repeat volume but household cost pressure increases sensitivity to pack size and price.
- South Korea’s smaller feline share favors focused distribution because cat-specific nutrition must justify dedicated assortment.
The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Japan's mature feline ownership base limits how much pet-population expansion can contribute to new food volume. Adoption of cat food in Japan is estimated to expand at 5.8% CAGR through 2036, influenced by recipe mix and feeding experience in a mature ownership base. The Pet Food Association of Japan estimated about 8.847 million cats in 2025 and described the population as broadly flat. Stable pet numbers make higher value per feeding occasion more important than simple expansion in household ownership. Suppliers are raising repeat value with moisture or sensory variety, but unsupported price increases remain difficult inside a mature ownership base with disciplined pack sizes.
- Germany's substantial cat population and frequent multi-cat ownership support high routine feeding volumes. Cat food sales in Germany are forecast to expand at 5.5% CAGR by 2036, supported by deep household ownership and repeated multi-cat replenishment. ZZF and IVH reported that cats lived in 24% of German households during 2025 and 43% of cat-owning households kept two or more cats. That national ownership depth raises food throughput and makes reliable pack availability important for households feeding several animals. Manufacturers need consistent pack sizes and pricing because the same households replenish through physical and online stores. Multi-cat households reward brands that maintain familiar wet and dry formats during repeated purchases.
- USA cat food demand draws on a broad household base that expanded during 2025. Cat food demand in the USA is predicted to advance at 4.6% CAGR through 2036, attributable to a large national cat-owning base that continues to expand. APPA reported in September 2026 that 53 million U.S. households owned a cat during 2025 and ownership increased 5% from the previous year. Mixers and toppers are adding variety beside the core meal without forcing a complete diet change. Pet snacks and treats give owners another repeat-purchase option within a familiar feeding routine. Brands need a clear step from staple nutrition to premium benefits so household budgets do not break repeat use.
- UK cat ownership provides a broad repeat-feeding base for the cat food market. The UK outlook is anticipated to advance at 4.0% CAGR over the assessment period, constrained by household cost pressure on premium recipes. UK Pet Food estimated about 13.1 million cats in homes during 2026 and reported that 31% of households had a cat. That installed base supports repeat volume without requiring rapid expansion in the number of cat-owning households. Household cost pressure is limiting how quickly premium recipes become routine purchases during grocery or specialty-store trips. Practical pack sizes and clear nutrition claims remain important for maintaining access during tighter household budgets.
- South Korea has a smaller feline share within pet-owning households than several mature Western consumer markets. South Korea is projected to grow at 3.6% CAGR by 2036, shaped by specialized feline offers gaining distribution from a narrower species base. The Ministry of Agriculture Food and Rural Affairs reported in February 2026 that 29.2% of households directly kept a pet during 2025. Cats were kept by 14.4% of pet-owning households and remained much less prevalent than dogs in the same survey. The narrower species base makes targeted distribution more important than undifferentiated national assortment for cat-specific products. Suppliers need visible nutrition or convenience benefits before expanding beyond proven specialty channels at commercial scale.
Who are the notable companies in the Cat Food Market?
Mars Petcare, Nestlé Purina PetCare, General Mills (Blue Buffalo), Hill's Pet Nutrition, Colgate-Palmolive (Hill's), The J.M. Smucker Co., Diamond Pet Foods, Wellness Pet Company, Simmons Pet Food, and Champion Petfoods are notable companies active in the defined market.
Competition spans broad branded nutrition systems and focused manufacturing models serving different routes to repeat household feeding. Mars Petcare and Nestlé Purina PetCare operate international cat-food portfolios and General Mills combines Blue Buffalo with Tiki Cat. Hill's Pet Nutrition is the operating nutrition business inside Colgate-Palmolive and the parent controls ownership and investment responsibility for that business.
- Broad branded nutrition: Mars Petcare, Nestlé Purina PetCare and General Mills combine multi-format offers with wide retail distribution and recent cat-food investment.
- Veterinary and condition-focused nutrition: Hill's Pet Nutrition and Colgate-Palmolive (Hill's) connect everyday feeding with science-led therapeutic or specialty nutrition routes.
- Specialist and manufacturing models: The J.M. Smucker Co. and Diamond Pet Foods join Wellness Pet Company alongside Simmons Pet Food and Champion Petfoods in narrower brand or production roles.
Competitive Benchmarking: Cat Food Market
| Company | Recent Cat-Food Activity | Production & Channel Control | Feline Nutrition Depth | Geographic Reach |
|---|---|---|---|---|
| Mars Petcare | High | High | Medium | Global |
| Nestlé Purina PetCare | High | High | Medium | Global |
| General Mills (Blue Buffalo) | High | Medium | Medium | North America; selected international activity |
| Hill's Pet Nutrition | High | Medium | High | North America; international markets |
| Colgate-Palmolive (Hill's) | Medium | High | High | Global through Hill’s Pet Nutrition |
| The J.M. Smucker Co. | Medium | Medium | Low | United States |
| Diamond Pet Foods | Low | Medium | Low | United States; selected exports |
| Wellness Pet Company | High | Medium | High | North America; international distribution |
| Simmons Pet Food | Low | High | Low | United States and Canada |
| Champion Petfoods | High | Medium | Medium | North America; international distribution |
Key Developments in the Cat Food Market
- In July 2026, Nestlé Purina PetCare announced a new integrated pet food plant and logistics platform in Mantova with production planned from 2029 for super-premium wet cat and dog food.
- In June 2026, Hill’s Pet Nutrition launched Prescription Diet k/d + z/d Hydrolyzed for cats to address kidney function alongside gastrointestinal or skin sensitivities through veterinarian recommendation.
- In March 2026, Wellness Pet Company unveiled a new protein-forward cat lineup at Global Pet Expo with additional wet meals and feline nutrition formats.
Key Players in the Cat Food Market
Scaled Branded Cat Nutrition Platforms
- Mars Petcare
- Nestlé Purina PetCare
- General Mills (Blue Buffalo)
- Champion Petfoods
Veterinary and Therapeutic Nutrition
- Hill's Pet Nutrition
- Colgate-Palmolive (Hill's)
Branded Specialists and Value Nutrition
- The J.M. Smucker Co.
- Diamond Pet Foods
- Wellness Pet Company
Private-Label and Contract Manufacturing
- Simmons Pet Food
Cat Food Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By nature, source, product type, pet type, packaging type, distribution channel and region. |
| Quantitative Units | Revenue in USD billion and CAGR in %. |
| Market Definition | Revenue from commercially prepared cat food and cat treats sold within the stated segmentation universe. Excludes dog and other pet food, pet litter and accessories, standalone veterinary medicines or supplements, upstream ingredient sales and non-food services. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Japan, Germany, USA, UK, South Korea, and 20+ countries included in the full report. |
| Key Companies Profiled | Mars Petcare, Nestlé Purina PetCare, General Mills (Blue Buffalo), Hill's Pet Nutrition, Colgate-Palmolive (Hill's), The J.M. Smucker Co., Diamond Pet Foods, Wellness Pet Company, Simmons Pet Food, and Champion Petfoods. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Cat Food Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Cat Food Market by Segments
Cat Food Market segmented by Nature:
- Conventional
- Organic
- Monoprotein
Cat Food Market segmented by Source:
- Animal Derived
- Plant-derived
- Chicken
- Beef
- Lamb
- Fish
- Insect-derived
- Pork
Cat Food Market segmented by Product Type:
- Kibble - Dry
- Treats and Chews
- Freeze-Dried Raw
- Wet Food
- Extruded
- Coated
- Frozen
- Dehydrated Food
Cat Food Market segmented by Pet Type:
- Senior
- Kitten
Cat Food Market segmented by Packaging Type:
- Bags
- Pouches
- Folding cartons
- Can
- Tubs & Cups
- Bottles & jars
Cat Food Market segmented by Distribution Channel:
- Store-based Retailing
- Hypermarkets - Supermarkets
- Pet Stores
- Online Retailers
- Discounters
- Independent Grocery Retailers
- Convenience Stores
- Mom and Pop Stores
Cat Food Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Nestlé. (2026, June 4). Purina Europe relaunches and expands key wet cat food range under Gourmet brand.
- ZZF and IVH. (2026, April 23). Der Deutsche Heimtiermarkt 2025.
- Association of American Feed Control Officials. (2025, June 10). Pet Food and Specialty Pet Food Nutrition Facts Calculator - June 10, 2025.
- FEDIAF. (2025, September 8). FEDIAF Publishes 2025 Nutritional Guidelines for Cats and Dogs.
- General Mills. (2026, March 12). Blue Buffalo™ Introduces BLUE Tastefuls™ Irresistible Gravy Experience.
- Hill's Pet Nutrition. (2025, April 22). Hill's Pet Nutrition Enhances Hill’s Science Diet Portfolio With Game-Changing Microbiome Innovation.
- Mars, Incorporated. (2025, July 31). Mars Debuts Recyclable Pet Food Pouches for WHISKAS®.
- Mars México. (2025, October 21). ORIJEN y ACANA llegan a todo México: Champion Petfoods fortalece su presencia regional.
- Nestlé. (2025, February 11). Cats Love Pyramids! Purina Expands Innovative Cat Food Range.
- UK Pet Food. (2026, April 21). UK Pet Food Industry Urged to Support ‘No Empty Bowls’ Initiative Keeping Pets in Loving Homes.
- Colgate-Palmolive. (2026, July). How Hill’s and Bond Pet Foods Are Crafting the Future of Pet Nutrition.
- Pet Food Association of Japan. (2025). 2025 National Dog and Cat Ownership Survey: Survey Topics.
- American Pet Products Association. (2026, September 14). Gen Z and Cat Dads Are Leading Cat Ownership’s Cultural Boom: New APPA Report Reveals What’s Driving Growth in America’s Feline Household.
- UK Pet Food. (2026, March 31). Britain’s Dog Ownership Boom as 15.5 Million Dogs Now Live in UK Homes.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, February 12). 2025 Pet Animal Rearing Status Survey Results.
- Nestlé. (2026, July 20). Nestlé Purina PetCare: CHF 520 Million Investment in New Integrated Pet Food Plant in Italy.
- Hill's Pet Nutrition. (2026, June 9). Hill’s Pet Nutrition Launches Premiere Nutrition Supporting Kidney Function Plus GI and Skin Sensitivities.
- Wellness Pet Company. (2026, March 24). Wellness Pet Company Unveils Expansive Portfolio of Protein-Forward Cat and Dog Innovations at Global Pet Expo 2026.
- Nestlé. (2026, September 9). Nestlé Invests CHF 157 Million in Thailand to Meet Growing Demand for High-Quality Pet Nutrition.
- Nestlé Purina PetCare. (2026, September 10). Fancy Feast and Paige DeSorbo Launch "The Paige Edit," a Limited-Edition Collection of Daphne's Favorites.
- Hill's Pet Nutrition. (2026, April 30). Hill’s Pet Nutrition Introduces Innovation to Support Feline Mobility and Weight Management.
- Wellness Pet Company. (2025, August 12). Wellness Pet Elevates Mealtime With 20+ New Wet Cat Food Offerings at SUPERZOO 2025.
- General Mills. (2026, August 25). Cozy Fall Flavors Are Back: Your Guide to General Mills’ New Seasonal Lineup.
- Hill's Pet Nutrition. (2025, June 18). Cats Declare World Domination Set for June 24, Stage Takeover of Hill’s Pet Nutrition.
- Colgate-Palmolive. (2025, August 1). Colgate-Palmolive Company Announces 2nd Quarter 2025 Results.
- The J.M. Smucker Co. (2025, June 27). Fiscal Year 2025 Annual Report.
- San Joaquin Valley Air Pollution Control District. (2025, August 11). Notice of Final Action: Authority to Construct Permits / Certificates of Conformity (Significant Mod), Diamond Pet Foods - Ripon.
- Wellness Pet Company. (2025, November 13). The Wellness Supper Club: Wellness Pet and Hayley Erbert Hough Encourage Cat Parents to Elevate the Shared Dining Experience.
- State of Kansas. (2025, July 31). 2025 Recovery Plan Performance Report.
- Nestlé. (2026, March 4). Nestlé Purina Opens a CHF 370 Million Pet Food Factory in Brazil.
- Mars U.S. (2026, September 9). The TEMPTATIONS™ Brand Debuts First-of-Its-Kind "Cat Bodega" to Celebrate Shop Cats Everywhere.
- Mars Canada. (2026, June 24). Champion Petfoods Unveils Global Innovation and Discovery Centre.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is cat food demand in 2026 and 2036?
- Which factors convert cat ownership into repeat commercial cat food purchases?
- Why does conventional account for 79.1% of the nature category in 2026?
- How does animal-derived sourcing shape commercial cat food formulation and purchasing choices?
- Why does kibble - dry retain a practical role in routine cat feeding?
- How do the five country growth rates shown here differ through 2036?
- Which companies combine branded cat nutrition with manufacturing or distribution scale?
- Which conditions can interrupt repeat purchases of higher-priced cat food products?
Frequently Asked Questions
How big is the Cat Food Market in 2026?
The cat food market is valued at USD 51.5 billion in 2026 and is projected to reach USD 82.6 billion by 2036. Daily feeding and a large installed cat-owning base support repeat purchases during the forecast period.
What is the Cat Food Market expected CAGR from 2026 to 2036?
The cat food market is forecast to expand at 4.8% CAGR between 2026 and 2036. Growth depends on repeat household feeding plus higher value from formats or nutrition benefits that owners continue purchasing.
Which source segment dominates in 2026?
The animal-derived segment is estimated to represent 43.2% of the source category in 2026, driven by widespread use of animal protein in complete commercial diets. Feline nutrition requirements keep protein quality and palatability central to formulation.
How do the country growth rates shown here differ through 2036?
Japan is projected to expand at 5.8% CAGR through 2036, with Germany forecast at 5.5% and the USA at 4.6%. These rates describe forecast pace and do not rank present revenue because ownership depth and feeding behavior differ by country.
Which companies are active in the Cat Food Market?
Key companies active in the cat food market include Mars Petcare and Nestlé Purina PetCare plus General Mills and Hill's Pet Nutrition. Other active companies include Colgate-Palmolive and The J.M. Smucker Co. plus Diamond Pet Foods and Wellness Pet Company together with Simmons Pet Food and Champion Petfoods.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- How big is Cat Food Market in 2026?
- Key Takeaways
- Analyst Perspective
- How is the cat food market segmented?
- How does conventional feeding support routine nature-category purchasing?
- What keeps animal-derived inputs central to source selection?
- Why does kibble - dry retain a practical product-type role?
- How do senior feeding needs change pet-type selection?
- What makes bags practical within packaging type?
- How does store-based retailing support routine replenishment?
- What are the drivers, restraints and opportunities in the Cat Food Market?
- Driver: Repeat feeding rewards formats that earn routine household acceptance
- Restraint: Household value seeking raises the retention test for premium recipes
- Opportunity: New protein and nutrient systems can broaden qualified recipe options
- Which country CAGRs are profiled in the Cat Food Market?
- How do country-level CAGRs compare in the Cat Food Market?
- Country-wise Analysis
- Who are the notable companies in the Cat Food Market?
- Competitive Benchmarking: Cat Food Market
- Key Developments in the Cat Food Market
- Key Players in the Cat Food Market
- Scaled Branded Cat Nutrition Platforms
- Veterinary and Therapeutic Nutrition
- Branded Specialists and Value Nutrition
- Private-Label and Contract Manufacturing
- Cat Food Market - Report Scope
- Cat Food Market - Research Methodology
- Cat Food Market by Segments
- Cat Food Market segmented by Nature:
- Cat Food Market segmented by Source:
- Cat Food Market segmented by Product Type:
- Cat Food Market segmented by Pet Type:
- Cat Food Market segmented by Packaging Type:
- Cat Food Market segmented by Distribution Channel:
- Cat Food Market by Region:
- Research Sources and Bibliography
- This Report Answers
- Frequently Asked Questions
- Competitive Landscape


