

- Market Size (2026)
- USD 8.8 Bn
- Forecast (2036)
- USD 24.4 Bn
- CAGR (2026 to 2036)
- 10.7%
How big is Clothing Recycling Market in 2026?
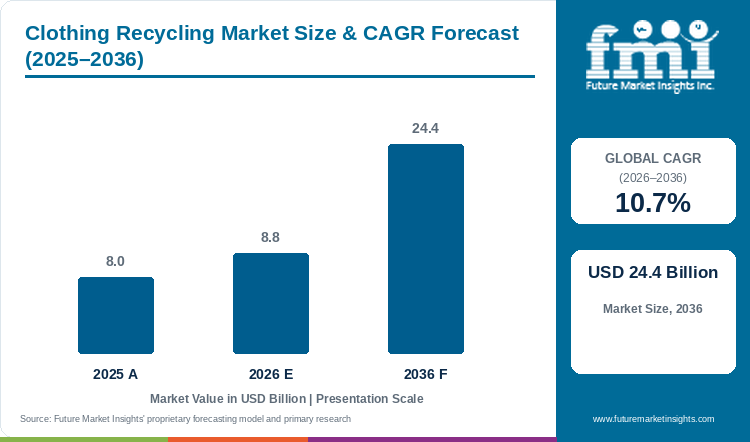
The clothing recycling market is estimated at USD 8.0 billion in 2025 and is projected to reach USD 8.8 billion in 2026. Clothing recycling sales are forecast to grow at a 10.7% CAGR and reach USD 24.4 billion by 2036.
Across collection, sorting and recovered fibre, the clothing recycling market is estimated at USD 8.0 billion in 2025. For 2026, USD 8.8 billion of clothing recycling sales is expected. The FMI model has the clothing recycling market at USD 24.4 billion by 2036, a 10.7% CAGR between 2026 and 2036. Governments are moving the cost of collecting and sorting used garments onto the brands that sell them. CalRecycle approved Landbell USA on 27 February 2026 as the producer responsibility organisation for California's textile law, and producers had until 1 July 2026 to join.[1] Producer fees turn clothing recovery from a charity-funded activity into a paid service, so sorters can plan capacity against contracted volumes.
Robotic sorting research gives South Korea a projected 11.1% CAGR, and the United Kingdom, with no mandatory scheme, comes in at 10.5%. Korean households discard about 300,000 to 350,000 tons of used clothing, and from 2026 the climate ministry is funding research on AI and robotic garment sorting.[2] Automated sorting will send cotton-polyester blends to fibre recyclers, and each new line will cut the tonnage burned. British collectors still work without that producer funding, which holds growth below the rate for the clothing recycling market.
Clothing recycling demand is moving beyond traditional sources of demand such as rag exports, as fibre makers buy sorted cotton and polyester for new yarn.
Key Market Trends & Insights
- Cotton is estimated to supply 38.6% of fiber type sales in 2026, and polyester about 33.4%. Over half of the clothing sold in South Korea is made of cotton-polyester blends, which complicates fibre recovery.[2]
- Reused and remade apparel is expected to hold an estimated 41.5% of end use sales in 2026, with non-woven felts and insulation near 19.3% and industrial wipers about 17.8%.
- Sales of post-consumer material are projected to make up an estimated 64.8% of waste type sales in 2026. India recycles nearly 97% of the pre-consumer textile waste generated by garment and textile factories, the Ministry of Textiles said in May 2026.[3]
- Shredding and carding lines give mechanical recycling an estimated 78.6% of recycling type sales in 2026, and dissolving and depolymerisation plants the other 21.4%.
- Charity bins and municipal drop-off points are likely to account for 46.3% of collection channel sales in 2026, ahead of retail and brand take-back at about 31.5% and online and mail-back schemes near 22.2%.
Regional Highlights
- The highest rate in the profiled set belongs to India, a projected 12.1% CAGR, as the country handles about 7.8 million tonnes of textile waste, over 90% of that waste domestic.[3]
- FMI's model shows South Korea next at 11.1%, a tenth of a point ahead of the United States. France, with a mature producer scheme and saturated export outlets for used clothing, grows at 10.4%, three tenths of a point behind the 10.7% CAGR for clothing recycling.
- Germany collected about 1.3 million tonnes of used textiles in 2023, and the reuse share fell from 62% in 2018 to 44%, the bvse textile study published in August 2026 found.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Clothing Recycling Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 8.0 billion |
| Estimated Market Size in 2026 | USD 8.8 billion |
| Projected Market Size by 2036 | USD 24.4 billion |
| CAGR, 2026 to 2036 | 10.7% |
| Added Revenue, 2026 to 2036 | USD 15.6 billion |
| Market Expansion Multiple | 2.8x |
Collectors and sorters are paid per tonne by producer schemes, so sorting capacity grows only after fee levels are set. France raised support for collectors and sorters to EUR 268 per tonne for 2026, from EUR 228 planned, after placing 891,309 tonnes of new textiles on the market and collecting 289,393 tonnes in 2024.[5] Peer-to-peer resale platforms and brand second-hand channels are taking the best items out of the collection stream, and the secondhand apparel market is likely to expand at an 11.1% CAGR as resale apps add sellers, which leaves sorters with a lower-grade mix to recycle. The FMI outlook expects roughly USD 15.6 billion of added clothing recycling sales by 2036, so the clothing recycling market at the end of the decade is expected to be close to 2.8 times the 2026 level. Export outlets are the main risk, since over 60% of textiles collected in France are exported, mostly to African markets that are now saturated.[5]
Sorting Quality, Producer Fees and Fibre-to-Fibre Capacity
Falling quality is changing the economics of every collection bin. Foreign and interfering materials rose from about 10.8% of German collections in 2018 to 15% to 20%, recycling rose from 26% to 35% of recovered volume, and 62.6% of single-layer garments analysed carried zips, buttons or rivets.[4] Sorters will need automated fibre sorting and trim removal before more of each bale can go to fibre recyclers.
Textile-to-textile capacity is restarting in Europe. Circulose, the former Renewcell business now owned by Altor, added Eileen Fisher, Marimekko, Samsøe Samsøe and King Louie as brand partners and plans to restart production at Ortviken in Sundsvall in Q4 2026.[6] REPREVE Fiber products accounted for USD 40.2 million of Unifi net sales over April to June 2026, or 28% of the total.[7] Brand contracts give recyclers a price floor for sorted feedstock, and recycled fibre makers will buy more cotton-rich and polyester-rich bales from sorters.
Table 2: Collection, Sorting and Recycled Fibre Indicators for the Clothing Recycling Market (volumes, fees and sales), 2024 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| France textile collection, 2024 | 289,393 tonnes collected; 891,309 tonnes placed on market | Collection covers about a third of new textiles. | [5] |
| France sorter support, 2026 | EUR 268 per tonne | Producer fees fund sorting capacity. | [5] |
| Germany used textile collection, 2023 | About 1.3 million tonnes; reuse share 44% | More volume goes to recycling and incineration. | [4] |
| Unifi REPREVE Fiber sales, Q4 FY2026 | USD 40.2 million; 28% of net sales | Recycled fibre demand from brands. | [7] |
| India textile waste, 2026 study | About 7,073 kilo tonnes | Large domestic recycling base. | [3] |
| Japan household clothing disposed, 2024 | 480,000 tons | Low reuse and fibre recovery. | [8] |
Analyst Perspective
“Producer fees are turning used clothing from a donation stream into contracted feedstock, and I expect sorters with automated fibre identification to set the terms in the clothing recycling market through 2036. The opening I see as most valuable is cotton-rich post-consumer waste sorted to fibre grade. Pulp and yarn makers are already signing brand partners for recycled content, opening a higher earning tier for sorted cotton bales.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the clothing recycling market segmented?
The market is segmented into fiber type, end use, waste type, recycling type, collection channel, and region. Cotton leads fiber type with an estimated 38.6% share in 2026, and apparel leads end use with about 41.5%.
By fiber type: cotton, polyester, wool, nylon, and other fiber.
By end use: apparel, non-woven, industrial, home furnishings, and other.
By waste type: post-consumer, and pre-consumer.
By recycling type: mechanical, and chemical.
By collection channel: charity and municipal collection, retail and brand take-back, and online and mail-back.
By region: collection, sorting and fibre recycling operations in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does cotton lead clothing recycling sales by fiber type?
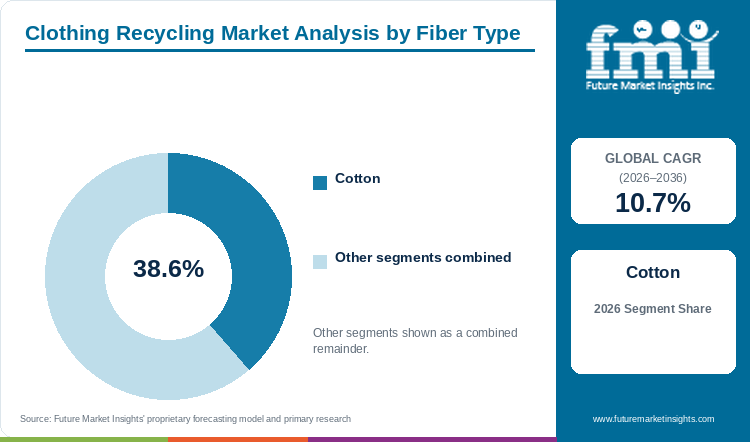
Cotton is estimated at 38.6% of fiber type sales in 2026, ahead of polyester at about 33.4% and other fibers near 12.7%.
Table 3: Fiber Type Share for the Clothing Recycling Market (percentage share), 2026
| Fiber Type | Estimated Share (2026) |
|---|---|
| Cotton | 38.6% |
| Polyester | 33.4% |
| Other Fiber | 12.7% |
| Wool | 9.2% |
| Nylon | 6.1% |
| Total | 100.0% |
Table 4: Fiber Type Leadership and Market Growth for the Clothing Recycling Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.7% |
| Leading Segment | Cotton |
T-shirts, denim and towels make up a large part of every collected bale, and cotton can be shredded into fibre or dissolved into pulp. On that basis, cotton is forecast to lead fiber type in 2026 with 38.6% share. Polyester, an estimated 33.4%, has the largest volume in new clothing, though blends with cotton and elastane make clean recovery harder. Other fibers, near 12.7%, include viscose, acrylic and mixed blends with few recycling routes. Wool, about 9.2%, keeps a premium as mechanical spinners turn old knitwear into new yarn. Nylon, roughly 6.1%, comes mainly from sportswear and hosiery in small, mixed lots. Sorters choosing which fibre to grade first will start with cotton, since pulp and yarn makers already pay for cotton-rich feedstock.
- Denim, T-shirts, sweatshirts and cotton towels supply most of the cotton stream.
- Birla Cellulose launched Liva Reviva M in October 2025 with up to 50% mechanically recycled post-consumer textile waste.[9]
Why does apparel lead clothing recycling sales by end use?
Apparel is expected to hold 41.5% of end use sales in 2026, with non-woven at about 19.3%, industrial uses near 17.8% and home furnishings roughly 14.2%.
Table 5: End Use Share for the Clothing Recycling Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Apparel | 41.5% |
| Non-Woven | 19.3% |
| Industrial | 17.8% |
| Home Furnishings | 14.2% |
| Other | 7.2% |
| Total | 100.0% |
Wearable garments resold second-hand earn far higher prices per kilogram than any recycled grade, so apparel is predicted to lead end use with 41.5% share in 2026. Children outgrow clothes within a season or two. With the kids apparel market likely to increase at a 6.3% CAGR, a steady flow of lightly worn items keeps reaching collection bins. Non-woven uses, an estimated 19.3%, turn shredded fibre into felts, insulation and car interior padding, and growth of the technical textiles market at a 6.2% CAGR supports those outlets. Industrial uses, near 17.8%, cut cotton garments into wiping rags for workshops and factories. Home furnishings, about 14.2%, use recycled fibre in blankets, cushions and filling. Other uses take 7.2%. A sorter grading each bale will pull reusable apparel first, since resale pays more per kilogram than any fibre outlet.
- Reusable garments go to second-hand retail at home and to export markets, and remade apparel uses recycled yarn.
- Over 60% of textiles collected in France are exported, mainly to African markets that are now saturated, textalks reported in February 2026.[5]
Why does post-consumer waste lead clothing recycling sales by waste type?
Post-consumer waste is projected at 64.8% of waste type sales in 2026, against about 35.2% for pre-consumer waste.
Table 6: Waste Type Share for the Clothing Recycling Market (percentage share), 2026
| Waste Type | Estimated Share (2026) |
|---|---|
| Post-Consumer | 64.8% |
| Pre-Consumer | 35.2% |
| Total | 100.0% |
Households discard far larger volumes than garment factories cut away, and producer schemes now pay for collecting that waste. In 2026, post-consumer waste is estimated to lead with 64.8% share of waste type sales. Pre-consumer waste, about 35.2%, is cleaner, single-fibre and sold by factories in sorted lots, and India already recycles nearly 97% of the pre-consumer waste generated in the country.[3] Pre-consumer supply grows only with garment output, so producer-funded collection of household clothing will add most of the new tonnage. A fibre maker choosing feedstock will pay more for pre-consumer cutting waste but will rely on post-consumer volume to fill large plants.
- Household donations, municipal textile bins, store drop-offs and mail-back parcels make up the post-consumer stream.
- Japanese households disposed of an estimated 480,000 tons of clothing as waste in 2024, Jiji Press reported in January 2026.[8]
Why does mechanical recycling lead clothing recycling sales by recycling type?
Mechanical recycling is likely to hold 78.6% of recycling type sales in 2026, and chemical recycling about 21.4%.
Table 7: Recycling Type Share for the Clothing Recycling Market (percentage share), 2026
| Recycling Type | Estimated Share (2026) |
|---|---|
| Mechanical | 78.6% |
| Chemical | 21.4% |
| Total | 100.0% |
Shredding, garnetting and carding lines cost little to run and already supply spinners, felt makers and insulation plants, and mechanical recycling will lead in 2026 with 78.6% share. Chemical recycling, an estimated 21.4%, dissolves cotton into pulp or breaks polyester and nylon into monomers, but needs high temperature and pressure, and recycled inputs from those routes cost 20% to 30% above virgin materials in South Korea.[2] Bottle flake competes with textile waste as feedstock for recycled polyester, and a 7% CAGR expected for the recycled PET market keeps price pressure on polyester recovered from clothing. A recycler choosing a route for mixed bales will stay mechanical until chemical plants reach full scale and lower cost per tonne.
- Mechanical routes cover shredding to fibre, garnetting and re-spinning, and chemical routes cover pulp dissolving and depolymerisation.
- Circulose plans to restart chemical pulp production at Ortviken in Sundsvall in Q4 2026, Ecotextile News reported in June 2026.[6]
Why does charity and municipal collection lead clothing recycling sales by collection channel?
Street bins and municipal recycling centres give charity and municipal collection an estimated 46.3% of collection channel sales in 2026, ahead of retail and brand take-back at about 31.5% and online and mail-back near 22.2%.
Table 8: Collection Channel Share for the Clothing Recycling Market (percentage share), 2026
| Collection Channel | Estimated Share (2026) |
|---|---|
| Charity and Municipal Collection | 46.3% |
| Retail and Brand Take-Back | 31.5% |
| Online and Mail-Back | 22.2% |
| Total | 100.0% |
Street bins and recycling centres reach every district and need no purchase to drop off a bag. As a result, charity and municipal collection is expected to lead collection channel sales with 46.3% share in 2026. Retail and brand take-back, about 31.5%, is growing as stores give vouchers for returned clothes. Brands have more reason to run take-back counters, with the sustainable fashion market forecast to rise at a 10.4% CAGR on recycled-content pledges. Online and mail-back schemes, near 22.2%, suit resale platforms and brands selling direct. Contamination is the weakness of open bins, with up to one in five collected kilograms sorted out at cost in Germany.[4] A producer scheme choosing collection partners will keep funding bins for volume and add retail points for cleaner, better-graded clothing.
- Charity bins, municipal recycling centres and door-to-door bag collections form the leading channel.
- California producers of covered apparel and textiles had to join Landbell USA by 1 July 2026, Keller and Heckman noted in March 2026.[1]
What are the drivers, restraints, and opportunities in the clothing recycling market?
Producer responsibility laws move the cost of collection and sorting onto clothing brands, which funds capacity. Falling bale quality and saturated export outlets squeeze sorters, and brand contracts for fibre-to-fibre feedstock open higher-value sales.
- Driver: Extended producer responsibility makes brands pay for every tonne collected and sorted, so sorting plants gain a funded, predictable intake.
- Restraint: Fast fashion with blends and trims lowers the share of each bale fit for reuse or recycling, which raises disposal costs for sorters.
- Opportunity: Fibre and pulp makers signing brand partners for recycled content will pay premium prices for sorted, single-fibre post-consumer feedstock.
Producer Fees Fund Collection and Sorting
Adoption of producer responsibility rules is moving clothing recovery from goodwill to contracts. California approved Landbell USA as the textile producer responsibility organisation on 27 February 2026, with statewide implementation from 1 January 2030.[1] The UK Textiles Pact asked government in January 2026 to legislate a mandatory textiles EPR scheme within this Parliament, run by one non-profit producer organisation.[10] Each new scheme sets a fee per item or per tonne, so collectors and sorters in those markets will add capacity once fees start.
Falling Bale Quality Squeezes Sorters
Producers of sorted clothing face a lower-value mix in every bale. Thermal recovery rose from 12% to 21% of German used textile volume between 2018 and 2023, the bvse study reported.[4] France added an exceptional EUR 40 per tonne in 2026 to keep collectors and sorters from failing.[5] FMI's analysis treats bale quality as the main constraint on sorter margins through 2036. Sorters without automated grading will lose money on mixed fast-fashion loads.
Fibre-to-Fibre Contracts Open Higher-Value Sales
Demand for recycled content from brands is creating a paid outlet for non-reusable clothing. Circulose added four brand partners, including Eileen Fisher and Marimekko, in June 2026.[6] Birla Cellulose offers a cellulosic fibre with up to 50% mechanically recycled post-consumer waste.[9] Sorters able to deliver cotton-rich bales to a fixed specification will sell at fibre-grade prices, well above rag and export prices, breaking through established market barriers that kept used clothing in the donation economy.
Which country CAGRs are profiled in the clothing recycling market?
Table 9: Country CAGR Comparison for the Clothing Recycling Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 12.1% |
| South Korea | 11.1% |
| United States | 11% |
| Germany | 10.8% |
| Japan | 10.6% |
| United Kingdom | 10.5% |
| France | 10.4% |
How do country-level CAGRs compare in the clothing recycling market?
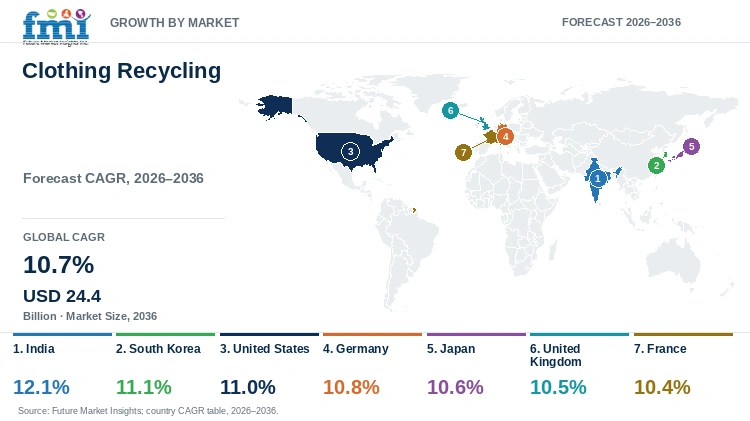
India produces about 7,073 kilo tonnes of textile waste, and over 90% of the waste managed in the country is domestic, the Ministry of Textiles said on 14 May 2026.[3] That domestic base gives India a projected 12.1% CAGR against the 10.7% rate for the clothing recycling market. South Korea, the United States and Germany are the countries setting the growth agenda for producer-funded sorting, and the FMI outlook gives all three rates between 10.8% and 11.1%. Japan grows near 10.6%, with reuse still weak. The United Kingdom is projected at 10.5% until a mandatory scheme passes. France has the slowest profiled rate, 10.4%. A mature producer scheme already runs there, and export outlets are saturated.
- Recycling clusters in India process large volumes of domestic textile waste.
- South Korean research on automated sorting starts in 2026.
- California has named a textile producer organisation for the first US scheme.
- German collectors face rising contamination and falling reuse shares.
- Japanese households discard most used clothing as waste.
- British industry is asking for mandatory textile EPR.
- French sorters need higher producer support to stay open.
Full report country CAGRs cover: Separate rates for India, South Korea, the United States and Germany are above the 10.7% clothing recycling market CAGR, and Japan, the United Kingdom and France grow more slowly, with regional coverage for Latin America, Eastern Europe and Middle East and Africa.
Country-wise Analysis
India Clothing Recycling Market Outlook (2026 to 2036)
Mapping of Textile Waste Value Chain in India 2026, cited by the Ministry of Textiles in May 2026, puts textile waste in the country at about 7,073 kilo tonnes, and the ministry said imported waste is only about 7% of the volume handled.[3] Birla Cellulose launched Liva Reviva M in October 2025, blending cellulosic fibre with up to 50% mechanically recycled post-consumer textile waste.[9] Recyclers in Panipat and other clusters will formalise and add cleaner processes, giving India an expected 12.1% CAGR.
Key takeaway: India grows fastest on a large domestic waste base and new recycled fibres.
South Korea Clothing Recycling Market Outlook (2026 to 2036)
Only about 20% of clothing collected in South Korean donation bins is resold or exported, and the rest is rejected and sent to incinerators, Financial News reported on 24 January 2026.[2] The climate ministry is funding automated sorting and fibre regeneration research from 2026, and rules on recycled content and take-back are under study.[2] FMI projects South Korea at 11.1%, as sorting lines move blends away from incineration.
Key takeaway: Funded sorting research moves Korean clothing waste toward fibre recovery.
United States Clothing Recycling Market Outlook (2026 to 2036)
California producers had to join Landbell USA by 1 July 2026, and the producer organisation is due to submit a needs assessment by 1 March 2027.[1] In the quarter to June 2026, net sales at Unifi grew 4.1% from a year earlier to USD 144.2 million.[7] FMI places the United States at an 11% CAGR. Other states will study the California model, and collectors and sorters will build capacity ahead of fees starting.
Key takeaway: The first state textile EPR scheme sets the pace in the United States.
Germany Clothing Recycling Market Outlook (2026 to 2036)
Collectors in Germany gathered about 1.3 million tonnes of used textiles in 2023, but foreign materials now make up 15% to 20% of the collected volume, bvse said on 25 August 2026.[4] The association asked for a binding 30% minimum share of textile-to-textile recyclate and a digital product passport.[4] Sorters will invest in fibre sorting once EPR funds flow, which supports a 10.8% CAGR.
Key takeaway: Quality problems slow German collection, and EPR funding will decide new sorting capacity.
Japan Clothing Recycling Market Outlook (2026 to 2036)
Japanese households bought 770,000 tons of clothing in 2024 and disposed of 480,000 tons as waste, and the Environment Ministry planned to compile an action plan on clothing waste by March 2026.[8] Reuse and fibre recycling lag, as resale shops and platforms are still few, so municipal and retail take-back will add volume slowly. Growth in Japan is projected at 10.6%, a little short of the clothing recycling market CAGR.
Key takeaway: An undeveloped reuse market holds Japan close to the clothing recycling market rate.
United Kingdom Clothing Recycling Market Outlook (2026 to 2036)
The UK Textiles Pact, published by WRAP on 29 January 2026, set out ten recommendations for a mandatory textiles EPR scheme and warned that costs to local authorities could reach GBP 200 million by 2035.[10] Nearly half of used textiles in the country are thrown away. The United Kingdom is projected at 10.5%, with faster growth once legislation fixes producer fees.
Key takeaway: Legislation timing decides when British sorting capacity grows.
France Clothing Recycling Market Outlook (2026 to 2036)
France collected 289,393 tonnes of used textiles in 2024 and raised sorter support to EUR 268 per tonne for 2026, textalks reported on 24 February 2026.[5] The government also pressed Refashion to propose fee penalties for ultra-fast fashion.[5] France is expected to grow at 10.4%, the lowest profiled rate, since the producer scheme is mature and exports to Africa are saturated.
Key takeaway: Saturated exports and an older producer scheme hold France at the bottom of the country ranking.
Who are the notable companies in the clothing recycling market?
Circulose, Worn Again Technologies, Lenzing, Birla Cellulose, Patagonia, Loop Industries, Unifi, Wolkat, American Textile Recycling Service and Boer Group are the profiled companies.
Coverage in the FMI report spans ten companies across fibre-to-fibre recycling, recycled fibre production, collection and sorting, and brand take-back. Circulose secured four new brand partners in June 2026 ahead of a production restart in Sundsvall.[6] Unifi reported fiscal 2026 net sales of USD 531.3 million, below USD 571.3 million in fiscal 2025.[7] Birla Cellulose added a mechanically recycled cellulosic fibre in October 2025.[9] Wolkat, Boer Group and American Textile Recycling Service run collection and sorting, and Patagonia runs brand take-back.
- Fibre-to-fibre recyclers: Circulose, Worn Again Technologies and Loop Industries.
- Recycled fibre producers: Lenzing, Birla Cellulose and Unifi.
- Collectors and sorters: Wolkat, Boer Group and American Textile Recycling Service.
- Brand take-back: Patagonia.
Competitive Benchmarking: Clothing Recycling Market
Table 10: Competitive Benchmarking for the Clothing Recycling Market (qualitative documentation ratings), 2026
| Company | Fibre-to-Fibre Output | Brand Partnerships | Collection Reach | Recency |
|---|---|---|---|---|
| Circulose | High | High | Low | High |
| Birla Cellulose | Medium | Medium | Low | Medium |
| Unifi | Medium | High | Low | High |
| Lenzing | Medium | High | Low | Low |
| Boer Group | Low | Low | High | Low |
Ratings follow what each company documented in releases and filings since May 2025, and none of the scores measures share.
Key Developments in the Clothing Recycling Market
- On 25 August 2026, bvse published a textile study showing reuse falling to 44% of German used textile volume.[4]
- On 19 August 2026, Unifi said REPREVE Fiber products made up 28% of fourth-quarter net sales.[7]
- On 24 June 2026, Circulose announced Eileen Fisher, Marimekko, Samsøe Samsøe and King Louie as brand partners.[6]
- On 14 May 2026, the Ministry of Textiles in India said nearly 97% of pre-consumer textile waste is recycled.[3]
- On 27 February 2026, CalRecycle approved Landbell USA as the textile producer responsibility organisation.[1]
- In February 2026, France raised support for textile collectors and sorters to EUR 268 per tonne.[5]
- On 29 January 2026, the UK Textiles Pact published a ten-point plan for mandatory textiles EPR.[10]
- On 4 January 2026, Japan said the Environment Ministry would draw up an action plan on clothing waste.[8]
- In October 2025, Birla Cellulose launched Liva Reviva M with recycled post-consumer waste.[9]
Key Players in the Clothing Recycling Market
Fibre-to-Fibre Recyclers
- Circulose
- Worn Again Technologies
- Loop Industries
Recycled Fibre Producers
- Lenzing
- Birla Cellulose
- Unifi
Collectors and Sorters
- Wolkat
- Boer Group
- American Textile Recycling Service
Brand Take-Back
- Patagonia
Clothing Recycling Market - Report Scope
Table 11: Report Scope for the Clothing Recycling Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Fiber type; end use; waste type; recycling type; collection channel; region |
| Quantitative units | USD billion |
| Market definition | Collection, sorting, reuse preparation and mechanical or chemical recycling of used and surplus clothing into resaleable garments, fibre, pulp, yarn and non-woven material. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Circulose, Worn Again Technologies, Lenzing, Birla Cellulose, Patagonia, Loop Industries, Unifi, Wolkat, American Textile Recycling Service, Boer Group |
| Forecast period | 2026 to 2036 |
Clothing Recycling Market - Research Methodology
Table 12: Research Methodology for the Clothing Recycling Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Regulator decisions, government statements, recycling association studies, fibre maker results and textile trade press from May 2025 onward. |
| Desk Research | Desk research covers producer responsibility schemes, collection volumes, bale quality, export outlets and recycled fibre capacity. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 8.8 billion and a 10.7% CAGR to 2036. |
| Data Validation | Tonnages, fees and company figures were checked against the regulator, association or company that published them. |
Clothing Recycling Market by Segments
Clothing Recycling Market segmented by Fiber Type:
- Cotton
- Polyester
- Wool
- Nylon
- Other Fiber
Clothing Recycling Market segmented by End Use:
- Apparel
- Non-Woven
- Industrial
- Home Furnishings
- Other
Clothing Recycling Market segmented by Waste Type:
- Post-Consumer
- Pre-Consumer
Clothing Recycling Market segmented by Recycling Type:
- Mechanical
- Chemical
Clothing Recycling Market segmented by Collection Channel:
- Charity and Municipal Collection
- Retail and Brand Take-Back
- Online and Mail-Back
Clothing Recycling Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Keller and Heckman LLP. (2026, March 9). CalRecycle approves Landbell USA as textile industry PRO. https://www.khlaw.com/insights/calrecycle-approves-landbell-usa-textile-industry-pro
- [2] Financial News. (2026, January 24). That old clothing you dropped in a collection bin: will it really be recycled? Lee You-beom's Eco & Energy column. https://en.fnnews.com/news/202601231531259599
- [3] IANS. (2026, May 14). Govt rejects portrayal of India as dumping ground for textile waste. https://ianslive.in/govt-rejects-portrayal-of-india-as-dumping-ground-for-textile-waste--20260514125418
- [4] bvse-Bundesverband Sekundärrohstoffe und Entsorgung. (2026, August 25). bvse-Textilstudie 2026 press release. https://www.bvse.de/dateien2020/2-PDF/02-Presse/06-Textil/2026/260825_Pressemitteilung%20bvse%20Textilstudie%202026.pdf
- [5] Textalks. (2026, February 24). France lifts textile-waste support to EUR 268/tonne as second-hand outlets clog. https://textalks.com/france-lifts-textile-waste-support-to-e268-tonne-as-second-hand-outlets-clog/
- [6] Ecotextile News. (2026, June 24). Circulose secures new brand partners. https://www.ecotextile.com/2026062463617/news/materials-production-news/circulose-secures-new-brand-partners/
- [7] Unifi, Inc. (2026, August 19). UNIFI, Makers of REPREVE, Reports Fourth Quarter Revenue Growth, Higher Margins, and Cash Generation (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000100726/000010072626000010/ufi-ex99_1.htm
- [8] Jiji Press via Nippon.com. (2026, January 4). Japan to draw up action plan to reduce clothing waste. https://www.nippon.com/en/news/yjj2026010400187
- [9] Indian Textile Magazine. (2025, October 14). Liva Reviva M launches as India's first mechanically recycled cellulosic fibre, championing circular fashion. https://www.indiantextilemagazine.in/liva-reviva-m-launches-as-indias-first-mechanically-recycled-cellulosic-fibre-championing-circular-fashion/
- [10] Fashion Capital. (2026, January 29). UK Textiles Pact sets out ten-point plan for a mandatory textiles EPR scheme. https://www.fashioncapital.co.uk/insights/uk-textiles-pact-sets-out-ten-point-plan-for-a-mandatory-textiles-epr-scheme/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the clothing recycling market during 2026?
- What market size is projected by 2036?
- Which fiber type holds notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the clothing recycling market expected in 2026?
On FMI figures the clothing recycling market is expected to reach USD 8.8 billion in 2026, from USD 8.0 billion in 2025. Clothing recycling sales are projected to reach USD 24.4 billion by 2036.
What CAGR is projected for the clothing recycling market through 2036?
Clothing recycling market growth at a 10.7% CAGR from 2026 to 2036 is expected by FMI. Producer responsibility fees that fund collection and sorting carry that growth.
Which fiber type holds a notable market share in 2026?
An estimated 38.6% of fiber type sales in 2026 is expected to come from cotton. Polyester follows at about 33.4%.
Which end use holds a notable market share in 2026?
Apparel resold or remade is likely to hold an estimated 41.5% share in 2026. Non-woven uses follow at about 19.3%.
Which country has a notable expansion outlook through 2036?
India is projected to grow fastest among profiled countries, at a 12.1% CAGR. South Korea comes next at 11.1%.
Who are the key companies in the clothing recycling market?
Circulose, Lenzing, Birla Cellulose and Unifi are among the profiled recyclers and fibre makers. Worn Again Technologies, Loop Industries, Wolkat, Boer Group, American Textile Recycling Service and Patagonia complete the group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Fiber Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fiber Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fiber Type, 2026 to 2036
- Cotton
- Polyester
- Wool
- Nylon
- Other Fiber
- Y-o-Y Growth Trend Analysis By Fiber Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Fiber Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Apparel
- Non-Woven
- Industrial
- Home Furnishings
- Other
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Waste Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Waste Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Waste Type, 2026 to 2036
- Post-Consumer
- Pre-Consumer
- Y-o-Y Growth Trend Analysis By Waste Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Waste Type, 2026 to 2036
- Global Market Analysis and Forecast, By Recycling Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Recycling Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Recycling Type, 2026 to 2036
- Mechanical
- Chemical
- Y-o-Y Growth Trend Analysis By Recycling Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Recycling Type, 2026 to 2036
- Global Market Analysis and Forecast, By Collection Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Collection Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Collection Channel, 2026 to 2036
- Charity and Municipal Collection
- Retail and Brand Take-Back
- Online and Mail-Back
- Y-o-Y Growth Trend Analysis By Collection Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Collection Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Fiber Type
- By End Use
- By Waste Type
- By Recycling Type
- By Collection Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Circulose
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Birla Cellulose
- Unifi
- Lenzing
- Boer Group
- Worn Again Technologies
- Loop Industries
- Wolkat
- American Textile Recycling Service
- Patagonia
- Circulose
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


