

- Market Size (2026)
- USD 622.0 Mn
- Forecast (2036)
- USD 1584.2 Mn
- CAGR (2026 to 2036)
- 9.8%
How big is Croutons Market in 2026?
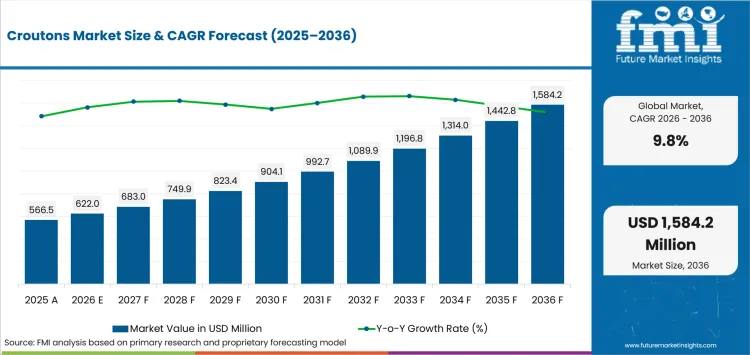
USD 622.0 million in 2026 and USD 1,584.2 million by 2036 at a 9.8% CAGR.
Sales of crouton is predicted to expand at a CAGR of 9.8% during the forecast period, as ready-to-use bread components remove cutting and seasoning work from restaurant kitchens. USA food-away-from-home activity gives that convenience a measurable outlet because USDA Economic Research Service reported in June 2026 that foodservice represented 56.3% of total food expenditures during 2025. Large bakers can apply production discipline from packaged bread programs to keep cube size and seasoning consistent through high-volume orders.
Country wise analysis changes pack economics because foodservice intensity differs sharply between mature grocery systems and hospitality-led markets. The UAE Ministry of Economy and Tourism stated in April 2026 that hotel guest nights increased 5.9% during 2025. Hotel kitchens therefore favor bulk cases and distributor replenishment while mature retail programs place more weight on shelf presentation and moisture control.
Key Takeaways of Croutons Market
- Ready-to-use croutons reduce bread preparation for restaurant kitchens and households while preserving a consistent texture cue in finished meals.
- By product type, classic - original is estimated to hold 37.0% in 2026 owing to a neutral seasoning profile that fits salads, soups and prepared meals.
- In 2026, conventional is expected to lead claim - nature with 44.0% share because familiar recipes keep formulation costs accessible for mainstream programs.
- Fresh is projected to hold 35.0% share in 2026 owing to frequent bakery and foodservice replenishment that protects a recently baked texture.
- Breakage and moisture exposure reduce usable product value before serving while higher delivered costs make a garnish easier to remove from value-sensitive orders.
- Some of the key players in this market include Sugar Foods LLC, The Marzetti Company, Olivia's Crouton Company, Inc., Croots Inc., Kooshy Inc., Legacy Bakehouse, NewPrinces S.p.A., and Darden Restaurants, Inc.
Analyst Perspective
"Crouton economics depend on how much saleable crunch survives case handling and storage. Repeat orders rise when cube size, seasoning adhesion, moisture protection and case cost fit the serving cycle of the intended retail or foodservice channel."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the croutons market segmented?
The croutons market is segmented by product type, claim - nature, format, packaging format, sales channel and region.
Product type includes classic - original, whole grain & seeded, flavored & filled, mini & snacking formats and premium / artisan. Claim - nature includes conventional, clean label, organic, gluten-free and high-protein / fortified. Format includes fresh, frozen, ambient packaged, chilled and par-baked / thaw-and-serve. Packaging format includes multipack, single-serve, family / loaf pack and bulk foodservice. Sales channel includes supermarkets & hypermarkets, artisan & specialty bakeries, convenience & forecourt, online & DTC and foodservice distributors.
What makes Classic - original central to the Product Type category?
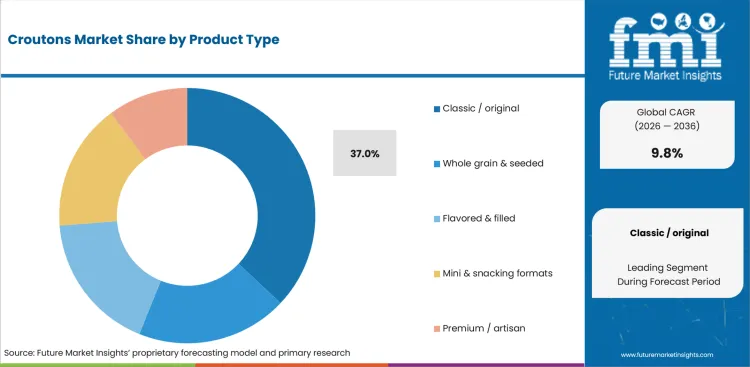
Classic recipes protect assortment productivity because mild seasoning fits soups and prepared meals without forcing a cuisine-specific use. Retailers can place a crouton beside breadcrumbs while keeping garnish demand inside one shelf set.
- By product type, classic - original is projected to account for 37.0% in 2026 due to broad meal compatibility and frequent replenishment in retail and foodservice.
- In August 2026, the Specialty Food Association named Croots Snacking Croutons among bite-sized products observed at its Summer Fancy Food Show. Snack-led formats therefore widen the category's use case while classic recipes retain broader meal compatibility.
Why does Conventional lead the Claim - nature category?
Conventional croutons lead because operators evaluate texture, taste and price before specialist claims. Alternative oils or certified ingredients can widen price gaps in the packaged food aisle and leave mainstream recipes with a simpler cost base.
- In 2026, conventional is expected to lead claim - nature with 44.0% share because familiar recipes serve broad channels with fewer formulation constraints.
- The FDA proposed front-of-package nutrition information in January 2025 for most packaged foods with visible levels for sodium and other nutrients. Conventional brands therefore need disciplined seasoning profiles and nutrition specifications without relying on organic or gluten-free positioning.
How does Fresh hold the lead in the Format category?
Fresh croutons fit bakery and foodservice routes that replenish often enough to protect recently baked texture. Extra holding time offers little value once moisture migration weakens crispness before service.
- Fresh is set to lead the format category with 35.0% share in 2026 due to route density and regular ordering that limit shorter-hold inventory risk.
- Sugar Foods announced in December 2025 that it secured a 617,000-square-foot Indiana production and distribution facility serving retail and foodservice customers. The facility expands logistics capacity for crouton programs that need consistent output and shorter replenishment windows.
What drives Supermarkets & Hypermarkets in the Sales Channel category?
Supermarkets and hypermarkets place croutons beside meal components already purchased during routine grocery trips. Shelf depth lets stores carry mainstream packs beside premium variants for several meal occasions within the wider salad dressings set.
- By sales channel, supermarkets & hypermarkets are forecast to represent 41.0% in 2026 driven by routine household visits that reduce replenishment effort.
- USDA Economic Research Service documented in August 2026 that grocery stores represented 56.2% of USA food-at-home sales during 2025. Grocery scale gives shelf-ready crouton packs repeated exposure beside meal components that already enter weekly baskets.
What are the drivers, restraints and opportunities in the Croutons Market?
Foodservice preparation savings increase demand while delivered-cost pressure limits discretionary garnish use and differentiated formats open higher-value buying occasions.
- Driver: Restaurant kitchens purchase croutons when the product replaces bread cutting and seasoning work without sacrificing the intended texture at service.
- Restraint: Higher foodservice prices and packaging costs weaken the economics of croutons when operators can remove the garnish without changing the core dish.
- Opportunity: Specialty formats can capture incremental orders when product claims or snack use create a reason to buy beyond routine salad preparation.
Restaurant Service Models Favor Ready-to-Use Texture
The commercial food service industry offers the significant repeat-use route because restaurants need ingredients ready for portioning during peak service. USDA Economic Research Service documented in July 2026 that full-service and limited-service restaurants represented 71.0% of USA food-away-from-home spending during 2025. High-volume accounts therefore favor stable cube size and seasoning because breakage raises usable cost just as sauces and condiments programs depend on case reliability.
Cost Pressure Raises the Garnish Removal Risk
Delivered cost becomes a restraint because croutons can disappear from a menu faster than core proteins or base ingredients. The USA Bureau of Labor Statistics reported in January 2026 that food-away-from-home prices increased 4.1% during 2025. Operators scrutinize breakage and stale product since unusable cubes raise serving cost while bakery ingredients must preserve texture without complicating formulation for operators.
Specialty Formats Extend the Purchase Occasion
Specialty formats earn incremental orders by changing the eating occasion instead of attaching a premium claim to the same use. At the 2026 Summer Fancy Food Show, Kooshy listed a new product beside its sourdough croutons and minis while confirming national distribution and foodservice readiness. Kooshy's broader format range extends snacking and menu programs, while frozen bakery portfolios illustrate how pack choice separates serving occasions.
Which country CAGRs are profiled in the Croutons Market?
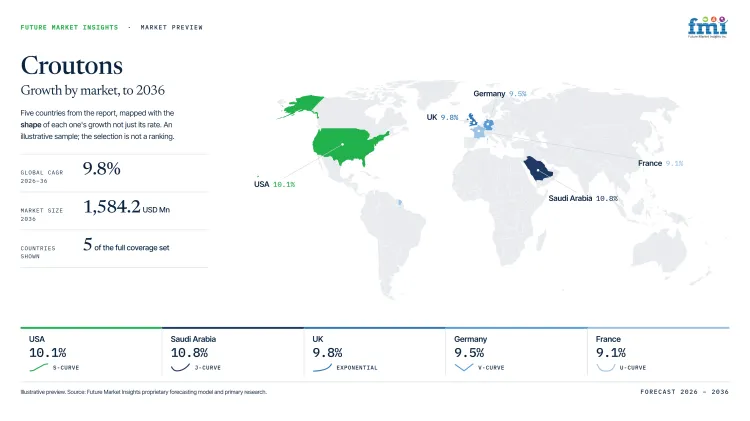
| Country | CAGR |
|---|---|
| Saudi Arabia | 10.8% |
| USA | 10.1% |
| UK | 9.8% |
| Germany | 9.5% |
| France | 9.1% |
How do country-level CAGRs compare in the Croutons Market?
The growth rates form a relatively narrow band, ranging from 9.1% in France to 10.8% in Saudi Arabia, with no significant outlier. Saudi Arabia and the USA lead the group, supported by expanding foodservice activity and broad distribution networks, while the UK, Germany, and France reflect steadier growth across mature grocery and restaurant channels.
- Saudi Arabia has strong demand for bulk crouton formats due to institutional catering, hospitality expansion, and large-scale foodservice operations.
- USA benefits from a large and diversified foodservice market, while extensive retail distribution creates additional opportunities for brands with strong shelf positioning.
- UK relies on established grocery and restaurant networks, making value differentiation, texture, and product quality important for premium positioning.
- Germany benefits from mature food retail and foodservice channels that favor consistent-quality croutons suited to established dining and packaged-food preferences.
- France sees growth through established restaurant and grocery channels, with product differentiation and quality supporting competition in the mature market.
Comparable CAGRs can conceal order-conversion constraints and entry requirements for new crouton brands. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Saudi Arabia is expected to record the fastest growth at 10.8% CAGR through 2036, supported by expanding hotel capacity, institutional catering, and foodservice activity. Demand for bulk crouton formats is likely to increase as hotel kitchens, buffet operations, and catering accounts expand across Riyadh, Jeddah, and pilgrimage centers. Seasonal occupancy peaks make reliable local warehousing and replenishment increasingly important for suppliers serving large hospitality accounts.
- USA crouton demand is projected to grow at 10.1% CAGR through 2036, supported by the scale of established grocery and restaurant channels. Competition among bread-based toppings makes texture retention, seasoning, and serving versatility important for securing shelf space and repeat purchases. Manufacturers that combine retail availability with efficient foodservice case formats can capture opportunities across both national grocery programs and restaurant accounts.
- UK demand is forecast to expand at 9.8% CAGR through 2036, reflecting the strength of established supermarket, restaurant, and pub networks. Mature purchasing systems place greater emphasis on cost efficiency, consistent quality, and clear product differentiation. Suppliers with practical case sizes, dependable replenishment, and a demonstrable texture or usage advantage are better positioned to compete during promotional and menu-planning cycles.
- Germany is expected to register 9.5% CAGR through 2036, with demand supported by established grocery distribution and foodservice consumption. The mature market favors dependable product quality, consistent texture, and efficient packaging rather than broad product proliferation. Suppliers can strengthen their position by aligning crouton formats with retail meal solutions and professional kitchen requirements while maintaining competitive pricing.
- France is projected to grow at 9.1% CAGR through 2036, supported by established restaurant, hospitality, and grocery channels. Product quality, flavor differentiation, and compatibility with salads, soups, and prepared meals can help suppliers gain visibility in a competitive market. Efficient distribution and appropriately sized foodservice packs are likely to remain important as buyers balance product differentiation with operating costs.
Who are the notable companies in the Croutons Market?
Sugar Foods LLC, The Marzetti Company, Olivia's Crouton Company, Inc., Croots Inc., Kooshy Inc., Legacy Bakehouse, NewPrinces S.p.A., and Darden Restaurants, Inc.
The field includes national topping manufacturers beside specialist crouton bakers, private-label producers and restaurant-linked licensors with different routes to recurring orders. Entry barriers come from texture control during distribution plus food-safety documentation and dependable account coverage rather than company scale alone.
- Sugar Foods LLC, The Marzetti Company and Darden Restaurants, Inc. reach grocery or foodservice accounts through branded toppings, bakery products and licensed restaurant channels.
- Olivia's Crouton Company, Inc., Kooshy Inc. and Legacy Bakehouse cover specialist crouton manufacturing through branded, private-label or foodservice programs.
- Croots Inc. concentrates on snack-led sourdough croutons while NewPrinces S.p.A. supplies retail and foodservice accounts through its United Kingdom bakery network.
Competitive Benchmarking: Croutons Market
| Company | Channel Coverage | Crouton Portfolio Breadth | Production / Qualification Depth | Geographic Reach |
|---|---|---|---|---|
| Sugar Foods LLC | High | High | High | North America |
| The Marzetti Company | High | Medium | High | United States |
| Olivia's Crouton Company, Inc. | High | High | High | United States and Canada |
| Croots Inc. | Medium | Medium | Low | Northeastern United States |
| Kooshy Inc. | High | High | Medium | United States |
| Legacy Bakehouse | High | High | High | United States |
| NewPrinces S.p.A. | Medium | Medium | High | United Kingdom and Europe |
| Darden Restaurants, Inc. | Medium | Low | Low | United States |
Scoring basis: High channel coverage requires documented retail, foodservice and private-label or licensing routes. Medium channel coverage requires two commercial routes while Low identifies one documented route. High crouton portfolio breadth requires at least three documented formats or claim routes while Medium requires two and Low identifies one. High production and qualification depth requires controlled manufacturing plus multiple documented quality systems while Medium reflects one manufacturing or qualification layer and Low reflects a licensing or single-route model.
Key Developments in the Croutons Market
- In September 2025, Sugar Foods LLC launched Fresh Gourmet salad toppings with Tajín Clásico including Chile Lime Seasoned Croutons for retail produce departments.
- In June 2026, Croots Inc. announced its expansion into Wegmans stores across the U.S. Northeast, extending its snackable sourdough croutons into additional retail locations.
- In July 2026, Darden Restaurants, Inc. filed its annual Form 10-K confirming licensed Olive Garden salad crouton distribution through wholesale and major grocery chains.
Key Players in the Croutons Market
Scaled Retail and Foodservice Platforms
- Sugar Foods LLC
- The Marzetti Company
Specialist Crouton Brands and Private-Label Producers
- Olivia's Crouton Company, Inc.
- Croots Inc.
- Kooshy Inc.
- Legacy Bakehouse
European Manufacturing and Licensed Restaurant Platforms
- NewPrinces S.p.A.
- Darden Restaurants, Inc.
Croutons Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, claim - nature, format, packaging format, sales channel and region. |
| Quantitative Units | USD Million. |
| Market Definition | Commercial revenue from finished croutons sold through retail, foodservice, bakery, convenience and online routes within the listed taxonomy. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | UAE, Saudi Arabia, South Korea, USA, UK, and 20+ countries included in the full report. |
| Key Companies Profiled | Sugar Foods LLC, The Marzetti Company, Olivia's Crouton Company, Inc., Croots Inc., Kooshy Inc., Legacy Bakehouse, NewPrinces S.p.A., and Darden Restaurants, Inc. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Croutons Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Croutons Market by Segments
Croutons Market segmented by Product Type:
- Classic - original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
Croutons Market segmented by Claim - nature:
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
Croutons Market segmented by Format:
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
Croutons Market segmented by Packaging Format:
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
Croutons Market segmented by Sales Channel:
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
Croutons Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- USA Department of Agriculture, Economic Research Service. (2026, June 11). Total USA food spending reached $2.51 trillion in 2025.
- Ministry of Economy and Tourism, UAE. (2026, April 13). Emirates Tourism Council discusses new action plans to enhance the growth and resilience of the sector in the coming period.
- Specialty Food Association. (2026, August 18). Farm-Fresh, Bite-Sized, Inside-Out: Specialty Food Association’s Trendspotter Panel Shares Top Trends from the 2026 Summer Fancy Food Show.
- USA Food and Drug Administration. (2025, January 14). FDA proposes requiring at-a-glance nutrition information on the front of packaged foods.
- Sugar Foods LLC. (2025, December 22). New Indiana Facility.
- USA Department of Agriculture, Economic Research Service. (2026, August 17). Retailing & Wholesaling - Retail Trends.
- USA Department of Agriculture, Economic Research Service. (2026, July 8). Food Service Industry - Market Segments.
- USA Bureau of Labor Statistics. (2026, January 13). Consumer Price Index News Release - 2025 M12 Results.
- Specialty Food Association. (2026). Kooshy Inc., 2026 Summer Fancy Food Show exhibitor profile. Retrieved August 24, 2026.
- Ministry of Economy and Tourism, UAE. (2026, February 8). Hospitality Advisory Council reviews its new initiatives for 2026 and underscores its role in driving growth and sustainability of the hotel sector.
- General Authority for Statistics, Saudi Arabia. (2026, January 8). GASTAT: Publishes Tourism Establishments Statistics for Q3 of 2025.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, March 29). 외식업 ‘매출 2억 5천만원’ 시대 열렸다 … 5년전 대비 41% 성장.
- USA Department of Agriculture, Economic Research Service. (2026, June 1). USA consumers spent 9.7 percent of their disposable personal income on food in 2025.
- Department for Environment, Food & Rural Affairs. (2026, July 29). Agriculture in the United Kingdom 2025: Chapter 14, The food chain.
- The Marzetti Company. (2025, August 21). 2025 Annual Report and Form 10-K.
- Specialty Food Association. (2026). Olivia's Crouton Co., Inc., 2026 Summer Fancy Food Show exhibitor profile. Retrieved August 24, 2026.
- Specialty Food Association. (2026). Croots Inc., 2026 Summer Fancy Food Show exhibitor profile. Retrieved August 24, 2026.
- Princes Group plc. (2026). Bradford: Baked Goods. Retrieved August 25, 2026.
- Legacy Bakehouse. (2025, February 5). Legacy Bakehouse Acquires Classic Cookie.
- Darden Restaurants, Inc. (2026, July 24). Annual Report on Form 10-K for the fiscal year ended May 31, 2026.
- Sugar Foods LLC. (2025, September 12). Fresh Gourmet & Tajín Clásico Team Up to Launch IrreZESTable Salad Toppings.
- Specialty Food Association. (2026, June 15). Olivia's Croutons Goes Seed Oil Free with Two New SKUs.
- Specialty Food Association. (2026, June 27). Croots Expands Into Wegmans as Brand Redefines the Crouton Category.
- The Marzetti Company. (2026, May 1). The Marzetti Company Completes Acquisition of Bachan’s Inc.
- Sugar Foods LLC. (2026, May 7). Sugar Food's Fresh Gourmet Crispy Dillies Bring Bold Crunch to Round Table Pizza's Dragon's Fire Feast.
- NewPrinces S.p.A. (2026, March 31). Annual Financial Report 2025.
- Darden Restaurants, Inc. (2025, July 18). Annual Report on Form 10-K for the fiscal year ended May 25, 2025.
This Report Answers
- What is the croutons market size in 2026 and what value is forecast by 2036?
- Which operating conditions convert foodservice activity into recurring crouton demand?
- Why does classic - original hold the leading position within product type?
- Why does conventional retain the largest share within claim - nature?
- Why does fresh lead the format category despite tighter inventory requirements?
- How do the five profiled country CAGRs differ between UAE and UK?
- Which eight companies have current evidence of direct participation in croutons?
- What packaging and channel conditions determine whether premium crouton formats earn repeat orders?
Frequently Asked Questions
How big is the croutons market in 2026?
The croutons market is valued at USD 622.0 million in 2026 and is projected to reach USD 1,584.2 million by 2036. Ready-to-use meal preparation and repeat foodservice purchasing reduce kitchen labor during busy service periods.
What is the CAGR of the croutons market from 2026 to 2036?
The croutons market is projected to grow at a CAGR of 9.8% between 2026 and 2036. Foodservice convenience and retail packs that protect texture support repeat purchasing through distribution.
Which product type leads the croutons market?
The classic - original segment is expected to hold 37.0% of the croutons market by product type in 2026, driven by mild seasoning that fits salads and soups. Its broad meal compatibility lowers cuisine-specific assortment risk for retailers and foodservice distributors.
Which claim - nature segment holds the largest current share in the croutons market?
The conventional segment is expected to hold 44.0% of the croutons market by claim - nature in 2026, attributable to familiar recipes and accessible formulation costs. Mainstream retail and foodservice programs can stock these recipes without specialist claim economics.
How much value is the croutons market expected to add between 2026 and 2036?
The croutons market is expected to add USD 962.2 million in value between 2026 and 2036. Repeat restaurant orders and retail packs that preserve crispness provide the main commercial route through grocery and foodservice channels.
Which countries are projected to record the highest growth in the croutons market?
UAE is projected to grow at 11.1% CAGR, followed by Saudi Arabia at 10.8% and South Korea at 10.4% through 2036. Hospitality expansion and ready-to-use restaurant inputs shape the upper growth band among the five profiled countries.
Which companies are active in the croutons market?
Key companies operating in the croutons market include Sugar Foods LLC, The Marzetti Company, Olivia's Crouton Company, Inc., Croots Inc., Kooshy Inc., Legacy Bakehouse, NewPrinces S.p.A., and Darden Restaurants, Inc. Their positions differ by channel reach and crouton specialization.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Classic / original
- Whole grain & seeded
- Flavored & filled
- Mini & snacking formats
- Premium / artisan
- Classic / original
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Claim / Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Claim / Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Claim / Nature, 2026 to 2036
- Conventional
- Clean label
- Organic
- Gluten-free
- High-protein / fortified
- Conventional
- Y-o-Y Growth Trend Analysis By Claim / Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim / Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Format, 2026 to 2036
- Fresh
- Frozen
- Ambient packaged
- Chilled
- Par-baked / thaw-and-serve
- Fresh
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packaging Format, 2026 to 2036
- Multipack
- Single-serve
- Family / loaf pack
- Bulk foodservice
- Multipack
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & hypermarkets
- Artisan & specialty bakeries
- Convenience & forecourt
- Online & DTC
- Foodservice distributors
- Supermarkets & hypermarkets
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Claim / Nature
- By Format
- By Packaging Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Grupo Bimbo
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Flowers Foods
- Aryzta
- Lantmannen Unibake
- Vandemoortele
- Yamazaki Baking
- Warburtons
- King's Hawaiian
- Europastry
- St Pierre Groupe
- Grupo Bimbo
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


