

- Market Size (2026)
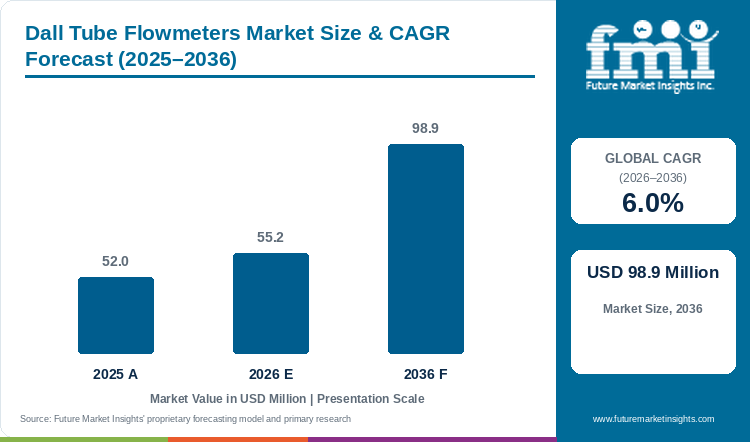
- USD 55.2 Mn
- Forecast (2036)
- USD 98.9 Mn
- CAGR (2026 to 2036)
- 6.0%
How big is Dall Tube Flowmeters Market in 2026?
Supported by an anticipated 6.0% ten-year CAGR, dall tube flowmeters demand is foreseen expanding above USD 52.0 million recorded for 2025 and USD 55.2 million estimated across 2026 toward USD 98.9 million projected through 2036.
Short-Lay-Length Flanged Cast/Fabricated Dall Tube assemblies are expected to claim 58.6% of construction format demand in 2026 because municipal water and desalination authorities need primary flow elements that bolt inside compact two-diameter underground vaults while recovering up to 97.5% of differential pressure. Global dall tube flowmeters expenditure is foreseen climbing above USD 52.0 million recorded in 2025 and an estimated USD 55.2 million across 2026 to attain a projected USD 98.9 million through 2036 on a predicted 6.0% CAGR, representing a USD 43.7 million increase in annual market revenue between 2026 and 2036. Developed by hydraulic engineer Horace E. Dall at George Kent Ltd., the Dall tube pairs a steep entrance cone and a slotted cylindrical throat with a truncated recovery diffuser to generate elevated differential head at a 0.65 to 0.70 discharge coefficient without inflicting the 40% to 95% permanent pressure drop of an orifice plate on megawatt booster pumps. In November 2025, the UK Environment Agency reported that water companies in England abstracted 14,637 million litres per day and supplied 13,946 million litres per day of distribution input during 2024 to 2025 while losing 18.77% to network leakage and 526 million litres per day across raw-water transport and treatment works alongside smart water metering networks [1].
Key Market Trends & Insights
- By construction format: Short-Lay-Length Flanged Cast/Fabricated Dall Tube (projected at 58.6% in 2026) leads procurement because flanged spools with a maximum 1.75D lay length bolt directly into compact underground metering chambers.
- By pipe diameter class: DN 300 to DN 1,200 Municipal & Industrial Trunk Mains (estimated at 54.0% in 2026) concentrates the largest revenue share across potable water distribution rings and industrial cooling headers.
- By end-use sector: Municipal Water Transmission & Desalination Plants (expected at 51.4% in 2026) drives utility spending as seawater reverse-osmosis plants prioritize ultra-low permanent head loss to cut high-pressure pump power bills.
Regional Highlights
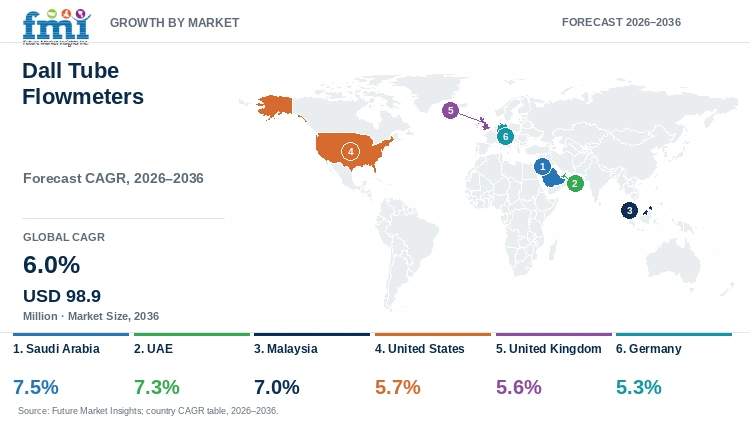
- Middle Eastern desalination leaders: Saudi Arabia leads desalination-focused nations at a projected 7.5% yearly growth rate, closely trailed by the UAE (estimated at 7.3%) on mega-scale reverse-osmosis aqueducts.
- Southeast Asian trunk-main upgrades: Malaysian utility orders are forecast to rise 7.0% annually through 2036 while federal non-revenue water programs replace aging cast-iron trunk meters.
- Western utility modernization: United States water authorities are predicted to grow 5.7% annually, ahead of anticipated British AMP8 water-network investments (5.6%) and German blast-furnace and municipal water loops (5.3%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Dall Tube Flowmeters Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| Market Value (2025) | USD 52.0 million |
| Market Value (2026) | USD 55.2 million |
| Forecast Value (2036) | USD 98.9 million |
| Absolute Dollar Opportunity (2026 to 2036) | USD 43.7 million |
| CAGR (2026 to 2036) | 6.0% |
Escalating municipal pumping electricity tariffs and multi-billion-dollar sovereign desalination buildouts across the Arabian Peninsula and North America are accelerating specification of ultra-low-loss differential-pressure tubes. U.S. Department of Energy Hydropower Market Reports updated in August 2026 tracked 80.25 GW of conventional U.S. hydro capacity and 43 pumped-storage plants alongside 167 FERC-licensed projects totaling 8 GW undergoing relicensing penstock and cooling upgrades [2]. When a 1,000-millimeter trunk main operates 8,760 hours per year, substituting an orifice plate with a short-lay-length Dall tube paired with expansion valves is estimated to recover tens of kilowatts of continuous hydraulic power and pay back the primary element within 14 to 22 months.
Trunk-Main Installations and Lay-Length Economics
Table 2: Shipped Dall Tubes and Hydraulic Performance Indicators for the Dall Tube Flowmeters Market (USD million, units, and USD per tube), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 52.0 | 55.2 | 98.9 |
| Annual shipped Dall tubes & Dall short inserts (units) | 3,850 to 4,300 | 4,050 to 4,550 | 6,650 to 7,450 |
| Large-bore >DN 1,200 aqueduct & condenser builds (units) | 620 to 710 | 660 to 750 | 1,180 to 1,340 |
| Average realized factory price (USD per unit) | 12,100 to 13,500 | 12,250 to 13,650 | 13,200 to 14,850 |
Operational note: Shipped unit figures encompass flanged carbon-steel and 316 stainless-steel Dall tubes (standard 150 mm to 600 mm, custom to 2,400 mm) alongside wafer-mounted Dall Short Inserts (0.3D length, 150 mm to 1,000 mm).
Water utilities across Britain and Commonwealth nations as well as the Middle East maintain thousands of underground Kent-heritage Dall tube chambers installed on strategic reservoir trunk mains. In January 2026, Ofwat published its updated national leakage dataset tracking annual average water distribution leakage across England and Wales from 1992-93 to 2024-25, reinforcing statutory five-year AMP8 targets to cut distribution losses through bulk trunk-main district metering [3]. Rather than excavating and enlarging concrete chambers to fit long venturi tubes, utility engineers specify drop-in flanged Dall tubes alongside centrifugal water pumps to upgrade bulk flow telemetry within existing vault dimensions.
Desalination & Utility Head-Loss Benchmarks
Table 3: Utility Spend and Head-Loss Recovery Indicators for the Dall Tube Flowmeters Market (USD and hydraulic metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global municipal trunk-main & desalination authorities (sites) | 3,100 | 3,180 | 3,750 |
| Average annual Dall tube spend per authority (USD) | 16,774 | 17,358 | 26,373 |
| Permanent pressure loss (% of differential head ΔP, Dall Tube) | 2.5% to 8.0% | 2.5% to 8.0% | 2.5% to 7.5% |
| Maximum Dall Tube lay length in pipe diameters (L / D) | 1.5D to 1.75D | 1.5D to 1.75D | 1.5D to 1.75D |
Table 4: Operational Benchmark Traceability for the Dall Tube Flowmeters Market (USD and percentages), 2025 to 2026
| Benchmark Indicator | Reported / Modeled Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 55.2 million | 2026 market baseline |
| Short-lay-length flanged Dall tube revenue, 2026 | USD 32.3 million | 58.6% construction format share |
| DN 300 to DN 1,200 trunk-main revenue, 2026 | USD 29.8 million | 54.0% pipe diameter share |
| Municipal water & desalination plant revenue, 2026 | USD 28.4 million | 51.4% end-use sector share |
Because flow curvature over the sharp throat slot adds radial streamline acceleration to Bernoullian velocity head, a Dall tube generates up to double the differential pressure of a classical venturi at identical beta ratio (0.3 to 0.8). Desalination plant engineers pairing gunmetal- or duplex-throttled Dall tubes with smart electric meters track specific kilowatt-hour consumption per cubic meter of permeate water across high-pressure booster trains.
Analyst Perspective
"Dall tubes deliver the lowest permanent pressure loss per unit of differential head among mechanical primary elements while fitting into half the vault length of a classical venturi. Manufacturers supplying corrosion-resistant duplex and epoxy-lined Dall tubes for DN 600+ desalination aqueducts are projected to secure long-term utility framework contracts."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the dall tube flowmeters market segmented?
The dall tube flowmeters market is segmented by construction format, pipe diameter class, end-use sector, and region. In 2026, Short-Lay-Length Flanged Cast/Fabricated Dall Tube is projected at 58.6%, DN 300 to DN 1,200 Municipal & Industrial Trunk Mains at 54.0%, and Municipal Water Transmission & Desalination Plants at 51.4%.
By construction format: Short-Lay-Length Flanged Cast/Fabricated Dall Tube, Weld-In Dall Liner / Insert for Large Mains, and Epoxy-Lined Ductile-Iron & Composite Dall Tubes.
By pipe diameter class: DN 300 to DN 1,200 Municipal & Industrial Trunk Mains, >DN 1,200 Desalination & Raw Water Aqueducts, and DN 150 to DN 300 Process Plant Headers.
By end-use sector: Municipal Water Transmission & Desalination Plants, Hydroelectric & Thermal Power Condenser Loops, and Large-Bore Natural Gas & Blast-Furnace Air Mains.
Why Does Short-Lay-Length Flanged Cast/Fabricated Dall Tube Lead Construction Format?
Short-Lay-Length Flanged Cast/Fabricated Dall Tube garners 58.6% of construction format in 2026, aided by compact vault installation footprints.
Table 5: Construction Format Share for the Dall Tube Flowmeters Market (percentage share), 2026
| Construction Format Segment | Share (2026) |
|---|---|
| Short-Lay-Length Flanged Cast/Fabricated Dall Tube | 58.6% |
| Weld-In Dall Liner / Insert for Large Mains | 27.4% |
| Epoxy-Lined Ductile-Iron & Composite Dall Tubes | 14.0%* |
| Total | 100.0% |
*Note: Combined share of remaining construction format categories totaling 100.0% of 2026 market demand.
Table 6: Construction Format Leadership and Market Growth for the Dall Tube Flowmeters Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Short-Lay-Length Flanged Cast/Fabricated Dall Tube |
Whereas a classical Herschel venturi tube requires an elongated diffuser cone spanning six to eight pipe diameters, the Dall tube's internal profile and annular throat tapping points produce almost no vena contracta while keeping overall lay length to a maximum of 1.75 times the pipe diameter. Casting or fabricating this profile inside a self-contained double-flanged spool piece allows utility crews to bolt the meter directly between standard BS or AWWA alongside EN 1092 flanges inside cramped underground concrete vaults. Water authorities integrating flanged Dall spools with electric sub-meters avoid costly civil vault extensions during reservoir outlet upgrades.
- Slated to secure 58.6% of 2026 construction format revenue, Short-Lay-Length Flanged Cast/Fabricated Dall Tube units cut civil chamber excavation volume by up to 60% compared with long-pattern venturis.
- ABB Ltd.'s Differential Pressure Flow Elements technical datasheet SS/DP_2 documents Kent-developed Dall Tubes (150 to 600 mm standard and custom larger bores, +/-0.5% calibrated accuracy, and 2.5% to 8% differential head loss) alongside wafer-mounted Dall Short Inserts (0.3D length) [4].
What Places DN 300 to DN 1,200 Municipal & Industrial Trunk Mains First by Pipe Diameter Class?
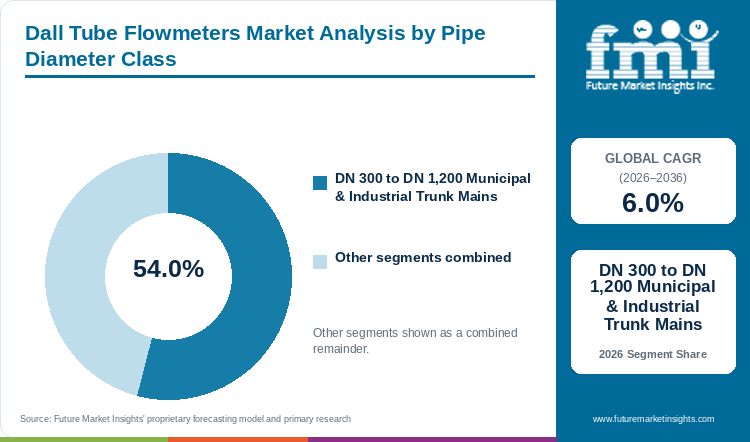
DN 300 to DN 1,200 Municipal & Industrial Trunk Mains reaches 54.0% of pipe diameter class in 2026, benefiting from aqueduct upgrades.
Below DN 150, standard orifice plates or full-bore electromagnetic meters are cheaper to purchase and install, whereas above DN 1,200 projects occur in smaller unit batches for mega-aqueducts. Trunk distribution mains between 300 millimeters and 1,200 millimeters carry primary bulk water and blast-furnace air volumes where permanent head loss directly inflates megawatt pumping and blower electricity bills. In the core DN 300 to DN 1,200 band, utilities pairing Dall tubes with industrial water treatment systems and regional booster stations achieve zero-moving-part reliability over 40-year service lives.
- In the competing low-loss Venturi segment, Rhode Island-based Primary Flow Signal detailed its NSF-61 potable-water-coated HVT-CI and HVT-DI cast and ductile-iron Venturi flow tubes in January 2026 across pipe bores from 4 to 96 inches [5].
- DN 300 to DN 1,200 Municipal & Industrial Trunk Mains are foreseen accounting for 54.0% of 2026 diameter-class orders as cities segment bulk transmission rings into district metered areas.
How Do Municipal Water Transmission & Desalination Plants Anchor the End-Use Sector?
Municipal Water Transmission & Desalination Plants posts 51.4% of end-use sector in 2026, accompanied by continuous pumping electricity savings.
Because a Dall tube contains no submerged electrodes or delicate ultrasonic transducers that drift in aerated water, desalination engineers specify bronze- or super-duplex-throttled Dall tubes on raw seawater intake and potable export mains. Seawater reverse-osmosis desalination plants and inter-basin municipal aqueducts run at high load factors year-round, making every millibar of unrecovered head loss across a flow primary element a compounding 25-year operating expense. Operators linking bulk Dall tube flow loops with automated control system platforms balance high-lift pump stations against reservoir storage levels in real time.
- Expected to account for 51.4% of 2026 end-use sector sales, Municipal Water Transmission & Desalination Plants favor Dall tubes for their 92% to 97.5% differential head recovery.
- In February 2026, Dubai Electricity and Water Authority PJSC (DEWA) reported record 2025 desalinated water demand of 161.505 Billion Imperial Gallons (+6.62% YoY) and 495 MIGD of installed desalination capacity en route to 735 MIGD by 2030 [6].
What are the drivers, restraints, and opportunities in the dall tube flowmeters market?
Large-bore desalination aqueducts and AMP8 leakage-reduction trunk metering are projected to propel dall tube flowmeters demand through 2036, whereas suspended-solids fouling of the sharp throat slot restrains raw-sewage use and weld-in Dall liners create high-value rehabilitation opportunities.
- Driver: Sovereign desalination mega-projects and municipal trunk-main energy-efficiency mandates drive demand for short-lay-length Dall tubes that cut permanent pumping head loss to 2.5% to 8% of differential pressure.
- Restraint: Fibrous ragging alongside heavy silt in unscreened raw sewage or dirty slurries can foul the sharp annular throat slot and require minimum Reynolds numbers above 100,000.
- Opportunity: Supplying pre-machined weld-in Dall Short Inserts and corrosion-proof super-duplex throat liners is anticipated to enable utilities to rehabilitate aging concrete and steel aqueducts without replacing outer pipe shells.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Decarbonizing municipal water utilities and scaling low-carbon reverse-osmosis desalination across the Arabian Gulf and Americas require bulk primary flow elements that minimize lifetime pumping kilowatt-hours. In January 2026, Badger Meter reported record full-year 2025 revenue of USD 916.7 million (+11% YoY) alongside a multi-year Puerto Rico Aqueduct and Sewer Authority (PRASA) award as utilities scaled non-revenue water and transmission monitoring [7]. When EPC contractors design 500,000-cubic-meter-per-day potable water transmission mains using general flow metering instruments, specifying fabricated Dall tubes instead of orifice plates or long venturis saves both valve-chamber concrete costs and continuous booster-pump electricity.
Risk Assessment of the Dall Tube Flowmeters Market: Operational and Formulation Friction
Unlike smooth-throated classical venturi tubes, the Dall tube relies on an open annular slot at the throat between the inlet and outlet cones plus sharp break-away edges that can trap fibrous debris or erode in sand-laden raw water. In March 2026, the UK water regulator Ofwat published its economic impact assessment covering 30 major water supply infrastructure schemes totaling GBP 49,684 million in whole-life TOTEX, noting rigorous capital-efficiency scrutiny across utility pipeline investments [8]. Furthermore, because the Dall discharge coefficient drops off below Reynolds numbers of 100,000 to 200,000, engineers designing pre-treatment headers ahead of membrane filtration systems or raw-sewage force mains frequently select full-bore electromagnetic meters when suspended solids are present.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Flow-element manufacturers are capturing lucrative rehabilitation contracts by supplying drop-in Dall Short Inserts and weld-in liners machined from 316L stainless steel or super-duplex alloy 2507 paired with dual-range smart DP transmitters. Introduced in February 2026, the OpreX EJX S Series from Yokogawa Electric Corporation provides IP68 protection alongside PROFINET connectivity and +/-0.1% twenty-year stability across bulk water flow tubes [9]. Inserting a precision-machined Dall liner inside an existing DN 1,000 steel aqueduct or blast-furnace header alongside industrial air filtration systems avoids excavating the main and upgrades bulk custody-transfer accuracy within a 48-hour outage window.
Dall Tube Flowmeters Market by Country (2026 to 2036)
Saudi Arabia ranks first among key desalination and water-utility markets with an anticipated 7.5% ten-year CAGR to 2036, just ahead of the UAE (estimated at 7.3%) and Malaysia (forecast at 7.0%) on large-bore desalination and non-revenue water trunk-main projects. Across established Western utility grids, United States aqueduct rehabilitations are expected to expand 5.7% annually while British water companies (predicted at 5.6%) and German industrial headers (anticipated at 5.3%) record steady upgrades.
Table 7: Country CAGR and Primary Growth Levers for the Dall Tube Flowmeters Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 7.5% | Red Sea and Arabian Gulf SWRO desalination plants and national strategic water transmission pipes |
| UAE | 7.3% | Dubai 735 MIGD SWRO expansion and Abu Dhabi low-carbon reverse-osmosis trunk headers |
| Malaysia | 7.0% | Air Selangor 26.76% Non-Revenue Water trunk-main upgrades and Rasau Water Supply Scheme |
| United States | 5.7% | Municipal aqueduct rehabilitations, 44.9 Bcf/d gas mains, and hydroelectric condenser loops |
| United Kingdom | 5.6% | Ofwat AMP8 RAPID strategic water grid interconnectors and Kent-heritage Dall chamber upgrades |
| Germany | 5.3% | Integrated steelworks blast-furnace air mains and municipal drinking-water ring headers |
Source: Future Market Insights analysis
Saudi Arabia Dall Tube Flowmeters Market Outlook (2026 to 2036)
Unlike surface-fed global utilities that rely on gravity aqueducts, Saudi Arabia pumps desalinated Red Sea and Arabian Gulf water hundreds of kilometers inland across high-elevation desert transmission corridors where every millibar of head loss inflates megawatt pumping bills. Speaking at the 25th WPC Energy Conference in Riyadh during October 2026, Aramco chief Amin H. Nasser detailed how the Kingdom's Master Gas System powers coastal desalination and industrial utilities while noting that over 90% of materials used during an 11-day post-disruption restoration came from local manufacturers [10]. Saudi Dall tube expenditure is expected to climb 7.5% per annum through 2036. Fabricators supplying epoxy-coated carbon-steel bodies with super-duplex UNS S32750 Dall throat inserts win aqueduct contracts.
Key takeaway: In Saudi Arabia, mega-scale SWRO desalination aqueducts and super-duplex throat specifications are expected to fuel 7.5% yearly expansion through 2036.
UAE Dall Tube Flowmeters Market Outlook (2026 to 2036)
In October 2025, the International Energy Agency's Gas 2025 report documented Middle Eastern gas-to-power efficiency and the transition from thermal cogeneration desalination toward standalone reverse-osmosis water plants and industrial gas grids [11]. UAE Dall tube turnover is estimated to rise by 7.3% yearly across 2026 to 2036 while utilities instrument DN 800 to DN 1,800 potable water and recycled-water mains. What distinguishes the Emirates from conventional municipal water markets is its rapid decoupling of seawater reverse osmosis from thermal power plants alongside Dubai's expansion toward 735 MIGD of desalinated water capacity by 2030. To withstand high coastal vault temperatures and bio-fouling, suppliers deliver AWWA-flanged Dall tubes with flushing annular-slot rings.
Key takeaway: In the UAE, standalone reverse-osmosis mega-plants and bulk water-reuse transmission mains are estimated to sustain a 7.3% CAGR until 2036.
Malaysia Dall Tube Flowmeters Market Outlook (2026 to 2036)
Malaysian Dall tube demand is forecast to climb 7.0% annually across the 2026-2036 horizon while state water operators replace aging Commonwealth-era Kent mechanical recorders and corroded trunk-main venturis. Unlike greenfield desert networks, Malaysia's water grid combines legacy British BS 1042 underground chambers across Selangor and Penang with surging industrial water headers serving hyperscale data centers. In August 2026, Malaysia's largest water utility Air Selangor (serving 9.62 million consumers) reported reducing Non-Revenue Water to 26.76% in 2025 (saving 301.3 million litres per day) alongside the Rasau Water Supply Scheme [12]. Because tropical river silt can plug unpurged throat slots, vendors supply flanged Dall tubes with sediment-purge valves and GSM DP totalizers.
Key takeaway: In Malaysia, Air Selangor non-revenue water trunk-main replacements and industrial water grids are forecast to drive 7.0% annual growth through 2036.
United States Dall Tube Flowmeters Market Outlook (2026 to 2036)
American municipal water districts and pipeline operators differ from overseas buyers because engineers must fit replacement primary elements inside century-old metropolitan vaults while complying with strict federal lead-free alloy statutes. U.S. EIA pipeline project data from May 2026 documented 44.9 billion cubic feet per day of new large-diameter U.S. natural gas transmission capacity scheduled for 2026 and 2027 (31.6 Bcf/d under construction) alongside municipal trunk upgrades [13]. United States Dall tube revenue is expected to grow by 5.7% per annum until 2036 while water districts and gas headers retrofit underground valve chambers where long-pattern venturis cannot fit. Domestic fabricators machine NSF-61 certified 316L stainless and epoxy-lined ductile-iron Dall tubes.
Key takeaway: In the United States, municipal aqueduct rehabilitations and NSF-61 stainless Dall liners are expected to support 5.7% yearly growth through 2036.
United Kingdom Dall Tube Flowmeters Market Outlook (2026 to 2036)
As the birthplace of the George Kent Ltd. Dall tube in Luton during the 1950s, the United Kingdom possesses the world's densest installed base of legacy municipal Dall tubes and weld-in Dall inserts across reservoir trunk mains. In June 2025, the UK water regulator Ofwat announced over GBP 2 billion in AMP8 development funding across 28 RAPID major water-transfer schemes supporting GBP 50 billion in long-term drought-resilience infrastructure [14]. British Dall tube shipments are predicted to grow at a 5.6% yearly rate from 2026 through 2036 as utilities execute AMP8 trunk-main leakage monitoring and refurbish 1970s cast-iron Dall chambers. To satisfy DWI Regulation 31 approvals, UK fabricators supply stainless weld-in Dall liners.
Key takeaway: In the United Kingdom, AMP8 strategic water-grid interconnectors and Kent-heritage chamber refurbishments are predicted to power 5.6% yearly growth through 2036.
Germany Dall Tube Flowmeters Market Outlook (2026 to 2036)
Unlike Middle Eastern desalination markets, German demand splits between large-bore blast-furnace cold-blast air mains in Duisburg and Salzgitter and inter-municipal long-distance drinking-water associations (Fernwasserversorgung) in Baden-Württemberg and Saxony. German Dall tube demand is anticipated to increase 5.3% per annum between 2026 and 2036 across DN 500 to DN 1,600 industrial gas and potable water trunk mains. USGS Iron Ore Statistics updated in June 2026 confirmed that 98% of global iron ore output feeds blast-furnace steelmaking where European metallurgical works intensify blower-efficiency and air-main energy-recovery retrofits [15]. Although strict DVGW W 270 hygiene testing and DIN EN 1092 flange tolerances lengthen custom fabrication lead times, European manufacturers win contracts with DVGW-compliant fabricated steel Dall tubes.
Key takeaway: In Germany, steelworks blast-furnace air mains and DVGW-certified regional water aqueducts are anticipated to support a 5.3% CAGR until 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the dall tube flowmeters market?
ABB Ltd. (Kent / Taylor Dall Tube Heritage), Primary Flow Signal, Inc., Solartron ISA (AMETEK, Inc.), KROHNE Messtechnik GmbH, Tekflo Sensors Ltd., SEIKOM Electronic GmbH & Co. KG, WIKA Alexander Wiegand SE & Co. KG, and Emerson Electric Co. are the notable companies in the dall tube flowmeters market.
Competitive structure in the Dall tube flowmeters market spans the original British developer of the Dall tube alongside custom low-loss differential-pressure primary-element fabricators and providers of secondary DP transmitters and adjacent thermal duct monitors. ABB Ltd. (which absorbed George Kent Ltd., where hydraulic engineer Horace E. Dall invented the Dall Tube and wafer-mounted Dall Short Insert) and WIKA SE (Euromisure) supply documented ISO 5167 and BS 1042 differential-pressure primary flow elements alongside secondary transmitters. Custom differential-pressure flow-tube specialists Primary Flow Signal and Solartron ISA (AMETEK) alongside Tekflo Sensors Pte Ltd engineer large-bore low-head-loss Venturi and differential-pressure flow tubes and multivariable DP transmitters for water and energy pipelines. Meanwhile, KROHNE Messtechnik GmbH alongside Emerson Electric Co. supplies secondary DP transmitters and competing full-bore trunk-main meters, whereas SEIKOM Electronic GmbH & Co. KG provides adjacent calorimetric/thermal air-and-gas flow monitors (such as its RLSW9 sensor) and electronic DP switches for industrial ducts.
- Confirmed Dall Tube Heritage & Custom DP Primary Element Leaders: ABB Ltd. (Kent / Taylor Dall Tube and Dall Short Insert manufacturer) alongside WIKA SE and Tekflo Sensors supplies documented Dall and low-loss differential-pressure primary elements.
- Competing Low-Loss Venturi & Large-Bore DP Tube Specialists: Primary Flow Signal (HVT-CI and HVT-DI Venturi meters) alongside Solartron ISA (AMETEK Dualstream wet-gas Venturi) engineers competing Venturi flow tubes for water and gas mains.
- Secondary DP Transmitter & Adjacent Thermal / EM Flow Providers: KROHNE Messtechnik GmbH alongside Emerson Electric Co. supplies smart DP transmitters and competing flowmeters, while SEIKOM Electronic GmbH & Co. KG supplies adjacent calorimetric/thermal gas velocity monitors (RLSW9) and DP switches.
Competitive Benchmarking: Dall Tube Flowmeters Market
Table 8: Competitive Benchmarking for the Dall Tube Flowmeters Market (qualitative capability ratings), 2026
| Company | In-Scope Dall Tube / Insert Offering | Potable Water & Desalination Certifications | Low-Loss Head Recovery Engineering | Global Utility Installed Base |
|---|---|---|---|---|
| ABB Ltd. (Kent Dall Tube Heritage) | High | High | High | High |
| WIKA Alexander Wiegand SE | Medium | High | High | High |
| Tekflo Sensors | Medium | High | High | Medium |
| Primary Flow Signal (Competing Venturi) | Low | High | High | High |
| Solartron ISA (Competing Venturi) | Low | Medium | High | High |
| KROHNE Messtechnik GmbH | Low | High | High | High |
| Emerson Electric Co. | Low | High | High | High |
| SEIKOM Electronic (Adjacent Thermal) | Low | Low | Low | Medium |
Scoring basis: In-Scope Dall Tube / Insert Offering is scored High where a manufacturer explicitly documents Dall Tube and Dall Short Insert production in its technical catalog (ABB Ltd. per datasheet SS/DP_2) and Medium for custom DP primary-element fabricators (WIKA and Tekflo). Companies receive a Low rating on Dall tube fabrication when supplying competing Venturi tubes (Primary Flow Signal and Solartron ISA) or secondary transmitters and adjacent calorimetric/thermal gas flow sensors (SEIKOM Electronic RLSW9). Potable Water & Desalination Certifications evaluates documented NSF/ANSI 61 or DWI Reg 31 alongside DVGW and AWWA coating compliance. Low-Loss Head Recovery Engineering reflects verified primary-element profiles that hold permanent head loss below 8% of differential pressure.
Key Developments in the Dall Tube Flowmeters Market
- KROHNE Group rolled out its upgraded IFC 400 flow signal processing platform in May 2026 and its AI-enhanced PipePatrol NEO pipeline monitoring system in July 2026 for large-bore water and industrial trunk mains [16].
- In May 2026, Solartron ISA parent company AMETEK, Inc. announced a USD 5.0 billion definitive agreement to acquire Indicor Instrumentation (USD 1.1 billion annual revenue) to expand its Electronic Instruments Group specialty flow portfolio [17].
- In the competing wet-gas Venturi segment, Solartron ISA (AMETEK, Inc.) detailed its ISO 5167-4 and ASME MFC-19G Dualstream differential-pressure primary element assemblies in January 2026 delivering 0.15% repeatability alongside >8:1 turndown and <1 bar permanent pressure loss [18].
Key Players in the Dall Tube Flowmeters Market
Confirmed Dall Tube Heritage & Custom DP Primary Element Leaders
- ABB Ltd. (Kent / Taylor Dall Tube Heritage)
- WIKA Alexander Wiegand SE & Co. KG
- Tekflo Sensors Ltd.
Competing Low-Loss Venturi & Large-Bore DP Tube Specialists
- Primary Flow Signal, Inc.
- Solartron ISA (AMETEK, Inc.)
Secondary DP Transmitter & Adjacent Thermal / EM Flow Providers
- KROHNE Messtechnik GmbH
- Emerson Electric Co.
- SEIKOM Electronic GmbH & Co. KG
Dall Tube Flowmeters Market - Report Scope
Table 9: Report Scope for the Dall Tube Flowmeters Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Construction Format; Pipe Diameter Class; End-Use Sector; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes manufacturer revenue from Dall tube differential-pressure flowmeters, encompassing short-lay-length double-flanged cast and fabricated Dall tubes (up to 1.75D length), wafer-mounted Dall Short Inserts (0.3D length) and weld-in Dall liners for large-bore mains, epoxy-lined ductile-iron and composite Dall spools, and bundled DP transmitter/manifold assemblies. Category Scope Note: The valuation covers closed-conduit Dall tube and Dall insert primary flow elements from DN 150 to >DN 2,000, excluding open-channel Parshall/Venturi flumes, competing long-pattern Herschel venturi tubes (such as Primary Flow Signal HVT-CI/DI and Solartron Dualstream), orifice plates, and adjacent calorimetric/thermal air-duct flow monitors (such as SEIKOM RLSW9). |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, UAE, Malaysia, United States, United Kingdom, Germany, and additional countries in the full report |
| Key Companies Covered | ABB Ltd. (Kent / Taylor Dall Tube Heritage), Primary Flow Signal, Inc., Solartron ISA (AMETEK, Inc.), KROHNE Messtechnik GmbH, Tekflo Sensors Ltd., SEIKOM Electronic GmbH & Co. KG, WIKA Alexander Wiegand SE & Co. KG, Emerson Electric Co. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Dall Tube Flowmeters Market - Research Methodology
Table 10: Research Methodology for the Dall Tube Flowmeters Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with municipal water-grid hydraulic engineers, SWRO desalination plant designers, hydroelectric condenser leads, and UK/U.S. primary-element fabricators to validate Dall throat-slot tolerances, lay-length savings, and head-loss payback periods. |
| Secondary Research | Secondary research included BS 1042 / ISO 5167 differential-pressure flow documentation, ABB Differential Pressure Flow Elements datasheet SS/DP_2 (covering Dall Tubes and Dall Short Inserts), Ofwat AMP8 and UK Environment Agency water infrastructure filings, and DEWA and Air Selangor utility reports. |
| Market Sizing and Forecasting | Market sizing and forecasting from 2026 to 2036 combined bottom-up unit volumes across DN 150-300, DN 300-1,200, and >DN 1,200 pipe diameter classes with top-down municipal water transmission, desalination, and power-condenser instrumentation budgets. |
| Data Triangulation and Validation | Market totals were triangulated against municipal trunk-main replacement schedules, SWRO desalination capacity additions (million m3/day), and vendor primary-element order books to exclude competing Herschel venturis, electromagnetic flowmeters, and calorimetric/thermal duct monitors. |
| Country Forecasting Model | Country CAGRs are projected around the 6.0% global baseline using econometric weights for contracted SWRO desalination capacity, regulatory non-revenue water (NRW) reduction funding, trunk-main chamber refurbishments, and industrial air/gas header upgrades. |
| Operational Benchmark Traceability | Hydraulic and commercial indicators in Tables 2, 3, and 4 (shipped Dall tube units, 1.5D-1.75D lay lengths, and 2.5%-8.0% permanent pressure loss) trace to ABB / George Kent SS/DP_2 hydraulic laboratory curves, Ofwat leakage datasets, and OEM engineering specifications. |
Dall Tube Flowmeters Market by Segments
By Construction Format
- Short-Lay-Length Flanged Cast/Fabricated Dall Tube
- Weld-In Dall Liner / Insert for Large Mains
- Epoxy-Lined Ductile-Iron & Composite Dall Tubes
By Pipe Diameter Class
- DN 300 to DN 1,200 Municipal & Industrial Trunk Mains
- >DN 1,200 Desalination & Raw Water Aqueducts
- DN 150 to DN 300 Process Plant Headers
By End-Use Sector
- Municipal Water Transmission & Desalination Plants
- Hydroelectric & Thermal Power Condenser Loops
- Large-Bore Natural Gas & Blast-Furnace Air Mains
Dall Tube Flowmeters Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Environment Agency. (2025, November 18). Water resources 2024 to 2025: analysis of the water industry's annual water resources performance. GOV.UK.
- [2] U.S. Department of Energy (DOE). (2026, August 28). Hydropower Market Reports. Hydropower and Hydrokinetic Office.
- [3] Office of Water Services (Ofwat). (2026, January 07). Leakage Dataset - November 2025. Ofwat.
- [4] ABB Ltd. (2025, May 21). Differential Pressure Flow Elements (Data Sheet SS/DP_2: Dall Tube and Dall Short Insert). ABB Measurement & Analytics.
- [5] Primary Flow Signal, Inc. (2026, January 20). Ductile Iron & Cast Iron Flow Meters (HVT-CI/DI). Primary Flow Signal, Inc.
- [6] Dubai Electricity and Water Authority PJSC (DEWA). (2026, February 10). Dubai Electricity and Water Authority PJSC announces record annual revenue of AED 32.84 billion, operating profit of AED 10.99 billion and an unprecedented EBITDA of AED 17.37 billion for 2025. Government of Dubai.
- [7] Badger Meter, Inc. (2026, January 28). Badger Meter Reports Fourth Quarter and Full Year 2025 Financial Results. Badger Meter Investor Relations.
- [8] Office of Water Services (Ofwat). (2026, March 01). Economic Impact of Water Supply Infrastructure Investment. Ofwat.
- [9] Yokogawa Electric Corporation. (2026, February 26). Yokogawa Releases OpreX Pressure Transmitter EJX S Series. Yokogawa Electric Corporation.
- [10] Saudi Arabian Oil Company (Aramco). (2026, October 12). Remarks by Amin H. Nasser at the 25th WPC Energy Conference in Riyadh. Aramco.
- [11] International Energy Agency (IEA). (2025, October 27). Gas 2025. International Energy Agency.
- [12] Pengurusan Air Selangor Sdn. Bhd. (Air Selangor). (2026, August 21). Driving Water Sustainability: Key Highlights from the Air Selangor Sustainability Report 2025. Air Selangor Hydro Hub.
- [13] U.S. Energy Information Administration (EIA). (2026, May 26). Most planned natural gas pipeline capacity additions in 2026 and 2027 originate in Texas. U.S. Department of Energy.
- [14] Office of Water Services (Ofwat). (2025, June 17). RAPID action on major water infrastructure is securing supply for future generations. Ofwat.
- [15] U.S. Geological Survey (USGS). (2026, June 01). Iron Ore Statistics and Information. National Minerals Information Center.
- [16] KROHNE Messtechnik GmbH. (2026, September 03). News | KROHNE Group. KROHNE Messtechnik GmbH.
- [17] AMETEK, Inc. (2026, May 06). AMETEK Announces Agreement to Acquire Indicor Instrumentation. AMETEK Newsroom.
- [18] Solartron ISA (AMETEK, Inc.). (2026, January 22). Dualstream Venturi - Solartron ISA. AMETEK, Inc.
- [19] Tekflo Sensors Pte Ltd. (2026, January 14). Our Products - Tekflo Sensors. Tekflo Sensors.
- [20] SEIKOM Electronic GmbH & Co. KG. (2026, January 19). RLSW9 Volume Flow Meter for Gases up to 350°C, LCD, Membrane Keypad. SEIKOM Electronic.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the dall tube flowmeters market in 2026 and what is forecast for 2036?
- Which desalination and municipal pumping energy pressures support demand for dall tube flowmeters?
- Why does Short-Lay-Length Flanged Cast/Fabricated Dall Tube lead construction format?
- Why do DN 300 to DN 1,200 Municipal & Industrial Trunk Mains lead pipe diameter class globally?
- How do growth rates differ across Saudi Arabia, the UAE, Malaysia, the United States, the United Kingdom, and Germany?
- Which notable companies engineer and fabricate dall tube flowmeters today?
- What limits adoption of dall tube flowmeters in dirty or low-Reynolds-number fluids?
- What should water-utility and desalination EPC buyers evaluate before ordering a dall tube flowmeter?
Frequently Asked Questions
How big is the dall tube flowmeters market in 2026, and what is forecast for 2036?
Worldwide dall tube flowmeters demand is estimated at USD 55.2 million in 2026 (up from USD 52.0 million in 2025) and is projected to climb to USD 98.9 million by 2036 as desalination plants and municipal water authorities instrument large-bore trunk mains.
What CAGR is projected for the dall tube flowmeters market from 2026 to 2036?
FMI projects that global dall tube flowmeters revenue will compound at 6.0% annually from 2026 to 2036, delivering a USD 43.7 million increase in annual market revenue between 2026 and 2036 across utility and industrial aqueducts.
Which construction format segment leads the dall tube flowmeters market in 2026?
Short-Lay-Length Flanged Cast/Fabricated Dall Tube is expected to hold 58.6% share in 2026 because self-contained flanged spools with a maximum 1.75D lay length bolt directly into compact underground concrete metering vaults.
Which pipe diameter class accounts for the largest revenue share in 2026?
DN 300 to DN 1,200 Municipal & Industrial Trunk Mains is estimated to capture 54.0% share in 2026 as cities and industrial parks instrument regional transmission rings for leakage and pumping efficiency.
Which country leads national growth projections through 2036?
Based on FMI analysis, Saudi Arabia tops national growth forecasts with a 7.5% CAGR from 2026 to 2036, driven by Red Sea and Arabian Gulf seawater reverse-osmosis desalination pipelines.
Who are the leading companies in the dall tube flowmeters market?
Leading participants include original Dall tube heritage owner ABB Ltd. (Kent / Taylor Dall Tube Heritage), DP primary element fabricators WIKA Alexander Wiegand SE & Co. KG and Tekflo Sensors, competing low-loss Venturi specialists Primary Flow Signal, Inc. and Solartron ISA (AMETEK, Inc.), secondary transmitter suppliers KROHNE Messtechnik GmbH and Emerson Electric Co., and adjacent thermal duct flow monitor provider SEIKOM Electronic GmbH & Co. KG.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Construction Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Construction Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Construction Format, 2026 to 2036
- Short-Lay-Length Flanged Cast/Fabricated Dall Tube
- Weld-In Dall Liner / Insert for Large Mains
- Epoxy-Lined Ductile-Iron & Composite Dall Tubes
- Y-o-Y Growth Trend Analysis By Construction Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Construction Format, 2026 to 2036
- Global Market Analysis and Forecast, By Pipe Diameter Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Pipe Diameter Class, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Pipe Diameter Class, 2026 to 2036
- DN 300 to DN 1,200 Municipal & Industrial Trunk Mains
- >DN 1,200 Desalination & Raw Water Aqueducts
- DN 150 to DN 300 Process Plant Headers
- Y-o-Y Growth Trend Analysis By Pipe Diameter Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Pipe Diameter Class, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Municipal Water Transmission & Desalination Plants
- Hydroelectric & Thermal Power Condenser Loops
- Large-Bore Natural Gas & Blast-Furnace Air Mains
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Malaysia
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Construction Format
- By Pipe Diameter Class
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ABB Ltd. (Kent Dall Tube Heritage)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- WIKA Alexander Wiegand SE
- Tekflo Sensors
- Primary Flow Signal (Competing Venturi)
- Solartron ISA (Competing Venturi)
- KROHNE Messtechnik GmbH
- Emerson Electric Co.
- SEIKOM Electronic (Adjacent Thermal)
- ABB Ltd. (Kent / Taylor Dall Tube Heritage)
- WIKA Alexander Wiegand SE & Co. KG
- Tekflo Sensors Ltd.
- Primary Flow Signal, Inc.
- Solartron ISA (AMETEK, Inc.)
- SEIKOM Electronic GmbH & Co. KG
- ABB Ltd. (Kent Dall Tube Heritage)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


