
- Market Size (2026)
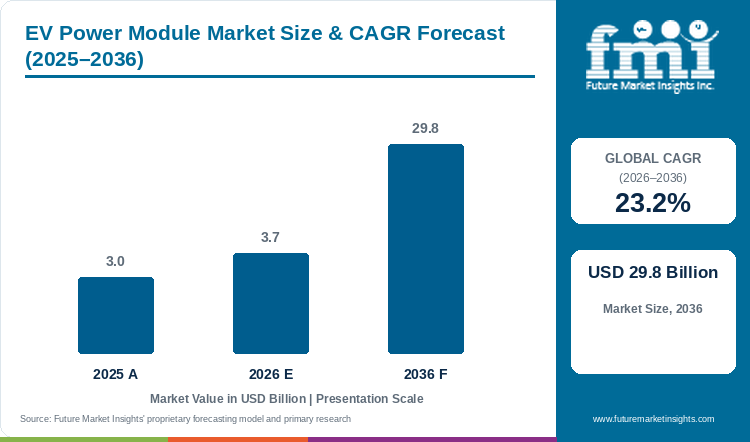
- USD 3.7 Bn
- Forecast (2036)
- USD 29.8 Bn
- CAGR (2026 to 2036)
- 23.2%
How big is EV Power Module Market in 2026?
EV power module revenue advances from USD 3.0 billion in 2025 to USD 3.7 billion in 2026. The market is projected to reach USD 29.8 billion by 2036, at a 23.2% CAGR over 2026 to 2036.
FMI tracks power module demand by linking vehicle output to semiconductor content per drivetrain across the forecast period. Global BEV deliveries reached 12.3 million units in 2025, a rise of 18.7% from 10.36 million in 2024, putting the annual run rate near one million BEVs per month [1]. Each BEV traction inverter carries between one and three power modules depending on voltage class and motor count, and the migration from 400 V to 800 V architectures raises the SiC die area per vehicle. STMicroelectronics introduced fourth-generation SiC MOSFETs in September 2024 with die sizes 12% to 15% smaller than the prior generation at matched on-resistance, a step aimed at bringing SiC into mid-range and compact BEVs [2]. Global SiC investment announcements have surpassed USD 30 billion across the United States, Europe and East Asia, and the SiC device market is forecast to reach USD 10.3 billion by 2030 [3].
Infineon Technologies opened the world's largest 200 mm SiC power fab in Kulim, Malaysia in August 2024, with phase-one investment of EUR 2 billion and reported design contracts of about EUR 5 billion. In May 2025, Infineon disclosed a supply agreement to provide HybridPACK Drive G2 SiC and silicon traction modules to Rivian for the R2 platform beginning in 2026, bringing cumulative HybridPACK Drive shipments past 10.5 million units since 2017. Bosch committed up to USD 2 billion to convert the Roseville, California facility into a 200 mm SiC production site, with sample output already underway and commercial manufacturing planned for 2026; the US Department of Commerce finalized up to USD 225 million in CHIPS Act direct funding for the project in July 2026. FMI expects module content per vehicle to widen as 800 V and 1,200 V inverter designs displace conventional silicon IGBTs across a broader range of BEV price tiers through 2036.
Key Market Trends & Insights
- Battery electric vehicles held 72.0% of vehicle technology demand in 2026. Each BEV powertrain requires a full traction inverter with one or more power modules, unlike mild-hybrid architectures that rely on lower-power devices.
- Passenger cars accounted for 68.0% of vehicle type demand in 2026, since consumer BEV registrations, which reached 12.3 million units globally in 2025, outpace commercial vehicle electrification by volume [1].
Regional Highlights
- Fastest profiled expansion: United States (9.2% CAGR, 2026 to 2036).
- Germany (9.0%) and South Korea (8.9%) follow, as Japan records the lowest profiled CAGR at 8.5%.
- South Korea's Ministry of Trade, Industry and Energy committed KRW 138.46 billion to a compound semiconductor R&D programme running from 2024 to 2028, targeting SiC and GaN device competitiveness.
Market Size & Forecast
Table 1: Market Size and Forecast for the EV Power Module Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.0 billion |
| Estimated Market Size in 2026 | USD 3.7 billion |
| Projected Market Size by 2036 | USD 29.8 billion |
| CAGR, 2026 to 2036 | 23.2% |
| Added Revenue, 2026 to 2036 | USD 26.1 billion |
| Market Expansion Multiple | 8.1x |
SiC adoption in traction inverters is the primary value driver, and each architecture generation raises the semiconductor bill of materials per vehicle. Wolfspeed launched 1,200 V SiC six-pack power modules built on Gen 4 MOSFETs in November 2025, claiming 22% lower on-resistance at 125 degrees Celsius and 60% lower turn-on energy versus the prior generation, with sampling underway and full distribution expected in early 2026. Mitsubishi Electric introduced six J3-Series power modules with SiC MOSFET and RC-IGBT options at NEPCON Japan in January 2024, with partial development support from Japan's NEDO. Capacity constraints for automotive-qualified SiC substrates and the cost premium over silicon IGBTs limit the pace of adoption in lower-priced vehicle segments. FMI's silicon carbide market assessment tracks the broader substrate and device market that underpins power module supply.
EV Production, Inverter Architecture and Module Content per Vehicle
Vehicle output and semiconductor content per drivetrain together determine power module demand across the forecast period.
Table 2: EV Production, Inverter Architecture and Module Content Indicators for the EV Power Module Market (mixed units), reporting years from 2024 to 2026
| Indicator | Data Point | Significance | Source |
|---|---|---|---|
| Global BEV deliveries, 2025 | 12.3 million units | Sets the addressable vehicle base for traction power modules | [1] |
| Infineon HybridPACK Drive cumulative shipments | Over 10.5 million units since 2017 | Indicates the installed base for the leading module platform | - |
| STMicroelectronics Gen 4 SiC die size reduction | 12% to 15% smaller at matched RDS(on) | Enables SiC module adoption in mid-range BEV price tiers | [2] |
| Wolfspeed Gen 4 1,200 V module on-resistance improvement | 22% lower RDS(on) at 125 degrees Celsius | Raises inverter current within a standard module footprint | - |
| Bosch Roseville SiC fab planned capacity share | Expanded US SiC wafer capacity | Supports domestic 200 mm SiC wafer supply for module producers | - |
Analyst Perspective
"SiC module content per vehicle is rising faster than the per-unit cost decline, widening the market opportunity even as die sizes shrink. Suppliers investing in 200 mm SiC wafer capacity now will be positioned to meet demand as 800 V and 1,200 V inverter architectures move from premium to volume BEV platforms."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the EV Power Module Market segmented?
EV power module market is segmented by two primary commercial axes and region: vehicle technology, vehicle type, and region. In 2026, battery electric vehicles are projected at 72.0%, passenger cars at 68.0%.
By vehicle technology: Battery Electric Vehicles (BEV), Hybrid Electric Vehicles (HEV), Plug-in Hybrid Electric Vehicles (PHEV), Fuel Cell Electric Vehicles (FCEV).
By vehicle type: Passenger Cars, Two-wheelers, Commercial Vehicles, Others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do battery electric vehicles concentrate the largest vehicle technology share?
Battery electric vehicles are projected at 72.0% of vehicle technology demand in 2026, as full electrification of the drivetrain requires higher-rated power modules than partial-hybrid systems.
Table 3: Vehicle Technology Share for the EV Power Module Market (percentage share), 2026
| Vehicle Technology | Share (2026) |
|---|---|
| Battery Electric Vehicles (BEV) | 72.0% |
| Other Segments Combined | 28.0%* |
| Total | 100.0% |
*Represents the combined share of all other vehicle technology segments.
Table 4: Vehicle Technology Leadership and Market Growth for the EV Power Module Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 23.2% |
| Leading Segment | Battery Electric Vehicles (BEV) |
A BEV traction inverter converts the full battery output into motor drive current, unlike a mild-hybrid system, in which the internal combustion engine carries the primary load. In FMI's assessment, BEVs account for 72.0% of EV power module value in 2026. Global BEV deliveries totalled 12.3 million units in 2025, up from 10.36 million in 2024, with China contributing 8.40 million units [1]. Module content per BEV is rising as 800 V platforms move beyond premium vehicles. Broader adoption of SiC-based traction inverters, tracked in FMI's IGBT market coverage alongside competing silicon devices, reinforces BEV as the value driver for the module market.
- BEVs account for 72.0% of vehicle technology value in 2026, reflecting higher power module ratings per vehicle.
- Migration to 800 V and 1,200 V architectures adds SiC die area per inverter, raising the semiconductor content of each BEV.
What places passenger cars at 68.0% of vehicle type demand?
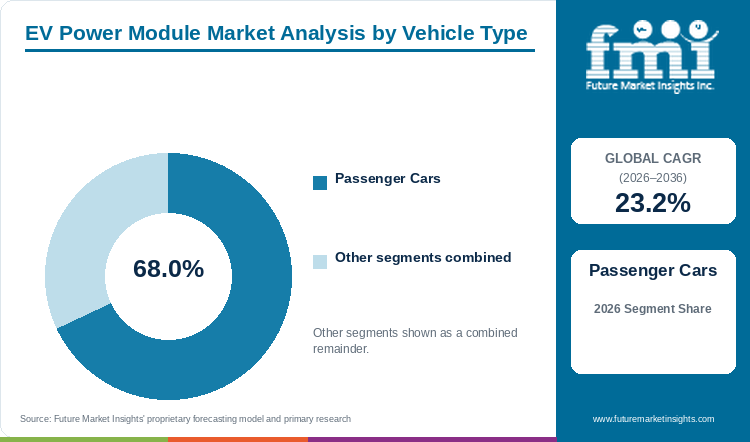
Passenger cars are projected at 68.0% of vehicle type demand in 2026, driven by the volume of consumer BEV registrations relative to commercial and two-wheeler segments.
FMI finds that consumer BEV adoption concentrates power module demand in the passenger car segment. The European Union's revised CO2 standards, adopted in March 2023, require a 55% cut in new-car emissions by 2030. In December 2025, the European Commission published a formal proposal to revise the 2035 target from a 100% to a 90% CO2 reduction relative to 2021 levels; the proposal has been forwarded to the European Parliament and Council for adoption and is expected to be finalised by end of 2026. In Europe, BEV registrations rose to 2.58 million units in 2025 from 1.99 million in 2024 [1]. Passenger car inverters typically carry single or dual power modules rated between 100 kW and 250 kW, and the shift to SiC raises the module value per vehicle.
- Passenger cars hold 68.0% of vehicle type demand in 2026, as the consumer BEV segment accounts for the highest unit volume.
- Tighter emission mandates in the EU and the United Kingdom, alongside commercial fleet electrification tracked in FMI's electric bus market assessment, concentrate inverter content in passenger and public transport vehicles through 2036.
What are the drivers, restraints, and opportunities in the EV Power Module Market?
Rising BEV production volumes push module shipments upward, high SiC substrate and manufacturing costs limit the pace of silicon-to-SiC migration, and 800 V and 1,200 V inverter architectures present the principal near-term commercial opportunity.
- Driver: Growing BEV production and tightening emission mandates increase per-vehicle power module requirements.
- Restraint: SiC wafer and device cost premiums over silicon IGBTs slow adoption in price-sensitive vehicle segments.
- Opportunity: Transition to 800 V and 1,200 V inverter architectures lifts the SiC module content per vehicle.
BEV production growth and emission mandates
Global BEV output is the direct volume driver for power module shipments. Deliveries reached 12.3 million units in 2025, and China alone shipped 8.40 million BEVs, representing 28% of China's total vehicle sales [1]. The UK Zero Emission Vehicle mandate requires 80% of new car sales to be zero-emission by 2030 and 100% by 2035. Inverter module demand tracks vehicle output on a near one-to-one basis as BEV volumes continue to scale.
SiC substrate and device cost premiums
SiC power modules carry higher material and processing costs than silicon IGBTs, and TrendForce reported that SiC power device revenue growth decelerated in 2024 after several years of rapid expansion. STMicroelectronics held the largest SiC device market share at 32.6% in 2023, followed by onsemi, and the top five suppliers together captured 91.9% of the device market. Cost compression follows the transition from 150 mm to 200 mm SiC wafers, a process now underway at Infineon's Kulim facility and at Wolfspeed, which in 2024 became the first company to generate more 8-inch than 6-inch wafer revenue [3][4].
800 V and 1,200 V inverter architectures
Architecture migration from 400 V to 800 V and eventually 1,200 V raises the voltage rating and SiC content per module. Wolfspeed's 1,200 V six-pack modules deliver 15% higher inverter current capability in an industry-standard footprint and are designed as a direct replacement for IGBT solutions, maintaining compatibility with existing capacitors, cooling solutions, gate drivers, and current sensors. Hitachi Astemo adopted ROHM's fourth-generation SiC MOSFETs for EV traction inverters, with supply to manufacturers beginning in 2025 and a claimed 6% power consumption reduction versus IGBTs on the WLTC cycle. As higher-voltage designs reach volume production, module revenue per vehicle increases even as die sizes shrink.
Which country CAGRs are profiled in the EV Power Module Market?
Table 5: Country CAGR Comparison for the EV Power Module Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
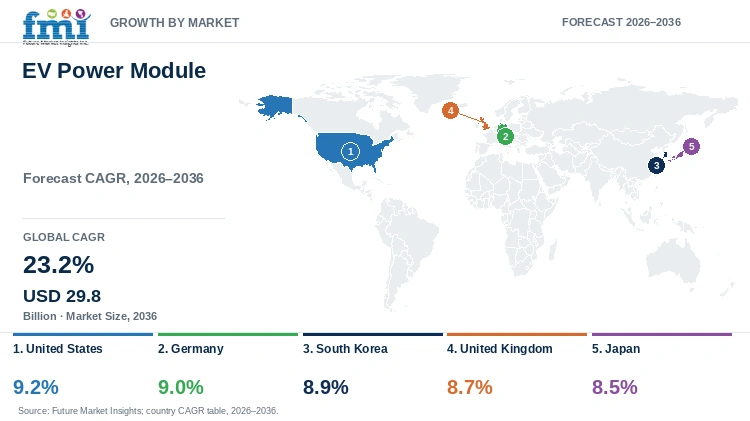
| United States | 9.2% |
| Germany | 9.0% |
| South Korea | 8.9% |
| United Kingdom | 8.7% |
| Japan | 8.5% |
How do country-level CAGRs compare in the EV Power Module Market?
Federal incentives and emission mandates shape the growth outlook across profiled markets. The United States leads at 9.2%, supported by CHIPS Act semiconductor manufacturing investment. Germany follows at 9.0% on the strength of EU-wide CO2 reduction mandates and domestic gigafactory investment. The narrowest spread among profiled rates, less than one percentage point, reflects the shared global trajectory of BEV adoption across mature automotive markets.
- United States growth is driven by federal EV credits and domestic SiC manufacturing investment, including Bosch's Roseville conversion.
- Germany, operating under the EU's 55% CO2 cut by 2030 and a proposed 90% cut by 2035 (still under review), sees accelerating inverter demand across its passenger car fleet.
- South Korea channels government R&D funding into compound power semiconductors through a 2024-to-2028 programme.
- The United Kingdom's ZEV mandate requires 100% zero-emission car sales by 2035, securing steady module demand.
- Japan's carbon neutrality target for 2050, together with domestic semiconductor development programmes, sustains module requirements.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- The United States leads the profiled group at 9.2% CAGR for 2026 to 2036. BEV sales in the United States held at 1.27 million units in both 2024 and 2025 [1]. The federal Section 30D consumer EV tax credit, which had provided up to USD 7,500 per qualifying BEV, was terminated for vehicles acquired after 30 September 2025 under the One Big Beautiful Bill Act, signed into law on 4 July 2025 [5]. US growth to 2036 is now driven primarily by CHIPS Act-backed domestic SiC manufacturing investment rather than consumer purchase incentives. Bosch secured up to USD 225 million in CHIPS Act funding for the Roseville, California SiC fab conversion in July 2026, and Infineon's HybridPACK Drive modules have already been adopted by Rivian for the R2 platform [6]. Domestic SiC wafer capacity expansion is expected to reinforce module supply and sustain power module market growth in the United States.
- Germany records a 9.0% CAGR to 2036. Revised EU CO2 emission standards adopted in March 2023 require new cars to cut emissions by 55% by 2030. The European Commission's December 2025 formal proposal revises the 2035 target from 100% to 90% CO2 reduction relative to 2021, pending co-legislative adoption by the European Parliament and Council. As the EU's largest passenger vehicle market, Germany anchors regional BEV demand; BEV registrations across 30 European countries totalled 2.58 million units in 2025, up from 1.99 million in 2024 [1]. Infineon's Villach, Austria site and the company's phase-two Kulim expansion, with investment of up to EUR 5 billion, are expected to supply European automakers, including those based in Germany. These policy and capacity conditions place Germany among the faster-growing profiled markets.
- South Korea's EV power module market is projected at an 8.9% CAGR to 2036. The Ministry of Trade, Industry and Energy committed KRW 138.46 billion to compound semiconductor R&D from 2024 to 2028, targeting SiC and GaN device development. This wide-bandgap semiconductor investment pipeline, rather than battery or thermal-system supply activity, is the primary platform for South Korean power module content growth.
- At 8.7% CAGR to 2036, the United Kingdom's trajectory follows the UK's Zero Emission Vehicle mandate. The mandate requires 80% of new car sales to be zero-emission by 2030 and 100% by 2035, with annual compliance steps from 2024 onward. SiC power module integration into traction inverters supplied to UK-based OEMs supports steady demand growth through the forecast period.
- Japan records the lowest profiled rate at 8.5% CAGR to 2036. Japan's government maintains a carbon neutrality target for 2050, and NEDO co-funded development of Mitsubishi Electric's J3-Series SiC and RC-IGBT modules released in January 2024. ROHM's fourth-generation SiC MOSFETs were adopted by Hitachi Astemo for EV traction inverters, with deliveries to manufacturers beginning in 2025. Japan's strength in semiconductor device development is expected to support module content growth through domestic and export inverter production.
Who are the notable companies in the EV Power Module Market?
Infineon Technologies, onsemi, STMicroelectronics, Mitsubishi Electric Corporation, Wolfspeed, Continental AG, Robert Bosch GmbH, Denso Corporation, Toshiba Corporation, NXP Semiconductors, ROHM Semiconductor, Hitachi Power Semiconductor, Semikron Danfoss, and Renesas Electronics are among the companies active in this market.
According to FMI, semiconductor device makers that supply SiC and IGBT dies and Tier 1 automotive suppliers that integrate these devices into inverter assemblies shape the EV power module market. Infineon Technologies reported design contracts worth about EUR 5 billion for the Kulim SiC facility, covering automotive, industrial and renewable energy applications. STMicroelectronics held a 32.6% share of the broader SiC power device market in 2023. Module assembly and system integration bring Continental AG, Denso Corporation and Bosch into the supply chain alongside the semiconductor specialists.
- Semiconductor device makers: Infineon Technologies, onsemi, STMicroelectronics, Wolfspeed, Mitsubishi Electric Corporation, ROHM Semiconductor, Renesas Electronics, NXP Semiconductors, Toshiba Corporation, BYD Semiconductor, StarPower Semiconductor, Hitachi Power Semiconductor.
- Tier 1 automotive integrators: Continental AG, Robert Bosch GmbH, Denso Corporation.
- Module packaging and assembly: Semikron Danfoss.
Competitive Benchmarking: EV Power Module Market
Table 6: Competitive Benchmarking for the EV Power Module Market (qualitative capability ratings), 2026
| Company | SiC Device Portfolio | Manufacturing Scale | OEM Supply Agreements | Reach |
|---|---|---|---|---|
| Infineon Technologies | High | High | High | High |
| onsemi | High | High | High | High |
| STMicroelectronics | High | High | High | High |
| Mitsubishi Electric | High | Medium | Medium | Medium |
| Wolfspeed | High | Medium | Medium | Medium |
| ROHM Semiconductor | High | Medium | Medium | Medium |
| Robert Bosch GmbH | Medium | High | Medium | High |
| Toshiba Corporation | Medium | Medium | Medium | Medium |
| Semikron Danfoss | Medium | Medium | Medium | Medium |
| Renesas Electronics | Medium | Medium | Low | Medium |
High reflects broad publicly documented activity in SiC and power module supply for EV traction applications. Medium reflects a narrower or more recently scaled programme. Low reflects limited public documentation of automotive traction module activity.
Key Developments in the EV Power Module Market
- In July 2026, the US Department of Commerce finalized up to USD 225 million in CHIPS Act funding for Bosch's Roseville, California SiC fab conversion, part of a project valued at up to USD 2 billion.
- In November 2025, Wolfspeed launched 1,200 V SiC six-pack power modules built on Gen 4 MOSFETs, claiming 22% lower on-resistance and 60% lower turn-on energy versus the prior generation.
- In August 2025, Toshiba Electronic Devices and Storage Corporation and BASiC Semiconductor signed an MOU on a strategic partnership in power module products, combining Toshiba Electronic Devices and Storage's SiC and IGBT power semiconductor technologies with BASiC's module architecture for automotive and industrial applications.
- In May 2025, Infineon disclosed a supply agreement to provide HybridPACK Drive G2 SiC and silicon power modules to Rivian for the R2 platform, with shipments beginning in 2026.
Key Players in the EV Power Module Market
Semiconductor Device Makers
- Infineon Technologies
- onsemi
- STMicroelectronics
- Wolfspeed
- Mitsubishi Electric Corporation
- ROHM Semiconductor
- Renesas Electronics
- NXP Semiconductors
- Toshiba Corporation
- BYD Semiconductor
- StarPower Semiconductor
- Hitachi Power Semiconductor
Tier 1 Automotive Integrators
- Continental AG
- Robert Bosch GmbH
- Denso Corporation
Module Packaging and Assembly
- Semikron Danfoss
EV Power Module Market - Report Scope
Table 7: Report Scope for the EV Power Module Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Vehicle technology; vehicle type; region |
| Quantitative units | USD billion |
| Market definition | Revenue from power semiconductor modules (IGBT modules, SiC MOSFET modules, GaN modules and hybrid Si/SiC modules) used in electric vehicle traction inverters, on-board chargers and DC-DC converters; excludes discrete semiconductor die sales, battery cells, motors, vehicle assembly and charging infrastructure |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Germany; United Kingdom; South Korea; Japan |
| Key companies profiled | Infineon Technologies; onsemi; STMicroelectronics; Mitsubishi Electric; Wolfspeed; Continental AG; Robert Bosch GmbH; Denso Corporation; Toshiba Corporation; NXP Semiconductors; ROHM Semiconductor; Hitachi Power Semiconductor; Semikron Danfoss; Renesas Electronics |
| Forecast period | 2026 to 2036 |
| Approach | A bottom-up build was reconciled against top-down estimates covering module content per vehicle with vehicle production data, SiC adoption rates, and inverter architecture trends. |
EV Power Module Market - Research Methodology
Table 8: Research Methodology for the EV Power Module Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with semiconductor device engineers, Tier 1 inverter suppliers, OEM powertrain procurement teams, and industry body representatives across North America, Europe and East Asia. |
| Desk Research | Review of company financial filings, product datasheets, investor presentations, trade association data, government semiconductor programme documents, and vehicle registration statistics. |
| Market Sizing and Forecasting | Bottom-up module content per vehicle multiplied by segmented BEV, PHEV, HEV and FCEV production volumes, cross-checked against top-down semiconductor device revenue reported by leading suppliers. |
| Data Validation | Triangulation across primary interview inputs, supplier revenue disclosures and third-party vehicle production databases to reconcile reported market size estimates. |
EV Power Module Market by Segments
EV Power Module Market segmented by Vehicle Technology:
- Battery Electric Vehicles (BEV)
- Hybrid Electric Vehicles (HEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Fuel Cell Electric Vehicles (FCEV)
EV Power Module Market segmented by Vehicle Type:
- Passenger Cars
- Two-wheelers
- Commercial Vehicles
- Others
EV Power Module Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Inovev. (2026, April 9). BEV sales reached 12.3 million units worldwide in 2025. https://inovev.com/index.php/en/market-analyses/category-blog/21800-2026-04-9
- [2] Charged EVs. (2024, September 25). STMicroelectronics unveils new SiC MOSFETs for EV traction inverters. https://chargedevs.com/newswire/stmicroelectronics-unveils-new-sic-mosfets-for-ev-traction-inverters/
- [3] BIS Infotech. (2025, December 23). Power SiC industry faces slowdown until 2027, but market set to reach $10B by 2030. https://www.bisinfotech.com/power-sic-industry-faces-slowdown-until-2027-but-market-set-to-reach-10b-by-2030/
- [4] Semiconductor Today. (2024, August 8). Infineon opens the world's largest 200-millimeter silicon carbide fab in Kulim. https://semiconductor-today.com/news_items/2024/aug/infineon-080824.shtml
- [5] Sidley Austin. (2024, May). US Treasury releases final electric vehicle tax credit regulations. https://www.sidley.com/en/insights/newsupdates/2024/05/us-treasury-releases-final-electric-vehicle-tax-credit-regulations
- [6] New Equipment Digest. (2026, July 13). Bosch locks in $225 million federal deal to power $2 billion silicon carbide plant in Roseville. https://www.newequipment.com/industry-trends/news/55390545/bosch-locks-in-225-million-federal-deal-to-power-2-billion-silicon-carbide-plant-in-roseville
- [7] EE Journal. (2025, May 19). Infineon will supply Rivian's R2 platform with power modules for electric vehicle traction inverters. https://www.eejournal.com/industry_news/infineon-will-supply-rivians-r2-platform-with-power-modules-for-electric-vehicle-traction-inverters/
- [8] Argus Media. (2023, July 14). S Korea invests in compound semiconductor R&D project. https://www.argusmedia.com/en/news-and-insights/latest-market-news/2469095-s-korea-invests-in-compound-semiconductor-r-d-project
- [9] Charged EVs. (2025, November 17). Wolfspeed unveils new 1200 V silicon carbide power modules for high-efficiency EV inverters. https://chargedevs.com/newswire/the-tech/wolfspeed-unveils-new-1200-v-silicon-carbide-power-modules-for-high-efficiency-ev-inverters/
- [10] Compound Semiconductor. (2024, January 23). Mitsubishi announces six power modules for EVs. https://compoundsemiconductor.net/article/118497/Mitsubishi_announces_six_power_modules_for_EVs
- [11] ICCT. (2023, May). EU CO2 standards for cars and vans. https://theicct.org/publication/eu-co2-standards-cars-vans-may23/
- [12] UK Government. (2023, September 28). Government sets out path to zero emission vehicles by 2035. https://www.gov.uk/government/news/government-sets-out-path-to-zero-emission-vehicles-by-2035
- [13] EE Times Asia. (2024, July 4). TrendForce: STMicroelectronics leads global SiC power device market. https://www.eetasia.com/trendforce-stmicroelectronics-leads-global-sic-power-device-market/
- [14] Power Electronics News. (2023, January 12). ROHM's 4th gen SiC MOSFETs to be used in Hitachi Astemo's inverters for EVs. https://www.powerelectronicsnews.com/rohms-4th-gen-sic-mosfets-to-be-used-in-hitachi-astemos-inverters-for-evs
- [15] Toshiba. (2025, August 29). Toshiba and BASiC sign MOU on strategic partnership in power module products. https://toshiba.semicon-storage.com/eu/company/news/2025/08/corporate-20250829-1.html
This Report Answers
- How big is the EV power module market during 2026?
- What value is projected by 2036?
- Which vehicle technology holds the largest share?
- Which vehicle type holds the largest share?
- Which countries show the fastest growth?
- Which companies are key in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Vehicle Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Technology, 2026 to 2036
- Battery Electric Vehicles (BEV)
- Hybrid Electric Vehicles (HEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Fuel Cell Electric Vehicles (FCEV)
- Y-o-Y Growth Trend Analysis By Vehicle Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Two-wheelers
- Commercial Vehicles
- Others
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Vehicle Technology
- By Vehicle Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Vehicle Technology
- By Vehicle Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Vehicle Technology
- By Vehicle Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Vehicle Technology
- By Vehicle Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Infineon Technologies
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- onsemi
- STMicroelectronics
- Mitsubishi Electric
- Wolfspeed
- ROHM Semiconductor
- Robert Bosch GmbH
- Toshiba Corporation
- Semikron Danfoss
- Renesas Electronics
- Mitsubishi Electric Corporation
- NXP Semiconductors
- BYD Semiconductor
- StarPower Semiconductor
- Hitachi Power Semiconductor
- Continental AG
- Denso Corporation
- Infineon Technologies
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Technology, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Vehicle Technology
- Figure 6: Global Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Vehicle Type
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Vehicle Technology
- Figure 23: North America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Vehicle Type
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Vehicle Technology
- Figure 30: Latin America Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Vehicle Type
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Vehicle Technology
- Figure 37: Western Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Vehicle Type
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Vehicle Technology
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Vehicle Type
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Vehicle Technology
- Figure 51: East Asia Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Vehicle Type
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Vehicle Technology
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Vehicle Type
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Technology, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Technology, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Vehicle Technology
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Type, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Type, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by Vehicle Type
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the EV power module market expected in 2026?
At USD 3.7 billion for 2026, the EV power module market stands at the beginning of a decade-long expansion to USD 29.8 billion by 2036. SiC penetration into traction inverters and annual BEV production growth underpin the 8.1x revenue increase across the forecast period.
What CAGR is projected for the EV power module market through 2036?
FMI's analysis places the EV power module market on a 23.2% CAGR trajectory from 2026 to 2036, derived directly from the USD 3.7 billion (2026) to USD 29.8 billion (2036) revenue path. This dollar-value CAGR runs well above the 8.5% to 9.2% range seen across profiled country CAGRs because it compounds unit volume growth together with rising SiC content and higher average selling price per module; the country figures reflect narrower, more conservative unit-and-price assumptions and are not directly comparable to the blended global rate.
Which vehicle technology holds a leading market share in 2026?
Battery electric vehicles account for 72.0% of EV power module demand by vehicle technology in 2026. Full electrification of the drivetrain concentrates power module content per vehicle in the BEV segment, unlike mild-hybrid systems that use lower-rated devices.
Which vehicle type holds the largest share in 2026?
Passenger cars represent 68.0% of EV power module demand by vehicle type in 2026. Consumer BEV registrations drive the highest unit volume, and tightening emission mandates in the EU and the United Kingdom sustain the passenger car segment's dominance.
Which country shows the strongest expansion outlook through 2036?
The United States leads the profiled group at 9.2% CAGR from 2026 to 2036. Inflation Reduction Act credits, CHIPS Act SiC manufacturing investments, and the Rivian-Infineon module supply agreement contribute to this outlook.
Who are the key companies in the EV power module market?
Key companies include Infineon Technologies, onsemi, STMicroelectronics, Mitsubishi Electric, Wolfspeed, Continental AG, Robert Bosch GmbH, Denso Corporation, Toshiba Corporation, NXP Semiconductors, ROHM Semiconductor, Hitachi Power Semiconductor, Semikron Danfoss, Renesas Electronics, BYD Semiconductor, and StarPower Semiconductor.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
