
- Market Size (2026)
- USD 26.1 Bn
- Forecast (2036)
- USD 43.8 Bn
- CAGR (2026 to 2036)
- 5.3%
How big is Fabric Softeners Market in 2026?
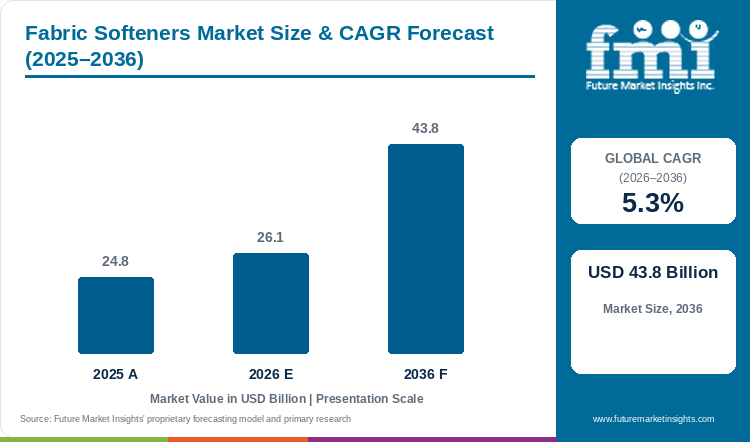
Sales of fabric softeners are set to rise at a 5.3% CAGR from 2026 to 2036. The global market moves from USD 24.8 billion in 2025 to USD 26.1 billion in 2026, with a projected value of USD 43.8 billion by 2036.
The per-capita consumption and wash frequency analysis of the fabric softeners market reveals wide gaps between mature and emerging markets. AISE's 2024 pan-European consumer survey, covering 23 countries and approximately 4,600 households, recorded an average of 6.3 machine washes per fortnight, with households of three or more children running 9.1 washes against 4.9 for child-free homes [1]. A February 2026 Wakefield Research survey of 1,000 US adults found that 68% of at-home launderers used fabric softener or dryer sheets, with 37% of households running four to six loads per week [2].
Softener penetration in India remains well below these levels, constrained by hand-washing prevalence and lower awareness of rinse-cycle additives, even as fabric conditioner volumes are expanding in urban centres. Per-wash cost differences between concentrated and dilute formats further widen the gap: a concentrated dose sold in Western Europe delivers a lower price per wash than an equivalent standard-dilution bottle in South Asia, which drives adoption of compacted products in high-frequency markets.
Adoption of plant-based softener formulations is gaining pace among suppliers positioning around eco-friendly laundry demand. Unilever reported high-single-digit volume-led growth for the Comfort brand in the first half of 2026, supported by premium formats and fragrance-led innovation, and the broader fabric enhancers category at the company grew at a comparable rate [3]. In June 2025, Comfort relaunched the Core, Creations and Fresh & Protect ranges in the UK with a GBP 7.6 million marketing investment and expanded the Scent Booster Elixir line, which reached 5% household penetration after the 2024 launch. P&G's Fabric Care business recorded low-single-digit organic sales growth in the fourth quarter of fiscal 2026, driven primarily by volume gains in Europe and favorable product mix. FMI expects growth through 2036 to be led by concentrated formats in Western Europe and East Asia, even as conventional formulations continue to dominate volume in price-sensitive South Asian and Latin American markets.
Key Market Trends & Insights
- Liquid softeners held 57.2% of product type demand in 2026, as automatic dispensers in modern washing machines favour pourable formats and concentrated doses reduce packaging waste per wash.
- An 86.5% share of nature demand went to conventional formulations in 2026. Key trends in the fabric softeners market point to a shift toward plant-derived softening agents, and Henkel's Vernel range relaunched in February 2026 with 100% recycled plastic bottles and a new Sensitiv line carrying a dermatological confirmation for sensitive skin.
- Household consumers accounted for the largest share of end use demand in 2026. In the United States, 43% of households run one to three laundry loads per week and a further 37% run four to six loads, making residential laundry the primary volume driver for softener products [2].
- Supermarkets and hypermarkets held the leading sales channel position in 2026. Online sales are gaining share as subscription and auto-replenishment models expand, and Lion Corporation scheduled a nationwide Japanese retail launch of SOFLAN Aroma Rich moA through retail and online channels in October 2026.
Regional Highlights
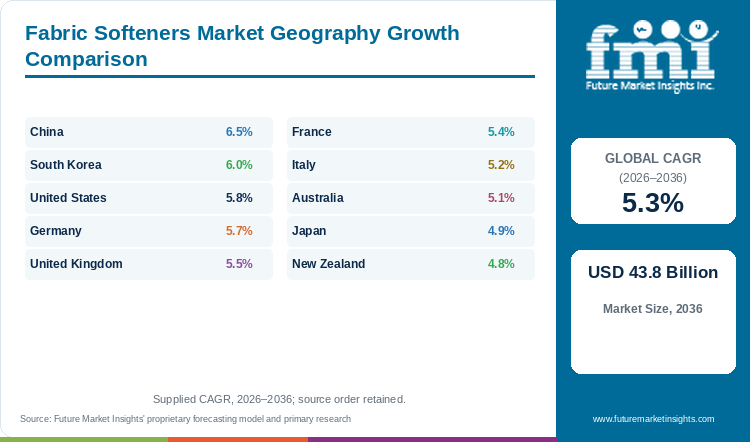
- China posts the quickest profiled growth at 6.5% CAGR over 2026 to 2036.
- South Korea (6.0%) and the United States (5.8%) follow. New Zealand records the lowest profiled CAGR at 4.8%.
- Unilever's Home Care division grew underlying sales 7.6% in the first half of 2026, with India recording double-digit growth and reaching a record Home Care market share [3].
Market Size & Forecast
Table 1: Market Size and Forecast for the Fabric Softeners Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 24.8 billion |
| Estimated Market Size in 2026 | USD 26.1 billion |
| Projected Market Size by 2036 | USD 43.8 billion |
| CAGR, 2026 to 2036 | 5.3% |
| Added Market Value, 2026 to 2036 | USD 17.7 billion |
| Market Expansion Multiple | 1.7x |
Demand for fabric softeners draws on laundry frequency, household income and consumer preference for scent and fabric feel. The laundry care market, the parent category in which fabric softeners rank as the second-largest product type after detergents, was estimated at USD 122.4 billion in 2026 by FMI. AISE's 2024 research found that 75% of European consumers preferred liquid or gel detergent, up from 64% in 2014 — a detergent-form trend rather than direct evidence of softener usage — and that 60% of washes were run at 40 degrees Celsius or below, which is more directly compatible with rinse-added softener use [1]. However, competition from built-in softening agents in detergent pods and from reusable alternatives such as wool dryer balls limits incremental softener usage in mature markets. Growth is expected to concentrate in Asia and Latin America, as rising disposable incomes and washing machine penetration expand the addressable consumer base.
Per-Capita Consumption and Wash Frequency Analysis
Under the per-capita consumption and wash frequency analysis carried out for this report, FMI links softener demand to five inputs: household laundry frequency, dosage per wash, product concentration, price per wash and regional water hardness.
Table 2: Per-Capita Consumption and Wash Frequency Indicators for the Fabric Softeners Market (mixed units), mixed reporting years from 2024 to 2026
| Indicator | Data Point | Significance | Source |
|---|---|---|---|
| European household wash frequency | 6.3 machine washes per fortnight (2024 survey, 23 countries) | Sets the base rinse-cycle count that drives softener doses per household | [1] |
| US fabric softener / dryer sheet usage | 68% of at-home launderers (February 2026 survey, n = 1,000) | Shows the penetration limit in a mature market | [2] |
| US unit-dose adoption | 38% of at-home launderers use pods, packets or sheets (February 2026) | Signals format migration that may bypass liquid softener | [2] |
| Comfort Scent Booster Elixir UK penetration | 5% household penetration within one year of 2024 launch | Measures speed at which premium add-on formats gain traction | - |
| European wash temperature | 60% of washes at 40 degrees Celsius or below (2024) | Low-temperature cycles favour liquid softeners over dryer sheets | [1] |
Analyst Perspective
"Wash frequency and dosing habits differ enough between regions to split the market into two competitive arenas. In Western Europe and East Asia, concentrated formats with fragrance capsules command a premium per wash; in South Asia and Latin America, conventional dilute softeners compete on price per litre, and raising penetration requires better affordability."
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Fabric Softeners Market segmented?
Fabric softeners market is segmented by four primary commercial axes and region: nature, product type, end use, sales channel, and region. In 2026, liquid holds 57.2% by product type, conventional holds 86.5% by nature, household leads by end use, and supermarkets and hypermarkets lead by sales channel.
By nature: conventional, organic.
By product type: liquid, sheets, sprays, tablets, dryer bars.
By end use: household, laundry services, hospitality industry, textile industry, others.
By sales channel: supermarkets and hypermarkets, specialty retail stores, online sales, others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
What sustains liquid softeners at the leading product type share?
Liquid softeners account for 57.2% of product type demand in 2026, underpinned by automatic dispensing compatibility and established consumer dosing habits.
Table 3: Product Type Share for the Fabric Softeners Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Liquid | 57.2% |
| Other Segments Combined | 42.8%* |
| Total | 100.0% |
*Represents the combined share of sheets, sprays, tablets and dryer bars, the segments that make up the remainder of 2026 product type demand.
Table 4: Product Type Leadership and Market Growth for the Fabric Softeners Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.3% |
| Leading Segment | Liquid |
Sales of concentrated fabric conditioners are rising within the liquid segment, as brands reformulate to deliver fewer millilitres per dose and reduce shipping weight. Henkel's February 2026 Vernel relaunch introduced fragrance capsules across four product lines and used 100% recycled plastic bodies. In the FMI report, liquid formats account for 57.2% of product type demand, reflecting the installed base of automatic dispensers in front-loading machines and the consumer habit of pouring softener into a rinse-cycle tray. Standalone in-wash scent booster products, such as Comfort's Scent Booster Elixir, sit outside the fabric softener market as scoped in this report and are tracked separately.
- Liquid formats lead at 57.2% in 2026, held in place by washing machine dispenser design and consumer familiarity with pour-and-dose routines.
- Concentrated liquids deliver a lower price per wash and less plastic per dose, and both P&G and Unilever now market concentrated variants as primary shelf lines for the category.
Why do conventional formulations retain a leading nature share?
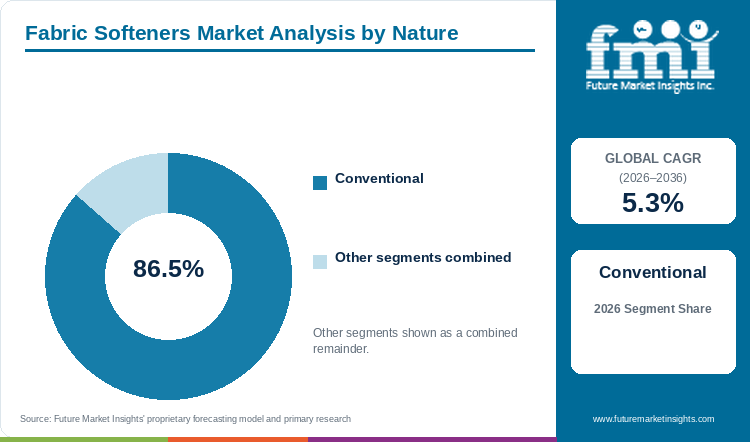
Conventional softeners hold 86.5% of nature demand in 2026, as petroleum-derived cationic surfactants remain the lowest-cost softening agent available at scale.
FMI finds that conventional fabric softeners use cationic surfactants, typically dialkyl ester quats, to deposit a lubricating film on fibres during the rinse cycle. These ingredients are produced at high volume and at a lower cost per dose than plant-derived equivalents, keeping conventional products dominant across nearly all markets. Organic and plant-based alternatives remain a small niche but are growing fastest in Western Europe, as the EU's revised detergent and surfactant regulation, Regulation 2026/405, published on 11 February 2026, retains the 60% ultimate aerobic biodegradation threshold within 28 days carried over from the 2004 regulation while adding a digital product passport requirement for all detergents entering the EU market [4]. According to the per-capita consumption and wash frequency analysis, higher wash counts in large households amplify any per-dose cost advantage, keeping conventional formulations dominant where price governs choice.
- Conventional formulations account for 86.5% of nature demand in 2026, driven by raw material cost and broad retail availability.
- Organic and plant-based variants, a low-double-digit niche share, are growing fastest in markets with strong eco-labelling frameworks and retailer sustainability mandates.
Which end use generates the most fabric softener volume?
Household consumption leads end use demand in 2026, fed by residential laundry frequency and retail softener availability.
Residential laundry is the largest single source of fabric softener volume. The Wakefield Research survey released in April 2026 found that 43% of US households ran one to three loads per week, 37% ran four to six, and 10% ran seven to ten, with only 1% relying entirely on laundry services [2]. Hospitality and textile industry users buy in bulk but represent a smaller share of total market revenue. Under the per-capita consumption and wash frequency analysis, household penetration rates above 60% in the United States and Western Europe contrast with far lower rates in South Asia, which positions residential demand as the primary growth vector as washing machine ownership expands.
- Household end use leads demand in 2026, supported by the frequency of residential laundry cycles across all major regions.
- Hospitality industry use concentrates on large-format concentrated products, as consistent fragrance and fabric feel across guest linens drive repeat purchasing.
How do supermarkets and hypermarkets maintain the leading sales channel position?
Supermarkets and hypermarkets remain the largest sales channel for fabric softeners in 2026, as shelf presence, promotional pricing and basket-building drive volume.
Fabric softeners are a high-frequency grocery purchase, and the physical display space available in supermarket aisles favours large-format bottles and multi-packs. Private-label softener lines, which compete directly with branded products on price, are strongest in hypermarket and supermarket channels. Online sales are growing as subscription and auto-replenishment models remove the need for store visits, and the US survey showed unit-dose products, including sheets, reaching 38% adoption among at-home launderers [2]. FMI expects the online share to rise through 2036 as direct-to-consumer brands and third-party marketplaces expand, particularly in East Asia and South Asia.
- Supermarkets and hypermarkets lead the sales channel in 2026 on the strength of in-store promotions and the impulse-driven nature of scented softener purchases.
- Online channels are the fastest-growing format, especially in South Korea and China, as e-commerce penetration in household care is already high.
What are the drivers, restraints, and opportunities in the Fabric Softeners Market?
Rising laundry frequency and consumer attachment to scent and fabric feel propel demand for fabric softeners. Regulatory tightening on surfactant biodegradability and competition from built-in softening agents in detergent pods constrain growth. Concentrated and refillable formats open a route to higher value per dose and reduced packaging waste.
- Driver: household laundry frequency and consumer preference for fragrance, softness and static control sustain baseline softener demand.
- Restraint: stricter surfactant biodegradability rules and rising consumer adoption of detergent pods with built-in softening agents limit incremental volume.
- Opportunity: concentrated formats, refillable packaging and microencapsulated fragrance technology create premium pricing headroom above dilute products.
Household laundry frequency anchors softener demand
Demand for fabric softeners tracks the number of rinse cycles run per household. AISE's 2024 European consumer survey showed households with three or more children averaging 9.1 washes per fortnight, nearly double the 4.9 washes recorded for child-free homes [1]. In the United States, 37% of households wash four to six loads per week [2]. Each wash that includes a softener dose converts directly into product consumption. Unilever's Home Care division, which includes the Comfort and Seventh Generation softener brands, posted 7.6% underlying sales growth in the first half of 2026, with 7.4 percentage points coming from volume, indicating that usage occasions are expanding instead of shifting purely to premium pricing [3]. Growth in laundry care spending in India and Brazil is expected to widen the addressable wash base through 2036.
Regulatory tightening on surfactant chemistry
EU Regulation 2026/405, published on 11 February 2026, replaces the 2004 detergent regulation and carries forward the same 60% ultimate aerobic biodegradation threshold within 28 days. The main change is a new digital product passport mandate for all detergents and surfactants placed on the EU market, with delegated acts on the passport due by October 2028. Fabric softener formulations that have not already demonstrated biodegradation compliance may still need reformulation before the September 2029 application date. Compliance costs from the new passport requirement will fall disproportionately on smaller manufacturers without in-house formulation laboratories.
Concentrated and refillable formats as a value migration path
Concentrated fabric softeners deliver more doses per bottle, lower shipping weight and less plastic per wash. Henkel's February 2026 Vernel relaunch paired fragrance capsule technology with bottles made from 100% recycled plastic. Lion Corporation's SOFLAN Aroma Rich moA, announced in August 2026 for October 2026 retail launch, uses plant-derived softening agents and offers a 530 ml bottle, a 700 ml refill pack and a 1,200 ml large refill pack. Demand for fragrance encapsulation technology, which releases scent gradually during wear, is rising as brands compete on long-lasting freshness claims. FMI sees this format migration raising the average revenue per dose and shifting competitive advantage toward suppliers with encapsulation and recycled-resin capabilities.
Which country CAGRs are profiled in the Fabric Softeners Market?
Table 5: Country CAGR Comparison for the Fabric Softeners Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 6.5% |
| South Korea | 6.0% |
| United States | 5.8% |
| Germany | 5.7% |
| United Kingdom | 5.5% |
| France | 5.4% |
| Italy | 5.2% |
| Australia | 5.1% |
| Japan | 4.9% |
| New Zealand | 4.8% |
How do country-level CAGRs compare in the fabric softeners market?
Consumer income, washing machine ownership and cultural preference for scented laundry separate the profiled country growth rates. FMI's per-capita consumption and wash frequency analysis places China (6.5%) and South Korea (6.0%) at the top of the ranking, as rising disposable income and skin-care-influenced softener preferences raise volumes. The United States (5.8%) and Western European countries range from 5.7% to 5.4%, reflecting mature penetration and a shift from volume growth to value growth via concentrated and premium formats. Japan (4.9%) and New Zealand (4.8%) close the group, with smaller household sizes and high existing penetration rates limiting incremental growth.
- China benefits from urban income growth and expanding online channels for antibacterial and fragrant softener variants.
- South Korea's demand tracks the skin-care crossover trend, with hypoallergenic and dermatologically tested softeners gaining shelf space, per domestic brand launches such as LG H&H's Saffron line.
- Concentrated formats are raising revenue per wash in the United States.
- Germany's consumers favour biodegradable, fragrance-free and vegan-certified products, with Henkel's Vernel relaunch targeting this segment.
- Premium botanicals and refill-point trials support softener consumption in the United Kingdom.
- France's demand leans toward subtle-scented and botanical formulations from heritage brands.
- Italian consumers prioritise fabric feel and colour retention, with low-foam softeners gaining in smart washing machine households.
- Eco-friendly and bulk refill packaging drives softener adoption in Australia.
- Compact, low-waste concentrated formats lead product development in Japan.
- Cruelty-free and septic-safe formulations anchor the New Zealand market.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- China's fabric softener market is on course to expand at 6.5% CAGR through 2036. Antibacterial and long-lasting fragrance claims are the primary purchase drivers in Chinese urban households, and direct-to-consumer platforms have shortened the path from brand trial to repeat purchase. Rising middle-class spending is expected to widen softener penetration beyond first-tier cities.
- South Korea's fabric softener market is set to grow at 6.0% CAGR through 2036. LG H&H's Saffron fabric softener line and Lion Corporation's domestic SOFLAN range compete on hypoallergenic and skin-friendly claims that resonate strongly in a market in which laundry care overlaps with the broader personal care sensibility. E-commerce penetration in household products reinforces the direct-to-consumer channel.
- The United States fabric softener market is projected at a 5.8% CAGR to 2036. A Wakefield Research survey of 1,000 US adults in February 2026 found that 68% of at-home launderers used fabric softener or dryer sheets, and 36% used scent beads or boosters [2]. Subscription and auto-replenishment models are extending purchase frequency, and concentrated doses are displacing standard-dilution bottles on retail shelves.
- A 5.7% CAGR is projected for Germany's fabric softener market through 2036. Henkel relaunched the Vernel fabric softener line on 4 February 2026 with four product variants, including a Sensitiv line with dermatological confirmation for sensitive skin and a Fresh Control line for sportswear. EU Regulation 2026/405 introduces tighter biodegradability standards for surfactants, with full application from September 2029. German consumers' preference for vegan and fragrance-free products positions the market as a test bed for reformulated, plant-based softener chemistry.
- The United Kingdom's fabric softener market is anticipated to rise at 5.5% CAGR through 2036. Comfort relaunched the Core, Creations and Fresh & Protect ranges in June 2025, backed by a GBP 7.6 million marketing campaign and the "Next Level Fresh" positioning. Private-label competition from supermarket own-brand softeners remains a margin pressure for branded suppliers.
- France's fabric softener market is forecast to grow at 5.4% CAGR to 2036. Colgate-Palmolive markets Soupline in France as a gentle, family-oriented conditioner, competing against Unilever's Comfort and local niche brands with botanical and subtle-scent positioning. Refill points in grocery stores are an emerging retail format that reduces packaging cost per dose and appeals to environmentally conscious French consumers. Demand for premium softeners with natural ingredient claims is expected to sustain above-average revenue per wash.
- Italy's fabric softener market is estimated to grow at 5.2% CAGR through 2036. Italian consumers place high importance on fabric feel and colour retention, and craft softener brands using olive oil or lavender ingredients occupy a visible niche. Low-foam softeners designed for smart washing machines with automatic dosing are gaining in urban households. Volume growth will be supported by household laundry frequency, which remains relatively high in Southern European markets.
- Australia's fabric softener market is projected at a 5.1% CAGR to 2036. Consumer demand for eco-friendly and natural softener formulations aligns with retail trends toward bulk and refill packaging. Ecover and Method, sold under SC Johnson's ownership, address the eco-conscious segment with plant-based formulations, and mainstream brands compete on fragrance performance. The per-capita consumption and wash frequency analysis points to a relatively high wash frequency in Australian households, supporting stable softener usage.
- Japan's fabric softener market is projected to record a 4.9% CAGR through 2036. Lion Corporation's SOFLAN Aroma Rich moA, scheduled for October 2026, uses the highest proportion of softening agents among Lion's fabric softener range and is formulated with plant-derived ingredients suitable for baby clothes. Compact, low-waste packaging aligns with Japanese consumer expectations for minimal environmental impact. Deodorising and antibacterial functions are standard requirements in a market in which cold-wash cycles are prevalent.
- New Zealand's fabric softener market is forecast at 4.8% CAGR to 2036. Cruelty-free and biodegradable certifications are baseline purchase criteria for a significant portion of New Zealand consumers, and septic-safe formulations address the rural housing stock. Ecostore, a domestic brand, competes with global players on plant-based credentials. Limited population growth constrains volume, and value growth hinges on premiumisation and format innovation.
Who are the notable companies in the Fabric Softeners Market?
Procter & Gamble, Unilever, Henkel, Colgate-Palmolive, SC Johnson, Church & Dwight, Seventh Generation, Kao Corporation, and Lion Corporation compete across the global fabric softener market.
Fabric softener competition is structured around three tiers. Global FMCG groups with multi-brand portfolios set shelf standards in most geographies. Regional leaders with strong domestic brand equity dominate specific markets. Eco-focused and niche brands target the growing organic and plant-based segment. Procter & Gamble leads with Downy and Lenor across North America, Europe and Asia, and Unilever's Comfort brand is strongest in the UK, South Asia and Southeast Asia. Henkel competes through Vernel in Europe and Snuggle in North America, and Colgate-Palmolive sells Suavitel and Soupline in the Americas and Europe. In East Asia, Kao's Humming and Lion's SOFLAN are established brands in Japan, and LG H&H's Saffron competes in South Korea.
- Global portfolio leaders: Procter & Gamble (Downy, Lenor), Unilever (Comfort), Henkel (Vernel, Snuggle).
- Regional and specialist brands: Colgate-Palmolive (Suavitel, Soupline), Kao Corporation (Humming), Lion Corporation (SOFLAN).
- Eco-focused and niche: SC Johnson (Ecover, Method), Seventh Generation (Unilever subsidiary), Church & Dwight.
Competitive Benchmarking: Fabric Softeners Market
Table 6: Competitive Benchmarking for the Fabric Softeners Market (qualitative capability ratings), 2026
| Company | Fragrance Technology | Sustainability and Reformulation | Format Innovation | Reach |
|---|---|---|---|---|
| Procter & Gamble | High | Medium | High | High |
| Unilever | High | High | High | High |
| Henkel | High | High | Medium | High |
| Colgate-Palmolive | Medium | Medium | Medium | High |
| SC Johnson | Low | High | Medium | Medium |
| Church & Dwight | Medium | Medium | Low | Medium |
| Kao Corporation | High | Medium | High | Medium |
| Lion Corporation | High | Medium | Medium | Medium |
| Seventh Generation | Low | High | Low | Low |
High indicates broad documented product or sustainability capability, Medium indicates selective capability, and Low indicates narrower documented capability for that company.
Key Developments in the Fabric Softeners Market
- In August 2026, Lion Corporation announced SOFLAN Aroma Rich moA, a premium fabric softener with plant-derived softening agents and natural aromatic oils, for nationwide Japanese retail launch in October 2026.
- In June 2025, Unilever relaunched Comfort's Core, Creations and Fresh & Protect fabric conditioner ranges in the UK, backed by a GBP 7.6 million marketing investment and expanded the Scent Booster Elixir line.
- In February 2026, Henkel relaunched the Vernel fabric softener range in Germany with fragrance capsule technology, 100% recycled plastic bottle bodies and a new Sensitiv line with dermatological confirmation.
- In February 2026, the European Union published Regulation 2026/405 on detergents and surfactants, introducing tighter biodegradability standards and a digital product passport requirement, with full application from September 2029.
Key Players in the Fabric Softeners Market
Global Portfolio Leaders
- Procter & Gamble
- Unilever
- Henkel
Regional and Specialist Brands
- Colgate-Palmolive
- Kao Corporation
- Lion Corporation
Eco-Focused and Niche
- SC Johnson
- Seventh Generation
- Church & Dwight
Fabric Softeners Market - Report Scope
Table 7: Report Scope for the Fabric Softeners Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Nature; product type; end use; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Revenue from the manufacture and sale of fabric softening and conditioning products, including liquid softeners, dryer sheets, sprays, tablets and dryer bars, used in residential, commercial laundry and industrial textile applications. Excludes laundry detergents, bleach, stain removers and in-wash scent boosters sold as standalone products. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Turkiye; Israel |
| Key companies profiled | Procter & Gamble; Unilever; Henkel; Colgate-Palmolive; SC Johnson; Church & Dwight; Seventh Generation; Kao Corporation; Lion Corporation |
| Forecast period | 2026 to 2036 |
| Approach | A hybrid bottom-up and top-down model, built to reconcile supplier revenue, trade data and consumer survey inputs within the defined revenue boundary, cross-checked against FMCG company filings and retailer scanner data. |
Fabric Softeners Market - Research Methodology
Table 8: Research Methodology for the Fabric Softeners Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with fabric softener brand managers, retail buyers and formulation chemists across six regions, supplemented by consumer focus groups and retailer panel data. |
| Desk Research | Analysis of FMCG annual reports, regulatory filings, patent databases, trade body publications and industry conference proceedings. |
| Market Sizing and Forecasting | Bottom-up build from national-level retail audit data and trade shipment volumes, calibrated against top-down estimates from company revenue disclosures and household consumption surveys. |
| Data Validation | Cross-referencing of estimates against FMCG earnings calls and customs trade records for fabric care chemicals. |
Fabric Softeners Market by Segments
Fabric Softeners Market segmented by Nature:
- Conventional
- Organic
Fabric Softeners Market segmented by Product Type:
- Liquid
- Sheets
- Sprays
- Tablets
- Dryer Bars
Fabric Softeners Market segmented by End Use:
- Household
- Laundry Services
- Hospitality Industry
- Textile Industry
- Others
Fabric Softeners Market segmented by Sales Channel:
- Supermarkets and Hypermarkets
- Specialty Retail Stores
- Online Sales
- Others
Fabric Softeners Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] AISE. (2025). 2025 AISE Consumer Research Report Summary. https://aise.eu/app/uploads/2025_AISE-consumer-research_report-summary.pdf
- [2] American Cleaning Institute / Wakefield Research. (2026, April 8). National Laundry Day: America's Laundry Habits Revealed. https://www.businesswire.com/news/home/20260408124834/en
- [3] Unilever. (2026, July). What's Behind Unilever's 2026 First Half Results. https://www.unilever.com/news/news-search/2026/whats-behind-unilevers-2026-first-half-results/
- [4] DQS Global. (2026). EU Updates Detergents Regulation (EU) 2026/405 Compliance Timelines. https://www.dqsglobal.com/en/explore/blog/eu-updates-detergents-regulation-eu-2026-405-compliance-timelines
- [5] Asian Trader. (2025, June 13). Comfort Relaunch Freshness Fabric Care Range. https://www.asiantrader.biz/comfort-relaunch-freshness-fabric-care-range-13-06-2025
- [6] Procter & Gamble. (2026, July). FY2526 Q4 AMJ Press Release. https://s204.q4cdn.com/332108499/files/doc_financials/2026/q4/FY2526-Q4-AMJ-Press-Release.pdf
- [7] Henkel. (2026, February 4). Henkel Pressemitteilung Vernel. https://www.henkel.de/resource/blob/2116398/5e3786b986c6be268df677ad30674cf8/data/2026-02-04-henkel-pressemitteilung-vernel.pdf
- [8] Lion Corporation. (2026, August 4). SOFLAN Aroma Rich moA Launch Announcement. https://www.lion.co.jp/en/newsroom/news/2026/5188
- [9] CIRS Group. (2026). EU Releases New Regulations for Detergents and Surfactants. https://www.cirs-group.com/en/cosmetics/eu-releases-new-regulations-for-detergents-and-surfactants-biodegradability-and-digital-product-passport-become-mandatory-requirements
- [10] Future Market Insights. (2025, April 5). Fabric Softeners Market Report. https://www.futuremarketinsights.com/reports/fabric-softeners-market
- [11] Unilever. (2026, February). What's Behind Unilever's 2025 Full Year Results. https://www.unilever.com/news/news-search/2026/whats-behind-unilevers-2025-full-year-results/
- [12] Colgate-Palmolive. (2026, January 30). Colgate-Palmolive Company Announces 4th Quarter and Full Year 2025 Results. https://investor.colgatepalmolive.com/news-releases/news-release-details/colgate-palmolive-company-announces-4th-quarter-and-full-year
- [13] Church & Dwight. (2026, July 31). Church & Dwight Delivers Strong Second Quarter Results. https://www.businesswire.com/news/home/20260731043652/en/
- [14] Henkel. (2026, May 7). Henkel Delivers Good Organic Sales Growth in the First Quarter of 2026. https://www.henkel.com/resource/blob/2155586/32095b1540a0e8ee499101a1eed0ab0d/data/henkel-quarterly-statement-q1-2026.pdf
- [15] Unilever. (2026, August 27). Unilever Home Care Transformation Reshapes Business and Accelerates Growth. https://www.unilever.com/news/news-search/2026/unilever-home-care-transformation-reshapes-business-and-accelerates-growth/
This Report Answers
- How big is the fabric softeners market during 2026?
- What value is projected by 2036?
- Which product type holds leading share?
- Which nature holds leading share?
- Which countries record leading growth?
- Which companies lead the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Liquid
- Sheets
- Sprays
- Tablets
- Dryer Bars
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Household
- Laundry Services
- Hospitality Industry
- Textile Industry
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Specialty Retail Stores
- Online Sales
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Product Type
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Procter & Gamble
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Unilever
- Henkel
- Colgate-Palmolive
- SC Johnson
- Church & Dwight
- Kao Corporation
- Lion Corporation
- Seventh Generation
- Procter & Gamble
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Nature
- Figure 6: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Type
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Nature
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End Use
- Figure 35: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sales Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Nature
- Figure 42: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Product Type
- Figure 45: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End Use
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Nature
- Figure 55: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Product Type
- Figure 58: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End Use
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Nature
- Figure 81: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Product Type
- Figure 84: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End Use
- Figure 87: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the fabric softeners market expected in 2026?
FMI's analysis places the fabric softeners market at USD 26.1 billion for 2026, rising from USD 24.8 billion in 2025. Revenue is projected at USD 43.8 billion by 2036, reflecting sustained growth from household laundry frequency and premiumisation of concentrated formats.
What CAGR is projected for the fabric softeners market through 2036?
FMI projects a 5.3% CAGR for the fabric softeners market from 2026 to 2036. Growth reflects rising wash frequency in emerging markets, format migration toward concentrated products and expansion of scent booster and fragrance capsule categories.
Which product type holds a leading market share in 2026?
Liquid fabric softeners hold 57.2% of product type demand in 2026. Automatic dispensing compatibility, established consumer dosing habits and the shift toward concentrated formulations anchor liquid at the top of the format mix.
Which nature holds a leading share in 2026?
Conventional formulations account for 86.5% of nature demand in 2026. Lower raw material costs for petroleum-derived cationic surfactants keep conventional products dominant, although organic and plant-based alternatives, a low-double-digit niche share, are gaining in markets with strong sustainability mandates.
Which country shows a leading expansion outlook through 2036?
China is profiled at a 6.5% CAGR from 2026 to 2036, the highest in the country set. Rising urban disposable income, demand for antibacterial and fragrant softeners and direct-to-consumer platform growth position China as the fastest-expanding country market.
Who are the key companies in the fabric softeners market?
Key companies include Procter & Gamble, Unilever, Henkel, Colgate-Palmolive, SC Johnson, Church & Dwight, Seventh Generation, Kao Corporation and Lion Corporation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
