

- Market Size (2026)
- USD 282.0 Mn
- Forecast (2036)
- USD 544.5 Mn
- CAGR (2026 to 2036)
- 6.8%
How big is Fiber-Based Meat Liners Market in 2026?
USD 282.0 million in 2026 and USD 544.5 million by 2036 at a 6.8% CAGR.
Demand for fiber-based meat liners is projected to expand at 6.8% CAGR between 2026 and 2036, increasing valuation from USD 282.0 million to USD 544.5 million. Recurring meat packaging systems need absorbent components that protect seals during continuous high-speed production cycles. USDA reported in August 2025 that poultry represented 51% of United States red meat and poultry disappearance in 2024, reinforcing repeat liner use across protein packaging formats.
Germany's larger industrial processing base creates broader material-recovery requirements than Japan's compact retail packaging programs. Destatis reported in February 2026 that German commercial slaughterhouses produced 6.9 million tonnes of meat during 2025. German fresh food packaging programs test bonded structures for practical recovery under national processor specifications. Japanese food tray formats require narrow dimensions for compact retail packs and controlled automated insertion lines.
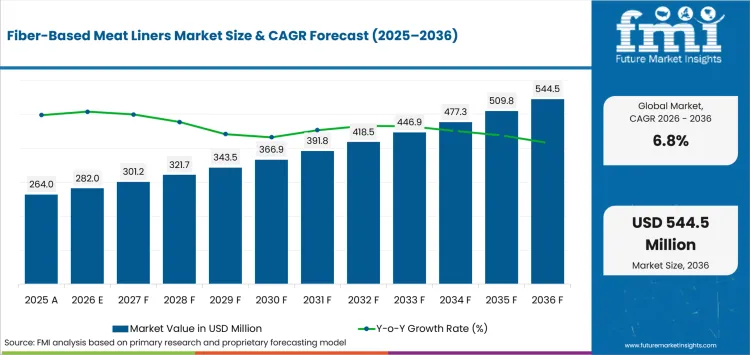
Key Takeaways of Fiber-Based Meat Liners Market
- Recurring fresh-protein output supports liner demand because every approved pack requires consistent purge control and seal protection.
- In 2026, Airlaid Absorbent Liners are projected to account for a 32.0% share due to adjustable absorbency and line-ready thickness.
- Airlaid Cellulose is estimated to hold a 34.0% share in 2026 owing to rapid uptake and flexible core conversion.
- Drip & Purge Absorption is forecast to represent a 40.0% share in 2026 driven by seal protection and visible fluid control.
- Full-pack qualification remains the material restraint because product weight and insertion speed can change laboratory absorption performance.
- Cellcomb AB, McAirlaid's Vliesstoffe GmbH, Coppice Alupack Ltd (Sirane), Novipax LLC, Elliott Absorbent Products Ltd, Tite-Dri Industries, Pomona Company Sp. z o.o. and MAGIC S.p.A. are the profiled companies.
Analyst Perspective
"Fiber-based meat liners earn approval by matching purge behavior with tray geometry and production speed. Strong manufacturers document every layer and prove compressed retention during commercial line trials to secure recurring orders."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Fiber-Based Meat Liners Market segmented?
The fiber-based meat liners market is segmented by product type, material, function, application, end use, sales channel and region.
Product Type includes Airlaid Absorbent Liners, Molded Fiber Tray Liners, Nonwoven Cellulose Liners, Interleaving Sheets and Others. Material covers Airlaid Cellulose, Fluff Pulp, Recycled Fiber, Bagasse - Agri-Fiber and Others, while Function includes Drip & Purge Absorption, Cushioning, Separation and Others. Application covers Fresh Red Meat, Poultry, Seafood, Processed Meats and Others, while End Use includes Meat Processors, Grocery Retail, Foodservice and Others. Sales Channel includes Direct - OEM Supply, Packaging Distributors, Online - E-commerce and Others across the standard regional taxonomy.
Why do airlaid absorbent liners lead the product type category?
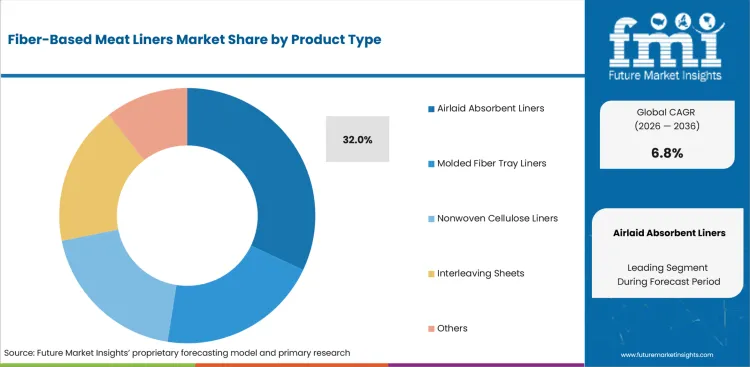
Airlaid liners distribute liquid across a thin porous core while retaining enough rigidity for automated insertion. Processors compare uptake speed with compressed retention across thermoformed tray alternatives during commercial qualification.
- Based on product type, airlaid absorbent liners are projected to account for 32.0% in 2026 due to adjustable basis weight and compact pack geometry.
- Line configuration determines whether a thin pad retains its operating value during commercial packing trials. In July 2026, ANDRITZ confirmed an order from MAGIC S.p.A. for a food pad eXcelle line with integrated airlaid forming technology at Oleggio, Italy, with commissioning scheduled for the first quarter of 2027. Controlled forming governs absorption and retention in pads used for meat, fish and fruit packs.
Why does airlaid cellulose lead the material category?
Airlaid cellulose forms an open web that acquires purge without requiring a bulky insert. Manufacturers adjust fiber weight and sealed edges for tray depths used beside moulded fiber pulp formats in chilled protein programs.
- By Material, airlaid cellulose is estimated to hold 34.0% in 2026 owing to rapid uptake and broad conversion flexibility.
- Material architecture also affects disposal claims and sealed-edge handling during processor qualification. In October 2025, Cellcomb AB retained sealed-edge construction while renaming Cellsorb ECO as Cellsorb CORE. The company separately documented industrial and home compost certification for the Cellsorb CIRCULAR cellulose format.
How does drip & purge absorption define the function category?
Free liquid can reach the seal area and weaken package appearance during chilled storage or retailer display. Effective liners acquire purge quickly and retain it under product weight beside cellulose film packaging.
- In 2026, drip & purge absorption is expected to lead the Function category with 40.0% share due to its direct role in leakage control.
- Regulatory records define which absorbent chemistry can contact specific fresh-protein categories. The FDA's Food Contact Substance Notification No. 1533 identifies a McAirlaid's absorbent core for poultry, red meat, fish and seafood packaging. The record establishes direct food-contact relevance but does not prove the modeled share within the 2026 function category.
Why does direct - OEM supply lead the sales channel category?
Direct programs connect liner design with tray dimensions and sealing conditions during plant qualification. Manufacturers receive operating data that supports scheduled samples beside vacuum skin paperboard and other competing pack structures.
- By sales channel, direct - OEM supply is forecast to represent 46.0% in 2026 driven by technical qualification and recurring plant-level commitments across multi-site processor accounts.
- Food-contact scope shapes the formulation records exchanged during direct processor qualification. Fiber-based cores and any bonded film or nonwoven layers each require their own documented food-contact basis before a processor approves recurring supply. Direct technical contact also helps processors control feeding behavior across several qualified tray configurations.
What are the drivers, restraints and opportunities in the Fiber-Based Meat Liners Market?
Repeat protein throughput supports liner demand, though full-pack qualification slows switching and simpler fiber structures improve the route to recurring contracts.
- Driver: Meat processors require repeatable purge control that protects seals and retail presentation across scheduled production programs.
- Restraint: Food-contact records and feeding behavior extend qualification across every complete tray and barrier configuration.
- Opportunity: Fiber-rich liners with clear material classification can strengthen direct processor programs and support recurring specifications.
Recurring fresh-protein output produces repeat demand because every tray requires a defined fluid-control component during packing. Packaging engineers match absorption capacity with cut weight and expected storage across approved meat and seafood packs. A successful specification reduces leakage rework and converts one trial into recurring orders across several processor lines.
Qualification remains the central restraint because laboratory uptake does not establish performance inside a moving chilled pack. In January 2025, the FDA determined that authorizations for 35 PFAS-related food-contact notifications were no longer effective. The action increases the value of complete formulation records during coating review and controlled supplier changes.
Bagasse - Agri-Fiber is expected to post the fastest material growth from a small base as manufacturers reduce reliance on plastic-rich constructions. PackUK published different illustrative 2026-27 fee treatments for red-rated fiber composites and paper or board in December 2025. Manufacturers need simple structures and defensible classification before processor trials can convert this route into recurring fiber-based packaging orders.
Which country CAGRs are profiled in the Fiber-Based Meat Liners Market?
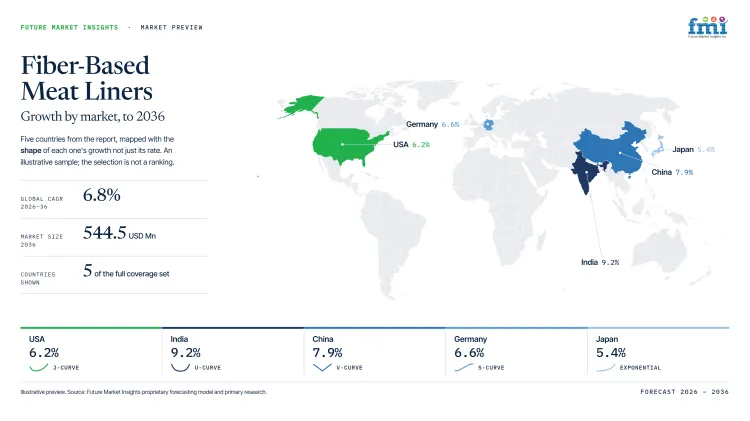
| Country | CAGR |
|---|---|
| Brazil | 7.2% |
| United Kingdom | 6.7% |
| Germany | 6.6% |
| United States | 6.2% |
| Japan | 5.4% |
How do country-level CAGRs compare in the Fiber-Based Meat Liners Market?
The five country forecasts span 1.8 percentage points from Brazil at 7.2% to Japan at 5.4%. The range measures projected pace and does not establish current revenue or installed processing volume.
- Brazil combines large inspected protein output with export routes that raise wet-strength and regional inventory requirements.
- The United Kingdom links retailer specifications with package classification and direct processor reporting across private-label programs.
- Germany evaluates practical material recovery beside food-contact performance for every bonded liner and barrier structure.
- The United States rewards dependable insertion across established high-speed lines and multi-plant case-ready packaging programs.
- Japan favors narrow dimensional tolerances and stable local conversion across compact retail packs and controlled approvals.
Comparable CAGRs reflect different qualification and distribution conditions across national packaging programs and material rules. The full report compares country-level CAGRs across seven standard regions without treating growth pace as current market scale.
Country-wise Analysis
- Brazilian exporters run high-volume beef and poultry programs that expose absorbent liners to long chilled routes and repeated handling across national logistics hubs and supermarket replenishment cycles. With inspected slaughter reaching 42.94 million cattle and 6.69 billion chickens during 2025, Brazilian fiber-based meat liner sales are expected to register 7.2% CAGR to 2036, underpinned by record protein throughput across both domestic and export programs. Local price pressure favors basic inserts and can delay conversion, so manufacturers need verified wet strength plus regional inventory and technical service that protects production continuity during seasonal peaks and sudden export schedule changes.
- United Kingdom meat packers operate within retailer-led programs that connect liner geometry with seal performance and packaging reporting across private-label product ranges at major national retail chains. The United Kingdom's fiber-based meat liners outlook is anticipated to advance at 6.7% CAGR over the assessment period, supported by DEFRA reporting in July 2026 that total domestic meat production reached 4.117 million tonnes during 2025. Material classification remains a practical friction across bonded fiber structures. Manufacturers need complete composition records and pack-level trials that support the intended reporting route without disrupting established tray sealing or repeat retailer approval schedules.
- German processors evaluate absorbent liners against high production speeds and practical recovery conditions across the complete used package for chilled red meat and poultry programs. A 6.6% CAGR is projected for German fiber-based meat liner demand through 2036, reflecting a commercial slaughter base that produced 6.9 million tonnes of meat during 2025 and a packaging register minimum standard that sets recovery expectations for bonded structures. Food contamination and bonded barrier layers can reduce recoverable content, so manufacturers need package-level evidence that connects liner construction with the applicable paper or composite pathway during processor qualification and retailer review across national fresh-protein programs without delayed approvals.
- United States processors use direct case-ready programs that link liner dimensions with high-speed insertion and repeat specifications across several plants with centralized specification control. The United States fiber-based meat liners sector is projected to record 6.2% CAGR during the assessment period, supported by USDA reporting in June 2025 that total poultry sector sales reached USD 70.2 billion during 2024. Formulation records and feeding behavior remain separate frictions, so manufacturers need complete food-contact documentation plus plant trials that confirm clean separation and consistent absorbency across meat cuts with different purge profiles and national retail requirements during seasonal product changes.
- Japanese processors favor compact retail formats with limited thickness clearance and stable dimensions across repeat deliveries to regional supermarkets and convenience channels using several tray sizes on established automated lines during frequent product changes. MAFF reported in May 2025 that April slaughter reached 1.38 million pigs and 94,940 adult cattle across regular national processing activity and established wholesale distribution serving chilled retail protein programs. Fiber-based meat liner demand in Japan is predicted to advance at 5.4% CAGR through 2036, but long approvals require dependable local converters and narrow controls for thickness plus edge sealing and absorption capacity.
Who are the notable companies in the Fiber-Based Meat Liners Market?
Cellcomb AB, McAirlaid's Vliesstoffe GmbH, Coppice Alupack Ltd (Sirane), Novipax LLC, Elliott Absorbent Products Ltd, Tite-Dri Industries, Pomona Company Sp. z o.o. and MAGIC S.p.A. are the notable companies serving this market.
The field remains fragmented across absorbent-core producers, finished-pad converters and material-platform companies. Processors compare compressed retention, feeding reliability and food-contact records before approving recurring supply. Entry requires repeatable conversion quality plus trials across several tray formats and line speeds. Scale alone does not replace documented performance inside the complete chilled pack or dependable technical support for specification changes linked with molded-fiber coatings.
- Cellcomb AB, McAirlaid's Vliesstoffe GmbH and MAGIC S.p.A. compete around airlaid fiber architecture and controlled absorbent-material supply.
- Coppice Alupack Ltd, Novipax LLC and Elliott Absorbent Products Ltd compete with sealed pads and line-ready cut or reel formats.
- Tite-Dri Industries and Pomona Company Sp. z o.o. compete through food-pad conversion and documented quality systems for fresh-protein packaging.
Competitive Benchmarking: Fiber-Based Meat Liners Market
| Company | Purge-Control Evidence | Line-Ready Format Control | Fiber End-of-Life Evidence | Geographic Reach |
|---|---|---|---|---|
| Cellcomb AB | High | High | High | Europe and international customers |
| McAirlaid's Vliesstoffe GmbH | High | Medium | Medium | Europe, North America and export markets |
| Coppice Alupack Ltd (Sirane) | High | High | Medium | United Kingdom, Europe and North America |
| Novipax LLC | High | High | Medium | North America |
| Elliott Absorbent Products Ltd | High | High | Medium | United Kingdom, Europe and international stockists |
| Tite-Dri Industries | High | High | Medium | North America and international programs |
| Pomona Company Sp. z o.o. | High | Medium | High | Europe and export markets |
| MAGIC S.p.A. | Medium | Medium | Not scored | Global specialty-material operations |
Key Developments in the Fiber-Based Meat Liners Market
- In July 2026, MAGIC S.p.A. placed an order with ANDRITZ for a food pad eXcelle production line incorporating airlaid forming technology at its Oleggio site in Italy, with commissioning scheduled for the first quarter of 2027. The investment adds dedicated forming capacity for absorbent pads used with meat, fish and fruit. Processor packaging teams gain an additional qualified European conversion route for airlaid protein pads.
- In June 2025, Cellcomb announced the acquisition of Finnish company Fatex, executed through its parent company Löftet Holding AB. The combined group reported approximately EUR 30 million in annual turnover and about 90 employees across Säffle in Sweden and Kronoby in Finland. The acquisition broadened regional fiber conversion and manufacturing coverage for recurring food-pad programs while improving technical service across Nordic accounts.
- In August 2024, Coppice Alupack Ltd acquired the business and certain assets of Telford-based Sirane Limited from the joint administrators appointed on 15 July 2024. The transaction secured continuity of Sirane's absorbent pad development and manufacturing operations. Processors retained an established United Kingdom supply route for meat and seafood pads under new ownership.
Key Players in the Fiber-Based Meat Liners Market
Airlaid Fiber and Absorbent-Core Platforms
- Cellcomb AB
- McAirlaid's Vliesstoffe GmbH
- MAGIC S.p.A.
Converted Protein-Pad Manufacturers
- Coppice Alupack Ltd (Sirane)
- Novipax LLC
- Elliott Absorbent Products Ltd
Regional Food-Pad Specialists
- Tite-Dri Industries
- Pomona Company Sp. z o.o.
Fiber-Based Meat Liners Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, material, function, application, end use, sales channel and region. |
| Quantitative Units | Revenue in USD million and CAGR in %. |
| Market Definition | Commercial fiber-based absorbent or protective liners sold for meat, poultry, seafood and processed-meat packs. Finished trays, films, machinery, padless systems and non-fiber absorbents are excluded from revenue. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | Brazil, United Kingdom, Germany, United States, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | Cellcomb AB, McAirlaid's Vliesstoffe GmbH, Coppice Alupack Ltd (Sirane), Novipax LLC, Elliott Absorbent Products Ltd, Tite-Dri Industries, Pomona Company Sp. z o.o. and MAGIC S.p.A. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Fiber-Based Meat Liners Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Fiber-Based Meat Liners Market by Segments
Fiber-Based Meat Liners Market segmented by Product Type:
- Airlaid Absorbent Liners
- Molded Fiber Tray Liners
- Nonwoven Cellulose Liners
- Interleaving Sheets
- Others
Fiber-Based Meat Liners Market segmented by Material:
- Airlaid Cellulose
- Fluff Pulp
- Recycled Fiber
- Bagasse - Agri-Fiber
- Others
Fiber-Based Meat Liners Market segmented by Function:
- Drip & Purge Absorption
- Cushioning
- Separation
- Others
Fiber-Based Meat Liners Market segmented by Application:
- Fresh Red Meat
- Poultry
- Seafood
- Processed Meats
- Others
Fiber-Based Meat Liners Market segmented by End Use:
- Meat Processors
- Grocery Retail
- Foodservice
- Others
Fiber-Based Meat Liners Market segmented by Sales Channel:
- Direct - OEM Supply
- Packaging Distributors
- Online - E-commerce
- Others
Fiber-Based Meat Liners Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Economic Research Service, USA Department of Agriculture. (2025, August 21). Poultry & Eggs.
- Federal Statistical Office of Germany. (2026, February 13). Fleischproduktion im Jahr 2025 nahezu unverändert.
- Coppice Alupack Ltd (Sirane). (2024, March 27). ABSORBENT PADS: In-Flex absorbent pad for pre-padding lines still popular after 20 years.
- Cellcomb AB. (2025, October 24). Cellsorb® ECO becomes Cellsorb® CORE.
- U.S. Food and Drug Administration. (accessed 2026, August 7). Food Contact Substance Notification No. 1533.
- U.S. Food and Drug Administration. (2025, January 3). FDA Determines Authorization for 35 Food Contact Notifications Related to PFAS Are No Longer Effective.
- PackUK and Department for Environment, Food & Rural Affairs. (2025, December 19). Year 2 illustrative waste disposal fees: Extended producer responsibility for packaging.
- Brazilian Institute of Geography and Statistics. (2026, March 18). In 2025, Brazil registers the highest production of milk, leather and eggs in history; slaughter of cattle, chickens and pigs also hits record.
- Department for Environment, Food & Rural Affairs. (2026, July 29). Chapter 8: Livestock.
- Central Agency Packaging Register. (2025, August 29). 2025 minimum standard published - initial touchstone for companies preparing for the EU Packaging and Packaging Waste Regulation (PPWR).
- Economic Research Service, USA Department of Agriculture. (2025, June 25). Poultry & Eggs - Sector at a Glance.
- Ministry of Agriculture, Forestry and Fisheries of Japan. (2025, May 30). Meat Distribution Statistics, April 2025.
- ANDRITZ Group. (2026, July 14). MAGIC S.p.A., Oleggio, Italy, orders a new food pad production line, including airlaid technology from ANDRITZ.
- Interpath Advisory. (2024, August 5). Future of Sirane secured following deal with Coppice Alupack.
- Pomona Company Sp. z o.o. (accessed 2026, August 7). About us.
- Cellcomb AB. (2025, June 4). Cellcomb acquires Fatex.
- ANDRITZ Group. (2026, July 14). MAGIC S.p.A., Oleggio, Italy, orders a new food pad production line, including airlaid technology from ANDRITZ
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fiber-based meat liners market in 2026 and 2036?
- Which processor conditions support recurring demand for purge-control liners?
- Why do Airlaid Absorbent Liners account for 32.0% of 2026 demand?
- How does Airlaid Cellulose influence absorption and package conversion?
- Why does Drip & Purge Absorption hold the leading function position?
- How do growth conditions differ across Brazil, the United Kingdom, Germany, the United States and Japan?
- Which companies supply absorbent cores, converted pads or line-ready food-pad formats?
- What qualification and material-classification factors delay wider adoption?
- What should processor packaging teams test before approving a fiber-based meat liner?
Frequently Asked Questions
How big is the Fiber-Based Meat Liners Market in 2026?
The fiber-based meat liners market is valued at USD 282.0 million in 2026 and is projected to reach USD 544.5 million by 2036, expanding at a 6.8% CAGR.
What is the CAGR of the Fiber-Based Meat Liners Market from 2026 to 2036?
The fiber-based meat liners market is projected to grow at a CAGR of 6.8% between 2026 and 2036. Expansion is supported by the need for effective purge control, sustainable packaging materials, and consistent performance across processing operations.
Which product type segment leads the Fiber-Based Meat Liners Market?
Airlaid absorbent liners are projected to account for 32.0% of the market in 2026. Their leading share is supported by high absorbency, customizable basis weights, and compatibility with automated packaging lines.
Which material segment grows fastest in the Fiber-Based Meat Liners Market?
Bagasse agri-fiber is expected to be the fastest-growing material segment through 2036. Growth is driven by increasing interest in renewable fiber sources that deliver wet-strength performance while supporting sustainability objectives.
Which companies are active in the Fiber-Based Meat Liners Market?
Key companies operating in the market include Cellcomb AB, McAirlaid's Vliesstoffe GmbH, Coppice Alupack Ltd, Novipax LLC, Elliott Absorbent Products Ltd, Tite-Dri Industries, Pomona Company Sp. z o.o., and Magnera Corporation. These companies provide absorbent liner materials and finished packaging solutions for meat processing and food packaging applications.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Airlaid Absorbent Liners
- Molded Fiber Tray Liners
- Nonwoven Cellulose Liners
- Interleaving Sheets
- Others
- Airlaid Absorbent Liners
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material, 2026 to 2036
- Airlaid Cellulose
- Fluff Pulp
- Recycled Fiber
- Bagasse - Agri-Fiber
- Others
- Airlaid Cellulose
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Function, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Function, 2026 to 2036
- Drip & Purge Absorption
- Cushioning
- Separation
- Others
- Drip & Purge Absorption
- Y-o-Y Growth Trend Analysis By Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Function, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Fresh Red Meat
- Poultry
- Seafood
- Processed Meats
- Others
- Fresh Red Meat
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Meat Processors
- Grocery Retail
- Foodservice
- Others
- Meat Processors
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct - OEM Supply
- Packaging Distributors
- Online - E-commerce
- Others
- Direct - OEM Supply
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material
- By Function
- By Application
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- McAirlaid's
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cellcomb
- Sirane
- Novipax
- Sealed Air
- Maxwell Chase Technologies
- Gelok International
- Huhtamaki
- Brodrene Hartmann
- Cascades
- McAirlaid's
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


