
- Market Size (2026)
- USD 2.5 Bn
- Forecast (2036)
- USD 4.2 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Ion Exchange Resins Market in 2026?
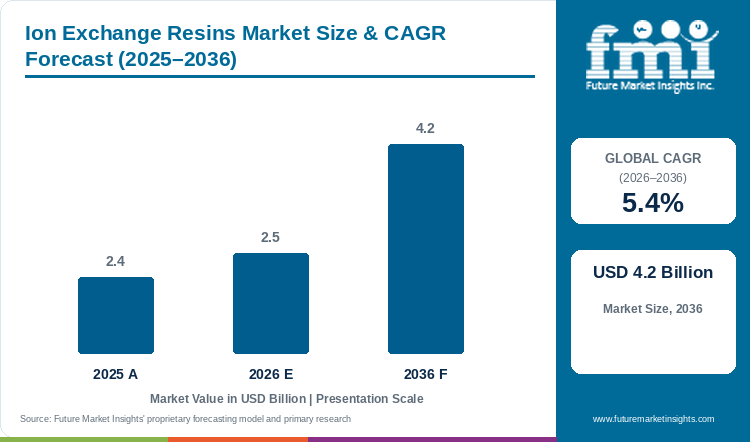
Starting from USD 2.4 billion in 2025, the ion exchange resins market valuation advanced to USD 2.5 billion in 2026, with projections pointing toward USD 4.2 billion by 2036 at a CAGR of 5.4%.
The global ion exchange resins market was valued at USD 2.4 billion in 2025 and is estimated to reach USD 2.5 billion in 2026. Total industry valuation is projected to reach USD 4.2 billion by 2036, expanding at a compound annual growth rate (CAGR) of 5.4% between 2026 and 2036. Strong Acid Cation (SAC) Resins are estimated to capture a leading 42.0% share of 2026 resin chemistry demand, given that industrial boilers and municipal softeners rely on sulfonated polystyrenic beads for continuous hardness removal. Formulation trend analysis by FMI indicates that procurement of cation, anion, and chelating resin beds is accelerating as enforceable trace-contaminant drinking water rules and sub-part-per-billion semiconductor rinse tolerances convert optional polishing stages into mandatory multi-vessel installations.
That compliance-driven replacement cycle distinguishes resin procurement from the faster-growing ultrapure water systems sector at an 8.0% CAGR, since plant owners purchase capital skids once during fab construction but reorder replacement resin charges every three to five years as oxidative fouling degrades exchange capacity. Regulatory enforcement is directly expanding municipal vessel orders, as the US Environmental Protection Agency advanced Drinking Water Act PFAS compliance updates in May 2026 requiring public water systems to strip perfluoroalkyl substances down to 4 parts per trillion using selective anion exchange beds. Suppliers are simultaneously introducing specialized industrial formulations to capture process purification budgets, highlighted when DuPont launched its AmberLite FPA57 weak base anion resin in January 2026 to raise organic acid purification yields and lower regenerant chemical consumption. Industrial water operators and chemical processors renew resin supply contracts based on bed cycle longevity and low pressure drop, ensuring that monodisperse beads cutting acid and caustic regeneration waste secure long-term plant specifications through 2036.
Key Market Trends & Insights
- By resin chemistry: Strong Acid Cation (SAC) Resins hold an estimated 42.0% share in 2026 given that sulfonated functional groups provide high exchange capacity across municipal softening and boiler demineralization trains.
- By polymer matrix: Styrene-Divinylbenzene Crosslinked Matrix represents 68.0% in 2026 since aromatic crosslinking resists thermal degradation and mechanical bead attrition during high-flow regeneration.
- By end-use industry: Water Softening and Deionization Demineralization accounts for 52.0% in 2026 owing to mandatory scale prevention in utility steam turbines and industrial cooling circuits.
- By bead structure: Gel-Type Microporous Beads secure 56.0% in 2026 on account of higher volumetric ionic capacity and lower synthesis cost in clear-water treatment vessels.
- By operating mode: Regenerable Service-Cycle Systems command 64.0% in 2026 through automated acid and brine backwash skids that extend resin bed life across multi-year industrial duty.
Regional Highlights
- Top national expansion: India leads national growth projections at a 6.8% CAGR through 2036 under semiconductor fab ultrapure water buildouts and zero-liquid-discharge industrial effluent rules.
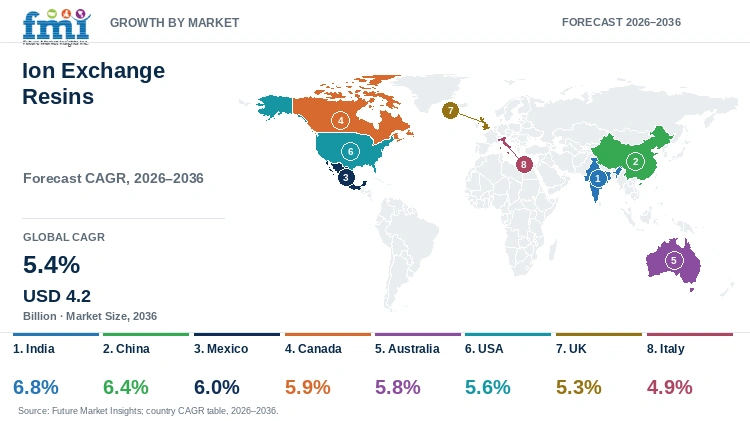
- Broader country progression: China tracks at a 6.4% CAGR ahead of Mexico at 6.0% and Canada at 5.9%, whereas Australia follows at 5.8% and the USA, the UK, and Italy record 5.6%, 5.3%, and 4.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ion Exchange Resins Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.4 billion |
| Estimated Market Size in 2026 | USD 2.5 billion |
| Projected Market Size by 2036 | USD 4.2 billion |
| CAGR, 2026 to 2036 | 5.4% |
| Added Revenue, 2026 to 2036 | USD 1.7 billion |
Power generation plants, semiconductor wafer fabs, and municipal water utilities confront rising raw-water dissolved solids and strict trace-ion discharge limits that overload conventional filtration media. When industrial operators rely solely on single-stage membrane filtration without downstream ion exchange polishing, trace silica, boron, and hardness ions slip into high-pressure boilers and microelectronic rinse baths. Official data from June 2026 data released by Eurostat, European Union member states invested EUR 79.0 billion in environmental protection assets in 2025, with wastewater treatment projects capturing 37.7% of total capital expenditure as corporations spent EUR 49.6 billion upgrading plant effluent control systems. Consequently, industrial water engineers pair automated water softeners with mixed-bed cation and anion resin columns to achieve sub-ppb ionic purity and zero-scale thermal operation.
Installed Resin Volume and Dosing Economics
Table 2: Installed Resin Bed Volume and Operating Economics for the Ion Exchange Resins Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.4 | 2.5 | 4.2 |
| Global commercial resin production volume (thousand cubic meters) | 710.0 to 760.0 | 745.0 to 795.0 | 1,180.0 to 1,260.0 |
| Average industrial bulk resin price (USD per liter) | 2.8 to 3.4 | 2.9 to 3.5 | 3.2 to 3.9 |
| Specialty PFAS, UPW & bioprocessing resin value share (%) | 24.0% to 27.0% | 25.5% to 28.5% | 36.0% to 40.0% |
Municipal drinking water authorities and industrial remediation engineers require selective quaternary ammonium functional groups on hydrophobic resin matrices to capture short-chain and long-chain fluorochemicals before bed breakthrough occurs. Technical treatment benchmarks published by the US Environmental Protection Agency confirm that anion exchange resins operated at empty-bed contact times of 1.5 to 3.0 minutes strip perfluorooctane sulfonate and perfluorooctanoic acid below 4 parts per trillion across thousands of bed volumes before incineration or regeneration. That rapid adsorption kinetics profile prompts utilities building deionized water systems to install lead-lag selective resin vessels occupying one-fourth the land footprint of granular activated carbon contactors.
Hydrometallurgical & Ultrapure Water Demand Indicators
Table 3: Industrial Water and Hydrometallurgical Resin Demand Indicators for the Ion Exchange Resins Market (operational metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global lithium mine output requiring brine/refining purification (thousand MT, USGS basis) | 290.0 | 325.0 | 740.0 |
| EU corporate & public wastewater treatment capex share of environmental investment (%) | 37.7% | 38.2% | 42.5% |
| Typical municipal PFAS anion exchange empty-bed contact time (minutes, US EPA basis) | 1.5 to 3.0 | 1.5 to 3.0 | 1.2 to 2.5 |
| Uniform particle size (UPS) monodisperse share of new industrial vessels (%) | 38.0% to 42.0% | 40.0% to 44.0% | 55.0% to 60.0% |
Table 4: Sectoral Resin Allocation & Institutional Reference Indicators for the Ion Exchange Resins Market (USD billion and reference basis), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 2.5 billion | 2026 global revenue baseline |
| EU environmental protection asset investment, 2025 | EUR 79.0 billion (37.7% wastewater) | Eurostat Environmental Protection Expenditure 2026 release |
| US EPA enforceable PFOA and PFOS drinking water limit | 4.0 parts per trillion (ppt) | US EPA National Primary Drinking Water Regulation |
| Water Softening and Deionization Demineralization allocation, 2026 | USD 1.3 billion | 52.0% primary end-use industry share |
Battery-grade lithium carbonate refiners and uranium miners steadily replace evaporative solar ponds with direct ion exchange adsorption and elution columns to shorten processing times and recover metals from low-grade brines. As documented in the February 2026 Mineral Commodity Summaries from the US Geological Survey, global mine production of lithium climbed 31% to 290,000 metric tons in 2025 while global lithium consumption rose 20% to 263,000 metric tons, prompting brine operators in South America and China to commission chelating and selective aluminum-loaded ion exchange extraction trains. Plant designers integrating zero liquid discharge systems and selective chelating columns recover both battery-grade metal salts and reusable process water.
Analyst Perspective
"Industrial plant managers and municipal water directors no longer purchase ion exchange resins as interchangeable commodity beads, as they buy verified bed-volume longevity, lower acid and caustic regenerant consumption, and guaranteed part-per-trillion contaminant capture. Resin manufacturers that combine monodisperse jetted bead geometry with application-specific chelating and PFAS-selective functional groups are positioned to lock in recurring vessel refill contracts through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Ion Exchange Resins Market segmented?
The ion exchange resins market is segmented by resin chemistry, polymer matrix, end-use industry, bead structure, and operating mode. In 2026, Strong Acid Cation (SAC) Resins are projected at 42.0%, Styrene-Divinylbenzene Crosslinked Matrix at 68.0%, Water Softening and Deionization Demineralization at 52.0%, Gel-Type Microporous Beads at 56.0%, and Regenerable Service-Cycle Systems at 64.0%.
By resin chemistry: Strong Acid Cation (SAC) Resins, Weak Acid Cation (WAC) Resins, Strong Base Anion (SBA) Resins, Weak Base Anion (WBA) Resins, and Chelating and Selective Ion Resins.
By polymer matrix: Styrene-Divinylbenzene Crosslinked Matrix, Polyacrylic Ester Crosslinked Matrix, Phenol-Formaldehyde Condensate Matrix, and Epichlorohydrin-Amine & Magnetic Hybrid Matrix.
By end-use industry: Water Softening and Deionization Demineralization, Pharmaceutical Drug Formulation and Taste-Masking, Food and Beverage Sugar Decolorization and Dairy Whey Demineralization, Chemical Processing Reaction Recovery and Hydrometallurgy Mining, and Semiconductor Ultrapure Water & Nuclear Condensate Polishing.
By bead structure: Gel-Type Microporous Beads, Macroporous Macroreticular Beads, Uniform Particle Size (UPS) Monodisperse Beads, and Powdered Precoat & Fine-Mesh Resins.
By operating mode: Regenerable Service-Cycle Systems, Single-Use Non-Regenerable Cartridges, Mixed-Bed Polishing Units, and Continuous Counter-Current Moving-Bed Systems.
Why do Strong Acid Cation (SAC) Resins lead the resin chemistry category?
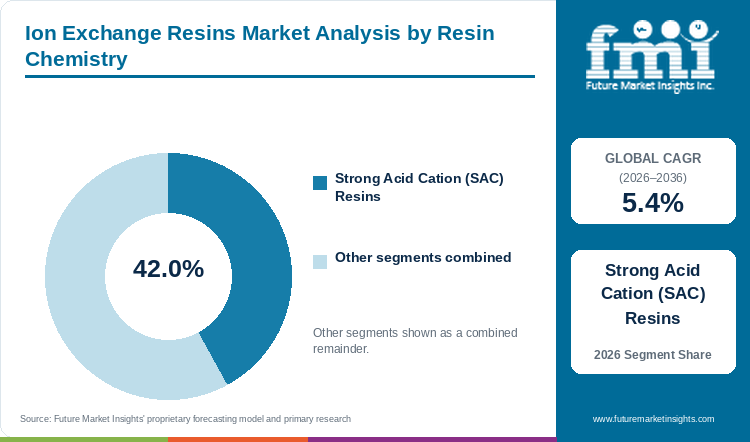
Strong Acid Cation (SAC) Resins hold an estimated 42.0% of resin chemistry demand in 2026, anchored by universal hardness and sodium splitting across industrial steam and municipal water systems.
Table 5: Resin Chemistry Share for the Ion Exchange Resins Market (percentage share), 2026
| Resin Chemistry | Share (2026) |
|---|---|
| Strong Acid Cation (SAC) Resins | 42.0% |
| Other Segments Combined | 58.0%* |
| Total | 100.0% |
*Note: Remaining resin chemistry categories account for the balance of 2026 global ion exchange resins demand.
Table 6: Resin Chemistry Leadership and Market Growth for the Ion Exchange Resins Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Leading Segment | Strong Acid Cation (SAC) Resins |
Strong Acid Cation (SAC) Resins functionalized with sulfonic acid groups operate across the entire pH range from 0 to 14, enabling industrial power plants and municipal softening facilities to split neutral salts and strip calcium, magnesium, iron, and sodium ions at high linear flow velocities. Procurement engineers managing high-pressure steam generators pair SAC beds with boiler water treatment chemicals to prevent turbine blade scaling and heat-exchanger tube failures. Despite their low per-liter price and broad operational versatility, SAC resins face practical hurdles from iron fouling, residual chlorine oxidation that cleaves polymer crosslinks, and strict municipal limits on sodium chloride brine discharge.
- Within the resin chemistry segment, Strong Acid Cation (SAC) Resins are projected to account for a leading 42.0% share in 2026, driven by continuous hardness removal across industrial steam boilers and municipal softening skids.
- DuPont published its updated AmberLite Water Conditioning Engineering Manual in September 2025, demonstrating how packed-bed Upcore counter-current regeneration cuts salt and rinse-water consumption across industrial SAC softening vessels.
What sustains Styrene-Divinylbenzene Crosslinked Matrix leadership in the polymer matrix segment?
Styrene-Divinylbenzene Crosslinked Matrix formats represent 68.0% of the polymer matrix category in 2026, supported by high osmotic stability and multi-year thermal endurance.
Styrene-Divinylbenzene (S-DVB) Crosslinked Matrix resins form a hydrophobic aromatic backbone whose physical rigidity and swelling resistance can be precisely tuned by adjusting divinylbenzene crosslinking levels between 4% and 16%. Industrial water operators placing S-DVB beds downstream of polymeric membrane filtration skids achieve multi-year mechanical bead integrity even under cyclic osmotic shock and high-temperature condensate polishing. Active supplier innovation continues to expand specialized bioprocessing matrices beyond S-DVB, as seen when Ecolab Life Sciences launched its Purolite AP+50 affinity chromatography resin with a 50-micron jetted agarose matrix in June 2025 to raise monoclonal antibody capture capacity. Nevertheless, petrochemical styrene and divinylbenzene monomer volatility periodically squeezes manufacturer margins on standard S-DVB grades.
- In 2026, Styrene-Divinylbenzene Crosslinked Matrix resins are anticipated to capture 68.0% of global polymer matrix demand, reflecting buyer preference for thermally stable aromatic beads that resist crushing in deep-bed vessels.
- While S-DVB matrices retain volume dominance across utility demineralization, polyacrylic ester matrices are projected to gain incremental share in sugar decolorization and high-organic surface waters where hydrophilic backbones resist irreversible humic fouling.
How does Water Softening and Deionization Demineralization lead the end-use industry category?
Water Softening and Deionization Demineralization accounts for 52.0% of end-use industry demand in 2026, driven by boiler scale prevention and industrial water reuse.
Water Softening and Deionization Demineralization represents the foundational volume anchor for global resin consumption, given that thermal power stations, chemical refineries, pulp mills, and municipal utilities must continuously strip dissolved minerals from makeup and feedwater streams. Plant engineers integrating two-bed and mixed-bed deionizers with water desalination and purification equipment protect high-pressure boilers and cooling towers from silica deposition and caustic embrittlement. However, maturing coal-fired power fleets in Western markets and rising competition from two-pass reverse osmosis coupled with electrodeionization constrain baseline volume growth in standard boiler softening.
- By end-use industry, Water Softening and Deionization Demineralization is estimated to reach 52.0% of total category share in 2026 as industrial and municipal operators prioritize scale-free steam generation and process water recycling.
- Mitsubishi Chemical Group expanded production capacity for its DIAION semiconductor-grade ion exchange resins at its Fukuoka facility in October 2024 to meet accelerating ultrapure water deionization demand across East Asian chip fabrication plants.
Why do Gel-Type Microporous Beads lead the bead structure category?
Gel-Type Microporous Beads secure 56.0% of bead structure share in 2026, supported by high volumetric ionic exchange capacity and lower regenerant chemical consumption.
Gel-Type Microporous Beads lack permanent discrete pores in the dry state but swell uniformly in aqueous streams to expose a dense interior network of exchange sites, delivering 15% to 25% higher operating ionic capacity per cubic meter than macroporous equivalents. That volumetric efficiency lowers vessel steel diameter and cuts acid or caustic regenerant consumption per kilograin of removed hardness. Technical product data released by DuPont in August 2025 for its AmberLite HPR1600 H gel-type uniform particle size strong acid cation resin confirmed a total exchange capacity of at least 2.40 equivalents per liter and up to 20% longer hydrogen-cycle run lengths for high-flow industrial demineralization. Even so, gel beads remain vulnerable to physical cracking when exposed to rapid osmotic shocks or severe oxidant spikes.
- Strong repeat ordering across municipal and industrial softening plants places Gel-Type Microporous Beads on course to hold an estimated 56.0% share of the bead structure category in 2026.
- Adoption of Uniform Particle Size (UPS) monodisperse gel and macroporous beads is forecast to accelerate fastest through 2036 as packed-bed counter-current vessels replace traditional polydisperse gravity columns.
What gives Regenerable Service-Cycle Systems the leading position in operating mode?
Regenerable Service-Cycle Systems command 64.0% of operating mode share in 2026, anchored by automated acid, caustic, and brine multi-cycle vessel operation.
Regenerable Service-Cycle Systems allow plant operators to restore exhausted cation and anion resin beds in place using hydrochloric acid, sulfuric acid, sodium hydroxide, or sodium chloride brine over hundreds of consecutive operating cycles. Large industrial demineralizers and municipal nitrate removal plants favor regenerable vessels over throwaway cartridges given that multi-year bead reuse reduces per-cubic-meter treatment expenditure by more than 60%. On the other hand, managing spent acidic and saline regeneration eluates requires neutralization tanks and environmental discharge permits that complicate operations in landlocked facilities.
- Regenerable Service-Cycle Systems are predicted to secure 64.0% of operating mode demand in 2026, supported by automated programmable-logic-controller backwash skids across utility and chemical plants.
- Technical analysis published by Ion Exchange (India) Limited in September 2026 documented that sensor-automated regeneration timing and brining recovery lower chemical regenerant consumption and extend service life across industrial resin columns.
What are the drivers, restraints, and opportunities in the Ion Exchange Resins Market?
In the ion exchange resins market, enforceable municipal PFAS drinking water limits and semiconductor ultrapure water expansion are projected to drive adoption whereas styrene monomer volatility and brine disposal rules restrain commodity margins and direct lithium and rare-earth extraction unlock specialty chelating growth.
- Driver: Enforceable municipal PFAS drinking water limits and semiconductor fab ultrapure water buildouts require high-selectivity anion and mixed-bed polishing resins.
- Restraint: Petrochemical styrene and divinylbenzene feedstock price swings combine with spent regeneration brine disposal regulations to raise total lifecycle treatment costs.
- Opportunity: Direct lithium extraction from continental brines and hydrometallurgical rare-earth and uranium recovery create high-margin demand for chelating resins.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Stringent drinking water regulations targeting trace fluorinated organics, nitrates, and heavy metals are compelling municipal water authorities and industrial dischargers to install dedicated ion exchange polishing trains. When public utilities confront part-per-trillion limits on perfluoroalkyl carboxylic and sulfonic acids, selective potable-water anion exchange resins provide 4 to 6 times the bed-volume capacity of conventional carbonaceous media while operating in compact pressure vessels paired with heavy metal chelation chemicals. Empirical findings published in MDPI Water in September 2025 substantiate this operational shift, demonstrating that regenerable anion exchange resins treat PFAS-contaminated groundwater at EUR 0.20 to 0.35 per cubic meter while single-use resins cost nearly double. Consequently, municipal capex allocations across North America and Europe are driving sustained multi-ton resin procurement.
Risk Assessment of the Ion Exchange Resins Market: Operational and Formulation Friction
Volatile petrochemical monomer costs for styrene, divinylbenzene, and acrylonitrile combined with strict environmental restrictions on chemical manufacturing effluents and spent regenerant brine disposal restrain margin expansion across commodity resin grades. Manufacture of aminated anion exchange resins traditionally requires chloromethylation intermediates that demand costly closed-loop scrubbing and hazardous-emission controls, while industrial end users face rising sewer surcharges on high-chloride regeneration wastewater compared with chemical-free activated carbon filters. Corporate pricing disclosures confirm this cost pressure, as LANXESS announced a global surcharge across its entire Lewatit ion exchange resin portfolio on April 7, 2026 in response to escalated raw material, energy, and logistics expenses. Price-sensitive municipal softening buyers frequently extend resin replacement intervals by six to twelve months when chemical surcharges spike.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Specialty chemical manufacturers are unlocking high-margin revenue streams by engineering macroporous chelating resins functionalized with iminodiacetic, aminophosphonic, and amidoxime groups for direct lithium extraction, uranium recovery, and precious-metal reaction recycling. Hydrometallurgical mining operators processing low-grade leach liquors and continental salar brines specify selective chelating beads that isolate target metal ions in a single column step while rejecting abundant sodium, calcium, and magnesium impurities paired with wastewater heavy metal treatment agents. Laboratory validation reported in MDPI Minerals in August 2025 confirms this commercial potential, verifying that two-column Lewatit MDS 200 H ion exchange fractionation recovers heavy rare earth elements at 98.4% purity while retaining 100% of calcium. Suppliers qualifying durable chelating beads for battery-metal and nuclear fuel cycles secure multi-year project supply contracts.
Ion Exchange Resins Market by Country (2026 to 2036)
FMI country modeling indicates that India leads ion exchange resins expansion at a 6.8% CAGR through 2036, while China advances at 6.4%, Mexico at 6.0%, Canada at 5.9%, Australia at 5.8%, the USA at 5.6%, the UK at 5.3%, and Italy at 4.9%. Commercial demand across Asian electronics and chemical hubs, North American PFAS remediation utilities, and Commonwealth hydrometallurgical mining corridors depends on local water reuse mandates and domestic bead synthesis capacity.
Table 7: Country CAGR and Primary Growth Levers for the Ion Exchange Resins Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 6.8% | Semicon 2.0 semiconductor fab UPW buildouts and zero-liquid-discharge industrial mandates |
| China | 6.4% | Electroplating PFAS wastewater compliance, coal-chemical demineralization, and salt-lake lithium extraction |
| Mexico | 6.0% | Nearshored electronics and automotive closed-loop water recycling and cane-sugar decolorization |
| Canada | 5.9% | Saskatchewan uranium ion exchange recovery and Alberta oil-sands produced-water softening |
| Australia | 5.8% | Resin-in-pulp gold and uranium hydrometallurgy and municipal bore-water PFAS and nitrate treatment |
| USA | 5.6% | EPA 4 ppt PFAS drinking water compliance, domestic chip fabs, and corn wet-milling purification |
| UK | 5.3% | AMP8 utility borehole nitrate and PFAS removal skids and domestic bioprocessing chromatography |
| Italy | 4.9% | Northern municipal PFAS groundwater treatment, API pharmaceutical fermentation, and food refining |
Source: Future Market Insights analysis
India Ion Exchange Resins Market Outlook (2026 to 2036)
Demand for ion exchange resins in India is forecast to climb at a leading 6.8% CAGR between 2026 and 2036 as domestic semiconductor fabrication plants, supercritical thermal power stations, and zero-liquid-discharge textile and chemical complexes scale water treatment capacity. What distinguishes India from mature Western markets is the simultaneous buildout of domestic export-oriented resin polymerization plants in Gujarat and Maharashtra and federally funded electronics and chemical manufacturing clusters. Official figures from the Press Information Bureau of the Government of India in September 2026 confirm this industrial momentum, reporting that 12 commercial semiconductor manufacturing and packaging units stand approved with 5 facilities in active production under the Semicon 2.0 program. Domestic water treatment integrators including Ion Exchange (India) Limited and Thermax Limited are capturing both local mixed-bed ultrapure water orders and export container shipments.
Key takeaway: In India, semiconductor fab ultrapure water installations and zero-liquid-discharge industrial mandates are projected to drive a leading 6.8% CAGR through 2036.
China Ion Exchange Resins Market Outlook (2026 to 2036)
China's industrial water purification and hydrometallurgical extraction sectors are undergoing rapid conversion toward high-purity nuclear, semiconductor, and electroplating effluent recovery resins. Consequently, national ion exchange resins adoption in China is anticipated to advance at a 6.4% CAGR through 2036, outpacing the global average on the strength of domestic wafer fab construction and lithium salt-lake extraction in Qinghai and Tibet. Field monitoring published in MDPI Toxics in July 2026 across 15 Chinese electroplating industrial parks and 97 enterprises documented that strong base anion exchange resins achieved over 98% removal of perfluorooctane sulfonic acid and 85% removal of 6:2 fluorotelomer sulfonate. Chinese producers such as Sunresin New Materials are expanding automated continuous moving-bed chromatographic columns across domestic chemical, pharmaceutical, and metal-refining complexes.
Key takeaway: In China, electroplating wastewater remediation mandates and domestic semiconductor and lithium extraction projects are anticipated to sustain a 6.4% CAGR.
Mexico Ion Exchange Resins Market Outlook (2026 to 2036)
In Mexico, market growth is forecast to reach a 6.0% CAGR through 2036, anchored by nearshored automotive, electronics, and food-processing factories across Nuevo Leon, Jalisco, and Queretaro that require closed-loop process water demineralization. Compared with water-abundant regions, northern and central Mexican industrial corridors confront severe aquifer depletion that forces plant managers to recycle treated municipal wastewater using softening and deionization skids. Sectoral assessments published by the US International Trade Administration in August 2026 confirm that Mexico's Plan Mexico industrial strategy prioritizes advanced manufacturing, electronics, and pharmaceutical production hubs requiring high-purity water infrastructure. Local cane-sugar refineries and beverage bottlers also generate steady replacement orders for acrylic and styrenic decolorization and dealkalization resins.
Key takeaway: In Mexico, industrial nearshoring across water-stressed manufacturing corridors and cane-sugar refining are forecast to propel demand at a 6.0% CAGR.
Canada Ion Exchange Resins Market Outlook (2026 to 2036)
Canadian ion exchange resins demand is estimated to progress at a 5.9% CAGR from 2026 to 2036, supported by uranium and base-metal hydrometallurgy in Saskatchewan and Ontario and oil-sands produced-water softening in Alberta. Rather than relying solely on municipal water softening, Canadian industrial procurement centers on weak acid cation resins that strip hardness from warm lime-softened steam-assisted gravity drainage boiler feedwater and strong base resins that recover uranium complexes from acid leach circuits. Official natural resource indicators released by Statistics Canada in April 2026 confirmed that Canadian minerals and mining export volumes increased 3.2% while energy export volumes rose 4.6% in the fourth quarter of 2025, sustaining high utilization of mine-water and steam-generation resin beds. Cold winter raw-water temperatures across Canadian municipalities also require high-kinetics uniform-particle resins to prevent silica leakage.
Key takeaway: In Canada, uranium hydrometallurgy and oil-sands steam-generation water softening are estimated to support a 5.9% CAGR through 2036.
Australia Ion Exchange Resins Market Outlook (2026 to 2036)
Procurement of ion exchange resins in Australia is projected to grow at a 5.8% CAGR from 2026 to 2036 across gold, uranium, lithium, and copper resin-in-pulp (RIP) and resin-in-leach (RIL) circuits and municipal groundwater treatment plants. What sets Australia apart from global baseline demand is the widespread deployment of coarse-mesh macroporous and chelating beads that extract dissolved metal cyanides and uranyl sulfate directly from unclarified mineral slurries in Western Australia and South Australia. Commodity production data released by the Australian Department of Industry, Science and Resources in October 2026 reported that Australian gold export earnings are forecast at AUD 68 billion in 2026-27 while lithium export earnings rise from AUD 10.2 billion in 2025-26 to AUD 16.6 billion in 2026-27. Municipal water corporations across Victoria, New South Wales, and Queensland also specify selective anion resins for bore-water nitrate and PFAS removal.
Key takeaway: In Australia, resin-in-pulp mineral extraction circuits and municipal groundwater remediation are projected to drive a 5.8% CAGR.
USA Ion Exchange Resins Market Outlook (2026 to 2036)
Commercial ion exchange resins valuation in the USA is anticipated to progress at a 5.6% CAGR during the 2026 to 2036 assessment window, driven by federally mandated municipal PFAS drinking water remediation and domestic semiconductor and green-hydrogen plant construction. Compared with export-dependent resin markets, American utilities and defense groundwater sites steadily specify domestically manufactured, NSF/ANSI 61-certified single-use and regenerable hybrid resins to meet Buy America infrastructure rules. To demonstrate domestic supplier innovation, New Jersey-based ResinTech announced the development of advanced hybrid ion exchange resins in May 2025 that achieve greater than 99% PFAS removal and heavy-metal, nitrate, and perchlorate reduction in contaminated groundwater. Corn wet-milling high-fructose corn syrup refiners across the Midwest and nuclear power stations further anchor recurring American replacement bed volumes.
Key takeaway: In the USA, municipal PFAS drinking water compliance and domestic semiconductor and sweetener refining are anticipated to sustain a 5.6% CAGR.
UK Ion Exchange Resins Market Outlook (2026 to 2036)
Sales of ion exchange resins in the UK are slated to advance at a 5.3% CAGR from 2026 to 2036, driven by water utility Asset Management Plan 8 (AMP8) nitrate and micropollutant removal upgrades and biopharmaceutical chromatography manufacturing. In contrast to heavy mining economies, British resin consumption is concentrated in municipal borehole nitrate stripping across East Anglia and the Midlands, nuclear power station condensate polishing, and high-value life-science purification. Official performance data published by the UK Environment Agency and DEFRA in October 2026 showed that national public water distribution input rose from 13,946 million liters per day in 2024-25 to 14,110 million liters per day in 2025-26, intensifying treatment capacity investments across English water companies. Ecolab's Purolite agarose and synthetic resin manufacturing center in Llantrisant, Wales supplies pharmaceutical purification resins across European bioprocessing plants.
Key takeaway: In the UK, utility groundwater nitrate and PFAS treatment investments along with domestic bioprocessing resin production are slated to support a 5.3% CAGR.
Italy Ion Exchange Resins Market Outlook (2026 to 2036)
In Italy, demand for ion exchange resins is predicted to rise at a 4.9% CAGR during the decade through 2036 in active pharmaceutical ingredient (API) fermentation plants, food and sugar processing facilities, and municipal drinking water networks in the Po Valley and Veneto regions. Italian industrial buyers prioritize food-contact-compliant polyacrylic and styrenic resins for fruit-juice deacidification, whey demineralization, and antibiotic extraction plus selective anion resins addressing industrial fluoroalkyl groundwater plumes in northern Italy. Official figures from the 2026 Sustainable Development Goals Report published by the Italian National Institute of Statistics (Istat) in July 2026 show that national drinking water abstraction reached 8,863.4 million cubic meters while 29.9% of Italian households reported tap-water quality concerns in 2025, reinforcing municipal filtration and softening demand. Cogeneration steam plants serving Lombardy and Emilia-Romagna manufacturing districts provide steady baseline cation and anion refill orders.
Key takeaway: In Italy, northern municipal groundwater remediation and pharmaceutical and food-ingredient purification are predicted to maintain a 4.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Ion Exchange Resins Market?
DuPont de Nemours, Inc., LANXESS AG, Ecolab Inc. (Purolite), Mitsubishi Chemical Group Corporation, Thermax Limited, Ion Exchange (India) Limited, ResinTech, Inc., Samyang Corporation, Sunresin New Materials Co., Ltd., and Jacobi Carbons AB are the notable companies in the ion exchange resins market.
Competitive positioning in the ion exchange resins industry spans global integrated copolymer and specialty resin multinationals, regional industrial and municipal water treatment resin manufacturers, and specialized adsorbent, chelating, and bioprocessing resin producers. DuPont de Nemours, LANXESS AG, Purolite (Ecolab Inc.), and Mitsubishi Chemical Group Corporation lead global high-purity and industrial resin synthesis. Thermax Limited, Ion Exchange (India) Limited, ResinTech, and Samyang Corporation supply broad utility, softening, and electronics grades, whereas Sunresin New Materials Group and Jacobi Carbons AB (Jacobi Group) focus on selective lithium, PFAS, and mixed-bed applications.
- Global Integrated Copolymer and Specialty Resin Leaders: DuPont de Nemours, LANXESS AG, Purolite (Ecolab Inc.), and Mitsubishi Chemical Group Corporation manufacture full-spectrum styrenic, acrylic, and bioprocessing resins across multi-continent plants.
- Regional Industrial and Municipal Water Resin Producers: Thermax Limited, Ion Exchange (India) Limited, ResinTech, and Samyang Corporation produce high-capacity softening, demineralization, and uniform-particle industrial resins.
- Specialty Chelating, Adsorbent, and Extraction Resin Specialists: Sunresin New Materials Group and Jacobi Carbons AB (Jacobi Group) engineer direct lithium extraction, PFAS-selective anion, and custom chromatographic resin systems.
Competitive Benchmarking: Ion Exchange Resins Market
Table 8: Competitive Benchmarking for the Ion Exchange Resins Market (qualitative capability ratings), 2026
| Company | Monodisperse & UPW Capability | PFAS & Selective Chelating Portfolio | Global Regeneration & Application Support | Geographic Reach |
|---|---|---|---|---|
| DuPont de Nemours, Inc. | High | High | High | Global synthesis network for AmberLite, AmberTec, and AmberSep lines across Americas, Europe, and Asia |
| LANXESS AG | High | High | High | Global Lewatit production in Bitterfeld and Leverkusen, Germany, serving Europe, Americas, and Asia |
| Ecolab Inc. (Purolite) | High | High | High | Global Purolite and Praesto plants in USA, UK (Wales), Romania, and China |
| Mitsubishi Chemical Group Corporation | High | Medium | High | Global DIAION semiconductor UPW and industrial resins anchored in Fukuoka, Japan |
| Thermax Limited | Medium | High | High | Dahej and Jhagadia chemical plants in India exporting Tulsion resins to North America, Europe, and Asia |
| Ion Exchange (India) Limited | Medium | Medium | High | Ankleshwar and Roha plants in India supplying INDION resins and turnkey water systems across Asia and MEA |
| ResinTech, Inc. | Medium | High | High | Camden, New Jersey headquarters and US cation/anion plants with regeneration hubs across North America |
| Samyang Corporation | High | Medium | Medium | Ulsan and Gunsan plants in South Korea supplying TRILITE uniform-particle and chromatography resins |
| Sunresin New Materials Co., Ltd. | Medium | High | Medium | Xi'an and Gaoling synthesis bases in China supplying Seplite DLE lithium and life-science resins globally |
| Jacobi Carbons AB (Jacobi Group) | Medium | High | Medium | European and Asian distribution hubs supplying Resinex PFAS-selective and mixed-bed water resins |
Key Developments in the Ion Exchange Resins Market
- In March 2025, Jacobi Carbons AB announced expanded ion exchange resin production capabilities at its Finex facility in Finland, following a multi-year integration of the plant acquired in 2020. The expansion increased output capacity for specialty resins used in chromatographic separation and water treatment applications [25].
- In November 2024, Samyang Corporation unveiled its AI-powered water treatment platform “TRIGENT” alongside an updated version of its ion exchange resin and RO membrane system design software “TriAngle,” extending digital support for TRILITE-brand resin specification across more than 100 languages for global industrial customers [26].
- In March 2026, Samyang Corporation presented its TRILITE MCK Series monodisperse ion exchange resin for chromatography separation at the BIO CHINA exhibition in China, targeting amino acid and organic acid refinement applications. The product features a uniformity coefficient of 1.05 or below, enabling high separation efficiency for bio-fermentation process customers [27].
Key Players in the Ion Exchange Resins Market
Global Integrated Copolymer and Specialty Resin Leaders
- DuPont de Nemours
- LANXESS AG
- Purolite (Ecolab Inc.)
- Mitsubishi Chemical Group Corporation
Regional Industrial and Municipal Water Resin Producers
- Thermax Limited
- Ion Exchange (India) Limited
- ResinTech
- Samyang Corporation
Specialty Chelating, Adsorbent, and Extraction Resin Specialists
- Sunresin New Materials Group
- Jacobi Carbons AB (Jacobi Group)
Ion Exchange Resins Market - Report Scope
Table 9: Report Scope for the Ion Exchange Resins Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Resin Chemistry; Polymer Matrix; End-Use Industry; Bead Structure; Operating Mode |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from synthetic polymeric and agarose ion exchange resin beads, granules, and powdered precoats (Strong Acid Cation, Weak Acid Cation, Strong Base Anion, Weak Base Anion, Chelating, and Mixed-Bed grades) used for water softening, demineralization, trace contaminant polishing, food/pharmaceutical purification, chemical catalysis, and hydrometallurgy. Category Scope Note: Excludes polymeric reverse-osmosis membranes, granular activated carbon media, inorganic zeolite molecular sieves, and standalone steel pressure vessels. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, China, Mexico, Canada, Australia, USA, UK, Italy, and additional countries in the full report |
| Key Companies Covered | DuPont de Nemours, Inc., LANXESS AG, Ecolab Inc. (Purolite), Mitsubishi Chemical Group Corporation, Thermax Limited, Ion Exchange (India) Limited, ResinTech, Inc., Samyang Corporation, Sunresin New Materials Co., Ltd., Jacobi Carbons AB |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up volumetric bed-capacity triangulation. |
Ion Exchange Resins Market - Research Methodology
Table 10: Research Methodology for the Ion Exchange Resins Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with industrial boiler and semiconductor UPW treatment engineers, municipal PFAS remediation directors, resin synthesis R&D managers, and hydrometallurgical process metallurgists to validate eq/L capacities and bed replacement intervals. |
| Secondary Research | Analysis of U.S. EPA National Primary Drinking Water Regulation technical dockets, Eurostat environmental protection investment releases, USGS Mineral Commodity Summaries, peer-reviewed membrane and adsorption journals, and corporate annual filings. |
| Market Sizing and Forecasting | Top-down industrial and municipal water treatment material baselines reconciled against bottom-up installed resin bed volumes (745,000 to 795,000 cubic meters in 2026) and grade-specific per-liter pricing from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight semiconductor fab capex, municipal PFAS and nitrate compliance deadlines, industrial zero-liquid-discharge mandates, and hydrometallurgical lithium/uranium project pipelines across eight key countries. |
| Operational Benchmark Traceability | Resin bed volume, empty-bed contact time, and sectoral allocation indicators in Tables 2, 3, and 4 trace to U.S. EPA PFAS treatment fact sheets, Eurostat wastewater investment records, and USGS lithium production statistics. |
| Data Triangulation and Validation | Revenue estimates isolate synthetic polymeric and bioprocessing ion exchange resins while strictly excluding reverse-osmosis membranes, activated carbon adsorbents, bulk coagulants, and mechanical filtration hardware. |
Ion Exchange Resins Market by Segments
Ion Exchange Resins Market segmented by Resin Chemistry:
- Strong Acid Cation (SAC) Resins
- Weak Acid Cation (WAC) Resins
- Strong Base Anion (SBA) Resins
- Weak Base Anion (WBA) & Chelating Selective Ion Resins
Ion Exchange Resins Market segmented by Polymer Matrix:
- Styrene-Divinylbenzene Crosslinked Matrix
- Polyacrylic Ester Crosslinked Matrix
- Phenol-Formaldehyde Condensate Matrix
- Epichlorohydrin-Amine & Magnetic Hybrid Matrix
Ion Exchange Resins Market segmented by End-Use Industry:
- Water Softening and Deionization Demineralization
- Pharmaceutical Drug Formulation and Taste-Masking
- Food and Beverage Sugar Decolorization and Dairy Whey Demineralization
- Chemical Processing reaction Recovery and Hydrometallurgy Mining
- Semiconductor Ultrapure Water & Nuclear Condensate Polishing
Ion Exchange Resins Market segmented by Bead Structure:
- Gel-Type Microporous Beads
- Macroporous Macroreticular Beads
- Uniform Particle Size (UPS) Monodisperse Beads
- Powdered Precoat & Fine-Mesh Resins
Ion Exchange Resins Market segmented by Operating Mode:
- Regenerable Service-Cycle Systems
- Single-Use Non-Regenerable Cartridges
- Mixed-Bed Polishing Units
- Continuous Counter-Current Moving-Bed Systems
Ion Exchange Resins Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Environmental Protection Agency. (2026, May 18). Per- and Polyfluoroalkyl Substances (PFAS). U.S. EPA Safe Drinking Water Act Docket.
- [2] DuPont de Nemours, Inc. (2026, January 28). DuPont Introduces DuPont™ AmberLite™ FPA57 Resin to Boost Efficiency in Organic Acid Purification. DuPont Water Solutions Press Releases.
- [3] Eurostat. (2026, June 24). Wastewater drives investments in environmental protection. European Commission Eurostat News Articles.
- [4] U.S. Environmental Protection Agency. (2024, April 8). Treatment Options for Removing PFAS from Drinking Water. U.S. EPA Office of Water Fact Sheet.
- [5] U.S. Geological Survey. (2026, February 15). Mineral Commodity Summaries 2026: Lithium. U.S. Department of the Interior USGS Publications.
- [6] DuPont de Nemours, Inc. (2025, September 2). DuPont™ AmberLite™ Ion Exchange Resins Water Conditioning Manual. DuPont Water Solutions Technical Literature (Form No. 45-D01951-en Rev. 2).
- [7] Ecolab Inc. (2025, June 16). Ecolab Life Sciences Launches New Bioprocessing Resin to Drive Manufacturing Efficiencies. Purolite An Ecolab Company Newsroom.
- [8] Mitsubishi Chemical Group Corporation. (2024, October 10). Mitsubishi Chemical Group Expands Production Capacity for Ion Exchange Resins Used in the Production of Ultrapure Water for Semiconductors. Mitsubishi Chemical Group News Releases.
- [9] DuPont de Nemours, Inc. (2025, August 14). DuPont™ AmberLite™ HPR1600 H Ion Exchange Resin Product Data Sheet. DuPont Water Solutions Technical Data Sheet (Form No. 45-D01195-en).
- [10] Ion Exchange (India) Limited. (2026, September 22). How to Improve Ion Exchange Resin Regeneration & Reduce Costs. Ion Exchange Global Technical Insights.
- [11] Water (MDPI). (2025, September 25). Life After Adsorption: Regeneration, Management, and Sustainability of PFAS Adsorbents in Water Treatment. MDPI Water Open-Access Journal, 17(19), 2813.
- [12] LANXESS AG. (2026, April 7). LANXESS introduces surcharge for Lewatit ion exchange resins. LANXESS Corporate Media Releases.
- [13] Minerals (MDPI). (2025, August 1). Separation of Rare Earth Elements by Ion Exchange Resin: pH Effect and the Use of Fractionation Column. MDPI Minerals Open-Access Journal, 15(8), 821.
- [14] Press Information Bureau, Government of India. (2026, September 17). India Building Semiconductor Future: Emerging Capabilities Across Design, Manufacturing, Packaging, Materials and Talent. Ministry of Electronics and Information Technology PIB.
- [15] Toxics (MDPI). (2026, July 27). Occurrence and Treatment Technologies of Per- and Polyfluoroalkyl Substances in Electroplating Wastewater: A Review. MDPI Toxics Open-Access Journal, 14(8), 661.
- [16] International Trade Administration. (2026, August 24). Mexico Advanced Manufacturing. U.S. Department of Commerce Trade.gov Market Intelligence.
- [17] Statistics Canada. (2026, April 2). The Daily - Natural resource indicators, fourth quarter 2025. Government of Canada Official Statistical Release.
- [18] Department of Industry, Science and Resources. (2026, October 2). Resources and energy quarterly: September 2026. Australian Government Office of the Chief Economist.
- [19] ResinTech, Inc. (2025, May 28). ResinTech Develops Advanced Hybrid Resins for Comprehensive Groundwater Remediation. ResinTech Corporate Newsroom.
- [20] UK Environment Agency & DEFRA. (2026, October 29). Water resources 2025 to 2026: analysis of the water industry's annual water resources performance. GOV.UK Official Publications.
- [21] Italian National Institute of Statistics (Istat). (2026, July 8). Infographics 2026 SDGs Report. Istat Official Statistical Releases.
- [22] Thermax Limited. (2026, June 15). Message from the MD & CEO - Thermax Annual Report 2025-26. Thermax Global Investor Disclosures.
- [23] ResinTech, Inc. (2026, September 29). ResinTech and FilterWorks Successfully Complete ISO 9001 Recertification. ResinTech Company News & Media Update.
- [24] LANXESS AG. (2025, March 13). LANXESS: innovative solutions for water treatment at Aquatech 2025. LANXESS Specialty Chemicals Newsroom.
- [25] Jacobi Carbons AB. (2025). Jacobi Resins, Forging Ahead with Increased Ion Exchange Resins Capabilities. https://www.jacobi.net/2025/03/25/
- [26] Samyang Corporation. (2024). Samyang ‘TRILITE’ Unveils New AI Water Treatment Solutions. https://kyodonewsprwire.jp/release/202411260570
- [27] Samyang Corporation. (2026). Samyang Corporation Showcases Ion Exchange Resin Technology at China Bio-Fermentation Expo. https://www.asiae.co.kr/en/article/2026030910410650403
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ion exchange resins market in 2026 and what is forecast for 2036?
- Which municipal PFAS regulations and ultrapure water standards drive demand for ion exchange resins?
- Why do Strong Acid Cation (SAC) Resins lead the resin chemistry category?
- Why does Styrene-Divinylbenzene Crosslinked Matrix lead the polymer matrix category globally?
- How do national growth rates differ across India, China, Mexico, Canada, Australia, and the USA?
- Which notable companies supply integrated styrenic and acrylic beads versus specialty bioprocessing and chelating grades?
- What raw material price swings and spent regeneration brine rules restrain adoption in the ion exchange resins market?
- What performance criteria should industrial water engineers evaluate when transitioning to monodisperse packed-bed resins?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Resin Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Resin Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Resin Chemistry, 2026 to 2036
- Strong Acid Cation (SAC) Resins
- Weak Acid Cation (WAC) Resins
- Strong Base Anion (SBA) Resins
- Weak Base Anion (WBA) & Chelating Selective Ion Resins
- Y-o-Y Growth Trend Analysis By Resin Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Resin Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Polymer Matrix, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Polymer Matrix, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Polymer Matrix, 2026 to 2036
- Styrene-Divinylbenzene Crosslinked Matrix
- Polyacrylic Ester Crosslinked Matrix
- Phenol-Formaldehyde Condensate Matrix
- Epichlorohydrin-Amine & Magnetic Hybrid Matrix
- Y-o-Y Growth Trend Analysis By Polymer Matrix, 2021 to 2025
- Absolute $ Opportunity Analysis By Polymer Matrix, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Water Softening and Deionization Demineralization
- Pharmaceutical Drug Formulation and Taste-Masking
- Food and Beverage Sugar Decolorization and Dairy Whey Demineralization
- Chemical Processing reaction Recovery and Hydrometallurgy Mining
- Semiconductor Ultrapure Water & Nuclear Condensate Polishing
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Bead Structure, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Bead Structure, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Bead Structure, 2026 to 2036
- Gel-Type Microporous Beads
- Macroporous Macroreticular Beads
- Uniform Particle Size (UPS) Monodisperse Beads
- Powdered Precoat & Fine-Mesh Resins
- Y-o-Y Growth Trend Analysis By Bead Structure, 2021 to 2025
- Absolute $ Opportunity Analysis By Bead Structure, 2026 to 2036
- Global Market Analysis and Forecast, By Operating Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Operating Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Operating Mode, 2026 to 2036
- Regenerable Service-Cycle Systems
- Single-Use Non-Regenerable Cartridges
- Mixed-Bed Polishing Units
- Continuous Counter-Current Moving-Bed Systems
- Y-o-Y Growth Trend Analysis By Operating Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Operating Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- By Country
- Market Attractiveness Analysis
- By Country
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Resin Chemistry
- By Polymer Matrix
- By End-Use Industry
- By Bead Structure
- By Operating Mode
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- DuPont de Nemours, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- LANXESS AG
- Ecolab Inc. (Purolite)
- Mitsubishi Chemical Group Corporation
- Thermax Limited
- Ion Exchange (India) Limited
- ResinTech, Inc.
- Samyang Corporation
- Sunresin New Materials Co., Ltd.
- Jacobi Carbons AB (Jacobi Group)
- Purolite (Ecolab Inc.)
- Sunresin New Materials Group
- DuPont de Nemours, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Resin Chemistry, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Polymer Matrix, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Bead Structure, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Operating Mode, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Resin Chemistry
- Figure 6: Global Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Polymer Matrix
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Industry
- Figure 12: Global Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Bead Structure
- Figure 15: Global Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Operating Mode
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Resin Chemistry
- Figure 32: North America Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Polymer Matrix
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: North America Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Bead Structure
- Figure 41: North America Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Operating Mode
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Resin Chemistry
- Figure 48: Latin America Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Polymer Matrix
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 54: Latin America Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Bead Structure
- Figure 57: Latin America Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Operating Mode
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Resin Chemistry
- Figure 64: Western Europe Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Polymer Matrix
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 70: Western Europe Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Bead Structure
- Figure 73: Western Europe Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Operating Mode
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Resin Chemistry
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Polymer Matrix
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Bead Structure
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Operating Mode
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Resin Chemistry
- Figure 96: East Asia Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Polymer Matrix
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 102: East Asia Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Bead Structure
- Figure 105: East Asia Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Operating Mode
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Resin Chemistry
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Polymer Matrix
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Bead Structure
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Operating Mode
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Resin Chemistry, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Resin Chemistry, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Resin Chemistry
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Polymer Matrix, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Polymer Matrix, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Polymer Matrix
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Bead Structure, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Bead Structure, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Bead Structure
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Operating Mode, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Operating Mode, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Operating Mode
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Ion Exchange Resins Market in 2026, and what is forecast for 2036?
FMI estimates that the global ion exchange resins market size stood at USD 2.4 billion in 2025 and reached USD 2.5 billion in 2026. Overall industry valuation is projected to hit USD 4.2 billion by 2036 as municipal utilities, semiconductor fabs, and hydrometallurgical plants expand high-purity resin bed installations.
What is the CAGR for the Ion Exchange Resins Market from 2026 to 2036?
The ion exchange resins sector is projected to expand at a 5.4% CAGR over the 2026 to 2036 forecast period, generating an incremental revenue opportunity of USD 1.7 billion across global water and process purification applications.
Which resin chemistry segment leads the Ion Exchange Resins Market?
Strong Acid Cation (SAC) Resins hold an estimated 42.0% share of resin chemistry demand in 2026 since sulfonated copolymer beds provide reliable, regenerable hardness and sodium removal across industrial steam boilers and municipal softeners.
Which polymer matrix segment leads the Ion Exchange Resins Market?
Styrene-Divinylbenzene Crosslinked Matrix resins represent 68.0% of the polymer matrix category in 2026 owing to high osmotic shock resistance and multi-year physical durability under cyclic acid and caustic regeneration.
Which country has a notable growth outlook during the assessment period?
India leads national growth projections at a 6.8% CAGR through 2036, supported by domestic semiconductor wafer fab construction, supercritical power demineralization, and zero-liquid-discharge industrial effluent regulations.
Who are the key players in the market?
DuPont de Nemours, LANXESS AG, Ecolab (Purolite), Mitsubishi Chemical Group Corporation, Thermax Limited, Ion Exchange (India) Limited, ResinTech, Samyang Corporation, Sunresin New Materials Group, and Jacobi Carbons AB lead commercial supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
