

- Market Size (2026)
- USD 74.9 Bn
- Forecast (2036)
- USD 135.4 Bn
- CAGR (2026 to 2036)
- 6.1%
How big is Iron Ore Pellet Market in 2026?
The iron ore pellet market is estimated at USD 70.6 billion in 2025 and USD 74.9 billion in 2026, and sales are predicted to grow at a 6.1% CAGR to USD 135.4 billion by 2036.
Sales of iron ore pellets are projected to rise at a 6.1% CAGR through 2036. The market is estimated at USD 70.6 billion in 2025 and is expected to reach USD 74.9 billion in 2026 and USD 135.4 billion by 2036. Looking across the decade, one trend leads the outlook, as merchant pellet producers move downstream into direct reduction grade and sponge iron. LKAB received an environmental permit on 15 June 2026 for expanded Malmberget operations, including a fossil-free sponge iron demonstration plant.[1] The shift matters because blast furnace pellets now earn a thinner margin, and the LKAB pellet premium for the June 2026 quarter was about USD 6 per tonne lower than a year earlier.[2] FMI analysts would steer merchant producers holding low-silica ore toward DR grade and sponge iron for new capacity, since integrated mills are taking control of captive pellet plants and will buy fewer merchant blast furnace pellets.
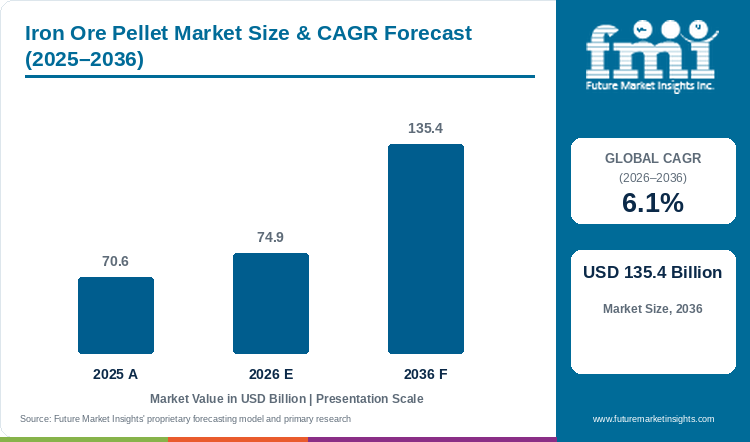
Key Market Trends & Insights
- Blast furnace pellets are projected to lead product grade sales with 61.1% share in 2026, ahead of direct reduction pellets at an estimated 38.9%. Ferrexpo produced 163 thousand tonnes of premium DR pellets within 1.4 Mt of pellet output in the first half of 2026.[3]
- Steel manufacturing is anticipated to lead application demand with 88.2% share in 2026, and foundries are likely to hold 7.4% through merchant pig iron.
Regional Highlights
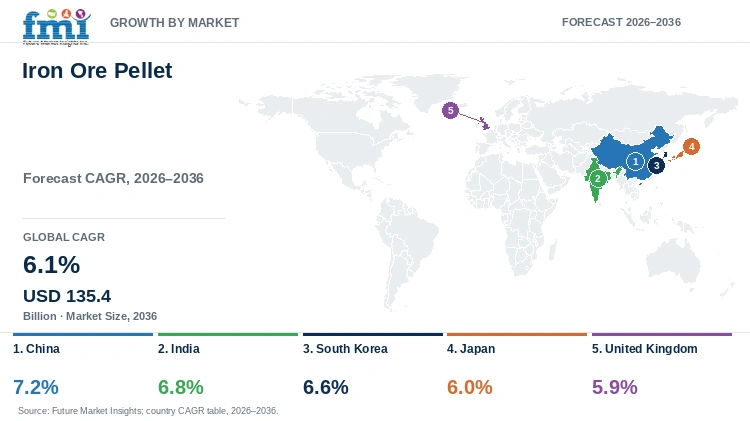
- Pellet demand in China grows fastest, at a 7.2% CAGR from 2026 to 2036.
- India follows on 6.8%, South Korea on 6.6% and Japan on 6.0%, and the United Kingdom is lowest at 5.9%, just under the 6.1% global CAGR.
- Tata Steel agreed in January 2026 to buy a 50.01% stake in Thriveni Pellets, owner of a 4 million tonne per annum pellet plant and a 212 km slurry pipeline.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Iron Ore Pellet Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 70.6 billion |
| Estimated Market Size in 2026 | USD 74.9 billion |
| Projected Market Size by 2036 | USD 135.4 billion |
| CAGR, 2026 to 2036 | 6.1% |
| Added Revenue, 2026 to 2036 | USD 60.5 billion |
| Market Expansion Multiple | 1.8x |
Pellet contracts follow the furnace calendar, and a rebuilt blast furnace runs for many years on the burden mix chosen at restart. Cleveland-Cliffs announced a USD 1 billion investment at Middletown Works on 21 August 2026, with the blast furnace rebuild due for completion in the first quarter of 2030.[5] The plant produces about 3 million tons of raw steel per year.[5] Tata Steel's Kalinganagar expansion added a 5,870 cubic metre blast furnace and a pellet plant as Phase II facilities in May 2025.[6] Analysts at FMI see USD 60.5 billion of added pellet sales between 2026 and 2036, a 1.8x expansion of the 2026 base. Pellet demand follows crude steel output, and growth of the steel market sets the base volume for both grades. Energy cost is the main risk to producer margins over 2026 to 2036, since electricity and fuel make up a large part of pelletising cost.
Delivery Shocks, Energy Costs and Downstream Moves
Pellet supply from Sweden and Ukraine was disrupted in 2026. LKAB expected a delivery shortfall of around 2 million tonnes in 2026 from changed geotechnical conditions in the Kiruna mine, and the Strait of Hormuz closure cut Middle East deliveries in the first quarter.[7] Ferrexpo suspended operations after attacks on Ukraine's electricity infrastructure and later restarted one of four pellet lines.[3] Ferrexpo's C1 cash cost rose to USD 81.3 per tonne in the first half of 2026, from USD 77.1.[3] Steel mills that relied on Swedish or Ukrainian pellets will add a second supplier, and Brazilian and Indian producers will pick up the spot tonnes.
LKAB secured an environmental permit on 15 June 2026 for continued and expanded operations in Malmberget, including a fossil-free sponge iron demonstration plant.[1] In India, Tata Steel is taking control of Brahmani River Pellet's 4 million tonne per annum plant through the Thriveni deal, priced at up to Rs 6.36 billion.[4] Integrated steelmakers that own pellet plants will cut exposure to merchant pellet premiums, and merchant producers will sell more DR grade and sponge iron to mills without captive supply.
Table 2: Supply, Cost and Capacity Indicators for the Iron Ore Pellet Market (tonnes, prices and dates), 2025 to 2030
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| LKAB pellet premium, Q2 2026 | About USD 6 per tonne lower than a year earlier | Merchant pellet margins are thinner. | [2] |
| LKAB delivery shortfall, 2026 | Around 2 million tonnes expected | Swedish supply gap for European mills. | [7] |
| Ferrexpo pellet output, H1 2026 | 1.4 Mt, including 163 kt DR pellets | Ukrainian supply cut by power outages. | [3] |
| Ferrexpo C1 cash cost, H1 2026 | USD 81.3 per tonne | Energy and fuel costs at pellet plants. | [3] |
| Middletown Works blast furnace rebuild | Completion due in Q1 2030 | Demand for blast furnace grade in the United States. | [5] |
| Tata Steel Kalinganagar Phase II | Crude steel capacity raised to 8 mtpa | New Indian blast furnace burden. | [6] |
| Thriveni Pellets stake | 50.01% for up to Rs 6.36 billion | Captive pellet supply for Tata Steel. | [4] |
| LKAB Malmberget permit | Sponge iron demonstration plant covered | Producer move downstream from pellets. | [1] |
Analyst Perspective
“Direct reduction pellets are the grade I would hold for the next decade, because every new gas-based or hydrogen-ready iron plant needs them and only a few mines can deliver the low-silica feed. Blast furnace pellets will keep the larger share through the 2030 rebuild cycle in the USA and India, but DR grade will earn the higher premium.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the iron ore pellet market segmented?
Two axes plus region divide iron ore pellet sales. Blast furnace grade is expected to lead product grade with 61.1% share in 2026, and steel manufacturing will lead application with 88.2%.
By product grade: blast furnace (BF) grade, and direct reduction iron (DRI) grade.
By application: steel manufacturing, foundries, and other applications.
By region: pellet coverage covers South Asia and Pacific, Western Europe, East Asia, North America, Latin America, Eastern Europe, and Middle East and Africa.
Why does blast furnace grade lead sales of iron ore pellets?
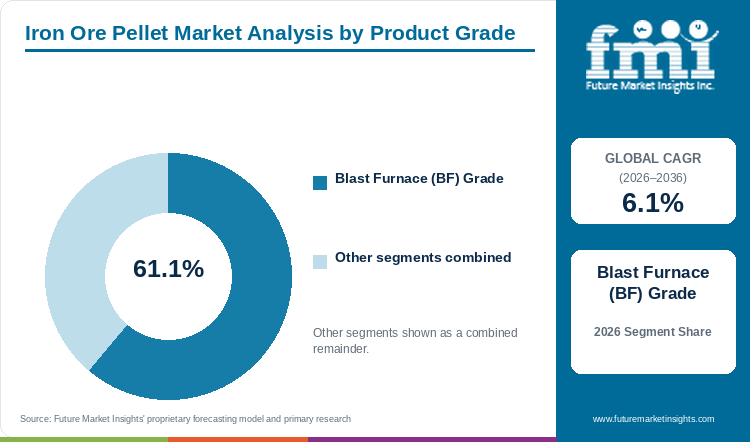
Blast furnace grade pellets are expected to lead with 61.1% share in 2026, and direct reduction grade is likely to hold 38.9%.
Table 3: Product Grade Share for the Iron Ore Pellet Market (percentage share), 2026
| Product Grade | Estimated Share (2026) |
|---|---|
| Blast Furnace (BF) Grade | 61.1% |
| Direct Reduction Iron (DRI) Grade | 38.9% |
| Total | 100.0% |
Table 4: Product Grade Leadership and Market Growth for the Iron Ore Pellet Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.1% |
| Leading Segment | Blast Furnace (BF) Grade |
Blast furnace grade pellets are expected to lead with 61.1% share in 2026, as integrated mills still make the bulk of world iron in blast furnaces. Blast furnace pellets tolerate more silica and alumina, so many mines in Brazil, India and North America can produce them. Integrated mills roll much of the blast furnace iron into car and appliance sheet, and growth of the galvanized and coated iron and steel sheets market keeps those mills on blast furnace grade. Direct reduction grade, at an estimated 38.9%, needs a high iron content and low gangue, and only a few mines can supply that feed. Ferrexpo, for example, made 163 thousand tonnes of DR pellets out of 1.4 Mt of premium pellets in the first half of 2026.[3] Gas-based reduction plants in the Middle East and India buy DR grade, and the iron from those reduction plants goes into electric furnaces. Rebuilds such as Middletown Works will keep BF grade ahead until new direct reduction capacity arrives in the 2030s.
- Blast furnace grade buyers include integrated mills in China, India, Japan, South Korea and the United States.
- Tata Steel's Kalinganagar Phase II, inaugurated in May 2025, added a 5,870 cubic metre blast furnace and a pellet plant.[6]
What keeps steel manufacturing ahead of foundries and other uses?
Steel manufacturing is projected to lead with 88.2% share in 2026, with foundries at an estimated 7.4%.
Table 5: Application Share for the Iron Ore Pellet Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Steel Manufacturing | 88.2% |
| Foundries | 7.4% |
| Other Applications | 4.4% |
| Total | 100.0% |
Steel manufacturing is projected to lead with 88.2% share in 2026, because steelmakers charge pellets straight into blast furnaces and reduction shafts. Foundries are estimated at 7.4%, as foundries buy merchant pig iron made from pellets and seldom buy pellets direct. Growth of the iron and steel casting market adds foundry volume for pipes, engine blocks and machine parts. Other applications, near 4.4% by estimate, cover heavy media and ballast uses. Large new furnaces such as the 5,870 cubic metre unit at Kalinganagar add steelmaking demand in single steps.[6] Stainless steel is made mostly from scrap and alloys in electric furnaces, so the stainless steel market, projected at a 5.4% CAGR from 2026 to 2036, adds little pellet demand as stainless output grows.
- Steelmakers charge pellets into blast furnaces at integrated mills and into reduction shafts at DRI plants.
- On 21 August 2026, Cleveland-Cliffs announced a USD 1 billion investment at Middletown Works.[5]
What are the drivers, restraints, and opportunities in the iron ore pellet market?
Long-life blast furnace rebuilds and new furnace capacity in growing steel economies anchor demand for iron ore pellets. Energy costs and supply shocks squeeze producer margins, and the move to direct reduction opens higher-value sales for DR grade and sponge iron.
- Driver: Steelmakers that rebuild or add blast furnaces commit to pellet feed for the full campaign life of each furnace, giving pellet producers long and predictable offtake.
- Restraint: Pelletising is an energy-intensive step, so higher power and fuel prices raise plant cash costs and leave producers exposed to swings in pellet premiums.
- Opportunity: Steelmakers cutting carbon through direct reduction need low-silica DR-grade pellets, opening premium contracts for producers with suitable ore and a route into sponge iron sales.
Rebuilt Blast Furnaces Lock In Pellet Tonnage
Demand for blast furnace grade pellets is set for years once a mill rebuilds a furnace. Cleveland-Cliffs will keep Middletown Works on the blast furnace route, preserving about 3 million tons of raw steel capacity and 2,300 jobs.[5] Cleveland-Cliffs also expects full-year 2026 steel shipments of about 16.5 to 17.0 million net tons.[8] As per FMI, blast furnace grade will hold 61.1% of sales in 2026, and American rebuilds will hold that grade's demand steady through 2030.
Energy Costs and Supply Shocks Squeeze Pellet Producers
Pelletising plants burn large amounts of fuel and power to harden each tonne, so energy prices and grid outages erode producer margins faster than steel prices adjust. Pellet producers in Sweden and Ukraine lost output and margin in 2026. Key challenges in the iron ore pellet market include energy prices at pelletising plants, war damage to power grids and shipping disruption. LKAB's operating profit fell to MSEK 860 in the first quarter of 2026 from MSEK 3,638, mainly on lower sales and higher energy prices.[7] Ferrexpo cut commercial production 54% against the first half of 2025.[3] Producers will pass energy surcharges into pellet contracts, and steel mills will hedge by buying from two or more origins.
DR Grade and Sponge Iron Open Higher-Value Sales
DR-grade pellets will find the widest new demand in steel hubs building gas-based or hydrogen-ready reduction plants. LKAB's Malmberget permit covers a sponge iron demonstration plant, which would turn pellets into metallic iron before sale.[1] Merchant producers with low-silica ore will move from pellet sales to sponge iron and DR-grade contracts, and each step adds value per tonne shipped.
Which country CAGRs are profiled in the iron ore pellet market?
Table 6: Country CAGR Comparison for the Iron Ore Pellet Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 7.2% |
| India | 6.8% |
| South Korea | 6.6% |
| Japan | 6.0% |
| United Kingdom | 5.9% |
How do country-level CAGRs compare in the iron ore pellet market?
Chinese blast furnaces use pellets to cut sinter-plant emissions, and the move from sinter to pellets drives the top profiled rate. FMI estimates China at a 7.2% CAGR from 2026 to 2036, India at 6.8%, South Korea at 6.6%, Japan at 6.0% and the United Kingdom at 5.9%, against a 6.1% global CAGR. Three countries grow above the global rate, and Japan and the United Kingdom grow below the global figure, as both have older blast furnace fleets and limited new steel capacity.
- China raises pellet ratios in blast furnace burdens to lower sintering.
- India adds furnaces and pellet plants, as at Kalinganagar in Odisha.
- South Korean integrated mills import pellets for large coastal furnaces.
- Japanese mills buy high-grade imported pellets for a mature furnace fleet.
- Steelmaking in the United Kingdom is shifting toward electric furnaces, which buy fewer pellets.
Full report country CAGRs cover: East Asian rates for China, South Korea and Japan, India for South Asia and Pacific, the United Kingdom for Western Europe, and regional data for North America, Latin America, Eastern Europe, and Middle East and Africa.
Country-wise Analysis
China Iron Ore Pellet Market Outlook (2026 to 2036)
Chinese mills are raising the pellet ratio in furnace burdens to replace sinter, which cuts emissions from sinter plants. According to FMI's analysis, sales of pellets in China will expand at 7.2% over 2026 to 2036, the top profiled CAGR. Chinese pellet plants and import contracts with Brazilian and Australian suppliers will both add tonnes as the pellet ratio rises.
Key takeaway: Higher pellet ratios in blast furnaces in China will drive the largest profiled growth rate.
India Iron Ore Pellet Market Outlook (2026 to 2036)
Tata Steel agreed to acquire a 50.01% stake in Thriveni Pellets for up to Rs 6.36 billion, gaining control of a 4 million tonne per annum pellet plant and a 212 km slurry pipeline.[4] The company's Kalinganagar plant in Odisha raised crude steel capacity from 3 to 8 million tonnes per annum, with an investment of about Rs 270 billion.[6] FMI projects sales of pellets in India to rise at a 6.8% CAGR from 2026 to 2036 as new furnaces fill.
Key takeaway: Captive pellet plants owned by Indian steelmakers will supply most new demand in India.
South Korea Iron Ore Pellet Market Outlook (2026 to 2036)
FMI expects demand for pellets in South Korea to grow at a 6.6% CAGR from 2026 to 2036. LKAB reported delivery problems for Middle East customers after the Strait of Hormuz closure in the first quarter of 2026.[7] Korean integrated mills on the coast import pellets by sea, so similar shipping shocks will raise freight and delivery risk for them.
Key takeaway: Korean mills will spread pellet purchases across Brazil, Australia and Canada to cut shipping risk.
Japan Iron Ore Pellet Market Outlook (2026 to 2036)
Japanese mills run large blast furnaces on imported ore, and furnace relines will set pellet orders, since few new furnaces are planned, and Japan grows at a 6.0% CAGR from 2026 to 2036, just under the global rate. Japanese mills also roll high-grade sheet, and growth of the electrical steel market favours blast furnace routes that make low-residual steel.
Key takeaway: Reline schedules at Japanese furnaces will decide pellet tonnage.
United Kingdom Iron Ore Pellet Market Outlook (2026 to 2036)
Electric furnace plans leave the United Kingdom with the slowest of the five profiled rates, as FMI forecasts sales of pellets there to grow at a 5.9% CAGR from 2026 to 2036. UK steelmakers are moving toward electric arc furnaces, so pellet demand will come mostly from DR-grade imports for any new iron unit and from the remaining blast furnace operation.
Key takeaway: Each new UK iron unit built for electric furnaces will add DR-grade pellet imports.
Who are the notable companies in the iron ore pellet market?
ArcelorMittal, Vale, LKAB, Bahrain Steel, Arya Group, KIOCL, AM/NS India, Jindal SAW, Cleveland-Cliffs, Ferrexpo, Samarco and Tata Steel are among the profiled companies.
Merchant producers sell pellets on contract and spot, and integrated steelmakers run captive pellet plants for in-house furnaces. LKAB delivered 6.0 Mt of iron ore products in the second quarter of 2026.[2] Ferrexpo produced 1.4 Mt of premium pellets in the first half of 2026.[3] Cleveland-Cliffs is rebuilding the Middletown blast furnace, and Tata Steel is adding captive pellet capacity through Thriveni Pellets.[5][4]
- Merchant pellet producers: Vale, LKAB, Samarco, Ferrexpo, Bahrain Steel and KIOCL.
- Integrated steelmakers with captive pellet plants: ArcelorMittal, AM/NS India, Cleveland-Cliffs and Tata Steel.
- Indian pellet and pipe producers: Arya Group and Jindal SAW.
Competitive Benchmarking: Iron Ore Pellet Market
Table 7: Competitive Benchmarking for the Iron Ore Pellet Market (qualitative documentation ratings), 2026
| Company | Merchant Sales | DR Grade Exposure | Downstream Iron | Recency |
|---|---|---|---|---|
| LKAB | High | Medium | High | High |
| Ferrexpo | High | Medium | Low | High |
| Cleveland-Cliffs | Low | Low | Low | High |
| Tata Steel | Low | Low | Low | Medium |
| Vale | High | High | Medium | Low |
Pellet producer ratings mirror the depth of dated company disclosure on each attribute and say nothing about market share.
Key Developments in the Iron Ore Pellet Market
- In September 2026, Ferrexpo reported first-half pellet output of 1.4 Mt, including 163 thousand tonnes of DR pellets.[3]
- In August 2026, Cleveland-Cliffs announced a USD 1 billion Middletown Works investment with a blast furnace rebuild.[5]
- In August 2026, LKAB reported second-quarter deliveries of 6.0 Mt.[2]
- In July 2026, Cleveland-Cliffs guided full-year steel shipments at about 16.5 to 17.0 million net tons.[8]
- In June 2026, LKAB received an environmental permit for Malmberget, including a sponge iron demonstration plant.[1]
- In April 2026, LKAB flagged a delivery shortfall of around 2 million tonnes for 2026.[7]
- In January 2026, Tata Steel agreed to acquire 50.01% of Thriveni Pellets.[4]
- In May 2025, Tata Steel inaugurated Phase II at Kalinganagar.[6]
Key Players in the Iron Ore Pellet Market
Merchant Pellet Producers
- Vale
- LKAB
- Samarco
- Ferrexpo
- Bahrain Steel
- KIOCL
Integrated Steelmakers
- ArcelorMittal
- AM/NS India
- Cleveland-Cliffs
- Tata Steel
Indian Pellet and Pipe Producers
- Arya Group
- Jindal SAW
Iron Ore Pellet Market - Report Scope
Table 8: Report Scope for the Iron Ore Pellet Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product grade; application; region |
| Quantitative units | USD billion |
| Market definition | Indurated iron ore pellets of blast furnace and direct reduction grade sold to steelmakers, foundry iron producers and other users. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | ArcelorMittal, Vale, LKAB, Bahrain Steel, Arya Group, KIOCL, AM/NS India, Jindal SAW, Cleveland-Cliffs, Ferrexpo, Samarco, Tata Steel |
| Forecast period | 2026 to 2036 |
Iron Ore Pellet Market - Research Methodology
Table 9: Research Methodology for the Iron Ore Pellet Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Producer interim reports, steelmaker releases and Indian infrastructure trade press dated May 2025 or later. |
| Desk Research | Desk research covers pellet output, delivery disruption, energy costs, furnace rebuilds and captive pellet deals. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 74.9 billion and the 6.1% CAGR from 2026 to 2036. |
| Data Validation | Output, cost and capacity figures were checked against each producer release. |
Iron Ore Pellet Market by Segments
Iron Ore Pellet Market segmented by Product Grade:
- Blast Furnace (BF) Grade
- Direct Reduction Iron (DRI) Grade
Iron Ore Pellet Market segmented by Application:
- Steel Manufacturing
- Foundries
- Other Applications
Iron Ore Pellet Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] LKAB. (2026, June 15). LKAB granted environmental permit for operations in Gällivare. https://lkab.com/en/press/lkab-granted-environmental-permit-for-operations-in-gallivare/
- [2] LKAB. (2026, August 13). Interim report April-June 2026: Lower earnings weighed down by foreign exchange effects and increased costs. https://lkab.com/en/press/interim-report-april-june-2026-lower-earnings-weighed-down-by-foreign-exchange-effects-and-increased-costs/
- [3] Ferrexpo plc. (2026, September 25). Interim Results for the six months ended 30 June 2026. https://www.ferrexpo.com/news-media/press-releases/2026/interim-results-for-the-six-months-ended-30-june-2026/
- [4] Indian Infrastructure. (2026, January 9). Tata Steel acquires majority stake in TPPL. https://indianinfrastructure.com/2026/01/09/tata-steel-acquires-majority-stake-in-tppl/
- [5] Cleveland-Cliffs Inc. (2026, August 21). Cleveland-Cliffs Announces $1 Billion Middletown Works Investment to be Supported by $500 Million U.S. Department of Energy Award. https://www.clevelandcliffs.com/news/news-releases/detail/702/cleveland-cliffs-announces-1-billion-middletown-works
- [6] Indian Infrastructure. (2025, May 27). Tata Steel inaugurates Phase II expansion of Kalinganagar plant operations. https://indianinfrastructure.com/2025/05/27/tata-steel-inaugurates-phase-ii-expansion-of-kalinganagar-plant-operations/
- [7] LKAB. (2026, April 23). Interim report January-March 2026: Lower earnings and weaker market conditions. https://lkab.com/en/press/interim-report-january-march-2026-lower-earnings-and-weaker-market-conditions/
- [8] Cleveland-Cliffs Inc. (2026, July 23). Cleveland-Cliffs Reports Second-Quarter 2026 Results. https://www.clevelandcliffs.com/news/news-releases/detail/700/cleveland-cliffs-reports-second-quarter-2026-results
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the iron ore pellet market during 2026?
- What market size is projected by 2036?
- Which product grade holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the iron ore pellet market expected in 2026?
Pellet buyers will purchase an estimated USD 74.9 billion of iron ore pellets in 2026, up from USD 70.6 billion in 2025. FMI sees USD 135.4 billion by 2036.
What CAGR is projected for the iron ore pellet market through 2036?
Pellet sellers can plan on a 6.1% CAGR from 2026 to 2036. New and rebuilt blast furnaces in India and the United States underpin that rate.
Which product grade holds a notable market share in 2026?
BF grade is expected to lead with 61.1% share in 2026. Direct reduction grade is estimated at 38.9%.
Which application holds a notable market share in 2026?
Steel manufacturing will lead with 88.2% share in 2026. Foundries are likely to hold about 7.4% through merchant pig iron.
Which country has a notable expansion outlook through 2036?
China, at a 7.2% CAGR from 2026 to 2036, leads the profiled countries according to FMI. The United Kingdom grows slowest at 5.9%.
Who are the key companies in the iron ore pellet market?
LKAB is planning a sponge iron demonstration plant, and Tata Steel is buying control of Thriveni Pellets. Cleveland-Cliffs is rebuilding the Middletown blast furnace.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Grade, 2026 to 2036
- Blast Furnace (BF) Grade
- Direct Reduction Iron (DRI) Grade
- Y-o-Y Growth Trend Analysis By Product Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Steel Manufacturing
- Foundries
- Other Applications
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Grade
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Grade
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Grade
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- LKAB
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ferrexpo
- Cleveland-Cliffs
- Tata Steel
- Vale
- Samarco
- Bahrain Steel
- KIOCL
- ArcelorMittal
- AM/NS India
- Arya Group
- Jindal SAW
- LKAB
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


