

- Market Size (2026)
- USD 188.5 Mn
- Forecast (2036)
- USD 554.8 Mn
- CAGR (2026 to 2036)
- 11.4%
How big is Nursery Establishment Boosters Market in 2026?
Demand in the nursery establishment boosters market is anticipated to expand at 11.4% CAGR through 2036. Industry valuation grows from USD 169.2 million in 2025 to USD 188.5 million in 2026 and is anticipated to reach USD 554.8 million by 2036.
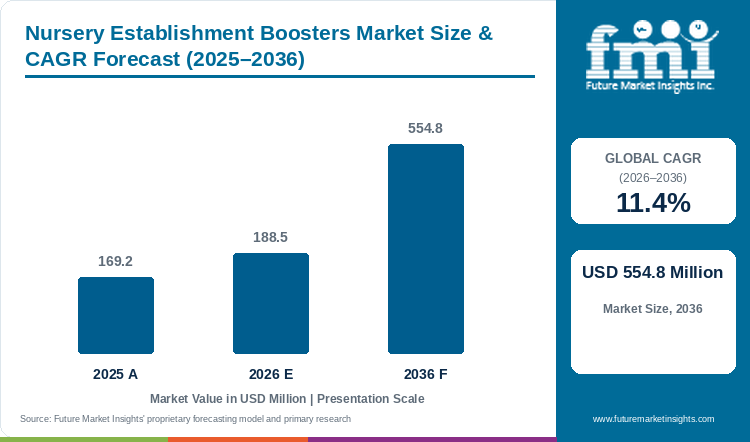
The global nursery establishment boosters market was valued at USD 169.2 million in 2025 and is projected to grow from USD 188.5 million in 2026 to USD 554.8 million by 2036, at a CAGR of 11.4% from 2026 to 2036. Amino acid and peptide-based products account for the leading 38.8% share in 2026, owing to low-dose application through seed treatment, root drench, soil placement and fertigation. USDA reported 23,060 horticulture operations and USD 18.3 billion in U.S. horticultural sales during 2024, including USD 5.34 billion from nursery stock [1]. Labour represented 36% of horticulture expenses, due to which growers are giving higher importance to uniform seedlings and avoiding repeated establishment work. USDA also estimated 95.3 million corn acres and 85.4 million soybean acres for 2026 [5]. Presence of broad planted area is expected to support repeatable seed and in-furrow treatment across field crops.
Key Market Trends & Insights
- By product type, amino acid and peptide-based products led with 38.8% of demand in 2026, supported by low-dose placement across seed, soil, root drench and fertigation routes.
- By crop type, cereals and grains accounted for 46.2% of demand in 2026. U.S. corn and soybean planting covered 180.7 million acres in 2026, creating broad scope for repeatable at-plant treatment. [5]
- By application method, soil application represented 40.7% in 2026 because treatment reaches seed and developing roots before adequate leaf area is formed.
- By farm type, large commercial farms held 44.3% in 2026, as standardized seed-treatment, in-furrow and irrigation equipment supports block trials and repeatable dosing.
- By sales channel, agri-input distributors generated 41.6% of demand in 2026, owing to local crop direction, planting-period inventory and first-use product support.
Regional Highlights
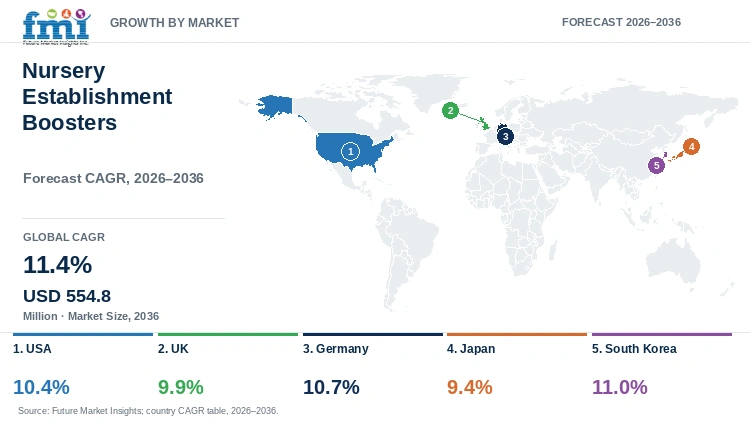
- Fastest-growing profiled country: South Korea (11.0% CAGR, 2026 to 2036).
- Germany (10.7%) and the USA (10.4%) follow, while Japan records the lowest profiled CAGR at 9.4%.
- Germany harvested 4.5 million tonnes of vegetables from 131,700 hectares in 2025 [3]. South Korea reported 53,517 hectares of vegetable greenhouses in 2024 [14], and the difference supports open-field placement in Germany and measured fertigation in South Korea.
Market Size & Forecast
Table 1: Market Size and Forecast for the Nursery Establishment Boosters Market (USD million and multiple), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 169.2 million |
| Estimated Market Size in 2026 | USD 188.5 million |
| Projected Market Size by 2036 | USD 554.8 million |
| CAGR, 2026 to 2036 | 11.4% |
| Added Revenue, 2026 to 2036 | USD 366.3 million |
| Market Expansion Multiple | 2.94x |
Broad-acre crops provide the largest application base for nursery establishment boosters, whereas nursery and protected-crop operations provide higher value from every treated unit, according to FMI. The 180.7 million U.S. corn and soybean acres planted in 2026 shows the area available for seed and in-furrow programs [5]. Apart from that, 23,060 horticulture operations provides a professional base for drench and fertigation products [1]. Germany produced 4.5 million tonnes of vegetables in 2025, including 219,200 tonnes under glass or high accessible cover, which supports separate application across outdoor crops and protected cultivation [3]. However, the complete planted area cannot be treated as addressable demand. Product dose, local crop response, equipment compatibility and allowed claims will decide whether first trial develops into regular purchasing.
Treated Acreage and Application Intensity
Nursery establishment boosters are purchased when growers can connect one application with seed, transplant or root-zone activity. Broad-acre crops provides application scale, while nursery and greenhouse crops support higher value per treated unit. The indicators below compare the operating base with application conditions that can support repeat purchasing.
Table 2: Treated Acreage and Application Intensity for the Nursery Establishment Boosters Market (operations, hectares, acres, percentages, and USD per unit), mixed reporting years from 2024 to 2036
| Metric | Operating Base | Application Input | Calculated Result | Market Meaning |
|---|---|---|---|---|
| U.S. horticulture sales per operation | USD 18.3 billion across 23,060 operations in 2024 | Revenue divided by operations | About USD 793,600 per operation | Higher committed crop value supports careful establishment trials and repeat dosing. |
| U.S. corn and soybean planting base | 95.3 million corn acres and 85.4 million soybean acres in 2026 | Combined planted area | 180.7 million acres | One seed or in-furrow program can scale across broad acreage where per-acre dose is suitable. |
| Germany outdoor vegetable intensity | 4.297 million tonnes from 130,448.9 hectares in 2025 | Output divided by area | About 32.9 tonnes per hectare | High output per hectare raises the cost of uneven establishment across vegetable programs. |
| South Korea greenhouse coverage | 53,517 hectares of vegetable greenhouses in 2024 | Controlled irrigation base | 53,517 hectares | Greenhouse systems provide measurable fertigation and root-zone placement opportunities. |
| Market value per U.S. operating base | USD 188.5 million global market in 2026 | Market divided by 23,060 U.S. horticulture operations | About USD 8,174 per operation | This is an intensity benchmark only and is not an estimate of U.S. spending. |
| Forecast expansion | USD 188.5 million in 2026 to USD 554.8 million in 2036 | 2036 value divided by 2026 value | 2.94x | Repeat purchasing must expand beyond first trials for the market to reach the forecast value. |
Basis: Calculations use report market values and official operating data. USD 18.3 billion / 23,060 = USD 793,582; 95.3 + 85.4 = 180.7 million acres; 4,297,226.2 tonnes / 130,448.9 hectares = 32.9 tonnes per hectare; USD 188.5 million / 23,060 = USD 8,174; USD 554.8 million / USD 188.5 million = 2.94x. Supporting years are mixed and the results are comparative indicators, not country-market estimates. [1] [5] [3] [14]
Analyst Perspective
“Products fitting existing planting and irrigation work will gain faster adoption as growers avoid adding another labour activity. Local crop trials will decide repeat demand because visible root response remains the main reason for wider acreage use.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the nursery establishment boosters market segmented?
Nursery establishment boosters market is segmented by product type, crop type, application method, farm type, sales channel and region. Amino acid and peptide-based products, cereals and grains, soil application, large commercial farms and agri-input distributors are the leading subsegments in 2026.
By product type: amino acid and peptide-based, seaweed and botanical-based, humic and fulvic-based, microbial-enhanced blends, and others.
By crop type: cereals and grains, fruits and vegetables, oilseeds and pulses, turf and ornamentals, and others.
By application method: soil application, foliar application, fertigation or drip, seed application, and others.
By farm type: large commercial farms, mid-size farms, smallholders, greenhouses and nurseries, and others.
By sales channel: agri-input distributors, cooperatives, agri-retail chains, online or direct-to-farm, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do amino acid and peptide products retain product type demand?
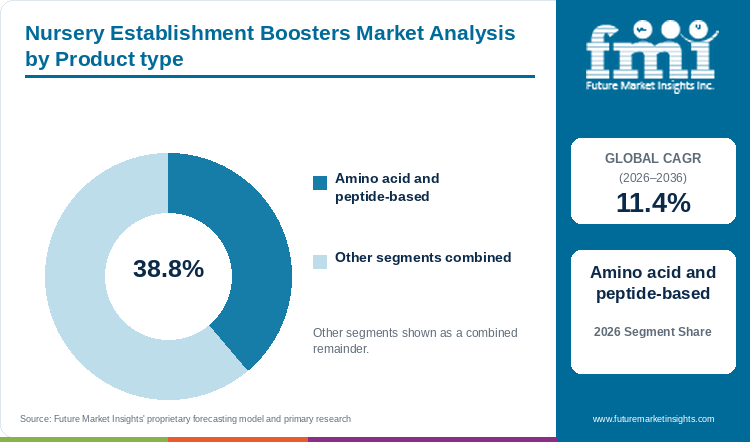
Based on product type, amino acid and peptide-based products are projected to account for 38.8% in 2026, supported by precise low-dose use.
Table 3: Product Type Share for the Nursery Establishment Boosters Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Amino Acid and Peptide-Based Products | 38.8% |
| Other Segments Combined | 61.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 4: Product Type Leadership and Market Growth for the Nursery Establishment Boosters Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.4% |
| Leading Segment | Amino Acid and Peptide-Based Products |
Amino acid and peptide-based products are facing higher preference during short nursery cycle as these products can be applied at low dose through seed treatment, root drench, soil and fertigation. These products are used along with the regular nutrient program and does not require replacement of the complete fertilizer plan. Low dose reduces handling volume and allows treatment near seed or young roots. Apart from that, wider application routes makes the product suitable for nurseries, field crops and protected cultivation. Owing to its easy inclusion in early crop programs, amino acid and peptide-based products are expected to retain higher product type demand.
- Amino acid and peptide-based products are projected to hold 38.8% of product type demand in 2026, supported by low-dose use during short establishment period.
- Syngenta reported in June 2025 that its Orangeburg biologicals facility can produce 16,000 tons of plant biostimulants annually. Wider production is increasing availability of biological products for early crop programs. [4]
What supports cereals and grains as the preferred crop category?
By crop type, cereals and grains are estimated to hold 46.2% in 2026, owing to repeatable at-plant treatment over broad acreage.
Cereals and grains are grown over broad planted area, due to which one establishment treatment can be repeated across a large number of acres. Seed coating and in-furrow products are placed near the seed and does not require another field operation after emergence. This allows growers to compare crop stand and early biomass over treated and untreated blocks. A suitable per-hectare dose also becomes important where one product is being applied across broad acreage. Repeatable treatment and large planted area is expected to support the demand for cereals and grains throughout the forecast period.
- Cereals and grains are estimated to account for 46.2% of crop type demand in 2026, owing to repeatable seed and in-furrow treatment over broad planted area.
- USDA reported in June 2026 that U.S. farmers planted 95.3 million acres of corn and 85.4 million acres of soybeans. Presence of broad acreage creates higher scope for repeatable establishment treatment. [5]
How does soil application meet early root-zone requirements?
In 2026, soil application is expected to lead application method with 40.7% share, driven by direct placement near developing roots.
Soil application places nursery establishment boosters close to seed and developing roots before the crop forms adequate leaf area. In-furrow treatment, root drench and soil granules can be included in regular planting and nursery operation, due to which the product remains available in the early root zone. Soil placement also supports crops where foliar area is not sufficient during the first growth stage. However, complicated mixing and separate equipment cleaning may limiting use among smaller growers. Direct placement near young roots is anticipated to uphold the soil application segment growth.
- Soil application is expected to represent 40.7% of application demand in 2026 because treatment reaches roots before substantial leaf growth.
- Rovensa Next launched GALACTEK in February 2026 for strengthening roots, nutrient uptake and early-season growth. The launch expands availability of products placed near developing roots. [6]
Why do large commercial farms support farm type demand?
Large commercial farms are likely to capture 44.3% share in 2026, enabled by standardized protocols and field-level return testing.
Large commercial farms are increasingly using nursery establishment boosters as these farms have standard seed treatment, in-furrow and fertigation equipment. Large farms can apply the product over selected blocks and compare stand count, root development and early biomass before using it across larger area. Existing equipment reduces the need for a separate application activity, which in turn supports repeatable dose on different fields. Moreover, larger planted area allows the cost of trial and technical support to be distributed over more acres. These factors are expected to support demand from large commercial farms.
- Large commercial farms are likely to capture 44.3% of farm type demand in 2026 because standardized equipment supports repeatable dosing.
- Large farms can compare treated blocks before wider use, which reduces the risk of applying an untested dose across the complete planted area.
Which conditions keep agri-input distributors relevant in sales channels?
Agri-input distributors are set to lead sales channel with 41.6% share in 2026, underpinned by local agronomy and inventory access.
Agri-input distributors provide crop, dose, timing and mixing information required for nursery establishment boosters. Product response differs according to soil, irrigation water, seed and application equipment, due to which growers requires local direction before using the product. Distributors also hold local inventory close to the planting period and provide information related to suitable application route. This makes distributor support important where a grower is testing the product for the first time. Presence of local agronomy and ready product availability is expected to favor agri-input distributors.
- Agri-input distributors are set to hold 41.6% of sales channel demand in 2026 because local agronomy supports product selection and timing.
- Local inventory and crop direction allows distributors to supply the selected product before the next nursery or planting period.
What are the drivers, restraints, and opportunities in the nursery establishment boosters market?
In the nursery establishment boosters market, the key driver is establishment risk, the key restraint is local proof, and the key opportunity is integrated delivery.
- Driver: Weather and production variability increase the value of protecting the first weeks of crop development.
- Restraint: Buyers require local efficacy, compatible handling, and compliant claims before routine use.
- Opportunity: Seed treatment, in-furrow placement, and fertigation can add support without a separate field operation.
Establishment Risk Raises Input Value
Weak emergence and transplant shock affects the crop stand during the first stage of growth and later nutrient application cannot completely recover the lost plants. Dry soil, limited water and changing temperature can reduce root growth, due to which growers are using establishment products with soil and irrigation programs. The UK produced 2.6 million tonnes of vegetables in 2025, increasing by 8.0%, while planted area increased by 6.7% to 104,000 hectares [7]. The government also reported dry conditions and water limits during spring and summer planting, which resulted in uneven establishment across several field vegetables. Increasing requirement to protect seed, transplant, labour and irrigation expenses is boosting the use of early root-support products. These factors are expected to drive the nursery establishment boosters market growth over the forecast period.
Local Proof Slows Repeat Purchasing
Performance of nursery establishment boosters can change according to soil, water, temperature, crop and application dose. A product showing suitable response in one crop or region may not provide the same result under another irrigation or soil condition, due to which growers requires local trial before regular purchasing. In August 2026, Acadian Plant Health stated that CE-marked biostimulants are assessed for safety, quality, environment protection and agronomic performance before use across 27 EU member states [8]. Such certification provides a common regulatory route; however, it does not remove the requirement of crop-specific dose and local application direction. A missed trial period can also delay repeat order until the next planting season. Requirement of local evidence, compliant claims and correct application may hamper the growth of nursery establishment boosters market.
Integrated Delivery Opens Expansion Route
Seed treatment and at-plant delivery places nursery establishment boosters close to seed or young root without requiring another field pass. The product can move with commercial seed treatment, in-furrow placement or planting operation, which reduces separate labour and supports uniform dose during establishment stage. In May 2026, Acadian Plant Health expanded its EMEA seed-treatment program by connecting seaweed-based biostimulants with early establishment and stress preparation [11]. Such application is suitable for seed processors and growers when the formulation remains stable during treatment, storage and planting. Increasing adoption of seed-applied and in-furrow biological products is expected to create new avenues for nursery establishment booster manufacturers.
Which country CAGRs are profiled in the nursery establishment boosters market?
Table 5: Country CAGR Comparison for the Nursery Establishment Boosters Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 10.4% |
| UK | 9.9% |
| Germany | 10.7% |
| Japan | 9.4% |
| South Korea | 11.0% |
How do country-level CAGRs compare in the nursery establishment boosters market?
FMI data suggests South Korea will record the highest growth among the profiled countries at 11.0% CAGR through 2036, followed by Germany at 10.7%.
- USA demand benefits from large professional horticulture and wholesale distribution channels.
- The UK combines planted vegetable scale with recurring water and establishment pressure.
- Germany offers extensive outdoor vegetable production and formal evidence expectations.
- Japan links adoption to labor-saving production methods and smart-agriculture conversion.
- South Korea is expanding smart greenhouse coverage and data-driven production systems.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- The USA nursery establishment boosters market is projected to grow at 10.4% CAGR through 2036. USDA reported in February 2026 that 23,060 horticulture operations generated USD 18.3 billion sales during 2024, of which nursery stock accounted for USD 5.34 billion and propagative materials represented USD 780 million [1]. Wholesale channels accounted for 85% of horticultural sales, which provides distributors a large base for seed, drench and fertigation products. High value nursery stock increases the loss associated with weak seedling and transplant establishment. Apart from that, professional horticulture operations have irrigation and application equipment that can support repeat dosing. Presence of specialist dealers and large nursery sales is expected to support the USA market growth.
- The UK nursery establishment boosters market is anticipated to rise at 9.9% CAGR through 2036. Defra reported in June 2026 that vegetable production reached 2.6 million tonnes in 2025, while planted area increased by 6.7% to 104,000 hectares [7]. Dry weather and limited water availability affected crop establishment during spring and summer planting. Nursery establishment boosters can be added through soil and fertigation application for supporting young roots where planting moisture remains uneven. Increasing vegetable area together with recurring water pressure is expected to raise requirement for early root-support products. These factors are likely to fuel the UK nursery establishment boosters market growth.
- Germany nursery establishment boosters market is expected to advance at 10.7% CAGR over the assessment period. Destatis recorded 130,448.9 hectares of outdoor vegetables and more than 4.29 million tonnes production during 2025 [3]. Carrots accounted for 14,190.7 hectares, whereas productive asparagus represented 19,217.6 hectares. Different planting cycles across vegetables increases application for transplant, soil and root-zone products. However, dose and crop response needs to be supported for each crop before wider application. Presence of extensive outdoor vegetable production and documented field practices is anticipated to support the Germany market revenue growth.
- Japan nursery establishment boosters market is estimated to expand at 9.4% CAGR through 2036. Japan agriculture ministry stated that the number of core farmers may decline from 1.16 million to 300,000 over twenty years and smart-agriculture demonstrations have been conducted in 217 districts [9]. Declining farm labour is increasing use of automated irrigation, transplanting and measured input application. Nursery establishment boosters that can be supplied with existing irrigation or transplant systems requires less additional handling during early crop stage. However, products still needs evidence for Japanese crops and nursery schedules before routine use. Increasing adoption of labour-saving production methods is expected to support the market growth in Japan.
- South Korea nursery establishment boosters market is estimated to post 11.0% CAGR over the forecast period. The agriculture ministry planned to increase designated smart-agriculture greenhouse districts from five locations in 2025 to ten cumulatively in 2026 [2]. The wider plan covers smart technology across 35% of 55,000 hectares of greenhouse area by 2030, compared to 16% in 2024. Smart greenhouse systems use controlled irrigation and digital production records, due to which soluble establishment products can be measured and supplied near the root zone. Expansion of protected cultivation and fertigation-compatible application is expected to drive the South Korea market growth.
Who are the notable companies in the nursery establishment boosters market?
Plant Health Care, Compo Expert, Valagro, UPL, Rovensa Next, Hello Nature, Acadian Plant Health, and Biolchim are notable companies profiled in this market.
nursery establishment boosters market is moderately fragmented with presence of peptide, seaweed, microbial and root-zone nutrition suppliers. Plant Health Care, Valagro and Hello Nature provide plant-response products, whereas Compo Expert, Rovensa Next and Biolchim offer soil, drench and fertigation programs. UPL and Acadian Plant Health connect natural-input technologies with seed treatment and stress-management application. Some of the prominent players are increasing production, developing crop-specific products and expanding regional registration in order to cater the growing demand for biological products. Wider product portfolio and presence of agronomy teams is expected to help companies in increasing its customer base.
- Plant-response platforms: Plant Health Care, Valagro, and Hello Nature connect biochemical responses with stress and early development programs.
- Root-zone suites: Compo Expert, Rovensa Next, and Biolchim combine nutrition, biostimulation, and soil or fertigation routes.
- Integrated natural-input platforms: UPL and Acadian Plant Health connect biological or marine technologies with seed and stress-management uses.
Competitive Benchmarking: Nursery Establishment Boosters Market
Table 6: Competitive Benchmarking for the Nursery Establishment Boosters Market (qualitative capability ratings), 2026
| Company | Rooting and stress portfolio | Delivery coverage | Biological breadth | Reach |
|---|---|---|---|---|
| Plant Health Care | High | Medium | Medium | Medium |
| Compo Expert | High | High | High | High |
| Valagro | High | High | High | High |
| UPL | High | High | High | High |
| Rovensa Next | High | High | High | High |
| Hello Nature | High | High | High | High |
| Acadian Plant Health | High | Medium | High | High |
| Biolchim | High | High | High | High |
High indicates presence of wider documented products or application capability in the stated area, whereas Medium indicates available but comparatively limited public evidence. The ratings describes documented company capability and does not indicate product quality, revenue share or company ranking.
Key Developments in the Nursery Establishment Boosters Market
- In August 2026, Acadian Plant Health documented CE-marked biostimulants for all 27 EU member states, including claims tied to root development and early establishment [8].
- In February 2026, Rovensa Next launched GALACTEK in North America for root strength, nutrient uptake, and early-season stress support [6].
- In August 2025, Acadian Plant Health added its fifth CE-marked biostimulant under the EU Fertilising Products Regulation [10].
- In May 2025, Syngenta opened its Orangeburg biologicals facility with annual capacity for 16,000 tons of plant biostimulants [13].
Key Players in the Nursery Establishment Boosters Market
Plant-response platforms
- Plant Health Care
- Valagro
- Hello Nature
Root-zone and multi-mode suites
- Compo Expert
- Rovensa Next
- Biolchim
Integrated natural-input platforms
- UPL
- Acadian Plant Health
Nursery Establishment Boosters Market - Report Scope
Table 7: Report Scope for the Nursery Establishment Boosters Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; crop type; application method; farm type; sales channel; region |
| Quantitative units | USD million |
| Market definition | Supplier revenue from dedicated products positioned for nursery and early establishment support. Base fertilizers, seeds, nursery stock, crop protection, and later-season products are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA; UK; Germany; Japan; South Korea; additional countries in the full report |
| Forecast period | 2026 to 2036 |
| Approach | The report covers supplier activity, market segments, application methods and country demand within the stated market definition. |
Nursery Establishment Boosters Market - Research Methodology
Table 8: Research Methodology for the Nursery Establishment Boosters Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | The research study includes primary interviews with manufacturers, distributors, end users, procurement teams and industry experts. Interviews covers purchasing decision, product evaluation, pricing, adoption barrier, approval requirement and technical support. Respondents are also asked about the evidence required before product trial develops into regular purchasing. |
| Desk Research | Desk research includes government statistics, regulatory publications, industry associations, technical literature, company filings, product information and official company announcements. Sources are checked for publication date, geographic relevance and market scope. Company development, capacity and product claims are retained when supported by public evidence. |
| Market Sizing and Forecasting | Market sizing combines baseline value with historical growth, segment structure, price and volume indicators, adoption level, company participation and country demand. Forecast considers economic activity, regulation, technology adoption, purchasing cycle and supply availability. Segment and regional estimates are matched with the final market value. |
| Data Validation | Market estimates are checked with government data, company activity, trade pattern, industry development and primary interviews. Validation also checks whether products, applications and company revenue falls within the market definition. Adjacent products, unsupported claims and overlapping revenue are excluded. |
Nursery Establishment Boosters Market by Segments
Product type
- Amino acid and peptide-based
- Seaweed and botanical-based
- Humic and fulvic-based
- Microbial-enhanced blends
- Others
Crop type
- Cereals and grains
- Fruits and vegetables
- Oilseeds and pulses
- Turf and ornamentals
- Others
Application method
- Soil application
- Foliar application
- Fertigation or drip
- Seed application
- Others
Farm type
- Large commercial farms
- Mid-size farms
- Smallholders
- Greenhouses and nurseries
- Others
Sales channel
- Agri-input distributors
- Cooperatives
- Agri-retail chains
- Online or direct-to-farm
- Others
Nursery Establishment Boosters Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, February 26). U.S. horticulture operations report USD 18.3 billion in sales.
- [2] Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, January 30). 2026 smart agriculture promotion implementation plan.
- [3] Statistisches Bundesamt. (2026, February 26). Farms, cultivated areas, yields and harvest quantities of vegetables and strawberries, 2025.
- [4] Syngenta. (2025, June 30). Syngenta to become global leader in biologicals; expanding nature-inspired solutions for farmers.
- [5] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, June 30). Corn planted acreage down 3% from 2025, soybean acreage up 5% from last year.
- [6] Rovensa Next. (2026, February 23). Rovensa Next launches TYPHOON and GALACTEK in North America.
- [7] Department for Environment, Food & Rural Affairs. (2026, June 25). Horticulture statistics 2025.
- [8] Acadian Plant Health. (2026, August 3). CE-marked biostimulants in EMEA.
- [9] Ministry of Agriculture, Forestry and Fisheries of Japan. (2026). Smart agriculture.
- [10] Acadian Plant Health. (2025, August 14). Acadian expands CE-marked biostimulant portfolio across Europe.
- [11] Acadian Plant Health. (2026, May 27). Advancing seed treatment biostimulant in EMEA.
- [12] Rovensa Next. (2026, June 11). Rovensa Next to distribute Novonesis biosolutions for plant health in the United States.
- [13] Syngenta. (2025, February 26). Syngenta strengthens global leadership in agricultural biologicals.
- [14] Kingdom of the Netherlands, Agroberichten Buitenland. (2026, April 29). Greenhouse in South Korea 2026.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is Nursery Establishment Boosters Market worth during 2026?
- What value is Nursery Establishment Boosters Market projected by 2036?
- Which product type holds notable Nursery Establishment Boosters Market share?
- Which crop type holds notable Nursery Establishment Boosters Market share?
- Which countries have notable Nursery Establishment Boosters Market growth?
- Which companies are notable in Nursery Establishment Boosters Market today?
Frequently Asked Questions
How big is the Nursery Establishment Boosters Market in 2026?
The nursery establishment boosters market is valued at USD 188.5 million in 2026 and is projected to reach USD 554.8 million by 2036.
What CAGR is projected for Nursery Establishment Boosters Market through 2036?
the nursery establishment boosters market is projected to grow at 11.4% CAGR from 2026 to 2036.
Which product type holds a notable share during 2026?
As per FMI, amino acid and peptide-based products are projected to hold 38.8% of product type demand in 2026, supported by low-dose use during short establishment period.
Which crop type holds a notable share during 2026?
FMI finds that cereals and grains will hold 46.2% of crop type demand in 2026, owing to repeatable seed and in-furrow treatment over broad planted area.
Which country has a notable expansion outlook through 2036?
South Korea demand is projected to expand at 11.0% CAGR from 2026 to 2036, supported by smart-greenhouse and controlled fertigation application.
Which companies are active in nursery establishment boosters during 2026?
Plant Health Care, Compo Expert, Valagro, UPL, Rovensa Next, Hello Nature, Acadian Plant Health and Biolchim are notable companies in the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product type, 2026 to 2036
- Amino acid and peptide-based
- Seaweed and botanical-based
- Humic and fulvic-based
- Microbial-enhanced blends
- Others
- Y-o-Y Growth Trend Analysis By Product type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product type, 2026 to 2036
- Global Market Analysis and Forecast, By Crop type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Crop type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Crop type, 2026 to 2036
- Cereals and grains
- Fruits and vegetables
- Oilseeds and pulses
- Turf and ornamentals
- Others
- Y-o-Y Growth Trend Analysis By Crop type, 2021 to 2025
- Absolute $ Opportunity Analysis By Crop type, 2026 to 2036
- Global Market Analysis and Forecast, By Application method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application method, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application method, 2026 to 2036
- Soil application
- Foliar application
- Fertigation or drip
- Seed application
- Others
- Y-o-Y Growth Trend Analysis By Application method, 2021 to 2025
- Absolute $ Opportunity Analysis By Application method, 2026 to 2036
- Global Market Analysis and Forecast, By Farm type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Farm type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Farm type, 2026 to 2036
- Large commercial farms
- Mid-size farms
- Smallholders
- Greenhouses and nurseries
- Others
- Y-o-Y Growth Trend Analysis By Farm type, 2021 to 2025
- Absolute $ Opportunity Analysis By Farm type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales channel, 2026 to 2036
- Agri-input distributors
- Cooperatives
- Agri-retail chains
- Online or direct-to-farm
- Others
- Y-o-Y Growth Trend Analysis By Sales channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product type
- By Crop type
- By Application method
- By Farm type
- By Sales channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Plant Health Care
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Compo Expert
- Valagro
- UPL
- Rovensa Next
- Hello Nature
- Acadian Plant Health
- Biolchim
- Plant Health Care
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


