

- Market Size (2026)
- USD 1.5 Bn
- Forecast (2036)
- USD 2.8 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is the Orthopedic Oncology Market in 2026?
USD 1.5 billion in 2026, reaching USD 2.8 billion by 2036 at a 6.5% CAGR
The orthopedic oncology market was valued at USD 1.4 billion in 2025. The market is set to reach USD 1.5 billion by 2026-end and grow at a CAGR of 6.5% between 2026–2036 to reach USD 2.8 billion by 2036. Diagnostic Imaging will dominate with a 74.0% share, while Stage II will lead with a 34.0% share.
Bone tumor diagnostics and treatment planning require multi-modal imaging and coordinated surgical oncology pathways. Orthopedic oncology demand is shaped by rising musculoskeletal cancer incidence, tumor staging complexity, and the shift toward limb-salvage surgery over amputation. Buyers include hospital radiology departments, cancer specialty centers, and orthopedic oncology programs that evaluate imaging resolution, biopsy precision, and treatment planning integration.
Growth reflects increased adoption of advanced MRI and PET imaging for tumor margin assessment and treatment response monitoring. The World Health Organization reported in 2025 that cancer incidence continued to rise globally with musculoskeletal tumors presenting across adolescent and adult populations. This diagnostic burden supports procurement of imaging equipment that improves staging accuracy and surgical planning.
Buyers separate suppliers on imaging resolution for bone and soft tissue evaluation, AI-assisted tumor detection capability, and integration with surgical navigation systems. GE HealthCare and Siemens Healthineers rely on broad oncology imaging portfolios, while Koninklijke Philips and Fujifilm Healthcare gain preference where buyers need ultrasound-guided biopsy and MRI workflow optimization.
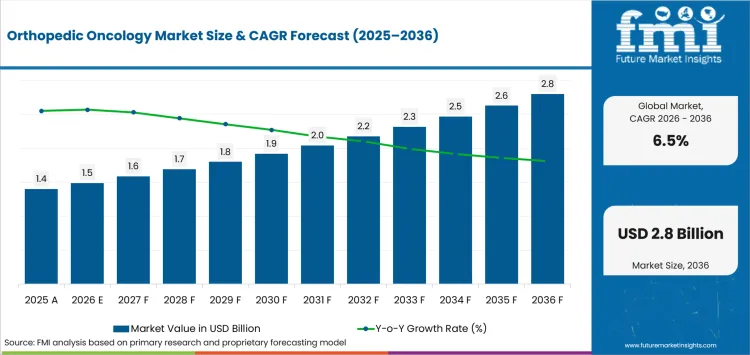
Key Takeaways of Orthopedic Oncology Market
- Hospitals and cancer specialty centers invest in orthopedic oncology imaging to improve tumor staging accuracy and surgical margin assessment from diagnosis through treatment planning.
- Diagnostic Imaging is projected to account for 74.0% share in 2026, supported by its role in tumor staging and treatment planning.
- Stage II is estimated to represent 34.0% share in 2026, reflecting the diagnostic and surgical intensity of localized high-grade tumors.
- Osteosarcoma is forecast to hold 38.0% share in 2026 due to adolescent and young adult case volumes.
- Legacy imaging interfaces and workflow disruption can delay implementation despite a clear case for improved staging accuracy.
- Competition includes GE HealthCare, Siemens Healthineers, Koninklijke Philips, Fujifilm Healthcare, and Hologic across oncology imaging and biopsy workflows.
Analyst Perspective
"Orthopedic oncology imaging earns budget approval by improving tumor staging accuracy and surgical margin assessment across the diagnostic pathway. Scanner capability alone cannot protect outcomes if treatment planning integration or surgical navigation links break. Expansion across departments should follow measured improvement in staging precision and treatment response monitoring with one accountable support route for technical failures."
- Anurag Sharma, Principal Consultant at Future Market Insights
Why is the Orthopedic Oncology Market growing?
Rising Diagnostic Imaging and Stage II demand across healthcare end users
- Orthopedic-oncology imaging demand follows cancer-center caseloads and staging-protocol upgrades rather than speculative equipment buying.
- Brazil leads growth at 6.9% CAGR as public health system cancer care expansion raises diagnostic procurement.
- Stage II holds 34.0% of cancer stage revenue, indicating where standardization is concentrating buyer spend.
Because staging accuracy drives clinical value, orthopedic-oncology imaging spend concentrates with vendors whose MRI, CT, and PET platforms integrate into surgical-navigation and tumor-board workflows.
How is the Orthopedic Oncology Market segmented?
The orthopedic oncology industry is segmented by diagnostic techniques, cancer stage, indication, end user, treatment type, and region.
The orthopedic oncology market is segmented by diagnostic techniques, cancer stage, indication, end user, treatment type, and region. By diagnostic techniques, the market covers diagnostic imaging and bone biopsy. By cancer stage, the market covers Stage I, Stage II, Stage III, and Stage IV. By indication, the market covers osteosarcoma, chondrosarcoma, Ewing sarcoma, and chordoma. By end user, the market covers hospitals, diagnostic centres, and specialty orthopedic clinics. By treatment type, the market covers surgical treatment, chemotherapy, and radiation therapy. Regions include North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
How does diagnostic imaging shape demand within the diagnostic techniques category?
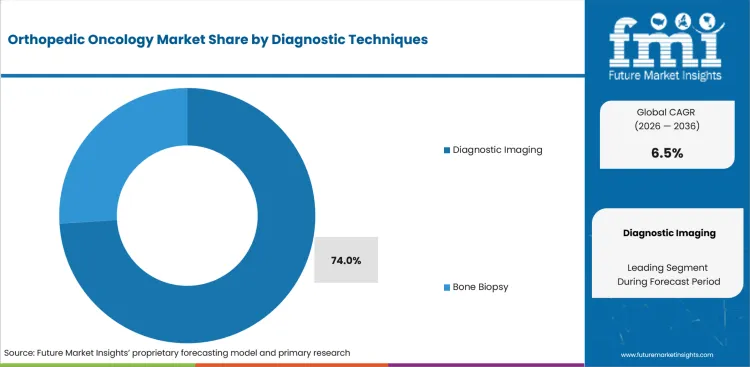
Diagnostic techniques selection determines tumor detection accuracy and treatment planning quality. Imaging resolution for bone and soft tissue directly affects staging decisions. The American College of Radiology confirmed updated musculoskeletal tumor imaging protocols in its 2025 practice guidelines.
- Diagnostic Imaging is expected to account for 74.0% of diagnostic techniques demand in 2026, driven by MRI, CT, and PET adoption for tumor margin assessment.
- Hospital oncology programs are expected to favor suppliers that integrate imaging with surgical navigation and biopsy planning.
What supports demand for Stage II within the cancer stage category?
Cancer staging determines treatment intensity and diagnostic resource allocation. Stage II represents localized high-grade tumors requiring aggressive surgical and chemotherapy intervention. National Cancer Institute data confirmed that early-stage bone cancer patients benefit from multi-modal imaging before surgical planning.
- Stage II is projected to hold 34.0% of cancer stage demand in 2026 because high-grade localized tumors require the most intensive imaging and surgical planning.
- Hospitals are likely to invest in staging-specific imaging protocols to improve limb-salvage surgical outcomes.
How do hospitals and treatment type shape procurement across end user and treatment categories?
Hospitals generate the majority of orthopedic oncology procurement due to surgical oncology caseloads and multi-disciplinary tumor board requirements.
- Hospitals are anticipated to represent 68.0% of end-user demand in 2026.
- Surgical Treatment is forecast to hold 52.0% of treatment type demand in 2026 as limb-salvage techniques expand beyond amputation in primary bone tumor management.
What are the drivers, restraints, and opportunities in the Orthopedic Oncology Market?
Near-term procurement is shaped by cancer incidence trends, imaging technology upgrades, and surgical oncology program expansion.
- Driver: Rising musculoskeletal cancer incidence is expected to push hospitals toward advanced diagnostic imaging procurement tied to tumor staging and treatment planning.
- Restraint: Adoption is likely to slow due to high capital costs for multi-modal imaging equipment and limited oncology imaging expertise in smaller hospital systems.
- Opportunity: Integration of AI-assisted tumor detection with existing imaging systems is expected to open supplier access if diagnostic accuracy improvements reduce surgical revision rates.
Rising bone tumor incidence is expected to increase imaging procurement across hospitals managing orthopedic oncology caseloads. WHO reported in 2025 that cancer continued to be a leading cause of mortality globally. That burden supports investment in imaging systems that improve tumor staging accuracy for surgical planning.
Capital cost barriers are expected to limit adoption if smaller hospital systems cannot justify multi-modal imaging investments for relatively low bone tumor volumes. National Comprehensive Cancer Network guidelines confirmed in 2025 that MRI remains the preferred modality for primary bone tumor evaluation.
AI-assisted diagnostic tools create a practical route around the restraint by improving tumor detection on existing imaging platforms. Siemens Healthineers reported in 2025 that its AI-powered imaging applications had received regulatory clearances across multiple markets, supporting oncology workflow improvements.
Which country CAGRs are profiled in the Orthopedic Oncology Market?
China 6.5%, Germany 6%, India 5.8%, UK 5.4%, USA 3.2% through 2036
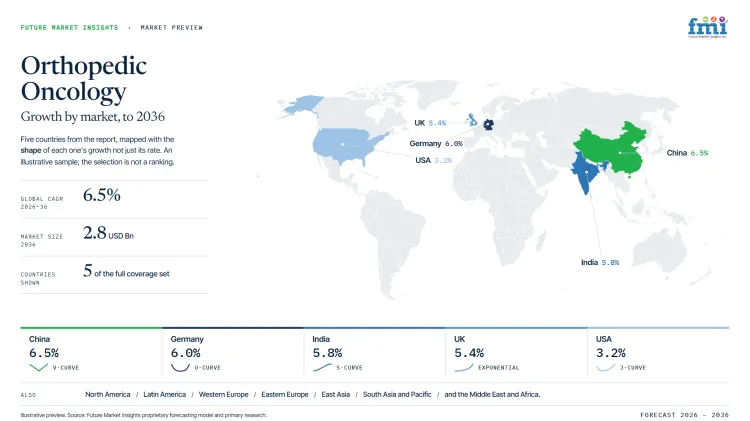
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 6.5% |
| Germany | 6% |
| India | 5.8% |
| UK | 5.4% |
| USA | 3.2% |
Source: FMI's proprietary forecasting model and primary research. 5 of the countries covered in the full report are shown here as a representative subset.
How do country-level CAGRs compare in the Orthopedic Oncology Market?
The country comparison spans 3.3 percentage points and reveals three distinct growth groups across the Orthopedic Oncology Market. China and Germany form the upper tier with only 0.5 percentage points separating them, while India and the United Kingdom create a closely aligned middle group with a 0.4-point difference. The United States stands apart with a 2.2-point gap from the United Kingdom, reflecting more mature oncology infrastructure and replacement-led imaging demand.
- China leads the comparison at a 6.5% CAGR through 2036, reflecting continued investment in national cancer-center programs, provincial hospital upgrades and broader access to advanced oncology imaging.
- Germany follows at a 6.0% CAGR, remaining only 0.5 percentage points below China as hospital modernization, cancer-center accreditation and advanced oncology-imaging requirements support market expansion.
- India records a 5.8% CAGR, placing it 0.2 percentage points below Germany. Expanding private oncology networks and rising cancer incidence are broadening access to staging and diagnostic imaging.
- The United Kingdom grows at a 5.4% CAGR, remaining 0.4 percentage points below India. Reimbursement gaps and uneven radiologist coverage can limit adoption outside major cancer centers, creating opportunities for suppliers offering tiered pricing, training and wider service coverage.
- The United States records a 3.2% CAGR, creating a 2.2-percentage-point gap from the United Kingdom. A large installed imaging base and value-based cancer-care contracts contribute to a more replacement-led pattern of oncology-imaging demand.
Comparable CAGRs can still produce different market conditions. Differences in cancer-center investment, hospital infrastructure, reimbursement structures, imaging access, radiologist availability and replacement cycles influence adoption patterns across countries. The full report provides country-level CAGR analysis across major regions and individual markets within the Orthopedic Oncology Market.
Country-wise Analysis
- Chinese hospitals procure orthopedic oncology through centralized purchasing programs that reward registered, competitively priced products. Value-based contracting and evidence requirements gate access to cancer-center volume. Suppliers protect renewals with GPO access, outcomes evidence, and installed-base service.
- German hospitals procure orthopedic oncology through engineering-led, specification-driven tenders. Demand draws on rising musculoskeletal cancer incidence. The Orthopedic Oncology Market in Germany is projected to record a 6% CAGR during the assessment period, supported by structured hospital procurement and a large installed equipment base. Volume-based procurement pressures pricing even as cancer caseloads expand. Suppliers need local registration, competitive tenders, and provincial service to convert cancer-center program demand.
- Indian providers buy orthopedic oncology across expanding private hospital chains and cost-sensitive public tenders. Sales in India are forecast to expand at a 5.8% CAGR by 2036, supported by private hospital chain expansion and tertiary care investment. Cancer-pathway evidence and framework listing gate diagnostic access. Suppliers need framework positions and health-economic evidence to convert NHS tender wins.
- UK providers procure orthopedic oncology through NHS frameworks and structured tender cycles. The market outlook in the United Kingdom is anticipated to advance at a 5.4% CAGR over the assessment period, supported by NHS procurement frameworks and structured tender demand. NHS procurement frameworks and cancer-pathway evidence gate diagnostic access. Suppliers need framework positions and health-economic evidence to convert NHS tender wins.
- US providers procure orthopedic oncology through GPO contracts against a large installed base on replacement cycles. Demand in the United States is forecast to rise at a 3.2% CAGR over the forecast period, supported by replacement cycles across a large installed base and GPO contracting. Accreditation-led procurement and budget discipline stretch oncology imaging evaluation timelines. Suppliers need documented staging performance, service contracts, and compliance depth to win.
Who are the notable companies in the Orthopedic Oncology Market?
GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Healthcare, and Hologic are the notable companies shaping this market.
The field concentrates around oncology-imaging companies that pair diagnostic breadth with cancer-center access and multimodal workflow support. Global diagnostic imaging companies compete across MRI, CT, PET imaging, Advanced oncology imaging and Diagnostic imaging systems throughout established accounts. Advanced imaging and oncology diagnostics emphasize Imaging and ultrasound, while specialty imaging and screening companies serve regional demand through Specialty imaging. A workable entry is a specialty imaging niche, such as ultrasound-guided biopsy or MRI workflow, or a regional service model. Growth depends on regulatory clearance, radiologist training, and service coverage across each launch market. Breadth pays off through clinical teams that keep staging platforms integrated with tumor-board and surgical-navigation workflows.
- GE HealthCare and Siemens Healthineers combine MRI, CT, PET imaging and Advanced oncology imaging across multiple national markets. Koninklijke Philips N.V. adds Diagnostic imaging systems through established account relationships. Their edge comes from multimodal staging platforms and cancer-center workflow integration.
- Fujifilm Healthcare follows focused routes across Imaging and ultrasound. Their commercial edge comes from biopsy and ultrasound-guided niches with strong radiologist support rather than one imaging suite.
- Hologic provides regional coverage through skeletal-health imaging, including bone densitometry and orthopedic mini C-arm systems. These firms compete on focused imaging strengths, though reach trails the global oncology majors.
Competitive Benchmarking: Orthopedic Oncology Market
| Company | Portfolio Relevance | Oncology Imaging Focus | Account Access | Service Reach |
|---|---|---|---|---|
| GE HealthCare | High | MRI, CT, PET imaging | Strong | Global |
| Siemens Healthineers | High | Advanced oncology imaging | Strong | Global |
| Koninklijke Philips N.V. | High | Diagnostic imaging systems | Strong | Global |
| Fujifilm Healthcare | Medium | Imaging and ultrasound | Moderate | Global |
| Hologic | Medium | Specialty imaging | Moderate | Regional |
Source: Future Market Insights competitive analysis, 2026. Ratings reflect relative portfolio relevance, workflow or project fit, service capability, and geographic reach.
Key Developments in the Orthopedic Oncology Market
- In January 2025, Siemens Healthineers expanded its AI-powered oncology imaging portfolio with updated tumor detection algorithms for musculoskeletal applications. The enhancement supports faster MRI-based staging workflows in hospital oncology departments.
- In March 2025, GE HealthCare confirmed deployment of its latest PET-CT imaging platform across cancer specialty centers in North America and Europe. The system supports improved metabolic assessment for bone tumor treatment response monitoring.
Key Players in the Orthopedic Oncology Market
Global diagnostic imaging companies
- GE HealthCare
- Siemens Healthineers
- Koninklijke Philips N.V.
Advanced imaging and oncology diagnostics
- Fujifilm Healthcare
Specialty imaging and screening companies
- Hologic
Orthopedic Oncology Market: Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Diagnostic techniques, cancer stage, indication, end user, treatment type, and region. |
| Quantitative Units | Revenue in USD billions and CAGR in %. |
| Market Definition | Orthopedic oncology includes diagnostic imaging, biopsy, and treatment systems used for detection, staging, and management of primary bone tumors including osteosarcoma, chondrosarcoma, Ewing sarcoma, and chordoma across hospital and specialty oncology settings. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa. |
| Countries Covered | United States, China, India, Germany, United Kingdom, Japan, and Brazil. |
| Key Companies Profiled | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Healthcare, Hologic. |
| Forecast Period | 2026 to 2036. |
| Approach | FMI used primary interviews, source validation, company authentication, and proprietary demand modeling to estimate market size, segment shares, country CAGRs, and competitive positioning. |
Source: Future Market Insights, analysis driven by proprietary forecasting models and primary research
Orthopedic Oncology Market: Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI interviewed orthopedic oncology suppliers, institutional and retail buyers, distributors, and procurement leads. Inputs tested adoption triggers, product preferences, and replacement cycle patterns across segments and countries. |
| Desk Research | Desk research used government releases, regulator updates, standards-body references, company filings, and official product pages. Evidence was restricted to public sources supporting adoption or company capability claims. |
| Market Sizing and Forecasting | The forecast model linked 2026 revenue anchors to demand drivers, distribution reach, penetration rates, and country-specific conditions. Segment shares were cross-checked against product, application, and end-user procurement patterns. |
| Data Validation | Data validation reconciled every external statistic against its source title, date, and reported figure. Forecast values were checked against the ten-year CAGR formula and reviewed for section-level consistency. |
Source: Future Market Insights (FMI) analysis, based on proprietary forecasting model and primary research
Market Segmentation Analysis
Orthopedic Oncology Market Segmented by Diagnostic Techniques:
- Diagnostic Imaging
- X Ray Imaging
- Primary Bone Tumor Detection
- Skeletal Structure Assessment
- MRI Imaging
- Soft Tissue Evaluation
- Tumor Margin Identification
- CT Imaging
- Detailed Bone Visualization
- Metastatic Assessment
- PET Imaging
- Cancer Activity Monitoring
- Treatment Response Evaluation
- Ultrasound Imaging
- Guided Diagnostic Procedures
- Soft Tissue Examination
- X Ray Imaging
- Bone Biopsy
- Biopsy Needles
- Minimally Invasive Sampling
- Accurate Tissue Diagnosis
- Biopsy Trays And Kits
- Sterile Sampling Procedures
- Comprehensive Diagnostic Support
- Biopsy Needles
Orthopedic Oncology Market Segmented by Cancer Stage:
- Stage II
- High Grade Localized Tumors
- Aggressive Tumor Assessment
- Combined Therapy Planning
- Intermediate Progression Cases
- Imaging Guided Evaluation
- Targeted Surgical Procedures
- High Grade Localized Tumors
- Stage I
- Localized Bone Tumors
- Early Detection Programs
- Curative Treatment Planning
- Low Grade Malignancies
- Minimal Tissue Involvement
- Surgical Management
- Localized Bone Tumors
- Stage III
- Regional Tumor Spread
- Advanced Imaging Monitoring
- Multimodal Therapy Support
- Multiple Bone Lesions
- Complex Surgical Oncology
- Adjunctive Chemotherapy
- Regional Tumor Spread
- Stage IV
- Metastatic Bone Cancer
- Systemic Disease Management
- Palliative Oncology Care
- Advanced Metastatic Conditions
- Comprehensive Imaging Follow Up
- Targeted Treatment Monitoring
- Metastatic Bone Cancer
Orthopedic Oncology Market Segmented by Indication:
- Osteosarcoma
- Conventional Osteosarcoma
- Long Bone Involvement
- Adolescent Patient Cases
- High Grade Osteosarcoma
- Aggressive Tumor Progression
- Chemotherapy Integration
- Conventional Osteosarcoma
- Chondrosarcoma
- Conventional Chondrosarcoma
- Cartilage Derived Tumors
- Surgical Resection Procedures
- Dedifferentiated Chondrosarcoma
- Advanced Malignant Progression
- Complex Oncology Management
- Conventional Chondrosarcoma
- Ewing Sarcoma
- Pediatric Ewing Sarcoma
- Bone And Soft Tissue Involvement
- Multimodal Treatment Approaches
- Extra Skeletal Ewing Sarcoma
- Rare Tumor Management
- Advanced Imaging Assessment
- Pediatric Ewing Sarcoma
- Chordoma
- Skull Base Chordoma
- Neurosurgical Oncology Support
- Advanced MRI Evaluation
- Spinal Chordoma
- Complex Spine Surgery
- Long Term Monitoring
- Skull Base Chordoma
Orthopedic Oncology Market Segmented by End User:
- Hospitals
- Multispecialty Hospitals
- Comprehensive Cancer Treatment
- Advanced Surgical Oncology
- Cancer Specialty Hospitals
- Orthopedic Oncology Departments
- Integrated Imaging Facilities
- Multispecialty Hospitals
- Diagnostic Centres
- Advanced Imaging Centers
- MRI And PET Diagnostics
- Early Tumor Detection
- Pathology Diagnostic Labs
- Biopsy Analysis Services
- Cancer Screening Support
- Advanced Imaging Centers
- Specialty Orthopedic Clinics
- Bone Tumor Clinics
- Specialized Orthopedic Oncology
- Long Term Patient Monitoring
- Rehabilitation And Follow Up Centers
- Post Surgical Care
- Functional Recovery Programs
- Bone Tumor Clinics
Orthopedic Oncology Market Segmented by Treatment Type:
- Surgical Treatment
- Limb Salvage Surgery
- Tumor Resection Procedures
- Functional Bone Preservation
- Reconstructive Orthopedic Surgery
- Bone Grafting Applications
- Implant Based Reconstruction
- Limb Salvage Surgery
- Chemotherapy
- Neoadjuvant Chemotherapy
- Pre Surgical Tumor Reduction
- Improved Surgical Outcomes
- Adjuvant Chemotherapy
- Post Surgical Cancer Control
- Metastasis Prevention
- Neoadjuvant Chemotherapy
- Radiation Therapy
- External Beam Radiation
- Localized Tumor Management
- Pain Reduction Therapy
- Advanced Targeted Radiation
- Precision Oncology Treatment
- Reduced Tissue Damage
- External Beam Radiation
Orthopedic Oncology Market by Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- 1. World Health Organization. (2025). Global Cancer Statistics and Incidence Trends.
- 2. National Cancer Institute. (2025). Bone Cancer Treatment Guidelines and Imaging Protocols.
- 3. American College of Radiology. (2025). Musculoskeletal Tumor Imaging Practice Parameters.
- 4. National Comprehensive Cancer Network. (2025). Clinical Practice Guidelines: Bone Cancer.
- 5. Siemens Healthineers. (2025). AI-Powered Oncology Imaging Portfolio Update.
- 6. Instituto Nacional de Cancer Brazil. (2025). National Oncology Center Investment Program.
- 7.European Medicines Agency. (2025). EU Medical Device Regulation Compliance Framework.
- 8.Pharmaceutical and Medical Devices Agency Japan. (2025). Imaging Device Approval Guidance.
- 9.National Health Commission of China. (2025). Cancer Diagnosis and Treatment Standardization.
This bibliography is provided for reader reference and uses primary government sources plus standards-body sources. Clinical body and company sources are included.
This Report Answers
- What is the estimated 2026 value of the orthopedic oncology market?
- What market value is projected for orthopedic oncology by 2036?
- What CAGR is forecast for orthopedic oncology from 2026 to 2036?
- Which diagnostic technique is expected to account for a notable 2026 share?
- Which countries are profiled for CAGR comparison?
- Which companies are notable in the competitive landscape?
Frequently Asked Questions
How big is the Orthopedic Oncology Market in 2026?
The Orthopedic Oncology Market is valued at USD 1.5 billion in 2026 and is forecast to reach USD 2.8 billion by 2036, expanding at a 6.5% CAGR. The Orthopedic Oncology Market grew from USD 1.4 billion in 2025, with Diagnostic Imaging holding 74.0% of diagnostic techniques demand in 2026.
What is the CAGR of the Orthopedic Oncology Market from 2026 to 2036?
The Orthopedic Oncology Market is projected to grow at a CAGR of 6.5% between 2026 and 2036, supported by increased adoption of advanced MRI and PET imaging for tumor margin assessment and treatment response monitoring. Diagnostic Imaging holds 74.0% of Orthopedic Oncology Market diagnostic techniques demand in 2026, while Stage II leads cancer stage with 34.0% in 2026.
Which diagnostic techniques lead the Orthopedic Oncology Market?
Diagnostic Imaging accounts for 74.0% of the Orthopedic Oncology Market by diagnostic techniques in 2026, driven by MRI, CT, and PET adoption for tumor margin assessment. The Orthopedic Oncology Market is valued at USD 1.5 billion in 2026 and grows at a 6.5% CAGR through 2036, while Stage II leads cancer stage with 34.0% in 2026.
How much will the Orthopedic Oncology Market add between 2026 and 2036?
The Orthopedic Oncology Market is set to add USD 1.3 billion between 2026 and 2036, growing from USD 1.5 billion to USD 2.8 billion at a 6.5% CAGR. Stage II leads cancer stage with 34.0% of Orthopedic Oncology Market revenue in 2026, anchoring that incremental demand.
Who are the leading companies in the Orthopedic Oncology Market?
The Orthopedic Oncology Market profiles 5 key companies in 2026, led by GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Healthcare, and Hologic. These suppliers compete across diagnostic techniques, where Diagnostic Imaging holds 74.0% of Orthopedic Oncology Market demand in 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Diagnostic Techniques, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Diagnostic Techniques, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Diagnostic Techniques, 2026 to 2036
- Diagnostic Imaging
- X Ray Imaging
- MRI Imaging
- CT Imaging
- PET Imaging
- Bone Biopsy
- Biopsy Needles
- Biopsy Trays And Kits
- Diagnostic Imaging
- Y-o-Y Growth Trend Analysis By Diagnostic Techniques, 2021 to 2025
- Absolute $ Opportunity Analysis By Diagnostic Techniques, 2026 to 2036
- Global Market Analysis and Forecast, By Cancer Stage, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Cancer Stage, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Cancer Stage, 2026 to 2036
- Stage II
- High Grade Localized Tumors
- Intermediate Progression Cases
- Stage I
- Localized Bone Tumors
- Low Grade Malignancies
- Stage III
- Regional Tumor Spread
- Multiple Bone Lesions
- Stage IV
- Metastatic Bone Cancer
- Advanced Metastatic Conditions
- Stage II
- Y-o-Y Growth Trend Analysis By Cancer Stage, 2021 to 2025
- Absolute $ Opportunity Analysis By Cancer Stage, 2026 to 2036
- Global Market Analysis and Forecast, By Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Indication, 2026 to 2036
- Osteosarcoma
- Conventional Osteosarcoma
- High Grade Osteosarcoma
- Chondrosarcoma
- Conventional Chondrosarcoma
- Dedifferentiated Chondrosarcoma
- Ewing Sarcoma
- Pediatric Ewing Sarcoma
- Extra Skeletal Ewing Sarcoma
- Chordoma
- Skull Base Chordoma
- Spinal Chordoma
- Osteosarcoma
- Y-o-Y Growth Trend Analysis By Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Indication, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Hospitals
- Multispecialty Hospitals
- Cancer Specialty Hospitals
- Diagnostic Centres
- Advanced Imaging Centers
- Pathology Diagnostic Labs
- Specialty Orthopedic Clinics
- Bone Tumor Clinics
- Rehabilitation And Follow Up Centers
- Hospitals
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Treatment Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Treatment Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Treatment Type, 2026 to 2036
- Surgical Treatment
- Limb Salvage Surgery
- Reconstructive Orthopedic Surgery
- Chemotherapy
- Neoadjuvant Chemotherapy
- Adjuvant Chemotherapy
- Radiation Therapy
- External Beam Radiation
- Advanced Targeted Radiation
- Surgical Treatment
- Y-o-Y Growth Trend Analysis By Treatment Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Treatment Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Diagnostic Techniques
- By Cancer Stage
- By Indication
- By End User
- By Treatment Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- GE Healthcare
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Siemens Healthineers
- Koninklijke Philips N.V.
- Hitachi Medical Systems
- Hologic
- Other Companies (combined)
- GE Healthcare
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


