

- Market Size (2026)
- USD 784.5 Mn
- Forecast (2036)
- USD 1365.7 Mn
- CAGR (2026 to 2036)
- 5.7%
How big is Shower Steamers Market in 2026?
USD 784.5 Million in 2026 and USD 1,365.7 Million by 2036 at a 5.7% CAGR.
Spending on shower steamers is estimated at USD 742.2 Million in 2025 and USD 784.5 Million in 2026, as per FMI. Revenue is projected to reach USD 1,365.7 Million by 2036 at a 5.7% CAGR, opening USD 581.2 Million of new sales for fragrance and bath-care producers. Soakmate announced a natural shower-steamer range in May 2025, presenting the scented tablet as an addition to an ordinary shower routine [1].
The format asks for little change in behaviour: the buyer needs a shower and a reason to choose the scent again. That makes trial straightforward, but repeat sales depend on consistent fragrance release and packaging that keeps moisture out before use. Smaller packs can help shoppers find a preferred scent, while gifts introduce the format to a new household. Suppliers will need to turn those first trials into everyday use to sustain growth.
Analysts at FMI see licensed gifting and reliable replenishment as complementary sources of volume. Lush’s 2025 How to Train Your Dragon collaboration and its 2026 Super Mario Galaxy Movie collection put shower products inside recognizable entertainment ranges [2] [3]. Those launches can create an initial purchase occasion. Brands that keep core scents available and explain product placement clearly have a better chance of retaining the buyer after the limited edition sells through.
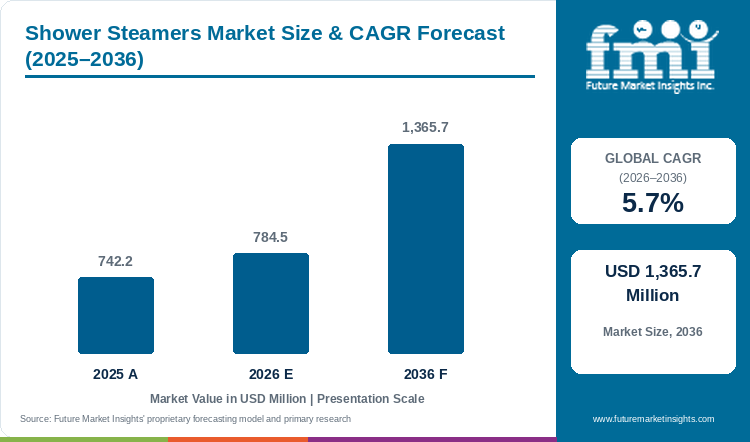
Key Takeaways
- Shower steamers fit into a routine people already have. Demand depends more on repeat use than on persuading buyers to purchase another device.
- Everyday essentials led Product Type with a 34.0% share in 2026 because they are easy to understand and easy to replace.
- Conventional led Nature with a 52.0% share in 2026 because brands have more freedom to balance fragrance, foaming and shelf life across different price points.
- Daily routine led Use Occasion with a 36.0% share in 2026 because the product can be used during an ordinary morning or evening shower.
- A steamer that loses fragrance in storage or performs unevenly is less likely to earn a repeat order. Ingredient disclosure and careful claims become more important when a brand moves toward therapeutic language.
- Profiled companies are Hyperice, Vitruvi, Church & Dwight, Vital Proteins, Lush, Plunge, Therabody, Renpho, HigherDOSE, and The Body Shop. The group spans direct shower formats, scent-led brands and broader at-home wellness platforms.
Analyst Perspective
“Consumers are more likely to keep buying shower steamers when the scent performs the same way from one pack to the next. Clear directions and sensible claims also matter. The strongest products fit naturally into an existing shower routine and are easy to reorder.”
- Rahul Pandita, Principal Consultant, FMI
How is the shower steamers market segmented?
Product Type; Nature; Use Occasion; Price Tier; Sales Channel.
Product Type comprises Everyday essentials, Targeted therapy formats, Premium & smart formats, and Gift & travel sets. Nature covers Conventional, Natural & organic, Vegan, and Clinically positioned products. Use Occasion includes Daily routine, Recovery & post-workout, Sleep & wind-down, and Gifting. Price Tier is divided into Mid-range, Mass, and Premium. Sales Channel includes E-commerce & DTC, Specialty wellness retail, Pharmacies, Supermarkets, and Spas & studios.
Why do Everyday essentials anchor the Product Type category?
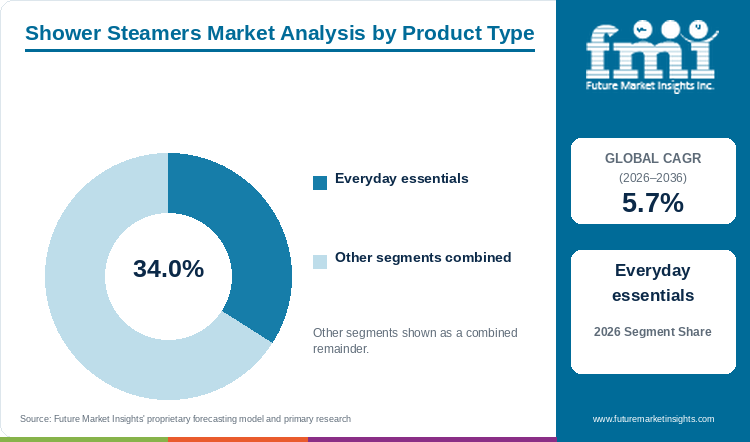
Everyday essentials held 34.0% of Product Type demand in 2026.
Everyday essentials lead because they are easy to add to a normal shower. Brands can sell them as single-use or multi-use products and adjust scent strength or cost per shower without making the format complicated. Targeted therapy formats and gift sets have a place, but they depend more on a specific occasion or benefit. Everyday products are easier to reorder because the reason to use them comes up more often.
- Everyday essentials held 34.0% of Product Type demand in 2026. They fit the widest range of routine shower occasions and require little change in consumer behavior.
- Soakmate’s May 2025 shower-steamer announcement places a scented tablet inside the ordinary shower routine [1]. The format can add a new purchase without requiring a separate appliance or bath.
What keeps Conventional formats central to Nature?
Conventional held 52.0% of Nature demand in 2026.
Conventional formulations give brands the most room to balance fragrance, foaming and shelf life. Natural and organic or vegan products can appeal to buyers who care about ingredients, while clinically positioned products need more care around claims. Conventional products remain easier to build across mass and mid-range price points because the formulation is not tied to a narrower certification or lifestyle promise.
- Conventional held 52.0% of Nature demand in 2026. Brands can use a wider range of formulations across different scents and price points.
- The May 2026 consolidated EU Cosmetics Regulation sets current composition and labeling requirements [4]. Where a shower product is classified as a cosmetic, its formulation and packaging need to meet those requirements.
Why does Daily routine lead Use Occasion demand?
Daily routine held 36.0% of Use Occasion demand in 2026.
Daily routine leads because shower steamers can be used during a normal shower. There is no need for a bath or a separate recovery session. Recovery, sleep and gifting are more specific occasions. Routine use therefore creates more chances for a consumer to finish a pack and buy another one.
- Daily routine held 36.0% of Use Occasion demand in 2026 because the product fits a habit that already happens frequently.
- Lush’s May 2025 How to Train Your Dragon collaboration put shower products within a themed bath-and-body collection [2]. A recognizable occasion can help introduce the format while core scents support subsequent purchases.
What supports Mid-range pricing across Price Tier?
Mid-range held 45.0% of Price Tier demand in 2026.
Mid-range products sit between cheap single units and higher-priced gift or premium formats. Buyers can pay a little more for scent strength, longer use or better packaging without treating the purchase as a luxury item. Mass products compete more heavily on price. Premium products need a clearer reason for the step up. That makes mid-range products easier to sell across both direct and specialty channels.
- Mid-range held 45.0% of Price Tier demand in 2026. The price is high enough to support better scent or packaging while still working for repeat purchase and gifting.
- For the 2025 holiday season, Alni Body Care introduced a six-steamer sampler gift box at US$30. The example shows how assortment and presentation can raise the value of the purchase without turning it into a high-priced wellness product. [5]
Why does E-commerce & DTC lead Sales Channel demand?
E-commerce & DTC held 29.0% of Sales Channel demand in 2026.
E-commerce and DTC suit a small product that is easy to ship and easy to explain online. Brands can show fragrance choices, bundle sizes and use instructions on the same page where the purchase happens. They can also change scents more quickly than a large retailer can reset a shelf. Specialty wellness stores still help with discovery, while pharmacies and supermarkets can add reach. Spas and studios can introduce the product but are less suited to frequent reordering.
- E-commerce & DTC held 29.0% of Sales Channel demand in 2026 because discovery, product information and repeat ordering can happen in one place.
- In August 2026, the U.S. Census Bureau reported that e-commerce accounted for 17.1% of second-quarter retail sales. This gives low-priced wellness and personal-care products a well-established online buying channel. [6]
What are the drivers, restraints and opportunities in the shower steamers market?
Regular shower use and online shopping support demand. Growth can slow when scent performance is inconsistent or claims go too far. Better formats and giftable products give brands room to charge more without changing the basic product.
- Driver: Consumers can add fragrance to a shower they already take without buying another device or setting aside time for a bath.
- Restraint: Therapeutic claims, fragrance sensitivity and poor performance in humid conditions can make repeat purchase harder.
- Opportunity: Multi-use tablets, products made for specific times of day and giftable collections can add value beyond a basic scented tablet.
Convenience is the main reason the format works. A shower steamer does not require new equipment or any change to the bathroom. It adds scent to something the buyer already does. Online sales make the product easier to explain because brands can show scent collections, pack sizes and use directions before checkout. The U.S. Census Bureau reported US retail e-commerce sales of US$340.2 billion in the second quarter of 2026. For shower-steamer brands, that makes it easier to test new assortments and earn repeat orders when a fragrance becomes part of a routine. [6]
Claims and product information can limit distribution when they are harder to substantiate than the scent experience itself. OPSS’s July 2025 guidance requires safety assessment and clear information for cosmetic products [7], while the May 2026 consolidated EU rules govern cosmetic composition and labeling [4]. Suppliers must establish the classification of their own product rather than assume every shower tablet follows the same route. Clear directions and restrained benefit claims can reduce retailer queries and disappointed purchases.
There is also room to make each shower feel more valuable without making the product harder to use. Multi-use tablets can last longer. Morning, wind-down or post-workout versions can give buyers a clearer reason to choose one scent over another. Giftable collaborations can bring the format into seasonal purchases. In March 2026, Lush announced a Super Mario Galaxy bath, body, shower and scent collection that included collectible shower gummies. The product is adjacent rather than a shower steamer, but it shows how a solid shower format can carry novelty and gifting. Shower-steamer brands can use the same idea with stable fragrance and careful claims. [3]
Which country CAGRs are profiled in the shower steamers market?
The profiled country CAGRs cover 2026 to 2036.
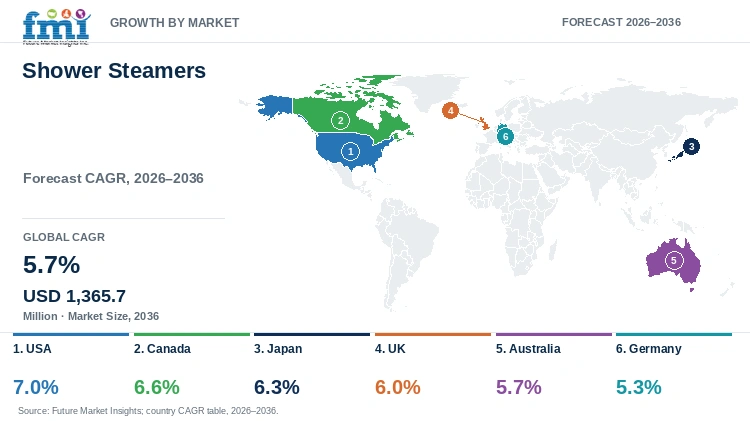
| Country | CAGR |
|---|---|
| USA | 7.0% |
| Canada | 6.6% |
| Japan | 6.3% |
| UK | 6.0% |
| Australia | 5.7% |
| Germany | 5.3% |
How do country-level CAGRs compare in the shower steamers market?
The six profiled countries are separated by 1.7 percentage points. USA and Canada sit at the top of the group, followed by Japan and the UK. Australia is close to the overall market pace, while Germany has the slowest rate in the set. These figures show growth speed, not the size of each country market.
- USA: The Census Bureau’s August 2026 e-commerce release shows a substantial digital retail channel for brands testing scents and bundles [6].
- Canada: Growth in health and personal care retail supports the category, and cross-border DTC can make it easier to test smaller scent ranges. [8]
- Japan: The Statistics Bureau recorded online shopping by 55.6% of households with two or more people in July 2026 [9].
- UK: A high share of online retail supports product discovery, while Responsible Person and labeling requirements make compliant market entry important. [10] [7]
- Australia: Online retail gives brands access to buyers across a large geography, while compact packs and manageable shipping costs remain important. [11]
- Germany: Online purchasing is well established; products classified as cosmetics also need accurate composition and labeling under current EU rules [12] [4].
Country growth also depends on how people buy the product and what local rules require. The profiles below explain those differences for each of the six countries.
Country-wise Analysis
- The USA leads the profiled shower-steamer growth rates at a 7.0% CAGR through 2036. Soakmate announced a natural shower-steamer range in May 2025, demonstrating continued supplier interest in adding fragrance to ordinary shower routines [1]. Direct selling lets brands test scents and pack sizes, but repeat demand depends on consistent performance. Moisture-resistant packaging and clear placement instructions can help turn a gift or trial pack into replenishment.
- Canada’s health-and-personal-care channel gives shower steamers a route alongside other routine purchases, supporting a 6.6% CAGR through 2036. Statistics Canada recorded 6.7% growth in that retail category in 2025 [8]. Brands can use specialty retail for scent discovery and online stores for repeat packs. Local fulfillment and an assortment that keeps order values practical will matter in serving customers across a dispersed market.
- Japan’s mix of online and physical shopping calls for more than a marketplace-only launch, with a 6.3% CAGR forecast through 2036. The Statistics Bureau recorded online shopping by 55.6% of households with two or more people in July 2026 [9]. Shower-steamer brands need clear scent descriptions and compact packs in both channels. Store discovery can introduce the format, while online replenishment makes a preferred scent easier to buy again.
- The UK’s established internet retail supports a 6.0% CAGR through 2036, with 27.4% of Great Britain’s retail sales made online in 2025 [13]. For scent-led products, that reach works best when the buyer understands fragrance strength, pack size and placement. OPSS’s July 2025 cosmetics guidance also makes product information relevant where the formulation is sold as a cosmetic [7]. Suppliers should settle classification and labeling before widening distribution.
- Australia’s online channel helps a compact product reach buyers over long distances, supporting a 5.7% CAGR through 2036. ABS recorded seasonally adjusted online retail sales of A$4.70 billion in June 2025 [11]. Shower-steamer suppliers need pack economics that can absorb delivery costs. Multipacks and gifts can raise order value, while clear instructions help consumers understand the format without an in-store demonstration.
- Germany’s digitally active buyers can compare specialist fragrance products easily, with a 5.3% CAGR forecast through 2036. Destatis recorded recent online purchases by 70% of people aged 16 to 74 in 2025 [12]. Suppliers should make scent, ingredients and storage needs straightforward to assess. Consistent tablets and dependable moisture protection can support repeat orders more effectively than broad wellness promises.
Who are the notable companies in the shower steamers market?
Hyperice, Vitruvi, Church & Dwight, Vital Proteins, Lush, Plunge, Therabody, Renpho, HigherDOSE, and The Body Shop are the notable companies profiled in this market.
The profiled companies span direct shower formats, scent brands and broader at-home wellness platforms. Lush sells shower bombs [14], Vitruvi offers a current scent catalogue [15], and The Body Shop sells bath-and-shower products [16]. Hyperice, Plunge, Therabody, RENPHO and HigherDOSE compete for adjacent recovery and wellness spending. Church & Dwight and Vital Proteins bring broader consumer-health capabilities. Those adjacent offers are kept outside direct shower-steamer revenue.
- Scent and bath/shower participants include Lush, Vitruvi and The Body Shop. Lush offers shower bombs [14], Vitruvi contributes an adjacent scent portfolio [15], and The Body Shop sells across bath and shower categories [16].
- At-home recovery and wellness ecosystems: Hyperice, Plunge, Therabody, Renpho, and HigherDOSE. These companies compete for consumer wellness spending through recovery devices and at-home wellness products. [17] [18] [19] [20] [21]
- Broad consumer health platforms: Church & Dwight and Vital Proteins. Both operate established consumer-health or personal-care businesses outside the core shower-steamer format. [22] [23]
Competitive Benchmarking: Shower Steamers Market
| Company | Direct Steamer Format | Scent-Ritual Depth | Wellness Channel Fit | Geographic Reach |
|---|---|---|---|---|
| Hyperice | Low | Low | High | Consumers in over 60 countries |
| Vitruvi | Medium | High | High | United States and Canada DTC shipping |
| Church & Dwight | Low | Low | Medium | Subsidiaries in several profiled countries plus distributor reach in 130+ additional countries |
| Vital Proteins | Low | Low | Medium | Not stated |
| Lush | High | High | High | Over 50 countries with 850+ shops and 38 websites |
| Plunge | Low | Low | High | California production with worldwide brand positioning |
| Therabody | Low | Low | High | Products available in over 60 countries |
| Renpho | Low | Low | High | Support coverage across North America, Europe, Oceania and several Asian markets |
| HigherDOSE | Low | Low | High | United Kingdom storefront |
| The Body Shop | Low | High | High | United Kingdom and United States retail sites |
Scoring basis: Direct Steamer Format reflects current shower-steamer or shower-bomb activity. Scent-Ritual Depth reflects the breadth of fragrance or aromatherapy activity. Wellness Channel Fit reflects access to consumer self-care or wellness channels. High indicates broader presence, Medium indicates narrower presence and Low indicates limited presence. These ratings do not indicate product quality or market share.
Key Developments in the Shower Steamers Market
- In May 2025, Soakmate launched an e-commerce brand around six aromatherapy shower-steamer blends made with essential oils. It positioned the products as an affordable at-home spa option and sold reusable tablets in ten-count packs. The launch shows how a small DTC brand can compete through scent choice, simple instructions and pack format without selling higher-priced wellness equipment. [1]
- In May 2025, Lush and Universal announced the How to Train Your Dragon collaboration [2]. The bath-and-body collection demonstrates how entertainment licensing can create a purchase occasion for shower products. The commercial opportunity continues after the launch when a first-time buyer finds a core scent worth buying again.
- In March 2026, Lush announced a Super Mario Galaxy collection that included collectible shower gummies [3]. These adjacent shower products show how licensed characters can create a gifting occasion. Shower-steamer suppliers can develop seasonal scent and pack offers while keeping the core product easy to replenish.
Key Players in the Shower Steamers Market
Direct Scent and Bath/Shower Adjacency
- Lush
- Vitruvi
- The Body Shop
At-Home Recovery and Wellness Ecosystems
- Hyperice
- Plunge
- Therabody
- Renpho
- HigherDOSE
Broad Consumer Health Platforms
- Church & Dwight
- Vital Proteins
Shower Steamers Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Nature; Use Occasion; Price Tier; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Revenue includes shower steamers and shower-bomb formats sold within the stated segmentation. Bath bombs, shower gels, room fragrance, recovery hardware, supplements, services and other adjacent substitutes are excluded. For mixed gift sets, only the attributable shower-steamer component is in scope when it can be separated. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Canada; Germany; Japan; Australia |
| Key Companies Profiled | Hyperice; Vitruvi; Church & Dwight; Vital Proteins; Lush; Plunge; Therabody; Renpho; HigherDOSE; The Body Shop |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Shower Steamers Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments and findings from primary interviews. Validation also tested whether products, services, applications and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Shower Steamers Market by Segments
Shower Steamers Market segmented by Product Type:
- Everyday essentials
- Targeted therapy formats
- Premium & smart formats
- Gift & travel sets
Shower Steamers Market segmented by Nature:
- Conventional
- Natural & organic
- Vegan
- Clinically positioned
Shower Steamers Market segmented by Use Occasion:
- Daily routine
- Recovery & post-workout
- Sleep & wind-down
- Gifting
Shower Steamers Market segmented by Price Tier:
- Mid-range
- Mass
- Premium
Shower Steamers Market segmented by Sales Channel:
- E-commerce & DTC
- Specialty wellness retail
- Pharmacies
- Supermarkets
- Spas & studios
Shower Steamers Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Soakmate (2025, May 29). Soakmate Introduces Natural Shower Steamers to Enhance Daily Self-Care Routines.
- [2] Universal Products & Experiences (2025, May 29). Turn Flight Mode On and Unwind with the How to Train Your Dragon x Lush Collaboration.
- [3] Universal Products & Experiences (2026, March 6). Lush To Launch An Out-Of-This-World Collection Celebrating Nintendo And Illumination’s The Super Mario Galaxy Movie.
- [4] European Union (2026, May 18 consolidated version). Cosmetics Regulation: current composition and labeling provisions.
- [5] Alni Body Care (n.d.). 6-Pack Flight of Shower Steamers - Sampler Holiday Gift Box. Current page, accessed 6 October 2026.
- [6] U.S. Census Bureau (2026, August 18). Quarterly Retail E-Commerce Sales.
- [7] Office for Product Safety and Standards (2025, July 10). Consumer products: cosmetics.
- [8] Statistics Canada (2026, February 20). Retail trade, December 2025.
- [9] Statistics Bureau of Japan (2026, September 4). Survey of Household Economy: July 2026 online shopping results.
- [10] Office for National Statistics (2026, August 21). Retail sales, Great Britain: July 2026.
- [11] Australian Bureau of Statistics (2025, July 31). Retail Trade, Australia, June 2025.
- [12] German Federal Statistical Office (2025, November 27). Internet users and online shoppers.
- [13] Office for National Statistics (2026, August 21). Internet sales as a percentage of total retail sales, series J4MC: 2025 annual figure.
- [14] Lush (n.d.). Shower Bombs | Steamer Bombs | LUSH. Current page, accessed 6 October 2026.
- [15] Vitruvi (n.d.). All Scents. Current product catalogue, accessed 6 October 2026.
- [16] The Body Shop (n.d.). Bath and Shower Products. Current page, accessed 6 October 2026.
- [17] Hyperice (n.d.). About us. Current page, accessed 6 October 2026.
- [18] Plunge (n.d.). About Plunge. Current page, accessed 6 October 2026.
- [19] Therabody (2025, November 6). Therabody Surpasses 6.5 Million Theragun Devices Sold.
- [20] RENPHO (n.d.). Contact Us. Current page, accessed 6 October 2026.
- [21] HigherDOSE (n.d.). About HigherDOSE. Current page, accessed 6 October 2026.
- [22] Church & Dwight (n.d.). International Personal Care and Household Cleaning Products. Current page, accessed 6 October 2026.
- [23] Vital Proteins (n.d.). Who We Are and How We Started: The Vital Proteins Story. Current page, accessed 6 October 2026.
- [24] Therabody (2025, August 5). Therabody Brings Science-Backed Wellness to Ulta Beauty.
- [25] RENPHO (2025, October 20). RENPHO Redefines Health Monitoring with MorphoScan Nova.
- [26] Lush (n.d.). Not Sleepy | Shower Bomb | LUSH. Current page, accessed 6 October 2026.
- [27] HigherDOSE (n.d.). All Wellness Products. Current page, accessed 6 October 2026.
- [28] Vitruvi (n.d.). Frequently Asked Questions. Current page, accessed 6 October 2026.
"This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations."
This Report Answers
- What is the Shower Steamers Market size in 2026 and what is forecast for 2036?
- Which industry pressures are supporting demand for shower steamers?
- Why does Everyday essentials hold the leading Product Type position?
- Why does Conventional hold the leading Nature position?
- How do profiled country growth rates differ from 2026 to 2036?
- Which companies supply or compete around the relevant shower, scent and wellness categories?
- What limits adoption, repeat purchase or supplier switching in shower steamers?
- What should buyers evaluate before purchasing or listing shower steamers?
Frequently Asked Questions
How big is the Shower Steamers Market in 2026, and what is forecast for 2036?
The market is valued at USD 784.5 Million in 2026 and is forecast to reach USD 1,365.7 Million by 2036. Growth comes from people adding scented tablets to a shower routine they already have.
What is the Shower Steamers Market CAGR from 2026 to 2036?
The market is forecast to expand at a 5.7% CAGR from 2026 to 2036. Repeat use, online reordering and product differences in scent, pack size and format will shape growth.
Which Product Type segment leads the Shower Steamers Market?
Everyday essentials leads Product Type with a 34.0% share in 2026. The format is simple to use and fits both morning and evening showers.
Which Nature segment leads the Shower Steamers Market?
Conventional leads Nature with a 52.0% share in 2026. Brands have more flexibility to adjust fragrance, foaming and price without narrowing the product around a certification or clinical claim.
Which profiled countries have the highest growth rates in the Shower Steamers Market?
The USA leads the profiled group at 7.0% CAGR from 2026 to 2036, followed by Canada at 6.6% and Japan at 6.3%. These figures compare growth rates and do not show which country has the largest market.
Which companies are active in or adjacent to the Shower Steamers Market?
Profiled companies are Hyperice, Vitruvi, Church & Dwight, Vital Proteins, Lush, Plunge, Therabody, Renpho, HigherDOSE, and The Body Shop. Lush sells shower bombs, Vitruvi publishes shower-steamer content, and the remaining companies participate through related bath, scent, consumer health or wellness categories.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Everyday essentials
- Targeted therapy formats
- Premium & smart formats
- Gift & travel sets
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Natural & organic
- Vegan
- Clinically positioned
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Use Occasion, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Use Occasion, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Use Occasion, 2026 to 2036
- Daily routine
- Recovery & post-workout
- Sleep & wind-down
- Gifting
- Y-o-Y Growth Trend Analysis By Use Occasion, 2021 to 2025
- Absolute $ Opportunity Analysis By Use Occasion, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Price Tier, 2026 to 2036
- Mid-range
- Mass
- Premium
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- E-commerce & DTC
- Specialty wellness retail
- Pharmacies
- Supermarkets
- Spas & studios
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By Use Occasion
- By Price Tier
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Hyperice
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Vitruvi
- Church & Dwight
- Vital Proteins
- Lush
- Plunge
- Therabody
- Renpho
- HigherDOSE
- The Body Shop
- Hyperice
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


