
- Market Size (2026)
- USD 11.7 Bn
- Forecast (2036)
- USD 14.1 Bn
- CAGR (2026 to 2036)
- 1.9%
How big is Urinary Tract Infection Treatment Market in 2026?
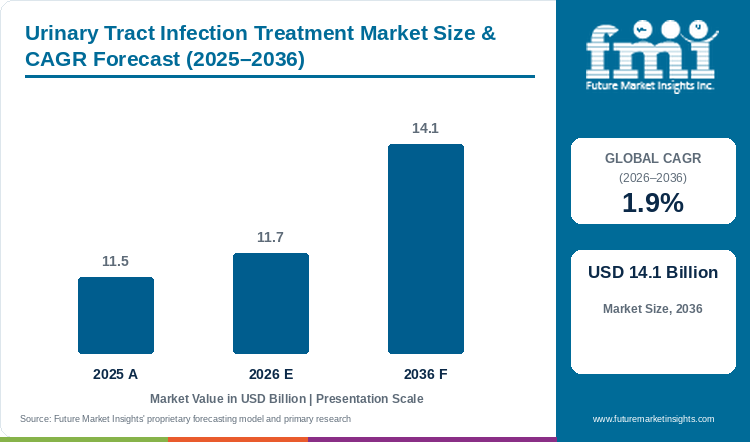
Starting from USD 11.5 billion in 2025, the urinary tract infection treatment market valuation advanced to USD 11.7 billion in 2026, with projections pointing toward USD 14.1 billion by 2036 at a CAGR of 1.9%.
FMI estimates indicate that the global urinary tract infection treatment market size stood at USD 11.5 billion in 2025 and reached USD 11.7 billion in 2026, with projections reaching USD 14.1 billion by 2036 at a 1.9% CAGR as fluoroquinolones and nitrofurans hold 45.7% of 2026 drug class demand. This 1.9% growth rate is more moderate than the 4.1% CAGR projected for wider urinary antibacterial and antiseptic pharmaceuticals since low-cost generic tablets already cover most routine bladder cases. Higher resistance to older antibiotics is now driving clinic adoption of newer oral treatments. For instance, in March 2025 GSK secured US FDA approval for Blujepa after trials across 1,605 patients showed 58.5% treatment success versus 43.6% for nitrofurantoin. However, strict insurer prior-authorization rules and cheap generic competition limit pricing, so market expansion depends on outpatient coverage for new oral pills.
Key Market Trends & Insights
- By drug class: Fluoroquinolones and nitrofurans (nitrofurantoin) are projected to capture 45.7% in 2026, supported by five-day oral nitrofurantoin tissue concentration.
- By clinical indication: Uncomplicated acute cystitis is estimated to command 70.1% in 2026, driven by high-volume outpatient prescriptions among adult women.
- By route of administration: Oral tablets and single-dose granules are expected to concentrate 73.9% in 2026, enabled by outpatient step-down protocols.
- By patient demographic: Adult female patients are forecast to generate 64.2% in 2026 due to anatomical urethra proximity and recurring post-menopausal episodes.
- By distribution channel: Retail and community pharmacies are anticipated to account for 60.3% in 2026, reinforced by same-day dispensing of oral courses.
Regional Highlights
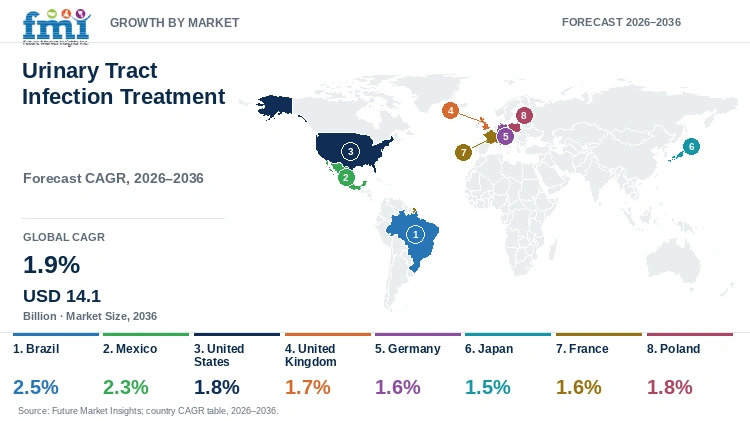
- Top national expansion: Brazil is projected to lead major national healthcare markets at a 2.5% CAGR through 2036 under expanded hospital resistance surveillance and generic oral access.
- Broader country progression: Mexico is expected to expand at a 2.3% CAGR ahead of the United States at 1.8% and the United Kingdom at 1.7%, while Germany is forecast to progress at 1.6% and Japan at 1.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Urinary Tract Infection Treatment Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.5 billion |
| Estimated Market Size in 2026 | USD 11.7 billion |
| Projected Market Size by 2036 | USD 14.1 billion |
| CAGR, 2026 to 2036 | 1.9% |
| Added Market Value, 2026 to 2036 | USD 2.4 billion |
Demand for oral step-down pills is rising across Latin American hospitals and European clinics as doctors work to avoid costly inpatient stays. Per an August 2026 review in PLoS Pathogens, five-day oral nitrofurantoin clears bladder infections more reliably than single-dose fosfomycin while sparing gut flora. Hospitals in Brazil and the US now pair oral courses with complicated urinary tract infection therapeutics to cut admission costs.
Patient-Pool and Regimen-Requirement Sizing
Table 2: Patient-Pool and Regimen-Requirement Sizing for the Urinary Tract Infection Treatment Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 11.5 | 11.7 | 14.1 |
| Treated UTI episodes globally (million) | 148.0 to 154.0 | 150.0 to 156.0 | 172.0 to 180.0 |
| Oral antibiotic courses dispensed (million) | 109.0 to 114.0 | 111.0 to 116.0 | 128.0 to 134.0 |
| Average value per treated episode (USD) | 74.5 to 77.7 | 75.0 to 78.0 | 78.3 to 82.0 |
Operational note: Patient-pool ranges apply global outpatient and inpatient symptomatic episode figures to five-to-seven-day oral tablet courses and inpatient parenteral step-down protocols.
Outpatient urgent-care clinics are increasing orders for five-day oral antibiotic packs to clear bladder symptoms on the first visit and prevent emergency room returns. Pharmacy benefit managers sign multi-year supply contracts with generic drugmakers to keep uncomplicated urinary tract infection therapies stocked across retail drugstore chains.
Per Capita & Healthcare Facility Sizing
Table 3: Per Capita and Facility Allocation Indicators for the Urinary Tract Infection Treatment Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 1,402.4 | 1,409.6 | 1,566.7 |
| Outpatient cystitis course cost range (USD) | 18.0 to 65.0 | 19.0 to 68.0 | 24.0 to 85.0 |
| Oral regimen share of prescriptions (%) | 73.5% to 74.2% | 73.8% to 74.5% | 75.5% to 76.8% |
Table 4: Facility & Institutional Treatment Allocation Indicators for the Urinary Tract Infection Treatment Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 11.7 billion | 2026 global market value baseline |
| Hospitals & urology clinics | 185,000 facilities | Global acute-care and outpatient urology registry |
| Average value per facility | USD 63,243 | Annualized institutional and outpatient anti-infective allocation |
| Uncomplicated cystitis value, 2026 | USD 8.2 billion | 70.1% clinical indication segment allocation |
Higher catheter infection rates in elderly hospital wards are pushing hospital buyers to adopt targeted intravenous antibiotics that clear resistant bacteria faster. Hospital purchasing groups combine beta-lactamase inhibitor infusions with antibiotic-resistant infection regimens to shorten intensive-care stays and reduce readmission penalties.
Analyst Perspective
"Hospital formulary directors and outpatient clinic buyers are moving from empirical fluoroquinolones toward five-day nitrofurantoin and novel oral triazaacenaphthylene tablets. Drugmakers that pair point-of-care susceptibility evidence with oral step-down convenience will secure preferred payer tiering through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the urinary tract infection treatment market segmented?
The urinary tract infection treatment market is segmented by five primary commercial axes (drug class, clinical indication, route of administration, patient demographic, and distribution channel) and region. In 2026, fluoroquinolones and nitrofurans are projected at 45.7%, uncomplicated acute cystitis at 70.1%, oral tablets and granules at 73.9%, adult female patients at 64.2%, and retail and community pharmacies at 60.3%.
By drug class: fluoroquinolones and nitrofurans (nitrofurantoin), beta-lactam penicillins, cephalosporins, and carbapenems, fosfomycin, trimethoprim-sulfamethoxazole, and novel gepotidacin or pivmecillinam, and urinary analgesics (phenazopyridine) and D-mannose or cranberry adjuncts.
By clinical indication: uncomplicated acute cystitis, complicated UTI and catheter-associated UTI, and acute pyelonephritis and recurrent prophylaxis.
By route of administration: oral tablets, capsules, and single-dose granules, and parenteral IV carbapenem and cephalosporin infusions.
By patient demographic: adult female patients, geriatric and catheterized patients, and pediatric patients.
By distribution channel: retail and community pharmacies, hospital pharmacies, and online and telehealth pharmacies.
Why do fluoroquinolones and nitrofurans account for leading drug class demand?
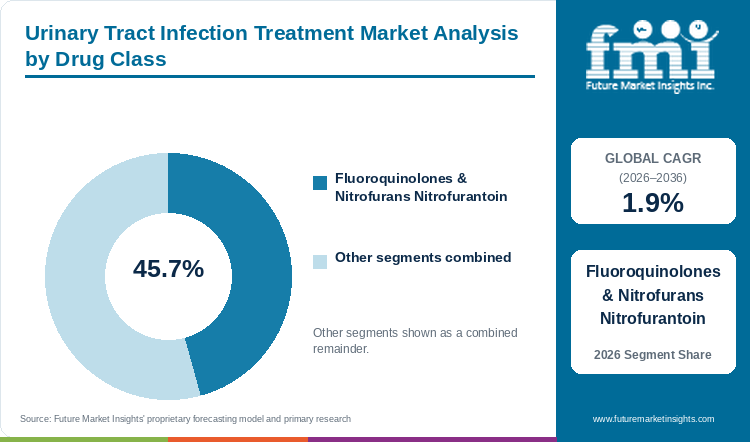
Based on drug class, fluoroquinolones and nitrofurans are projected to account for 45.7% in 2026, supported by bladder bactericidal concentration.
Table 5: Drug Class Share for the Urinary Tract Infection Treatment Market (percentage share), 2026
| Drug Class | Share (2026) |
|---|---|
| Fluoroquinolones & Nitrofurans Nitrofurantoin | 45.7% |
| Other Drug Classes Combined | 54.3%* |
| Total | 100.0% |
*Note: Remaining drug class categories sum to 100.0% of 2026 market value.
Table 6: Drug Class Leadership and Market Growth for the Urinary Tract Infection Treatment Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 1.9% |
| Leading Segment | Fluoroquinolones & Nitrofurans Nitrofurantoin |
Family doctors and clinic prescribers prefer five-day oral nitrofurantoin capsules because the medicine concentrates directly in the bladder and clears routine infections at a low cost per course. Hospitals reserve stronger fluoroquinolones for kidney cases while directing inpatient buyers toward catheter-associated urinary tract infection care across surgical wards.
- Within the drug class category, fluoroquinolones and nitrofurans are likely to secure 45.7% share in 2026, supported by low E. coli resistance and generic affordability.
- For instance, a May 2026 Spanish primary-care trial in Antibiotics showed rapid clinic susceptibility testing found 21.5% fosfomycin resistance and cut empirical fosfomycin prescriptions from 65.9% to 37.7% in favor of nitrofurantoin.
What supports uncomplicated acute cystitis as the primary clinical indication?
By clinical indication, uncomplicated acute cystitis is estimated to hold 70.1% in 2026, driven by recurring outpatient female clinic visits.
High-frequency lower bladder infections among adult women generate steady year-round prescription demand across family medicine practices, urgent-care centers, and retail walk-in clinics. Clinicians pair rapid urine dipstick screening and point-of-care urinary tract infection diagnostic testing with short oral tablet courses to relieve symptoms within three days.
- Uncomplicated acute cystitis is set to lead the clinical indication category with 70.1% share in 2026, influenced by high seasonal recurrence across adult women.
- Per a December 2025 Belgian primary-care study in Acta Clinica Belgica across 237 women, E. coli caused 74.6% of bladder infections and showed 100% susceptibility to oral nitrofurantoin and fosfomycin.
How are oral tablets and granules gaining use by administration route?
In 2026, oral tablets and granules are expected to lead route of administration with 73.9% share, enabled by step-down therapy.
Patients and insurance payers favor oral tablets, capsules, and single-dose powder sachets because home dosing eliminates hospital infusion-chair fees and nursing charges. Surgical recovery wards also lower catheter infection risks by combining early oral step-down pills with antimicrobial-coated medical devices during post-operative care.
- Oral tablets and single-dose granules are projected to hold 73.9% share in 2026, associated with outpatient self-dosing convenience.
- For instance, an October 2026 randomized trial in Clinical Infectious Diseases across 299 complicated UTI patients showed switching to 3-gram oral fosfomycin achieved a 92.8% cure rate versus 95.2% for continued IV beta-lactams.
Why do adult female patients represent the leading patient demographic?
By patient demographic, adult female patients are forecast to represent 64.2% in 2026, owing to anatomical urethra proximity and recurrence.
High repeat infection rates among adult women across both pre-menopausal and post-menopausal age groups drive recurring prescription refills at retail and telehealth pharmacies. Gynecology and primary-care clinics prescribe both five-day acute clearance packs and low-dose nightly preventive tablets to keep recurrent patients out of hospital wards.
- Patient demographic volume will be led by adult female patients at 64.2% share in 2026, linked to repeat outpatient prophylaxis.
- Pooled Phase 3 trial results in Clinical Infectious Diseases in April 2026 across 3,136 female patients confirmed over 80% early symptom relief within two to four days for oral gepotidacin and nitrofurantoin.
Which market conditions keep retail and community pharmacies leading distribution?
Retail and community pharmacies are likely to capture 60.3% distribution channel share in 2026, reinforced by same-day oral script pickup.
Neighborhood drugstores and supermarket pharmacy counters capture the largest share of prescription sales because patients with painful bladder symptoms need same-day tablet pickup close to home. Pharmacist-led test-and-treat services in the United Kingdom, Canada, and the United States further boost walk-in dispensing of generic oral antibiotics.
- Within distribution channel, retail and community pharmacies are anticipated to maintain the leading position with 60.3% share in 2026, due to neighborhood pharmacist test-and-treat access.
- Per an October 2025 Dutch study in PLoS One analyzing 366 urine samples from 272 primary-care patients, community pharmacy regimens achieved 95% treatment success for nitrofurantoin and 90% for fosfomycin.
What are the drivers, restraints, and opportunities in the urinary tract infection treatment market?
In the urinary tract infection treatment market, the key driver is ESBL uropathogen resistance, the key restraint is generic price erosion, and the key opportunity is oral step-down therapy.
- Driver: Widespread extended-spectrum beta-lactamase resistance across community uropathogens compels clinicians to adopt novel oral triazaacenaphthylene and penem classes.
- Restraint: Strict antimicrobial stewardship duration caps and low-cost generic nitrofurantoin competition restrict premium pricing for newly approved branded antibiotics.
- Opportunity: Oral transition regimens and non-antibiotic D-mannose or cranberry prophylaxis protocols reduce inpatient stay lengths and recurrent episode frequency.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Higher resistance to older generic antibiotics such as trimethoprim and ciprofloxacin is the primary factor driving hospitals and clinics to adopt newly approved oral and intravenous treatments. FMI analysis shows that updated clinical guidelines now set clear treatment duration limits to stop bacterial resistance while protecting hospital central venous catheter systems from secondary bloodstream infections. For instance, in August 2026, the Infectious Diseases Society of America published updated complicated UTI guidelines in Clinical Infectious Diseases recommending five to seven days of fluoroquinolones or seven days of non-fluoroquinolone drugs. These shorter treatment rules encourage hospital buyers to adopt fast-acting branded oral and IV drugs that clear infections quickly and reduce total bed days.
Risk Assessment of the Urinary Tract Infection Treatment Market: Operational and Formulation Friction
High treatment failure rates in catheterized hospital patients and strict insurance approval rules for branded drugs are the main factors restraining market value growth. Patients in intensive-care wards often develop stubborn catheter bacteria that do not respond to standard low-cost oral pills and require doctors to use expensive reserve hospital infusions. Per a November 2025 study in BMC Infectious Diseases across 327 catheterized ICU patients at King Abdullah Hospital, 27.8% developed catheter-associated infections with 46.2% Klebsiella prevalence and 74.7% cotrimoxazole resistance. To control drug budgets, hospital pharmacy committees restrict new branded infusions to specialist orders while outpatient insurers require patients to try generic pills and urogenital women probiotic formulations first.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Stronger healthcare payer demand for outpatient treatments that avoid three-to-five-day hospital stays opens new commercial growth opportunities for oral penem and triazaacenaphthylene drugmakers. Urology clinics and emergency rooms want oral tablets that can clear resistant bladder and kidney infections at home and fit beside community-acquired bacterial infection drugs on retail pharmacy shelves. For instance, in December 2025, an efficacy analysis in Clinical Infectious Diseases showed that 185 mg oral pivmecillinam taken three times daily for three to seven days achieved 62.0% to 71.7% overall clinical success and up to 86.9% bacterial clearance. Suppliers that pair targeted oral antibiotics with clinically tested cranberry and D-mannose preventive packs can capture both acute and repeat buyer demand.
Urinary Tract Infection Treatment Market by Country (2026 to 2036)
As per FMI, Brazil is projected to lead urinary tract infection treatment growth across evaluated healthcare systems at a 2.5% CAGR through 2036, whereas Japan is forecast to progress at a 1.5% CAGR. Commercial performance across Latin American and North American medical networks as well as European and East Asian hospitals depends on national antimicrobial stewardship rules and outpatient generic reimbursement tiers.
Table 7: Country CAGR and Primary Growth Levers for the Urinary Tract Infection Treatment Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 2.5% | Inpatient ESBL uropathogen management and expanding private hospital formulary coverage |
| Mexico | 2.3% | High outpatient clinic presentation volume and retail pharmacy oral antibiotic fulfillment |
| United States | 1.8% | FDA approvals of oral Blujepa and Pivya with outpatient stewardship protocols |
| United Kingdom | 1.7% | NHS Pharmacy First community pharmacist cystitis consultations and trust stewardship |
| Germany | 1.6% | Comprehensive laboratory susceptibility panels and S3 narrow-spectrum oral guidelines |
| Japan | 1.5% | Geriatric catheter infection management and clinical shifts from resistant cephalosporins |
| France | 1.6% | 2026 SPILF duration stratification and pharmacy point-of-care cystitis screening |
| Poland | 1.8% | Peri-operative urogynecological prophylaxis shifts toward oral fosfomycin trometamol |
Source: Future Market Insights analysis
Brazil Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Higher bacterial resistance across public and private hospitals in Brazil is driving strong demand for culture-guided intravenous cephalosporins and single-dose oral fosfomycin sachets. Per an August 2025 cohort study in IJID Regions examining 1,117 hospitalized adult UTI patients across Sao Paulo (894 women and 223 men), E. coli isolates showed widespread resistance to older beta-lactams and fluoroquinolones. By 2036, Brazil is projected to grow at 2.5% CAGR, supported by expanding private hospital insurance coverage and stricter hospital infection audits. Although ANVISA prescription rules prohibit over-the-counter antibiotic sales at retail drugstores, higher private clinic attendance across Sao Paulo and Rio de Janeiro sustains steady uptake of branded oral and hospital anti-infectives.
Key takeaway: In Brazil, inpatient beta-lactamase resistance pressures and broader private hospital formulary coverage are projected to drive 2.5% annual growth through 2036.
Mexico Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
High walk-in patient volume across pharmacy-attached medical clinics and public IMSS health centers in Mexico is fueling steady prescription demand for fast-acting oral bladder antibiotics. For instance, in October 2025, the World Health Organization Global Antibiotic Resistance Surveillance Report covering 23 million confirmed infections across 104 countries documented high cephalosporin and fluoroquinolone resistance in E. coli urinary isolates across Latin America. Mexico's urinary tract infection treatment outlook is anticipated to advance at 2.3% CAGR over the assessment period, driven by outpatient clinic expansion and hospital demand for beta-lactamase inhibitor infusions. Consolidated government drug tenders still cap public hospital generic prices, so drugmakers focus commercial promotion on private retail pharmacy chains where patients pay out of pocket.
Key takeaway: In Mexico, high community cystitis presentation volume across pharmacy-linked clinics and hospital ESBL escalation are expected to support a 2.3% CAGR.
United States Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Broader commercial insurance coverage for newly approved oral antibiotics and strong consumer spending on recurrent-infection prevention are shaping demand across the United States. Per a January 2025 six-month randomized controlled trial in The American Journal of Clinical Nutrition across 150 women, daily use of 500 mg whole cranberry fruit powder cut culture-confirmed recurrent UTI episodes by 52%. Urinary tract infection treatment demand in the United States is forecast to rise at 1.8% CAGR over the forecast period, enabled by commercial uptake of FDA-approved Pivya and Blujepa and validated preventive supplements. However, pharmacy benefit manager step-therapy rules still require patients to try cheap generic nitrofurantoin first, which slows early prescription volume for higher-priced branded tablets.
Key takeaway: In the United States, FDA approvals of novel oral antibiotics and clinically validated recurrent prophylaxis protocols are anticipated to sustain a 1.8% CAGR.
United Kingdom Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Walk-in community pharmacy prescribing under the National Health Service Pharmacy First program is expanding patient access to same-day oral cystitis treatment across British community pharmacies. Per a July 2026 antimicrobial susceptibility review in Infection and Drug Resistance spanning 13 countries, E. coli isolates maintained a 96% mean susceptibility rate to fosfomycin trometamol, with British and Spanish samples exceeding 95% susceptibility. Adoption of urinary tract infection treatment in the United Kingdom is estimated to expand at 1.7% CAGR through 2036, reinforced by community pharmacist consultations and hospital stewardship protocols. Strict NICE three-day oral course guidelines and NHS Drug Tariff generic price ceilings keep retail pack spending low while directing hospital budgets toward reserve gram-negative infusions.
Key takeaway: In the United Kingdom, NHS Pharmacy First outpatient consultation pathways and preserved fosfomycin and nitrofurantoin susceptibility are estimated to support a 1.7% CAGR.
Germany Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Strict clinical stewardship guidelines and routine laboratory urine testing across Germany direct outpatient prescribing toward narrow-spectrum oral tablets that spare gut bacteria. For instance, a December 2025 study of 258 German medical laboratories published in BJGP Open found that labs tested an average of 13.1 antibiotics per E. coli culture and included ciprofloxacin in 98.1% and nitrofurantoin in 91.5% of panels. The German urinary tract infection treatment sector is projected to record 1.6% CAGR during the assessment period, supported by statutory Krankenkassen reimbursement for culture-guided oral therapy. Mandatory pharmacy generic substitution rebates and reference price caps squeeze margins on older tablets, so suppliers focus on single-dose fosfomycin granules and hospital infusions.
Key takeaway: In Germany, comprehensive laboratory susceptibility profiling and S3 guideline preference for narrow-spectrum oral agents are forecast to anchor a 1.6% CAGR.
Japan Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
High catheter usage across geriatric hospital wards and clinical shifts away from resistant oral cephalosporins are driving treatment demand in Japan. Per an October 2025 cohort study of 71,476 Japanese women with acute cystitis in JAC-Antimicrobial Resistance, 5.24% of patients experienced initial treatment failure as clinics relied on fluoroquinolones (45.48%) and third-generation cephalosporins (43.37%). In Japan, urinary tract infection treatment demand is slated to advance at 1.5% CAGR through 2036 due to elderly inpatient care needs and adoption of targeted gram-negative antibiotics. Regular National Health Insurance price cuts reduce revenue from older oral generics, so domestic drugmakers like Shionogi focus on hospital infusions for resistant infections.
Key takeaway: In Japan, geriatric hospital catheter care and clinical transitions from resistant oral cephalosporins toward targeted gram-negative agents are projected to sustain a 1.5% CAGR.
France Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Updated national prescribing duration rules and community pharmacy dipstick screening programs in France are steering doctors and patients toward targeted oral antibiotic courses. For instance, a June 2026 guideline paper in Infectious Diseases Now explaining the 2026 SPILF male urinary infection rules recommended seven-day oral nitrofurantoin or fosfomycin and pivmecillinam courses for male cystitis versus fourteen-day courses for acute prostatitis. France is estimated to post 1.6% CAGR over the forecast period, influenced by pharmacist-led cystitis screening and hospital antimicrobial stewardship audits. Government price controls and mandatory generic substitution limit price growth on standard oral capsules and direct drugmakers to focus on rapid pharmacy test-and-treat packs and hospital beta-lactamase inhibitor combinations.
Key takeaway: In France, updated 2026 SPILF duration stratification and pharmacist-led cystitis screening pathways are slated to guide steady 1.6% annual growth.
Poland & Central Europe Urinary Tract Infection Treatment Market Outlook (2026 to 2036)
Higher fluoroquinolone resistance among surgical and urogynecological patients in Poland and Central Europe is accelerating hospital and clinic adoption of single-dose oral fosfomycin trometamol. Per a December 2025 clinical study in Annals of Agricultural and Environmental Medicine covering 173 post-operative urogynecological UTI patients, 95.95% of isolated uropathogens remained susceptible to fosfomycin, including 90.91% of ciprofloxacin-resistant strains. Urinary tract infection treatment demand in Poland is forecast to expand at 1.8% CAGR by 2036, linked to updated surgical prophylaxis protocols and growing outpatient pharmacy access. Public hospital tender price caps still favor low-cost multi-source generics, so specialty suppliers pair susceptibility testing support with branded inpatient infusions across tertiary surgical centers.
Key takeaway: In Poland and Central Europe, high fosfomycin susceptibility among ciprofloxacin-resistant surgical isolates is likely to drive peri-operative and outpatient formulary shifts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the urinary tract infection treatment market?
Pfizer Inc., GSK plc, Merck & Co., Inc., Shionogi & Co., Ltd., Teva Pharmaceutical Industries Ltd., Cipla Limited, Iterum Therapeutics plc, and Zambon S.p.A. are the notable companies in the urinary tract infection treatment market.
FMI analysis indicates that the urinary tract infection treatment sector is moderately consolidated across patented hospital anti-infectives and fragmented across first-line generic oral tablets. Multinational innovators invest in Phase 3 trials for beta-lactamase-resistant oral compounds and inpatient carbapenem combinations, whereas generic producers compete on vertical active ingredient integration and retail pharmacy chain contracting.
- Branded Anti-Infective Innovators: GSK plc and Pfizer Inc. with Merck & Co., Inc. commercialize novel oral triazaacenaphthylene tablets and inpatient beta-lactamase inhibitor infusions.
- Gram-Negative Siderophore & Specialty Leaders: Shionogi & Co., Ltd. and Iterum Therapeutics plc with Zambon S.p.A. supply cefiderocol parenteral infusions, oral sulopenem, and fosfomycin trometamol sachets.
- Global Generic & AMR Access Platforms: Teva Pharmaceutical Industries Ltd. and Cipla Limited manufacture high-volume oral nitrofurantoin, fluoroquinolones, and hospital aminoglycoside infusions.
Competitive Benchmarking: Urinary Tract Infection Treatment Market
Table 8: Competitive Benchmarking for the Urinary Tract Infection Treatment Market (qualitative capability ratings), 2026
| Company | Oral Cystitis Portfolio | Inpatient cUTI & AMR Depth | Hospital & Pharmacy Access | Geographic Reach |
|---|---|---|---|---|
| Pfizer Inc. | High | High | High | High |
| GSK plc | High | High | High | High |
| Merck & Co., Inc. | Medium | High | High | High |
| Shionogi & Co., Ltd. | Medium | High | High | High |
| Teva Pharmaceutical Industries Ltd. | High | Medium | High | High |
| Cipla Limited | High | High | High | Medium |
| Iterum Therapeutics plc | High | Medium | Medium | Medium |
| Zambon S.p.A. | High | Medium | High | Medium |
Scoring basis: Capability tiers evaluate documented clinical portfolio breadth across first-line oral cystitis agents and reserve inpatient gram-negative infusions. Formulary access and geographic ratings reflect verified hospital GPO contracts and retail pharmacy fulfillment reach.
Key Developments in the Urinary Tract Infection Treatment Market
- In October 2026, Shionogi & Co., Ltd. presented US real-world PROVE study data and SENTRY surveillance across 1,400 isolates at IDWeek showing 99.5% CLSI susceptibility for Fetroja (cefiderocol).
- In July 2026, Teva Pharmaceutical Industries Ltd. reported second-quarter 2026 revenue of USD 4.1 billion and 237 million trailing-twelve-month US generic prescriptions representing 6.1% of all US generic scripts.
- In April 2026, Merck & Co., Inc. reported first-quarter 2026 global sales of USD 16.3 billion and raised full-year 2026 revenue guidance to USD 65.8 to 67.0 billion while supplying Recarbrio for complicated UTI.
Key Players in the Urinary Tract Infection Treatment Market
Multinational Branded Anti-Infective Innovators
- Pfizer Inc.
- GSK plc
- Merck & Co., Inc.
Gram-Negative Siderophore and Specialty Urology Leaders
- Shionogi & Co., Ltd.
- Iterum Therapeutics plc
- Zambon S.p.A.
High-Volume Generic and AMR Access Manufacturers
- Teva Pharmaceutical Industries Ltd.
- Cipla Limited
Urinary Tract Infection Treatment Market Report Scope
Table 9: Report Scope for the Urinary Tract Infection Treatment Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Drug Class, Clinical Indication, Route of Administration, Patient Demographic, Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer value from prescription and over-the-counter urinary anti-infectives, beta-lactamase inhibitor infusions, urinary analgesics, and clinically validated D-mannose or cranberry prophylaxis formulations. Category Scope Note: Excludes general systemic sepsis biologics, urological surgical lasers, and standalone urinary catheters. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Germany, Japan, France, Poland, and additional countries in the full report |
| Key Companies Covered | Pfizer Inc., GSK plc, Merck & Co., Inc., Shionogi & Co., Ltd., Teva Pharmaceutical Industries Ltd., Cipla Limited, Iterum Therapeutics plc, Zambon S.p.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Urinary Tract Infection Treatment Market Research Methodology
Table 10: Research Methodology for the Urinary Tract Infection Treatment Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with hospital infectious-disease pharmacists, outpatient urologists, clinical microbiologists, and retail pharmacy category managers to validate empirical prescribing and step-down workflows. |
| Secondary Research | Analysis of corporate financial filings, US FDA and EMA approval packages, IDSA and SPILF clinical guidelines, WHO GLASS surveillance reports, and peer-reviewed PubMed clinical trials. |
| Market Sizing and Forecasting | Top-down pharmaceutical anti-infective expenditure models reconciled against bottom-up symptomatic episode incidence and average prescription course pricing from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight female adult and geriatric demographics, ESBL prevalence rates, and pharmacy reimbursement structures across major healthcare systems. |
| Operational Benchmark Traceability | Patient-pool and facility indicators in Tables 2, 3, and 4 trace to Phase 3 EAGLE-2 and EAGLE-3 cohorts, WHO GLASS surveillance records, and multi-country outpatient prescribing studies. |
| Data Triangulation and Validation | Market value estimates are cross-checked against manufacturer anti-infective segment disclosures and national outpatient prescription registries without double counting bulk active ingredients. |
Urinary Tract Infection Treatment Market by Segments
Urinary Tract Infection Treatment Market segmented by Drug Class:
- Fluoroquinolones & Nitrofurans Nitrofurantoin
- Beta-Lactam Penicillins, Cephalosporins & Carbapenems
- Fosfomycin, Trimethoprim-Sulfamethoxazole & Novel Gepotidacin/Pivmecillinam
- Urinary Analgesics Phenazopyridine & D-Mannose/Cranberry Adjuncts
Urinary Tract Infection Treatment Market segmented by Clinical Indication:
- Uncomplicated Acute Cystitis
- Complicated UTI & Catheter-Associated UTI
- Acute Pyelonephritis & Recurrent Prophylaxis
Urinary Tract Infection Treatment Market segmented by Route of Administration:
- Oral Tablets, Capsules & Single-Dose Granules
- Parenteral IV Carbapenem/Cephalosporin Infusions
- Intravesical Bladder Instillations
Urinary Tract Infection Treatment Market segmented by Patient Demographic:
- Adult Female Patients
- Geriatric & Catheterized Patients
- Pediatric Patients
- Adult Male Urology Patients
Urinary Tract Infection Treatment Market segmented by Distribution Channel:
- Retail & Community Pharmacies
- Hospital Pharmacies
- Online & Telehealth Pharmacies
- Institutional & Long-Term Care Dispensaries
- Specialty Urology Clinics
Urinary Tract Infection Treatment Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] GSK plc. (2025, March 25). Blujepa (gepotidacin) approved by US FDA for treatment of uncomplicated urinary tract infections (uUTIs) in female adults and paediatric patients 12 years of age and older. GSK plc.
- [2] Szlachta-McGinn, A., & Ackerman, A. L. (2026, August 13). Nitrofurantoin treatment and prophylaxis for recurrent urinary tract infections in women: First-line for a reason. PLoS Pathogens, 22(8), e1014516 (PubMed PMID 42594063).
- [3] Martínez-Berganza Asensio, L., Largo-Rojo, G., Menéndez-Fernández, A. I., Solano-Villarrubia, C., Fuentes-Romero, M., & Medina-Polo, J. (2026, May 21). Impact of PA-100 AST System Rapid Antibiotic Susceptibility Test on Antibiotic Prescription for Community-Acquired Urinary Tract Infections in Spanish Primary Care Settings. Antibiotics (Basel), 15(5), 520 (PubMed PMID 42192742).
- [4] Vanderpoorten, L., Vandevelde, S., De Corte, L., Holvoet, J., Vandevelde, L., Thys, C., et al. (2025, December 29). Overview and resistance profiles of isolated pathogens in women with uncomplicated urinary tract infection in primary care. Acta Clinica Belgica, 1-9 (PubMed PMID 41459978).
- [5] Seo, J.-W., Kim, D. Y., Yoon, Y., Lyu, Y. S., Na, Y. S., Moon, D. S., et al. (2026, October 7). Fosfomycin as Oral Transition Therapy Versus Continued Intravenous Beta-Lactams for Complicated Urinary Tract Infections Caused by Extended-Spectrum Beta-Lactamase-Producing Enterobacterales: A Multicenter, Open-Label, Randomized Controlled Trial. Clinical Infectious Diseases, 83(3), 364-372 (PubMed PMID 42313397).
- [6] Wagenlehner, F., Perry, C. R., Hooton, T. M., Scangarella-Oman, N. E., Millns, H., Flight, W., et al. (2026, April 30). Early Symptom Response in Patients With Uncomplicated Urinary Tract Infection Treated With Gepotidacin or Nitrofurantoin: Pooled Analysis From Two Pivotal Phase 3 Studies. Clinical Infectious Diseases, 82(4), e684-e692 (PubMed PMID 41495938).
- [7] Bruins, M. J., Eijkelkamp-Biesterbos, L., Meutstege, A. M., & Oliveira Dos Santos, C. (2025, October 9). Escherichia coli antimicrobial resistance in acute urinary tract infection lower than reported in Dutch national surveillance database. PLoS One, 20(10), e0334222 (PubMed PMID 41066378).
- [8] Trautner, B. W., Cortés-Penfield, N. W., Gupta, K., Hirsch, E. B., Horstman, M., Moran, G. J., et al. (2026, August 24). Clinical Practice Guidelines by Infectious Diseases Society of America (IDSA): 2025 Guidelines on Management and Treatment of Complicated Urinary Tract Infections--Duration of Antibiotics for Complicated UTI. Clinical Infectious Diseases, 82(Suppl 3), i79-i88 (PubMed PMID 41419448).
- [9] Al-Amri, H. A., Almalhan, L. A., Alghamdi, M. A., & Ibrahim, M. E. (2025, November 24). Catheter-associated urinary tract infection and associated factors among patients admitted to intensive care unit at King Abdullah Hospital, Bisha, Saudi Arabia. BMC Infectious Diseases, 25(1), 1640 (PubMed PMID 41286652).
- [10] Lodise, T. P., Das, A. F., Frimodt-Møller, N., Gupta, K., Rodvold, K. A., Santerre Henriksen, A., et al. (2025, December 24). Pivmecillinam for Treatment of Uncomplicated Urinary Tract Infection: New Efficacy Analysis. Clinical Infectious Diseases, 81(5), e285-e293 (PubMed PMID 40567143).
- [11] da Silva, C. E., Carvalho, P. H. S., Capretz, G. C. G., Ciriaco, Y. S., de Souza, W. H. M., Alves, M. E. F. S., et al. (2025, August 7). Profile of antimicrobial resistance of uropathogens in urinary tract infections: An analysis of 1117 hospitalized patients in Brazil. IJID Regions, 16, 100724 (PubMed PMID 40927058).
- [12] World Health Organization. (2025, October 13). Global antibiotic resistance surveillance report 2025: WHO Global Antimicrobial Resistance and Use Surveillance System (GLASS). World Health Organization.
- [13] Stonehouse, W., Benassi-Evans, B., Bednarz, J., & Vincent, A. D. (2025, January 23). Whole cranberry fruit powder supplement reduces the incidence of culture-confirmed urinary tract infections in females with a history of recurrent urinary tract infection: A 6-month multicenter, randomized, double-blind, placebo-controlled trial. The American Journal of Clinical Nutrition, 121(4), 932-941 (PubMed PMID 39863114).
- [14] Stefani, S., & Tascini, C. (2026, July 15). Fosfomycin Trometamol in the Management of Urinary Tract Infection: A Focus on Antimicrobial Susceptibility and Resistance. Infection and Drug Resistance, 19, 589847 (PubMed PMID 42519673).
- [15] Bender, H., Jobski, K., Schmiemann, G., Hamprecht, A., & Hoffmann, F. (2025, December 19). Urinary tract infection in outpatients in Germany: a cross-sectional study of diagnostics and susceptibility testing in medical laboratories. BJGP Open, 9(4), BJGPO.2025.0004 (PubMed PMID 40550633).
- [16] Preib, M. T., Emden, M. R., Sacks, N. C., Mitrani-Gold, F. S., Ju, S., Kawano, Y., et al. (2025, October 17). Prevalence and economic evaluation of acute uncomplicated cystitis in women from Japan: a retrospective cohort study. JAC-Antimicrobial Resistance, 7(5), dlaf178 (PubMed PMID 41113066).
- [17] Forestier, E., Soudais, B., Caspar, Y., Etienne, M., Milacic, H., Orcel, V., et al. (2026, June 25). Antibiotic treatment of male urinary tract infections: scientific rationale behind the 2026 SPILF guidelines. Infectious Diseases Now, 105319 (PubMed PMID 42349553).
- [18] Wawrysiuk, S. P., Bogusiewicz, M., Pachciński, O., Grywalska, E., & Miotła, P. (2025, December 22). Fosfomycin susceptibility of uropathogens resistant to antibiotics used in peri-operative prophylaxis of urinary tract infection among patients after urogynaecological surgery. Annals of Agricultural and Environmental Medicine, 32(4), 488-491 (PubMed PMID 41472582).
- [19] Shionogi & Co., Ltd. (2026, October 21). IDWeek 2026: Shionogi Presents U.S. Analysis of Real-World Data Showing Early Treatment Initiation with Fetroja/Fetcroja (cefiderocol) Improved Clinical Outcomes in Patients with Respiratory Infections. Shionogi Inc.
- [20] Teva Pharmaceutical Industries Ltd. (2026, July 29). Teva Delivers Strong Q2 Results and Raises Outlook for All Three Key Innovative Brands, Reflecting Continued Execution of Its Pivot to Growth Strategy. Teva Pharmaceutical Industries Ltd.
- [21] Merck & Co., Inc. (2026, April 30). Merck & Co., Inc., Rahway, N.J., USA Announces First-Quarter 2026 Financial Results; Highlights Significant Regulatory Approvals and Clinical Milestones. Merck & Co., Inc.
- [22] Pfizer Inc. (2025, December 16). Pfizer Reaffirms Full-Year 2025 EPS Guidance and Provides Full-Year 2026 Guidance. Pfizer Inc.
- [23] World Health Organization. (2026, July 16). Antimicrobial resistance: Fact sheet on global bacterial resistance and treatment cost projections. World Health Organization.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the urinary tract infection treatment market in 2026?
- Which antimicrobial resistance pressures support demand for novel urinary infection drugs?
- Why do fluoroquinolones and nitrofurans lead the drug class category today?
- Why does uncomplicated acute cystitis lead the clinical indication category globally?
- How do growth rates differ across Brazil, Mexico, and the USA?
- Which notable pharmaceutical companies supply oral cystitis and inpatient cUTI therapies?
- What limits branded drug adoption in the urinary infection treatment market?
- What should hospital pharmacy committees evaluate before approving a urinary anti-infective?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Drug Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Drug Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Drug Class, 2026 to 2036
- Fluoroquinolones & Nitrofurans Nitrofurantoin
- Beta-Lactam Penicillins, Cephalosporins & Carbapenems
- Fosfomycin, Trimethoprim-Sulfamethoxazole & Novel Gepotidacin/Pivmecillinam
- Urinary Analgesics Phenazopyridine & D-Mannose/Cranberry Adjuncts
- Y-o-Y Growth Trend Analysis By Drug Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Drug Class, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Indication, 2026 to 2036
- Uncomplicated Acute Cystitis
- Complicated UTI & Catheter-Associated UTI
- Acute Pyelonephritis & Recurrent Prophylaxis
- Y-o-Y Growth Trend Analysis By Clinical Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Route of Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route of Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route of Administration, 2026 to 2036
- Oral Tablets, Capsules & Single-Dose Granules
- Parenteral IV Carbapenem/Cephalosporin Infusions
- Intravesical Bladder Instillations
- Y-o-Y Growth Trend Analysis By Route of Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route of Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Patient Demographic, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Patient Demographic, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Patient Demographic, 2026 to 2036
- Adult Female Patients
- Geriatric & Catheterized Patients
- Pediatric Patients
- Adult Male Urology Patients
- Y-o-Y Growth Trend Analysis By Patient Demographic, 2021 to 2025
- Absolute $ Opportunity Analysis By Patient Demographic, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail & Community Pharmacies
- Hospital Pharmacies
- Online & Telehealth Pharmacies
- Institutional & Long-Term Care Dispensaries
- Specialty Urology Clinics
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Drug Class
- By Clinical Indication
- By Route of Administration
- By Patient Demographic
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pfizer Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- GSK plc
- Merck & Co., Inc.
- Shionogi & Co., Ltd.
- Teva Pharmaceutical Industries Ltd.
- Cipla Limited
- Iterum Therapeutics plc
- Zambon S.p.A.
- Pfizer Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Drug Class, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Route of Administration, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Drug Class
- Figure 6: Global Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Clinical Indication
- Figure 9: Global Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Route of Administration
- Figure 12: Global Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Patient Demographic
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Drug Class
- Figure 32: North America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Clinical Indication
- Figure 35: North America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Route of Administration
- Figure 38: North America Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Patient Demographic
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Drug Class
- Figure 48: Latin America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Clinical Indication
- Figure 51: Latin America Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Route of Administration
- Figure 54: Latin America Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Patient Demographic
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Drug Class
- Figure 64: Western Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Clinical Indication
- Figure 67: Western Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Route of Administration
- Figure 70: Western Europe Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Patient Demographic
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Drug Class
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Clinical Indication
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Route of Administration
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Patient Demographic
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Drug Class
- Figure 96: East Asia Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Clinical Indication
- Figure 99: East Asia Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Route of Administration
- Figure 102: East Asia Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Patient Demographic
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Drug Class
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Clinical Indication
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Route of Administration
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Patient Demographic
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Drug Class, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Drug Class, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Drug Class
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Clinical Indication
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Route of Administration, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Route of Administration, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Route of Administration
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Patient Demographic
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the urinary tract infection treatment market in 2026, and what is forecast for 2036?
In the FMI report, global urinary tract infection treatment market value is estimated to reach USD 11.7 billion in 2026 from USD 11.5 billion in 2025 and climb to USD 14.1 billion by 2036.
What is the CAGR for the urinary tract infection treatment market from 2026 to 2036?
Future Market Insights projects a 1.9% compound annual growth rate between 2026 and 2036, which yields an anticipated USD 2.4 billion increase in market value across outpatient and hospital pharmacy channels.
Which drug class segment leads the urinary tract infection treatment market?
Fluoroquinolones and nitrofurans (nitrofurantoin) are projected to capture 45.7% of drug class demand in 2026 since five-day oral nitrofurantoin courses maintain high E. coli susceptibility.
Which clinical indication segment leads the urinary tract infection treatment market?
Uncomplicated acute cystitis is estimated to secure 70.1% of the clinical indication category in 2026 as adult female lower bladder infections drive high-frequency outpatient prescribing.
Which country has a notable growth outlook during the assessment period?
Brazil is projected to lead national growth at a 2.5% CAGR through 2036, supported by inpatient ESBL resistance management and expanding private hospital coverage.
Who are the key players in the market?
Pfizer Inc. and GSK plc with Merck & Co., Inc. and Shionogi & Co., Ltd. lead commercial supply across hospital and retail pharmacies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
