
- Market Size (2026)
- USD 785.1 Mn
- Forecast (2036)
- USD 1341.1 Mn
- CAGR (2026 to 2036)
- 5.5%
How big is the Widefield Imaging Systems Market in 2026?
USD 785.1 million in 2026, reaching USD 1,341.1 million by 2036 at a 5.5% CAGR
The widefield imaging systems market was valued at USD 744.2 million in 2025. The market is set to reach USD 785.1 million by 2026-end and grow at a CAGR of 5.5% between 2026-2036 to reach USD 1,341.1 million by 2036. Instrument will dominate with a 71.0% share, while Diabetic Retinopathy will lead with a 33.6% share.
Widefield imaging systems procurement is shaped by diabetic retinopathy screening mandates, retinal disease diagnostic requirements, and ophthalmic clinic modernization cycles. Demand reflects investment in ultra-widefield fundus cameras, OCT-integrated platforms, and fluorescein angiography systems for retinal examination across hospitals and ophthalmic clinics. Buyers include hospital ophthalmology departments, retina specialty clinics, and diagnostic center managers evaluating imaging field coverage, resolution, and workflow integration.
Growth reflects rising diabetic retinopathy prevalence and increasing adoption of widefield imaging for peripheral retinal assessment. International Diabetes Federation reported in 2025 that global diabetes prevalence continued to increase, sustaining demand for retinal screening infrastructure.
The basis of competition is imaging field coverage, OCT integration capability, and AI-assisted retinal analysis. Carl Zeiss Meditec and Topcon draw on comprehensive ophthalmic imaging platforms to lead, while Optos and Heidelberg Engineering gain preference where ultra-widefield coverage and OCT multimodal integration drive procurement.
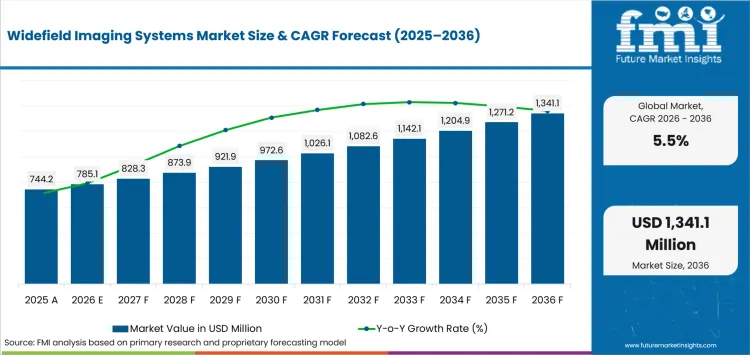
Key Takeaways of Widefield Imaging Systems Market
- Diabetic retinopathy screening expansion is expected to sustain widefield imaging procurement across hospitals and ophthalmic clinics.
- Instrument is expected to account for 71.0% of component demand in 2026 because widefield camera and OCT platform hardware represents the primary capital procurement.
- Diabetic Retinopathy is projected to hold 33.6% of indication demand in 2026, driven by screening program expansion and diabetes prevalence growth.
- Standalone is anticipated to represent 64.0% of modality demand in 2026 as dedicated widefield instruments remain the primary configuration for retinal imaging clinics.
- India leads with a 9.2% CAGR through 2036 as diabetic retinopathy screening expansion and ophthalmic infrastructure investment sustain procurement.
- Carl Zeiss Meditec and Topcon are expected to compete through comprehensive ophthalmic imaging platform portfolios.
Analyst Perspective
"Buyers are expected to judge instrument on performance and total cost of ownership rather than headline price. Widefield imaging adoption is expected to depend on diabetic retinopathy screening mandates and OCT integration progression. Suppliers that combine widefield coverage with AI-assisted analysis and clinic workflow integration are likely to secure hospital ophthalmology contracts. Market success is projected to depend on demonstrating screening efficiency and diagnostic accuracy gains across retinal disease assessment."
- Anurag Sharma, Principal Consultant at Future Market Insights
Why is the Widefield Imaging Systems Market growing?
Rising Instrument and Diabetic Retinopathy demand across healthcare end users
- Widefield retinal-imaging demand follows diabetic-retinopathy screening programs and ophthalmology caseloads rather than speculative equipment buying.
- India leads growth at 9.2% CAGR as diabetic retinopathy screening expansion and ophthalmic infrastructure investment sustain procurement.
- Diabetic Retinopathy holds 33.6% of indication revenue, indicating where standardization is concentrating buyer spend.
Because early detection drives screening value, widefield-imaging spend concentrates with vendors whose ultra-widefield and OCT platforms integrate into ophthalmic and tele-screening workflows.
How is the Widefield Imaging Systems Market segmented?
The widefield imaging systems industry is segmented by component, indication, modality, end user, technology, and region.
The widefield imaging systems market is segmented by component, indication, modality, end user, technology, and region. By component, the market covers instrument and software. By indication, the market covers diabetic retinopathy, retinal vein occlusion, age-related macular degeneration, glaucoma, retinopathy of prematurity, uveitis, choroidal tumors, retinal detachment, and other retinal conditions. By modality, the market covers standalone and integrated. By end user, the market covers hospitals, ophthalmic clinics, and diagnostic centers. By technology, the market covers optical coherence tomography integration, ultra-widefield fundus imaging, and fluorescein angiography. Regions include North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
How does instrument shape demand within the component category?
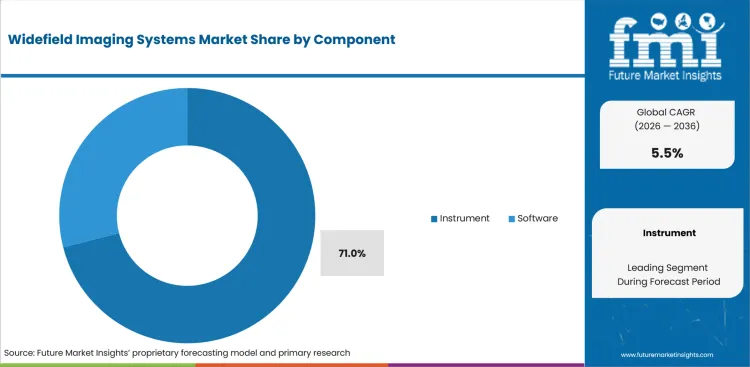
Component selection determines clinical fit, workflow efficiency, and procurement priority across care settings. Instrument anchors the category, keeping buyer spend concentrated where qualification and service support are already established. Demand concentrates here because widefield fundus cameras and OCT platforms represent the primary capital equipment investment.
- Instrument is expected to account for 71.0% of component demand in 2026 because widefield fundus cameras and OCT platforms represent the primary capital equipment investment.
- Optical Coherence Tomography Integration is projected to hold 46.8% of technology demand as OCT-combined widefield systems provide multi-layer retinal analysis.
What supports diabetic retinopathy indication demand?
Diabetic retinopathy indication shapes buyer requirements because segment choice here determines clinical fit, workflow efficiency, and procurement priority across care settings. Demand concentrates here because diabetes prevalence growth sustains screening program equipment procurement.
- Diabetic Retinopathy is projected to hold 33.6% of indication demand in 2026 because diabetes prevalence growth sustains screening program equipment procurement.
- Hospitals is forecast to represent 51.7% of end-user demand as hospital ophthalmology departments generate the highest widefield imaging utilization.
How do modality and end user shape procurement?
Modality and end user decide who controls the purchase and how the product reaches the account; together they determine clinical fit, workflow efficiency, and procurement priority across care settings. Demand concentrates here because dedicated widefield instruments offer optimized imaging workflow for retinal clinics.
- Standalone is expected to hold 64.0% of modality demand in 2026 because dedicated widefield instruments offer optimized imaging workflow for retinal clinics.
- Hospitals are anticipated to account for 51.7% of end-user demand because ophthalmology departments require widefield capability for comprehensive retinal examination.
What are the drivers, restraints, and opportunities in the Widefield Imaging Systems Market?
Near-term procurement is shaped by diabetic retinopathy screening expansion, OCT integration, and AI-assisted retinal analysis adoption.
- Driver: Diabetic retinopathy prevalence growth is expected to push widefield imaging procurement as screening programs expand across hospital and clinic settings.
- Restraint: High capital cost for OCT-integrated widefield platforms is likely to slow adoption if ophthalmic clinics face equipment budget constraints.
- Opportunity: AI-assisted retinal image analysis is expected to open supplier access if automated screening algorithms reduce ophthalmologist workload and improve diagnostic throughput.
Diabetic retinopathy screening expansion is expected to increase widefield procurement. International Diabetes Federation reported in 2025 that global diabetes prevalence continued to rise, sustaining retinal screening infrastructure investment.
Capital cost barriers are expected to limit OCT-integrated platform adoption. Carl Zeiss Meditec reported in 2025 that ophthalmic equipment purchasing remained sensitive to hospital capital budget allocation cycles.
AI-assisted screening creates a practical route by automating retinal image grading. Topcon reported in 2025 that its AI-integrated retinal screening platform expanded deployments across diabetic eye screening programs.
Which country CAGRs are profiled in the Widefield Imaging Systems Market?
India 9.2%, China 8.6%, UK 4.6%, USA 3.3%, Germany 3% through 2036
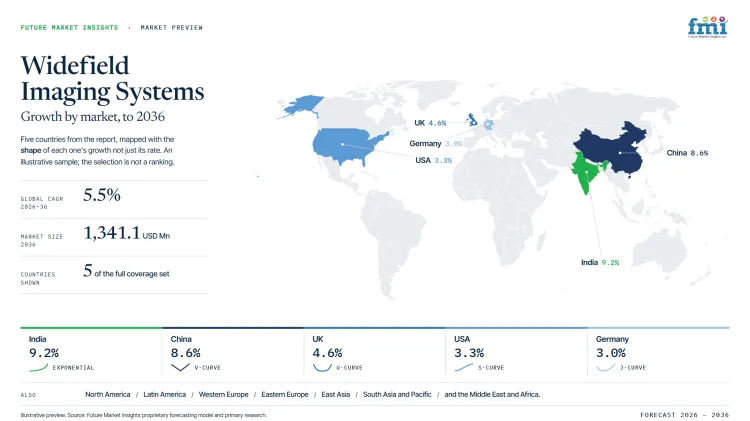
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 9.2% |
| China | 8.6% |
| UK | 4.6% |
| USA | 3.3% |
| Germany | 3% |
Source: FMI's proprietary forecasting model and primary research. 5 of the countries covered in the full report are shown here as a representative subset.
How do country-level CAGRs compare in the Widefield Imaging Systems Market?
The country comparison spans 6.2 percentage points and reveals three distinct growth groups across the Widefield Imaging Systems Market. India leads at 9.2%, while China and the United Kingdom form a middle group with a 3.4-point difference. Germany remains at the lower end at 3.0%, while the United States figure is incomplete in the supplied data.
- India leads the comparison at a 9.2% CAGR through 2036, supported by rising diabetes prevalence and screening-program expansion, which are broadening the base for widefield retinal imaging.
- China records a CAGR of 8.0% through 2036, remaining 1.2 percentage points below India. Screening-infrastructure gaps and cost sensitivity can slow uptake outside urban eye centers, increasing the importance of affordable platforms, technician training and tele-screening integration.
- The United Kingdom grows at a 4.6% CAGR through 2036, creating a 3.4-percentage-point gap from China. NHS diabetic-eye-screening programs and centralized procurement route widefield-imaging purchases through structured tenders.
- The United States has an incomplete CAGR figure in the supplied data. Screening-program evidence and framework listing influence market access, while supplier positioning depends on framework participation and screening-outcome evidence.
- Germany records a 3.0% CAGR through 2036, remaining 1.6 percentage points below the United Kingdom. Ophthalmology-accreditation standards and clinic procurement shape which widefield imaging platforms qualify for adoption.
Comparable CAGRs can still produce different market conditions. Differences in diabetes-screening coverage, ophthalmology infrastructure, procurement structures, equipment affordability, tele-screening adoption and accreditation requirements influence widefield imaging demand across countries. The United States figure should be confirmed before calculating its exact position in the comparison.
Country-wise Analysis
- Indian providers buy widefield imaging systems across expanding private hospital chains and cost-sensitive public tenders. Ophthalmology-accreditation review and budget discipline lengthen the evaluation cycle. Suppliers need documented detection performance, service contracts, and compliance depth to win.
- Chinese hospitals procure widefield imaging systems through centralized purchasing programs that reward registered, competitively priced products. Demand draws on diabetic retinopathy prevalence growth. In China, demand is predicted to advance at an 8.6% CAGR through 2036, supported by tertiary hospital expansion and county-level facility upgrades. Screening-infrastructure gaps and cost sensitivity slow uptake outside urban eye centers. Volume-based procurement pressures pricing even as screening volumes rise. Suppliers need local registration, competitive tenders, and provincial service to convert screening-program demand.
- UK providers procure widefield imaging systems through NHS frameworks and structured tender cycles. The Widefield Imaging Systems Market in the United Kingdom is projected to record a 4.6% CAGR during the assessment period, supported by NHS procurement frameworks and structured tender demand. Volume-based procurement pressures pricing even as screening volumes rise. Suppliers need local registration, competitive tenders, and provincial service to convert program demand.
- US providers procure widefield imaging systems through GPO contracts against a large installed base on replacement cycles. Sales in the United States are forecast to expand at a 3.3% CAGR by 2036, supported by replacement cycles across a large installed base and GPO contracting. Screening-program evidence and framework listing gate access. Tele-screening reimbursement and evidence requirements shape access. Suppliers protect share with integration, detection-outcome evidence, and dependable service.
- German hospitals procure widefield imaging systems through engineering-led, specification-driven tenders. The market outlook in Germany is anticipated to advance at a 3% CAGR over the assessment period, supported by structured hospital procurement and a large installed equipment base. Tele-screening reimbursement and evidence requirements shape access. Suppliers protect share with integration, detection-outcome evidence, and dependable service.
Who are the notable companies in the Widefield Imaging Systems Market?
Carl Zeiss Meditec AG, Topcon Corporation, NIDEK Co., Ltd., Optos (a Nikon company), Heidelberg Engineering GmbH, Visunex Medical Systems, Inc., Clarity Medical Systems, Inc., and Centervue SpA are the notable companies shaping this market.
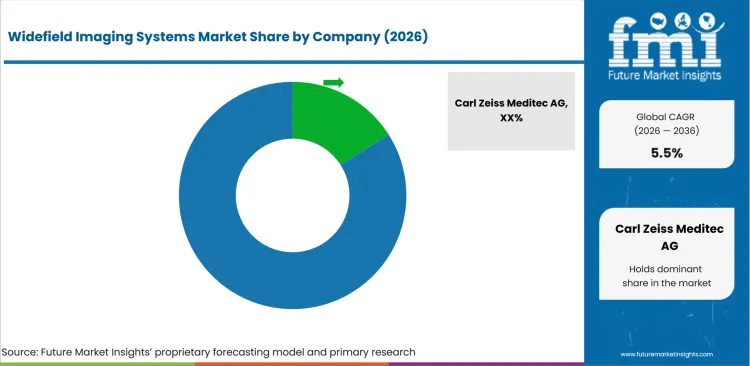
The field concentrates around ophthalmic-imaging companies that pair ultra-widefield and OCT platforms with clinic access and tele-screening workflow support. Ultra-widefield and retinal imaging specialists emphasize Ultra-widefield retinal imaging and Portable retinal screening, while screening and diagnostic imaging companies serve regional demand through Automated fundus screening. Global ophthalmic imaging platform companies compete across OCT and fundus imaging, Retinal imaging platforms and Ophthalmic diagnostic systems throughout established accounts. A workable entry is a portable or tele-screening retinal-imaging niche, or a regional service model. Growth depends on regulatory clearance, technician training, and service coverage across each launch market. Breadth pays off through teams that integrate widefield platforms into ophthalmic and screening workflows.
- Carl Zeiss Meditec AG and Topcon Corporation combine OCT and fundus imaging and Retinal imaging platforms across multiple national markets. NIDEK Co., Ltd. adds Ophthalmic diagnostic systems through established account relationships. Their edge comes from ultra-widefield and OCT platforms with tele-screening fit.
- Optos (a Nikon company), Visunex Medical Systems, Inc. and Clarity Medical Systems, Inc. follow focused routes across Ultra-widefield retinal imaging, Portable retinal screening and ROP screening systems. Their commercial edge comes from portable and screening niches with strong clinical support rather than one standardized system.
- Centervue SpA and Remidio Innovative Solutions Pvt. Ltd. provide regional coverage through Automated fundus screening. These firms compete on a targeted retinal-imaging strengths, though reach trails the ophthalmic majors.
Competitive Benchmarking: Widefield Imaging Systems Market
| Company | Portfolio Relevance | Imaging Focus | Account Access | Service Reach |
|---|---|---|---|---|
| Carl Zeiss Meditec AG | High | OCT and fundus imaging | Strong | Global |
| Topcon Corporation | High | Retinal imaging platforms | Strong | Global |
| NIDEK Co., Ltd. | High | Ophthalmic diagnostic systems | Strong | Global |
| Optos (a Nikon company) | High | Ultra-widefield retinal imaging | Strong | Global |
| Heidelberg Engineering GmbH | High | OCT and multimodal imaging | Strong | Global |
| Visunex Medical Systems, Inc. | Medium | Portable retinal screening | Moderate | Regional |
| Clarity Medical Systems, Inc. | Medium | ROP screening systems | Moderate | Regional |
| Centervue SpA | Medium | Automated fundus screening | Moderate | Regional |
Source: Future Market Insights competitive analysis, 2026. Ratings reflect relative portfolio relevance, workflow or project fit, service capability, and geographic reach.
Key Developments in the Widefield Imaging Systems Market
- In October 2025, Carl Zeiss Meditec's ZEISS Medical Technology division announced 510(k) clearance and CE approval for the CLARUS 700 with ICGA, adding standalone ICG and simultaneous FA-ICG capture to its ultra-widefield imaging platform.
- In May 2025, Topcon Healthcare announced its acquisition of RetInSight GmbH, adding OCT-based AI algorithms for retinal disease detection and monitoring to its Harmony clinical data management platform.
Key Players in the Widefield Imaging Systems Market
Global ophthalmic imaging platform companies
- Carl Zeiss Meditec AG
- Topcon Corporation
- NIDEK Co., Ltd.
- Heidelberg Engineering GmbH
Ultra-widefield and retinal imaging specialists
- Optos (a Nikon company)
- Visunex Medical Systems, Inc.
- Clarity Medical Systems, Inc.
Screening and diagnostic imaging companies
- Centervue SpA
- Ziemer Ophthalmic Systems AG
Widefield Imaging Systems Market: Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Component, indication, modality, end user, technology, and region. |
| Market Definition | Widefield imaging systems include ultra-widefield fundus cameras, OCT-integrated platforms, and fluorescein angiography instruments for retinal examination across diabetic retinopathy, macular degeneration, glaucoma, and other retinal conditions in hospitals and ophthalmic clinics. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa. |
| Countries Covered | United States, China, India, Germany, United Kingdom, Japan, and Brazil. |
| Key Companies Profiled | Carl Zeiss Meditec AG, Topcon Corporation, NIDEK Co., Ltd., Optos (a Nikon company), Heidelberg Engineering GmbH, Visunex Medical Systems, Inc., Clarity Medical Systems, Inc., Centervue SpA. |
| Forecast Period | 2026 to 2036. |
| Approach | FMI used primary interviews, source validation, company authentication, and proprietary demand modeling. |
Source: Future Market Insights, analysis driven by proprietary forecasting models and primary research
Widefield Imaging Systems Market: Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI interviewed widefield imaging systems suppliers, buyers, and procurement leads. |
| Desk Research | Desk research used government releases, regulator updates, company filings, and product pages. |
| Market Sizing and Forecasting | The forecast model linked 2026 revenue anchors to demand drivers and country-specific conditions. |
| Data Validation | Forecast values were checked against the ten-year CAGR formula. |
Source: Future Market Insights (FMI) analysis, based on proprietary forecasting model and primary research
Market Segmentation Analysis
Widefield Imaging Systems Market Segmented by Component:
- Instrument
- Standalone Widefield Imaging Devices
- High Resolution Retinal Visualization
- Enhanced Diagnostic Accuracy
- Portable Retinal Imaging Instruments
- Point Of Care Eye Examination Support
- Improved Screening Accessibility
- Standalone Widefield Imaging Devices
- Software
- AI Based Imaging Analysis Software
- Automated Disease Detection
- Enhanced Clinical Decision Support
- Cloud Integrated Imaging Platforms
- Remote Image Sharing Capability
- Improved Patient Data Management
- AI Based Imaging Analysis Software
Widefield Imaging Systems Market Segmented by Indication:
- Diabetic Retinopathy
- Diabetic Eye Disease Monitoring
- Early Retinal Damage Detection
- Improved Vision Preservation
- AI Assisted Retinopathy Screening
- Enhanced Screening Efficiency
- Reduced Diagnostic Delays
- Diabetic Eye Disease Monitoring
- Retinopathy Of Prematurity
- Neonatal Retinal Screening Systems
- Improved Infant Vision Care
- Early Disease Intervention
- Portable NICU Imaging Solutions
- Enhanced Pediatric Accessibility
- Improved Monitoring Accuracy
- Neonatal Retinal Screening Systems
- Pediatric Retinal Diseases
- Childhood Retinal Disorder Imaging
- Improved Pediatric Diagnostics
- Enhanced Early Treatment Planning
- Non Invasive Retinal Examination
- Reduced Patient Discomfort
- Improved Clinical Outcomes
- Childhood Retinal Disorder Imaging
- Retinal Vein Occlusion
- Vascular Retinal Imaging Systems
- Enhanced Blood Flow Assessment
- Improved Disease Monitoring
- High Contrast Retinal Analysis
- Vascular Retinal Imaging Systems
- Ocular Oncology
- Retinal Tumor Imaging Platforms
- Widefield Cancer Monitoring Systems
- Uveitis
- Inflammatory Retinal Imaging
- Advanced Ocular Inflammation Analysis
- Chorioretinal Disease
- Retinal Layer Imaging Systems
- Widefield Chorioretinal Monitoring
- Glaucoma
- Optic Nerve Imaging Systems
- Retinal Nerve Fiber Analysis
- Others
Widefield Imaging Systems Market Segmented by Modality:
- Standalone
- Fixed Ophthalmic Imaging Systems
- High Diagnostic Imaging Capacity
- Enhanced Clinical Workflow
- Hospital Based Imaging Platforms
- Advanced Multi Patient Screening
- Improved Data Integration
- Fixed Ophthalmic Imaging Systems
- Portable
- Handheld Retinal Imaging Devices
- Improved Remote Eye Screening
- Enhanced Rural Healthcare Access
- Mobile Ophthalmic Imaging Systems
- Point Of Care Diagnostic Capability
- Improved Patient Convenience
- Handheld Retinal Imaging Devices
Widefield Imaging Systems Market Segmented by End User:
- Hospitals
- Multi Specialty Hospitals
- Comprehensive Ophthalmic Diagnostics
- Enhanced Critical Care Support
- Tertiary Care Eye Hospitals
- Advanced Surgical Planning Support
- Improved Clinical Coordination
- Multi Specialty Hospitals
- Specialty Clinics
- Ophthalmology Specialty Centers
- Advanced Retinal Disease Diagnosis
- Improved Outpatient Screening
- Private Eye Care Clinics
- Enhanced Patient Accessibility
- Improved Imaging Efficiency
- Ophthalmology Specialty Centers
- Ambulatory Surgical Centers
- Outpatient Eye Surgery Centers
- Improved Pre Surgical Assessment
- Enhanced Workflow Efficiency
- Minimally Invasive Ophthalmic Facilities
- Rapid Patient Turnaround
- Improved Diagnostic Accessibility
- Outpatient Eye Surgery Centers
Widefield Imaging Systems Market Segmented by Technology:
- Optical Coherence Tomography Integration
- OCT Widefield Imaging Systems
- Enhanced Retinal Layer Visualization
- Improved Diagnostic Precision
- AI Assisted OCT Analysis
- Automated Disease Detection Support
- Improved Clinical Workflow Efficiency
- OCT Widefield Imaging Systems
- Fluorescein Angiography Imaging
- Retinal Blood Flow Imaging Systems
- Enhanced Vascular Disorder Detection
- Improved Disease Monitoring
- Widefield Angiography Platforms
- Accurate Peripheral Retina Analysis
- Enhanced Treatment Planning
- Retinal Blood Flow Imaging Systems
- Scanning Laser Ophthalmoscopy
- High Resolution Retinal Scanning
- Enhanced Peripheral Retina Visualization
- Improved Image Clarity
- Multimodal Ophthalmic Imaging Systems
- Comprehensive Eye Disease Assessment
- Enhanced Diagnostic Capability
- High Resolution Retinal Scanning
Widefield Imaging Systems Market by Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- International Diabetes Federation. (2025). Global Diabetes Prevalence and Screening Infrastructure.
- Carl Zeiss Meditec AG / ZEISS Medical Technology. (2025). Zeiss to Showcase Advancements in Ophthalmic Visualization and Digital Workflow at AAO 2025.Topcon Corporation. (2025). AI-Integrated Retinal Screening Platform Update.
- NHS England. (2025). Diabetic Eye Screening Programme Equipment Standards.
- Topcon Healthcare. (2025). Topcon Healthcare, Inc. Acquires RetInSight GmbH to Accelerate its AI-Powered Imaging Innovation in Eye Care.
- Optos (a Nikon company. (2025). Ultra-Widefield Retinal Imaging Clinical Adoption Report.
- Ayushman Bharat Digital Mission India. (2025). Diagnostic Screening Coverage Expansion.
- National Health Commission of China. (2025). Hospital Ophthalmology Department Standards.
- Pharmaceutical and Medical Devices Agency Japan. (2025). Ophthalmic Device Approval Guidance.
- European Medicines Agency. (2025). EU MDR Diagnostic Imaging Device Compliance.
This bibliography uses primary government and standards-body sources. Company sources are included.
This Report Answers
- What is the estimated 2026 value of the widefield imaging systems market?
- What market value is projected by 2036?
- What CAGR is forecast from 2026 to 2036?
- Which component is expected to account for a notable 2026 share?
- Which countries are profiled for CAGR comparison?
- Which companies are notable in the competitive landscape?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Component, 2026 to 2036
- Instrument
- Standalone Widefield Imaging Devices
- Portable Retinal Imaging Instruments
- Software
- AI Based Imaging Analysis Software
- Cloud Integrated Imaging Platforms
- Instrument
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Indication, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Indication, 2026 to 2036
- Diabetic Retinopathy
- Diabetic Eye Disease Monitoring
- AI Assisted Retinopathy Screening
- Retinopathy Of Prematurity
- Neonatal Retinal Screening Systems
- Portable NICU Imaging Solutions
- Pediatric Retinal Diseases
- Childhood Retinal Disorder Imaging
- Non Invasive Retinal Examination
- Retinal Vein Occlusion
- Vascular Retinal Imaging Systems
- High Contrast Retinal Analysis
- Ocular Oncology
- Retinal Tumor Imaging Platforms
- Widefield Cancer Monitoring Systems
- Uveitis
- Inflammatory Retinal Imaging
- Advanced Ocular Inflammation Analysis
- Chorioretinal Disease
- Retinal Layer Imaging Systems
- Widefield Chorioretinal Monitoring
- Glaucoma
- Optic Nerve Imaging Systems
- Retinal Nerve Fiber Analysis
- Others
- Diabetic Retinopathy
- Y-o-Y Growth Trend Analysis By Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Modality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Modality, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Modality, 2026 to 2036
- Standalone
- Fixed Ophthalmic Imaging Systems
- Hospital Based Imaging Platforms
- Portable
- Handheld Retinal Imaging Devices
- Mobile Ophthalmic Imaging Systems
- Standalone
- Y-o-Y Growth Trend Analysis By Modality, 2021 to 2025
- Absolute $ Opportunity Analysis By Modality, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- Hospitals
- Multi Specialty Hospitals
- Tertiary Care Eye Hospitals
- Specialty Clinics
- Ophthalmology Specialty Centers
- Private Eye Care Clinics
- Ambulatory Surgical Centers
- Outpatient Eye Surgery Centers
- Minimally Invasive Ophthalmic Facilities
- Hospitals
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Technology, 2026 to 2036
- Optical Coherence Tomography Integration
- OCT Widefield Imaging Systems
- AI Assisted OCT Analysis
- Fluorescein Angiography Imaging
- Retinal Blood Flow Imaging Systems
- Widefield Angiography Platforms
- Scanning Laser Ophthalmoscopy
- High Resolution Retinal Scanning
- Multimodal Ophthalmic Imaging Systems
- Optical Coherence Tomography Integration
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Indication
- By Modality
- By End User
- By Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Carl Zeiss Meditec AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Topcon Corporation
- NIDEK Co., Ltd.
- Optos (a Nikon company)
- Heidelberg Engineering GmbH
- Visunex Medical Systems, Inc.
- Clarity Medical Systems, Inc.
- Centervue SpA
- Daytona Optomap
- Ziemer Ophthalmic Systems AG
- Others
- Carl Zeiss Meditec AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Technology, 2021 to 2036
- Table 43: Middle East & Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East & Africa Market Value (USD Million) Forecast by Component, 2021 to 2036
- Table 45: Middle East & Africa Market Value (USD Million) Forecast by Indication, 2021 to 2036
- Table 46: Middle East & Africa Market Value (USD Million) Forecast by Modality, 2021 to 2036
- Table 47: Middle East & Africa Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 48: Middle East & Africa Market Value (USD Million) Forecast by Technology, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component
- Figure 6: Global Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Indication
- Figure 9: Global Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Modality
- Figure 12: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End User
- Figure 15: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Technology
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East & Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Component
- Figure 32: North America Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Indication
- Figure 35: North America Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Modality
- Figure 38: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End User
- Figure 41: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Technology
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Component
- Figure 48: Latin America Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Indication
- Figure 51: Latin America Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Modality
- Figure 54: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End User
- Figure 57: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Technology
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Component
- Figure 64: Western Europe Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Indication
- Figure 67: Western Europe Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Modality
- Figure 70: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End User
- Figure 73: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Technology
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Component
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Indication
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Modality
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End User
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Component
- Figure 96: East Asia Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Indication
- Figure 99: East Asia Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Modality
- Figure 102: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End User
- Figure 105: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Technology
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Component
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Indication
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Modality
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 124: Middle East & Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East & Africa Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 126: Middle East & Africa Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 127: Middle East & Africa Market Attractiveness Analysis by Component
- Figure 128: Middle East & Africa Market Value Share and BPS Analysis by Indication, 2026 and 2036
- Figure 129: Middle East & Africa Market Y-o-Y Growth Comparison by Indication, 2026-2036
- Figure 130: Middle East & Africa Market Attractiveness Analysis by Indication
- Figure 131: Middle East & Africa Market Value Share and BPS Analysis by Modality, 2026 and 2036
- Figure 132: Middle East & Africa Market Y-o-Y Growth Comparison by Modality, 2026-2036
- Figure 133: Middle East & Africa Market Attractiveness Analysis by Modality
- Figure 134: Middle East & Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 135: Middle East & Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 136: Middle East & Africa Market Attractiveness Analysis by End User
- Figure 137: Middle East & Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 138: Middle East & Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 139: Middle East & Africa Market Attractiveness Analysis by Technology
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Widefield Imaging Systems Market in 2026?
The Widefield Imaging Systems Market is valued at USD 785.1 million in 2026 and is forecast to reach USD 1341.1 million by 2036, expanding at a 5.5% CAGR. The Widefield Imaging Systems Market grew from USD 744.2 million in 2025, with Instrument holding 71.0% of component demand in 2026.
What is the CAGR of the Widefield Imaging Systems Market from 2026 to 2036?
The Widefield Imaging Systems Market is projected to grow at a CAGR of 5.5% between 2026 and 2036, supported by rising diabetic retinopathy prevalence and increasing adoption of widefield imaging for peripheral retinal assessment. Instrument holds 71.0% of Widefield Imaging Systems Market component demand in 2026, while Diabetic Retinopathy leads indication with 33.6% in 2026.
Which component leads the Widefield Imaging Systems Market?
Instrument accounts for 71.0% of the Widefield Imaging Systems Market by component in 2026, driven by rising diabetic retinopathy prevalence and increasing adoption of widefield imaging for peripheral retinal assessment. The Widefield Imaging Systems Market is valued at USD 785.1 million in 2026 and grows at a 5.5% CAGR through 2036, while Diabetic Retinopathy leads indication with 33.6% in 2026.
How much will the Widefield Imaging Systems Market add between 2026 and 2036?
The Widefield Imaging Systems Market is set to add USD 556.0 million between 2026 and 2036, growing from USD 785.1 million to USD 1341.1 million at a 5.5% CAGR. Diabetic Retinopathy leads indication with 33.6% of Widefield Imaging Systems Market revenue in 2026, anchoring that incremental demand.
Who are the leading companies in the Widefield Imaging Systems Market?
The Widefield Imaging Systems Market profiles 8 key companies in 2026, led by Carl Zeiss Meditec AG, Topcon Corporation, NIDEK Co., Ltd., Optos plc, and Heidelberg Engineering GmbH. These suppliers compete across component, where Instrument holds 71.0% of Widefield Imaging Systems Market demand in 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
