
- Market Size (2026)
- USD 118.0 Bn
- Forecast (2036)
- USD 195.9 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Yogurt Market in 2026?
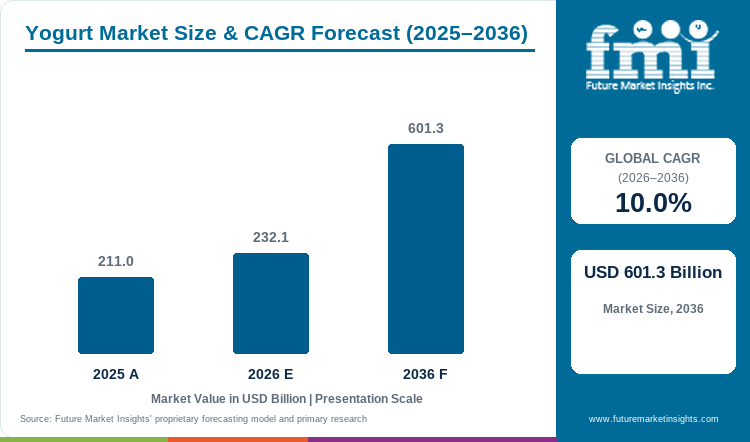
Sales in the yogurt market are projected to grow at 5.2% CAGR, with market valuation rising from USD 112.2 billion in 2025 to USD 118.0 billion in 2026 and reaching USD 195.9 billion by 2036.
Fermented milk processing has become a central volume anchor for commercial creameries as plants convert fluid milk into cultured foods that retain bioavailable calcium and native casein protein. In March 2025, the International Dairy Federation reported that global commercial fermented milk output reached 86.0 million metric tons [1]. According to Future Market Insights analysis, global yogurt sales rise from USD 112.2 billion in 2025 to USD 118.0 billion in 2026 and are projected to reach USD 195.9 billion by 2036, advancing at a 5.2% CAGR from 2026 to 2036 and adding USD 77.9 billion in new revenue. Dairy milk holds 55.9% of source demand in 2026, though cold-chain electricity tariffs still squeeze plant margins.
Key Market Trends & Insights
- By source: Dairy milk led the market with a share of 55.9% in 2026, as native casein micelles and lactose sugars support uniform acid coagulation in commercial vats.
- By flavor / type: Strained Greek and skyr accounted for 40.2% of volume in 2026, reflecting strong household preference for dense, protein-concentrated breakfast servings.
- By distribution channel: Supermarkets and hypermarkets held 37.9% of revenue in 2026, underpinned by multi-deck refrigerated dairy aisles and high weekly grocery footfall.
- By form: With a 33.3% share in 2026, spoonable cups and tubs led the category because single-serve thermoformed cups prevent whey separation during household storage.
Regional Highlights
- Fastest-growing evaluated country: Italy, at 6.3% CAGR from 2026 to 2036.
- By country: Denmark at 5.8%, Canada at 5.4%, the USA at 5.0%, and Australia at 4.6% follow, while Germany records the lowest evaluated CAGR at 4.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Yogurt Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 112.2 billion |
| Estimated Market Size in 2026 | USD 118.0 billion |
| Projected Market Size by 2036 | USD 195.9 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 77.9 billion |
Dairy cooperatives in Denmark and Germany operate under strict farm nitrogen ceilings and returnable-jar retail mandates, whereas Italian and American creameries focus on strained Greek-style vats and high-protein drinkable bottles. Commercial formulators are replacing gelatin and modified starch thickeners with membrane ultrafiltration and fermented dairy ingredients to satisfy clean-label supermarket specifications. In May 2025, the European Food Safety Authority updated its Qualified Presumption of Safety biological agent registry for lactic acid bacteria used in commercial dairy vats [2]. Owing to these microbial safety standards, regional creameries are adopting direct-vat freeze-dried inoculants that keep curd acidity and viscosity uniform across extended retail storage.
Fermentation Processing and Bioactive Culture Metrics
Table 2: Fermentation Processing and Bioactive Culture Metrics for the Yogurt Market (USD billion and operational metrics), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 112.2 | 118.0 | 195.9 |
| Global Yogurt Production Volume (million metric tons) | 46.2 | 48.5 | 74.0 |
| Average Live Colony Forming Units per Gram (billion CFU) | 1.0 to 2.5 | 1.2 to 3.0 | 2.5 to 5.0 |
| Fermentation Incubation Duration Range (hours) | 6.5 to 8.5 | 6.0 to 8.0 | 4.5 to 6.5 |
Commercial creamery vats track colony density and incubation hours across spoonable cups, drinkable bottles, and bulk foodservice tubs to maintain uniform lactic acidity.
Per Capita Intake & Retail Channel Penetration Sizing
Cultured dairy foods have gained wide acceptance in household diets because they supply bioavailable calcium and live digestive cultures in ready-to-eat portions. Supermarkets allocate prime chilled shelf space to strained Greek yogurt and Icelandic skyr tubs that deliver fifteen to twenty grams of protein per serving. Besides this, institutional foodservice operators procure bulk plain yogurt for breakfast parfaits and savory culinary dressings.
Table 3: Per Capita Intake and Commercial Spending Indicators for the Yogurt Market (USD, kilograms, and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Developed Market Per Capita Consumption (kilograms per year) | 14.8 | 15.3 | 20.1 |
| Annual Yogurt Expenditure per Urban Household (USD) | 112.5 | 118.2 | 168.4 |
| High-Protein Greek Segment Share of Total Volume (%) | 38.5% | 40.2% | 51.5% |
| Cold-Chain Logistics Cost Share of Retail Price (%) | 14.2% to 16.8% | 14.5% to 17.2% | 13.0% to 15.5% |
Table 4: Facility & Dairy Plant Operational Spending Indicators for the Yogurt Market (USD and metric units), mixed reporting years from 2024 to 2026
| Operational Spend Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Raw Farmgate Milk Procurement Cost per Liter (USD) | 0.4 to 0.5 | 0.5 to 0.6 | 0.5 to 0.6 |
| Industrial Separator Capital Expenditure per Line (USD million) | 1.8 to 2.6 | 1.9 to 2.8 | 2.1 to 3.0 |
| Live Starter Culture Cost per Batch (USD) | 420.0 to 650.0 | 450.0 to 700.0 | 480.0 to 750.0 |
| Sustainable Thermoformed Cup Cost per Thousand Units (USD) | 38.0 to 52.0 | 42.0 to 58.0 | 44.0 to 62.0 |
Analyst Perspective
"Concentrated strained curd formats and clean-label active cultures allow dairies to expand unit value across refrigerated retail aisles. Cold-chain energy expenses and batch whey separation still require tighter ultrafiltration control before wider regional rollout."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the yogurt market segmented?
The yogurt market is segmented by form, source, distribution channel, flavor / type, and region. In 2026, dairy milk is projected at 55.9% of source demand, strained Greek and skyr at 40.2% of flavor / type, supermarkets and hypermarkets at 37.9% of distribution channel, and spoonable cups and tubs at 33.3% of form.
By form: Spoonable cups & tubs, drinkable bottles & pouches, set & strained tubs, and frozen yogurt.
By source: Conventional bovine (cow) milk dairy, specialty A2 cow & goat milk dairy, and plant-based / dairy-free milk alternatives.
By distribution channel: Supermarkets & hypermarkets, convenience stores, online retail & direct delivery, and specialty food stores.
By flavor / type: Strained Greek & skyr, plain / unflavored, and flavored & fruit-blended.
Why does Dairy Milk lead the source category?
Dairy milk is expected to account for 55.9% of source demand in 2026, supported by native casein protein density.
Table 5: Source Share for the Yogurt Market (percentage share), 2026
| Source | Share (2026) |
|---|---|
| Dairy Milk | 55.9% |
| Other Segments Combined | 44.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Source Leadership and Market Growth for the Yogurt Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Dairy Milk |
Conventional cow milk remains the foundational input for commercial vats because natural lactose disaccharides feed bacterial starter cultures without requiring added sugar dosing during incubation. As lactic acid accumulates in the vat, the pH drops toward the isoelectric point of casein and creates a firm protein gel that traps serum moisture. In addition to this, cow milk supplies complete amino acids and natural milkfat globules that prevent chalky mouthfeel in strained cups. Plant-based oat and almond bases require hydrocolloid gums and pectin stabilizers to build comparable viscosity, which raises ingredient formulation costs and lengthens retail ingredient labels.
- Dairy milk is expected to account for 55.9% of source revenue in 2026, supported by native casein micelle coagulation and established farmgate milk collection.
- In April 2026, the USDA National Agricultural Statistics Service reported that U.S. commercial yogurt production totaled 4.78 billion pounds during the 2025 calendar year [3].
What supports Supermarkets & Hypermarkets leadership in distribution channel?
Supermarkets and hypermarkets are projected to capture 37.9% of distribution channel sales in 2026, underpinned by multi-tier chilled display aisles.
Unbroken refrigeration between two and four degrees Celsius from filling line to household checkout keeps retail yogurt volume concentrated inside large grocery chains. Supermarkets operate continuous glass-door dairy vaults that display single-serve cups beside family-sized tubs and fermented dairy products. Owing to high weekly shopper traffic, supermarkets rotate chilled inventory rapidly and minimize expiration write-offs across fruit and strained SKUs. Convenience stores and direct home delivery routes face steeper last-mile insulated packaging expenses, which restricts their refrigerated dairy assortment to fast-moving drinkable bottles and single-serve snack packs.
- Supermarkets and hypermarkets are projected to capture 37.9% of distribution channel demand in 2026, underpinned by dedicated cold-chain display capacity and multi-pack promotions.
- In March 2025, the Food and Agriculture Organization updated its Codex Alimentarius fermented milk distribution guidance to standardize cold-chain labeling for retail dairy cases [4].
How do Spoonable Cups & Tubs maintain the leading position by form?
Spoonable cups and tubs are estimated to represent 33.3% of form demand in 2026, reflecting portioned household breakfast convenience.
Set and strained curds hold much higher viscosity than pumpable liquids, making wide-mouth thermoformed cups and family tubs the primary packaging format across dairy plants. High-speed form-fill-seal lines dose fruit prep layers and flavored yogurt cups under nitrogen-flushed foil lids, protecting live bacterial cultures from oxygen exposure during warehouse storage. Furthermore, rigid polypropylene cups wrapped in separable paperboard sleeves prevent physical crushing on stacked pallets. This structural rigidity prevents curd cracking and reduces surface whey pooling before the consumer opens the lid at home.
- Spoonable cups and tubs are estimated to represent 33.3% of form revenue in 2026, reflecting widespread household breakfast and snacking routines.
- In July 2025, the European Dairy Association documented that European creameries upgraded high-speed thermoforming filling lines to cut packaging film weight by 18% [5].
What are the drivers, restraints, and opportunities in the yogurt market?
In the yogurt market, clinical microbiome validation supports daily fermented dairy intake, refrigerated energy and milk price swings constrain plant margins, and high-protein lactose-free ultrafiltration creates premium retail value through 2036.
- Driver:Household shift toward gut microbiome maintenance and high-protein breakfast replacement will continue to expand fermented dairy volume through 2036.
- Restraint:Refrigerated transport electricity costs and seasonal farmgate milk price swings will continue to compress processor operating margins through 2036.
- Opportunity:Membrane ultrafiltration for high-protein, lactose-free strained recipes is expected to unlock higher per-cup margins across retail grocers through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Preventive digestive healthcare has shifted consumer grocery spending toward foods carrying live bacterial cultures rather than synthetic vitamin tablets. Urban households increasingly purchase probiotic yogurt formulations as a daily breakfast staple to maintain intestinal flora and morning satiety. In April 2025, a randomized clinical nutrition trial in the American Journal of Clinical Nutrition reported that adults consuming two daily servings of live fermented yogurt recorded a 24% increase in beneficial gut bifidobacteria diversity [6]. Owing to this clinical evidence, dairy brands are printing specific strain counts and colony guarantees on cup lids. Processors must verify colony survival through the final day of refrigerated shelf life before retailers approve premium slotting.
Risk Assessment of the Yogurt Market: Operational and Formulation Friction
Maintaining uninterrupted two-to-four-degree Celsius storage from creamery vat to grocery checkout creates heavy energy and spoilage exposure for commercial dairy processors. When chilled trucks experience temperature drift during summer transit, lactic cultures over-acidify the curd and force liquid whey to pool on top of the cup. In September 2025, the European Commission Milk Market Observatory reported that European raw milk spot prices rose by 11.4% year-over-year while cold-storage electricity charges remained elevated [7]. In addition to this, upgrading dairy product packaging to recyclable mono-material polypropylene requires re-tooling heat-seal heads on filling lines, delaying capital payback for mid-sized regional creameries.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Dairy processors are capturing higher unit margins by combining membrane ultrafiltration with lactase enzyme hydrolysis to serve fitness-focused and lactose-sensitive shoppers at the same time. Conventional acid straining discards large volumes of acid whey, which creates wastewater disposal fees for creameries. In August 2025, a technical study in the International Journal of Dairy Technology demonstrated that closed-loop ceramic ultrafiltration skids raise native milk protein retention by 21% while cutting acid whey effluent in Greek yogurt plants [8]. Furthermore, pairing ultrafiltration with lactase dosing allows creameries to market lactose-free dairy products that taste naturally sweet without added cane sugar. Suppliers that validate zero-sugar, twenty-gram protein cups can secure national grocery distribution.
Yogurt Market by Country (2026 to 2036)
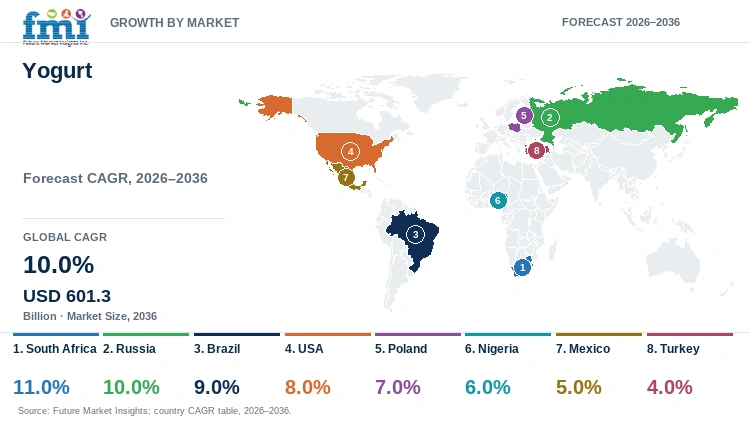
Strained Mediterranean breakfast tubs and organic cooperative skyr lines push Italy to a 6.3% CAGR and Denmark to 5.8% from 2026 to 2036, whereas discount-heavy grocery pricing keeps Germany at 4.2%. Local creameries across all six profiled markets are adapting cultured dairy products to regional milk quota rules and cold-chain transport distances.
Table 7: Country CAGR and Primary Growth Levers for the Yogurt Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Italy | 6.3% | Artisan strained Greek-style tubs and functional Mediterranean breakfast habits |
| Denmark | 5.8% | Cooperative organic milk pools and Nordic skyr fermentation technology |
| Canada | 5.4% | On-site membrane ultrafiltration under domestic milk supply management |
| USA | 5.0% | High-protein drinkable bottles and probiotic kefir aisle expansion |
| Australia | 4.6% | Pasture-fed clean-label positioning and chilled airfreight exports to Asia |
| Germany | 4.2% | High-speed private-label filling lines and paperboard-wrapped eco-cups |
Source: Future Market Insights analysis
Italy Yogurt Market Outlook (2026 to 2036)
Italian households have shifted morning eating habits from pastry breakfasts toward protein-rich strained dairy cups and probiotic drinks. Annual retail tracking by the Italian Dairy Association Assolatte in September 2025 showed that domestic yogurt and fermented milk sales exceeded EUR 1.9 billion as strained Greek-style volumes climbed by 9.4% [9]. Demand in the Italy yogurt market is projected to rise at 6.3% CAGR through 2036, propelled by artisan regional fruit preparations and adult digestive wellness positioning. However, fragmented cold-chain distribution across southern peninsula provinces increases refrigerated trucking rates for northern alpine creameries. Domestic producers counter this friction by operating regional cross-docking cold depots and sourcing protected-origin citrus purees.
Key takeaway:Italian creameries rely on strained Greek-style tubs and protected-origin fruit preparations to sustain category growth despite southern cold-transport costs.
Denmark Yogurt Market Outlook (2026 to 2036)
The Denmark yogurt market is anticipated to grow at 5.8% CAGR between 2026 and 2036, underpinned by farmer-owned organic milk cooperatives and Nordic skyr culture engineering. Unlike markets reliant on conventional confinement dairies, Danish processors draw on certified organic pasture farms that command strong retail trust. In June 2025, the Danish Agriculture and Food Council documented that organic milk accounted for 32.0% of national dairy reception across Danish cooperative plants [10]. High baseline per-capita dairy intake limits pure volume expansion, and strict national farm nitrogen ceilings cap herd growth. Danish creameries protect revenue growth by exporting concentrated skyr cultures and carbon-audited cups across neighboring European supermarket chains.
Key takeaway:Certified organic milk pools and proprietary skyr culture exports allow Danish cooperatives to offset domestic volume maturity and farm emission limits.
Canada Yogurt Market Outlook (2026 to 2036)
Canadian dairy processors operate within a federal supply management framework that fixes industrial milk prices and restricts duty-free dairy solids imports. In October 2025, the Canadian Dairy Information Centre reported that commercial dairies processed 9.6 million hectoliters of fluid milk while increasing allocation to cultured yogurt vats [11]. Adoption of yogurt in Canada is estimated to expand at 5.4% CAGR through 2036, supported by household demand for zero-sugar strained tubs. Tariff-rate quotas prevent compounders from importing cheap foreign milk protein concentrates to boost batch yields. Consequently, plants in Quebec and Ontario are installing domestic ceramic ultrafiltration skids to concentrate local skim milk on site.
Key takeaway:On-site milk ultrafiltration enables Canadian creameries to expand high-protein Greek and skyr lines within federal dairy import quotas.
USA Yogurt Market Outlook (2026 to 2036)
Retail grocery aisles in the United States are reshaping around high-protein drinkable yogurt bottles tailored for commuters and users of metabolic weight-management therapies who need nutrient-dense mini meals. Sales of yogurt in the USA are forecast to expand at 5.0% CAGR through 2036, reinforced by updated federal identity standards that allow flexible milkfat and ultrafiltered milk fortification. Modernized yogurt standard of identity rules enforced by the U.S. Food and Drug Administration in February 2026 streamlined milkfat and ultrafiltration compliance across commercial interstate dairy plants [12]. Intense private-label price competition in big-box grocers still squeezes margins on conventional fruit cups, prompting national brands to focus on lactose-free twenty-gram protein shakes.
Key takeaway:Modernized federal identity standards and twenty-gram drinkable protein shakes help U.S. brands defend margins against private-label supermarket cups.
Australia Yogurt Market Outlook (2026 to 2036)
Pasture-based milk sourcing and proximity to affluent Southeast Asian import hubs distinguish Australian yogurt manufacturing from northern hemisphere feedlot models. In August 2025, Dairy Australia reported that national milk production reached 8.4 billion liters during the 2024 to 2025 season as cultured dairy processors expanded chilled export shipments [13]. Between 2026 and 2036, the Australia yogurt market is expected to progress at 4.6% CAGR, aided by grass-fed pasture branding and gourmet culinary pouch formats. However, recurring rainfall variability across Victoria and New South Wales raises seasonal irrigation and feed costs for dairy farmers. Processors mitigate raw milk swings through multi-region farm supply pools and high-margin airfreight exports to Singapore.
Key takeaway:Australian processors leverage grass-fed pasture credentials to expand domestic culinary pouch sales and chilled airfreight exports across Southeast Asia.
Germany Yogurt Market Outlook (2026 to 2036)
Germany processes the largest raw milk pool in the European Union, but heavy retail concentration among hard-discount supermarket chains keeps unit prices tightly capped. In December 2025, the Federal Ministry of Food and Agriculture reported that German dairies processed 33.0 million metric tons of raw milk while expanding organic and lactose-free cultured lines [14]. The Germany yogurt sector is projected to record 4.2% CAGR during the assessment period, driven by automated private-label production and mandatory VerpackG recyclable packaging compliance. Because discount retailers resist wholesale price hikes on standard fruit cups, German dairy cooperatives are shifting toward paperboard-sleeved 500-gram returnable glass jars and high-protein quark-yogurt hybrids.
Key takeaway:Returnable 500-gram glass jars and quark-yogurt hybrids allow German dairy cooperatives to protect margins inside a discount-dominated retail sector.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the yogurt market?
Danone S.A., Chobani LLC, General Mills, Inc., Fage International S.A., Lactalis Group, Nestlé S.A., Arla Foods amba, Müller Group, Yakult Honsha Co., Ltd., and Fonterra Co-operative Group Limited are the notable companies in this market.
Retail dairy category buyers source fermented lines from multinational packaged-food corporations, farmer-owned dairy cooperatives, and strained-curd specialists. Global food groups operate multi-country fermentation complexes and refrigerated distribution fleets that replenish national grocery chains daily. Strained-yogurt producers focus on centrifugal whey separation and membrane ultrafiltration to deliver thick, clean-label protein tubs without stabilizer gums. Farmer-owned cooperatives connect raw milk collection directly with certified organic and carbon-audited processing lines, while probiotic beverage specialists market proprietary bacterial strain banks.
- Multinational Cultured-Dairy Platforms: Danone S.A., Lactalis Group, Nestlé S.A., General Mills, Inc., and Müller Group operate multi-regional filling plants and broad retail brand portfolios.
- Strained Greek and Probiotic Specialists: Chobani LLC, Fage International S.A., and Yakult Honsha Co., Ltd. focus on high-protein strained curds and clinically documented probiotic beverages.
- Farmer-Owned Cooperative Processors: Arla Foods amba and Fonterra Co-operative Group Limited link direct farmgate milk pools with organic skyr and cultured dairy ingredient production.
Competitive Benchmarking: Yogurt Market
Table 8: Competitive Benchmarking for the Yogurt Market (qualitative capability ratings), 2026
| Company | Strained & Probiotic Breadth | Ultrafiltration & Culture Depth | Retail Cold-Chain Access | Geographic Reach |
|---|---|---|---|---|
| Danone S.A. | High | High | High | High |
| Chobani LLC | High | High | High | Medium |
| General Mills, Inc. | High | Medium | High | High |
| Fage International S.A. | High | High | High | Medium |
| Lactalis Group | High | Medium | High | High |
| Nestlé S.A. | Medium | High | High | High |
| Arla Foods amba | High | High | High | Medium |
| Müller Group | High | Medium | High | Medium |
| Yakult Honsha Co., Ltd. | Medium | High | High | High |
| Fonterra Co-operative Group | Medium | High | Medium | High |
Scoring basis: Table 8 evaluates documented dairy processing capabilities across four operational dimensions. Producers offering spoonable, strained, and drinkable lines simultaneously receive High for Strained & Probiotic Breadth. Proprietary bacterial strain banks or closed-loop membrane filtration earn High under Ultrafiltration & Culture Depth, while direct supermarket cold-vault delivery and multi-continent plant networks determine Retail Cold-Chain Access and Geographic Reach.
Key Developments in the Yogurt Market
- In February 2026, Danone S.A. commissioned automated membrane ultrafiltration lines across its European fermented dairy plants to expand twenty-gram protein Oikos and Activia production [15].
- In October 2025, Lactalis Group completed the integration of acquired regional organic cultured-dairy facilities to scale grass-fed and skyr cup distribution across North America and Europe [17].
- In June 2025, Chobani LLC expanded high-speed aseptic and chilled bottling capacity in New York and Idaho for zero-sugar, lactose-free drinkable Greek yogurt shakes [16].
Key Players in the Yogurt Market
Multinational Cultured-Dairy Platforms
- Danone S.A.
- Lactalis Group
- Nestlé S.A.
- General Mills, Inc.
- Müller Group
Strained Greek and Probiotic Specialists
- Chobani LLC
- Fage International S.A.
- Yakult Honsha Co., Ltd.
Farmer-Owned Cooperative Processors
- Arla Foods amba
- Fonterra Co-operative Group Limited
Yogurt Market - Report Scope
Table 9: Report Scope for the Yogurt Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; Source; Distribution Channel; Flavor / Type; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from spoonable, drinkable, and frozen yogurts, strained Greek yogurts, and skyr produced from conventional cow dairy milk, specialty A2 cow and goat milk, and certified plant-based non-dairy milks. Excludes unfermented fluid table milk, butter, and raw cheese curds. Source Taxonomy Note: The source axis provides a mutually exclusive classification distinguishing conventional bovine milk dairy, specialty A2 and caprine/ovine dairy, and non-dairy plant-based cultured alternatives. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Italy, Denmark, Canada, USA, Australia, Germany, and additional countries in the full report |
| Key Companies Covered | Danone S.A., Chobani LLC, General Mills, Inc., Fage International S.A., Lactalis Group, Nestlé S.A., Arla Foods amba, Müller Group, Yakult Honsha Co., Ltd., Fonterra Co-operative Group Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Yogurt Market - Research Methodology
Table 10: Research Methodology for the Yogurt Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial dairy plant directors, fermentation microbiologists, starter-culture suppliers, cold-chain logistics managers, and grocery category buyers to validate yield ratios, culture stability, and retail pricing. |
| Secondary Research | Secondary research covered International Dairy Federation bulletins, USDA National Agricultural Statistics Service releases, European Food Safety Authority scientific opinions, FAO Codex standards, national dairy association reports, and corporate disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined top-down raw milk allocation balances with bottom-up retail scanner volume and foodservice procurement across evaluated countries. |
| Data Triangulation and Validation | Estimates were cross-checked against commercial dairy herd output, ultrafiltration capacity additions, cold-storage energy indices, and household dietary expenditure surveys to prevent double counting. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's cultured dairy econometric model, calibrating evaluated national growth rates against the 5.2% global baseline through verified probiotic yogurt per-capita intake, Greek strained yogurt breakfast substitution, and supermarket chilled dairy grab-and-go case expansion. |
| Operational Benchmark Traceability | Operational benchmarks (global yogurt production volume, live starter culture CFU inoculations, and ultrafiltration whey separation yields) represent modeled estimates synthesized from USDA NASS dairy reports, EFSA qualified presumption of safety lists, Codex Standard CXS 243, and commercial creamery disclosures. |
Yogurt Market by Segments
Yogurt Market segmented by Form:
- Spoonable Cups & Tubs
- Drinkable Bottles & Pouches
- Set & Strained Tubs
- Frozen Yogurt
Yogurt Market segmented by Source:
- Conventional Bovine (Cow) Milk Dairy
- Plant-Based / Dairy-Free Milk Alternatives
- Specialty A2 Cow & Goat Milk Dairy
Yogurt Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores
- Online Retail & Direct Delivery
- Specialty Food Stores
Yogurt Market segmented by Flavor / Type:
- Strained Greek & Skyr
- Plain / Unflavored
- Flavored & Fruit-Blended
Yogurt Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- Italy
- France
- United Kingdom
- Denmark
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Dairy Federation. (2025, March 18). The World Dairy Situation: Global production and consumption of fermented milk products. IDF Bulletin No. 528/2025.
- [2] European Food Safety Authority. (2025, May 14). Scientific opinion on the maintenance of the list of QPS-recommended biological agents intentionally added to food. EFSA Journal, 23(5), 8872.
- [3] United States Department of Agriculture. (2026, April 24). Dairy products 2025 annual summary: Commercial yogurt and cultured dairy manufacturing. USDA National Agricultural Statistics Service Report Da 2-1(26).
- [4] Food and Agriculture Organization. (2025, March 20). Codex standard for fermented milks and retail cold-chain labeling. Codex Alimentarius Standard CXS 243.
- [5] European Dairy Association. (2025, July 11). Packaging efficiency and cold-chain compliance in European dairy processing facilities. EDA Technical Policy Bulletin, 19, 112-130.
- [6] American Journal of Clinical Nutrition. (2025, April 09). Daily consumption of live fermented dairy products and adult gut microbiome diversity: A randomized controlled trial. AJCN Research Articles, 121(4), 845-859.
- [7] European Commission. (2025, September 16). EU Milk Market Observatory: Raw milk spot pricing and dairy processing energy balances. DG Agriculture and Rural Development Market Observatory Report.
- [8] International Journal of Dairy Technology. (2025, August 22). Closed-loop ceramic membrane ultrafiltration advances in Greek yogurt manufacturing. IJDT Review Series, 78(3), 210-228.
- [9] Assolatte. (2025, September 19). Relazione annuale sull'industria lattiero-casearia italiana: Il mercato dello yogurt e dei latti fermentati. Assolatte Pubblicazioni Statistiche, 46, 55-74.
- [10] Danish Agriculture and Food Council. (2025, June 12). Dairy statistics and certified organic milk reception in Denmark. Landbrug & Fødevarer Annual Dairy Report, 28, 38-54.
- [11] Canadian Dairy Information Centre. (2025, October 15). Canadian dairy industry profile: Fluid milk intake and cultured vat allocation. CDIC Market Bulletin No. 2025-06.
- [12] United States Food and Drug Administration. (2026, February 10). Milk and cream products: Enforcement of modernized yogurt standard of identity. Federal Register Compliance Update, 91(28), 14205-14228.
- [13] Dairy Australia. (2025, August 27). Australian dairy industry in focus: Milk production volumes and chilled Asian export trade. Dairy Australia Annual Report, 22, 60-82.
- [14] Bundesministerium für Ernährung und Landwirtschaft. (2025, December 08). Milchwirtschaft in Deutschland: Erzeugung, Verarbeitung und Konsum von Molkereiprodukten. BMEL Statistischer Monatsbericht, 75(12), 102-125.
- [15] Danone S.A. (2026, February 18). Expansion of automated ultrafiltration lines for high-protein fermented dairy brands in Europe. Danone Corporate Press Releases.
- [16] Chobani LLC. (2025, June 24). Commissioning of high-speed bottling lines for zero-sugar drinkable Greek yogurt shakes. Chobani Newsroom Announcements.
- [17] Lactalis Group. (2025, October 29). Integration of regional organic cultured-dairy plants across North America and Europe. Lactalis Corporate Communications.
- [18] Arla Foods amba. (2025, August 14). Rollout of recyclable paperboard-wrapped skyr and protein tubs across European retail. Arla Foods Cooperative News.
- [19] Fage International S.A. (2025, November 06). Strained Greek yogurt capacity expansion at Luxembourg and United States creameries. Fage Investor Relations Disclosures.
- [20] General Mills, Inc. (2026, January 21). Portfolio reformulation of Yoplait and Liberté lines with elevated protein and natural fruit sweetening. General Mills Corporate Releases.
- [21] Fonterra Co-operative Group Limited. (2025, July 17). Pasture-raised cultured dairy ingredient and probiotic strain commercialization update. Fonterra Co-operative Reports.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the global yogurt market in 2026 and what is forecast for 2036?
- How does ceramic membrane ultrafiltration improve native protein retention and reduce acid whey effluent?
- Why does dairy milk command the largest share within the source category?
- What keeps supermarkets and hypermarkets ahead of alternative retail channels in 2026?
- How do growth rates and commercial drivers differ across Italy, Denmark, Canada, and the USA?
- Which multinational corporations, strained-curd specialists, and dairy cooperatives lead the market today?
- What operational and cold-chain constraints limit margin expansion in commercial creameries?
- What microbiological and packaging criteria should grocery buyers audit before qualifying a supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Spoonable Cups & Tubs
- Drinkable Bottles & Pouches
- Set & Strained Tubs
- Frozen Yogurt
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Conventional Bovine (Cow) Milk Dairy
- Plant-Based / Dairy-Free Milk Alternatives
- Specialty A2 Cow & Goat Milk Dairy
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores
- Online Retail & Direct Delivery
- Specialty Food Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor / Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor / Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor / Type, 2026 to 2036
- Strained Greek & Skyr
- Plain / Unflavored
- Flavored & Fruit-Blended
- Y-o-Y Growth Trend Analysis By Flavor / Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor / Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Italy
- France
- United Kingdom
- Denmark
- Spain
- Benelux
- Nordics
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Denmark
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Source
- By Distribution Channel
- By Flavor / Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Danone S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Chobani LLC
- General Mills, Inc.
- Fage International S.A.
- Lactalis Group
- Nestlé S.A.
- Arla Foods amba
- Müller Group
- Yakult Honsha Co., Ltd.
- Fonterra Co-operative Group
- Fonterra Co-operative Group Limited
- Danone S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Flavor / Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form
- Figure 6: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Source
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Flavor / Type
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Form
- Figure 29: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Flavor / Type
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Form
- Figure 42: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Source
- Figure 45: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 48: Latin America Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Flavor / Type
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Form
- Figure 55: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Source
- Figure 58: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 61: Western Europe Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Flavor / Type
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Form
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Source
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Flavor / Type
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Form
- Figure 81: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Source
- Figure 84: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 87: East Asia Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Flavor / Type
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Flavor / Type
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Flavor / Type, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor / Type, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Flavor / Type
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Yogurt Market expected to be in 2026?
Global yogurt sales are estimated at USD 118.0 billion in 2026, advancing from USD 112.2 billion in 2025, and are projected to reach USD 195.9 billion by 2036 as households adopt protein-concentrated cultured dairy cups.
What CAGR is forecast for the Yogurt Market through 2036?
As per FMI, the yogurt market is projected to expand at a 5.2% CAGR from 2026 to 2036, underpinned by everyday probiotic breakfast consumption and membrane-concentrated Greek and skyr lines.
Which source segment holds the leading yogurt demand share in 2026?
Dairy milk accounts for 55.9% of source demand in 2026 because native casein micelles coagulate cleanly during vat fermentation without requiring added hydrocolloid gums.
Which distribution channel leads retail yogurt sales in 2026?
Supermarkets and hypermarkets command 37.9% of distribution channel sales in 2026, supported by continuous multi-deck refrigerated dairy cases and rapid weekly inventory turnover.
Which country has the highest yogurt expansion outlook during the forecast period?
FMI finds that Italy is projected to register a 6.3% CAGR during the 2026 to 2036 assessment period, propelled by retail uptake of strained Greek-style tubs and regional Mediterranean fruit preparations.
Which companies are active in the Yogurt Market during 2026?
Key producers operating in the market include Danone S.A., Chobani LLC, General Mills, Inc., Fage International S.A., Lactalis Group, Nestlé S.A., Arla Foods amba, Müller Group, Yakult Honsha Co., Ltd., and Fonterra Co-operative Group Limited, with investments centered on membrane ultrafiltration and recyclable thermoformed cups.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
