
- Market Size (2026)
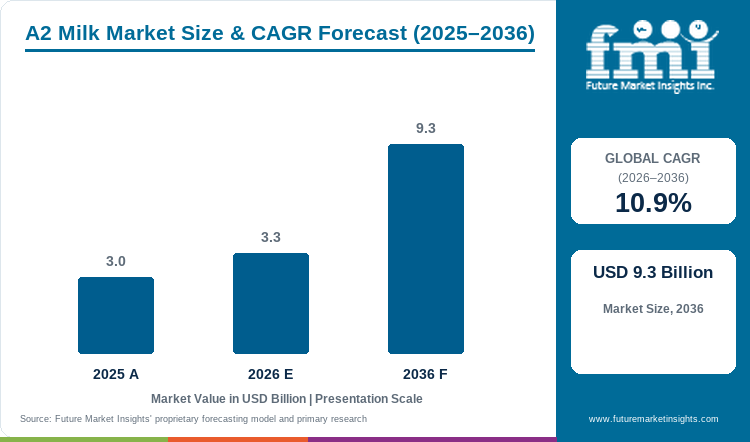
- USD 3.3 Bn
- Forecast (2036)
- USD 9.3 Bn
- CAGR (2026 to 2036)
- 10.9%
How big is the A2 Milk Market in 2026?
Demand for milk from cows carrying only the A2-type beta-casein gene should lift the A2 Milk Market to USD 9.3 billion by 2036. FMI values the market at USD 3.3 billion in 2026 and projects a CAGR of 10.9% between 2026 and 2036. The market was valued at USD 3.0 billion in 2025. Liquid products hold 84.0% by form in 2026. Conventional milk accounts for 92.0% by nature, and supermarkets and hypermarkets represent 66.0% by sales channel.
Shoppers pay more for differentiated milk while total milk drinking falls. The a2 Milk Company lifted liquid milk sales by 21.8% to NZD 421.9 million in fiscal 2026. The Milchindustrie-Verband recorded German drinking milk consumption of 45.1 kg per head in 2025, down from 49.6 kg in 2019. MAFF reported Japanese drinking milk output down 1.2% in fiscal 2025. A2 brands grow by gaining value share within a shrinking category.
Herd supply is the material restraint. Only cows with two copies of the A2 gene qualify, and the Bavarian State Research Center for Agriculture estimates that share at 38.0% of Fleckvieh cows and 42.0% of Holsteins. The a2 Milk Company offers a qualified example of supply investment. Its completion announcement confirms the purchase of an infant formula plant at Pokeno on 1 September 2025, and its FY25 results update sets out about NZD 100.0 million of planned upgrades. One plant does not prove global demand.
Key Market Trends & Insights
- A2 and lactose-free are converging on the same shopper. The a2 Milk Company launched a2 Milk Lactose Free in Coles stores in Western Australia during FY26 and reported a record 22.6% value share of the Australian lactose-free category. Brands that sell both claims in one carton compete directly with products covered in the lactose-free dairy products market.
- Clinical evidence is growing but remains modest. A randomised crossover trial of 48 adults who avoid milk found symptom scores below 1 out of 10 for all milks tested, with lower bloating after A2 milk than after lactose-free A2 milk on the first test day. An open-label trial of 997 Australian adults reported small mood and stool consistency differences and called for blinded replication. Marketing claims must therefore stay narrow, which limits how far brands can price above regular milk.
- Shelf-stable formats are extending reach. Moriyama Dairy lengthened the shelf life of its ambient A2 Hokkaido milk from 90 to 120 days from 1 March 2026. The a2 Milk Company reported 39.0% growth in emerging markets on higher UHT and milk powder volumes. Long-life packs let a certified milk pool serve markets that have no A2 herds of their own.
Regional Highlights
- In East Asia, A2 brands are growing against falling milk drinking. Japan's MAFF reported drinking milk output down 1.2% in fiscal 2025 and down 1.2% again in August 2026. South Korea counted 362,000 dairy cows at 1 September 2026, a 3.0% fall in a year. Processors in both countries need higher value per litre, which favours certified A2 lines over commodity milk.
- In North America, a national A2 brand has reached profitability while organic challengers enter. The a2 Milk Company grew USA revenue by 28.6% to NZD 179.0 million in FY26 and reached EBITDA breakeven in the second half. Clover Sonoma launched an organic A2 whole milk in Northern California in February 2025 at a suggested USD 7.49. The USDA expects 2026 US milk production of 236.9 billion pounds, so raw material is not the limit.
A2 Milk Market Size and Forecast
Table 1: A2 Milk Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 3.0 billion |
| Estimated market size in 2026 | USD 3.3 billion |
| Projected market size by 2036 | USD 9.3 billion |
| CAGR from 2026 to 2036 | 10.9% |
Source: Future Market Insights analysis of the A2 milk market, 2026.
Analyst Perspective
“Shoppers buy A2 milk when regular milk leaves them uncomfortable, and they judge it on taste and price against lactose-free milk on the same shelf. Suppliers separate themselves by proving that every litre comes from genotyped cows and by holding that proof through collection, processing and packing. The qualification risk is greatest at the farm, because a processor that cannot keep enough A2A2 cows in one collection route cannot hold a retail listing.”
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the A2 Milk Market segmented?
- By nature: Conventional and Organic.
- By form: Liquid and Powder.
- By sales channel: Supermarkets and Hypermarkets, Convenience Stores, Online Retail, and Specialty and Other Channels.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Liquid lead by Form in the A2 Milk Market in 2026?
Liquid holds 84.0% of the A2 Milk Market by form in 2026.
Most A2 milk is sold as fresh or long-life drinking milk, because the purchase decision is made at the dairy chiller. The a2 Milk Company grew liquid milk sales by 21.8% to NZD 421.9 million over the twelve months to June 2026. Its Australian liquid milk value share rose by 0.5 percentage points to 11.7%. In the United States its liquid milk sales rose 28.9% to NZD 177.0 million. These figures show the brand being bought as an everyday milk, with a price premium attached.
Long-life liquid packs widen the lead. Moriyama Dairy uses aseptic filling so its A2 Hokkaido milk can be stored at room temperature. From 1 March 2026 that product carries a 120-day shelf life. Ambient A2 milk competes with products in the UHT milk market and lets one certified milk pool serve distant regions.
Powder accounts for the remaining 16.0% by form. The a2 Milk Company reported growth in kids and seniors fortified milk powder in China and launched a locally made kids milk powder in the six months to June 2026. Powder suits markets with weak chilled logistics, but it carries a higher processing cost per litre of milk equivalent.
Table 2: Form, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Liquid | 84.0% |
| All Other Segments Combined Share | 16.0% |
Source: Future Market Insights analysis of the A2 milk market, 2026.
Why does Conventional lead by Nature in the A2 Milk Market in 2026?
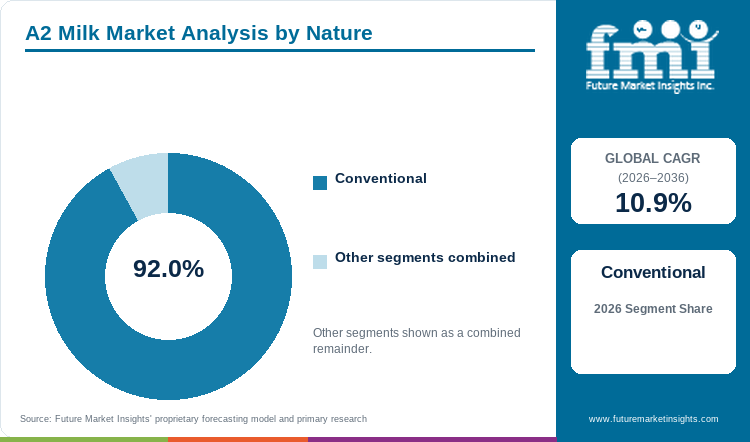
Conventional milk accounts for 92.0% of the A2 Milk Market by nature in 2026.
A2 status depends on cow genetics, so most certified herds are ordinary conventional farms selected for the A2A2 genotype. The a2 Milk Company lists 14 farmer suppliers for its Australian and New Zealand liquid milk and 154 farmer suppliers for infant formula. It also holds a long-term agreement with Fonterra for A1 protein free raw milk from the North Island of New Zealand. These programmes are built on conventional herds selected for genotype, which keeps the certified pool large enough for national brands.
Organic milk remains a small base to build from. In Germany, organic milk made up 4.8% of raw milk collected in June 2026. Stacking an organic requirement on top of an A2A2 genotype test shrinks the eligible herd further. Organic A2 products are therefore regional. Clover Sonoma sells its organic A2 whole milk through Raley's, Whole Foods Market and independent retailers in California. Alexandre Family Farm markets A2/A2 organic milk, cream and yoghurt from a single coastal California operation.
Organic holds the remaining 8.0% by nature. Its growth tracks the wider organic milk market more than the A2 category itself. Mengniu's organic A2 infant formula, launched during the first six months of 2026, shows the premium end of that overlap.
Table 3: Nature, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Conventional | 92.0% |
| All Other Segments Combined Share | 8.0% |
Source: Future Market Insights analysis of the A2 milk market, 2026.
Why do Supermarkets and Hypermarkets lead by Sales Channel in the A2 Milk Market in 2026?
Supermarkets and Hypermarkets hold 66.0% of the A2 Milk Market by sales channel in FMI's 2026 assessment.
Chilled milk is bought on the weekly grocery trip, so the large-format store decides which A2 brand wins. The a2 Milk Company attributes its US growth to higher household penetration, more distribution points and higher sales per distribution point. Its Australian share is measured in grocery scan data. Clover Sonoma chose Raley's supermarkets and Whole Foods Market for its organic A2 launch. A national listing in these chains is the entry ticket for any A2 brand.
Online sales of food remain a minority channel in the profiled markets. METI reports Japan's e-commerce ratio for food, beverages and alcohol at 4.5% in 2024. In South Korea, food and beverage orders grew 9.8% online in August 2026, which is faster than total online sales growth of 7.3%. Online pages give room to explain A2 protein, but they cannot yet move the volumes a supermarket moves.
Convenience Stores, Online Retail, and Specialty and Other Channels together represent the remaining 34.0%. Specialty outlets matter most in infant nutrition. The a2 Milk Company expanded Vietnamese distribution to more than 3,500 mother and baby stores. Foodservice is a new line, shown by the company's exclusive partnership with the restaurant chain Steak 'n Shake.
Table 4: Sales Channel, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Supermarkets and Hypermarkets | 66.0% |
| All Other Segments Combined Share | 34.0% |
Source: Future Market Insights analysis of the A2 milk market, 2026.
What are the key drivers restraints and opportunities?
A2 milk sells a genetic difference that shoppers cannot see, so the market depends on trust in testing and on a price premium that stays affordable. The same genetics that create the premium also limit how fast supply can grow.
Driver
Shoppers are paying more per litre in markets where total milk volumes fall. In Great Britain, cows' milk volumes fell 1.3% in the 12 weeks to 8 August 2026 while spend rose 1.2% and whole milk volumes rose 1.4%. The a2 Milk Company raised its Australian liquid milk value share to 11.7%. Nestlé sells an A2 beta-casein growing-up formula in Hong Kong at HKD 388.0 per 800 g pack and says it selects cows through DNA testing. Premium pricing for an A2 claim is now established across milk and infant nutrition, which gives processors a reason to invest in certified herds.
Restraint
Herd verification and segregated collection cap supply. The Bavarian State Research Center for Agriculture found the A2A2 genotype in 38.0% of Fleckvieh cows, 42.0% of Holstein cows and 73.0% of Braunvieh cows. It estimates 10 to 15 years to convert the Fleckvieh and Holstein populations. The a2 Milk Company describes segregation and testing of beta-casein from farm to finished product as a core quality step. Each separate milk pool needs its own tanks, routes and tests, which adds equipment demand covered in the dairy processing equipment market. Shrinking herds in Great Britain and South Korea make the pool harder to fill.
Opportunity
Shelf-stable and foodservice formats can carry a verified milk pool further than the chilled chain allows. Moriyama Dairy's ambient A2 milk now holds for 120 days and its A2 milk coffee for 150 days. The a2 Milk Company launched a fortified kids UHT product and an exclusive foodservice partnership with Steak 'n Shake in the year to June 2026. Its emerging markets sales grew 39.0% on UHT and milk powder volumes. Each format turns one certified pool into several revenue lines, but each also needs its own shelf-life testing before launch.
How do infant formula registration and health-claim rules affect A2 milk demand?
Infant formula registration decides where certified A2 milk can earn the highest margin. The a2 Milk Company bought the Pokeno plant with two China label infant formula registrations and plans to relaunch them under its own brand within 12 to 18 months, subject to Chinese regulatory approvals. It now targets two new China label products in the half-year to December 2026. Its US infant formula submission to the FDA remains under review. Each approval moves A2 milk from a retail premium into a regulated nutrition product.
Health claims are restricted. The Bavarian State Research Center for Agriculture states that health benefits cannot currently be advertised for A2 milk in Germany and classes it as a lifestyle product. Published trials support only modest effects. The 48-person crossover trial recorded mean symptom scores below 1 out of 10 for every milk tested. The 997-person Australian trial was open label and its authors asked for blinded replication. Brands must therefore sell on digestion comfort and taste, and they should expect regulators to challenge stronger wording.
What limits reliable A2 milk supply and quality?
Processing partners can fail even when the herd is ready. A Synlait production backlog and extended product release times contributed to a fourth-quarter supply disruption that cut the a2 Milk Company's China label infant formula revenue by 14.0% to NZD 544.3 million in FY26. Synlait itself reported revenue of NZD 1.94 billion and a net loss of NZD 75.4 million for the year to July 2026. The a2 Milk Company is moving a2 Platinum production from Synlait to its own Pokeno plant in the first half of its 2027 financial year.
Own capacity takes time to ramp. The company spent NZD 51.6 million of its planned NZD 100.0 million Pokeno upgrade in the year to June 2026 and produced under 5,000 tonnes of infant formula there. It targets 10,000 to 15,000 tonnes in the next year. Raw milk is the other limit. AHDB forecasts GB milk production down 2.2% in the 2026/27 season, and South Korea's dairy herd fell 3.0% in the year to September 2026. A2 programmes must recruit genotyped cows from these smaller herds, so processors should sign multi-year supply contracts before they commit to listings.
Where can A2 milk suppliers win additional business?
Licensing and export let a certified pool earn revenue outside its home market. The a2 Milk Company reports double-digit growth in licensed brand sales in Canada, an entry into the Philippines with UHT milk and a stronger brand presence in Singapore. It intends to enter Indonesia in the first half of calendar 2027, subject to registration. In Japan, the Japan A2 Milk Association reported in October 2026 that the first domestically certified A2 milk had been exported. Paediatric supplements add a further line, with the a2 Zhi Yi range launched in China in the third quarter of the company's 2026 financial year. Suppliers with spare certified milk should look first at long-life exports, because registration for infant products takes longer and costs more.
A2 Milk Market by Country (2026 to 2036)
Table 5: A2 Milk Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
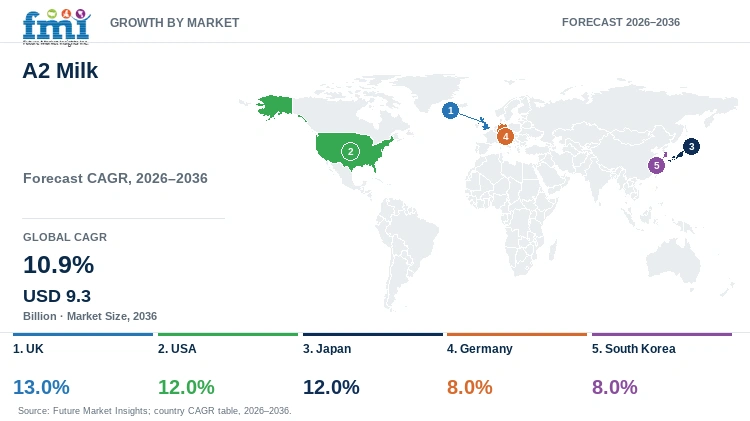
| United Kingdom | 13.0% |
| United States | 12.0% |
| Japan | 12.0% |
| Germany | 8.0% |
| South Korea | 8.0% |
Source: Future Market Insights analysis of the A2 milk market, 2026.
United Kingdom
British processors are handling less milk and selling more of it as whole milk. Defra reports that UK dairies processed 1,167.0 million litres in August 2026 and sent 473.6 million litres of that to liquid milk. AHDB retail data for the 12 weeks to 8 August 2026 show cows' milk volumes down 1.3% while spend rose 1.2%. Whole milk volumes rose 1.4% in the same period as semi-skimmed and skimmed fell. Shoppers are paying more per litre and choosing richer products. That is the buying pattern an A2 brand needs.
Supply is tightening at the farm. AHDB expects GB milk production of 12,737 million litres in the 2026/27 season, 2.2% lower than a year earlier. The milking herd stood at 1.57 million head in July 2026, also down 2.2%. Processors facing lower volumes have a reason to earn more per litre, and a certified A2 line is one route. The farmgate price stood at 35.00 pence per litre in July 2026. A premium contract for A2 herds must be priced above that level to hold farmer interest.
A2 milk carries the highest forecast rate among the profiled countries at 13.0% over 2026 to 2036, because the British category starts from a small base with no national brand of scale. The a2 Milk Company names China, Australia, New Zealand, Vietnam, South Korea and North America as its primary markets. That leaves the United Kingdom to domestic processors and to retailers' own labels. A shrinking herd makes it harder to assemble enough A2A2 cows in one collection area. Processors will need multi-year contracts with genotyped herds before they commit to a national listing. The retailer that lists first will set the price points for the category.
United States
The United States combines the largest raw milk base in the profiled group with a growing branded A2 business. The USDA forecasts 2026 milk production at 236.9 billion pounds from a herd of 9.680 million cows. It expects an all-milk price of USD 19.90 per hundredweight in 2026. Abundant conventional milk keeps the base price low, which widens the room for a premium A2 product above it. That cost structure is one reason US A2 milk sales are expected to compound at a 12.0% CAGR over 2026 to 2036.
The a2 Milk Company grew USA revenue by 28.6% to NZD 179.0 million in its 2026 financial year and reached EBITDA breakeven in the second half. Its liquid milk sales rose 28.9% to NZD 177.0 million. Its dollar share of premium milk in grocery rose to 2.8% from 2.2%. The company has established a new grassfed milk farm in the Southeast to support year-round supply. Organic challengers are also moving. Clover Sonoma launched a Pasture Raised Organic A2 whole milk in Northern California in February 2025 at a suggested USD 7.49. Alexandre Family Farm sells A2/A2 organic milk, cream and cultured products from its coastal California herd.
Supply security and household reach decide how much of that growth each brand captures. Growth depends on how fast brands add distribution points and households, which the a2 Milk Company cites as the drivers of its latest gain. Regional organic brands rely on single herds and single-state distribution, so they cannot match a national brand on shelf presence. The a2 Milk Company's infant formula submission to the FDA is still under review, which keeps the US business a liquid milk story for now. Buyers should watch whether A2 moves from premium grocery into mass channels, where price competition is harder.
Japan
Japanese A2 milk is being built by regional processors around certified Hokkaido herds. Moriyama Dairy sells an A2 Hokkaido milk made from raw milk that the Japan A2 Milk Association has genetically tested and certified. From 1 March 2026 the company extended that product's shelf life from 90 to 120 days and its A2 milk coffee and fruit drinks from 90 to 150 days. Ambient storage lets a regional dairy reach stores nationwide without a chilled chain. The association measures beta-casein protein in the milk itself and runs a registration system for individual cows.
The wider category is shrinking. MAFF reports that drinking milk output fell 1.2% in fiscal 2025 and fell 1.2% again in August 2026. Raw milk production rose 0.3% in fiscal 2025, so processors have milk to allocate but fewer drinkers to sell it to. A certified A2 line gives a dairy a way to hold value while volumes slip, and that value shift carries Japan's 12.0% CAGR for 2026 to 2036 at the same rate as the United States.
Online sales will not carry much of that growth. METI records an e-commerce ratio of 4.5% for food and drink in 2024, so supermarkets and convenience stores remain the shelf that matters. Export is a second lever. The association's October 2026 notice points to the first domestically certified A2 milk shipped overseas. The risk is the number of certified farms. Hokkaido supply rests on a few contract herds, and any herd that loses certification removes volume at once. Processors that spread sourcing across more certified farms will protect their listings.
Germany
Germans are drinking less milk each year, and A2 is still a niche inside that decline. The Milchindustrie-Verband reports drinking milk consumption of 45.1 kg per head in 2025, down from 46.2 kg in 2024 and 49.6 kg in 2019. The BLE recorded drinking milk production of 3,997.6 thousand tonnes in 2025. Organic milk was 4.8% of raw milk collected in June 2026, which shows how far any differentiated line must travel to reach scale. Against that backdrop an 8.0% CAGR for 2026 to 2036 is a measured rate, and it ties with South Korea.
Herd genetics set the pace of any A2 programme. The Bavarian State Research Center for Agriculture reports that 38.0% of Fleckvieh cows, 42.0% of Holstein cows and 73.0% of Braunvieh cows carry the A2A2 genotype. It estimates conversion of a 100-cow herd at EUR 60,000 to EUR 80,000 and full breed conversion at 10 to 15 years for Fleckvieh and Holstein. It expects a farm to convert only where a buyer pays a lasting premium of at least 5 cents per kilogram. Health benefits cannot be advertised, and the agency classes A2 milk as a lifestyle product.
Slow herd conversion and restricted claims explain that measured pace. EU farmgate prices averaged 42 cents per kilogram in July 2026, so a 5-cent A2 premium adds about 12.0% to a farmer's milk price. That premium is affordable for a dairy selling A2 milk at retail, but only if the dairy can fill a separate collection route. Braunvieh herds in southern Germany offer the quickest path. Dairies that start with those herds can build a regional A2 line before national brands arrive. The LfL notes that German A2 milk is sold mainly direct from farms and through milk vending machines, with supermarket listings in some regions. Those listings will decide whether the category moves past the farm gate.
South Korea
Fewer cows each year is the first fact facing any Korean A2 programme. The National Data Office counted 362,000 dairy cows at 1 September 2026, a fall of 11,000 head or 3.0% in a year. Every A2 line must be assembled from genotyped cows inside that smaller herd. A processor that wants to convert a whole brand to A2 must therefore test and segregate cows faster than the national herd declines. Cooperatives that own the farm relationship can organise that testing more easily than an importer can.
Demand is moving to channels where premium milk can be explained. Korean online shopping transactions totalled KRW 24.2 trillion in August 2026 and were 7.3% higher than a year earlier, with food and beverage orders up 9.8%. A product page gives space for the A2 story that a shelf label cannot carry. International brands also treat the country as a priority. The a2 Milk Company lists South Korea among its six primary markets and reported progress with its emerging markets strategy there during FY26.
Herd shrinkage and a small certified pool cap the pace of growth. Imported A2 milk arrives as UHT or powder and competes on shelf life. Fresh domestic A2 milk competes on taste and short delivery times. Between those two formats the Korean market is expected to grow at 8.0% a year over 2026 to 2036, which matches Germany. The decisive factor will be whether processors can pay farmers enough to keep A2A2 cows in production while total herd numbers fall. Processors that lock in certified herds early will hold the category when raw milk tightens. Retail buyers should ask each supplier how many herds stand behind its A2 line and how often those herds are retested.
Who are the notable companies in the A2 Milk Market?
The a2 Milk Company, Mengniu, Synlait and Moriyama Dairy occupy the four main commercial positions in A2 milk. The a2 Milk Company sells A2 branded milk, infant formula and nutrition products across six primary markets. It reported FY26 revenue of NZD 1,974.9 million, up 12.4%. It now owns the Pokeno infant formula plant and holds a 19.8% stake in Synlait. Its liquid milk business reached NZD 421.9 million.
Mengniu brings a far larger group revenue base, with first-half 2026 revenue of RMB 44.8 billion. Its Yashili arm sold the Yashili New Zealand business to the a2 Milk Company in 2025 and launched the Chuai Niuniu Jingzhi desert organic A2 infant formula in the first half of 2026. Synlait remains a contract manufacturer for a2 Platinum and reported a return to operational stability in the second half of its 2026 financial year. Its FY26 net loss of NZD 75.4 million shows the strain on processing partners.
Regional specialists compete on certification and freshness. Moriyama Dairy builds its A2 range on milk certified by the Japan A2 Milk Association and sells it in ambient packs. Clover Sonoma and Alexandre Family Farm sell organic A2 milk in California. Fonterra supplies A1 protein free raw milk to the Pokeno plant under a long-term agreement. Nestlé competes in infant nutrition with an A2 beta-casein formula sold in Hong Kong. Buyers should compare each supplier on the number of certified herds, testing frequency and shelf life before they sign.
Key Developments in the A2 Milk Market
- In September 2025, The a2 Milk Company Limited completed the acquisition of an integrated nutritional manufacturing facility in Pokeno, New Zealand. The acquisition included two China label infant milk formula registrations subject to regulatory approval for rebranding under The a2 Milk Company brand [1].
- In September 2025, Moriyama Milk Industry Co., Ltd. launched two shelf-stable A2 milk beverages, MORIYAMA A2 Oishii Milk Coffee and MORIYAMA A2 Oishii Milk Fruits, for nationwide distribution in Japan. Both products contain more than 50.0% A2 raw milk from Hokkaido and can be stored at room temperature for 90 days unopened [2].
- In June 2025, Oisix ra daichi Inc. launched "Oisix Minna no A2 Milk," Japan's first private-label milk using an A2 certification label provided by SwissDeCode. The product uses 100.0% A2 raw milk from a dedicated farm in Suzuka, Mie Prefecture, and was introduced to university cafeterias in Tokyo from June 2025 [4].
Key Players in the A2 Milk Market
- The a2 Milk Company Limited
- China Mengniu Dairy Company Limited
- Synlait Milk Limited
- Fonterra Co-operative Group Limited
- Moriyama Milk Industry Co., Ltd.
- Clover Sonoma
- Alexandre Family Farm, LLC
- Nestlé S.A.
- Seoul Milk Cooperative
- Hori Dairy Co., Ltd.
- Oisix ra daichi Inc.
A2 Milk Market Report Scope
Table 6: A2 Milk Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Cow's milk products containing only A2-type beta-casein, sold as liquid milk and milk powder for drinking. Infant formula and paediatric nutrition are covered as adjacent demand and are excluded from the market value. |
| Nature | Conventional; Organic |
| Form | Liquid; Powder |
| Sales Channel | Supermarkets and Hypermarkets; Convenience Stores; Online Retail; Specialty and Other Channels |
| Supply chain stages | Herd genotyping and certification; segregated collection; processing and packing; retail and foodservice |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | United Kingdom, United States, Japan, Germany, South Korea |
| Companies covered | The a2 Milk Company Limited; China Mengniu Dairy Company Limited; Synlait Milk Limited; Fonterra Co-operative Group Limited; Moriyama Milk Industry Co., Ltd.; Clover Sonoma; Alexandre Family Farm, LLC; Nestlé S.A.; Seoul Milk Cooperative; Hori Dairy Co., Ltd.; Oisix ra daichi Inc. |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the A2 milk market, 2026.
A2 Milk Market Research Methodology
The A2 milk assessment draws on company results and annual reports, national dairy statistics, government research papers and peer-reviewed trials. FMI measures annual retail and foodservice sales value of A2 beta-casein milk in liquid and powder form. Segment values are classified by nature, form and sales channel. Country forecasts reflect local milk consumption, herd genetics, certification capacity and retail structure over the same 2026 to 2036 period. Company revenue, herd counts and milk production are reviewed as separate measures.
A2 Milk Market by Segments
A2 Milk Market segmented by Nature:
- Conventional
- Organic
A2 Milk Market segmented by Form:
- Liquid
- Powder
A2 Milk Market segmented by Sales Channel:
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Specialty and Other Channels
A2 Milk Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] The a2 Milk Company Limited. (2025). Completion of a2MC Pokeno facility acquisition. https://www.nzx.com/announcements/457905
- [2] Moriyama Milk Industry Co., Ltd. (2025). MORIYAMA A2 Oishii Milk Coffee / Milk Fruits launch announcement. https://www.jacom.or.jp/articles/250917-84495
- [4] Oisix ra daichi Inc. (2025). Oisix Minna no A2 Milk launch announcement. https://foods-ch.infomart.co.jp/news/172980
- [4] The a2 Milk Company Limited. (2025, August 18). FY25 Results and Supply Chain Transformation Update. Australian Securities Exchange. https://announcements.asx.com.au/asxpdf/20250818/pdf/06myxcy9z32rhz.pdf
- [5] The a2 Milk Company Limited. (2025, September 1). Completion of a2MC Pokeno facility acquisition. NZX. https://announcements.nzx.com/announcement/457905
- [6] U.S. Department of Agriculture, Economic Research Service. (2026, October 16). Livestock, Dairy, and Poultry Outlook: October 2026 (LDP-M-388).
- [7] AHDB. (2026, October 14). Dairy October 2026 forecast update: GB milk production under pressure.
- [8] AHDB. (2026, September 9). August 2026 dairy market review. https://ahdb.org.uk/news/august-2026-dairy-market-review
- [9] Department for Environment, Food and Rural Affairs. (2026, October 1). Milk utilisation: statistics notice (data to August 2026). https://www.gov.uk/government/statistics/milk-utilisation-by-dairies-in-england-and-wales/milk-utilisation-statistics-notice-data-to-august-2026
- [10] Ministry of Agriculture, Forestry and Fisheries, Japan. (2026, October). Recent situation regarding milk and dairy products. https://www.maff.go.jp/j/chikusan/gyunyu/lin/attach/pdf/index-411.pdf
- [11] Moriyama Dairy Co., Ltd. (2026, March 1). Notice of shelf-life change and partial design change for the A2 milk series. https://www.fujimilk.co.jp/Information/index.html
- [12] Moriyama Dairy Co., Ltd. (2025). A2 milk series product page, accessed 3 November 2026. https://www.fujimilk.co.jp/lp/a2milk.html
- [13] Japan A2 Milk Association. (2026). Association website and news notices, accessed 3 November 2026. https://www.japan-a2milk-association.or.jp/
- [14] Ministry of Economy, Trade and Industry, Japan. (2025, August 26). Results of the FY2024 e-commerce market survey. https://www.meti.go.jp/policy/it_policy/statistics/outlook/250826_kohyoshiryo.pdf
- [15] Milchindustrie-Verband e.V. (2026, April). Pro-Kopf-Verbrauch von Milchprodukten in Deutschland 2019 bis 2025. https://milchindustrie.de/wp-content/uploads/2026/04/ProkopfDeutschland_Mopro_2019-2025_Homepage.pdf
- [16] Bundesanstalt für Landwirtschaft und Ernährung. (2026, August). Bericht zur Markt- und Versorgungslage Milch und Milcherzeugnisse 2026. https://bmel-statistik.de/fileadmin/daten/0611100-2026.pdf
- [17] Bayerische Landesanstalt für Landwirtschaft. (2020, June 30). LfL-Standpunkt: A2-Milch. https://lfl.bayern.de/mam/cms07/publikationen/standpunkte/dateien/a2-milch_lfl-standpunkt.pdf
- [18] European Commission, Directorate-General for Agriculture and Rural Development. (2026, September 17). Milk market situation factsheet.
- [19] National Data Office, Republic of Korea. (2026, October 23). Livestock trend survey results for the third quarter of 2026. KDI Economic Information and Education Center. https://eiec.kdi.re.kr/policy/materialView.do?num=288440
- [20] National Data Office, Republic of Korea. (2026, October 1). Online shopping trends, August 2026. KDI Economic Information and Education Center. https://eiec.kdi.re.kr/policy/materialView.do?num=287670
- [21] China Mengniu Dairy Company Limited. (2026, August 27). Mengniu's 2026 Interim Results: Broad-Based Growth Leads the Industry into a New Cycle. https://www.mengniuir.com/pdf/press/20260827_en.pdf
- [22] Synlait Milk Limited. (2026, September 27). Synlait reports FY26 result and operational recovery. NZX. https://www.nzx.com/announcements/480619
- [23] Clover Sonoma. (2025, February 4). Clover Sonoma Unveils Pasture Raised Organic A2 4% Whole Milk. https://cloversonoma.com/press/clover-unveils-pasture-raised-organic-a2/
- [24] Alexandre Family Farm. (2026). Company website, accessed 3 November 2026. https://www.alexandrefamilyfarm.com/
- [25] Robinson, L. A., Cavanah, A. M., Lennon, S., Mattingly, M. L., Anglin, D. A., Boersma, M. D., Roberts, M. D., & Frugé, A. D. (2025, June 6). Lactase-Treated A2 Milk as a Feasible Conventional Milk Alternative: Results of a Randomized Controlled Crossover Trial. Nutrients, 17(12), 1946.
- [26] Starck, C., Blumfield, M., Petocz, P., Duve, E., Downey, L., Abbott, K., & Fayet-Moore, F. (2025, June 3). A1 protein free milk benefits mood and subjective cognition in free-living Australian adults: a pragmatic, exploratory, open label randomised controlled trial. Frontiers in Nutrition, 12, 1579986. https://www.frontiersin.org/journals/nutrition/articles/10.3389/fnut.2025.1579986/pdf
- [27] Nestlé Hong Kong Limited. (2026). NESTLÉ NAN INFINIPRO A2 β-Casein 3 800g product page, accessed 3 November 2026. https://shop.nestle.com.hk/en/products/nestle%C2%AE-nan%C2%AE-infinipro%C2%AE-a2-%CE%B2-casein-3-800g-gut-immunity
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Liquid
- Powder
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Specialty and Other Channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Form
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Form
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Form
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The a2 Milk Company Limited
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- China Mengniu Dairy Company Limited
- Synlait Milk Limited
- Moriyama Milk Industry Co., Ltd.
- Clover Sonoma
- Fonterra Co-operative Group Limited
- Alexandre Family Farm, LLC
- Nestlé S.A.
- Seoul Milk Cooperative
- Hori Dairy Co., Ltd.
- Oisix ra daichi Inc.
- The a2 Milk Company Limited
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Nature
- Figure 6: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Form
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Nature
- Figure 26: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Form
- Figure 29: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sales Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Nature
- Figure 36: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Form
- Figure 39: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Nature
- Figure 46: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Form
- Figure 49: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Form
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Nature
- Figure 66: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Form
- Figure 69: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the A2 Milk Market in 2026?
FMI estimates the market at USD 3.3 billion in 2026, up from USD 3.0 billion in 2025. It is forecast to reach USD 9.3 billion by 2036 at a 10.9% CAGR.
Which form leads the A2 Milk Market in 2026?
Liquid leads by form with 84.0% in 2026. Powder holds the remaining 16.0%.
Which nature and sales channel lead in 2026?
Conventional holds 92.0% by nature. Supermarkets and Hypermarkets hold 66.0% by sales channel in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
The United Kingdom has the highest forecast CAGR at 13.0% during 2026 to 2036. The United States and Japan tie at 12.0%, and Germany and South Korea tie at 8.0%. These are FMI forecasts and are not rates reported by the cited public bodies.
Why is A2 milk supply hard to expand?
Only cows with two copies of the A2 gene qualify. The Bavarian State Research Center for Agriculture found the A2A2 genotype in 38.0% of Fleckvieh cows and 42.0% of Holstein cows, and it estimates 10 to 15 years to convert those breeds [17].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
