

- Market Size (2026)
- USD 80.9 Bn
- Forecast (2036)
- USD 255.8 Bn
- CAGR (2026 to 2036)
- 12.2%
How big is ADAS Market in 2026?
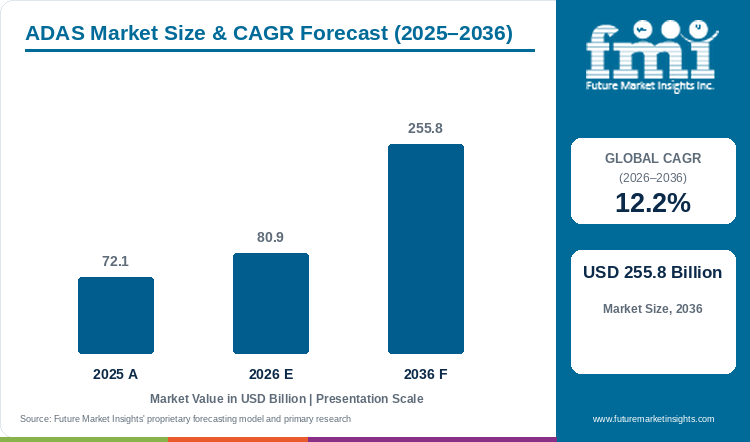
The ADAS market is estimated at USD 72.1 billion in 2025 and is forecast to reach USD 80.9 billion in 2026. A CAGR of 12.2% is projected for the ADAS market over the decade, taking sales to USD 255.8 billion by 2036.
Sales of ADAS are highest in safety systems, an estimated 80.1% of 2026 application sales, as regulators write braking and attention warnings into type approval. From 7 July 2026, every newly registered passenger car and light van in the EU has to carry advanced emergency braking that detects pedestrians and cyclists, plus advanced driver distraction warning, ERTICO reported.[1] With fitment compulsory, ADAS market size is estimated at USD 72.1 billion for 2025 and is expected to reach USD 80.9 billion in 2026, and demand for ADAS is predicted to rise at a 12.2% CAGR to USD 255.8 billion by 2036.
Porter's five forces analysis points first to strong buyer power. A few global carmakers award multi-year platform contracts covering millions of vehicles, so suppliers bid hard on unit price. Mobileye shipped 10.0 million systems in the second quarter of 2026, 3% more than in the same quarter of 2025, but average system price slipped to USD 48.5 from USD 49.7.[2] Volume is outpacing value per unit for front camera suppliers.
The threat of new entrants is rising, as chip designers and carmakers with in-house software bid for central compute once supplied by tier one firms. FMI's analysts expect suppliers holding radar, camera and software together to defend price best, as carmakers want one sensor fusion partner.
Key Market Trends & Insights
- Adaptive cruise control (ACC) is expected to lead system type with 19% share in 2026, as highway assist packages bundle speed and distance control, and automatic emergency braking (AEB) follows at an estimated 16.5%.
- Level 2 is projected to hold 51.4% of 2026 level of autonomy sales, with Level 1 at 36% and Level 3 near 8.9%.
- Cameras, radars and control units keep hardware ahead on component, at 58% of 2026 sales, with software at an estimated 42%. NXP reported automotive revenue of USD 1,938 million in the second quarter of 2026, up 12%.[3]
- Within vehicle type, passenger cars are likely to hold 54% of 2026 sales, light commercial vehicles about 27.3% and heavy commercial vehicles near 18.7%.
- Demand for ADAS cameras is estimated at 49.8% of sensor type sales in 2026, ahead of radar at 34% and LiDAR at about 16.2%.
- Safety systems are projected to lead application with 80.1% share in 2026. Euro NCAP rated the Kia EV2 five stars under the 2026 protocols, helped by a driver state monitoring system whose warnings vary with alertness.[4]
- OEM fitment is expected to hold 62% of 2026 sales channel demand, against an estimated 38% for aftermarket systems and calibration.
Regional Highlights
- India is first among the countries covered at a 14.3% CAGR, as carmakers add radar and camera packages to mid-priced models.
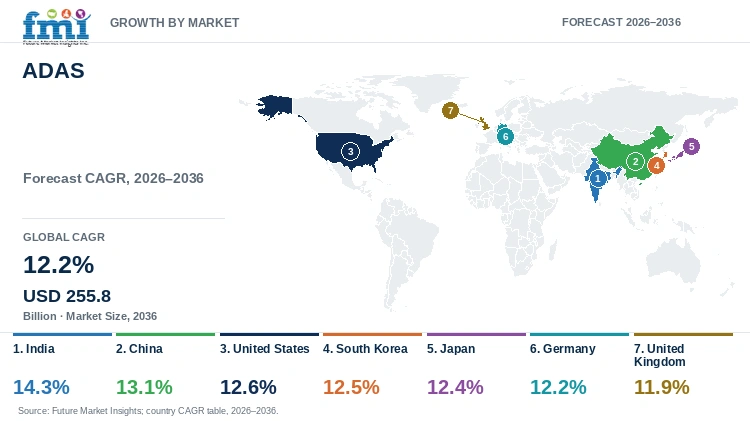
- China is forecast at 13.1%. The United States leads a close group at 12.6%, with South Korea a tenth behind and Japan two tenths behind. Germany matches the global rate exactly, and the slowest profiled rate, 11.9%, belongs to the United Kingdom.
- All newly registered passenger cars and light vans in the EU had to carry advanced emergency braking with pedestrian and cyclist detection from 7 July 2026.[1]
Market Size & Forecast
Table 1: Market Size and Forecast for the ADAS Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 72.1 billion |
| Estimated Market Size in 2026 | USD 80.9 billion |
| Projected Market Size by 2036 | USD 255.8 billion |
| CAGR, 2026 to 2036 | 12.2% |
| Added Revenue, 2026 to 2036 | USD 174.9 billion |
| Market Expansion Multiple | 3.2x |
ADAS revenue reaches suppliers through platform awards signed three to four years before start of production, and each award then ships for the life of a model. Valeo said BRAIN Division sales were EUR 2,527 million in the first half of 2026, flat against the first half of 2025, and outperformed automotive production by one point.[5] Valeo also secured a corner radar suite contract with a North American electric vehicle maker over the same months. Hybrid models are taking a larger share of new builds, and a 21.5% CAGR forecast for the hybrid vehicles market adds new platforms for radar and camera packages. On the FMI outlook, the ADAS market is expected to gain USD 174.9 billion in annual sales between 2026 and 2036, so the 2036 figure is about 3.2 times the 2026 one. Slower vehicle production is the main risk, as fitment rates cannot offset a fall in builds.
Safety Rules, Ratings and Platform Awards
Rules and ratings are moving ADAS from option lists to standard equipment. The EU extended advanced emergency braking with pedestrian and cyclist detection and driver distraction warning from new models to all new registrations on 7 July 2026.[1] In the United States, the DOT told the D.C. Circuit on 23 March 2026 that a proposal to extend the FMVSS 127 compliance lead time by two years was being prepared, with the 1 September 2029 date still in force, Nelson Mullins reported.[6] Euro NCAP began scoring physical driving controls and driver state monitoring under the 2026 protocols, and published new ratings on 12 October 2026.[4] Carmakers selling in Europe will fit camera-based monitoring and AEB on every trim.
Platform awards show which suppliers are gaining content. Mobileye added a high-volume Cloud-Enhanced ADAS design award with Stellantis in the second quarter of 2026 and raised 2026 revenue guidance to USD 1,970 million to USD 2,020 million.[2] Hyundai Mobis and Qualcomm signed an MOU at CES 2026 to co-develop ADAS and parking solutions on the Snapdragon Ride Flex SoC, with India named as a target market.[7] Suppliers that pair sensors with compute will take a larger part of each vehicle's ADAS bill.
Table 2: Regulation, Shipment and Supplier Indicators for the ADAS Market (rules, units and sales), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| EU General Safety Regulation phase, July 2026 | AEB with pedestrian and cyclist detection and ADDW on all new cars and vans | Compulsory fitment in Europe | [1] |
| US FMVSS 127 status, March 2026 | Proposal to extend compliance lead time by two years; 1 September 2029 still in force | Timing of AEB demand in the United States | [6] |
| Mobileye systems shipped, Q2 2026 | 10.0 million; average system price USD 48.5 | Buyer power on unit price | [2] |
| Valeo BRAIN Division sales, H1 2026 | EUR 2,527 million; flat | Tier one ADAS sales trend | [5] |
| NXP automotive revenue, Q2 2026 | USD 1,938 million; up 12% | Radar and processor demand | [3] |
| Aptiv revenue, Q2 2026 | USD 3.3 billion; up 2% | Safety and software supplier sales | [8] |
| Euro NCAP 2026 protocol ratings, October 2026 | Driver state monitoring and physical controls scored | Rating pressure on carmakers | [4] |
Analyst Perspective
“ADAS revenue over the next decade will follow the rulebook, as EU registration rules, Euro NCAP scoring and the US AEB standard turn safety features into standard equipment. I expect the strongest supplier positions to belong to companies that sell radar, camera and the software that fuses them, since carmakers want one accountable partner for sensor fusion. Level 3 will add value in premium cars, and I would back Level 2 packages for mid-priced models as the volume prize.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the ADAS market segmented?
The market is segmented into system type, level of autonomy, component, vehicle type, sensor type, application, sales channel, and region. Adaptive cruise control (ACC) is expected to lead system type with 19% share in 2026, and Level 2 is projected to lead level of autonomy with 51.4%.
By system type: adaptive cruise control (ACC), lane departure warning (LDW), lane keeping assist (LKA), blind spot detection (BSD), automatic emergency braking (AEB), forward collision warning (FCW), traffic sign recognition (TSR), parking assist, pedestrian detection system (PDS), night vision system (NVS), driver monitoring systems (DMS), and surround view system (SVS).
By level of autonomy: Level 1, Level 2, Level 3, Level 4, and Level 5.
By component: hardware and software.
By vehicle type: passenger cars, light commercial vehicle, and heavy commercial vehicle.
By sensor type: radar, camera, and LiDAR.
By application: safety systems, parking assistance, and driver monitoring.
By sales channel: OEM and aftermarket.
By region: carmakers, fleets and drivers in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does adaptive cruise control lead ADAS sales by system type?
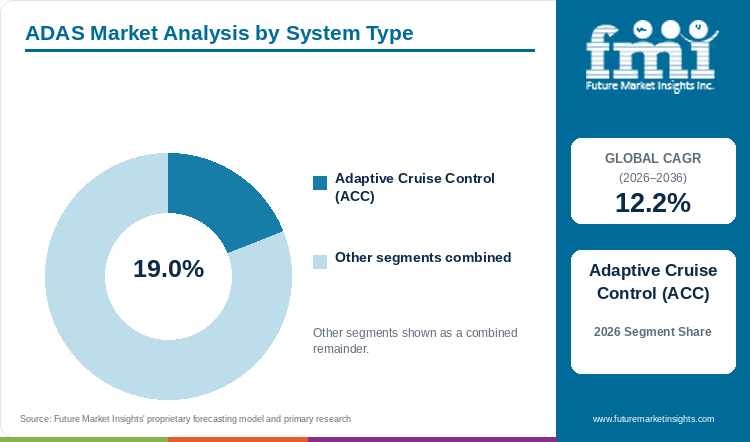
Adaptive cruise control (ACC) is expected to lead system type sales with 19% share in 2026, ahead of automatic emergency braking (AEB) at an estimated 16.5% and lane keeping assist (LKA) at about 11.2%.
Table 3: System Type Share for the ADAS Market (percentage share), 2026
| System Type | Estimated Share (2026) |
|---|---|
| Adaptive Cruise Control (ACC) | 19% |
| Automatic Emergency Braking (AEB) | 16.5% |
| Lane Keeping Assist (LKA) | 11.2% |
| Blind Spot Detection (BSD) | 9.4% |
| Parking Assist | 8.6% |
| Lane Departure Warning (LDW) | 7.1% |
| Forward Collision Warning (FCW) | 6.3% |
| Surround View System (SVS) | 6.1% |
| Driver Monitoring Systems (DMS) | 5.2% |
| Traffic Sign Recognition (TSR) | 4.3% |
| Pedestrian Detection System (PDS) | 3.6% |
| Night Vision System (NVS) | 2.7% |
| Total | 100.0% |
Table 4: System Type Leadership and Market Growth for the ADAS Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.2% |
| Leading Segment | Adaptive Cruise Control (ACC) |
Highway assist packages are the reason adaptive cruise control (ACC) is expected to lead with a 19% share in 2026, since each ACC system carries a long-range radar, a front camera and the control software that later supports lane centring. Automatic emergency braking (AEB), an estimated 16.5%, is fitted to more cars, but many low-cost AEB units run on a single camera and sell for less. Lane keeping assist (LKA), about 11.2%, and lane departure warning (LDW), 7.1%, share the same camera, so carmakers add them at small extra cost. Blind spot detection (BSD), 9.4%, needs two rear corner radars. Parking assist, 8.6%, and surround view (SVS), 6.1%, are mostly comfort options. AEB and camera packages usually bundle forward collision warning (FCW), 6.3%, with traffic sign recognition (TSR), 4.3%. Rules and premium trims carry driver monitoring (DMS) at 5.2%, pedestrian detection (PDS) at 3.6% and night vision (NVS) at 2.7%. AEB pulls brake hardware into every package, and the automotive brake system and components market is expected to rise at a 3.5% CAGR, so brake suppliers will add sensor interfaces to keep pace. ACC will hold the lead as Level 2 packages spread to mid-priced cars.
- Stop-and-go ACC, highway assist and predictive speed control make up most ACC value.
- Valeo secured a corner radar suite contract with a North American electric vehicle maker in the first half of 2026.[5]
Why does Level 2 lead ADAS sales by level of autonomy?
Level 2 is projected to lead level of autonomy sales with 51.4% share in 2026, ahead of Level 1 at 36%, Level 3 at an estimated 8.9%, Level 4 near 3.4% and Level 5 at about 0.3%.
Table 5: Level of Autonomy Share for the ADAS Market (percentage share), 2026
| Level of Autonomy | Estimated Share (2026) |
|---|---|
| Level 2 | 51.4% |
| Level 1 | 36% |
| Level 3 | 8.9% |
| Level 4 | 3.4% |
| Level 5 | 0.3% |
| Total | 100.0% |
Combining steering and speed control in one package puts Level 2 in front, at a projected 51.4% share in 2026, as each system carries several radars, cameras and a domain controller. Level 1, at 36%, covers single-function systems such as AEB or basic cruise, which sell in larger numbers at a lower price. Level 3, an estimated 8.9%, is limited to premium cars that let the driver hand over control on approved roads, and approval rules differ by country. Level 4, near 3.4%, and Level 5, about 0.3%, are robotaxi and pilot fleets with very high sensor content per vehicle and few vehicles. Mobileye said SuperVision carries more hardware content and lower margins than front-camera systems.[2] Carmakers will move mid-priced models from Level 1 to Level 2 first, and Level 3 will stay a premium option.
- Highway assist, traffic jam assist and hands-on lane centring make up most Level 2 systems.
- Mobileye said MOIA began public user testing of robotaxis with safety drivers in Hamburg in the second quarter of 2026.[2]
Why does hardware lead ADAS sales by component?
Hardware is expected to lead component sales with 58% share in 2026, against an estimated 42% for software.
Table 6: Component Share for the ADAS Market (percentage share), 2026
| Component | Estimated Share (2026) |
|---|---|
| Hardware | 58% |
| Software | 42% |
| Total | 100.0% |
Every ADAS function needs physical sensing, so hardware is expected to lead with a 58% share in 2026, from camera units, radar sensors, ultrasonic sensors, LiDAR and ECUs. Software, an estimated 42%, covers middleware, application software and operating systems, and carmakers are paying more for over-the-air updates and sensor fusion. NXP grew automotive revenue 12% to USD 1,938 million in the second quarter of 2026.[3] Software value will rise faster as central compute replaces separate ECUs, and hardware will keep the larger share through most of the decade.
- Camera units, radar sensors, ultrasonic sensors, LiDAR and ECUs make up the hardware segment.
- Hyundai Mobis and Qualcomm agreed on 7 January 2026 to co-develop ADAS software and hardware on the Snapdragon Ride Flex SoC.[7]
Why do passenger cars lead ADAS sales by vehicle type?
Passenger cars are likely to lead vehicle type sales with 54% share in 2026, ahead of light commercial vehicles at an estimated 27.3% and heavy commercial vehicles at about 18.7%.
Table 7: Vehicle Type Share for the ADAS Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Cars | 54% |
| Light Commercial Vehicle | 27.3% |
| Heavy Commercial Vehicle | 18.7% |
| Total | 100.0% |
Passenger cars will lead with a 54% share in 2026, as compact, mid-size, luxury, sedan and SUV models carry the widest range of ADAS options. Light commercial vehicles, an estimated 27.3%, are catching up, since EU rules now cover all new vans and delivery fleets buy AEB and blind spot systems to cut accident costs. Heavy commercial vehicles, about 18.7%, carry fewer but costlier systems, and truck fleets pay for collision warning and lane keeping to lower insurance claims. Camera calibration after a windscreen change links ADAS to glass, and the automotive glass market is projected to expand at a 5.7% CAGR, which keeps windscreen makers fitting camera brackets on new models. Passenger cars will hold the lead on model count.
- Compact, mid-size, luxury, sedan and SUV models make up the passenger car base.
- Under EU rules, light vans newly registered from 7 July 2026 needed driver distraction warning and pedestrian-detecting emergency braking.[1]
Why do cameras lead ADAS sales by sensor type?
Cameras are estimated to lead sensor type sales with 49.8% share in 2026, ahead of radar at 34% and LiDAR at about 16.2%.
Table 8: Sensor Type Share for the ADAS Market (percentage share), 2026
| Sensor Type | Estimated Share (2026) |
|---|---|
| Camera | 49.8% |
| Radar | 34% |
| LiDAR | 16.2% |
| Total | 100.0% |
Cameras are estimated to lead with a 49.8% share in 2026, as one front camera reads lanes, signs, pedestrians and vehicles and supports several functions at once. Radar, at 34%, gauges distance and speed in rain, fog and darkness, so ACC and blind spot systems still rely on radar units at the front and corners. LiDAR, about 16.2%, gives a detailed 3D picture but costs more per unit and is limited to premium Level 3 cars and robotaxi fleets. Mobileye shipped 10.0 million camera-based systems in the second quarter of 2026.[2] Camera and radar fusion will remain the standard pairing, with LiDAR added for higher automation.
- Front cameras, surround cameras and interior driver monitoring cameras make up camera sales.
- Mobileye cut average system price to USD 48.5 in the second quarter of 2026, from USD 49.7 in the same quarter of 2025.[2]
Why do safety systems lead ADAS sales by application?
Safety systems are projected to lead application sales with 80.1% share in 2026, ahead of parking assistance at an estimated 14.7% and driver monitoring at about 5.2%.
Table 9: Application Share for the ADAS Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Safety Systems | 80.1% |
| Parking Assistance | 14.7% |
| Driver Monitoring | 5.2% |
| Total | 100.0% |
Mandates and ratings give safety systems the lead, a projected 80.1% share in 2026, as braking, cruise, lane, blind spot and collision functions all count toward approval or star scores. Parking assistance, an estimated 14.7%, is a comfort feature that buyers choose on larger cars and SUVs. Driver monitoring, about 5.2%, is small today and growing quickly, since Euro NCAP now rewards systems that react differently to alert and distracted drivers.[4] Cabin cameras for drowsiness and distraction are a separate growth line, and the driver monitoring system market is forecast to grow at an 8.1% CAGR, close to the ADAS rate as EU rules spread to every new car. Safety systems will keep most of the value.
- AEB, ACC, lane keeping, blind spot detection and collision warning make up the safety systems group.
- Euro NCAP said on 12 October 2026 that the XPENG X9 speed assistance failed effectiveness benchmarks in a 2,000 km real-world test.[4]
Why does OEM fitment lead ADAS sales by sales channel?
OEM fitment is expected to lead sales channel demand with 62% share in 2026, against an estimated 38% for the aftermarket.
Table 10: Sales Channel Share for the ADAS Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 62% |
| Aftermarket | 38% |
| Total | 100.0% |
Factory fitment is the only route to type approval, so OEM channels are expected to lead with a 62% share in 2026. The aftermarket, an estimated 38%, covers retrofit kits for fleets, replacement radars and cameras after collisions, and the recalibration work that follows windscreen and bumper repairs. Each recalibration needs a homologated procedure, and the automotive homologation services market is predicted to rise at a 3.2% CAGR, slower than ADAS, as approval work shifts toward software updates. Aptiv reported second quarter 2026 revenue of USD 3.3 billion, up 2%, with North America up 10%.[8] OEM channels will keep the lead, and repair shops will keep growing the aftermarket.
- Factory-fitted packages on new vehicles make up OEM sales.
- Aptiv completed the separation of the former Electrical Distribution Systems segment as Versigent on 1 April 2026.[8]
What are the drivers, restraints, and opportunities in the ADAS market?
Registration rules and safety ratings make ADAS standard on new vehicles. Price pressure from carmakers and shifting regulatory timelines squeeze suppliers, and Level 2 packages for mid-priced cars open the largest volume.
- Driver: Regulators and rating bodies are turning braking, lane and attention functions into standard equipment, so every new model needs a sensor set.
- Restraint: Carmakers award large platforms on price, and changing compliance dates make supplier capacity planning harder.
- Opportunity: Level 2 packages moving down to mid-priced cars and emerging markets open the largest unit volume for radar, camera and compute suppliers.
Rules and Ratings Make ADAS Standard
Adoption of ADAS follows the rulebook more closely than buyer choice. The EU applied advanced emergency braking with pedestrian and cyclist detection to all new cars and vans on 7 July 2026.[1] Euro NCAP's 2026 protocols score driver state monitoring and the use of physical controls.[4] Carmakers will fit full safety packages on base trims to protect five-star ratings.
Price Pressure and Shifting Deadlines Squeeze Suppliers
Producers of ADAS hardware face falling unit prices and moving compliance dates. Mobileye's average system price fell to USD 48.5 in the second quarter of 2026.[2] The US DOT is preparing a proposal to give carmakers two more years for FMVSS 127 compliance, Nelson Mullins reported on 22 April 2026.[6] FMI's view is that suppliers will need higher volumes per platform to hold margins. Capacity built for a 2029 US deadline may stay idle longer if the extension passes.
Level 2 for Mid-Priced Cars Opens Volume
Mid-priced cars in emerging economies are the next source of growth for the ADAS market. Hyundai Mobis and Qualcomm named India as a fast-growing market for driving and parking solutions in January 2026.[7] Valeo was selected by a leading Indian carmaker to deploy advanced ADAS systems in May 2026.[5] Low-cost Level 2 packages are bringing radar and camera fusion to a new tier of first-time buyers, and suppliers with local plants will gain those programmes.
Which country CAGRs are profiled in the ADAS market?
Table 11: Country CAGR Comparison for the ADAS Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 14.3% |
| China | 13.1% |
| United States | 12.6% |
| South Korea | 12.5% |
| Japan | 12.4% |
| Germany | 12.2% |
| United Kingdom | 11.9% |
How do country-level CAGRs compare in the ADAS market?
Indian carmakers are moving radar and camera packages into mid-priced models, and Valeo opened a vision camera assembly line in India in April 2026.[5] FMI's model shows India at 14.3%, the highest in the table, with China on 13.1% as domestic brands fit Level 2 on export models. The United States, on 12.6%, gains from the AEB standard. Korean and Japanese rates are a fraction lower, 12.5% and 12.4%, as both countries already fit AEB widely. Germany matches the global 12.2%. Slower fleet renewal leaves the United Kingdom on 11.9%, short of the 12.2% rate set for the ADAS market as a whole.
- Mid-priced models with radar and camera packages carry India.
- Export models from Chinese brands are adding Level 2 features in China.
- The FMVSS 127 AEB standard anchors fitment in the United States.
- Korean suppliers are pairing sensors with new compute platforms in South Korea.
- Japanese carmakers are spreading Level 2 highway assist across model lines.
- EU registration rules push full safety packages in Germany.
- In the United Kingdom, Euro NCAP scores shape fleet and retail choices.
Full report country CAGRs cover: India, with 14.3%, and China, with 13.1%, form the fastest group. Next comes a tight cluster led by the United States (12.6%), with South Korea (12.5%) and Japan (12.4%) just behind. Germany is level with the global 12.2%, the United Kingdom closes on 11.9%, and other standard countries are included at regional level.
Country-wise Analysis
India ADAS Market Outlook (2026 to 2036)
India heads the ADAS table with a forecast 14.3% CAGR. Valeo was selected by one of India's leading carmakers to deploy advanced ADAS systems in May 2026, and opened a vision camera line in the country in April.[5] Hyundai Mobis and Qualcomm named India as a target for low-cost driving and parking solutions.[7] Mid-priced SUVs will carry most of the new fitment.
Key takeaway: Local camera lines and mid-priced SUVs drive India.
China ADAS Market Outlook (2026 to 2036)
For China, the forecast CAGR is 13.1%. Valeo's original equipment sales in China fell 8.9% like for like in the first half of 2026, and the company expects to return to growth with Chinese carmakers in the second half.[5] Domestic brands are fitting Level 2 as standard on many models, and local chip and software suppliers compete hard on price.
Key takeaway: Standard Level 2 fitment and local suppliers shape China.
United States ADAS Market Outlook (2026 to 2036)
In the FMI outlook, the United States grows at a 12.6% CAGR. FMVSS 127 requires AEB and pedestrian AEB on light vehicles from 1 September 2029, and the DOT is preparing a proposal for two more years of lead time.[6] Aptiv reported 10% higher revenue in North America in the second quarter of 2026.[8] Carmakers will keep fitting AEB ahead of the deadline, as most models already carry the hardware.
Key takeaway: The AEB standard keeps the United States above the global pace.
South Korea ADAS Market Outlook (2026 to 2036)
Hyundai Mobis signed an MOU with Qualcomm at CES 2026 to co-develop ADAS and parking solutions on the Snapdragon Ride Flex SoC.[7] Euro NCAP rated the Kia EV2 five stars under the 2026 protocols, with driver state monitoring among the reasons.[4] Korean carmakers selling in Europe will carry those systems across ranges, which supports a 12.5% CAGR for South Korea.
Key takeaway: Korean supplier platforms and export ratings support South Korea.
Japan ADAS Market Outlook (2026 to 2036)
Japanese carmakers fit collision mitigation braking and lane keeping across most new models, and Level 3 approvals on selected premium cars have opened a small high-value segment. FMI places Japan at a 12.4% CAGR, a fraction above the global rate, as replacement of the vehicle parc with ADAS-equipped models continues.
Key takeaway: Broad standard fitment keeps Japan near the global pace.
Germany ADAS Market Outlook (2026 to 2036)
Germany's 12.2% in FMI's model equals the global CAGR. EU rules required driver distraction warning and pedestrian-detecting AEB on every newly registered car and van from 7 July 2026.[1] Mobileye said MOIA started public robotaxi testing in Hamburg with safety drivers.[2] German premium brands will lead Level 3 approvals in Europe.
Key takeaway: EU rules and premium Level 3 programmes carry Germany.
United Kingdom ADAS Market Outlook (2026 to 2036)
British buyers and fleets use Euro NCAP stars when choosing cars, and the 2026 protocols reward driver monitoring and physical controls.[4] The United Kingdom is projected to grow at an 11.9% CAGR, short of the 12.2% rate set for the ADAS market as a whole, as a smaller new car market slows fleet renewal.
Key takeaway: Rating-led fleet buying sets a slower pace in the United Kingdom.
Who are the notable companies in the ADAS market?
Bosch, Continental, Denso, Aptiv, Valeo, ZF, Magna, Mobileye, NXP Semiconductors and Texas Instruments are the profiled companies.
Tier one system suppliers and chip and vision platform companies make up the ten names in FMI's company set. Mobileye reported second quarter 2026 revenue of USD 508 million, close to the USD 506 million of Q2 2025, on 10.0 million systems shipped.[2] Valeo's BRAIN Division held sales at EUR 2,527 million in the first half.[5] NXP Semiconductors grew automotive revenue 12% to USD 1,938 million.[3] Aptiv reported USD 3.3 billion of second quarter revenue.[8] Bosch, Continental, Denso, ZF, Magna and Texas Instruments complete the group.
- Tier one system suppliers: Bosch, Continental, Denso, Aptiv, Valeo, ZF and Magna.
- Chip and vision platform suppliers: Mobileye, NXP Semiconductors and Texas Instruments.
Competitive Benchmarking: ADAS Market
Table 12: Competitive Benchmarking for the ADAS Market (qualitative documentation ratings), 2026
| Company | Radar and Camera | Compute and Software | OEM Programme Reach | Recency |
|---|---|---|---|---|
| Mobileye | High | High | High | High |
| Valeo | High | Medium | High | High |
| Aptiv | Medium | High | High | High |
| NXP Semiconductors | High | Medium | Medium | High |
| Bosch | High | High | High | Medium |
Scores track how fully dated 2025 and 2026 releases document each capability, and carry no ranking of ADAS sales.
Key Developments in the ADAS Market
- On 12 October 2026, Euro NCAP published ratings under the 2026 protocols, including five stars for the Kia EV2.[4]
- On 4 August 2026, Aptiv said North America revenue rose 10% in the second quarter.[8]
- On 28 July 2026, NXP Semiconductors reported automotive revenue of USD 1,938 million.[3]
- On 23 July 2026, Mobileye raised 2026 revenue guidance and reported a Stellantis design award.[2]
- On 22 July 2026, Valeo reported BRAIN Division sales of EUR 2,527 million for the first half.[5]
- On 15 July 2026, ERTICO reported that new EU safety rules applied to all new cars and vans from 7 July.[1]
- On 22 April 2026, Nelson Mullins reported the DOT plan to extend FMVSS 127 lead time.[6]
- On 7 January 2026, Hyundai Mobis and Qualcomm signed an MOU on ADAS and SDV solutions.[7]
Key Players in the ADAS Market
Tier One System Suppliers
- Bosch
- Continental
- Denso
- Aptiv
- Valeo
- ZF
- Magna
Chip and Vision Platform Suppliers
- Mobileye
- NXP Semiconductors
- Texas Instruments
ADAS Market - Report Scope
Table 13: Report Scope for the ADAS Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | System type; level of autonomy; component; vehicle type; sensor type; application; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Advanced driver assistance systems, including sensors, control units and software for cruise, braking, lane, blind spot, parking, monitoring and vision functions, fitted by vehicle makers or added in the aftermarket. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Bosch, Continental, Denso, Aptiv, Valeo, ZF, Magna, Mobileye, NXP Semiconductors, Texas Instruments |
| Forecast period | 2026 to 2036 |
ADAS Market - Research Methodology
Table 14: Research Methodology for the ADAS Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Supplier results and filings, chip maker releases, safety rating bodies, transport association reports and legal analysis of vehicle rules from May 2025 onward. |
| Desk Research | Desk research covers safety regulations, rating protocols, platform awards, sensor prices and supplier capacity. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 80.9 billion and the 12.2% CAGR for 2026 to 2036. |
| Data Validation | Shipment, revenue and rule dates were matched to the filing, rating release or legal update that first carried them. |
ADAS Market by Segments
ADAS Market segmented by System Type:
- Adaptive Cruise Control (ACC)
- Lane Departure Warning (LDW)
- Lane Keeping Assist (LKA)
- Blind Spot Detection (BSD)
- Automatic Emergency Braking (AEB)
- Forward Collision Warning (FCW)
- Traffic Sign Recognition (TSR)
- Parking Assist
- Pedestrian Detection System (PDS)
- Night Vision System (NVS)
- Driver Monitoring Systems (DMS)
- Surround View System (SVS)
ADAS Market segmented by Level of Autonomy:
- Level 1
- Level 2
- Level 3
- Level 4
- Level 5
ADAS Market segmented by Component:
- Hardware
- Software
ADAS Market segmented by Vehicle Type:
- Passenger Cars
- Light Commercial Vehicle
- Heavy Commercial Vehicle
ADAS Market segmented by Sensor Type:
- Radar
- Camera
- LiDAR
ADAS Market segmented by Application:
- Safety Systems
- Parking Assistance
- Driver Monitoring
ADAS Market segmented by Sales Channel:
- OEM
- Aftermarket
ADAS Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] ERTICO - ITS Europe. (2026, July 15). Safer cars, safer roads: new rules take effect. https://ertico.com/safer-cars-safer-roads-new-rules-take-effect
- [2] Mobileye Global Inc. (2026, July 23). Mobileye Releases Second Quarter 2026 Results, Updates Guidance, and Provides Business Overview. https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-second-quarter-2026-results-updates-guidance
- [3] NXP Semiconductors N.V. (2026, July 28). NXP Semiconductors Reports Second Quarter 2026 Results. https://mfn.se/all/a/nxp-semiconductors/nxp-semiconductors-reports-second-quarter-2026-results-5d29ebc9
- [4] Euro NCAP. (2026, October 12). Buttons are back for basic functions, Euro NCAP confirms in testing. https://www.euroncap.com/press-media/buttons-are-back-for-basic-functions-euro-ncap-confirms-in-testing/
- [5] Valeo. (2026, July 22). Valeo H1 2026 Results. https://www.globenewswire.com/news-release/2026/07/22/3331600/0/en/Valeo-H1-2026-Results.html
- [6] Nelson Mullins. (2026, April 22). The Road Ahead for FMVSS 127: Whither the Automatic Emergency Braking Mandate? https://www.nelsonmullins.com/insights/blogs/driving-forward-developments-in-transportation-law-and-innovation/all/the-road-ahead-for-fmvss-127-whither-the-automatic-emergency-braking-mandate
- [7] Hyundai Mobis and Qualcomm Technologies (PR Newswire). (2026, January 7). Hyundai Mobis and Qualcomm Sign Comprehensive Agreement to Collaborate on SDV architecture for ADAS. https://tools.prnewswire.com/en-us/live/20823/release/20260107EN54998
- [8] Aptiv PLC. (2026, August 4). Aptiv Reports Second Quarter 2026 Financial Results. https://www.aptiv.com/en/newsroom/article/aptiv-reports-second-quarter-2026-financial-results
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the ADAS market during 2026?
- What market size is projected by 2036?
- Which system type holds notable share?
- Which level of autonomy holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the ADAS market expected in 2026?
The ADAS market is expected to reach USD 80.9 billion in 2026 in the FMI model, from USD 72.1 billion in 2025. Sales of ADAS are projected to reach USD 255.8 billion by 2036.
What CAGR is projected for the ADAS market through 2036?
A 12.2% CAGR from 2026 to 2036 is projected for the ADAS market. Mandatory safety equipment and Level 2 packages on mid-priced cars carry that growth.
Which system type holds a notable market share in 2026?
Adaptive cruise control (ACC) is expected to lead with 19% share in 2026. Automatic emergency braking (AEB) follows at an estimated 16.5%.
Which level of autonomy holds a notable market share in 2026?
Level 2 is projected to lead with 51.4% share. Level 1 follows at 36%.
Which country has a notable expansion outlook through 2036?
India leads the FMI country table with a 14.3% CAGR. China follows at 13.1%.
Who are the key companies in the ADAS market?
Bosch, Continental, Denso, Aptiv, Valeo, ZF and Magna lead the tier one supplier group. Mobileye, NXP Semiconductors and Texas Instruments lead chips and vision platforms.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By System Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By System Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By System Type, 2026 to 2036
- Adaptive Cruise Control (ACC)
- Lane Departure Warning (LDW)
- Lane Keeping Assist (LKA)
- Blind Spot Detection (BSD)
- Automatic Emergency Braking (AEB)
- Forward Collision Warning (FCW)
- Traffic Sign Recognition (TSR)
- Parking Assist
- Pedestrian Detection System (PDS)
- Night Vision System (NVS)
- Driver Monitoring Systems (DMS)
- Surround View System (SVS)
- Y-o-Y Growth Trend Analysis By System Type, 2021 to 2025
- Absolute $ Opportunity Analysis By System Type, 2026 to 2036
- Global Market Analysis and Forecast, By Level of Autonomy, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Level of Autonomy, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Level of Autonomy, 2026 to 2036
- Level 1
- Level 2
- Level 3
- Level 4
- Level 5
- Y-o-Y Growth Trend Analysis By Level of Autonomy, 2021 to 2025
- Absolute $ Opportunity Analysis By Level of Autonomy, 2026 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- Hardware
- Software
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger Cars
- Light Commercial Vehicle
- Heavy Commercial Vehicle
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sensor Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sensor Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sensor Type, 2026 to 2036
- Radar
- Camera
- LiDAR
- Y-o-Y Growth Trend Analysis By Sensor Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sensor Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Safety Systems
- Parking Assistance
- Driver Monitoring
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By System Type
- By Level of Autonomy
- By Component
- By Vehicle Type
- By Sensor Type
- By Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mobileye
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Valeo
- Aptiv
- NXP Semiconductors
- Bosch
- Continental
- Denso
- ZF
- Magna
- Texas Instruments
- Mobileye
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


