

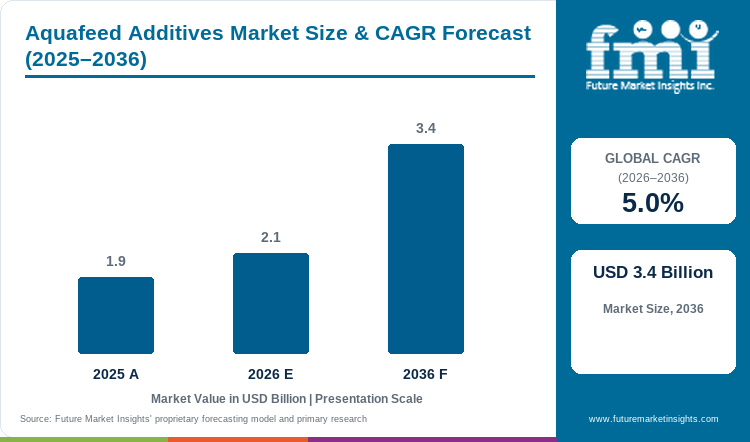
- Market Size (2026)
- USD 2.1 Bn
- Forecast (2036)
- USD 3.4 Bn
- CAGR (2026 to 2036)
- 5.0%
How big is Aquafeed Additives Market in 2026?
USD 2.1 billion in 2026 and USD 3.4 billion by 2036, expanding at 5.0% CAGR.
Sales of aquafeed additives are estimated to rise at 5.0% CAGR through 2036, increasing valuation from USD 1.9 billion in 2025 to USD 2.1 billion in 2026, and reaching USD 3.4 billion by 2036. Kemin Industries describes aquafeed enzymes as formulation tools for releasing nutrients from plant-rich raw materials in its April 2026 technical guidance. Feed mills are using such low-inclusion inputs when nutrient recovery and processing stability justify their cost inside recurring commercial formulas.
Japan is projected at 5.1% CAGR through 2036 compared with 4.1% for Germany. The German Federal Statistical Office recorded about 16,600 tonnes of farmed fish in 2025, with production concentrated in carp and trout. Japanese producers face a different cost structure because feed carries a larger share of fed marine aquaculture expenses. The rate difference therefore follows distinct production economics instead of a simple ranking of current market size.
Key Takeaways of Aquafeed Additives Market
- Farmed aquatic-animal output is expanding the recurring feed base and increasing demand for additives that improve nutrient use under commercial production conditions.
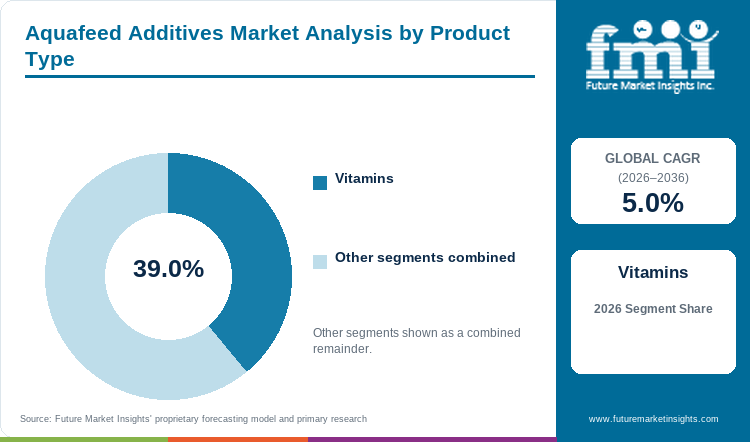
- By product type, vitamins are estimated to hold 39.0% in 2026, supported by recurring micronutrient requirements during fish and shrimp production stages.
- In 2026, carps are expected to lead application with 30.0% share, influenced by large freshwater feed volumes and persistent feed-efficiency pressure.
- By source, plant inputs are forecast to represent 96.0% in 2026, shaped by phytogenic and other non-animal functional formulations.
- Species-specific efficacy and regulatory eligibility delay supplier changes because technically credible additives still require lawful use and stable processing performance.
- Key players in the aquafeed additives market include Cargill, Incorporated, ADM, dsm-firmenich, BASF SE, Evonik Industries AG, Kemin Industries, Inc., Adisseo, and Alltech, Inc.
Analyst Perspective
"Feed mills are paying for additives that survive processing and produce measurable biological returns under local species conditions. Suppliers need regulatory access and formulation evidence together because either weakness can prevent a successful trial from becoming routine purchasing."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Aquafeed Additives Market segmented?
Aquafeed Additives Market is segmented by Product Type, Application, Source, and Region. Forecast period from 2026 to 2036.
Product type covers vitamins, antioxidants, antibiotics, amino acids, minerals, feed acidifiers, and feed enzymes. Application includes carps, marine shrimps, tilapia, catfish, salmon, sea bass, and others. Source distinguishes plant, animal, and micro-organism inputs. Region covers North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
How do vitamins shape demand within the product type category?
Vitamin supplementation remains a recurring formulation requirement because feed processing and ingredient variation can change micronutrient delivery. BASF currently lists aquaculture among the species served by its animal-nutrition platform and vitamins among its feed-ingredient portfolio. Feed formulators compare stability and bioavailability before setting inclusion rates inside a feed premix specification.
- By product type, vitamins are estimated to hold 39.0% in 2026, supported by repeated micronutrient requirements during growth and production transitions.
- The segment retains recurring purchasing because a validated vitamin program must remain stable during storage and feed manufacturing before it reaches the target species.
What supports carps within the application category?
Carp production rewards additives that improve nutrient use without materially raising the cost of each tonne of formulated feed. FAO production data identify grass carp as a high-volume farmed finfish within global aquaculture output. Large freshwater volumes keep fish feed formulations focused on economical micronutrients and digestibility support that can be repeated through commercial production cycles.
- Based on application, carps are projected to account for 30.0% in 2026, influenced by high freshwater feed volumes and formulation economics.
- Carp-focused feed programs favor additives with species-relevant proof because small performance gains must remain economical at substantial compound-feed volumes.
Why do plant sources represent 96.0% of source revenue?
Plant-origin additives give formulators phytobiotic and organic-acid options without requiring animal-derived active materials. Adisseo currently maps Sanacore GM and Bacti-Nil Aqua to health management in fish and shrimp functional feeds. Formulators use phytogenic feed additives when the active material addresses a defined health or feed-efficiency condition.
- By source, plant inputs are forecast to represent 96.0% in 2026, shaped by broad use of phytogenic and plant-origin functional compounds.
- Plant sourcing also complements lower-fishmeal feed strategies because formulators can combine functional additives with changing protein ingredients without making the additive animal-derived.
What are the drivers, restraints and opportunities in the Aquafeed Additives Market?
Aquaculture output expands the feed base, regulatory authorization slows switching, and processing-stable enzymes improve nutrient recovery from plant-rich formulations.
- Driver: Expanding aquaculture output increases the recurring volume of formulated feed that must deliver consistent nutrition and animal performance.
- Restraint: Regulatory authorization and species-specific efficacy requirements can delay supplier changes even when an additive performs well technically.
- Opportunity: Processing-stable enzymes can improve nutrient recovery from plant-rich diets without requiring feed mills to replace their existing production route.
Aquaculture scale enlarges the addressable base for animal feed additives used in recurring commercial feed production. FAO reported in June 2026 that aquatic-animal aquaculture reached 103 million tonnes during 2024 and supplied more than half of global aquatic-animal production. Feed mills serving this output are repeatedly buying low-inclusion inputs because each production cycle must reproduce nutrient availability and health performance. Additives earn repeat use when species evidence converts a biological response into a formulation rule that commercial batches can reproduce.
Market access constrains switching because feed additives cannot be treated as interchangeable ingredients between jurisdictions. The European Commission requires authorization before a feed additive enters the EU market and ties approvals to specific animal categories plus conditions of use. Feed manufacturers therefore evaluate feed acidifiers against both technical performance and the approved species route. A strong trial cannot compensate for a missing authorization or an unsupported use claim during commercial qualification.
Plant-rich diets increase the value of aquafeed enzymes that release nutrients otherwise limited by phytate and other antinutritional factors. Kemin published aquafeed guidance in June 2026 that links precision enzyme systems with nutrient availability and formulation economics. Feed mills still need enzyme activity to survive processing and match the actual ingredient mix before they assign a matrix value. Heat stability and substrate fit determine whether an enzyme becomes part of a recurring formulation instead of a trial inclusion.
Which country CAGRs are profiled in the Aquafeed Additives Market?
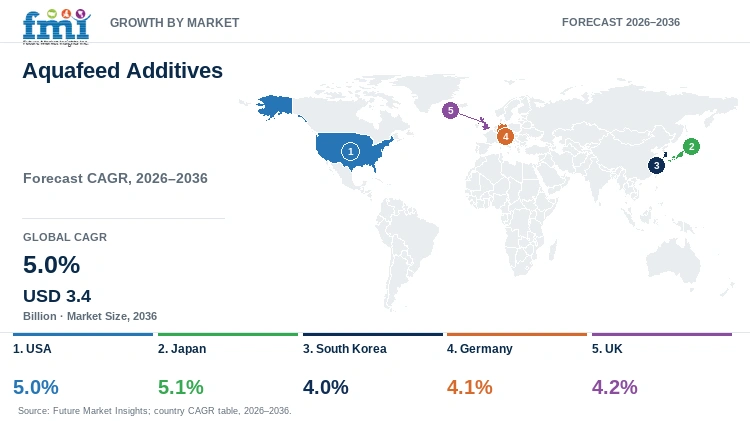
| Country | CAGR |
|---|---|
| USA | 5.0% |
| Japan | 5.1% |
| South Korea | 4.0% |
| Germany | 4.1% |
| UK | 4.2% |
How do country-level CAGRs compare in the Aquafeed Additives Market?
Japan is projected at 5.1% CAGR and the USA at 5.0% under different national demand conditions. The UK records 4.2%, Germany 4.1% and South Korea 4.0% across their local feed systems. The 1.1-point spread describes forecast speed instead of current revenue size. Feed economics and authorization routes determine how distinct rates convert into supplier qualification and repeat orders.
- US aquaculture spans many species and farm formats, so suppliers face a fragmented formulation base instead of one national feed specification.
- Japanese marine aquaculture carries unusually high feed-cost exposure, making nutrient-use economics central to additive evaluation.
- South Korean farms are managing lower feed use alongside weather stress, which raises the value of efficiency and resilience evidence.
- German production combines carp and salmonid systems, requiring additive suppliers to support different nutritional programs within EU authorization rules.
- UK commercial entry depends heavily on Great Britain authorization while salmon production creates concentrated demand for technically validated nutrition inputs.
Comparable CAGRs can therefore produce different purchasing conditions because local operating costs and qualification rules are not interchangeable. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- US aquaculture has a broad commercial base that distributes additive demand among food fish and crustacean producers. The USA is projected to grow at 5.0% CAGR through 2036, supported by recurring feed requirements within a diverse farm structure. USDA NASS recorded 3,453 aquaculture farms with sales in the 2023 national census. Feed suppliers compare animal feed probiotics with other functional inputs only after ingredient status and species directions satisfy federal feed rules. Products need reproducible efficacy without adding a compliance burden before mills move them into regular formulas.
- Japanese fish farmers operate under strong feed-cost pressure in fed marine aquaculture production systems. Aquafeed additive demand in Japan is forecast to rise at 5.1% CAGR over the forecast period, influenced by efforts to reduce fishmeal exposure and improve feed efficiency. The Fisheries Agency states that feed costs account for about 70% of fish-aquaculture costs. Mills evaluate feed amino acids and other additives against nutrient utilization before accepting a different formulation. Local trials still need performance data from the species and processing conditions used by Japanese producers.
- South Korean fish culture is balancing modest production growth with lower feed use and recurring high-temperature pressure. South Korea is estimated to post 4.0% CAGR over the forecast period, shaped by demand for more biological performance from each unit of feed. Statistics Korea reported that 2025 fish-culture output rose 1.1% as feed use fell 4.6%. The operating pattern raises interest in microbial feed additives and other functional tools that can show a usable response under local conditions. Suppliers still need species evidence before mills convert an efficiency claim into regular purchasing.
- Germany combines carp and salmonid aquaculture without relying on one dominant feed system. Germany is forecast to grow at 4.1% CAGR through 2036, linked to recurring nutrition demand within these freshwater categories. Destatis recorded about 16.6 thousand tonnes of farmed fish nationwide during 2025 aquaculture production. Common carp contributed about 4.3 thousand tonnes and salmonids (primarily rainbow trout) about 9.6 thousand tonnes within that national total. EU authorization determines which additives can be supplied for the intended species and conditions of use. Suppliers compete on documentation and formulation economics during mill approval for recurring use in these freshwater feed systems.
- UK aquaculture purchasing is centered on technically demanding fish production and a regulated market-access route. The UK is expected to maintain 4.2% CAGR through 2036, supported by repeat formulation demand tied to production economics. Food Standards Agency guidance issued in June 2026 states that only authorized feed additives may be marketed or used in Great Britain. Suppliers need species-relevant evidence and lawful status before mills can make a routine formulation change. Qualification speed therefore limits supplier switching more directly than the underlying need for functional nutrition.
Who are the notable companies in the Aquafeed Additives Market?
Cargill, Incorporated, ADM, dsm-firmenich, BASF SE, Evonik Industries AG, Kemin Industries, Inc., Adisseo, and Alltech, Inc. are active within the defined aquafeed additives supply boundary.
Competition in aquafeed additives includes integrated nutrition groups and amino-acid specialists alongside aquaculture-focused functional additive developers. Entry depends on species evidence plus processing stability and lawful-use documentation instead of corporate scale alone. Direct positions combine aquaculture application support with several in-scope additive functions. Natural feed additives can complement this portfolio when suppliers map each active material to a defined fish or shrimp formulation.
- Cargill and ADM combine broad feed-additive portfolios with direct aquaculture application evidence for fish and shrimp formulations. dsm-firmenich and BASF SE also cover multiple in-scope additive families with documented aquaculture use and technical support.
- Evonik Industries AG focuses on amino-acid nutrition with aquaculture application support linked to feed-efficiency decisions. Kemin Industries, Inc. covers enzymes and functional aquaculture ingredients with technical guidance for commercial feed formulations.
- Adisseo competes through functional nutrition programs backed by aquaculture field support for health and feed-efficiency decisions. Alltech, Inc. supports aquaculture programs through nutrition research and application guidance aimed at resilience under commercial production conditions.
Competitive Benchmarking: Aquafeed Additives Market
| Company | Aquaculture-Specific Additive Portfolio | In-Scope Functional Breadth | Aquaculture Technical Support | Geographic Reach |
|---|---|---|---|---|
| Cargill, Incorporated | High | High | High | Global |
| ADM | High | Medium | High | Global |
| dsm-firmenich | High | High | High | Global |
| BASF SE | High | High | Medium | Global |
| Evonik Industries AG | Medium | Medium | High | Global |
| Kemin Industries, Inc. | High | High | High | Global |
| Adisseo | High | High | High | Global |
| Alltech, Inc. | Medium | Medium | High | Global |
Scoring basis: High portfolio evidence requires several direct aquaculture additive solutions documented for commercial fish or shrimp use. Medium portfolio evidence requires a narrower direct set that still supports at least one aquaculture formulation route. High functional breadth covers several product types defined in this report under the same current supplier platform. Medium functional breadth covers a smaller verified set of in-scope additive types. High technical support requires dedicated aquaculture trials or research with formulation services available to customers. Medium technical support reflects narrower public evidence for aquaculture-specific technical functions. Low identifies a documented narrow position rather than missing information.
Key Developments in the Aquafeed Additives Market
- In September 2026, ADM inaugurated its Tianjin Early Nutrition Aqua Feed Facility for hatchery and nursery fish plus shrimp feeds. The operating facility connects local production with APAC aquaculture research and application support.
- In July 2026, Evonik completed backward integration of its global MetAMINO production network by adding on-site intermediate production at Mobile, Alabama. The action strengthened feed-grade methionine supply reliability across the Americas.
- In February 2026, dsm-firmenich entered an agreement to divest its Animal Nutrition & Health business to CVC Capital Partners for an enterprise value of approximately €2.2 billion. The divested business excludes feed enzymes, which were sold to Novonesis in 2025, and also excludes Bovaer and Veramaris, which remain with dsm-firmenich. The transaction is expected to complete by the end of 2026, subject to regulatory approvals.
Key Players in the Aquafeed Additives Market
Broad aquaculture nutrition platforms
- Cargill, Incorporated
- ADM
- dsm-firmenich
- BASF SE
Specialist feed-additive and functional nutrition platforms
- Evonik Industries AG
- Kemin Industries, Inc.
- Adisseo
- Alltech, Inc.
Aquafeed Additives Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, application, source and region. |
| Quantitative Units | Revenue in USD billion and CAGR in %. |
| Market Definition | Revenue includes vitamins, antioxidants, antibiotics, amino acids, minerals, feed acidifiers and feed enzymes sold for aquafeed applications. Complete aquafeed and adjacent macro feed ingredients are excluded. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, Japan, South Korea, Germany, UK, and 20+ countries included in the full report. |
| Key Companies Profiled | Cargill, Incorporated, ADM, dsm-firmenich, BASF SE, Evonik Industries AG, Kemin Industries, Inc., Adisseo, and Alltech, Inc. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Aquafeed Additives Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Aquafeed Additives Market by Segments
Aquafeed Additives Market segmented by Product Type:
- Vitamins
- Antioxidants
- Antibiotics
- Amino acids
- Minerals
- Feed Acidifiers
- Feed Enzymes
Aquafeed Additives Market segmented by Application:
- Carps
- Marine Shrimps
- Tilapia
- Catfish
- Salmon
- Sea Bass
- Others
Aquafeed Additives Market segmented by Source:
- Plant
- Animal
- Micro-organisms
Aquafeed Additives Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Future Market Insights. (2026). Aqua Feed Additives Market.
- Kemin Industries. (2026, April 3). Enzymes in Aquaculture: Unlocking Nutritional Efficiency for a Sustainable Future.
- German Federal Statistical Office (Destatis). (2025, May 27). Aquaculture production businesses and volume produced.
- BASF. (n.d.). Animal Nutrition. Retrieved September 18, 2026.
- Food and Agriculture Organization of the United Nations. (2022). Aquaculture production.
- Adisseo. (n.d.). Aquaculture Health Strategy. Retrieved September 18, 2026.
- Food and Agriculture Organization of the United Nations. (2026, June 16). SOFIA 2026: Global fisheries and aquaculture production reaches new highs.
- European Commission. (n.d.). Feed additives. Retrieved September 18, 2026.
- Kemin Industries. (2026, June 16). From Supplement to Strategy: Why Enzymes Are Becoming Foundational in Aquafeed.
- USDA National Agricultural Statistics Service. (2024, December 16). USDA Releases the 2023 Census of Aquaculture Results.
- Fisheries Agency of Japan. (2025, June 6). FY2024 White Paper on Fisheries: Trends in fisheries and FY2025 fisheries policy.
- Ministry of Data and Statistics, Republic of Korea. (2026, March 20). Preliminary Results of the Survey on the Status of Fish Culture in 2025.
- German Federal Statistical Office (Destatis). (2026, June 5). Aquaculture production businesses and volume produced in 2025 by selected species and Länder.
- Food Standards Agency. (2026, June 25). Guidance for trials using feed additives not authorised.
- Cargill. (n.d.). Our performance in 2025. Retrieved September 18, 2026.
- Alltech Coppens. (n.d.). About. Retrieved September 18, 2026.
- ADM. (2026, September 16). ADM Inaugurates Tianjin Early Nutrition Aqua Feed Facility, Strengthening Aquaculture Nutrition Capabilities in China and Across Asia Pacific.
- Evonik Industries AG. (2026, July 16). Evonik completes backward integration of its global MetAMINO production network.
- dsm-firmenich. (2026, February 9). dsm-firmenich announces agreement to divest Animal Nutrition & Health to CVC Capital Partners.
- Evonik Industries AG. (2026, June 23). Evonik optimizes methanol supply for its methionine production network in Europe.
- Coastal Aquaculture Authority of India. (2026). CAA Approved Antibiotic-free Aquaculture Inputs.
- dsm-firmenich. (2026, August 25). dsm-firmenich Animal Nutrition & Health releases updated Digital SalmoFan color measurement tool for trout.
- ADM. (2026, June 11). ADM Bern Aqua is First BAP-Certified Producer in Belgium.
- Adisseo. (2026, April 23). Health-promoting feed additives to enhance resilience, profitability and environmental efficiency in shrimp farming.
- Cargill. (n.d.). Product highlights from 2025: Supporting salmon health in Norway’s closed farming systems. Retrieved September 18, 2026.
- dsm-firmenich Animal Nutrition & Health. (2026, May 5). Putting the Hy-D back in diets.
- Evonik Industries AG. (2026, March 5). Evonik to increase its global price for MetAMINO.
- Servicio Nacional de Aduana del Ecuador. (2026, May 2). SENAE-SGN-2026-0064-RE.
- Adisseo. (2026, August 31). Q2 2026: high double-digit quarter-to-quarter growth across all business performance metrics.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the aquafeed additives market in 2026 and what value is projected for 2036?
- Which operating conditions convert aquaculture expansion into recurring additive purchases?
- Why do vitamins hold 39.0% of product type revenue in the 2026 base year?
- Why do carps account for 30.0% of application revenue during 2026?
- Why do plant sources represent 96.0% of source revenue in the base year?
- How do regulatory authorization and species proof affect supplier switching?
- How do the five profiled country CAGRs differ in their commercial meaning?
- Which companies combine direct aquaculture additive capability with technical support?
- Which 2026 company actions are changing supply, validation and formulation support?
Frequently Asked Questions
How big is the Aquafeed Additives Market in 2026?
The aquafeed additives market is valued at USD 2.1 billion in 2026 and is projected to reach USD 3.4 billion by 2036. Recurring aquaculture feed production keeps nutritional and functional inputs inside regular feed-mill purchasing decisions.
What is the CAGR of the Aquafeed Additives Market from 2026 to 2036?
The aquafeed additives market is projected to grow at 5.0% CAGR between 2026 and 2036. Growth depends on additives producing measurable nutrient or feed-efficiency results under commercial species and processing conditions.
Which product type leads the Aquafeed Additives Market in 2026?
The vitamins segment is estimated to hold 39.0% of product type revenue in the aquafeed additives market during 2026. Feed formulators use repeated micronutrient supplementation when vitamins remain stable through storage and commercial feed processing.
Which source segment leads the Aquafeed Additives Market in 2026?
The plant segment is forecast to represent 96.0% of source revenue in the aquafeed additives market during 2026. Phytogenic and other plant-origin compounds support health and feed-efficiency programs without requiring animal-derived active materials.
Which application segment leads the Aquafeed Additives Market in 2026?
The carps segment is expected to hold 30.0% of application revenue in the aquafeed additives market during 2026. Large freshwater feed volumes keep additive economics closely tied to nutrient utilization and repeatable performance.
Which countries share the 5.0% profiled CAGR through 2036?
Japan is projected to grow at 5.1% CAGR and the USA at 5.0% through 2036 within the profiled country set. Their distinct rates reflect different mechanisms involving high feed-cost exposure in Japan and farm diversity in the USA.
Which companies are active in the Aquafeed Additives Market?
Key companies operating in the aquafeed additives market include Cargill, Incorporated, ADM, dsm-firmenich, BASF SE, Evonik Industries AG, Kemin Industries, Inc., Adisseo, and Alltech, Inc. These suppliers compete through different combinations of additive breadth and aquaculture technical support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Vitamins
- Antioxidants
- Antibiotics
- Amino acids
- Minerals
- Feed Acidifiers
- Feed Enzymes
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Carps
- Marine Shrimps
- Tilapia
- Catfish
- Salmon
- Sea Bass
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Plant
- Animal
- Micro-organisms
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill, Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ADM
- dsm-firmenich
- BASF SE
- Evonik Industries AG
- Kemin Industries, Inc.
- Adisseo
- Alltech, Inc.
- Cargill, Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


