
- Market Size (2026)
- USD 8.3 Bn
- Forecast (2036)
- USD 15.6 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is At-Home Testing Market in 2026?
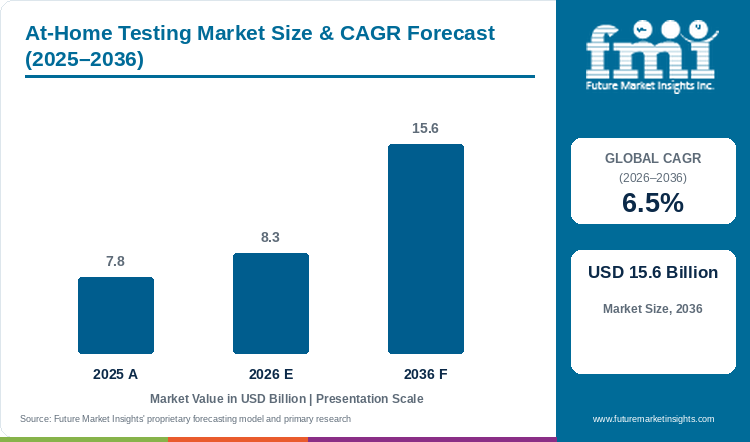
Global at-home testing industry valuation advances from a 2025 baseline of USD 7.8 billion to reach USD 8.3 billion in 2026 before hitting USD 15.6 billion by 2036 under a 6.5% CAGR.
Consumer and pharmacy adoption lifted the global at-home testing market size past its 2025 level of USD 7.8 billion to record USD 8.3 billion in 2026. Between 2026 and 2036, total market valuation is forecast to climb toward a 2036 target of USD 15.6 billion under a 6.5% CAGR, delivering USD 7.3 billion in ten-year industry expansion. Household adoption is growing steadily because patients want to check blood sugar and hormone levels or common infections at home instead of waiting for clinic lab appointments. Because shoppers prefer simple strip kits that show clear results in 15 minutes without a machine, Lateral Flow Strips hold an estimated 53.7% share of Assay Technology volume in 2026 and see much broader household use than niche cryptococcal antigen lateral flow assay tests used in specialty care. The practical value of home screening is confirmed by an April 2026 review in EClinicalMedicine covering 61 studies and 25,288,225 participants, where rapid self-tests detected 31 cases per 1,000 people at a 0.4% false-positive rate and reduced lost workdays. However, user mistakes when reading faint test lines and limited insurance coverage for retail test kits still act as key challenges that hold back repeat buying.
Key Market Trends & Insights
- By assay technology: Lateral Flow Strips are estimated at 53.7% of 2026 Assay Technology volume, linked to 15-minute visual readouts without cold-chain shipping.
- By distribution channel: Across distribution channels, Retail Pharmacy Chains are projected at 54.9% in 2026, resulting from walk-in respiratory and glucose strip purchases during prescription visits.
- By patient demographic: Adults 18-64 Years are forecast at 56.4% of Patient Demographic volume in 2026 because working-age households drive repeat fertility and metabolic self-monitoring.
- By sample type: By sample type, Capillary Whole Blood is expected to reach 44.7% in 2026, due to daily fingerstick glucose and lipid strip replenishment.
- By clinical indication: Among clinical indications, Metabolic Glucose Panels are anticipated at 37.9% in 2026, reinforced by multi-daily diabetic test strip consumption.
Regional Highlights
- Asia-Pacific pharmacy leadership: South Korea heads the eight evaluated consumer diagnostic nations at a 7.6% compound yearly expansion rate to 2036 via pharmacy multiplex respiratory cassettes.
- Broader country progression: Public screening programs in Australia post a 7.3% yearly expansion rate followed by USA drugstores at 6.2% and Canada provinces at 6.1%, while pharmacies in France record a 5.6% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the At-Home Testing Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 7.8 billion |
| Estimated Market Size in 2026 | USD 8.3 billion |
| Projected Market Size by 2036 | USD 15.6 billion |
| CAGR, 2026 to 2036 | 6.5% |
| Added Revenue, 2026 to 2036 | USD 7.3 billion |
Primary-care health systems and preventive-care payers face persistent colonoscopy and outpatient laboratory appointment backlogs that delay early cancer and chronic disease detection. When health plans mail pre-labeled specimen collection kits directly to patient homes, screening adherence rises without consuming clinic room capacity. In October 2026, Veterans Health Administration investigators published a cohort study in AJG across 643,933 mailed fecal immunochemical tests evaluated through September 2025 that documented a 40.2% return rate (230,427 testable kits) and detected adenomas in 68.0% of follow-up colonoscopies. As a result, health plans and pharmacy chains pair mailed collection programs with rapid test reader instruments to standardize household result reporting into electronic medical records.
Household Screening Pool and Kit-Volume Sizing
Table 2: Household Screening Pool and Kit-Volume Sizing for the At-Home Testing Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 7.8 | 8.3 | 15.6 |
| Households using self-tests annually (million) | 310 to 340 | 330 to 365 | 540 to 590 |
| Disposable test strips & cassettes per year (billion) | 6.8 to 7.5 | 7.2 to 8.0 | 12.5 to 14.2 |
| Average household annual self-test outlay (USD) | 22.5 to 25.0 | 23.5 to 26.2 | 27.0 to 30.5 |
Operational note: Volume ranges reflect daily capillary blood glucose strips and over-the-counter lateral flow cassettes plus mail-in molecular collection kits across retail and payer channels.
Public health agencies and commercial telehealth platforms require foolproof sample collection devices that maintain specimen integrity across ambient postal transit. Diagnostic kit manufacturers integrate spring-loaded safety lancets and stabilizing buffers perfected in HIV self-testing kits to reduce invalid specimen cancellations at central reference laboratories.
Per Capita & Pharmacy Distribution Sizing
Table 3: Per Capita and Household Spending Indicators for the At-Home Testing Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 951.2 | 1,000.0 | 1,733.3 |
| Annual procurement per regular screening user (USD) | 85.0 to 102.0 | 89.0 to 108.0 | 135.0 to 165.0 |
| Pharmacy & payer-reimbursed kit share (%) | 68.0% to 72.0% | 70.0% to 74.0% | 78.0% to 82.0% |
Table 4: Pharmacy & Channel Distribution Indicators for the At-Home Testing Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 8.3 billion | 2026 global valuation baseline |
| Retail pharmacies & drugstores globally | 1,400,000 outlets | Global community pharmacy outlet registry |
| Average value per pharmacy | USD 5,928.6 | Annualized OTC diagnostic strip and kit procurement |
| Retail Pharmacy Chains allocation | USD 4.6 billion | 54.9% distribution-channel segment share |
Over-the-counter multiplex test expansion requires balancing analytical sensitivity at low viral or hormone concentrations with affordable multi-pack retail pricing. Assay developers combine gold-nanoparticle signal amplification in rapid antigen diagnostic kits with smartphone camera apps to eliminate subjective visual interpretation errors.
Analyst Perspective
"Consumer diagnostic brands no longer rely on single-pathogen pandemic surges to retain pharmacy shelf space. Manufacturers that pair 3-in-1 respiratory lateral flow strips and smartphone colorimetric dipsticks with payer-reimbursed colorectal and HPV mail-in kits capture recurring household replenishment."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the at-home testing market segmented?
The at-home testing market is segmented by assay technology, distribution channel, patient demographic, sample type, and clinical indication. In 2026, Lateral Flow Strips are projected at 53.7%, Retail Pharmacy Chains at 54.9%, Adults 18-64 Years at 56.4%, Capillary Whole Blood at 44.7%, and Metabolic Glucose Panels at 37.9%.
By assay technology: Lateral Flow Strips, Electrochemical Biosensors, Mail-In PCR Kits, and Optical Smartphone Dipsticks.
By distribution channel: Retail Pharmacy Chains, Telehealth E-Commerce Portals, and Payer Mail-Order Screening.
By patient demographic: Adults 18-64 Years, Seniors 65+ Years, and Pediatric Patients.
By sample type: Capillary Whole Blood, Urine Midstream Samples, Nasal Swab Saliva, and Stool Samples.
By clinical indication: Metabolic Glucose Panels, Fertility Hormone Testing, Respiratory Viral Multiplex, STI Self-Collection Kits, and Colorectal Cancer Screening.
Why do Lateral Flow Strips lead assay technology demand?
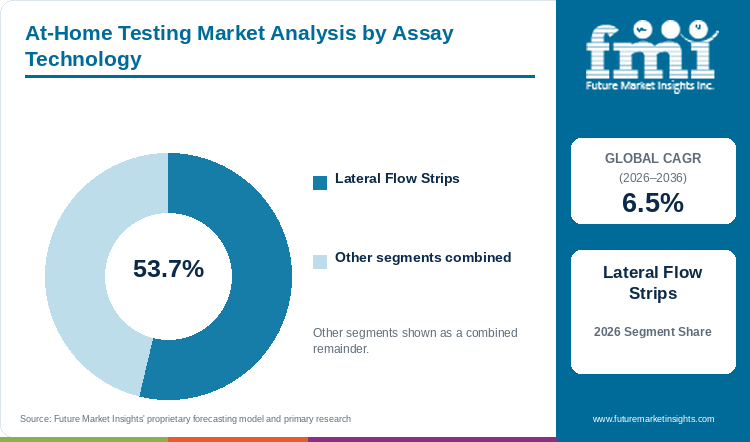
Within Assay Technology segmentation, Lateral Flow Strips hold an estimated 53.7% share in 2026, supported by instrument-free 15-minute visual readouts.
Table 5: Assay Technology Share for the At-Home Testing Market (percentage share), 2026
| Assay Technology | Share (2026) |
|---|---|
| Lateral Flow Strips | 53.7% |
| Other Segments Combined | 46.3%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Assay Technology Leadership and Market Growth for the At-Home Testing Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Leading Segment | Lateral Flow Strips |
Over-the-counter diagnostic buyers favor immunochromatographic Lateral Flow Strips and cassettes because nitrocellulose membranes wick capillary blood or nasal buffer across immobilized capture antibodies in 10 to 15 minutes without external power. Ambient shelf stability of 18 to 24 months at up to 30 degrees Celsius allows pharmacies to stock self-testing diagnostic cassettes without refrigerated display cases.
- Lateral Flow Strips are estimated at 53.7% of 2026 Assay Technology volume, driven by low per-test manufacturing cost and equipment-free household visual readout.
- Specifically, in February 2026, researchers at Oregon Health & Science University published a study in Biosensors demonstrating a paper-based nanobody lateral flow assay with gold nanoparticles that detects nucleocapsid protein down to 40 ng/mL visually without mammalian cell culture reagents.
What keeps Retail Pharmacy Chains ahead among distribution channels?
Across distribution channels, Retail Pharmacy Chains are projected at 54.9% in 2026, enabled by walk-in acute and prescription-adjacent purchases.
Community pharmacies and national drugstore chains remain the primary purchasing point when consumers experience acute febrile symptoms or replenish glucose test strips during prescription pickups. Pharmacist consultation and immediate walk-in availability complement network point-of-care glucose testing systems and health-plan flexible spending card reimbursement.
- Across distribution channels, Retail Pharmacy Chains are projected at 54.9% in 2026, owing to immediate neighborhood counter availability for acute and chronic self-tests.
- Analytical validation published in Talanta in December 2025 validated a self-enhancing triplex lateral flow immunoassay with time-delayed gold growth pads achieving detection limits of 1.0 ng/mL for influenza A and B and 0.2 ng/mL for SARS-CoV-2.
How do Adults 18-64 Years generate the largest patient demographic share?
Adults 18-64 Years are forecast at 56.4% of Patient Demographic volume in 2026 due to recurring reproductive and metabolic self-checks.
Working-age adults between 18 and 64 years represent the core buyer cohort for ovulation and hCG hormone monitoring as well as confidential sexually transmitted infection mail-in panels and cholesterol checks. Digital fluency with smartphone-linked at-home pregnancy testing kits and telehealth prescription portals accelerates repeat subscription orders across this demographic.
- Adults 18-64 Years are forecast at 56.4% of Patient Demographic volume in 2026 owing to high reproductive health and workplace wellness self-testing frequency.
- To support this digital self-testing workflow, in August 2026, a clinical diagnostic trial of 99 subjects published in Diagnostic Microbiology and Infectious Disease demonstrated that artificial intelligence interpretation of at-home lateral flow antigen tests achieved 96.97% accuracy and 100% specificity against RT-PCR.
Why does Capillary Whole Blood remain the leading sample type segment?
By sample type, Capillary Whole Blood is expected to reach 44.7% in 2026, resulting from daily fingerstick glucose and lipid strip consumption.
Capillary fingerstick whole blood represents the highest recurring dollar volume in household diagnostics because hundreds of millions of diabetic and cardiometabolic patients consume disposable electrochemical glucose and lipid test strips daily. Micro-sampling dried blood spot cards and TASSO capillary lancet devices also enable mail-in HbA1c and thyroid panel quantification.
- By sample type, Capillary Whole Blood is expected to reach 44.7% in 2026, associated with daily electrochemical strip replenishment and dried blood spot panels.
- Specifically, in November 2025, bioengineers at CIBER-BBN Spain published a study in Advanced Materials integrating electrolyte-gated organic field-effect transistors with paper fluidics to achieve a 0.1 femtomolar limit of detection for human immunoglobulin G in 20 to 30 minutes.
What makes Metabolic Glucose Panels the preferred clinical indication?
Among clinical indications, Metabolic Glucose Panels are anticipated at 37.9% in 2026, reinforced by multi-daily diabetes strip replenishment.
Unlike episodic infectious or pregnancy tests used only a few times per year, managing type 1 and type 2 diabetes and metabolic syndrome requires multiple daily blood glucose checks plus quarterly HbA1c and lipid tracking. High consumable strip volume per patient locks in predictable annuity demand for electrochemical strip and meter manufacturers.
- Among clinical indications, Metabolic Glucose Panels are anticipated at 37.9% in 2026, supported by continuous daily strip consumption across diabetic households.
- For example, a December 2025 study published in Mikrochimica Acta demonstrated that smartphone video deep learning algorithms accurately quantify lateral flow diagnostic strip kinetics in real time without dedicated optical hardware attachments.
What are the drivers, restraints, and opportunities in the at-home testing market?
In the at-home testing market, payer-mailed cancer screening kits and OTC respiratory multiplex strips drive adoption, whereas specimen postal delays and visual reading errors restrain switching and smartphone-linked telehealth prescriptions create new growth.
- Driver: Payer-sponsored colorectal and cervical cancer mail-in screening programs and OTC multiplex respiratory strips expand recurring household test volumes.
- Restraint: User sample collection errors and delayed postal transit above 15 days plus lower capillary glucometer sensitivity versus venous lab standards trigger test cancellations.
- Opportunity: Smartphone computer-vision strip readers paired with instant telehealth antiviral or metabolic prescriptions convert standalone kits into closed-loop care episodes.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Health maintenance organizations and national screening agencies are mailing non-invasive stool and vaginal self-collection kits directly to unscreened adults to close preventive cancer screening gaps. Because home collection avoids bowel preparation and workplace time off, first-round screening participation rises substantially among 45-to-75-year-old beneficiaries beside continuous glucose monitoring devices used for home glycemic titration. Translational oncology researchers in April 2025 published a clinical perspective in Gastroenterology detailing the development of the multitarget fecal immunochemical test (mtFIT) to improve sensitivity for advanced precancerous colorectal lesions over standard single-marker FIT. Through this screening sensitivity gain, payers expand annual bulk purchasing contracts for validated home collection kits.
Risk Assessment of the At-Home Testing Market: Pre-Analytical and Analytical Friction
Unsupervised household specimen collection and variable capillary blood hematocrit levels represent the principal quality barriers restraining clinical reliance on self-testing. When consumers omit collection dates on mailed stool tubes or expose urine samples to summer mailbox heat, clinical laboratories must reject the specimen and order confirmatory venous draws. Prenatal diagnostic evaluations in Johannesburg published in the International Journal of Gynecology & Obstetrics in January 2025 tested seven point-of-care glucometers across 1,076 pregnant women and found gestational diabetes sensitivity ranging from 17.6% to 87.18%. In addition to this analytical gap, clinical guideline committees require standardized genomic urine diagnostic assays with onboard sample-adequacy controls before approving reimbursement.
Commercial Opportunity Analysis: Quantitative Risk Stratification and Telehealth Bundling
Diagnostic manufacturers capture higher gross margins when they link quantitative home assay readouts directly to personalized screening intervals and telehealth pharmacy fulfillment. Through quantitative hemoglobin and hormone or viral-load readers, diagnostic platforms stratify longitudinal patient risk and trigger automated kit reshipments paired with colorectal cancer molecular diagnostics. To capture this risk-stratified demand, in June 2026, a longitudinal screening cohort study published in AJG demonstrated that quantitative first-round fecal immunochemical test hemoglobin concentrations strongly predict colorectal cancer and advanced neoplasia risk in second-round screening. As a result, combining smartphone optical quantification with automated telehealth follow-up allows manufacturers to win durable direct-to-consumer and payer contracts.
At-Home Testing Market by Country (2026 to 2036)
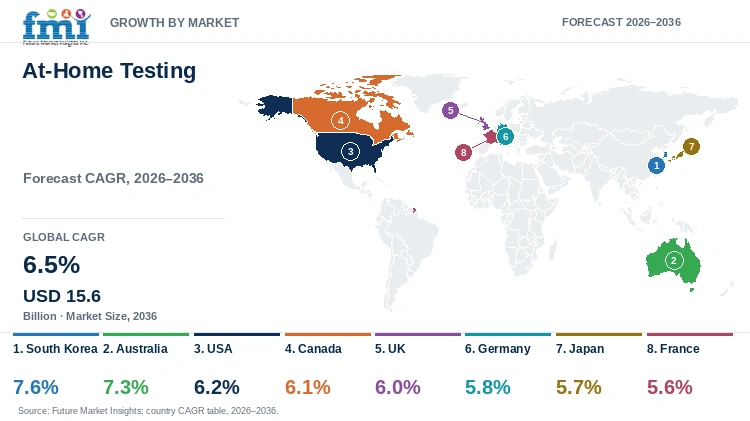
Adoption analysis indicates that pharmacy self-testing in South Korea leads evaluated country expansion at a 7.6% compound yearly rate to 2036, followed by Australia at 7.3% and the USA at 6.2%, while France records a 5.6% CAGR. Country demand patterns depend on over-the-counter multiplex regulatory clearances and national cancer self-sampling reimbursement.
Table 7: Country CAGR and Primary Growth Levers for the At-Home Testing Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 7.6% | MFDS clearances for multiplex respiratory cassettes and smartphone-read pharmacy self-tests |
| Australia | 7.3% | Universal national HPV self-collection eligibility and mailed bowel screening kits |
| USA | 6.2% | Medicare Advantage HEDIS mailed colorectal kits and FDA-cleared OTC triplex respiratory strips |
| Canada | 6.1% | Provincial organized colon and cervical self-sampling mailings and pharmacy minor-ailment testing |
| UK | 6.0% | NHS mailed bowel and first-void urine HPV catch-up screening and high-street wellness kits |
| Germany | 5.8% | High drugstore lateral flow demand and statutory GKV quantitative stool screening |
| Japan | 5.7% | Pharmacist-supervised combo influenza-COVID antigen cassettes and municipal urine dipsticks |
| France | 5.6% | Assurance Maladie pharmacy-dispensed colorectal FIT and Mon Test IST self-sampling kits |
Source: Future Market Insights analysis
South Korea At-Home Testing Market Outlook (2026 to 2036)
High-density urban pharmacy networks and consumer familiarity with rapid multiplex cassettes in South Korea are accelerating household adoption of respiratory and metabolic self-tests. Because neighborhood pharmacies in South Korea stock combo influenza A/B and SARS-CoV-2 strips beside smartphone-read urine and fecal occult blood dipsticks, consumers bypass hospital outpatient queues for initial symptom triage. In fact, a June 2026 systematic review and meta-analysis of 17 colorectal screening studies published in BMC Gastroenterology confirmed that fecal immunochemical testing achieved 77% pooled sensitivity and 95% specificity where endoscopy capacity is constrained. Domestic at-home testing valuation in South Korea is projected to compound at 7.6% annually between 2026 and 2036, although Ministry of Food and Drug Safety stability rules require local bridging trials.
Key takeaway: In South Korea, rapid MFDS clearances for multiplex respiratory cassettes and dense pharmacy retail distribution are projected to drive household self-test adoption.
Australia At-Home Testing Market Outlook (2026 to 2036)
Federal public health subsidies for universal cervical self-sampling and mailed bowel cancer kits in Australia are pushing non-invasive specimen collection into regional and remote households. When primary-care clinics and postal screening registries in Australia offer dry vaginal swabs and two-sample fecal immunochemical tubes, participation rises sharply among under-screened adults across outback postal codes. In February 2026, a national retrospective cohort study published in The Lancet Public Health documented that self-collected HPV sample uptake in Australia rose more than twenty-two-fold across primary-care clinics to reach 26.9% national participation while maintaining histological lesion detection. Sales of at-home testing kits in Australia are estimated to climb at a 7.3% annual rate to 2036, whereas summer postal heat requires ambient buffer stability.
Key takeaway: In Australia, universal national HPV self-collection eligibility and mailed bowel screening kits are estimated to sustain strong volume growth across postal channels.
USA At-Home Testing Market Outlook (2026 to 2036)
Medicare Advantage HEDIS star-rating incentives and FDA over-the-counter triplex respiratory clearances are reshaping household diagnostic procurement across the USA. Because health plans and retail pharmacy chains in the USA seek to close colorectal cancer and diabetes care gaps without scheduling clinic visits, payers ship millions of pre-paid stool DNA and fingerstick HbA1c kits directly to member homes. In April 2026, an implementation review of 40 studies published in Sexually Transmitted Infections confirmed that home-accessible chlamydia and gonorrhoea testing reduces clinic stigma and hours-of-operation barriers. USA household testing turnover is forecast to post a 6.2% compound rate from 2026 to 2036 owing to telehealth STI panels, while FDA laboratory-developed test rules require authorized collection tubes.
Key takeaway: In the USA, Medicare Advantage HEDIS gap-closure mailings and FDA-cleared over-the-counter multiplex assays are forecast to support retail pharmacy and payer fulfillment.
Canada At-Home Testing Market Outlook (2026 to 2036)
Provincial cancer agency mail-in fecal immunochemical screening and expanded pharmacist minor-ailment prescribing authority create a strong operational foundation for home testing across Canada. When provincial screening registries in Ontario and Alberta mail non-invasive stool and cervix self-sampling kits to rural households, diagnostic labs cut endoscopy waiting lists across public hospitals. Specifically, a population-based cohort study of 169,117 colonoscopy patients in the BC Colon Screening Program published in Clinical Gastroenterology and Hepatology in May 2026 analyzed 25,438 interval FIT kits (15.73% positive) over a 43.17-month median follow-up. At-home testing volume across Canada posts an expected 6.1% yearly gain through 2036, balanced against mandatory bilingual packaging and Health Canada Class III device licensing.
Key takeaway: In Canada, provincial organized colon and cervical self-sampling programs and expanded pharmacy minor-ailment authority are expected to reinforce household kit uptake.
UK At-Home Testing Market Outlook (2026 to 2036)
Expansion of NHS mailed bowel and sexual-health self-sampling and private high-street pharmacy fingerstick wellness panels in the UK is driving demand for home collection devices. When urban general practices and local authorities in the UK mail first-void urine and capillary blood collection tubes to non-attenders, screening uptake rises across hard-to-reach populations. According to the UK Catch-Up Screen randomized trial of 3,074 women aged 60 to 79 in Hull and Manchester GP practices published in BJOG in December 2025, 59% (1,816 women) returned an at-home first-void urine sample for HPV screening. Commercial at-home testing turnover across the UK is anticipated to increase by 6.0% per year over 2026 to 2036.
Key takeaway: In the UK, postal first-void urine and stool catch-up screening plus high-street pharmacy fingerstick panels are anticipated to expand multi-channel diagnostic volume.
Germany At-Home Testing Market Outlook (2026 to 2036)
High consumer footfall across retail drugstore chains and statutory sickness-fund preventive colorectal screening programs are turning Germany into Western Europe's largest volume market for rapid cassettes and stool tests. Because consumers in Germany routinely purchase over-the-counter respiratory antigen strips and vitamin or ferritin self-tests at neighborhood drugstores, manufacturers enjoy broad shelf distribution outside hospital clinics. In practice, investigators at the Cancer Research Center (DKFZ) in Germany analyzed 7,398 participants in the BLITZ study in EClinicalMedicine in March 2026 across quantitative FIT cutoffs from 8.5 to 120 ug Hb/g feces, documenting colorectal cancer sensitivity from 55.6% to 98.1%. Germany at-home testing volume is projected to record a 5.8% compound annual rate to 2036.
Key takeaway: In Germany, high drugstore lateral flow turnover and statutory colorectal screening programs are projected to accelerate adoption of IVDR-certified self-tests.
Japan At-Home Testing Market Outlook (2026 to 2036)
Ministry of Health, Labour and Welfare reclassifications of over-the-counter combo antigen cassettes and municipal preventive urine and stool screening programs shape consumer diagnostics in Japan. While strict pharmaceutical rules in Japan channel Class I and Class II self-tests through pharmacist-staffed drugstore counters, household demand for simultaneous influenza and SARS-CoV-2 self-testing remains high during winter waves. For instance, a September 2025 VACCELERATE multi-pathogen self-testing study of 1,429 adults published in Frontiers in Public Health demonstrated that single-swab 5-virus lateral flow devices enabled rapid household pathogen identification across 1,119 symptomatic episodes. Volume in Japan records an estimated 5.7% compound annual gain through 2036 due to pharmacy combo antigen kits and municipal checkup dipsticks.
Key takeaway: In Japan, pharmacist-dispensed combo influenza-and-COVID lateral flow kits and municipal preventive screening are estimated to sustain retail diagnostic demand.
France At-Home Testing Market Outlook (2026 to 2036)
Assurance Maladie reimbursement for pharmacy-dispensed colorectal fecal immunochemical kits and youth sexually transmitted infection self-sampling packages in France drives steady volume through licensed community pharmacies. To keep quality control under pharmacist supervision, public health rules in France restrict retail medical self-tests (autotests) to bricks-and-mortar pharmacies while expanding online postal ordering for state cancer and Mon Test IST screening. Population screening research in October 2025 published in AJG confirmed that organized fecal immunochemical test screening programs significantly improve early-stage colorectal cancer diagnosis and short-term survival. National at-home testing turnover in France is forecast to post a 5.6% yearly expansion rate between 2026 and 2036, constrained by the statutory ban on supermarket self-test sales.
Key takeaway: In France, Assurance Maladie pharmacy-dispensed colorectal FIT kits and youth STI self-sampling programs are forecast to support regulated household testing growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the at-home testing market?
Abbott Laboratories, F. Hoffmann-La Roche Ltd, QuidelOrtho Corporation, Exact Sciences Corporation, OraSure Technologies, Inc., Becton, Dickinson and Company, Everlywell, Inc., and LetsGetChecked are the notable companies in the at-home testing market.
Supplier competition divides between point-of-care immunoassay and blood-glucose manufacturers that operate high-speed lateral flow lines and molecular self-collection companies that manage CLIA reference labs. Because health plans and pharmacies want multiplex respiratory cassettes and high-adherence cancer screening kits, leading manufacturers are expanding dry-swab and stool DNA self-collection portfolios.
- Global Point-of-Care and Rapid Assay Manufacturers: Abbott Laboratories and F. Hoffmann-La Roche Ltd plus QuidelOrtho Corporation manufacture documented over-the-counter lateral flow strips and capillary blood glucose meters.
- Molecular Self-Collection and Screening Specialists: Exact Sciences Corporation and OraSure Technologies, Inc. plus Becton, Dickinson and Company supply FDA-authorized stool DNA and vaginal HPV home-collection systems.
- Direct-to-Consumer Telehealth Testing Platforms: Everlywell, Inc. and LetsGetChecked provide digital health portals and CLIA-certified reference lab fulfillment for mailed capillary blood and urine panels.
Competitive Benchmarking: At-Home Testing Market
Table 8: Competitive Benchmarking for the At-Home Testing Market (qualitative capability ratings), 2026
| Company | Assay & Strip Breadth | OTC Regulatory Depth | Pharmacy Shelf Access | Geographic Reach |
|---|---|---|---|---|
| Abbott Laboratories | High | High | High | USA, Europe, and global pharmacy network |
| F. Hoffmann-La Roche Ltd | High | High | High | Europe, North America, Asia-Pacific, and Latin America |
| QuidelOrtho Corporation | High | High | High | USA, Canada, and international drugstore channels |
| Exact Sciences Corporation | Medium | High | Medium | USA and Europe colorectal screening channels |
| OraSure Technologies, Inc. | Medium | High | High | USA, Europe, and global public-health distribution |
| Becton, Dickinson and Company | High | High | High | Global pharmacy and screening lab networks |
| Everlywell, Inc. | Medium | Medium | Medium | USA retail pharmacy and telehealth portals |
| LetsGetChecked | Medium | Medium | Medium | USA, UK, and Ireland home-collection fulfillment |
Scoring basis: Assay & Strip Breadth evaluates documented lateral flow cassettes and electrochemical glucose strips plus mail-in molecular collection kits. OTC Regulatory Depth and Pharmacy Shelf Access reflect FDA 510(k) or EU IVDR lay-user certifications and national drugstore or Medicare Advantage HEDIS fulfillment reach.
Key Developments in the At-Home Testing Market
- Abbott Laboratories announced in October 2026 that the noninvasive Cologuard Plus multitarget stool DNA colorectal cancer screening test received CE-mark certification for European expansion following its March 2026 acquisition of Exact Sciences.
- Abbott Laboratories reported real-world outcomes in October 2026 covering 2.5 million adults showing that completing at-home Cologuard screening was associated with 54% lower colorectal cancer incidence and 45% lower mortality odds.
- OraSure Technologies, Inc. reported USD 30.6 million in second-quarter revenue and USD 161 million in cash in August 2026 following FDA clearance of its Colli-Pee Dx at-home urine collection kit for STI testing.
Key Players in the At-Home Testing Market
Global Point-of-Care and Rapid Assay Manufacturers
- Abbott Laboratories
- F. Hoffmann-La Roche Ltd
- QuidelOrtho Corporation
Molecular Self-Collection and Screening Specialists
- Exact Sciences Corporation
- OraSure Technologies, Inc.
- Becton, Dickinson and Company
Direct-to-Consumer Telehealth Testing Platforms
- Everlywell, Inc.
- LetsGetChecked
At-Home Testing Market - Report Scope
Table 9: Report Scope for the At-Home Testing Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Assay Technology; Distribution Channel; Patient Demographic; Sample Type; Clinical Indication |
| Quantitative Units | USD Billion |
| Market Definition | Commercial supplier revenue from consumer self-administered lateral flow cassettes, electrochemical blood glucose and lipid strips and meters, optical smartphone dipsticks, and CLIA or CE-marked mail-in self-collection kits. Excludes inpatient hospital point-of-care analyzers and continuous wearable glucose patches. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Australia, USA, Canada, UK, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, QuidelOrtho Corporation, Exact Sciences Corporation, OraSure Technologies, Inc., Becton, Dickinson and Company, Everlywell, Inc., LetsGetChecked |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
At-Home Testing Market - Research Methodology
Table 10: Research Methodology for the At-Home Testing Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with retail pharmacy category directors, CLIA reference laboratory operations heads, health-plan HEDIS quality managers, and OTC assay regulatory specialists. |
| Secondary Research | Analysis of FDA OTC 510(k) and De Novo clearances, EU IVDR self-test certifications, PubMed and PMC screening cohort studies, and corporate annual reports. |
| Market Sizing and Forecasting | Top-down retail pharmacy and payer preventive-screening budgets reconciled against bottom-up household strip consumption and mailed kit return volumes from 2026 to 2036. |
| Country Forecasting Model | Econometric country models weight diabetes prevalence, organized colorectal and HPV self-sampling coverage, OTC pharmacy dispensing laws, and out-of-pocket household spending across eight national markets. |
| Operational Benchmark Traceability | Screening pool and pharmacy indicators in Tables 2, 3, and 4 trace to EClinicalMedicine self-testing meta-analyses, VA mailed FIT cohorts, and Lancet Public Health HPV registries. |
| Data Triangulation and Validation | Revenue estimates are cross-checked against manufacturer test-cassette shipment disclosures while excluding central hospital lab reagents and inpatient bedside analyzers. |
At-Home Testing Market by Segments
At-Home Testing Market segmented by Assay Technology:
- Lateral Flow Strips
- Electrochemical Biosensors
- Mail-In PCR Kits
- Optical Smartphone Dipsticks
At-Home Testing Market segmented by Distribution Channel:
- Retail Pharmacy Chains
- Telehealth E-Commerce Portals
- Payer Mail-Order Screening
At-Home Testing Market segmented by Patient Demographic:
- Adults 18-64 Years
- Seniors 65+ Years
- Pediatric Patients
At-Home Testing Market segmented by Sample Type:
- Capillary Whole Blood
- Urine Midstream Samples
- Nasal Swab Saliva
- Stool Samples
At-Home Testing Market segmented by Clinical Indication:
- Metabolic Glucose Panels
- Fertility Hormone Testing
- Respiratory Viral Multiplex
- STI Self-Collection Kits
- Colorectal Cancer Screening
At-Home Testing Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Brümmer, L. E., Faehling, V., McGrath, S., Zorger, A.-M., Worbes, K., Erdmann, C., Tolle, H., Katzenschlager, S., Yerlikaya, S., Grilli, M., et al. (2026, April 7). Population health and implementation outcomes of self-testing for SARS-CoV-2 using antigen detecting diagnostics: a systematic review and meta-analysis. EClinicalMedicine, 94, 103838 (PubMed PMID 42005922).
- [2] Gawron, A. J., Gupta, S., & Veterans Health Administration Mailed FIT Study Group. (2026, October 16). Implementation of Programmatic Mailed Fecal Immunochemical Testing for Colorectal Cancer Screening in the Veterans Health Administration. The American Journal of Gastroenterology, 121(10), 2105-2114 (PubMed PMID 42895834).
- [3] Bates, T. A., Gurmessa, S. K., Reyes-Weinstein, J. B., Barklis, E., & Tafesse, F. G. (2026, February 22). A Nanobody-Based Lateral Flow Assay for Point-of-Care Diagnostics. Biosensors (Basel), 16(2), 132 (PubMed PMID 41744750).
- [4] Tian, Y., Zhang, H., & Northeastern University Biosensor Group. (2025, December 8). Self-enhancing triplex lateral flow assay for simultaneous detection of influenza A, influenza B, and SARS-CoV-2. Talanta, 300, 129228 (PubMed PMID 41385880).
- [5] Smith, J. R., & Clinical Trial Antigen AI Study Group. (2026, August 15). Smart diagnostics: Leveraging artificial intelligence for accurate at-home COVID-19 testing. Diagnostic Microbiology and Infectious Disease, 115(4), 117414 (PubMed PMID 42000671).
- [6] Mas-Torrent, M., & CIBER-BBN Organic Transistor Diagnostic Group. (2025, November 16). Electrically Readable Lateral Flow Assay Using Organic Transistors for Diagnostic Applications. Advanced Materials, 37(46), e13468 (PubMed PMID 41243399).
- [7] Zhang, Q., & XJTLU Smartphone Diagnostics Laboratory. (2025, December 22). Smartphone-based video deep learning enables rapid and accurate lateral flow diagnostics. Mikrochimica Acta, 193(1), 41 (PubMed PMID 41423536).
- [8] Meijer, G. A., de Wit, M., & Multitarget FIT Consortium. (2025, April 15). Developing a New Stool Test for Colorectal Cancer Screening, the Multitarget Fecal Immunochemical Test (mtFIT). Gastroenterology, 168(4), 712-724 (PubMed PMID 40232574).
- [9] George, J. A., & Johannesburg Prenatal Point-of-Care Glucose Study Group. (2025, January 10). Performance of point-of-care glucose testing for the diagnosis of gestational diabetes mellitus in pregnant women. International Journal of Gynecology & Obstetrics, 168(2), 541-548 (PubMed PMID 39306742).
- [10] Lansdorp-Vogelaar, I., & Second-Round FIT Screening Study Group. (2026, June 1). First-Round Fecal Immunochemical Test Concentration Predicts Colorectal Cancer and Advanced Neoplasia in Second-Round Screening. The American Journal of Gastroenterology, 121(6), 1484-1491 (PubMed PMID 40853361).
- [11] Lee, J. H., & Systematic Colorectal Screening Meta-Analysis Group. (2026, June 29). The efficacy of colorectal cancer screening: a systematic review and meta-analysis of fecal immunochemical testing and colonoscopy. BMC Gastroenterology, 26(1), 298 (PubMed PMID 42472250).
- [12] Gertig, D., Smith, M. A., & Australian National Cervical Screening Program Study Group. (2026, February 15). Uptake and performance of self-collection offered through primary care to all eligible participants in a national cervical screening programme in Australia: a retrospective cohort study. The Lancet Public Health, 11(2), e101-e110 (PubMed PMID 41611360).
- [13] Tucker, J. D., & STI Point-of-Care Testing Review Group. (2026, April 2). Point-of-care testing for chlamydia and gonorrhoea: a narrative review of patient perspectives and implementation determinants. Sexually Transmitted Infections, 102(3), 185-193 (PubMed PMID 41927463).
- [14] Telford, J. J., & British Columbia Colon Screening Program Investigators. (2026, May 12). Interval Positive Fecal Immunochemical Test Is Associated With Postcolonoscopy Colorectal Cancer in a Screening Program. Clinical Gastroenterology and Hepatology, 24(5), S1542-3565 (PubMed PMID 42128038).
- [15] Kitchener, H. C., Sasieni, P., & Catch-Up Screen Study Group. (2025, December 15). The Use of First-Void Urine to Screen Women Aged 60-79 for HPV in the UK: The Catch-Up Screen Study. BJOG: An International Journal of Obstetrics & Gynaecology, 133(4), 814-822 (PubMed PMID 41397685).
- [16] Brenner, H., Niedermaier, T., & German BLITZ Screening Study Group. (2026, March 16). Variation in diagnostic performance of fecal immunochemical test (FIT) by cutoffs used in screening programs globally. EClinicalMedicine, 94, 103835 (PubMed PMID 41884490).
- [17] Cornely, O. A., Salmanton-García, J., & VACCELERATE Respiratory Self-Testing Consortium. (2025, September 3). Self-testing for 5 respiratory viruses in adult VACCELERATE volunteers in Germany-a pilot study on multi-pathogen rapid antigen testing to monitor community-acquired acute respiratory infections. Frontiers in Public Health, 13, 1638280 (PubMed PMID 40969624).
- [18] Zorzi, M., & Organized FIT Screening Survival Investigators. (2025, October 13). An Organized Fecal Immunochemical Test-Based Screening Program Affects Colorectal Cancer Early Diagnosis and Survival in the Short Term. The American Journal of Gastroenterology, 120(12), 2890-2898 (PubMed PMID 41081565).
- [19] Abbott Laboratories. (2026, October 20). Abbott's Cologuard Plus receives CE Mark for colorectal cancer screening in Europe. Abbott MediaRoom.
- [20] Abbott Laboratories. (2026, October 12). Abbott Reports New Real-World Evidence Linking Cologuard Screening to Lower Colorectal Cancer Incidence and Odds of Death. Abbott MediaRoom.
- [21] OraSure Technologies, Inc. (2026, August 5). OraSure Announces Second Quarter 2026 Financial Results. OraSure Investor Relations.
- [22] Becton, Dickinson and Company. (2025, October 22). BD Simplifies At-Home HPV Testing to Broaden Access to Cervical Cancer Screening Outside United States. BD Newsroom.
- [23] Abbott Laboratories. (2026, May 27). ACS guideline reaffirms Abbott leadership in noninvasive colorectal cancer screening. Abbott MediaRoom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the at-home testing market in 2026 and what valuation is projected by 2036?
- Which chronic care and preventive screening pressures drive households toward at-home testing?
- Why do Lateral Flow Strips hold the largest assay technology share?
- Why do Retail Pharmacy Chains lead distribution channels?
- How do national growth rates compare across South Korea, Australia, the USA, and Canada?
- Which diagnostic manufacturers document OTC lateral flow strips versus mail-in molecular kits?
- Why do postal transit delays and visual reading errors restrain clinical reliance?
- What ambient stability and lay-user accuracy checks should buyers run before listing a test kit?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Assay Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Assay Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Assay Technology, 2026 to 2036
- Lateral Flow Strips
- Electrochemical Biosensors
- Mail-In PCR Kits
- Optical Smartphone Dipsticks
- Y-o-Y Growth Trend Analysis By Assay Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Assay Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail Pharmacy Chains
- Telehealth E-Commerce Portals
- Payer Mail-Order Screening
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Patient Demographic, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Patient Demographic, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Patient Demographic, 2026 to 2036
- Adults 18-64 Years
- Seniors 65+ Years
- Pediatric Patients
- Y-o-Y Growth Trend Analysis By Patient Demographic, 2021 to 2025
- Absolute $ Opportunity Analysis By Patient Demographic, 2026 to 2036
- Global Market Analysis and Forecast, By Sample Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sample Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sample Type, 2026 to 2036
- Capillary Whole Blood
- Urine Midstream Samples
- Nasal Swab Saliva
- Stool Samples
- Y-o-Y Growth Trend Analysis By Sample Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sample Type, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Indication, 2026 to 2036
- Metabolic Glucose Panels
- Fertility Hormone Testing
- Respiratory Viral Multiplex
- STI Self-Collection Kits
- Colorectal Cancer Screening
- Y-o-Y Growth Trend Analysis By Clinical Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- By Country
- Market Attractiveness Analysis
- By Country
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Assay Technology
- By Distribution Channel
- By Patient Demographic
- By Sample Type
- By Clinical Indication
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Abbott Laboratories
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- F. Hoffmann-La Roche Ltd
- QuidelOrtho Corporation
- Exact Sciences Corporation
- OraSure Technologies, Inc.
- Becton, Dickinson and Company
- Everlywell, Inc.
- LetsGetChecked
- Abbott Laboratories
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Assay Technology, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Patient Demographic, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Sample Type, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Indication, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Assay Technology
- Figure 6: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Distribution Channel
- Figure 9: Global Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Patient Demographic
- Figure 12: Global Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sample Type
- Figure 15: Global Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Clinical Indication
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Assay Technology
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Patient Demographic
- Figure 38: North America Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sample Type
- Figure 41: North America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Clinical Indication
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Assay Technology
- Figure 48: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 51: Latin America Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Patient Demographic
- Figure 54: Latin America Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Sample Type
- Figure 57: Latin America Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Clinical Indication
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Assay Technology
- Figure 64: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 67: Western Europe Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Patient Demographic
- Figure 70: Western Europe Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Sample Type
- Figure 73: Western Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Clinical Indication
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Assay Technology
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Patient Demographic
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Sample Type
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Clinical Indication
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Assay Technology
- Figure 96: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 99: East Asia Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Patient Demographic
- Figure 102: East Asia Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Sample Type
- Figure 105: East Asia Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Clinical Indication
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Assay Technology
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Patient Demographic
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Sample Type
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Clinical Indication
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Assay Technology, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Assay Technology, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Assay Technology
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Patient Demographic, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Patient Demographic, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Patient Demographic
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Sample Type, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Sample Type, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Sample Type
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Clinical Indication, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Indication, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Clinical Indication
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the at-home testing market in 2026, and what is forecast for 2036?
Global at-home testing valuation climbs from a 2025 baseline of USD 7.8 billion to USD 8.3 billion in 2026. Total turnover is forecast to hit USD 15.6 billion by 2036 as households adopt self-administered metabolic and cancer screening kits.
What is the CAGR for the at-home testing market from 2026 to 2036?
The global sector is projected to compound at a 6.5% annual rate over the 2026-2036 decade, creating USD 7.3 billion in added yearly revenue for consumer diagnostic manufacturers.
Which assay technology segment leads the at-home testing market?
Lateral Flow Strips are estimated at 53.7% of 2026 Assay Technology volume, supported by 15-minute visual readouts without external laboratory analyzers.
Which distribution channel segment leads the at-home testing market?
Across distribution channels, Retail Pharmacy Chains are projected at 54.9% in 2026, enabled by walk-in neighborhood access and pharmacist consultation.
Which country has a notable growth outlook during the assessment period?
South Korea is forecast to head major diagnostic nations with a 7.6% CAGR to 2036, driven by pharmacy multiplex respiratory cassettes and smartphone-read self-tests.
Who are the key players in the market?
Notable market participants include Abbott Laboratories, F. Hoffmann-La Roche Ltd, QuidelOrtho Corporation, Exact Sciences Corporation, OraSure Technologies, Inc., Becton, Dickinson and Company, Everlywell, Inc., and LetsGetChecked across pharmacy and mail-order channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
