

- Market Size (2026)
- USD 45.2 Bn
- Forecast (2036)
- USD 84.1 Bn
- CAGR (2026 to 2036)
- 6.4%
How big is the Automotive Foams Market in 2026?
USD 45.2 billion in 2026, reaching USD 84.1 billion by 2036 at a 6.4% CAGR
The automotive foams market was valued at USD 42.5 billion in 2025. The market is set to reach USD 45.2 billion by 2026-end and grow at a CAGR of 6.4% between 2026-2036 to reach USD 84.1 billion by 2036. Polyurethane will dominate with a 67.0% share, while Seating will lead with a 58.0% share.
Automotive foam procurement is shaped by vehicle production volumes, seating comfort specifications, and NVH performance requirements. Demand reflects polyurethane, polypropylene, and polyethylene foam consumption for seating cushions, headliners, door panels, and instrument panels. Buyers include OEM interior component purchasing teams, tier-one seating suppliers, and aftermarket foam producers evaluating density, compression characteristics, and molding capability.
Growth reflects sustained vehicle production and increasing foam content per vehicle as comfort and acoustic insulation expectations expand. OICA reported global vehicle production in 2025 confirming the production base for automotive foam consumption across seating and interior applications.
Suppliers compete mainly on polyurethane chemistry, molded foam precision, and integration with OEM seating system suppliers. BASF and Dow hold position through global polyurethane foam system portfolios; Bridgestone and Adient win where seating foam integration and comfort engineering drive procurement.
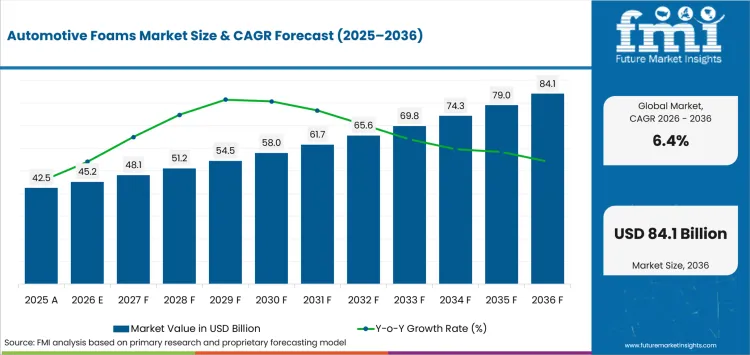
Key Takeaways of Automotive Foams Market
- Vehicle production volumes are expected to sustain automotive foam procurement for seating, headliner, and interior panel applications.
- Polyurethane is expected to account for 67.0% of foam type demand in 2026 because PU flexible foam dominates seating and interior applications.
- Seating is projected to hold 58.0% of application demand in 2026, driven by seat cushion and backrest foam consumption across every vehicle produced.
- Passenger Vehicles is anticipated to represent 67.8% of end-use demand in 2026, supported by production volumes and increasing comfort content per car.
- China leads with an 8.6% CAGR through 2036 as domestic vehicle production and foam content growth sustain procurement.
- BASF and Dow are expected to compete through global polyurethane foam system portfolios.
Analyst Perspective
"Buyers are expected to judge polyurethane on performance and total cost of ownership rather than headline price. Automotive foam adoption is expected to depend on vehicle production volumes and seating comfort specification evolution. Suppliers that combine polyurethane chemistry with molded foam precision and OEM integration are likely to secure platform-level foam supply contracts. Market success is projected to depend on meeting comfort, acoustic, and sustainability requirements across vehicle interior foam applications."
- Nikhil Kaitwade, Principal Consultant at Future Market Insights
Why is the Automotive Foams Market growing?
Rising Polyurethane and Seating demand across automotive end users
- Automotive-foam demand follows vehicle output and seating, NVH, and lightweighting content rather than speculative buying.
- China leads growth at 8.6% CAGR as domestic vehicle production and foam content growth sustain procurement.
- Seating holds 58.0% of application revenue, indicating where standardization is concentrating buyer spend.
Because foams carry comfort, acoustic, and weight functions, automotive-foam spend concentrates with suppliers offering polyurethane and polyolefin breadth and consistent processing quality.
How is the automotive foams market segmented?
The automotive foams industry is segmented by foam type, application, end use, density type, technology, and region.
The automotive foams market is segmented by foam type, application, end use, density type, technology, and region. By foam type, the market covers polyurethane, polypropylene, and polyethylene. By application, the market covers seating, headliner and roof, door panels, instrument panels, and bumpers. By end use, the market covers passenger vehicles, light commercial vehicles, and heavy commercial vehicles. By density type, the market covers medium density foams, low density foams, and high density foams. By technology, the market covers molded foam technology, slabstock foam technology, and spray foam technology. Regions include North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
How does polyurethane shape demand within the foam type category?
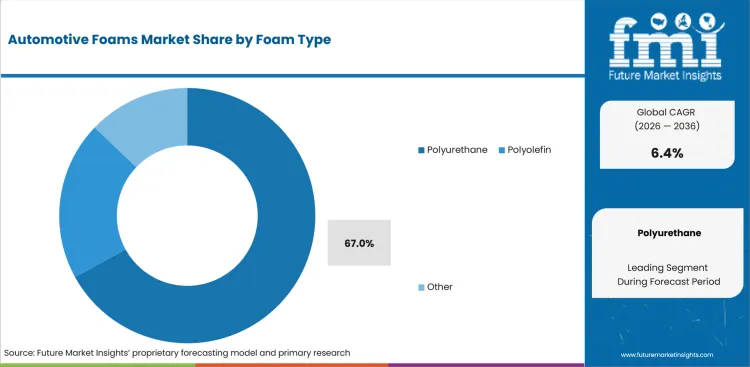
Foam type selection determines fitment scope, program economics, and channel mix across OEM and aftermarket purchasing. Polyurethane anchors the category, keeping buyer spend concentrated where qualification and service support are already established. Demand concentrates here because flexible PU foam dominates seating cushion, headliner, and interior panel applications.
- Polyurethane is expected to account for 67.0% of foam type demand in 2026 because flexible PU foam dominates seating cushion, headliner, and interior panel applications.
- Molded Foam Technology is projected to hold 51.6% of technology demand as molded PU foam provides precision seat cushion and component shapes.
What supports seating application demand?
Seating application shapes buyer requirements because segment choice here determines fitment scope, program economics, and channel mix across OEM and aftermarket purchasing. Demand concentrates here because every vehicle produced requires seat cushion and backrest foam components.
- Seating is projected to hold 58.0% of application demand in 2026 because every vehicle produced requires seat cushion and backrest foam components.
- Medium Density Foams is forecast to represent 44.8% of density demand as mid-range density balances comfort and durability.
How do end use and density type shape procurement?
End use and density type decide who controls the purchase and how the product reaches the account; together they determine fitment scope, program economics, and channel mix across OEM and aftermarket purchasing. Demand concentrates here because high production volumes generate the largest foam consumption.
- Passenger Vehicles is expected to hold 67.8% of end-use demand because high production volumes generate the largest foam consumption.
- Medium Density Foams is anticipated to account for 44.8% of density demand because medium density provides the balance of comfort, support, and durability required for automotive seating applications.
What are the drivers, restraints, and opportunities in the Automotive Foams Market?
Near-term procurement is shaped by vehicle production cycles, comfort specification evolution, and sustainable foam material development.
- Driver: Vehicle production growth and increasing comfort content per vehicle are expected to push automotive foam procurement for seating and interior applications.
- Restraint: MDI and polyol raw material price volatility is likely to slow adoption if foam pricing fluctuations exceed OEM interior component budget allocations.
- Opportunity: Bio-based polyol and recycled content foam development is expected to open supplier access if OEMs set interior component lifecycle sustainability targets.
Vehicle production is expected to increase foam procurement. BASF reported in its 2025 annual filing that its polyurethane division maintained growth across automotive seating and interior foam applications.
Raw material price volatility is expected to pressure margins. Huntsman reported in 2025 that MDI pricing remained subject to feedstock cost and global capacity utilization fluctuations.
Bio-based foam creates a practical route by offering sustainable polyol alternatives. Dow reported in 2025 that its bio-based polyurethane foam portfolio expanded across automotive OEM sustainability programs.
Which country CAGRs are profiled in the Automotive Foams Market?
China 8.6%, India 8%, South Korea 6.7%, USA 6.5%, UK 5.9% through 2036
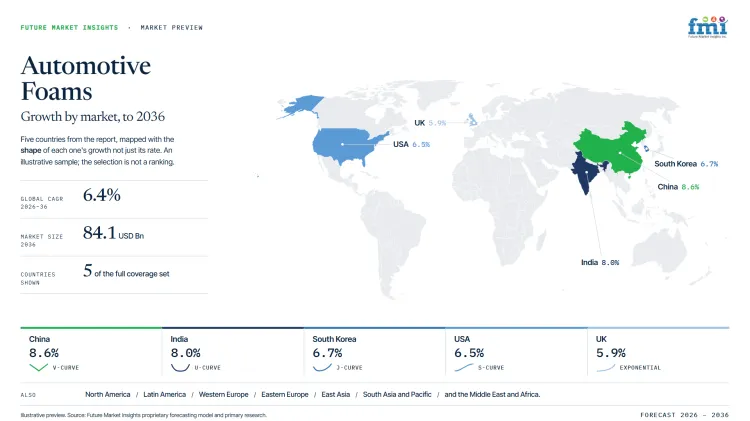
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 8.6% |
| India | 8.0% |
| South Korea | 6.7% |
| USA | 6.5% |
| UK | 5.9% |
Source: FMI's proprietary forecasting model and primary research. 5 of the countries covered in the full report are shown here as a representative subset.
How do country-level CAGRs compare in the Automotive Foams Market?
The country comparison spans 2.7 percentage points and reveals three distinct growth groups across the Automotive Foams Market. China and India form the upper tier with a 0.6-point difference, while South Korea and the United States create a closely aligned middle group separated by only 0.2 percentage points. The United Kingdom remains at the lower end with a 0.6-point gap from the United States.
- China leads the comparison at an 8.6% CAGR through 2036, supported by the scale of Chinese vehicle production and rapid EV adoption, which are strengthening demand for automotive foams across local supply chains.
- India follows at an 8.0% CAGR, remaining 0.6 percentage points below China. Rising passenger vehicle production, component localization and extensive aftermarket channels support both OEM and replacement demand.
- South Korea records a 6.7% CAGR, creating a 1.3-percentage-point gap from India. Established OEM supply chains, high electronics content and rapid platform cycles support continued demand for automotive foams.
- The United States grows at a 6.5% CAGR, only 0.2 percentage points below South Korea. A large vehicle parc, steady replacement demand and feature-led purchasing across OEM and aftermarket channels sustain market expansion.
- The United Kingdom records a 5.9% CAGR, remaining 0.6 percentage points below the United States. Its large vehicle parc, import-based supply structure and established aftermarket channels support replacement-oriented demand.
Comparable CAGRs can still produce different market conditions. Differences in vehicle production, EV adoption, lightweighting requirements, foam chemistry preferences, component localization and aftermarket activity influence automotive foam demand across countries. The full report provides country-level CAGR analysis across major regions and individual markets within the Automotive Foams Market.
Country-wise Analysis
- Automotive foams demand in China moves with the world's largest vehicle production base and an accelerating shift to electric platforms. Sales in China are forecast to expand at an 8.6% CAGR by 2036, supported by China's vehicle-build scale and local automotive foams supply chains. Polyurethane foams lead application demand in 2026, concentrating spend on seating and NVH systems. Local automotive foams suppliers and rapid platform cycles pressure pricing for newcomers. Winning here means local automotive foams manufacturing, sharp program pricing, and engineering presence at OEM centers.
- Indian demand for automotive foams spans rising vehicle output, localization requirements, and one of the deepest aftermarket networks globally. Demand draws on vehicle production growth and increasing comfort content per vehicle. The market outlook in India is anticipated to advance at an 8.0% CAGR over the assessment period, supported by rising vehicle output and deep automotive foams aftermarket channels. Price-sensitive buyers and scattered automotive foams aftermarket channels raise the distribution bar. Reaching Indian demand means local automotive foams sourcing and dealer-depth distribution.
- South Korean automotive foams sourcing sits inside conglomerate OEM supply chains and rapid platform turns concentrate Korean automotive foams demand. Demand in South Korea is forecast to rise at a 6.7% CAGR over the forecast period, supported by conglomerate OEM chains and rapid automotive foams platform cycles. Fast Korean platform turns raise the automotive foams co-development bar for smaller players. Holding Korean programs means fast automotive foams co-development and dependable delivery.
- US automotive foams demand rests on the size of the US parc and feature-driven purchasing anchor steady automotive foams replacement demand. Adoption in the United States is estimated to expand at a 6.5% CAGR through 2036, supported by a large installed automotive foams base and steady replacement demand. Regional aftermarket fragmentation lifts the cost of covering automotive foams demand nationally. US demand rewards automotive foams suppliers with OEM program ties and wide regional aftermarket reach.
- UK automotive foams demand is import-based supply and a replacement-weighted parc shape UK automotive foams demand. In the United Kingdom, demand is predicted to advance at a 5.9% CAGR through 2036, supported by a large automotive foams parc and replacement-led aftermarket demand. Import-based automotive foams supply is vulnerable to logistics shocks at peak demand. Serving UK demand means dependable automotive foams availability and strong distributor ties.
Who are the notable companies in the Automotive Foams Market?
BASF SE, Dow Inc., Huntsman Corporation, Bridgestone Corporation, Adient plc, Woodbridge Foam Corporation, Evonik Industries are the notable companies shaping this market.
The field concentrates around foam-materials suppliers that link chemistry engineering to OEM seating and NVH program access. Automotive seating foam specialists emphasize Automotive seating foams and Seating foam integration, while diversified foam and insulation companies serve regional demand through Flexible foam products. Global chemical and polyurethane foam companies compete across PU foam systems and materials, Polyurethane and polyolefin foams and MDI and polyurethane systems throughout established accounts. A workable entry is a seating-foam or NVH-material niche, or a regional supply position for a specific vehicle class. Growth then depends on material qualification, delivery performance, and parts availability across each launch territory. Breadth pays off through chemists who develop foam systems across platforms and support localized foam production.
- BASF SE and Dow Inc. combine PU foam systems and materials and Polyurethane and polyolefin foams across multiple national markets. Huntsman Corporation adds MDI and polyurethane systems through established account relationships. Their edge comes from polyurethane and polyolefin foam breadth across seating and NVH.
- Bridgestone Corporation, Adient plc and Woodbridge Foam Corporation follow focused routes across Automotive seating foams, Seating foam integration and Automotive foam components. Their commercial edge comes from bio-based and recycled-content foam niches rather than one standardized chemistry.
- Sekisui Chemical Co., Ltd. and Zotefoams plc provide regional coverage through Flexible foam products. These firms compete on focused foam strengths, though platform reach trails the global materials majors.
Competitive Benchmarking: Automotive Foams Market
| Company | Portfolio Relevance | Foam Focus | Account Access | Service Reach |
|---|---|---|---|---|
| BASF SE | High | PU foam systems and materials | Strong | Global |
| Dow Inc. | High | Polyurethane and polyolefin foams | Strong | Global |
| Huntsman Corporation | High | MDI and polyurethane systems | Strong | Global |
| Bridgestone Corporation | Medium | Automotive seating foams | Strong | Global |
| Adient plc | High | Seating foam integration | Strong | Global |
| Woodbridge Foam Corporation | Medium | Automotive foam components | Strong | Regional |
| Evonik Industries | Medium | Specialty foam additives | Strong | Global |
Source: Future Market Insights competitive analysis, 2026. Ratings reflect relative portfolio relevance, workflow or project fit, service capability, and geographic reach.
Key Developments in Automotive Foams Market
- Jan 2025, BASF and Covestro announced a strategic partnership to co-develop and commercialize sustainable automotive PU foams with recycled content.
- Mar 2025, BASF launched biomass-balance flexible PU foam systems, cutting product carbon footprint by up to 75% versus conventional systems.
- Apr 2026, Adient acquired a seating-foam plant in Romulus, MI from Woodbridge, expanding its global foam footprint to 30 plants.
- Aug 2026, Dow and Adient commercially launched SPECFLEX™ REN, a bio-circular polyurethane seating foam.
Key Players in the Automotive Foams Market
Global chemical and polyurethane foam companies
- BASF SE
- Dow Inc.
- Huntsman Corporation
- Evonik Industries
Automotive seating foam specialists
- Bridgestone Corporation
- Adient plc
- Woodbridge Foam Corporation
Diversified foam and insulation companies
- Sekisui Chemical Co., Ltd.
- Zotefoams plc
Automotive Foams Market: Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Foam type, application, end use, density type, technology, and region. |
| Market Definition | Automotive foams include polyurethane, polypropylene, and polyethylene flexible and rigid foams for seating, headliner, door panel, instrument panel, and bumper applications across passenger and commercial vehicles. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa. |
| Countries Covered | United States, China, India, South Korea, United Kingdom, and Japan. |
| Key Companies Profiled | BASF SE, Dow Inc., Huntsman Corporation, Bridgestone Corporation, Adient plc, Woodbridge Foam Corporation, Evonik Industries, |
| Forecast Period | 2026 to 2036. |
| Approach | FMI used primary interviews, source validation, and proprietary demand modeling. |
Source: Future Market Insights, analysis driven by proprietary forecasting models and primary research
Automotive Foams Market: Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, sourcing teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Source: Future Market Insights (FMI) analysis
Market Segmentation Analysis
Automotive Foams Market Segmented by Foam Type:
- Polyurethane
- Flexible Polyurethane Foams
- Enhanced Passenger Comfort
- Improved Noise Reduction
- Rigid Polyurethane Foams
- Lightweight Structural Support
- Enhanced Thermal Insulation
- Flexible Polyurethane Foams
- Polyolefin
- Expanded Polyolefin Foams
- Improved Impact Resistance
- Enhanced Vehicle Safety
- Cross Linked Polyolefin Foams
- Lightweight Automotive Integration
- Improved Durability Performance
- Expanded Polyolefin Foams
- Other
- PVC Automotive Foams
- Enhanced Interior Finishing Support
- Improved Moisture Resistance
- Melamine Based Foams
- Superior Acoustic Insulation
- Enhanced Heat Resistance
- PVC Automotive Foams
Automotive Foams Market Segmented by Application:
- Seating
- Seat Cushion Foams
- Enhanced Driving Comfort
- Improved Ergonomic Support
- Headrest And Armrest Foams
- Improved Passenger Safety
- Enhanced Interior Aesthetics
- Seat Cushion Foams
- Door Panels & Water Shields
- Acoustic Door Panel Foams
- Reduced Cabin Noise Levels
- Enhanced Passenger Experience
- Water Shield Protection Foams
- Improved Moisture Resistance
- Enhanced Vehicle Durability
- Acoustic Door Panel Foams
- Instrument Panels
- Dashboard Insulation Foams
- Enhanced Thermal Protection
- Improved Cabin Comfort
- Soft Touch Instrument Panel Foams
- Improved Interior Appearance
- Enhanced Shock Absorption
- Dashboard Insulation Foams
- Bumper System
- Energy Absorbing Bumper Foams
- Improved Crash Protection
- Enhanced Vehicle Safety
- Lightweight Impact Foams
- Reduced Vehicle Weight
- Improved Fuel Efficiency
- Energy Absorbing Bumper Foams
- Other Applications
- Roof Liner Foams
- Enhanced Acoustic Insulation
- Improved Cabin Temperature Control
- Trunk And Floor Insulation Foams
- Reduced Vehicle Vibrations
- Enhanced Ride Comfort
- Roof Liner Foams
Automotive Foams Market Segmented by End Use:
- Passenger Vehicles
- Compact And Sedan Vehicles
- Enhanced Cabin Comfort
- Improved Interior Design Quality
- Luxury Passenger Vehicles
- Premium Acoustic Insulation
- Enhanced Driving Experience
- Compact And Sedan Vehicles
- Light Commercial Vehicles (LCV)
- Delivery And Utility Vehicles
- Improved Driver Comfort
- Enhanced Vehicle Durability
- Electric Commercial Vans
- Lightweight Foam Integration
- Improved Energy Efficiency
- Delivery And Utility Vehicles
- Heavy Commercial Vehicles (HCV)
- Truck Cabin Insulation Systems
- Enhanced Driver Fatigue Reduction
- Improved Thermal Stability
- Bus Interior Foam Applications
- Enhanced Passenger Comfort
- Improved Noise Dampening
- Truck Cabin Insulation Systems
Automotive Foams Market Segmented by Density Type:
- Medium Density Foams
- Multi Purpose Automotive Foams
- Balanced Strength And Comfort
- Enhanced Durability Support
- Acoustic Insulation Foams
- Improved Noise Reduction Capability
- Enhanced Cabin Experience
- Multi Purpose Automotive Foams
- Low Density Foams
- Lightweight Comfort Foams
- Reduced Vehicle Weight
- Improved Fuel Efficiency
- Soft Interior Cushioning Foams
- Enhanced Passenger Comfort
- Improved Flexibility Performance
- Lightweight Comfort Foams
- High Density Foams
- Structural Reinforcement Foams
- Enhanced Impact Resistance
- Improved Vehicle Safety
- Heavy Duty Insulation Foams
- Superior Load Bearing Capacity
- Enhanced Long Term Performance
- Structural Reinforcement Foams
Automotive Foams Market Segmented by Technology:
- Molded Foam Technology
- Custom Molded Seat Foams
- Enhanced Ergonomic Design
- Improved Passenger Comfort
- Precision Molded Interior Foams
- Improved Dimensional Accuracy
- Enhanced Production Efficiency
- Custom Molded Seat Foams
- Spray Foam Technology
- Insulation Spray Foams
- Enhanced Thermal Protection
- Improved Noise Dampening
- Sealant Spray Foam Systems
- Improved Moisture Resistance
- Enhanced Structural Insulation
- Insulation Spray Foams
- Bio Based Foam Technology
- Plant Derived Automotive Foams
- Reduced Environmental Impact
- Enhanced Sustainability Support
- Recyclable Foam Materials
- Improved Circular Economy Integration
- Enhanced Eco Friendly Manufacturing
- Plant Derived Automotive Foams
Automotive Foams Market by Region:
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Rest of Latin America
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
- OICA. (2025). Global Motor Vehicle Production Statistics.
- BASF SE. (2025). Polyurethane Division Annual Report.
- Dow Inc. (2025). Bio-Based Polyurethane Foam Portfolio Update.
- Huntsman Corporation. (2025). MDI and Polyurethane Systems Performance Report.
- SIAM. (2025). Indian Automobile Production Statistics.
- KAMA. (2025). Korean Vehicle Production Data.
- JAMA. (2025). Japanese Vehicle Production Statistics.
- CAAM. (2025). Chinese Vehicle Production Report.
- Adient plc. (2025). Seating Systems and Foam Integration Report.
This bibliography uses primary government and company sources.
This Report Answers
- What is the estimated 2026 value of the automotive foams market?
- What market value is projected by 2036?
- What CAGR is forecast from 2026 to 2036?
- Which foam type is expected to account for a notable 2026 share?
- Which countries are profiled for CAGR comparison?
- Which companies are notable in the competitive landscape?
Frequently Asked Questions
How big is the Automotive Foams Market in 2026?
The Automotive Foams Market is valued at USD 45.2 billion in 2026 and is forecast to reach USD 84.1 billion by 2036, expanding at a 6.4% CAGR. The Automotive Foams Market grew from USD 42.5 billion in 2025, with Polyurethane holding 67.0% of foam type demand in 2026.
What is the CAGR of the Automotive Foams Market from 2026 to 2036?
The Automotive Foams Market is projected to grow at a CAGR of 6.4% between 2026 and 2036, supported by sustained vehicle production and increasing foam content per vehicle as comfort and acoustic insulation expectations expand. Polyurethane holds 67.0% of Automotive Foams Market foam type demand in 2026, while Seating leads application with 58.0% in 2026.
Which foam type leads the Automotive Foams Market?
Polyurethane accounts for 67.0% of the Automotive Foams Market by foam type in 2026, driven by sustained vehicle production and increasing foam content per vehicle as comfort and acoustic insulation expectations expand. The Automotive Foams Market is valued at USD 45.2 billion in 2026 and grows at a 6.4% CAGR through 2036, while Seating leads application with 58.0% in 2026.
How much will the Automotive Foams Market add between 2026 and 2036?
The Automotive Foams Market is set to add USD 38.9 billion between 2026 and 2036, growing from USD 45.2 billion to USD 84.1 billion at a 6.4% CAGR. Seating leads application with 58.0% of Automotive Foams Market revenue in 2026, anchoring that incremental demand.
Who are the leading companies in the Automotive Foams Market?
The Automotive Foams Market profiles 8 key companies in 2026, led by BASF SE, Dow Inc., Huntsman Corporation, Bridgestone Corporation, and Adient plc. These suppliers compete across foam type, where Polyurethane holds 67.0% of Automotive Foams Market demand in 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Foam Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Foam Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Foam Type, 2026 to 2036
- Polyurethane
- Flexible Polyurethane Foams
- Rigid Polyurethane Foams
- Polyolefin
- Expanded Polyolefin Foams
- Cross Linked Polyolefin Foams
- Other
- PVC Automotive Foams
- Melamine Based Foams
- Polyurethane
- Y-o-Y Growth Trend Analysis By Foam Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Foam Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Seating
- Seat Cushion Foams
- Headrest And Armrest Foams
- Door Panels & Water Shields
- Acoustic Door Panel Foams
- Water Shield Protection Foams
- Instrument Panels
- Dashboard Insulation Foams
- Soft Touch Instrument Panel Foams
- Bumper System
- Energy Absorbing Bumper Foams
- Lightweight Impact Foams
- Other Applications
- Roof Liner Foams
- Trunk And Floor Insulation Foams
- Seating
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Passenger Vehicles
- Compact And Sedan Vehicles
- Luxury Passenger Vehicles
- Light Commercial Vehicles (LCV)
- Delivery And Utility Vehicles
- Electric Commercial Vans
- Heavy Commercial Vehicles (HCV)
- Truck Cabin Insulation Systems
- Bus Interior Foam Applications
- Passenger Vehicles
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Density Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Density Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Density Type, 2026 to 2036
- Medium Density Foams
- Multi Purpose Automotive Foams
- Acoustic Insulation Foams
- Low Density Foams
- Lightweight Comfort Foams
- Soft Interior Cushioning Foams
- High Density Foams
- Structural Reinforcement Foams
- Heavy Duty Insulation Foams
- Medium Density Foams
- Y-o-Y Growth Trend Analysis By Density Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Density Type, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Molded Foam Technology
- Custom Molded Seat Foams
- Precision Molded Interior Foams
- Spray Foam Technology
- Insulation Spray Foams
- Sealant Spray Foam Systems
- Bio Based Foam Technology
- Plant Derived Automotive Foams
- Recyclable Foam Materials
- Molded Foam Technology
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Foam Type
- By Application
- By End Use
- By Density Type
- By Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BASF SE
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Dow Inc.
- Huntsman Corporation
- Bridgestone Corporation
- Armacell International
- FoamPartner
- Johnson Controls (Adient plc)
- Evonik Industries
- Woodbridge Foam Corporation
- Saint-Gobain Performance Plastics
- FXI Holdings Inc.
- Sekisui Chemical Co., Ltd.
- UFP Technologies, Inc.
- Zotefoams plc
- BASF SE
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


