

- Market Size (2026)
- USD 245.5 Mn
- Forecast (2036)
- USD 602.9 Mn
- CAGR (2026 to 2036)
- 9.4%
How big is Autonomous Power Multiplexers Market in 2026?
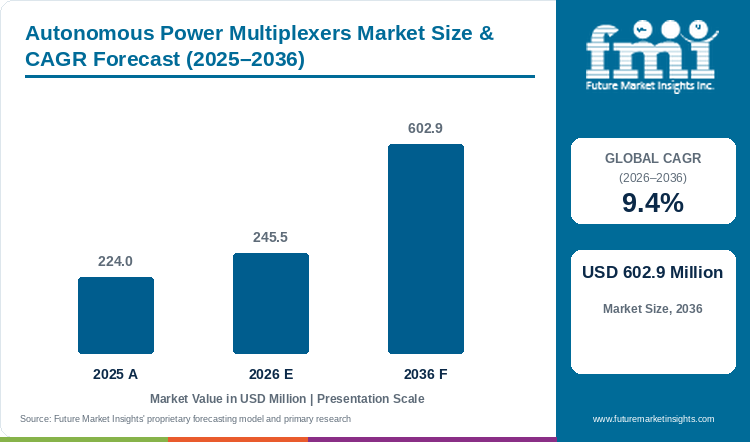
Autonomous power multiplexers demand progressed from USD 224.0 million across 2025 to USD 245.5 million across 2026, heading toward USD 602.9 million in 2036 under a 9.4% CAGR.
Uninterrupted backup rail switching across cloud solid-state storage arrays and multi-port notebooks is driving steady procurement of automatic power multiplexer chips. Second-quarter financial disclosures from Texas Instruments in July 2026 reporting a 26.0% year-on-year rise in analog billings reflect strong customer orders for integrated power-path chips fabricated on 300-millimeter wafers [1]. Every dual-rail storage bay and multi-port notebook needs instant protection against reverse current backfeed. Because enterprise solid-state drives and laptop charging ports require built-in clamping against voltage spikes during live plug-in events, Full Protection Clamping Mux devices secure 68.2% of protection demand in 2026 and outpace general power management integrated circuits. Assessed at USD 224.0 million for 2025 and USD 245.5 million across 2026, autonomous power multiplexers industry valuation is forecast by FMI at USD 602.9 million for 2036 with a 9.4% CAGR, delivering USD 357.4 million in net ten-year expansion. However, junction self-heating inside compact chip packages above 12 amperes of continuous current remains the main technical hurdle pushing heavier loads toward external transistor stages.
Key Market Trends & Insights
- By switchover control mode: Priority Fast OR-ing Mux accounts for 61.4% in 2026 because enterprise U.3/E3.S SSDs and USB-PD laptops require deterministic master-rail lock.
- By voltage rating: 2.7-28V Rails represent 58.6% across 2026 whereas 28-60V Rails post the steepest 11.1% annual growth across 48V server and automotive buses.
- By protection suite: Full Protection Clamping Mux holds 68.2% in 2026 by combining programmable dV/dt soft-start with overvoltage clamping and reverse-current blocking.
- By end-use application: Enterprise NVMe & Servers supply 49.5% of 2026 demand due to dual-rail 12V main and 3.3V/12V auxiliary hot-swap requirements per drive bay.
- By sales channel: Direct OEM & Cloud Supply secures 64.8% in 2026 via multi-year 300mm BCD wafer allocation agreements with server and automotive Tier-1 buyers.
Regional Highlights
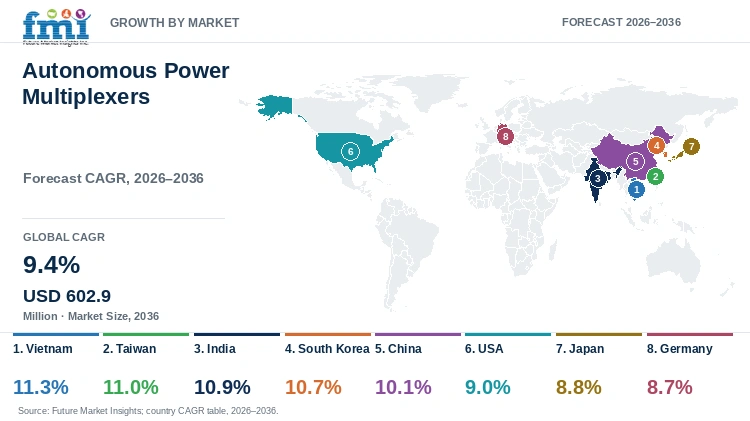
- Notebook & dock EMS expansion: Vietnam tops national multiplexer growth via an 11.3% CAGR through 2036 as Taiwan logs 11.0% and India posts 10.9% on notebook and AI server ODM assembly.
- Storage & automotive progression: South Korea charts a 10.7% CAGR compared with China at 10.1% plus the USA at 9.0% and Germany at 8.7%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Autonomous Power Multiplexers Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 224.0 million |
| Estimated Market Size in 2026 | USD 245.5 million |
| Projected Market Size by 2036 | USD 602.9 million |
| CAGR, 2026 to 2036 | 9.4% |
| Added Valuation, 2026 to 2036 | USD 357.4 million |
Compact dual-MOSFET board footprints and holdup-capacitor isolation during live hot-swap events have made autonomous power multiplexers essential across enterprise NVMe storage bays and fail-operational automotive ECUs. Unlike passive Schottky barrier diodes that drop 350 mV to 550 mV and waste 4W of heat at 8A loads, monolithic BCD multiplexers achieve 15 to 35 milliohm path resistance with sub-microsecond reverse-current blocking [2]. Consequently, global multiplexer billings advance from USD 245.5 million across 2026 toward USD 602.9 million by 2036 under a 9.4% CAGR.
Enterprise SSD & Multi-Port Device Socket Sizing
Table 2: Global Autonomous Power Multiplexer Unit Shipments and Blended ASP (million units and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Annual Power Multiplexer IC Shipments (Million Units) | 311.1 | 336.3 | 735.2 |
| Blended Average Selling Price (USD per IC) | USD 0.72 | USD 0.73 | USD 0.82 |
| AEC-Q100 28V to 60V Automotive Mux ASP (USD) | USD 1.35 | USD 1.42 | USD 1.65 |
| Enterprise NVMe & Multi-Port Type-C Attach Rate (%) | 58.0% | 64.5% | 84.0% |
Operational note: Unit shipments reflect 1 autonomous power multiplexer per enterprise NVMe SSD carrier, 1-to-2 dual-input selectors per multi-port USB-C notebook, and 1-to-2 redundant 12V feed switches per ASIL-D automotive controller.
Blended unit pricing moves from USD 0.72 during 2025 up to a 2036 average of USD 0.82 as 28-60V automotive-grade multiplexers scale across redundant vehicle power nets and battery management systems. Monolithic integration of two back-to-back power FETs and high-speed comparators with active thermal shutdown inside a 3x3 mm QFN package cuts printed circuit board area by 58% over discrete implementations.
Board Footprint Savings & Wafer Cost Structure
Table 3: PCB Area Compression and Conduction Efficiency Metrics per Multiplexer Socket (percentage and milliohms), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| PCB Footprint Reduction vs Discrete Dual-FET + Comparator (%) | 52.0% | 58.0% | 66.0% |
| Typical Integrated Path On-Resistance RDS(on) (Milliohms) | 38 mOhm | 31 mOhm | 19 mOhm |
| Break-Before-Make Rail Handover Latency (Microseconds) | 1.10 µs | 0.80 µs | 0.45 µs |
| Quiescent Standby Current in Backup Mode (Nanoamperes) | 420 nA | 350 nA | 180 nA |
Table 4: Manufacturing Cost Structure and 300mm BCD Wafer Economics for Autonomous Power Multiplexers (USD million and percentage share), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 245.5 million | 2026 global valuation baseline |
| BCD (Bipolar-CMOS-DMOS) Power Die | 36.0% of unit cost | Monolithic dual back-to-back DMOS switch die |
| Copper-Clip Thermal QFN / WCSP Packaging | 24.5% of unit cost | Low-inductance thermally improved package |
| Comparator IP, Kelvin Sort & Safety Qualification | 39.5% of unit cost | Sub-µs comparator, pulse sort & AEC-Q100/UL test |
Wafer fabrication of monolithic power multiplexers on 300mm Bipolar-CMOS-DMOS lines lowers die cost by 35% to 40% compared with 200mm fabs while incorporating copper-clip thermal packaging. Above 12A continuous current, however, package self-heating prompts board designers to transition toward external discrete power MOSFETs driven by standalone controllers.
Analyst Perspective
"Autonomous power multiplexers win sockets wherever board edge real estate is too tight for discrete FETs and holdup capacitors cannot afford a single microsecond of reverse backfeed into a shorted primary rail."
- Sudip Saha, Co-founder, FMI
How is the autonomous power multiplexers market segmented?
The autonomous power multiplexers market is segmented by switchover control mode, voltage rating, protection suite, end-use application, and sales channel. In 2026, Priority Fast OR-ing Mux holds 61.4% and 2.7-28V Rails capture 58.6%, while Full Protection Clamping Mux reaches 68.2% and Enterprise NVMe & Servers generate 49.5%.
By switchover control mode: Priority Fast OR-ing Mux, Smooth Ideal-Diode Auto-Mux, and Manual Logic-Selected Mux.
By voltage rating: 2.7-28V Rails, 28-60V Rails, 1.5-5.5V Rails, and Sub-1.5V Backup Rails.
By protection suite: Full Protection Clamping Mux, Basic Dual-FET Switch Matrix, Reverse-Block Only Mux, and Programmable Slew-Rate Mux.
By end-use application: Enterprise NVMe & Servers, USB-C Notebook & Docks, Automotive ADAS Dual-Battery, and Smart Meters & Medical.
By sales channel: Direct OEM & Cloud Supply, Franchised Broadline Distributors, Board Contract Assemblers, and Catalog e-Commerce Channels.
Why does Priority Fast OR-ing Mux lead the switchover control mode category?
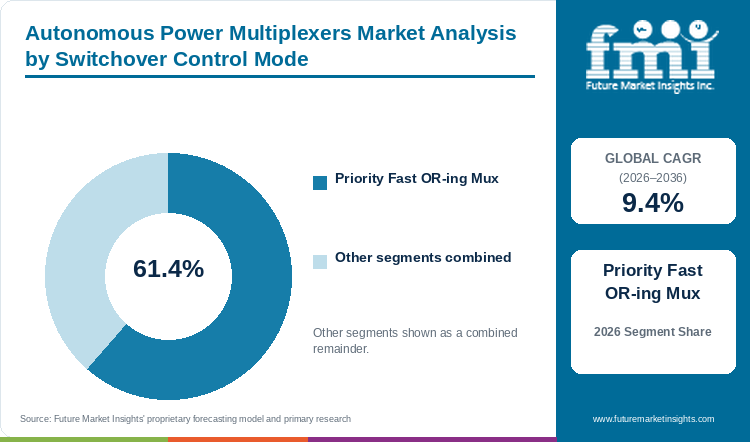
Priority Fast OR-ing Mux secures 61.4% of 2026 switchover control mode volume (equaling USD 150.7 million) and tracks a 9.8% CAGR to 2036.
Table 5: Switchover Control Mode Share for the Autonomous Power Multiplexers Market (percentage share), 2026
| Switchover Control Mode | Share (2026) |
|---|---|
| Priority Fast OR-ing Mux | 61.4% |
| Other Segments Combined | 38.6% |
| Total | 100.0% |
*Note: Smooth Ideal-Diode Auto-Mux and Manual Logic-Selected Mux account for the remaining 38.6% of 2026 market value.
Table 6: Switchover Control Mode Leadership and Market Growth for the Autonomous Power Multiplexers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.4% |
| Leading Segment | Priority Fast OR-ing Mux |
Enterprise U.3/E3.S solid-state drives and multi-port USB-C notebooks require precision resistor-programmable input voltage comparators that keep the designated master supply locked until it drops below undervoltage thresholds, preventing rail chatter when a backup battery presents a similar potential. Sub-microsecond fast reverse-current blocking gates work with automotive integrated power modules and server backplanes to isolate upstream bus shorts.
- Priority Fast OR-ing Mux accounts for 61.4% of 2026 switchover control mode demand (equaling USD 150.7 million) and tracks a 9.8% CAGR to 2036.
- February 2026 full-year earnings statements from Monolithic Power Systems documented a 46.0% annual jump in FY2025 Storage and Computing revenue to reach USD 732.5 million on enterprise SSD priority power multiplexer and PMIC shipments [3].
Why do 2.7V to 28V Rails define the largest voltage rating segment?
Across the voltage rating breakdown, 2.7-28V Rails hold 58.6% during 2026 (totaling USD 143.9 million) and notch a 9.2% CAGR to 2036.
High-density 90nm and 180nm BCD processes rated for 12V and 20V nominal operation (with 28V to 32V transient standoff) deliver 12 to 30 milliohm on-resistance across enterprise 12V storage bays and USB-PD 3.1 Extended Power Range notebook ports. Meanwhile, 28-60V Rails (holding 24.8% share) record the fastest 11.1% annual gain across 24V industrial PLCs and 48V auxiliary rails paired with isolated and non-isolated gate driver ICs.
- 2.7-28V Rails secure 58.6% across the 2026 voltage rating breakdown (totaling USD 143.9 million) and notch a 9.2% CAGR to 2036.
- Fiscal 2026 results from Alpha and Omega Semiconductor in August 2026 documented annual revenue of USD 678.9 million supported by AI server advanced computing and Tier-1 USB-C notebook power protection ramps [4].
What keeps Full Protection Clamping Mux ahead by protection suite?
Full Protection Clamping Mux provides 68.2% of 2026 protection suite demand (amounting to USD 167.4 million) while charting a 9.9% CAGR to 2036.
Hot-swapping an enterprise NVMe drive or docking cable into a live 12V or 20V bus generates severe capacitive inrush spikes that destroy unprotected switches. On-die integration of programmable dV/dt soft-start slew-rate control and active overvoltage output clamping saves USD 0.35 in discrete components while protecting downstream voltage regulators for advanced semiconductors and storage controllers.
- Full Protection Clamping Mux supplies 68.2% of 2026 protection suite volume (worth USD 167.4 million) while charting a 9.9% CAGR to 2036.
- Wide-SOA MOSFET protection stages unveiled by ROHM Co., Ltd. during November 2025 were engineered to survive severe capacitive inrush pulses during hot-swap and redundant rail switching [5].
Why do Enterprise NVMe & Servers lead the end-use application category?
Enterprise NVMe & Servers account for 49.5% of 2026 end-use application billings (valued at USD 121.5 million) and hold a 9.6% CAGR to 2036.
Dual-port U.3 and EDSFF E1.S/E3.S solid-state drives and PCIe Gen 5/6 SmartNICs must multiplex main 12V power with 3.3V or 12V auxiliary standby rails to maintain out-of-band telemetry and prevent holdup-capacitor backfeed into the server motherboard. Every 24-bay NVMe storage server embeds 24 to 32 autonomous multiplexers on its drive backplane and storage carrier cards.
- Enterprise NVMe & Servers provide 49.5% of 2026 end-use application billings (amounting to USD 121.5 million) and hold a 9.6% CAGR to 2036.
- Hardware engineering sessions scheduled in September 2026 by the Open Compute Project covered EDSFF NVMe storage bays and OCP NIC Gen 7 server cards across hyperscale AI deployments [6].
What gives Direct OEM & Cloud Supply the leading position in sales channel?
Direct OEM & Cloud Supply generates 64.8% of 2026 channel volume at USD 159.1 million while tracking a 9.7% CAGR through 2036 across 300mm wafer contracts.
Hyperscale storage ODMs and automotive Tier-1 suppliers procure nearly two-thirds of autonomous power multiplexers via direct wafer-allocation contracts with 300mm BCD analog chipmakers. Direct qualification locks in AEC-Q100 Grade-1 reliability and UL/IEC 62368-1 safety certifications across multi-year motherboard programs.
- Direct OEM & Cloud Supply accounts for 64.8% of 2026 sales channel revenue (totaling USD 159.1 million), while broadline distributors and board contract assemblers with e-commerce portals contribute 35.2%.
- February 2026 annual SEC Form 10-K reports filed by Diodes Incorporated showed USD 1,482.1 million in FY2025 sales with 44% automotive and industrial contribution across direct OEM and distributor accounts [7].
What are the drivers, restraints, and opportunities in the autonomous power multiplexers market?
Market growth is driven by EDSFF E3.S NVMe enterprise storage hot-swap requirements and ISO 26262 ASIL-D redundant automotive power mandates, tempered by QFN thermal dissipation limits above 12A continuous load.
- Driver: EDSFF E3.S NVMe enterprise SSD holdup-capacitor isolation and ISO 26262 ASIL-D dual-battery automotive redundancy mandate sub-microsecond autonomous rail switchover.
- Restraint: Junction self-heating above 12A continuous current inside compact QFN packages caps monolithic multiplexer power handling and shifts >15A sockets to external-FET controllers.
- Opportunity: Extended-voltage 28-60V BCD power multiplexers grow via an 11.1% CAGR across 48V AI server auxiliary buses and USB-PD 3.1 EPR ports.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Artificial intelligence training clusters require continuous checkpoint storage access where a single power-supply glitch cannot take dual-port NVMe drives offline. Passenger-car OEMs deploying Level 2+ ADAS computers and steer-by-wire actuators mandate dual-input AEC-Q100 power multiplexers to bridge primary and secondary 12V/48V battery rails under ISO 26262 ASIL-D fail-operational rules [8]. Inside EDSFF E3.S enterprise SSDs, an autonomous priority multiplexer isolates the bank of tantalum or polymer holdup capacitors from the 12V backplane within 0.8 microseconds of a bus droop while coordinating with automotive battery management systems across redundant vehicle domain controllers.
Risk Assessment of the Autonomous Power Multiplexers Market: Operational and Engineering Friction
Package thermal resistance and continuous current ceilings above 12A represent the primary technical boundaries restraining monolithic autonomous power multiplexers. Because an autonomous multiplexer integrates two back-to-back DMOS transistors (totaling 25 to 40 milliohms of series resistance) inside a 3x3 mm or 4x4 mm QFN footprint, continuous currents above 12A generate more than 4.5W of localized heat that exceeds 125°C junction limits without forced airflow [9]. Consequently, high-current 20A to 100A automotive zonal trunks and 48V server busbars bypass monolithic multiplexers in favor of external power discrete devices and modules driven by standalone ideal diode controllers.
Commercial Opportunity Analysis: Architecture Differentiation and Value-Add Formats
Analog IC manufacturers capture 2.0x to 2.5x higher average selling prices by extending monolithic BCD power multiplexers into the 28-60V standoff tier for 48V data center auxiliary rails and USB-PD 3.1 Extended Power Range laptops. During August 2026, onsemi posted USD 1,604.0 million in second-quarter sales (a 9% year-on-year gain) while scaling its 65nm Treo BCD mixed-signal platform across AI data center and automotive power sockets [10]. Integration of triple-supply priority supervision with precision telemetry pins allows Tier-1 analog vendors to displace discrete dual-FET circuits ahead of standalone DC-DC converters across smart utility meters and portable medical monitors.
Autonomous Power Multiplexers Market by Country (2026 to 2036)
Large-scale notebook and docking station EMS campuses put Vietnam first in national autonomous power multiplexer growth via an 11.3% CAGR until 2036, whereas Germany charts an 8.7% CAGR. Global shipments cluster around laptop and AI server motherboard assembly corridors in Asia and hyperscale or automotive engineering hubs in the USA and Europe.
Table 7: Country CAGR and Primary Growth Levers for the Autonomous Power Multiplexers Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Vietnam | 11.3% | USB-C Notebooks, Docking Stations & Server NIC EMS Assembly |
| Taiwan | 11.0% | AI Server Motherboards & EDSFF E3.S Storage Bay ODMs |
| India | 10.9% | PLI Server/IT Hardware EMS & Smart Utility Meter Rollouts |
| South Korea | 10.7% | Enterprise U.3/E3.S NVMe SSDs & Automotive ADAS ECUs |
| China | 10.1% | Multi-Port USB-PD Computing & State Grid Smart Utility Meters |
| USA | 9.0% | Hyperscale Storage Arrays & Autonomous EV Compute |
| Japan | 8.8% | Factory Automation 24V PLCs & Medical Instrumentation |
| Germany | 8.7% | ISO 26262 ASIL-D Automotive Dual-Battery Zonal ECUs |
Source: Future Market Insights analysis
Vietnam Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Multinational PC brands and Taiwanese contract manufacturers have concentrated multi-port USB Type-C notebook and Thunderbolt docking station assembly in Bac Ninh and Hai Phong, lifting Vietnam via an 11.3% CAGR across 2026 to 2036. May 2026 first-quarter earnings statements from Diodes Incorporated recorded over 20.0% year-on-year top-line expansion driven by USB Type-C power-path switches and client protection sockets across Asian assembly plants [11]. Unlike server-heavy countries, board assembly lines in Vietnam predominantly consume 20V and 28V Full Protection Clamping Mux ICs that prevent cross-port charger backfeeding on laptop motherboards. Duty-free component import corridors push unit volume upward, whereas reliance on imported BCD wafers and tight seaport logistics during peak third-quarter holiday builds moderate quarterly shipment pacing.
Key takeaway: In Vietnam, large-scale commercial notebook and USB-C docking station EMS campuses in Bac Ninh drive top-ranked unit growth.
Taiwan Autonomous Power Multiplexers Market Outlook (2026 to 2036)
What sets Taiwan apart from consumer assembly hubs is its control over hyperscale AI server motherboard and 24-bay EDSFF E3.S storage backplane original design manufacturing across New Taipei and Taoyuan. October 2026 third-quarter results from Nexperia showing a 9.3% sequential sales rise to USD 389.0 million reflected growing server and computing power-protection deliveries to Taiwanese board makers [12]. Multiplexer procurement across Taiwan climbs via an 11.0% CAGR from 2026 to 2036 on the back of dual-rail 12V and 48V auxiliary power multiplexing across cloud compute racks. Local power management IC suppliers partner directly with server motherboard architects and Hsinchu BCD foundries to customize sub-microsecond priority switches, although intense competition for 180nm wafer capacity constrains spot allocations.
Key takeaway: In Taiwan, hyperscale AI server motherboard and EDSFF storage bay ODMs anchor high-value priority multiplexer procurement.
India Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Domestic electronics manufacturing services plants in Tamil Nadu and Uttar Pradesh assembling multi-port USB-C laptops and enterprise storage cards procure 2.7-28V Full Protection Clamping Mux ICs to prevent adapter cross-conduction during hot-plug events. May 2025 Scientific Reports research by Rajendran and co-authors established that advanced manufacturing technologies and workforce development directly strengthen domestic electronics supply chains across Indian industrial corridors [13]. Supported by federal Production-Linked Incentive hardware programs and national smart utility meter rollouts, autonomous power multiplexer demand in India climbs via a 10.9% CAGR from 2026 to 2036. Smart electricity meter makers simultaneously integrate ultra-low-quiescent-current 1.5-5.5V backup multiplexers to switch between grid power and lithium cells during brownouts, though reliance on imported 300mm BCD dies remains a supply constraint.
Key takeaway: In India, PLI server and notebook EMS assembly paired with national smart utility meter tenders drive a 10.9% CAGR through 2036.
South Korea Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Enterprise NAND flash manufacturers headquartered in Gyeonggi-do produce more than half of world dual-port U.3 and EDSFF E3.S NVMe solid-state drives deployed inside hyperscale cloud data centers. March 2026 MethodsX research by Nguyen and Nguyen showed that Opal-RT power hardware-in-the-loop transient emulation prevents bus voltage collapse during sub-microsecond power-stage switchover across storage and automotive test benches [14]. Every enterprise solid-state drive embeds a compact 12V priority power multiplexer with active overvoltage clamping ahead of its holdup capacitor bank, propelling South Korea via a 10.7% CAGR from 2026 until 2036. Domestic automotive Tier-1 groups simultaneously qualify AEC-Q100 dual-battery multiplexers for steer-by-wire ECUs, though cyclical memory capital expenditure pauses occasionally moderate quarterly enterprise solid-state drive component orders.
Key takeaway: In South Korea, enterprise U.3 and E3.S NVMe SSD production in Gyeonggi-do creates concentrated demand for 12V clamping multiplexers.
China Autonomous Power Multiplexers Market Outlook (2026 to 2036)
High-volume USB Type-C notebook and docking station factories in Kunshan and Shenzhen pair with annual State Grid smart electricity meter tenders exceeding 70 million units to anchor baseline component consumption. September 2026 product releases by ROHM Co., Ltd. introducing wide-SOA protection switches for automotive safety functions point to rising adoption of redundant power-path protection across electric vehicle domain computers [15]. Multiplexer billings across China register a 10.1% CAGR to 2036 as domestic cloud server builders and electric vehicle OEMs integrate dual-input priority multiplexers across RAID storage controllers and autonomous driving ECUs. Strong unit demand supports domestic design-ins across East China, although intense local price competition in basic 5V dual-FET switches compresses merchant gross margins.
Key takeaway: In China, Kunshan notebook assembly lines and State Grid smart meter tenders sustain massive unit volumes.
USA Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Cloud infrastructure architects in California and Virginia mandate sub-microsecond reverse-current blocking multiplexers across enterprise EDSFF E3.S storage shelves and 48V rack management controllers to eliminate single points of failure during power supply swaps. March 2025 automotive technology updates from Infineon Technologies launching its 24/48V smart high-side switch family confirmed the shift of passenger-car and commercial fleet architectures toward redundant dual-voltage power nets [16]. Hyperscale data center storage architecture specifications and domestic electric vehicle dual-battery compute design-ins lift the USA via a 9.0% CAGR from 2026 to 2036. Domestic analog leaders Texas Instruments and Monolithic Power Systems anchor local supply across 300mm wafer fabs in Texas and Utah, although offshore PCB assembly shifts physical unit delivery to Asian contract hubs.
Key takeaway: In the USA, enterprise storage backplane specifications and domestic 300mm analog wafer fabs drive high-ASP multiplexer adoption.
Japan Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Consumption in Japan is uniquely weighted toward zero-downtime 24V factory automation programmable logic controllers and precision medical monitors manufactured in Tokyo and Kyoto rather than consumer laptops. June 2026 automotive releases from ROHM Co., Ltd. expanded its high-reliability power protection portfolio by launching the copper-clip AG16xFNxx series for 48V vehicle and industrial auxiliary power supply rails [17]. Autonomous power multiplexer demand across Japan rises via an 8.8% CAGR from 2026 to 2036 inside industrial robotics control cabinets and automated guided vehicles with optical transceiver backup rails. High domestic reliability standards support premium average selling prices, although conservative multi-year industrial qualification gates temper rapid semiconductor vendor switching across long-lifecycle factory automation accounts.
Key takeaway: In Japan, zero-downtime 24V factory automation PLCs and medical monitors sustain premium demand for smooth ideal-diode multiplexers.
Germany Autonomous Power Multiplexers Market Outlook (2026 to 2036)
Automotive Tier-1 suppliers and passenger car OEMs across Stuttgart and Munich mandate AEC-Q100 qualified dual-input power multiplexers to satisfy ISO 26262 ASIL-D redundant power requirements in steer-by-wire and electro-mechanical braking controllers. September 2025 mobility architecture briefings by STMicroelectronics showed how software-defined vehicle zonal gateways replace mechanical relays with solid-state redundant power-path switches across European vehicle platforms [18]. Autonomous power multiplexer shipments across Germany chart an 8.7% CAGR from 2026 until 2036 as industrial automation leaders in Nuremberg and Erlangen embed 28-60V OR-ing multiplexers inside DIN-rail 24V power supplies. Strong automotive and factory fieldbus demand sustains European analog billings, despite softer baseline mechanical engineering orders across domestic industrial machinery plants.
Key takeaway: In Germany, ISO 26262 ASIL-D fail-operational automotive power nets and 24V industrial PLCs anchor long-lifecycle multiplexer contracts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the autonomous power multiplexers market?
Texas Instruments Incorporated; Analog Devices, Inc.; Monolithic Power Systems, Inc.; STMicroelectronics N.V.; Diodes Incorporated; Alpha and Omega Semiconductor Limited; onsemi; and ROHM Co., Ltd. are the notable companies in the autonomous power multiplexers market.
Vertically integrated 300mm BCD analog chipmakers anchor the autonomous power multiplexers sector, with the top five vendors capturing 79.5% of 2026 global demand across enterprise storage and automotive power-path accounts. Competitive leadership rests on sub-30 milliohm dual-MOSFET on-resistance and sub-microsecond reverse-current blocking.
- Tier 1 300mm BCD & High-Density Analog Leaders (62.5% Tier Share): Texas Instruments at 26.5% plus Analog Devices at 19.0% and Monolithic Power Systems at 17.0% lead across enterprise SSDs and industrial automation.
- Tier 2 Client Computing & Automotive Discrete-Plus-IC Challengers (17.0% Combined Share): Diodes Incorporated (9.5%) and STMicroelectronics (7.5%) supply high-volume client computing and European automotive zonal gateways.
- Tier 3 Regional Power Switch Specialists (20.5% Combined Share): Alpha and Omega Semiconductor and onsemi with ROHM serve notebook USB-C docking and secondary server rail sockets.
Competitive Benchmarking: Autonomous Power Multiplexers Market
Table 8: Competitive Benchmarking for the Autonomous Power Multiplexers Market (qualitative capability ratings), 2026
| Company | 300mm BCD Low-RDS(on) IP | Sub-µs Priority & Clamping | NVMe, USB-PD & ASIL-D Reach | Geographic Reach |
|---|---|---|---|---|
| Texas Instruments Inc. | High | High | High | High |
| Analog Devices, Inc. | High | High | High | High |
| Monolithic Power Systems | High | High | High | High |
| STMicroelectronics N.V. | High | Medium | High | High |
| Diodes Incorporated | Medium | Medium | High | High |
| Alpha and Omega Semi | High | Medium | Medium | High |
| onsemi | High | High | High | High |
| ROHM Co., Ltd. | Medium | High | Medium | High |
Scoring basis: Vendor ratings and market shares are triangulated from 2025 annual and 2026 quarterly financial disclosures and Open Compute Project storage bill-of-materials teardowns.
Key Developments in the Autonomous Power Multiplexers Market
- Texas Instruments Incorporated reported third-quarter 2026 revenue growth of 28% year-on-year in October 2026 supported by USD 8,400.0 million in trailing twelve-month free cash flow and 300mm BCD analog power-path capacity [19].
- Analog Devices, Inc. filed its third-quarter fiscal 2026 Form 10-Q in August 2026 documenting a 39.6% year-on-year revenue increase to USD 4,021.9 million across industrial and automotive power management lines [20].
- In August 2026, Diodes Incorporated announced second-quarter 2026 operating cash flow of USD 68.5 million and third-quarter revenue guidance of USD 510.0 million across power protection switches [21].
Key Players in the Autonomous Power Multiplexers Market
Tier 1 300mm BCD Power Multiplexer Leaders
- Texas Instruments Incorporated
- Analog Devices, Inc.
- Monolithic Power Systems, Inc.
Tier 2 Client Computing & Automotive Power Path Suppliers
- STMicroelectronics N.V.
- Diodes Incorporated
- Alpha and Omega Semiconductor Limited
Tier 3 High-Efficiency Server & Industrial Switch Specialists
- onsemi
- ROHM Co., Ltd.
Autonomous Power Multiplexers Market - Report Scope
Table 9: Report Scope for the Autonomous Power Multiplexers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Switchover Control Mode; Voltage Rating; Protection Suite; End-Use Application; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes monolithic autonomous multi-input power multiplexers and priority power-path selector ICs integrating back-to-back power switches, voltage comparators, and reverse-current blocking (0.5A to 12A continuous load). Category Scope Note: Excludes single-channel eFuses, buck/boost regulators, and external-MOSFET active ideal diode controllers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Vietnam, Taiwan, India, South Korea, China, USA, Japan, Germany, and additional countries in the full report |
| Key Companies Covered | Texas Instruments Incorporated; Analog Devices, Inc.; Monolithic Power Systems, Inc.; STMicroelectronics N.V.; Diodes Incorporated; Alpha and Omega Semiconductor Limited; onsemi; ROHM Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down parent PMIC market cap checks and bottom-up SSD, notebook, and automotive ECU socket triangulation. |
Autonomous Power Multiplexers Market - Research Methodology
Table 10: Research Methodology for the Autonomous Power Multiplexers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with enterprise SSD power architects, notebook USB-PD board designers, automotive ASIL-D power-net engineers, and 300mm BCD product marketing directors to validate socket counts and ASPs. |
| Secondary Research | Analysis of SEC Form 10-K/10-Q filings (TI, Analog Devices, Monolithic Power Systems, Diodes, AOS, onsemi), OCP EDSFF storage specifications, and SAE 48V / ISO 26262 automotive power standards. |
| Market Sizing and Forecasting | Top-down parent Power Management Integrated Circuit Market (USD 35,300.0 million in 2026; autonomous power mux share = 0.70%) models reconciled against bottom-up NVMe SSD, USB-C laptop, and ADAS ECU builds from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight enterprise SSD fabrication, commercial notebook EMS assembly, smart meter tenders, and fail-operational automotive ECU production across eight national markets. |
| Operational Benchmark Traceability | Unit shipment, ASP, RDS(on), and BCD wafer cost indicators in Tables 2, 3, and 4 trace to TI and MPS segment disclosures, OCP storage hardware specs, and peer-reviewed power electronics literature. |
| Data Triangulation and Validation | Demand estimates are cross-checked against monolithic power-path IC billings without double counting single-input load switches or external-MOSFET ideal diode controllers. |
Autonomous Power Multiplexers Market by Segments
Autonomous Power Multiplexers Market segmented by Switchover Control Mode:
- Priority Fast OR-ing Mux
- Smooth Ideal-Diode Auto-Mux
- Manual Logic-Selected Mux
Autonomous Power Multiplexers Market segmented by Voltage Rating:
- 2.7V to 28V Rails
- 28V to 60V Rails
- 1.5V to 5.5V Rails
- Sub-1.5V Backup Rails
Autonomous Power Multiplexers Market segmented by Protection Suite:
- Full Protection Clamping Mux
- Basic Dual-FET Switch Matrix
- Reverse-Block Only Mux
- Programmable Slew-Rate Mux
Autonomous Power Multiplexers Market segmented by End-Use Application:
- Enterprise NVMe & Servers
- USB-C Notebook & Docks
- Automotive ADAS Dual-Battery
- Smart Meters & Medical
Autonomous Power Multiplexers Market segmented by Sales Channel:
- Direct OEM & Cloud Supply
- Authorized Electronics Distribution
- Contract EMS & ODM
- Catalog e-Commerce Channels
Autonomous Power Multiplexers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Texas Instruments Incorporated. (2026, July 22). TI reports second quarter 2026 financial results and shareholder returns. Texas Instruments Newsroom.
- [2] Hasan Babayi Nozadian, M., et al. (2025, May 12). Impact of the non-ideal condition in the analysis of high voltage gain switched impedance inverter with cost perspectives. Scientific Reports, 15(1), 16444 (PMC12069717).
- [3] Monolithic Power Systems, Inc. (2026, February 5). Monolithic Power Systems Announces Results for the Fourth Quarter and Year Ended December 31, 2025 and an Increase in Quarterly Cash Dividend. Monolithic Power Systems Investor Relations.
- [4] Alpha and Omega Semiconductor Limited. (2026, August 12). Alpha and Omega Semiconductor Reports Financial Results for Fiscal Fourth Quarter and Fiscal Year Ended June 30, 2026. AOS Investor Relations.
- [5] ROHM Co., Ltd. (2025, November 25). ROHM launches wide SOA MOSFET for AI servers in compact 5x6mm package. ROHM Newsroom.
- [6] Open Compute Project Foundation. (2026, September 30). Explore 22 Tracks at the 2026 OCP Global Summit. Open Compute Project News.
- [7] Diodes Incorporated. (2026, February 12). Form 10-K Annual Report for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
- [8] Green, G. (2025, June 12). SAE-MA-07610: 48V is coming, and not just for EVs. SAE International Automotive Engineering.
- [9] Ko, J. Y., et al. (2026, August 7). A hybrid piezoelectric resonator-based DC-DC converter. Nature Communications, 17(1), 4054 (PMC13139477).
- [10] onsemi. (2026, August 3). onsemi Reports Second Quarter 2026 Results. onsemi Newsroom.
- [11] Diodes Incorporated. (2026, May 7). Diodes Incorporated Reports First Quarter 2026 Financial Results. Diodes Investor Relations.
- [12] Nexperia B.V. (2026, October 27). Nexperia builds momentum with continued growth in Q3 2026. Nexperia Newsroom.
- [13] Rajendran, S., et al. (2025, May 5). Enhancing competitiveness in India's electric vehicle industry: impact of advanced manufacturing technologies and workforce development. Scientific Reports, 15(1), 15647 (PMC12053658).
- [14] Nguyen, H. P., & Nguyen, T. T. (2026, March 10). Design methodology for a photovoltaic emulator based on power hardware-in-the-loop with Opal-RT simulator. MethodsX, 17, 104119 (PMC13571559).
- [15] ROHM Co., Ltd. (2026, September 15). ROHM Launches a MOSFET with Industry-Leading Wide-SOA for Automotive Safety Functions and Protection Circuits. ROHM Newsroom.
- [16] Infineon Technologies AG. (2025, March 31). Power PROFET™ + 24/48V smart power switch family with highest energy efficiency for automotive power distribution. Infineon Technology News.
- [17] ROHM Co., Ltd. (2026, June 17). ROHM Launches AG16xFNxx Series MOSFETs for Automotive 48V Power Supply Systems. ROHM Newsroom.
- [18] STMicroelectronics N.V. (2025, September 19). STMicroelectronics and the Transformation of the Automotive Industry. STMicroelectronics Media Center.
- [19] Texas Instruments Incorporated. (2026, October 21). TI reports third quarter 2026 financial results and shareholder returns. Texas Instruments Newsroom.
- [20] Analog Devices, Inc. (2026, August 18). Form 10-Q Quarterly Report for the Quarterly Period Ended August 1, 2026. U.S. Securities and Exchange Commission EDGAR.
- [21] Diodes Incorporated. (2026, August 5). Diodes Incorporated Reports Second Quarter 2026 Financial Results. Diodes Investor Relations.
- [22] ROHM Co., Ltd. (2026, May 21). ROHM Launches ESD Protection Diodes for High-Speed Interfaces Exceeding 10 Gbps. ROHM Newsroom.
- [23] Vishay Intertechnology, Inc. (2025, May 21). Vishay Unveils High-Efficiency 80 V MOSFET in Compact PowerPAK® 8x8SW Package (SiEH4800EW). Vishay Company Press Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the global autonomous power multiplexers market in 2025, 2026, and 2036, and what is the 10-year CAGR?
- Why do enterprise EDSFF E3.S NVMe SSDs require sub-microsecond autonomous rail switchover instead of passive Schottky diodes?
- Why does Priority Fast OR-ing Mux lead the switchover control mode taxonomy in 2026?
- Which voltage rating tier records the fastest CAGR between 2026 and 2036?
- Why do Vietnam, Taiwan, and India lead country-level growth in autonomous power multiplexer procurement?
- At what continuous current threshold do monolithic power multiplexers cede sockets to external-FET ideal diode controllers?
- How do 300mm BCD wafer processes and copper-clip QFN packaging improve multiplexer thermal efficiency?
- Which companies lead global supply across enterprise storage, USB-C client computing, and ASIL-D automotive power nets?
Frequently Asked Questions
What is the market size of the autonomous power multiplexers market in 2025, 2026, and 2036?
Global autonomous power multiplexer demand advanced from USD 224.0 million in 2025 to USD 245.5 million in 2026, with long-term industry valuation forecast to hit USD 602.9 million by 2036 at a 9.4% CAGR.
How do autonomous power multiplexers differ from external-MOSFET active ideal diode controllers?
Autonomous power multiplexers integrate the back-to-back power MOSFETs and priority voltage comparators inside a single monolithic package for 0.5A to 12A rails, whereas active ideal diode controllers drive external discrete N-channel MOSFETs for 15A to 200A buses.
Which switchover control mode captures the largest market share in 2026?
Priority Fast OR-ing Mux commands a 61.4% share (USD 150.7 million) in 2026 because enterprise SSDs and USB-PD laptops require deterministic master-rail lock and sub-1-microsecond reverse-current blocking.
Why is the 28V to 60V Rails subsegment the fastest-growing voltage tier?
Demand for 28V to 60V Rails rises at an 11.1% CAGR from USD 60.9 million in 2026 to USD 174.5 million by 2036 owing to 48V AI server rack auxiliary buses and 36V/48V USB-PD Extended Power Range ports.
Which end-use application generates the largest demand in 2026?
Enterprise NVMe & Servers represent 49.5% of 2026 valuation (USD 121.5 million), supported by dual-rail U.3 and EDSFF E3.S solid-state drives and PCIe Gen 6 SmartNICs.
Which country achieves the highest CAGR between 2026 and 2036?
Vietnam posts the fastest country growth at an 11.3% CAGR through 2036 on multi-port USB Type-C notebook and docking station manufacturing in Bac Ninh and Hai Phong, ahead of Taiwan at 11.0%.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Switchover Control Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Switchover Control Mode, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Switchover Control Mode, 2026 to 2036
- Priority Fast OR-ing Mux
- Smooth Ideal-Diode Auto-Mux
- Manual Logic-Selected Mux
- Y-o-Y Growth Trend Analysis By Switchover Control Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Switchover Control Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Voltage Rating, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Voltage Rating, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Voltage Rating, 2026 to 2036
- 2.7V to 28V Rails
- 28V to 60V Rails
- 1.5V to 5.5V Rails
- Sub-1.5V Backup Rails
- Y-o-Y Growth Trend Analysis By Voltage Rating, 2021 to 2025
- Absolute $ Opportunity Analysis By Voltage Rating, 2026 to 2036
- Global Market Analysis and Forecast, By Protection Suite, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Protection Suite, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Protection Suite, 2026 to 2036
- Full Protection Clamping Mux
- Basic Dual-FET Switch Matrix
- Reverse-Block Only Mux
- Programmable Slew-Rate Mux
- Y-o-Y Growth Trend Analysis By Protection Suite, 2021 to 2025
- Absolute $ Opportunity Analysis By Protection Suite, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Application, 2026 to 2036
- Enterprise NVMe & Servers
- USB-C Notebook & Docks
- Automotive ADAS Dual-Battery
- Smart Meters & Medical
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct OEM & Cloud Supply
- Authorized Electronics Distribution
- Contract EMS & ODM
- Catalog e-Commerce Channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Vietnam
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Taiwan
- Pricing Analysis
- Market Share Analysis, 2025
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Switchover Control Mode
- By Voltage Rating
- By Protection Suite
- By End-Use Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Texas Instruments Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Analog Devices, Inc.
- Monolithic Power Systems
- STMicroelectronics N.V.
- Diodes Incorporated
- Alpha and Omega Semi
- onsemi
- ROHM Co., Ltd.
- Texas Instruments Incorporated
- Alpha and Omega Semiconductor Limited
- Texas Instruments Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


