

- Market Size (2026)
- USD 85.9 Bn
- Forecast (2036)
- USD 153.8 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Baby Food Market in 2026?
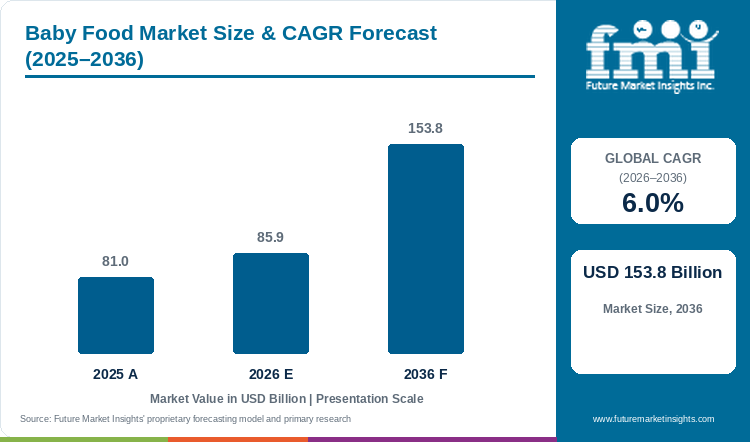
Worldwide baby food sector worth totals an estimated USD 85.9 billion across 2026 compared with USD 81.0 billion during 2025 and is forecast to scale to USD 153.8 billion by 2036 at a 6.0% CAGR.
Dual-income parents who supplement breastfeeding look for infant formulas and weaning foods that match the prebiotic sugars and essential fats found in mother's milk. Clinical findings published in Archivos Argentinos de Pediatria during August 2025 confirmed that infant formulas enriched with structurally identical human milk oligosaccharides such as 2'-FL and LNT plus sialylated fractions feed beneficial infant bifidobacteria while blocking harmful gut pathogens [1]. Because families purchase these multi-stage milk powders every week before solid weaning, Milk Formula is projected to take 51.9% of the 2026 product type market share as brands add human milk oligosaccharides into flagship supermarket cans. Compared with a USD 81.0 billion sector worth during 2025, FMI estimates that worldwide baby food market value totals USD 85.9 billion across 2026 and scales to a projected USD 153.8 billion by 2036, exhibiting a 6.0% CAGR that generates USD 67.9 billion in ten-year valuation expansion.
Key Market Trends & Insights
- By product type: Milk Formula is projected to take 51.9% of the 2026 product mix because powdered and ready-to-feed infant milks serve as the primary nutrition source before weaning.
- By nature: Conventional HMO-Fortified products are estimated to collect 59.3% of the 2026 nature category as pediatricians recommend five-HMO synbiotic blends at accessible grocery price points.
- By distribution channel: Supermarkets & Hypermarkets are expected to constitute 40.9% of the 2026 distribution channel market size through one-stop weekly family shopping and WIC-eligible shelf assortments.
- By infant age stage: Stage 1 & 2 Starter and Follow-On 0 to 12 Months is forecast to retain 41.7% of the 2026 age division owing to strict composition mandates during the first 12 months.
- By packaging format: Composite Metal Cans & Tubs are anticipated to hold 53.7% of the 2026 packaging format share while HMO, DHA/ARA & Probiotic Enriched recipes secure 43.9% of functional ingredient market value.
Regional Highlights
- Highest national growth rate: The baby food market size in Indonesia is projected to increase by 7.4% every year through 2036 on rising female workforce participation and toddler growing-up milk adoption.
- Multi-region growth comparison: Brazil's baby food valuation is expected to climb 7.1% per annum followed by Mexican sector worth at 6.8% and the USA at 5.3%, while British industry valuation grows 5.0% and France widens 4.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Baby Food Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 81.0 billion |
| Estimated Market Size in 2026 | USD 85.9 billion |
| Projected Market Size by 2036 | USD 153.8 billion |
| CAGR, 2026 to 2036 | 6.0% |
| Added Market Value, 2026 to 2036 | USD 67.9 billion |
Medical society guidelines covering probiotic and prebiotic fortification paired with synbiotic blends in infant formulas now shape how pediatric brands back up gut-health claims on retail cans. In August 2025, the ESPGHAN Special Interest Group on Gut Microbiota and Modifications published clinical practice recommendations in the Journal of Pediatric Gastroenterology and Nutrition concluding that evaluated biotic-supplemented formulas fed to healthy infants raise no safety concerns and issuing a conditional recommendation that galacto- and fructo-oligosaccharides soften infant stool consistency [2]. Formula producers are therefore upgrading infant formula recipes with clinically tested five-HMO blends and Bifidobacterium infantis strains to earn hospital nursery and pediatrician recommendations.
Global Birth Cohort and Per-Infant Nutrition Sizing
Table 2: Birth Cohort and Per-Child Market Value Indicators for the Baby Food Market (USD billion, million infants, and USD per child), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 81.0 | 85.9 | 153.8 |
| Global annual birth cohort (million births) | 132.1 | 132.5 | 134.9 |
| Infants & toddlers aged 0 to 36 months (million) | 392.0 to 398.0 | 394.0 to 400.0 | 401.0 to 408.0 |
| Annual baby food market value per child 0-36m (USD) | 203.5 to 206.6 | 214.8 to 218.0 | 377.0 to 383.5 |
Operational note: Per-child valuation indicators divide the global baby food market value covering Stages 1 to 3 milk formulas and weaning purees plus dry cereals across the global 0-to-36-month infant cohort.
Because global annual births stay nearly flat between 132.5 million in 2026 and 134.9 million in 2036, industry valuation growth depends on higher market value per child across urban middle-class families. Pediatric nutrition brands increasingly bundle Stage 1 starter formulas with prepared baby food purees and toddler growing-up milks to keep households within the same brand across the full 36-month feeding window.
Per Capita & Retail Channel Sizing
Table 3: Per Capita and Per-Birth Valuation Indicators for the Baby Food Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per capita (USD) | 9.9 | 10.3 | 17.1 |
| Market value per 1,000 people (USD) | 9,878.0 | 10,349.4 | 17,088.9 |
| Annual market value per birth (USD) | 613.2 | 648.3 | 1,140.1 |
Table 4: Product & Distribution Channel Valuation Indicators for the Baby Food Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 85.9 billion | 2026 global retail & clinical baseline |
| Milk formula segment valuation, 2026 | USD 44.6 billion | 51.9% product type segment allocation |
| Supermarket & hypermarket channel valuation, 2026 | USD 35.1 billion | 40.9% distribution channel allocation |
| Stage 1 & 2 (0-12m) segment valuation, 2026 | USD 35.8 billion | 41.7% infant age stage allocation |
Infants moving from liquid milk feeding to solid weaning foods between 6 and 24 months need allergen-tested cereal flakes and low-sugar vegetable purees. Pediatric dietitians guide parents toward iron-fortified early life nutrition plans that pair follow-on milk formulas with single-grain rice and oat porridges.
Analyst Perspective
"With global birth cohorts stabilizing, baby food manufacturers are driving market valuation growth by upgrading standard milk formulas to five-HMO and A2 beta-casein recipes. Brands maintaining zero-defect Cronobacter and heavy-metal traceability across composite cans and pouches will secure retail shelf leadership."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the baby food market segmented?
The baby food market is segmented by product type, nature, distribution channel, infant age stage, packaging format, functional ingredient, and region. In 2026, Milk Formula is projected at 51.9%, Conventional HMO-Fortified at 59.3%, Supermarkets & Hypermarkets at 40.9%, Stage 1 & 2 Starter and Follow-On 0 to 12 Months at 41.7%, Composite Metal Cans & Tubs at 53.7%, and HMO, DHA/ARA & Probiotic Enriched at 43.9%.
By product type: Milk Formula, Prepared Purees, Dried Baby Cereals, and Teething Biscuits & Finger Snacks.
By nature: Conventional HMO-Fortified pediatric formulations versus Certified Organic & Grass-Fed retail ranges.
By distribution channel: Supermarkets & Hypermarkets, Pharmacies & Drugstores, and Online Retail & Subscription.
By infant age stage: Stage 1 & 2 Starter and Follow-On 0 to 12 Months, Stage 3 Toddler & Growing-Up 12 to 36 Months, and Special Medical & Hypoallergenic Hydrolyzed.
By packaging format: Composite Metal Cans & Tubs, Reclosable Spouted Stand-Up Pouches, Vacuum-Sealed Glass Jars, and Aseptic RTD Hospital Nursery Bottles.
By functional ingredient: HMO, DHA/ARA & Probiotic Enriched, A2 Beta-Casein & Goat-Milk Based, and Plant-Based & Soy-Based Pediatric.
What makes Milk Formula the largest product type category?
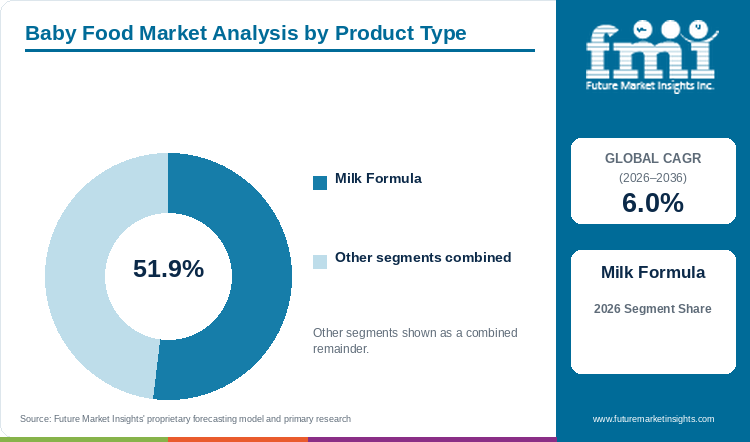
Milk Formula is projected to take 51.9% of the 2026 product type mix, powered by infant nutritional completeness.
Table 5: Product Type Share for the Baby Food Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Milk Formula | 51.9% |
| Other Segments Combined | 48.1%* |
| Total | 100.0% |
*Note: Combined share of remaining product type categories totaling 100.0% of 2026 global baby food market value.
Table 6: Product Type Leadership and Market Growth for the Baby Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Milk Formula |
Spray-dried and ready-to-feed infant milk formulas represent the highest-value recurring purchase for bottle-fed babies because every batch must meet strict statutory protein and lipid minimums together with vitamin and mineral standards. Manufacturers blend demineralized whey and lactose with infant formula ingredients such as algal DHA and arachidonic acid to support newborn brain and eye development.
- Milk Formula is projected to take 51.9% of the 2026 product type mix because multi-stage powdered cans command higher unit prices and daily feeding frequency than weaning purees.
- In August 2025, Abbott Laboratories highlighted clinical findings from its 607-infant U.S. randomized controlled trial confirming that Similac 360 Total Care with five HMOs supports growth and cognitive language outcomes comparable to breastfed infants [3].
Why does Conventional HMO-Fortified lead the nature category?
Conventional HMO-Fortified recipes are estimated to collect 59.3% of the 2026 nature category, shaped by prebiotic oligosaccharide inclusion.
Fermentation-derived 2'-fucosyllactose and lacto-N-neotetraose blended into standard cow's milk formulas let mainstream baby brands deliver immune and gut-flora support without the 30% to 45% retail price jump of certified organic milk. Hospital maternity tenders and public nutrition programs likewise specify conventional baby milk formulations enriched with prebiotic oligosaccharides paired with lutein and nucleotides.
- Conventional HMO-Fortified products are estimated to collect 59.3% of the 2026 nature category as five-HMO blends become standard across flagship supermarket formula lines.
- A March 2026 ex vivo infant gastrointestinal microbiota study by Abbott Nutrition scientists in Frontiers in Pediatrics demonstrated that a five-HMO blend supports microbiome recovery after antibiotic exposure and inhibits pathogen adhesion in cultured intestinal epithelial cells [4].
How do Supermarkets & Hypermarkets retain the top distribution channel share?
Supermarkets & Hypermarkets are expected to constitute 40.9% of 2026 channel valuation, assisted by family grocery trips.
Dedicated baby aisles inside national supermarket and hypermarket chains let parents check can expiration dates and redeem government nutrition vouchers during weekly family grocery trips. Grocery chains also run multi-pack promotions on baby snacks and finger foods and private-label infant formulas produced under FDA and EU safety rules.
- Supermarkets & Hypermarkets are expected to constitute 40.9% of the 2026 distribution channel market size ahead of pharmacies and drugstores plus online subscription platforms.
- In November 2025, Perrigo Company plc reported that its U.S. and Canadian store-brand and Good Start infant formula operations generated approximately USD 360 million in annual net sales across major grocery and pharmacy retailers [5].
Why does Stage 1 & 2 Starter and Follow-On 0 to 12 Months lead by age stage?
Stage 1 & 2 Starter and Follow-On 0 to 12 Months is forecast to retain 41.7% in 2026, facilitated by neonatal feeding.
Infants aged 0 to 12 months need six to eight liquid feedings a day during the first six months, followed by iron-fortified follow-on formulas and smooth Stage 2 weaning purees through their first birthday. Strict marketing rules on Stage 1 starter formulas also lead pediatric brands to differentiate Stage 2 follow-on and medical hypoallergenic formulas across pediatric clinics.
- Stage 1 & 2 Starter and Follow-On 0 to 12 Months is forecast to retain 41.7% of the 2026 infant age stage division due to mandatory nutritional reliance prior to table-food transition.
- A February 2025 narrative review of 43 studies published between 2004 and 2024 from the University of Colorado Anschutz Medical Campus in Nutrients documented that introducing solid complementary foods between 6 and 24 months increases infant gut microbial alpha-diversity [6].
What keeps Composite Metal Cans & Tubs and HMO, DHA/ARA & Probiotic Formats ahead?
Composite Metal Cans & Tubs are anticipated to carry 53.7% of 2026 packaging shipments, attributed to oxygen barriers.
Hermetically seamed tinplate and aluminum-foil composite cans flushed with nitrogen keep delicate DHA and ARA fatty acids from oxidizing while shielding live probiotic powders from moisture. Inside those cans, HMO, DHA/ARA & Probiotic Enriched recipes capture 43.9% of functional ingredient market value by pairing prebiotic sugars with live LGG and Bifidobacterium strains.
- Composite Metal Cans & Tubs are anticipated to carry 53.7% of 2026 packaging format shipments while Reclosable Spouted Stand-Up Pouches expand across organic fruit and vegetable purees.
- In March 2025, a pediatric feeding mini-review published in Frontiers in Pediatrics emphasized offering a variety of nutrient-dense and appropriately textured foods while practicing motor feeding skills across infant complementary feeding stages [7].
What are the drivers, restraints, and opportunities in the baby food market?
Premiumization toward multi-HMO synbiotic formulas and organic spouted purees is projected to expand baby food market value through 2036, whereas microbial recall liabilities restrain plant margins and hypoallergenic hydrolyzed and A2 goat-milk lines create specialized growth opportunities.
- Driver: Higher maternal workforce participation in emerging economies and multi-HMO probiotic formula upgrades lift per-infant market value.
- Restraint: Stringent FDA and European microbial testing rules combined with batch recall risks and low birth rates in mature economies raise plant compliance costs.
- Opportunity: Extensively hydrolyzed hypoallergenic formulas and A2 beta-casein goat-milk recipes paired with zero-added-sugar toddler snacks capture pediatrician-referred niches.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Dual-income urban households across Asia-Pacific and the Americas increasingly buy clinically tested Stage 1 through Stage 3 formulas and organic ready-to-serve purees that save preparation time while guaranteeing daily vitamins and iron. Future Market Insights notes that parents willingly trade up to probiotic infant formula SKUs containing five to six human milk oligosaccharides and omega-3 phospholipids. In August 2025, Reckitt Benckiser Group plc marked 120 years of Mead Johnson Nutrition innovation by highlighting clinical research behind Enfamil NeuroPro with MFGM and 2'-FL HMO as well as Nutramigen LGG hypoallergenic formulas [8]. Sustained brand investment in clinical trials therefore supports a 6.0% ten-year growth rate through 2036.
Risk Assessment of the Baby Food Market: Operational and Formulation Friction
Zero-tolerance regulatory enforcement against Cronobacter sakazakii and Salmonella plus Clostridium botulinum contamination in powdered infant formula plants creates heavy recall and legal exposure for manufacturers. Under U.S. Food and Drug Administration rules in 21 CFR 106 and Section 412 of the U.S. FD&C Act, every new infant formula requires a 90-day premarket notification plus strict batch pathogen and nutrient testing. In September 2026, the U.S. FDA updated its Infant Formulas Marketed in the U.S. registry documenting the June 2026 multistate infant botulism outbreak investigation and voluntary recall of imported whole-milk organic powdered formula [9]. Cleanroom dry-blending hygiene across pediatric nutrition products therefore demands continuous capital investment and daily environmental swabbing.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
More frequent diagnosis of cow's milk protein allergy (CMPA) and preterm low-birth-weight admissions coupled with parental demand for gentle proteins create high-margin sales for exempt medical formulas and goat-milk or A2 beta-casein recipes. Instead of competing on price in standard bovine Stage 1 powder, pediatric specialists formulate extensively hydrolyzed casein and free amino-acid powders plus goat-milk formulas. In June 2026, the U.S. Food and Drug Administration updated its Exempt Infant Formulas Marketed in the United States directory covering metabolic and premature lines together with extensively hydrolyzed and amino-acid formulas from Abbott and Mead Johnson plus Nestle Health Science and Nutricia [10]. Manufacturers that pair extensively hydrolyzed proteins with galacto-oligosaccharide prebiotics are winning pharmacy-reimbursed clinical prescriptions.
Baby Food Market by Country (2026 to 2036)
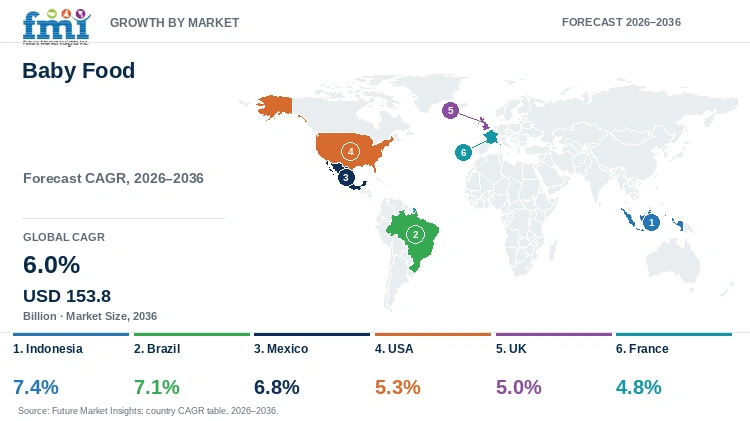
Indonesia sets the pace across the six analyzed baby food countries by increasing 7.4% annually in sector valuation until 2036 ahead of Brazil at 7.1% and Mexico at 6.8%. United States baby food market value advances 5.3% per year while the UK climbs 5.0% and France widens 4.8% on pharmacy HMO upgrades.
Table 7: Country CAGR and Primary Growth Levers for the Baby Food Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Indonesia | 7.4% | 4.4 million annual birth cohort and rapid urban adoption of Stage 3 growing-up milks and fortified cereals |
| Brazil | 7.1% | 9% retail food expansion and pharmacy-led demand for HMO-enriched and hypoallergenic infant formulas |
| Mexico | 6.8% | Record USD 30.6 billion U.S. agricultural/dairy trade and expanding modern supermarket baby aisles |
| USA | 5.3% | FDA Operation Stork Speed supply diversification and 5-HMO, organic whole-milk, and goat formula launches |
| UK | 5.0% | NHS weaning guidance and #1 organic spouted pouch and HMO follow-on formula adoption |
| France | 4.8% | Pharmacy-supervised specialized infant formula dispensing and strict organic puree standards |
Source: Future Market Insights analysis
Indonesia Baby Food Market Outlook (2026 to 2036)
Southeast Asia's largest annual birth cohort of roughly 4.4 million newborns combined with national stunting-reduction initiatives makes Indonesia the primary regional growth engine for iron-fortified infant cereals and Stage 3 growing-up milks. April 2026 Jakarta agricultural analysts documented that Indonesia's domestic food and beverage processing sector continues to expand imported dairy and micronutrient utilization across pediatric and family nutrition product lines [11]. Indonesia's commercial baby food sector valuation is projected to increase by 7.4% every year through 2036 across modern minimarkets and mobile e-commerce platforms. Strict BPOM halal certification timelines and sucrose-labeling rules still require multinational pediatric brands to localize domestic dry blending and packaging across Java.
Key takeaway: In Indonesia, anti-stunting micronutrient fortification and a 4.4 million annual birth cohort are projected to lift baby food market value by 7.4% every year.
Brazil Baby Food Market Outlook (2026 to 2036)
Modern urban pharmacy chains and rising female workforce participation across Sao Paulo and Rio de Janeiro propel commercial demand for HMO-enriched milk formulas and organic fruit-and-grain pouches in Brazil. November 2025 Sao Paulo retail food filings confirmed that the Brazilian grocery retail sector expanded 9% as domestic household demand and consumer-oriented food imports strengthened across modern supermarket chains [12]. Brazil's baby food market valuation is expected to climb 7.1% per annum across the ten-year forecast decade inside drugstore chains and cash-and-carry hypermarkets. Because ANVISA Law 11.265 strictly prohibits promotional price discounting on Stage 1 infant formulas, manufacturers focus commercial marketing on Stage 3 toddler compounds and zero-added-sugar cereal porridges.
Key takeaway: In Brazil, drugstore pediatric nutrition expansion and 9% retail grocery growth are expected to lift baby food market valuation by 7.1% per annum.
Mexico Baby Food Market Outlook (2026 to 2036)
Close North American dairy supply-chain integration under USMCA and rapid modern supermarket expansion across northern and central industrial cities anchor commercial pediatric nutrition demand in Mexico. April 2026 Mexico City agricultural trade filings showed that Mexico remained the top global destination for United States agricultural exports at a record USD 30.6 billion, led by record dairy and food preparation shipments [13]. The baby food industry valuation in Mexico is anticipated to ascend at a 6.8% annual tempo until 2036 as urban families adopt spouted fruit purees and iron-fortified follow-on formulas. COFEPRIS front-of-pack warning-octagon rules on added sugars and sodium compel baby snack and cereal producers to reformulate with whole-grain flours and prebiotic fibers.
Key takeaway: In Mexico, USMCA dairy-ingredient integration and COFEPRIS sugar-free recipe reformulation are forecast to underpin a 6.8% annual climb until 2036.
USA Baby Food Market Outlook (2026 to 2036)
Regulatory diversification under FDA Operation Stork Speed and rapid parental shifts toward five-HMO and organic grass-fed or goat-milk formulas reshape the United States baby food sector. In September 2026, the U.S. Department of Justice and FDA documented heightened federal consent-decree and safety compliance oversight across domestic infant formula manufacturing plants [14]. The baby food industry valuation in the USA is forecast to develop at a 5.3% yearly rate over the ten-year window across national supermarkets and wholesale club stores plus home-delivery subscriptions. State laws mandating QR-code batch disclosure for heavy metals including lead and arsenic in baby purees also push U.S. brands toward hydroponic and soil-screened organic farm crops.
Key takeaway: In the USA, five-HMO formula premiumization and heavy-metal QR-code transparency mandates are forecast to sustain a 5.3% yearly rate through 2036.
UK Baby Food Market Outlook (2026 to 2036)
High household penetration of organic spouted stand-up pouches and strict Competition and Markets Authority scrutiny of infant formula retail pricing characterize the United Kingdom baby food market. During 2026, the UK National Health Service Best Start in Life weaning framework reinforced public guidance on introducing iron-rich and no-added-sugar solid foods with breast milk or infant formula from around six months of age [15]. British baby food market value is slated to build at a 5.0% compound pace to 2036 across national grocery chains and retail pharmacy counters. Cost-of-living pressures and NHS limits on sugary fruit snacks prompt UK parents to favor savory vegetable-and-lentil pouches and whole-milk British infant formulas across domestic supermarkets.
Key takeaway: In the UK, NHS six-month weaning guidelines and high organic savory pouch adoption are slated to build market valuation at a 5.0% compound pace.
France Baby Food Market Outlook (2026 to 2036)
Strong pediatric pharmacy dispensing traditions and deeply rooted parental preference for vacuum-sealed glass vegetable and fish jars distinguish France from Anglo-Saxon baby food markets. September 2026 Paris agricultural trade data indicated that French retail food price inflation moderated to 1.2% as large general food retailers accounted for 58.6% of national retail food distribution while adapting to national AGEC packaging waste laws [16]. French baby food market size is likely to widen by 4.8% each year through 2036 despite a gradually declining national birth cohort. Because French parents scrutinize pesticide residues and ultra-processed emulsifiers, domestic market leaders expand organic biodynamic glass-jar purees and thickened anti-regurgitation pharmacy formulas across specialized drugstores and suburban hypermarkets.
Key takeaway: In France, pharmacy-dispensed specialty formulas and organic glass-jar culinary standards are likely to widen category value by 4.8% each year.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the baby food market?
Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group plc, The Hain Celestial Group, Inc., Hero Group, HiPP GmbH & Co. Vertrieb KG, and Perrigo Company plc are the notable companies in the baby food market.
Brand leadership across the global baby food industry rests on clinical HMO trial proof and hospital nursery contracts backed by certified-organic puree pouch distribution. Global nutrition groups operate multi-continent spray-drying towers and pouch lines across more than 100 countries, whilst pharmaceutical-rooted formula makers anchor hospital nursery contracts and WIC state tenders. European and North American organic specialists differentiate through certified-organic pouches and glass jars plus store-brand infant formulas.
- Global Early-Life & Specialized Nutrition Leaders: Nestlé S.A. and Danone S.A. supply flagship multi-HMO infant formulas such as NAN and Aptamil plus Gerber and Bledina weaning purees and cereals.
- Clinical & Hospital Infant Formula Platforms: Abbott Laboratories and Reckitt Benckiser Group plc anchor hospital nursery and WIC contracts while Perrigo Company plc supplies store-brand FDA-notified formulas.
- Organic Baby Puree & Biodynamic Formula Specialists: The Hain Celestial Group Inc. and Hero Group lead in certified-organic pouches such as Ella's Kitchen and Beech-Nut while HiPP GmbH & Co. Vertrieb KG anchors European organic combiotic formulas.
Competitive Benchmarking: Baby Food Market
Table 8: Competitive Benchmarking for the Baby Food Market (qualitative capability ratings), 2026
| Company | Formula & Puree Breadth | HMO & Clinical Fortification | Hospital & Retail Access | Geographic Reach |
|---|---|---|---|---|
| Nestlé S.A. | High | High | High | High |
| Danone S.A. | High | High | High | High |
| Abbott Laboratories | Medium | High | High | High |
| Reckitt Benckiser Group plc | Medium | High | High | High |
| The Hain Celestial Group, Inc. | High | Medium | High | Medium |
| Hero Group | High | Medium | High | Medium |
| HiPP GmbH & Co. Vertrieb KG | High | High | High | Medium |
| Perrigo Company plc | Medium | Medium | High | Medium |
Scoring basis: Matrix ratings review commercial breadth across Stages 1 to 3 milk formulas and exempt hypoallergenic formulas paired with pureed pouches and dry cereals. HMO fortification and access marks reflect verified five- and six-HMO clinical studies paired with FDA/EFSA premarket notifications and hospital/supermarket distribution reach.
Key Developments in the Baby Food Market
- Hero Group reported CHF 1,187 million in 2025 net sales and 7.0% organic growth across its Better Snacking platform in March 2026 led by Organix and Beech-Nut plus Freche Freunde baby and toddler foods [17].
- Nestlé S.A. announced in February 2026 the strategic integration of its Nutrition and Nestlé Health Science divisions into a single global Nutrition powerhouse generating CHF 14.304 billion in combined 2025 sales across infant and medical nutrition [18].
- Danone S.A. recorded EUR 9.3 billion in 2025 Specialized Nutrition sales and implemented its updated 2026 Baby Formula Marketing Standards across Aptamil and Bledina plus Neocate early-life nutrition portfolios [19].
Key Players in the Baby Food Market
Global Early-Life & Specialized Nutrition Leaders
- Nestlé S.A.
- Danone S.A.
Clinical & Hospital Infant Formula Platforms
- Abbott Laboratories
- Reckitt Benckiser Group plc
- Perrigo Company plc
Organic Baby Puree, Snack & Biodynamic Formula Specialists
- The Hain Celestial Group, Inc.
- Hero Group
- HiPP GmbH & Co. Vertrieb KG
Baby Food Market - Report Scope
Table 9: Report Scope for the Baby Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Nature; Distribution Channel; Infant Age Stage; Packaging Format; Functional Ingredient; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial retail, pharmacy, and hospital market value from packaged nutrition formulated for infants and young children aged 0 to 36 months (Stage 1 starter, Stage 2 follow-on, Stage 3 growing-up, and exempt hypoallergenic/special medical milk formulas; prepared vegetable, fruit, and meat purees; dried baby cereals; and teething biscuits and finger snacks). Category Scope Note: Excludes bulk B2B dairy or HMO raw ingredients sold prior to blending, feeding bottles/appliances, and general family foods not labeled for children under 36 months. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Indonesia, Brazil, Mexico, USA, UK, France, and additional countries in the full report |
| Key Companies Covered | Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group plc, The Hain Celestial Group, Inc., Hero Group, HiPP GmbH & Co. Vertrieb KG, Perrigo Company plc |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Baby Food Market - Research Methodology
Table 10: Research Methodology for the Baby Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with pediatric nutrition R&D directors, hospital neonatal dietitians, infant formula quality-assurance managers, and supermarket baby-category buyers to validate stage pricing and channel shares. |
| Secondary Research | Analysis of corporate annual filings, U.S. FDA non-exempt and exempt infant formula registries, ESPGHAN clinical practice guidelines, PubMed and PMC pediatric nutrition studies, and USDA FAS retail food reports. |
| Market Sizing and Forecasting | Top-down pediatric nutrition market valuation models reconciled against bottom-up 0-to-36-month birth cohorts, non-exclusive breastfeeding rates, and annual per-child market value from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight national birth cohorts, female labor participation, pharmacy versus grocery channel mix, and HMO/organic price tiers across Indonesia, Brazil, Mexico, the USA, the UK, and France. |
| Operational Benchmark Traceability | Birth cohort, per-child valuation, and channel allocation indicators in Tables 2, 3, and 4 trace to UN demographic projections, FDA formula registries, ESPGHAN clinical reviews, and corporate segment disclosures. |
| Data Triangulation and Validation | Market size estimates are cross-checked against branded and store-brand formula notifications and retail scanner audits without double counting upstream B2B whey or HMO ingredient valuations. |
Baby Food Market by Segments
Baby Food Market segmented by Product Type:
- Milk Formula
- Prepared Purees
- Dried Baby Cereals
- Teething Biscuits & Finger Snacks
Baby Food Market segmented by Nature:
- Conventional HMO-Fortified
- Certified Organic & Grass-Fed
Baby Food Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Pharmacies & Drugstores
- Online Retail & Subscription
Baby Food Market segmented by Infant Age Stage:
- Stage 1 & 2 Starter and Follow-On 0 to 12 Months
- Stage 3 Toddler & Growing-Up 12 to 36 Months
- Special Medical & Hypoallergenic Hydrolyzed
Baby Food Market segmented by Packaging Format:
- Composite Metal Cans & Tubs
- Reclosable Spouted Stand-Up Pouches
- Vacuum-Sealed Glass Jars
- Aseptic RTD Hospital Nursery Bottles
Baby Food Market segmented by Functional Ingredient:
- HMO, DHA/ARA & Probiotic Enriched
- A2 Beta-Casein & Goat-Milk Based
- Plant-Based & Soy-Based Pediatric
Baby Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Del Compare, M., Fernández, A., Tabacco, O., & Vinderola, G. (2025, August 1). Human milkoligosaccharides: Role in lactation and infant formulas. Archivos Argentinos de Pediatria, 123(4), e202410489 (PubMed PMID 39699572).
- [2] Dinleyici, E. C., Indrio, F., Szajewska, H., Hojsak, I., Salvatore, S., Mihatsch, W. A., et al. (2025, August 17). Recommendations on the health outcomes of infant formula supplemented with biotics by the ESPGHAN Special Interest Group on Gut Microbiota and Modifications. Journal of Pediatric Gastroenterology and Nutrition, 82(1), 289-304 (PubMed PMID 40819278).
- [3] Abbott Laboratories. (2025, August 20). With infant formula, innovating means getting ever closer to breast milk. Abbott Corporate Newsroom.
- [4] Morrin, S. T., Buck, R. H., & Hill, D. R. (2026, March 5). A unique blend of five human milk oligosaccharides supports recovery of infant microbiome composition and function after ex vivo antibiotic use. Frontiers in Pediatrics, 14, 1765159 (PubMed PMID 41867919).
- [5] Perrigo Company plc. (2025, November 5). Perrigo to Conduct Strategic Review of its Infant Formula Business. Perrigo Investor Relations.
- [6] Noles, D. L., Matzeller, K. L., Frank, D. N., Krebs, N. F., & Tang, M. (2025, February 20). Complementary Feeding and Infant Gut Microbiota: A Narrative Review. Nutrients, 17(5), 743 (PubMed PMID 40077613).
- [7] Swanson, W. S., Ross, E. S., Matiz, L. A., Czerkies, L., Huss, L. R., Smith-Simpson, S., Bettler, J., & Pac, S. (2025, March 27). Essential elements for learning to eat: guidance to support families with infants and young children. Frontiers in Pediatrics, 13, 1493780 (PubMed PMID 40212062).
- [8] Reckitt Benckiser Group plc. (2025, August 29). Mead Johnson Nutrition Celebrates 120 Years of Innovation in Global Infant Nutrition. Reckitt Newsroom.
- [9] U.S. Food and Drug Administration. (2026, September 1). Infant Formulas Marketed in the U.S. U.S. Food and Drug Administration Infant Formula Homepage.
- [10] U.S. Food and Drug Administration. (2026, June 1). Exempt Infant Formulas Marketed in the United States By Manufacturer and Category. U.S. Food and Drug Administration Guidance & Regulation.
- [11] USDA Foreign Agricultural Service. (2026, April 2). Indonesia: Food Processing Ingredients Annual. USDA Foreign Agricultural Service GAIN Report ID2026-0011.
- [12] USDA Foreign Agricultural Service. (2025, November 21). Brazil: Retail Foods Annual. USDA Foreign Agricultural Service GAIN Report BR2025-0035.
- [13] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual. USDA Foreign Agricultural Service GAIN Report MX2026-0022.
- [14] U.S. Department of Justice Office of Public Affairs. (2026, September 14). Abbott Agrees to Pay Over $384M to Settle Allegations Related to Contaminated Infant Formula. U.S. Department of Justice Press Releases.
- [15] National Health Service (NHS). (2026, August 15). Weaning - Best Start in Life. NHS GOV.UK.
- [16] USDA Foreign Agricultural Service. (2026, September 30). France: Retail Foods Annual. USDA Foreign Agricultural Service GAIN Report FR2026-0010.
- [17] Hero Group. (2026, March 20). Hero Group delivers profitable growth in 2025 and sets 'Hero 2035' strategy to lead in Better Snacking. Hero Group Press Releases.
- [18] Nestlé S.A. (2026, February 19). Full-year results 2025 and strategic update: Strong momentum, accelerating strategic change. Nestlé Global Media Releases.
- [19] Danone S.A. (2025, October 15). Supporting health at all life stages with Specialized Nutrition. Danone Group.
- [20] The Hain Celestial Group, Inc. (2026, August 17). Hain Celestial Announces Fiscal 2026 Fourth Quarter and Full Year Financials Results Conference Call and Webcast. The Hain Celestial Group Investor Relations.
- [21] HiPP GmbH & Co. Vertrieb KG. (2026, February 12). Welcome to HiPP International: HiPP Organic Milk Formula and Baby Food. HiPP International.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the baby food market in 2026 and what is forecast for 2036?
- Which clinical HMO and weaning nutrition pressures support demand for baby food?
- Why does Milk Formula lead the product type category?
- Why does Conventional HMO-Fortified lead the nature category globally?
- How do growth rates differ across Indonesia, Brazil, Mexico, the USA, the UK, and France?
- Which leading companies manufacture infant formulas, organic purees, and baby snacks today?
- What limits adoption or supplier switching in the baby food market?
- What should retail, pharmacy, and hospital buyers evaluate before procuring baby food?
Frequently Asked Questions
How big is the baby food market in 2026, and what is forecast for 2036?
Compared with a USD 81.0 billion sector worth during 2025, FMI estimates that worldwide baby food market value totals USD 85.9 billion across 2026 and scales to a projected USD 153.8 billion by 2036 on multi-HMO formula and organic puree adoption.
What is the CAGR for the baby food market from 2026 to 2036?
The global baby food market value is projected by Future Market Insights to exhibit a 6.0% ten-year growth rate from 2026 to 2036, generating USD 67.9 billion in added market value across retail and pharmacy channels.
Which product type segment leads the baby food market?
Milk Formula is projected to take 51.9% of the 2026 product type mix because powdered and ready-to-feed formulas provide complete daily nutrition across starter and follow-on stages plus toddler milks.
Which nature segment leads the baby food market?
Conventional HMO-Fortified recipes are estimated to collect 59.3% of the 2026 nature category as pediatricians recommend five-HMO synbiotic formulas at accessible supermarket price points.
Which country has a notable growth outlook during the assessment period?
Indonesia is projected to pace analyzed baby food markets by increasing 7.4% every year through 2036 on a 4.4 million annual birth cohort and anti-stunting micronutrient fortification.
Who are the key players in the market?
Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group plc, The Hain Celestial Group, Inc., Hero Group, HiPP GmbH & Co. Vertrieb KG, and Perrigo Company plc anchor global retail and pharmacy supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Milk Formula
- Prepared Purees
- Dried Baby Cereals
- Teething Biscuits & Finger Snacks
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional HMO-Fortified
- Certified Organic & Grass-Fed
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Pharmacies & Drugstores
- Online Retail & Subscription
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Infant Age Stage, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Infant Age Stage, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Infant Age Stage, 2026 to 2036
- Stage 1 & 2 Starter and Follow-On 0 to 12 Months
- Stage 3 Toddler & Growing-Up 12 to 36 Months
- Special Medical & Hypoallergenic Hydrolyzed
- Y-o-Y Growth Trend Analysis By Infant Age Stage, 2021 to 2025
- Absolute $ Opportunity Analysis By Infant Age Stage, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Composite Metal Cans & Tubs
- Reclosable Spouted Stand-Up Pouches
- Vacuum-Sealed Glass Jars
- Aseptic RTD Hospital Nursery Bottles
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Functional Ingredient, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Functional Ingredient, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Functional Ingredient, 2026 to 2036
- HMO, DHA/ARA & Probiotic Enriched
- A2 Beta-Casein & Goat-Milk Based
- Plant-Based & Soy-Based Pediatric
- Y-o-Y Growth Trend Analysis By Functional Ingredient, 2021 to 2025
- Absolute $ Opportunity Analysis By Functional Ingredient, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Indonesia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By Distribution Channel
- By Infant Age Stage
- By Packaging Format
- By Functional Ingredient
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- Abbott Laboratories
- Reckitt Benckiser Group plc
- The Hain Celestial Group, Inc.
- Hero Group
- HiPP GmbH & Co. Vertrieb KG
- Perrigo Company plc
- Nestlé S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


