

- Market Size (2026)
- USD 4.0 Bn
- Forecast (2036)
- USD 8.7 Bn
- CAGR (2026 to 2036)
- 8.1%
How big is Calf Milk Replacer Market in 2026?
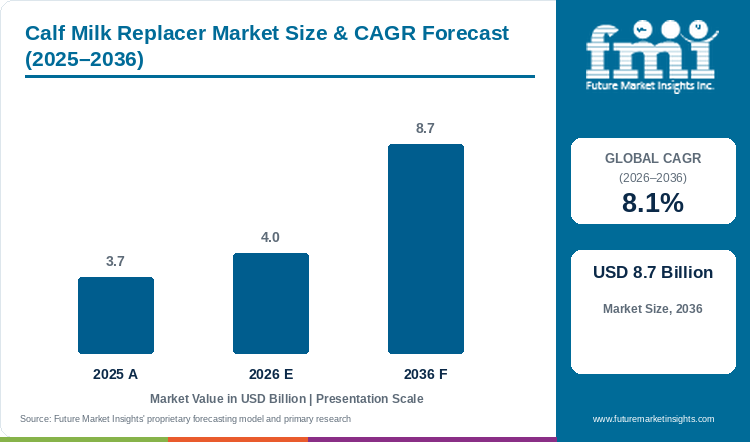
Demand for calf milk replacer is projected to grow at 8.1% CAGR between 2026 and 2036. The market increases from USD 3.7 billion in 2025 to USD 4.0 billion in 2026 and is expected to reach USD 8.7 billion by 2036.
Increasing number of calves moving under planned liquid feeding and rising need for the same nutrition at every feeding is supporting the calf milk replacer market. USDA NASS counted 9.65 million milk cows in July 2026 and estimated calf crop at 32.5 million head, 2% lower than 2025 [1]. The decline in calf crop shows that the market cannot grow only from addition of animals. FMI research indicates that the USD 4.0 billion value in 2026 is therefore being driven by higher adoption of replacer within the calves already available, replacement of variable whole milk and increasing value of each prepared litre. Calf milk replacer gives farms a measured combination of protein, fat and solids and also allows saleable milk to remain outside calf feeding. Due to these operating benefits, farms with larger calf groups are likely to increase its use. However, premium formulas will gain demand only when higher energy, milk protein or functional ingredients also gives a visible return in growth and prepared feeding cost. As a result, 8.1% CAGR is expected to come from rising penetration, regular feeding and higher value formulas rather than growth in calf numbers alone.
Calf milk replacer demand expands at different rates across countries because calf population and farm structure are not moving in the same direction. Poland is projected to grow at 9.8% CAGR, while Germany is forecast to expand at 9.0% through 2036. Eurostat reported in January 2026 that European Union bovine livestock totaled 74.3 million head with young cattle under one year representing 21.4 million head [2]. This gives Eastern and Western European producers a substantial young-cattle group where feeding programs can increase product reach. Farm structural consolidation across leading dairy nations further concentrates calf rearing into specialized accounts where formula consistency, regular stock and feeding support become more important.
Key Takeaways of Calf Milk Replacer Market
- Calf cohorts create repeat demand when farms select defined liquid nutrition instead of depending on variable whole-milk supply.
- Based on form, dry powder is projected to account for 96.2% in 2026 owing to storage convenience and measured reconstitution.
- By ingredient type, all milk protein is estimated to hold 49.0% in 2026 due to early-life digestive suitability.
- Indirect sales are expected to lead with 44.9% share because available local stock reduces replenishment risk during daily feeding.
- Poland is projected at 9.8% CAGR and Germany at 9.0%, but their growth is connected with different herd and farm-structure factors.
- Notable companies include ADM, Cargill, Trouw Nutrition, FrieslandCampina, Land O’Lakes, DSM-Firmenich, Glanbia and Lesaffre.
Analyst Perspective
“I expect farms to reward the formulas that reduce mixing variation during routine feeding. Premium products will expand only when the prepared cost remains clear and the formula works with the labour already available on the farm.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Calf Milk Replacer Market segmented?
Calf milk replacer market is segmented by form, ingredient type, sales channel, and region.
Form covers dry powder and reconstituted liquid.
Ingredient type covers all milk protein, dried whey protein concentrate, dried skimmed milk, dried whey, dried whey product, casein, animal plasma, and sodium or calcium caseinate.
Sales channel covers indirect, animal feed stores, modern trade, direct, online retail, and veterinary clinics.
Region covers North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does dry powder account for notable form demand?
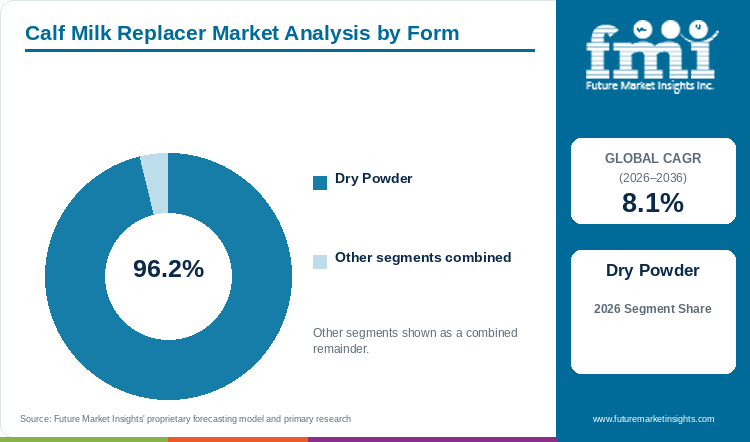
Based on form, dry powder is projected to account for 96.2% in 2026, owing to bagged storage, longer handling window and measured farm reconstitution.
Dry powder has facing very high adoption as one bag can be stored and mixed only when the feeding volume is required. This makes the form suitable for bucket feeding, group mixing and automatic calf feeders and is one of the main factors behind its 96.2% share in 2026. Apart from that, powder reduces the need of holding a ready liquid product and gives farms control over water and solids at each feeding. However, the benefit is available only when workers use correct powder weight, water volume and mixing temperature. Penn State Extension updated its newborn-calf guidance in October 2025 and stressed accurate preparation [3]. A change in concentration can change the amount of nutrients received by the calf even when the same product is being used. Due to storage advantage, easier transport and measured preparation, dry powder is expected to continue holding the majority demand, while reconstituted liquid will remain limited to situations where transport infrastructure and cold-chain handling are available.
- Dry powder is projected at 96.2% because storage, transport and measured mixing fit daily calf routines.
- The remaining share is limited for reconstituted liquid because transport and shelf handling are less flexible for many farms.
What supports all milk protein as a preferred ingredient type?
By ingredient type, all milk protein is estimated to hold 49.0% in 2026, supported by early-life digestive suitability and familiar dairy-protein specifications.
As noted by FMI, all milk protein is expected to hold 49.0% of ingredient type demand in 2026 as the digestive system of a young calf is better suited for milk-derived proteins than several plant and non-milk alternatives. This biological suitability along with familiar dairy ingredient specifications is increasing preference for all milk protein formulas during early feeding. Cargill lists all-milk-protein replacers with protein levels between 20% and 24% in its HerdFirst range [4]. The share does not mean farms will purchase these formulas at any cost. Buyers are comparing protein level, amino-acid contribution, fat, digestibility and cost per feeding before selecting the product. All milk protein will therefore retain strong demand where early-life digestion and dependable performance is more important than the lower price offered by substituted proteins.
- All milk protein is estimated to hold 49.0% of ingredient type demand in 2026, supported by early-life digestive suitability and familiar dairy-protein specifications.
- Dairy-origin protein specifications match early digestive capacity, supporting consistent nutrient uptake before calves transition to solid starter feed.
How does indirect sales meet farm replenishment needs?
In 2026, indirect sales are expected to lead with 44.9% share, enabled by local inventory, familiar dealer relationships and feeding support.
A calf feeding program requires powder every day and a delay in the next bag can disturb the complete feeding schedule. Owing to this requirement, indirect sales are expected to hold 44.9% share in 2026. Local dealers keep inventory close to the farm and also help buyers in selecting formulas, changing mixing rates and shifting calves from one feeding program to another. This gives the channel an advantage over direct and online sales where wider choice may be available but immediate replacement is not always possible. In June 2025, European Feed Manufacturers' Federation (FEFAC) documented that specialized agricultural feed distributors and cooperatives handle over 65% of compound dairy feed deliveries to regional farms [5]. Such activities show that product commercialization, logistics and technical discussion continue near livestock customers. Indirect sales are therefore expected to remain the leading channel where dealers are providing stock availability along with feeding support and not only selling the bags.
- Indirect sales are expected to lead with 44.9% share in 2026, enabled by local inventory, dealer relationships, and feeding support.
- Local dealer networks minimize replenishment risk and provide on-farm guidance for mixing rates and formula transitions.
What are the drivers, restraints, and opportunities in the Calf Milk Replacer Market?
In the calf milk replacer market, the key driver is standardized nutrition, the key restraint is preparation economics, and the key opportunity is functional powder that remains stable and simple to dose.
- Driver: Farms adopt replacer when defined nutrients, hygiene control and repeat feeding outweigh the value of whole milk.
- Restraint: Dairy-protein prices and inaccurate reconstitution can remove the cost or performance benefit expected by the farm.
- Opportunity: Functional ingredients can raise formula value when they remain stable in powder and practical during routine feeding.
Standard Nutrition Supports Repeat Feeding
Increasing requirement for the same solids and nutrient concentration at every feeding is one of the primary factors driving calf milk replacer adoption. A USDA ARS record updated in September 2026 described a 96-calf trial comparing two milk replacer programs [6]. Daily gain remained close even when protein, fat, powder volume and weaning schedules were different. This does not make all formulations equal, but indicates that calf performance is connected with the complete feeding program instead of one nutrient written on the label. Milk replacer gives farms a defined base for comparing growth, powder use, labour and weaning response across the dairy herd. As more workers handle feeding on larger farms, repeat preparation is expected to become more important. This in turn will increase demand for formulas that can deliver similar concentration through the routine feeding period.
Mixing Errors Weaken Product Economics
Incorrect preparation is one of the key factors restraining the performance and economics of calf milk replacer. Trouw Nutrition described a 32-calf study where part of lactose was exchanged with fat and feeding behaviour was followed for 84 days [7]. Calves changed intake according to energy density, which shows that a change in prepared concentration can also change feeding response. A scoop used without weighing, additional water or unsuitable mixing temperature can move the final feed away from the labelled formula. In such cases, even a low-priced bag can become costly when nutrient intake becomes variable or more powder is consumed. The market will therefore place higher value on easy mixing, clear instructions and on-farm training. These factors are expected to reduce preparation errors and protect the performance benefit for which the farm has purchased the formula.
Functional Powders Create Formulation Space
Functional powders are creating growth prospects for calf milk replacer manufacturers as ingredients can be added for a selected digestive, microbial or performance purpose. In November 2025, the FDA inventory listed pending and completed animal food ingredient consultations [8]. This provides ingredient companies a route for placing safety evidence behind a new animal food use. Selected fibres, microbial products, enzymes and specialty proteins can therefore enter calf formulations where the purpose and dose is clear. However, addition of an ingredient alone will not support adoption. It must remain uniform inside the powder, tolerate storage and dissolve without adding a separate farm process. Functional calf milk replacer is expected to witness higher demand when it gives additional value while using the same mixing and feeding routine already followed by the farm.
Which country CAGRs are profiled in the Calf Milk Replacer Market?
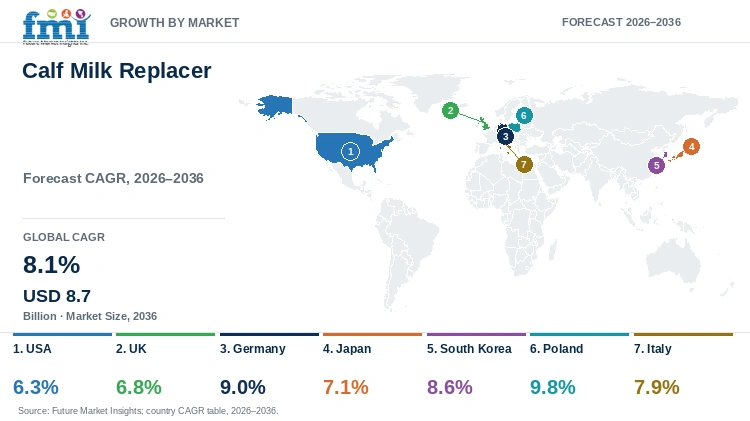
| Country | CAGR |
|---|---|
| USA | 6.3% |
| UK | 6.8% |
| Germany | 9.0% |
| Japan | 7.1% |
| South Korea | 8.6% |
| Poland | 9.8% |
| Italy | 7.9% |
How do country-level CAGRs compare in the calf milk replacer market?
Country-level growth is not only based on the size of cattle herd. Poland and Germany are expected to witness higher CAGRs, but the factors behind this growth are different. Poland has an increasing young-cattle group, while Germany has a large calf base moving into fewer and larger holdings. The USA and UK already have established dairy systems and the opportunity is mainly available by increasing replacer use within the existing calf population. Japan and South Korea have smaller or consolidating dairy structures, due to which companies need to capture higher value from each eligible calf. Therefore, a higher CAGR can be generated by lower present penetration, increasing professional feeding, wider dealer reach and adoption of premium formulas. It should not be considered as a direct indication of total cattle growth.
- USA: A large calf crop sustains repeat liquid-feeding decisions even when total calf numbers decline.
- UK: A stable dairy herd maintains demand, while labour pressure increases the value of repeatable preparation.
- Germany: A large calf base inside a consolidating farm structure supports standardized account programs.
- Japan: Fewer dairy farms and larger herds increase the need for focused distributor coverage.
- South Korea: A compact dairy herd puts more weight on value captured per eligible calf.
- Poland: Growth in calves below one year supports calf-specific demand even with a smaller total cattle herd.
- Italy: Flat livestock output and higher farm-input prices keep buyers focused on feeding efficiency.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- USA calf milk replacer sales are forecast to expand at 6.3% CAGR through 2036, owing to a large calf feeding base and increasing need for one feeding standard across farms. USDA Economic Research Service reported in February 2026 that United States commercial dairy herds maintained 9.35 million milk cows while dairy replacement heifer inventory totaled 4.05 million head [9]. The stable replacement herd makes evident that the projected growth will not be generated by animal numbers alone. More feeding occasions are expected to shift towards replacer where saleable milk has a better commercial use, pooled milk creates hygiene concern or several workers are feeding calves. As a result, growth will be supported by higher penetration within the existing calf population. However, changes in whole-milk availability and the cost of replacer solids can affect the buying decision and will remain a key restraint in the country.
- The UK calf milk replacer market is anticipated to advance at 6.8% CAGR through 2036, supported by a stable dairy herd and rising requirement for easier feeding under limited labour. DEFRA reported that dairy herd increased 0.7% to 1.8 million animals in 2025, while total cattle and calves declined 1.3% to 9.3 million [10]. This provides a steady dairy base but does not indicate a broad increase in livestock. Farms with fewer workers are expected to prefer powders that dissolve properly and can be prepared in the same manner by different people. This will support demand for measured calf nutrition and reliable local stock. However, farms will continue comparing replacer with whole milk, especially when milk availability and price changes. Suppliers that reduce mixing work and maintain regular delivery are likely to gain higher demand in the UK.
- German calf milk replacer demand is forecast to rise at 9.0% CAGR through 2036 due to a sizeable calf base and continued consolidation of dairy farms. Destatis counted 2.19 million calves aged eight months or below in May 2026 and 3.59 million dairy cows, while dairy-cow holdings declined from 47,157 in November 2025 to 46,231 in May 2026 [11]. Fewer holdings means that more product volume can move through larger farm accounts. These farms require formula consistency, traceability, regular supply and technical support as one buying decision covers a higher number of calves. According to FMI, the growing CAGR is linked with deeper adoption inside professional calf programs and not with continuous increase in cattle. Companies having dependable distribution and feeding support are expected to gain an advantage in Germany.
- Calf milk replacer adoption in Japan is estimated to expand at 7.1% CAGR through 2036 as dairy production is moving through fewer farms having larger herds. ALIC reported 11,300 dairy farms in February 2025, down 5.0%, while average herd size increased 3.7% to 114.4 head [12]. This structural change gives distributors fewer accounts to cover, but each account can require higher feeding volume. Defined powder can help such farms in handling larger calf groups with a similar preparation routine. At the same time, larger accounts will compare cost and performance more closely because the purchase is multiplied across more animals. Reliable delivery, measured preparation and technical support are therefore expected to drive adoption, while the market route will remain concentrated around key dairy accounts rather than a wide retail network.
- South Korea is projected to register 8.6% CAGR through 2036 despite a smaller dairy cattle base. The Ministry of Data and Statistics counted 365 thousand dairy cattle in the second quarter of 2026, down 1.6% from one year earlier [13]. Therefore, growth from additional animals is limited and companies will need to increase milk replacer penetration among the calves already available. Specialized formulas, dependable inventory and higher value nutrition can increase the revenue captured from each eligible calf. The projected CAGR is thus connected with premiumization and wider use inside a compact dairy sector. Products that provide a visible feeding purpose without making preparation difficult are expected to find higher opportunity in South Korea.
- Poland is estimated to post 9.8% CAGR through 2036, supported by an increasing population of calves below one year. Statistics Poland counted 6.143 million cattle in December 2025, down 0.8% from one year earlier, whereas calves below one year increased 2.8% to 1.901 million head [14]. The increase in young cattle gives a more direct demand signal for milk replacer than the decline in total herd. Professional calf nutrition can therefore expand even when older cattle categories are decreasing. Wider dealer reach and higher adoption inside calf programs are expected to support revenue growth. However, prepared feeding cost will remain important as changes in milk and feed prices can move farms between whole milk and commercial replacer.
- Calf milk replacer sales in Italy are projected to rise at 7.9% CAGR through 2036 as farms are placing higher focus on the return generated from each feed input. Istat reported that agricultural output volume increased 0.3% in 2025, livestock output remained unchanged and prices for goods and services used by farms increased 1.0% [15]. Flat livestock output along with increasing input prices makes feeding efficiency more important than herd growth. Milk replacer can gain adoption where measured powder protects saleable milk and reduces variation between feedings. However, premium proteins and functional ingredients will need a clear purpose to justify their additional cost. Stable sourcing, simple preparation and visible cost per feeding are expected to support demand in Italy.
Who are the notable companies in the Calf Milk Replacer Market?
ADM, Cargill, Trouw Nutrition, FrieslandCampina, Land O’Lakes, DSM-Firmenich, Glanbia, and Lesaffre are notable companies covered in the calf milk replacer market.
The calf milk replacer market is moderately fragmented as finished replacer companies, dairy-protein suppliers, functional-ingredient developers and regional feed distributors are operating at different stages of the value chain. ADM, Cargill, Trouw Nutrition, FrieslandCampina and Land O’Lakes have direct relevance in finished formulas or calf feeding programs. DSM-Firmenich, Glanbia and Lesaffre support the market through dairy ingredients, functional nutrition and fermentation capabilities. An FMI analyst notes that finished replacer suppliers, dairy-protein companies and feed distributors are operating across different stages of the value chain, and no single company controls the total market demand. Competition is largely taking place through powder solubility, clear mixing instructions, batch consistency, local stock and cost per prepared litre. Companies that combine the formula with dependable feeding support are expected to retain stronger farm accounts.
- Finished replacer and calf-program providers: ADM, Cargill, Trouw Nutrition, FrieslandCampina, and Land O’Lakes.
- Functional and dairy-ingredient platforms: DSM-Firmenich, Glanbia, and Lesaffre.
- Route-to-market advantage: local feed coverage, account support, bag-to-bag consistency, and reliable powder supply.
Competitive Benchmarking: Calf Milk Replacer Market
| Company | Replacer relevance | Ingredient capability | Feed route | Reach |
|---|---|---|---|---|
| ADM | High | Medium | High | High |
| Cargill | High | High | High | High |
| Trouw Nutrition | High | High | High | High |
| FrieslandCampina | High | High | Medium | High |
| Land O’Lakes | High | Medium | High | Medium |
| DSM-Firmenich | Medium | High | High | High |
| Glanbia | Low | High | Low | High |
| Lesaffre | Low | High | Medium | High |
Scoring basis: High indicates broad documented capability, Medium indicates credible but narrower evidence, and Low indicates limited direct finished-product evidence. The ratings describe public capability and do not rank product quality or market share.
Key Developments in the Calf Milk Replacer Market
- In November 2025, Glanbia approved an investment with its joint-venture partners at the Southwest Cheese plant in New Mexico to add 10 million pounds of whey protein isolate capacity, with production expected to come on stream in 2027. The investment expands upstream dairy-protein capability rather than dedicated calf replacer output [16].
- In September 2025, ADM introduced Digest Carb for Ruminants at SPACE in Rennes, France, a feed additive formulated to support rumen fermentation and milk performance in dairy cows [17].
- In July 2025, Lesaffre made a strategic investment in CanBiocin, a Canadian probiotic developer, to expand its companion animal and livestock probiotic portfolio through Phileo by Lesaffre [18].
Key Players in the Calf Milk Replacer Market
Finished-Replacer and Calf-Program Providers
- ADM
- Cargill
- Trouw Nutrition
- FrieslandCampina
- Land O’Lakes
Functional and Dairy-Ingredient Platforms
- DSM-Firmenich
- Glanbia
- Lesaffre
Calf Milk Replacer Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; Ingredient Type; Sales Channel; Region |
| Quantitative units | USD billion |
| Market definition | Revenue from commercially sold bovine calf milk replacer. Whole milk, colostrum, starter feed, electrolytes, separately sold raw ingredients and other-species replacers are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA, UK, Germany, Japan, South Korea, Poland, Italy, and additional countries |
| Key companies | ADM; Cargill; Trouw Nutrition; FrieslandCampina; Land O’Lakes; DSM-Firmenich; Glanbia; Lesaffre |
| Forecast period | 2026 to 2036 |
| Approach | Product revenue, calf-feeding demand, segment structure, company activity and country operating conditions. |
In the FMI report, the market coverage focuses on commercial bovine calf milk replacers while excluding liquid whole milk and other-species milk replacers.
Calf Milk Replacer Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | Inputs from manufacturers, distributors, service providers, procurement teams, farm users and subject-matter experts were used to examine buying decisions, pricing, formula approval and technical support. |
| Desk Research | Government statistics, regulatory publications, company filings, official product information, technical literature and corporate announcements were reviewed for date, geography and market relevance. |
| Market Sizing and Forecasting | The baseline value was combined with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country demand. |
| Data Validation | Estimates were checked against public data, company activity, trade patterns and primary interviews. Overlapping categories and unsupported activity were excluded. |
Calf Milk Replacer Market by Segments
Calf Milk Replacer Market segmented by Form:
- Dry Powder
- Reconstituted Liquid
Calf Milk Replacer Market segmented by Ingredient Type:
- All Milk Protein
- Dried Whey Protein Concentrate
- Dried Skimmed Milk
- Dried Whey
- Dried Whey Product
- Casein
- Animal Plasma
- Sodium or Calcium Caseinate
Calf Milk Replacer Market segmented by Sales Channel:
- Indirect
- Animal Feed Stores
- Modern Trade
- Direct
- Online Retail
- Veterinary Clinics
Calf Milk Replacer Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, July 24). United States Cattle Inventory Up Slightly.
- [2] Eurostat. (2026, January 16). Cattle population in the European Union.
- [3] Penn State Extension. (2025, October 6). Feeding the Newborn Dairy Calf.
- [4] Cargill. (2026). HerdFirst milk replacers and calf feeds.
- [5] European Feed Manufacturers' Federation. (2025, June 5). Compound Feed Production and Distribution Report 2024-2025.
- [6] USDA Agricultural Research Service. (2026, September 9). Impact of milk replacer feeding program on growth and efficiency of Angus x Holstein calves.
- [7] Trouw Nutrition. (2026). Dairy calves regulate milk replacer intake on the basis of energy density.
- [8] U.S. Food and Drug Administration. (2025, November 17). Current Animal Food Ingredient Consultation Inventory.
- [9] U.S. Department of Agriculture, Economic Research Service. (2026, February 12). Dairy Data and Cattle Inventory Overview.
- [10] Department for Environment, Food & Rural Affairs. (2026, October 2). Livestock populations in the United Kingdom at 1 June 2025.
- [11] German Federal Statistical Office. (2026, June 26). Holdings with cattle and stock of cattle.
- [12] Agriculture & Livestock Industries Corporation. (2025, September). Overview of 2025 Livestock Statistics.
- [13] Ministry of Data and Statistics, Republic of Korea. (2026, July 24). Livestock Statistics in the Second Quarter of 2026.
- [14] Statistics Poland. (2026, January 28). Cattle population as of December 2025.
- [15] Italian National Institute of Statistics. (2026, June 12). Economic accounts for agriculture: Year 2025.
- [16] Glanbia plc. (2025, November 19). Capital Markets Day 2025 transcript.
- [17] ADM. (2025, September 16). ADM Unveils New Feed Solution for Optimized Dairy Performance.
- [18] Lesaffre. (2025, July 8). Lesaffre and CanBiocin expand animal-care capabilities.
- [19] Trouw Nutrition. (2026). Sprayfo calf milk replacers.
- [20] Royal FrieslandCampina N.V. (2026, February 18). 2025 Results of Royal FrieslandCampina N.V.
- [21] Cargill. (2025, July 29). Cargill to acquire Mig-Plus.
- [22] DSM-Firmenich. (2025, September 12). DSM-Firmenich joins the Milk Sustainability Center.
- [23] Land O’Lakes, Inc. (2026, July 9). Investment to expand high-value dairy protein production at Tulare.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is the calf milk replacer market worth in 2026?
- What value is projected by 2036?
- Which form holds notable market share?
- Which ingredient type holds notable market share?
- Which countries have notable growth outlook?
- Which companies are active in the market?
Frequently Asked Questions
How big is the calf milk replacer market in 2026?
The calf milk replacer market is valued at USD 4.0 billion in 2026 and is projected to reach USD 8.7 billion by 2036. Growth is tied to repeat pre-weaning nutrition needs and commercial dairy operations that separate calf feeding from saleable whole milk.
What is the CAGR of the calf milk replacer market from 2026 to 2036?
The calf milk replacer market is projected to grow at a CAGR of 8.1% between 2026 and 2036. Expansion is supported by repeat calf cohorts and standardized feeding programs used in commercial dairy systems.
Which form leads the calf milk replacer market?
The dry powder segment is expected to hold 96.2% of the calf milk replacer market in 2026, driven by storage efficiency and controlled on-farm reconstitution. Farms can transport concentrated product through existing feed channels without shipping water inside the finished formulation.
Which ingredient type holds a major share of the calf milk replacer market?
The all milk protein segment is expected to hold 49.0% of the calf milk replacer market in 2026, attributable to early-life digestibility and familiar dairy protein fractions. Formulators must carefully control protein cost and solubility without weakening feeding specifications.
Which countries are projected to record the highest growth in the calf milk replacer market?
Poland is projected to grow at 9.8% CAGR, followed by Germany at 9.0% and South Korea at 8.6% through 2036. Their growth paths depend on dairy-sector specialization and different levels of technical distribution intensity.
Which companies are active in the calf milk replacer market?
Key companies operating in the market include Archer Daniels Midland Company, Nutreco, Cargill, Denkavit, Land O'Lakes Inc., dsm-firmenich, Lesaffre, and Glanbia plc. Their roles span finished calf nutrition, ruminant feed systems, functional inputs and dairy proteins.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Dry Powder
- Reconstituted Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Ingredient Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient Type, 2026 to 2036
- All Milk Protein
- Dried Whey Protein Concentrate
- Dried Skimmed Milk
- Dried Whey
- Dried Whey Product
- Casein
- Animal Plasma
- Sodium or Calcium Caseinate
- Y-o-Y Growth Trend Analysis By Ingredient Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Indirect
- Animal Feed Stores
- Modern Trade
- Direct
- Online Retail
- Veterinary Clinics
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By Ingredient Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Ingredient Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Ingredient Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Ingredient Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ADM
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill
- Trouw Nutrition
- FrieslandCampina
- Land O’Lakes
- DSM-Firmenich
- Glanbia
- Lesaffre
- ADM
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


