
- Market Size (2026)
- USD 109.3 Bn
- Forecast (2036)
- USD 158.7 Bn
- CAGR (2026 to 2036)
- 3.8%
How big is Cider and Perry Market in 2026?
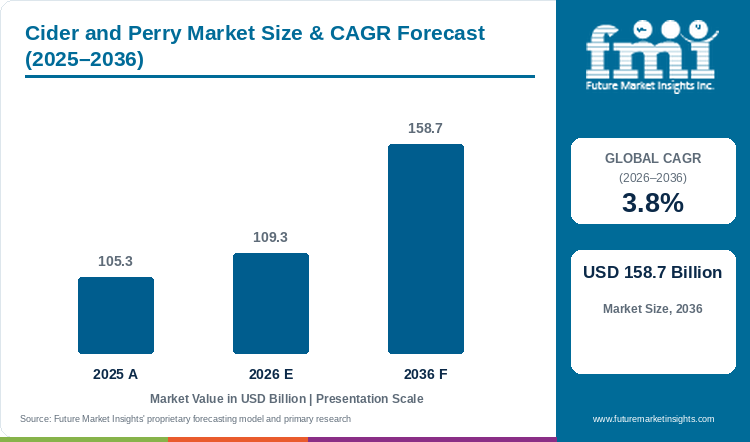
Sales in the cider and perry market are projected to grow at 3.8% CAGR, with the market size rising from USD 105.3 billion in 2025 to USD 109.3 billion in 2026 and reaching USD 158.7 billion by 2036.
The cider and perry market is estimated at USD 109.3 billion in 2026 against USD 105.3 billion in 2025, and at 3.8% CAGR it is likely to reach USD 158.7 billion by 2036. This is not a market where volume alone is expected to do the work. Much of the USD 49.4 billion addition will come when producers take the same apple base into premium bottles, cans, draught and alcohol-free products without making the range difficult for retailers to sell. Apple cider holding 72.0% share makes this possible because the shopper already understands the taste, The same dependence leaves producers exposed when crop quality or concentrate cost changes.
USDA forecast the 2025 U.S. apple crop 6% above 2024 and Washington at a record 8 billion pounds, which can improve fruit availability for pressing, but a larger harvest does not by itself protect fermentation quality or the price finally paid for usable cider fruit. According to Future Market Insights, growth is therefore expected to remain value-led, while tax, pack cost and weaker alcohol volumes can keep the increase steady rather than sharp.
Key Market Trends & Insights
- By product type: Apple cider is projected to account for 72.0% in 2026, supported by established consumer familiarity and wider brand distribution.
- By packaging format: Cans and glass bottles remain the principal retail formats as they support multipacks, premium cues, and e-commerce handling.
- By alcohol content: Alcoholic cider remains the revenue base, while alcohol-free and lower-ABV variants attract moderation-led occasions.
- By distribution channel: Off-trade sales anchor household purchase, whereas draught remains important for premium on-trade value.
- By price positioning: Mainstream cider carries scale, while crafted and vintage products improve value per litre.
Category movement also reflects wider innovation across fruit-flavoured cider and moderation-focused formats.
Regional Highlights
- The UK remains the most mature cider economy, with a 2025 industry report placing on-trade cider value at USD-equivalent scale and documenting 342 million pints sold across the preceding year.
- The USA, Canada, Japan, Australia, Germany, France, and South Korea expand through craft retail, imported premium brands, and fruit-led alternatives to beer.
Market Size & Forecast
Table 1: Market Size and Forecast for the Cider and Perry Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 105.3 billion |
| Estimated Market Size in 2026 | USD 109.3 billion |
| Projected Market Size by 2036 | USD 158.7 billion |
| CAGR, 2026 to 2036 | 3.8% |
| Added Revenue, 2026 to 2036 | USD 49.4 billion |
Fruit supply and affordability are moving in opposite directions in several markets. Better orchard output can lower the immediate pressure on pressing schedules, yet it cannot settle glass, aluminium, duty and retailer margin at the same time. The World Health Organization reported that alcohol tax design and tax levels still vary widely between countries, which means a pack that remains affordable in one market can move out of the regular purchase range in another. FMI data suggests that producers will respond through smaller packs, lower-ABV products and a wider price ladder, but these changes will support revenue only when aroma and body are retained and the cheaper entry point does not weaken the main brand.
Fruit Supply and Revenue Intensity Sizing
Table 2: Fruit Supply and Revenue Intensity Indicators for the Cider and Perry Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 105.3 | 109.3 | 158.7 |
| Apple-led revenue (USD billion, 72.0% proxy) | 75.8 | 78.7 | 114.3 |
| Added revenue versus 2026 (USD billion) | - | - | 49.4 |
| Revenue index (2026=100) | 96.3 | 100.0 | 145.2 |
Channel and Consumption Structure
Retail multipacks keep cider within planned household purchase, whereas draught gives the category visibility and a higher value per serve when pubs have enough tap space. This difference is important because one format cannot cover both occasions. A producer may have secure fruit and enough fermentation capacity, but demand can still remain limited if the pack misses the cold shelf or the draught line is replaced by beer. Cloudy, vintage, flavoured and alcohol-free products are therefore being used to open a new occasion around the core apple taste, not to remove the product buyers already recognise.
Table 3: Channel and Product Indicators for the Cider and Perry Market (percentages and counts), 2025 reporting
| Indicator | Value | Commercial Reading |
|---|---|---|
| Apple share in global product demand | 72.0% | Core scale platform |
| UK on-trade draught share by volume | 77% | Tap visibility remains decisive |
| UK packaged cider share sold through fridges | 28% | Cold-box assortment matters |
| US apple crop change forecast | +6% | Processing supply improves |
Table 4: Market Revenue Conversion Indicators (USD billion), 2026
| Metric | Value | Basis |
|---|---|---|
| Global market value | USD 109.3 billion | FMI report value |
| Apple-led category value | USD 78.7 billion | 72.0% share proxy |
| Non-apple balance | USD 30.6 billion | Calculated remainder |
| Absolute opportunity to 2036 | USD 49.4 billion | Ten-year growth potential |
Moderation-led innovation also connects cider with expanding non alcoholic beverages through taste retention and occasion expansion.
Analyst Perspective
"Cider makers cannot treat fruit, pack and channel as separate decisions. The companies that secure useful apple supply and can shift the same liquid across draught, can, bottle and moderation-led formats will be better placed when harvest quality, tax or retailer price points move."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Cider and Perry Market segmented?
The cider and perry market is segmented by product type, packaging format, alcohol content, distribution channel, and price positioning.
By product type: Apple cider, perry, fruit-flavoured cider, and other blends.
By packaging format: Glass bottles, cans, draught or kegs, PET bottles, and others.
By alcohol content: Standard alcoholic, lower-ABV, and alcohol-free.
By distribution channel: Off-trade, on-trade, and online retail.
By price positioning: Mainstream, premium, craft, and vintage or specialty.
Why does Apple Cider account for the largest product share?
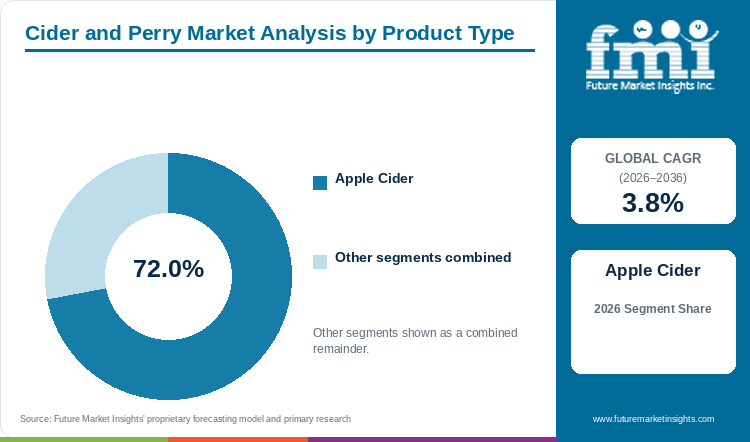
Apple cider represents 72.0% of product demand in 2026, linking established taste recognition with broad international distribution.
Table 5: Product Type Share for the Cider and Perry Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Apple Cider | 72.0% |
| Other Segments Combined | 28.0%* |
| Total | 100.0% |
Table 6: Product Type Leadership and Market Growth, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR | 3.8% |
| Leading Segment | Apple Cider |
| Leading Share | 72.0% |
Apple cider holds 72.0% share because it gives producers one understood flavour base that can move from mainstream packs to cloudy, vintage and alcohol-free products. The share is large, but it does not mean all apple cider sells for the same reason. Mainstream variants depend on price and availability, whereas small-batch and vintage products need a visible orchard or process story before the buyer pays more. This wide use of the same fruit base is also why cider can compete for occasions commonly served by alcoholic beverages.
- Apple cider is projected to hold 72.0% share in 2026, underpinned by established shelf presence and recognisable fruit provenance.
- USDA projected a 6% increase in the 2025 United States apple crop, improving processing-fruit availability.
What supports Cans and Glass Bottles across packaging demand?
Packaged formats remain central to retail cider demand as multipacks widen home consumption and simplify inventory handling.
Cans are likely to gain where freight, rapid chilling and multipack handling matter, while glass will remain useful when the producer is asking the buyer to read the cider as premium or vintage. The choice is not only appearance. A cheaper pack may improve distribution but can reduce the price cue, whereas heavier glass can defend value and still lose margin through transport and breakage. Producers will therefore use both formats, but not for the same product or channel job.
- Packaging mix is shaped by retailer shelf strategy and brand positioning rather than one universal format.
How are Alcohol-Free and Lower-ABV Ciders widening the category?
Moderation-led cider extends drinking occasions without removing the fruit-led taste profile that defines category recognition.
Alcohol-free cider widens the time and place in which cider can be purchased, but taking alcohol out can also remove body and aroma, which is the part that makes the product recognisable. Heineken UK introduced Inch’s 0.0 and Inch’s Cloudy in March 2025 following a two-year development programme, suggesting that moderation demand alone is not enough and the liquid has to survive the technical change first. Lower-ABV and 0.0 products can therefore add occasions, while weak sensory performance can stop repeat purchase after the first trial.
- Alcohol-free expansion raises technical requirements for flavour retention and microbiological control.
Why does Off-Trade remain important within distribution?
Off-trade channels protect category reach through multipacks, chilled singles, seasonal displays, and online grocery replenishment.
Off-trade remains important because a national grocery listing can move multipacks, chilled singles and seasonal stock at a scale that independent venue distribution cannot quickly match. However, retail promotion can train shoppers to wait for a deal and put pressure on value per litre. Draught partly offsets this by supporting trial and a higher value per serve, although a supplier must first win limited pub tap space. The better route is not choosing one channel, but giving each pack a clear reason to sit there.
- Channel strategy must balance retail volume with on-trade discovery and value per serve.
What keeps Premium and Crafted Cider commercially relevant?
Premium and crafted cider support higher value per litre through provenance, vintage cues, and differentiated fermentation stories.
Premium cider can gain value even when the buyer drinks less, provided the product shows why it is different. Westons made Henry Westons 1880 Vintage a permanent addition in February 2025, placing a heritage recipe into a repeat retail role rather than leaving it as a short seasonal release. This type of move can lift value per litre, but premium pricing will weaken if provenance is only written on the label and is not carried through fruit choice, fermentation and pack design.
- Premiumisation rewards verifiable provenance, disciplined fermentation, and channel-specific pack design.
Format economics link category strategy to beverage packaging formats as cans and bottles carry different cost, recycling, and premium cues.
What are the drivers, restraints, and opportunities in the Cider and Perry Market?
Premium fruit provenance and moderation-led formats create value, while harvest volatility and tax-linked affordability limit volume expansion.
- Driver: Premium apple provenance, craft positioning, and broader fruit flavour choice raise value per litre.
- Restraint: Orchard yields, concentrate prices, glass and aluminium costs, and alcohol duties compress supplier and retailer margins.
- Opportunity: Alcohol-free, lower-ABV, canned, and vintage products recruit new occasions across retail and hospitality.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Growth will come faster where fruit provenance is made useful to the channel rather than added as a general claim. Cloudy and vintage cider can justify a step-up price in specialist retail or hospitality, while the same product may move slowly in a price-led multipack fixture. Better apple availability helps a producer plan pressing and contract volume, but usable sugar, acidity and storage condition still decide what can be fermented consistently. As per FMI, diversified grower contracts and flexible tanks are likely to matter more than simply buying more fruit, because both the core blend and the limited harvest release have to be protected at the same time.
Risk Assessment of the Cider and Perry Market: Supply and Affordability Friction
A weak harvest can lower fermentable solids, increase concentrate use and make one season taste different from the next. The risk then moves beyond fruit cost because duty and packaging can widen the shelf-price gap against soft drinks at the same time. Producers will need an entry pack that remains reachable, but repeated downsizing or discounting can damage the brand they are trying to protect. Clearer grower contracts, storage planning and the ability to switch pack format before a seasonal peak are likely to reduce this exposure, although none of these removes weather or tax risk completely.
Commercial Opportunity Analysis: Moderation, Craft, and Pack Differentiation
Product development is moving away from adding flavour for the sake of a longer range. Heineken UK introduced Inch’s Reserve in March 2026 as a 7.4% ABV, 500ml premium bottle, with 98.6% of apples used for Inch’s ciders grown within 40 miles of the Ledbury mill. The local fruit claim, higher strength and single-bottle format point to a slower premium occasion rather than a multipack volume play. Thatchers took another route in November 2025 by adding Redwood, Grenadier and Tremletts to its small-batch Cider Barn range, using apple variety and process to create difference. Both moves can defend price, but only while the range remains easy to understand and does not take shelf space from products with a faster rate of sale.
Cider and Perry Market by Country (2026 to 2036)
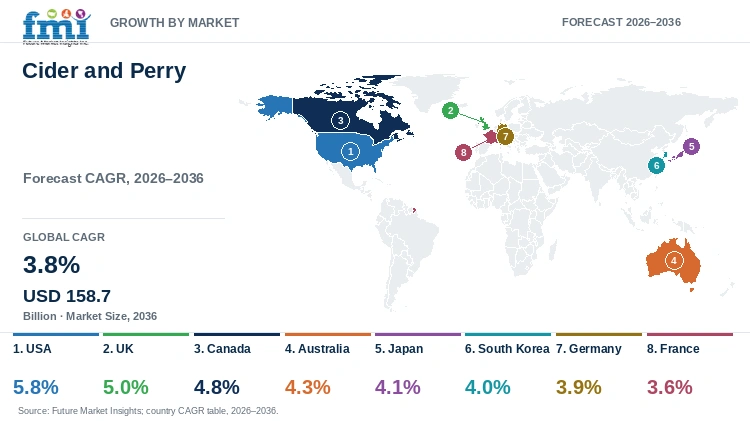
The USA carries the fastest comparator outlook at 5.8% CAGR, while France at 3.6% reflects a market where cider is already tied to established regional use. The difference is not simply a larger appetite in one country. Newer markets can grow from a smaller craft, import or premium base, whereas mature markets must earn more from products that are already familiar. As per the analysis from FMI, orchard access will influence cost, but route to market, alcohol rules and the position of cider beside beer or wine will decide how much of that supply becomes sale.
Table 7: Country Growth Outlook and Primary Growth Levers for the Cider and Perry Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.8% | Craft retail, orchard supply, and alcohol-free innovation |
| UK | 5.0% | Large on-trade base and draught premiumisation |
| Canada | 4.8% | Provincial retail expansion and local orchard branding |
| Australia | 4.3% | Craft beverage venues and canned formats |
| Japan | 4.1% | Imported premium cider and fruit-led moderation |
| South Korea | 4.0% | Urban premium retail and western beverage trial |
| Germany | 3.9% | Regional apfelwein heritage and organic positioning |
| France | 3.6% | Protected regional styles and culinary premiumisation |
Source: Future Market Insights analysis; published country comparator used where available and remaining outlook categories presented directionally.
USA Cider and Perry Market Outlook (2026 to 2036)
The USA is projected to rise at 5.8% CAGR because cider still has room to move beyond tasting rooms into wider craft retail, cans and alcohol-free products. Local orchard identity helps trial, yet the market is broken by state rules and distributor coverage, so national scale can cost more than the size of demand first suggests. A larger U.S. apple crop improves the raw material position, but fresh-market pricing and the distance between orchard, cidery and distributor can still hold back margin. Regional brands may grow faster by owning a few states properly before spending for a broad listing.
UK Cider and Perry Market Outlook (2026 to 2036)
The UK outlook at 5.0% CAGR comes from a much more developed cider habit, with draught visibility and pub purchase giving the market a structure not seen in every country. This maturity can support premium taps and alcohol-free extensions, but it also means the product competes for a fixed line in venues already under cost pressure. Duty movement can quickly alter the price of one strength or pack against another. Growth is therefore likely to come from better value per serve and a tighter range, rather than expecting existing drinkers to add much more volume.
Canada Cider and Perry Market Outlook (2026 to 2036)
Canada is forecast at 4.8% CAGR, but a producer does not enter one national retail system. Provincial listings, deposits and distribution conditions make expansion a province-by-province exercise, which can slow a brand that is selling well at the cidery. Local orchards give Canadian cider a credible point of difference, and farm visits can build direct recognition before retail scale. Cans and seasonal releases reduce some freight and stock risk, while winter logistics and a short harvest window keep storage planning central to margin.
Australia Cider and Perry Market Outlook (2026 to 2036)
Australia is estimated to expand at 4.3% CAGR, helped by farm-gate trial and venues that already know how to sell a premium fermented drink. The challenge is that cider fruit competes with the fresh apple market, while production regions and large cities are separated by costly freight. A compact range in cans can travel with less weight and reduce slow stock, but a producer still needs contract fruit if a good fresh-market year pulls apples away from processing. Wine knowledge can help fermentation and hospitality placement, although it does not guarantee supermarket scale.
Japan Cider and Perry Market Outlook (2026 to 2036)
Japan is projected at 4.1% CAGR and will remain more of a precise single-serve market than a large multipack market. Limited shelf space means the bottle has to explain itself quickly, and imported cider must justify freight and price beside beer, wine and local fruit drinks. Smaller packs, restrained sweetness and a clear food-pairing position can improve trial in department stores and hospitality. Seasonal orchard stories may also work, but only when the flavour stays consistent enough for repeat purchase after the novelty period ends.
South Korea Cider and Perry Market Outlook (2026 to 2036)
South Korea is predicted to advance at 4.0% CAGR, largely from urban premium retail and hospitality where a fruit-led drink can be tried without a large pack commitment. The category still risks being read as a sweet ready-to-drink product, which can push it into the wrong shelf and price comparison. Trial-size cans and food pairing can give cider a clearer role beside craft beer. Import cost and low category familiarity will remain the main hurdle, so distributor education may matter as much as consumer advertising in the early stage.
Germany Cider and Perry Market Outlook (2026 to 2036)
Germany is estimated at 3.9% CAGR, with apfelwein giving apple fermentation a known regional place, especially in Hesse. That heritage is useful but it can also make international sweet or highly carbonated cider look like a different drink altogether. Producers need to state sweetness, carbonation and apple origin clearly rather than rely on the word cider alone. Organic fruit and modern cans can bring younger trial, while products that ignore regional taste expectations may remain limited to imported beverage shelves.
France Cider and Perry Market Outlook (2026 to 2036)
France is forecast at 3.6% CAGR, the slowest comparator in the table, because cider already has a recognised place around Normandy, Brittany and food use. The opportunity is not to standardise these regional habits into one national taste. Brut and doux ladders, origin and premium glass can raise value through restaurants and tourism, while mature household purchase limits how quickly volume can change. Expansion outside the traditional regions is possible, but the product will need a modern occasion without losing the regional cues that make French cider credible.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Competitive portfolios overlap with commercial brewed beer through shared distributors, cold-box space, and on-trade taps.
Who are the notable companies in the Cider and Perry Market?
Heineken N.V., Asahi Group Holdings, C&C Group plc, Thatchers Cider, Westons Cider, Carlsberg Group, Molson Coors Beverage Company, and Kopparbergs Brewery are significant market participants.
Competition is divided between groups that can place a cider through existing beverage distribution and specialists that can show closer orchard and fermentation control. Scale helps win listings, but a wide portfolio can also leave cider behind larger beer brands when marketing is allocated. Independent producers can react faster with vintage or single-variety releases, yet they remain more exposed to one poor harvest and limited distribution. FMI research indicates that retailers will look beyond the number of flavours and ask whether the range has a clear price ladder, dependable seasonal supply and enough rate of sale to keep the shelf or tap.
- Global Beverage Platforms: Heineken, Asahi Group Holdings, Carlsberg Group, and Molson Coors combine cider brands with extensive distribution.
- UK and Irish Cider Specialists: C&C Group, Thatchers Cider, and Westons Cider retain strong orchard, heritage, and hospitality positions.
- Fruit-Cider Specialists: Kopparbergs Brewery uses flavoured cider recognition across international retail channels.
Competitive Benchmarking: Cider and Perry Market
Table 8: Competitive Benchmarking for the Cider and Perry Market (qualitative capability ratings), 2026
| Company | Core Cider Breadth | Format Innovation | Channel Access | Geographic Reach |
|---|---|---|---|---|
| Heineken | High | High | High | High |
| Asahi Group Holdings | High | Medium | High | High |
| C&C Group plc | High | Medium | High | Medium |
| Thatchers Cider | High | High | Medium | Medium |
| Westons Cider | High | High | Medium | Medium |
| Carlsberg Group | Medium | Medium | High | High |
| Molson Coors | Medium | Medium | High | High |
| Kopparbergs Brewery | Medium | High | High | High |
The ratings compare the breadth visible across products, formats, channels and countries. High indicates repeated evidence across more than one part of the business, while Medium indicates a narrower position. The table does not compare profit or company value.
Key Developments in the Cider and Perry Market
- In March 2026, Heineken UK launched Inch's Reserve at 7.4% ABV in 500ml bottles, with 98.6% of apples across the Inch's range sourced within 40 miles of the Ledbury mill in Herefordshire.
- In November 2025, Thatchers Cider launched Redwood, Grenadier, and Tremletts within its small-batch Cider Barn range.
- In March 2025, Heineken UK introduced Inch’s 0.0 and Inch’s Cloudy after a two-year development programme.
- In February 2025, Westons Cider launched Henry Westons 1880 Vintage as a permanent range addition.
Key Players in the Cider and Perry Market
Global Beverage Platforms
- Heineken N.V.
- Asahi Group Holdings
- Carlsberg Group
- Molson Coors Beverage Company
Specialist Cider Producers
- C&C Group plc
- Thatchers Cider
- Westons Cider
- Kopparbergs Brewery
Premium fruit fermented products also compete with sparkling wine where origin, vintage, and food pairing influence value.
Cider and Perry Market - Report Scope
Table 9: Report Scope for the Cider and Perry Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Packaging Format; Alcohol Content; Distribution Channel; Price Positioning |
| Quantitative Units | USD Billion |
| Market Definition | Supplier revenue from cider and perry products sold through retail and hospitality channels. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Canada, Australia, Japan, South Korea, Germany, France, and additional countries |
| Key Companies Covered | Heineken, Asahi Group Holdings, C&C Group, Thatchers Cider, Westons Cider, Carlsberg Group, Molson Coors, Kopparbergs Brewery |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Cider and Perry Market - Research Methodology
Table 10: Research Methodology for the Cider and Perry Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with producers, fruit suppliers, distributors, retailers, hospitality buyers, packaging suppliers, and industry specialists validate category trends and purchase criteria. |
| Secondary Research | Company reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data were reviewed. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess supplier revenue, channel demand, price movement, and product adoption over 2026 to 2036. |
| Data Triangulation and Validation | Findings are checked against crop conditions, alcohol regulation, category sales indicators, company activity, and historical trends to avoid double counting adjacent beverages. |
Cider and Perry Market by Segments
Cider and Perry Market segmented by Product Type:
- Apple Cider
- Perry
- Fruit-Flavoured Cider
- Other Blends
Cider and Perry Market segmented by Packaging Format:
- Glass Bottles
- Cans
- Draught or Kegs
- PET Bottles
- Others
Cider and Perry Market segmented by Alcohol Content:
- Standard Alcoholic
- Lower-ABV
- Alcohol-Free
Cider and Perry Market segmented by Distribution Channel:
- Off-Trade
- On-Trade
- Online Retail
Cider and Perry Market segmented by Price Positioning:
- Mainstream
- Premium
- Craft
- Vintage or Specialty
Cider and Perry Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Chile
- Western Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Alcohol-free product development draws on processing capabilities within dealcoholization systems where aroma recovery and gentle separation are core requirements.
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2025, September 25). Fruit and tree nuts outlook: September 2025.
- [2] World Health Organization. (2025). Global report on the use of alcohol taxes, 2025.
- [3] Heineken UK. (2026, March 13). Inch’s Reserve: A new premium cider crafted in the heart of Herefordshire.
- [4] Thatchers Cider. (2025, November 25). Three new flavours launched in 2025 Cider Barn range.
- [5] Heineken UK. (2025). Cider Public House Rules: Cider Report 2025.
- [6] Heineken UK. (2025, March 10). Inch’s 0.0 and Inch’s Cloudy product launch.
- [7] Westons Cider. (2025, February 27). Henry Westons 1880 Vintage launch.
- [8] C&C Group plc. (2025). Annual Report and Accounts 2025.
- [9] World Health Organization. (2025, May 13). Total alcohol per capita consumption indicator update.
- [10] HM Revenue & Customs. (2026, August 28). Alcohol Bulletin: Provisional clearances and receipts.
- [11] Westons Cider. (2026). Westons Cider Report 2026.
The sources below support the outside statistics and company developments used in this report. Each numbered citation is placed with the sentence it supports.
This Report Answers
- How large is the cider and perry market in 2026 and what is forecast for 2036?
- Which orchard, pricing, and moderation trends support category demand?
- Why does apple cider lead product demand?
- How do packaged and draught formats influence route to market?
- Which country environments offer the strongest commercial conditions?
- Which companies shape international cider competition?
- What limits adoption or supplier switching?
- What should buyers evaluate before selecting a cider supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Apple Cider
- Perry
- Fruit-Flavoured Cider
- Other Blends
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles
- Cans
- Draught or Kegs
- PET Bottles
- Others
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Alcohol Content, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Alcohol Content, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Alcohol Content, 2026 to 2036
- Standard Alcoholic
- Lower-ABV
- Alcohol-Free
- Y-o-Y Growth Trend Analysis By Alcohol Content, 2021 to 2025
- Absolute $ Opportunity Analysis By Alcohol Content, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Off-Trade
- On-Trade
- Online Retail
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Price Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Positioning, 2026 to 2036
- Mainstream
- Premium
- Craft
- Vintage or Specialty
- Y-o-Y Growth Trend Analysis By Price Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- Chile
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- Alcohol-free product development draws on processing capabilities within dealcoholization systems where aroma recovery and gentle separation are core requirements.
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Packaging Format
- By Alcohol Content
- By Distribution Channel
- By Price Positioning
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Heineken
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Asahi Group Holdings
- C&C Group plc
- Thatchers Cider
- Westons Cider
- Carlsberg Group
- Molson Coors
- Kopparbergs Brewery
- Heineken N.V.
- Molson Coors Beverage Company
- Heineken
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Alcohol Content, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Price Positioning, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Packaging Format
- Figure 9: Global Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Alcohol Content
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Price Positioning
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Packaging Format
- Figure 35: North America Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Alcohol Content
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Price Positioning
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 51: Latin America Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Alcohol Content
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Price Positioning
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 67: Western Europe Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Alcohol Content
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Price Positioning
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Alcohol Content
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Price Positioning
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 99: East Asia Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Alcohol Content
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Price Positioning
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Alcohol Content
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Price Positioning
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Alcohol Content, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Alcohol Content, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Alcohol Content
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Price Positioning, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Price Positioning, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Price Positioning
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the cider and perry market in 2026, and what is forecast for 2036?
Future Market Insights estimates the market at USD 109.3 billion in 2026 and USD 158.7 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 3.8% CAGR during the assessment period.
Which product type leads?
Apple cider is projected to hold 72.0% share in 2026, supported by established taste recognition and broad international distribution.
What supports premiumisation?
Vintage releases, orchard provenance, craft fermentation, and premium pack design help raise value per litre.
Which formats are creating new occasions?
Alcohol-free, lower-ABV, cloudy, canned, and premium single-bottle formats widen product choice.
Who are key players?
Heineken, Asahi Group Holdings, C&C Group, Thatchers Cider, Westons Cider, Carlsberg Group, Molson Coors, and Kopparbergs Brewery are notable participants.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
