

- Market Size (2026)
- USD 725.2 Mn
- Forecast (2036)
- USD 1032.9 Mn
- CAGR (2026 to 2036)
- 3.6%
How big is Coconut Sugar Market in 2026?
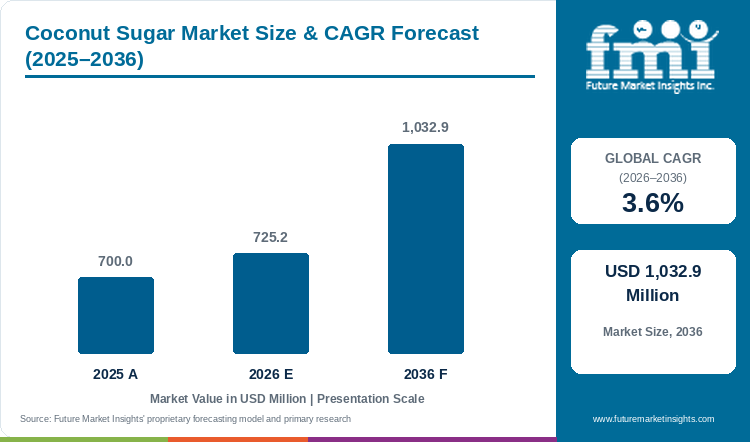
Sales in the coconut sugar market are projected to grow at 3.6% CAGR, with the market size rising from USD 700.0 million in 2025 to USD 725.2 million in 2026 and reaching USD 1032.9 million by 2036.
According to Future Market Insights analysis, food manufacturers face persistent formulation trade-offs as consumers demand unrefined natural sweetener solutions while production lines require thermal stability and uniform particle dosing. Liquid syrups complicate dough hydration and shorten finished shelf stability, driving processors toward crystalline sap derivatives. The global coconut sugar market stands at USD 700.0 million in 2025 and rises to USD 725.2 million in 2026. Industry valuation is projected to reach USD 1032.9 million by 2036, expanding at a 3.6% CAGR and generating USD 307.7 million in added revenue. In the United States, official USDA Economic Research Service reporting documented certified organic retail food sales at USD 69.7 billion, verifying that unrefined botanical sweeteners enter an established distribution channel [1]. Granular coconut sugar captures the leading position with 52.8% share in 2026, delivering direct 1:1 volumetric recipe substitution across dry bakery blends. Growth across evaluated economies spans 4.1% in Italy to 5.4% in the USA, although higher ingredient price spreads over cane sugar keep mass confectionery buyers selective.
Key Market Trends & Insights
- By form: Granular coconut sugar led with 52.8% share in 2026, supported by direct recipe substitution and familiar kitchen handling.
- By nature: Organic coconut sugar accounted for 44.6% in 2026, gaining momentum as certified sourcing reinforces clean-label claims.
- By application: Bakery and confectionery held 48.2% in 2026, driven by natural caramel flavoring and dry dough compatibility.
- By sales channel: Specialty and online retail represented 38.4% in 2026, reflecting detailed provenance storytelling and wider brand access.
Regional Highlights
- Fastest-growing evaluated country: USA, at 5.4% CAGR from 2026 to 2036.
- By country: South Korea at 5.1%, Australia at 4.9%, and the UK at 4.7% follow, while Italy records the lowest evaluated CAGR at 4.1%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Coconut Sugar Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 700.0 million |
| Estimated Market Size in 2026 | USD 725.2 million |
| Projected Market Size by 2036 | USD 1032.9 million |
| CAGR, 2026 to 2036 | 3.6% |
| Added Revenue, 2026 to 2036 | USD 307.7 million |
Country commercial conditions differ as tropical coconut harvests do not directly translate into export-grade coconut sugar. Sap collection requires tight temperature and harvest timing to prevent uncontrolled bacterial fermentation before evaporation. In preliminary agricultural documentation, the Philippine Council for Agriculture, Aquatic and Natural Resources Research and Development (PCAARRD) reported national coconut harvest at 14.5 million metric tons in 2025, with Davao Region contributing 1.9 million metric tons [2]. Only organized farmer collectives equipped with sanitary stainless evaporation pans and low-moisture drying beds can convert this raw harvest into exportable crystals. Commercial buyers of organic food ingredients therefore prioritize water activity metrics, batch traceability, and multi-origin supplier contracts over headline crop availability.
Coconut Supply and Market Conversion Sizing
Table 2: Coconut Supply and Market Conversion Indicators, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 700.0 | 725.2 | 1032.9 |
| Indicative average supplier revenue per 1,000 metric tons (USD) | Scenario range | Scenario range | Scenario range |
| Share of demand routed through certified supply | Rising | Rising | Higher adoption |
| Primary conversion risk | Moisture variation | Moisture variation | Climate and sourcing |
Market values follow the published market base and the 3.6% growth path used for the 2026 to 2036 assessment. Procurement indicators show how buyers are likely to read supply quality and are not presented as measured global volumes.
Per Capita and Procurement Sizing
Table 3: Per Capita Market Value Indicators for the Coconut Sugar Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population basis (billion) | 8.23 | 8.30 | 8.95 |
| Market value per capita (USD) | 0.085 | 0.087 | 0.115 |
| Market value per 1,000 people (USD) | 85.05 | 87.37 | 115.41 |
Table 4: Commercial Procurement Indicators for Coconut Sugar, 2026
| Procurement Metric | Commercial Interpretation | Buyer Relevance |
|---|---|---|
| Granulation consistency | Uniform particle size and low caking | Supports dosing and recipe repeatability |
| Moisture control | Reduced clumping during storage | Protects shelf life in humid supply lanes |
| Organic certification | Documented chain of custody | Supports certified finished-product claims |
| Origin diversification | Multiple approved supplier regions | Reduces harvest and freight exposure |
Analyst Perspective
“Coconut sugar suppliers must pair stable flavor with verified sourcing and low-moisture handling. Processors that standardize quality can enter broader bakery, beverage, and retail programs.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the coconut sugar market segmented?
The coconut sugar market is segmented by form, nature, application, and sales channel. In 2026, granular coconut sugar is projected at 52.8%, conventional at 55.4% (with organic at 44.6%), bakery and confectionery at 48.2%, and specialty and online retail at 38.4%.
By form: Granular, powder, syrup / liquid, block, and others.
By nature: Organic and conventional.
By application: Bakery and confectionery, beverages, dairy and frozen desserts, nutraceuticals, personal care, and others.
By sales channel: Direct sales, supermarkets / hypermarkets, specialty stores, online retail, and others.
Why does Granular Coconut Sugar lead the form category?
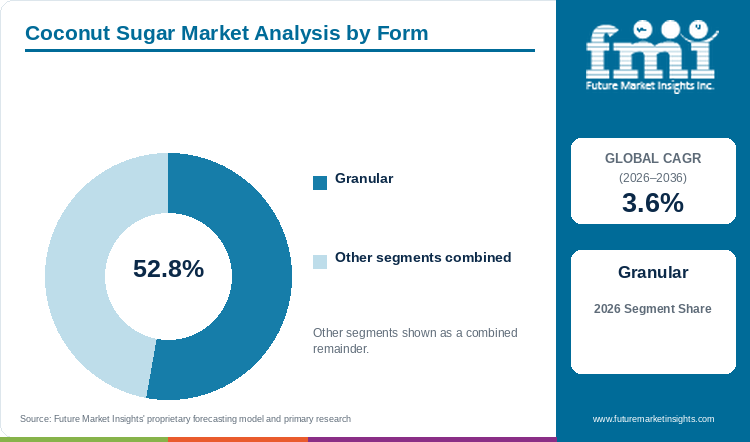
Granular coconut sugar represents 52.8% of form demand in 2026, supported by direct recipe substitution and familiar kitchen handling.
Table 5: Form Share for the Coconut Sugar Market (percentage share), 2026
| Form | Share (2026) |
|---|---|
| Granular Coconut Sugar | 52.8% |
| Other Segments Combined | 47.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Form Leadership and Market Growth for the Coconut Sugar Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.6% |
| Leading Form | Granular Coconut Sugar |
Granular coconut sugar is likely to remain ahead because it follows the same measuring habit used for ordinary sugar and can be added to bakery mixes without changing the liquid balance. Its position may weaken in instant beverages, where undissolved particles are visible and finer powder works better. Formulators incorporating beverage flavoring systems prefer micro-milled formats for rapid suspension. This makes form demand application-led rather than one format replacing every other grade.
- Granular coconut sugar represents 52.8% of form demand in 2026 because 1:1 recipe substitution for conventional cane sugar and familiar measuring habits make it the primary format for commercial bakeries and home kitchens.
- In March 2025, commercial milling trials demonstrated that micronized coconut sugar powders reduce beverage sedimentation without requiring synthetic anti-caking agents [2].
Why is Organic Coconut Sugar gaining prominence by nature?
Organic coconut sugar accounts for 44.6% of nature in 2026, underpinned by certified smallholder sourcing, non-GMO verification, and clean-label formulation demand.
Organic coconut sugar carries a visible premium cue, however the certification has value only when records remain intact from tapping and collection to cooking, drying and packing. The segment can gain where a brand sells certified finished products and needs an approved input. In specialty bakery ingredients, audit compliance ensures that non-GMO and organic claims withstand regulatory verification. Higher audit cost and an incomplete chain of custody can hold it back, especially for price-led buyers.
- Organic coconut sugar accounts for 44.6% of nature in 2026 because packaged food manufacturers and health-conscious shoppers prioritize certified pesticide-free sourcing and auditable organic traceability.
- In 2026, Tradin Organic initiated a dedicated program supporting 2,275 organic coconut sugar farmers in Central Java to reinforce certified supply chains [3].
What keeps Bakery and Confectionery ahead by application?
Bakery and confectionery accounts for 48.2% of application in 2026, driven by natural caramel flavoring, unrefined browning characteristics, and dry dough compatibility.
Bakery and confectionery remain the practical demand centre because caramel notes can support cookies, bars, chocolate fillings and selected desserts, while the dry form fits existing ingredient handling. Within plant-based food formulations, natural browning properties enhance visual texture. Darker color can work in brown products but may be unwanted in light cakes, and the higher cost can limit use to premium lines or partial replacement.
- Bakery and confectionery holds 48.2% of application in 2026 because natural caramel notes and thermal stability make coconut crystals an ideal botanical sweetener for cookies, snack bars, and artisanal chocolates.
- In 2025, industrial baking trials confirmed that coconut sugar delivers comparable dough spread and moisture retention relative to brown cane sugar without requiring recipe re-engineering.
What gives Specialty and Online Retail a strong role in distribution?
Specialty and online retail represents 38.4% of sales channel in 2026, reflecting detailed provenance storytelling, organic certification visibility, and direct-to-consumer reach.
Specialty and online retail give coconut sugar more room to explain origin, certification and use than a crowded standard sugar shelf. This helps discovery and allows smaller certified brands to reach buyers without full national distribution. Sourcing for confectionery ingredient systems increasingly leverages online portals for sample verification. Repeat purchasing is more likely when pack information, availability and recipe performance all remain dependable.
- Specialty and online retail accounts for 38.4% of sales channel in 2026 because dedicated wellness grocers and direct-to-consumer digital storefronts provide the educational platform required to communicate low-glycemic and unrefined benefits.
- In 2025, specialty natural-food retail audits showed that organic sugar alternatives achieved significantly higher basket placement through curated digital wellness platforms than through conventional commodity aisles.
What are the drivers, restraints, and opportunities in the coconut sugar market?
Clean-label formulation supports demand, while crop concentration and moisture instability constrain scale, and certified ingredient systems create premium value.
- Driver: Food brands are broadening natural sweetener use across bakery, beverages, snacks, and premium household products.
- Restraint: Variable sap quality, labor-intensive collection, and humidity-sensitive processing can disrupt color, flavor, and granulation.
- Opportunity: Supplier training, low-emission cooking, traceability, and blended sweetener development can expand approved applications.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clean-label demand is supporting coconut sugar where the ingredient performs a job beyond a front-label claim. Its caramel note matches cookies, bars and dark beverages, and the granular form can enter an existing dry mix without a separate liquid handling step. Commercial demand for specialty food ingredients reinforces botanical sugars that avoid artificial additives. United States organic retail sales reached USD 69.7 billion in 2023, demonstrating a substantial addressable consumer platform. Brands will continue with coconut sugar when flavor, color and replenishment remain stable.
Risk Assessment of the Coconut Sugar Market: Supply and Processing Friction
Coconut sap starts changing soon after collection, therefore the production risk sits between the tree and the drying stage rather than only at the farm. Slow collection can bring fermentation, excessive heating can darken the batch and moisture picked up after drying can turn free-flowing sugar into a caked shipment. While liquid coconut syrup provides an alternative format, dry crystals remain essential for bakeries. Incoming moisture checks, barrier packaging and multi-origin sourcing reduce this operational exposure.
Commercial Opportunity Analysis: Certification and Formulation Differentiation
The better commercial opening is with suppliers that remove variation before asking for a premium. Fine powder can move into instant drinks because it disperses faster, while controlled granules suit bakery dosing and create less dust. In 2026, Tradin Organic initiated a three-year project benefiting 2,275 coconut sugar farmers in Central Java, targeting safer processing, living incomes, and certified organic production [3]. Demand for botanical sugar alternatives rewards suppliers that translate origin investments into verifiable batch quality and multi-year supply contracts.
Coconut Sugar Market by Country (2026 to 2036)
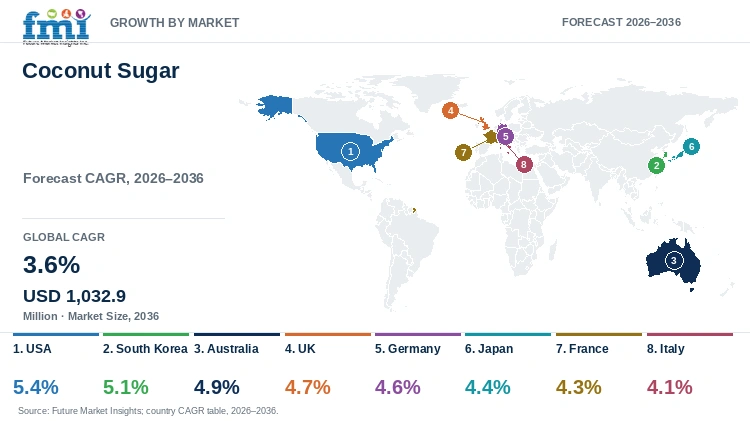
As per Future Market Insights, the USA represents the fastest-growing coconut sugar market among the eight evaluated countries, at a 5.4% CAGR from 2026 to 2036, while Italy records 4.1% CAGR. Across all eight covered economies, commercial success is dictated by clean-label certification, low-glycemic positioning, and consistent batch quality.
Table 7: Country CAGR and Primary Growth Levers for the Coconut Sugar Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.4% | Organic retail scale and clean-label formulation |
| South Korea | 5.1% | Premium natural sweetener adoption |
| Australia | 4.9% | Organic retail and plant-based food demand |
| UK | 4.7% | Sugar reduction and specialty retail |
| Germany | 4.6% | Mature organic food purchasing |
| Japan | 4.4% | Premium ingredient quality expectations |
| France | 4.3% | Gourmet and organic food applications |
| Italy | 4.1% | Premium bakery and specialty retail |
Source: Future Market Insights analysis
USA Coconut Sugar Market Outlook (2026 to 2036)
The USA has the strongest published rate among the retained countries at 5.4% CAGR from 2026 to 2036. The country has broad organic retail, online grocery and a large bakery and snack formulation base in which specialty coconut-derived specialty ingredients can be tested in limited lines before wider rollout. Coconut sugar gains in cookies, bars and household baking, but the price gap against cane sugar keeps buyers selective. Stable import lanes and careful label compliance matter more than broad wellness claims.
Key takeaway: In the USA, expansive organic retail presence and specialty bakery formulation drive commercial coconut sugar adoption.
South Korea Coconut Sugar Market Outlook (2026 to 2036)
South Korea is projected at 5.1% CAGR from 2026 to 2036, driven by upscale foodservice and specialty cafés. Premium cafés, bakery formats and visually led retail products create demand for a small-volume ingredient with an authentic origin story. Coconut sugar enters through finished drinks, desserts and gifting confectionery before ordinary cooking use. The hurdle remains color and flavor consistency, because batch shifts alter standardized beverage menus, while imported pricing keeps the addressable base narrow.
Key takeaway: In South Korea, premium café culture and gifting confectionery create targeted demand for origin-certified natural sweeteners.
Australia Coconut Sugar Market Outlook (2026 to 2036)
Australia is expected to expand at 4.9% CAGR from 2026 to 2036, supported by an established natural-food channel and consumer access to organic products. Bulk-food dispensaries and home baking give coconut sugar an active retail route outside packaged manufacturing, while cafés and premium snack brands provide secondary volume. Distance from Southeast Asian supply is shorter than for Europe, but freight and certification overhead still challenge distribution economics. Demand holds where brands maintain shelf availability.
Key takeaway: In Australia, strong natural food retail networks and plant-based baking habits support recurring household purchasing.
UK Coconut Sugar Market Outlook (2026 to 2036)
The UK outlook of 4.7% CAGR from 2026 to 2036 is tied to sugar reduction pressure and clean-label bakery reformulations. Coconut sugar offers unrefined positioning and natural caramel notes for artisanal biscuits, vegan pastries, and specialty retail. Online availability broadens geographic reach, though cost-conscious supermarket procurement and strict scrutiny over health claims limit mass conversion. Suppliers that explain exact functional properties and sweetness equivalence retain repeat commercial contracts.
Key takeaway: In the UK, sugar reduction awareness and vegan bakery lines encourage selective adoption of unrefined coconut crystals.
Germany Coconut Sugar Market Outlook (2026 to 2036)
Germany is placed at 4.6% CAGR from 2026 to 2036, underpinned by Europe's most mature organic retail environment. Certified organic coconut sugar benefits from established health-food aisles where consumers verify origins and certifications. However, German industrial buyers enforce strict specification tolerances regarding moisture content, granule diameter, and color consistency. Suppliers providing complete analytical documentation and segregated supply chains secure stable contracts, while uncertified lots face severe commercial resistance.
Key takeaway: In Germany, strict organic certification standards and specification discipline govern supplier approval across bio-retail channels.
Japan Coconut Sugar Market Outlook (2026 to 2036)
Japan is forecast at 4.4% CAGR from 2026 to 2036, where stringent physical purity standards dictate commercial viability. Coconut sugar fits boutique confectionery and functional beverages requiring distinct caramel notes, but shipments must meet strict microbiological limits, low moisture levels, and elegant barrier packaging. Growth remains value-led rather than volume-driven because food formulators are deliberate in qualifying foreign agricultural inputs. Processors delivering batch-to-batch consistency secure enduring foodservice programs.
Key takeaway: In Japan, rigorous physical purity standards and compact premium packaging define commercial market access.
France Coconut Sugar Market Outlook (2026 to 2036)
France is expected to grow at 4.3% CAGR from 2026 to 2036, accessing consumers primarily through organic boutiques, artisanal patisseries, and gourmet chocolate formulations. Coconut sugar provides an aromatic profile that complements dark chocolates and specialty desserts, but imported origins must justify higher price points against domestic beet sugars. Uptake expands when pastry chefs leverage its sensory character for signature creations, whereas basic tabletop substitution remains modest.
Key takeaway: In France, artisanal patisserie formulations and organic gastronomy provide high-value niches for unrefined coconut sugar.
Italy Coconut Sugar Market Outlook (2026 to 2036)
Italy carries the lowest published rate in the retained set at 4.1% CAGR from 2026 to 2036, reflecting entrenched traditional confectionery and espresso sweetening habits. Coconut sugar finds selective placement in health-focused espresso bars, organic bakeries, and vegan biscuit formulations where darker coloration is acceptable. Higher import costs and traditional palate preferences limit mainstream bakery adoption, keeping commercial volumes concentrated in urban specialty retail channels.
Key takeaway: In Italy, traditional confectionery preferences restrict volume replacement to modern health cafes and specialty vegan bakeries.
Full report country coverage includes North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the coconut sugar market?
Big Tree Farms, The Coconut Company, Nutiva, Madhava, Tradin Organic, Celebes Coconut Corporation, Coco Sugar Indonesia, and Rapunzel Naturkost are notable market participants.
Competition is not decided only by the number of retail packs a company sells. Origin processors have an advantage when they control farmer collection and drying, traders gain where buyers require several certifications and destinations, while consumer brands are stronger at explaining use and getting shelf space. A wide farmer network without batch discipline can create inconsistent supply, and a strong retail name without dependable origin control faces similar vulnerability during dry harvests.
- Origin and processing platforms: Big Tree Farms, Celebes Coconut Corporation, and Coco Sugar Indonesia.
- Organic ingredient and trading platforms: Tradin Organic and Rapunzel Naturkost.
- Consumer natural sweetener brands: Nutiva, Madhava, and The Coconut Company.
Competitive Benchmarking: Coconut Sugar Market
Table 8: Competitive Benchmarking for the Coconut Sugar Market (qualitative capability ratings), 2026
| Company | Sourcing Depth | Certification Position | Retail / Ingredient Access | Geographic Reach |
|---|---|---|---|---|
| Big Tree Farms | High | High | High | High |
| The Coconut Company | Medium | High | High | Medium |
| Nutiva | Medium | High | High | High |
| Madhava | Medium | High | High | Medium |
| Tradin Organic | High | High | Medium | High |
| Celebes Coconut Corporation | High | Medium | Medium | High |
| Coco Sugar Indonesia | High | Medium | Medium | Medium |
| Rapunzel Naturkost | Medium | High | High | High |
Scoring basis: Ratings reflect publicly visible sourcing, certification, channel, and geographic capabilities. They are qualitative and do not represent market share.
Key Developments in the Coconut Sugar Market
- In March 2026, Tradin Organic launched a three-year farmer resilience program in Central Java covering 2,275 smallholders with organic certification, food safety, and low-carbon processing equipment [3].
- In October 2025, Big Tree Farms expanded its certified organic Nira sap collection network across East Indonesia to stabilize bulk granular sugar supply for export programs [5].
- In May 2025, Celebes Coconut Corporation commissioned high-efficiency vacuum drying equipment in Mindanao to lower moisture variation in export-grade coconut sugar shipments [6].
Key Players in the Coconut Sugar Market
Origin and Processing Platforms
- Big Tree Farms
- Celebes Coconut Corporation
- Coco Sugar Indonesia
Organic Ingredient and Trading Platforms
- Tradin Organic
- Rapunzel Naturkost
Consumer Natural Sweetener Brands
- Nutiva
- Madhava
- The Coconut Company
Coconut Sugar Market - Report Scope
Table 9: Report Scope for the Coconut Sugar Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; Nature; Application; Sales Channel |
| Quantitative units | USD Million |
| Market definition | Supplier revenue from coconut sugar in granular, powder, liquid, block, and related commercial formats. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries evaluated | USA, South Korea, Australia, UK, Germany, Japan, France, and Italy |
| Key companies covered | Big Tree Farms, The Coconut Company, Nutiva, Madhava, Tradin Organic, Celebes Coconut Corporation, Coco Sugar Indonesia, Rapunzel Naturkost |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Coconut Sugar Market - Research Methodology
Table 10: Research Methodology for the Coconut Sugar Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with manufacturers, suppliers, distributors, food formulators, retailers, certification specialists, and industry experts validate purchasing requirements and market direction. |
| Secondary Research | Company disclosures, government publications, industry associations, technical papers, trade journals, websites, product literature, and public sources support the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess value demand, pricing, applications, and channel adoption for 2026 to 2036. |
| Data Triangulation and Validation | Findings are checked against agricultural supply, organic retail indicators, regulatory context, corporate evidence, and historical market trends. |
Coconut Sugar Market by Segments
Coconut Sugar Market segmented by Form:
- Granular
- Powder
- Syrup / Liquid
- Block
- Others
Coconut Sugar Market segmented by Nature:
- Organic
- Conventional
Coconut Sugar Market segmented by Application:
- Bakery and Confectionery
- Beverages
- Dairy and Frozen Desserts
- Nutraceuticals and Supplements
- Personal Care and Cosmetics
- Others
Coconut Sugar Market segmented by Sales Channel:
- Direct Sales
- Supermarkets / Hypermarkets
- Specialty Stores
- Online Retail
- Others
Coconut Sugar Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Raszap Skorbiansky, S. (2025). Organic Situation Report, 2025 Edition. U.S. Department of Agriculture, Economic Research Service.
- [2] Philippine Council for Agriculture, Aquatic and Natural Resources Research and Development. (2026). Coconut industry profile and 2025 preliminary production statistics. Department of Science and Technology.
- [3] Tradin Organic. (2026). Indonesia’s sweet spot: Livelihood resilience through innovation for safe, organic coconut sugar production. Corporate Newsroom.
- [4] Food and Agriculture Organization of the United Nations. (2025). World food and agricultural statistics yearbook: Production of sugar and tropical crops. FAO Statistical Reports.
- [5] Big Tree Farms. (2025). Sustainable organic coconut sugar sourcing and regenerative agriculture report. Corporate Sustainability Disclosures.
- [6] Celebes Coconut Corporation. (2025). Export quality standards and product specifications for organic coconut sugar. Technical Product Releases.
- [7] U.S. Food and Drug Administration. (2025). Food labeling and sweetener guidance: Botanical and unrefined nutritive sugars. Center for Food Safety and Applied Nutrition.
- [8] Future Market Insights. (2025, March 31). Coconut Sugar Market Size, Trends & Growth 2025 to 2035. Syndicated Market Report.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the coconut sugar market in 2026 and what is forecast for 2036?
- Which clean-label and organic trends support demand for coconut sugar?
- Why does granular coconut sugar lead form demand across dry mixes?
- How does organic certification affect procurement and commercial pricing?
- How do listed growth rates differ across evaluated national economies?
- Which companies operate across origin processing, ingredient trading, and retail brands?
- What technical factors limit wider industrial adoption across large-scale food lines?
- What should buyers evaluate before approving a coconut sugar supplier?
Frequently Asked Questions
How big is the coconut sugar market in 2026, and what is forecast for 2036?
Future Market Insights estimates the global market at USD 725.2 million in 2026. The market is projected to reach USD 1032.9 million by 2036, expanding at a 3.6% CAGR.
What is the CAGR from 2026 to 2036?
The market is projected to expand at 3.6% CAGR over the assessment period. Growth is supported by steady reformulation across bakery, beverage, and retail specialty channels.
Which form leads the coconut sugar market?
Future Market Insights projects that granular coconut sugar will hold 52.8% share in 2026. The segment benefits from direct 1:1 recipe substitution and familiar kitchen handling.
Which nature segment is gaining traction?
Organic coconut sugar accounts for 44.6% share in 2026 as food processors and household consumers demand certified non-GMO and chemical-free sweeteners.
Which evaluated country has the strongest growth outlook?
FMI data suggests that the USA has the highest projected country CAGR at 5.4% from 2026 to 2036, followed by South Korea at 5.1% and Australia at 4.9%.
Who are notable companies in the market?
Notable participants include Big Tree Farms, The Coconut Company, Nutiva, Madhava, Tradin Organic, Celebes Coconut Corporation, Coco Sugar Indonesia, and Rapunzel Naturkost.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Granular
- Powder
- Syrup / Liquid
- Block
- Others
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Organic
- Conventional
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Bakery and Confectionery
- Beverages
- Dairy and Frozen Desserts
- Nutraceuticals and Supplements
- Personal Care and Cosmetics
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct Sales
- Supermarkets / Hypermarkets
- Specialty Stores
- Online Retail
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Form
- By Nature
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Nature
- By Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Nature
- By Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Nature
- By Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Big Tree Farms
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Coconut Company
- Nutiva
- Madhava
- Tradin Organic
- Celebes Coconut Corporation
- Coco Sugar Indonesia
- Rapunzel Naturkost
- Big Tree Farms
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


